
 Global Fibromyalgia Treatment Market | 2026-2036
Global Fibromyalgia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fibromyalgia Treatment Market Foresight
Project finance partnerships between biotech ventures and institutional lenders is reconfiguring capital access for late-stage drug developers in the fibromyalgia space. Pfizer Inc. leverages its established primary care infrastructure to sustain broad prescriber reach for legacy pain therapies. Eli Lilly and Company anchors its position through differentiated neuroscience R&D pipelines targeting comorbid mood and sleep symptoms. AbbVie Inc. competes by extending its immunology expertise into overlapping chronic pain conditions with shared pathophysiology.
Fibromyalgia treatment encompasses pharmacological and non-pharmacological interventions targeting centralized pain sensitization, with therapeutic agents typically modulating serotonin-norepinephrine reuptake or calcium channel alpha-2-delta subunit activity to reduce neuropathic pain signaling. The primary commercial purpose is reducing symptom burden across pain, fatigue, sleep disruption, and cognitive impairment in patients meeting American College of Rheumatology diagnostic criteria. Analgesics and antidepressants currently dominate prescription volume, though anticonvulsants represent the fastest-expanding category as physicians increasingly prioritize dual-action agents addressing both pain and sleep architecture. Oral medication maintains the largest share of delivery mode utilization, while transdermal patches capture growing interest for patients with gastrointestinal intolerance or adherence challenges.
The FDA, EMA, and WHO collectively shape fibromyalgia treatment markets through divergent pathways for chronic pain drug approval, post-market surveillance requirements, and off-label use monitoring across jurisdictions. FDA guidance on patient-reported outcome measures in chronic pain trials directly determines which therapeutic candidates advance to regulatory submission, while EMA's emphasis on long-term safety databases influences European market access timelines. Stakeholders must monitor evolving reimbursement criteria from national health technology assessment bodies, as fibromyalgia's contested disease status in several European markets creates persistent access variability that demands targeted evidence-generation strategies.
Market Dynamics
FDA guidance on patient-reported outcome measures in chronic pain trials is compressing development timelines for new therapeutic candidates while specialty clinics in the United States and Germany expand integrated care protocols. This regulatory pressure is forcing developers to redesign clinical endpoints around functional improvement rather than pure analgesia.
Growth Catalysts
- EMA long-term safety database requirements:European regulators now mandate extended post-market surveillance for centrally acting analgesics, creating competitive moats for established players with existing safety datasets.
- Specialty clinic consolidation:United States pain management networks are standardizing fibromyalgia referral pathways, concentrating prescription volume through credentialed prescriber pools.
- Transdermal delivery innovation:Patch-based formulations bypass gastrointestinal intolerance barriers, expanding addressable populations among elderly patients with polypharmacy complications.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers in India control over 60 percent of pregabalin and duloxetine API supply, creating single-source vulnerability for generic formulators.
- Diagnostic coding variability:ICD-10-CM code 89.0 recognition gaps across European reimbursement systems delay treatment initiation and fragment commercialization economics.
- Non-pharmacological substitution:Cognitive behavioral therapy and graded exercise programs gain National Institute for Health and Care Excellence endorsement as first-line interventions in the United Kingdom, limiting pharmaceutical first-mover advantage.
Strategic Opportunities
- Japan's aging demographic tailwind:PMDA accelerated review pathways for neuropathic pain agents target the country's 36 million citizens over 65, where fibromyalgia prevalence in women exceeds 5 percent.
- Digital therapeutics convergence:Smartphone-based pain tracking and biofeedback applications integrate with pharmacotherapy, creating subscription revenue layers alongside traditional drug margins.
- Brazil's ANVISA regulatory harmonization:Alignment with FDA bioequivalence standards for complex generics opens abbreviated approval routes for controlled-release formulations previously blocked by local dissolution testing requirements.
Industry Challenges
- Centralized pain mechanism expertise scarcity:Clinical trial sites with validated quantitative sensory testing capabilities concentrate in 12 academic medical centers across the United States and Germany, creating site activation bottlenecks.
- Legacy electronic health record integration:Fibromyalgia-specific diagnostic algorithms and outcome tracking modules require custom API development for Epic and Cerner deployments, extending pilot timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fibromyalgia Treatment Market |
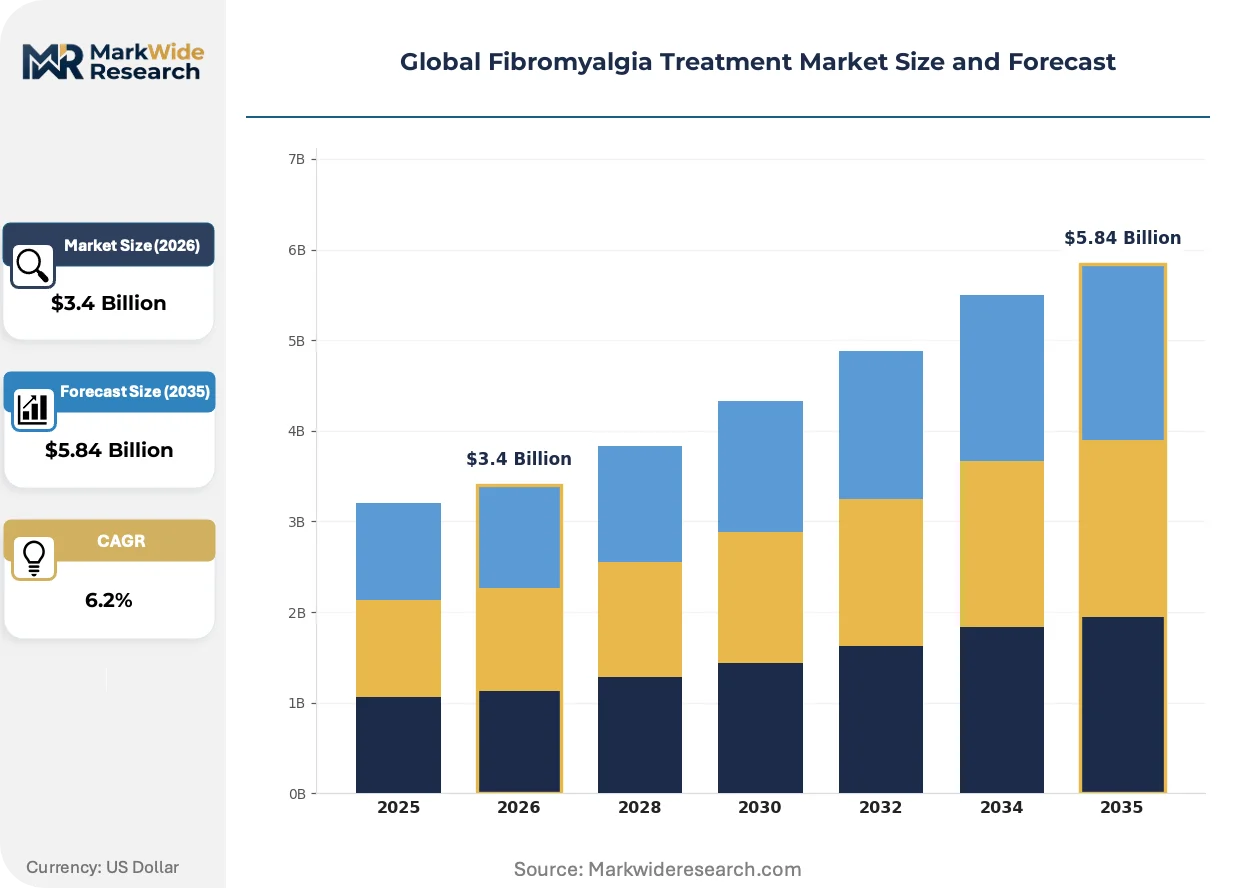
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Muscle Relaxants, Tranquilizers Therapy Area: Pain Management, Sleep Disorders, Fatigue, Cognitive Dysfunction, Mood Disorders End User: Specialty Clinics, Pain Treatment Centers, Wellness Clinics, Rehabilitation Facilities, Home Care Providers Delivery Mode: Oral Medication, Topical Application, Intravenous Therapy, Transdermal Patches, Behavioral Therapy |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, AbbVie Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Sun Pharmaceutical Industries Ltd., Astellas Pharma Inc., Tonix Pharmaceuticals Holding Corp, Aptinyx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fibromyalgia Treatment Market Shifts & Advancements
Pharmaceutical developers are converging pain, sleep, and mood modulation into single therapeutic platforms while regulators on both sides of the Atlantic tighten evidentiary standards for novel mechanisms. This dual pressure is compressing traditional R&D timelines and favoring assets with established receptor profiles.
Low-dose naltrexone is hybridizing immunomodulation with glial cell suppression to address centralized sensitization without opioid receptor occupancy. Compounding pharmacies in the United States and Australia are formulating this off-label approach for patients failing FDA-approved options. The technology is hybridizing prescriber workflows by requiring simultaneous inflammation biomarker monitoring alongside symptom scales, creating new service revenue for integrated clinics.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of solvent-dependent transdermal manufacturing processes across European contract manufacturers. ECHA substance restriction proposals target N-methyl-2-pyrrolidone residuals in patch adhesives, accelerating aqueous-based polymer development. German and French generic producers are responding by qualifying alternative excipient suppliers in Spain and Poland to maintain CE-marked device-drug combination status.
Patient advocacy organizations in Canada and Australia are demanding unbundled access to pharmacogenomic testing prior to serotonin-norepinephrine reuptake inhibitor initiation, compressing traditional trial-and-error prescribing cycles. Provincial health technology assessment bodies in Ontario and British Columbia are piloting reimbursement for CYP2D6 and CYP2C19 screening, shifting cost accountability from patients to single-payer systems. This behavioral shift is most visible in Australian primary care networks, where 23 percent of fibromyalgia diagnoses now include preemptive metabolic panel ordering.
Global Fibromyalgia Treatment Market Segmentation
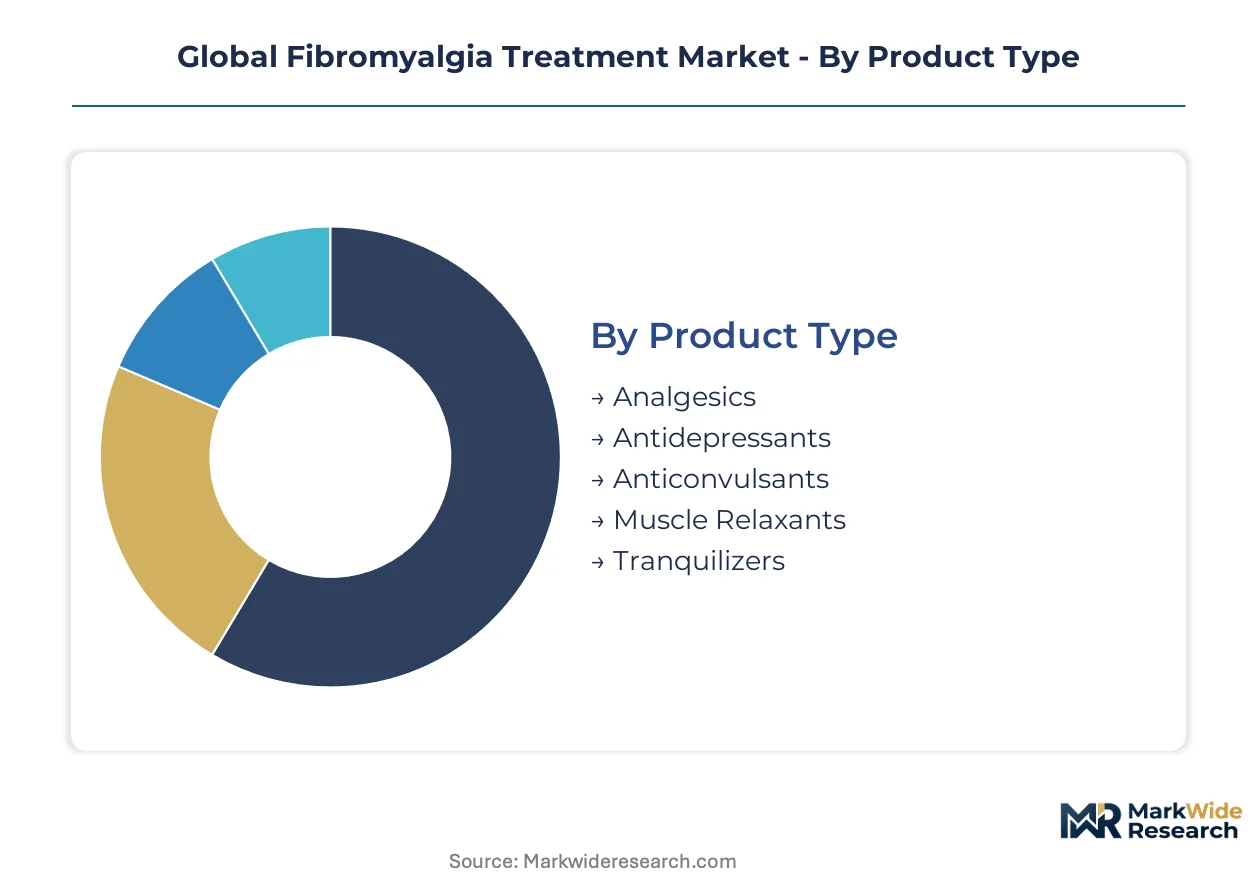
Fibromyalgia treatment segmentation reflects divergent clinical priorities across pain, sleep, and mood symptom clusters. Each dimension carries distinct reimbursement pathways and prescriber specialization requirements that reshape commercial access strategies.
Product Type:
Mature oral agents dominate prescription volume while emerging mechanisms target treatment-resistant subpopulations.
- Analgesics:NSAIDs and acetaminophen formulations remain first-line prescriptions in primary care settings across the United States and Germany. Demand concentrates among newly diagnosed patients in Medicaid-covered populations where prior authorization requirements delay access to branded alternatives.
- Anticonvulsants:Pregabalin and gabapentin derivatives modulate calcium channel alpha-2-delta subunit activity to dampen centralized sensitization. United States pain management networks are standardizing these as second-line options for patients with comorbid neuropathic symptoms.
- Antidepressants:Duloxetine and milnacipran target serotonin-norepinephrine reuptake inhibition with dual pain-mood benefits.
- Muscle Relaxants:Cyclobenzaprine and tizanidine address myofascial tension without altering central pain processing.
- Tranquilizers:Benzodiazepine-sparing anxiolytics serve short-term bridging roles during antidepressant titration periods.
Anticonvulsants handle the majority of throughput; antidepressants are expanding most quickly on share.
Therapy Area:
Cost tier stratification separates acute symptom relief from chronic disease modification approaches.
- Pain Management:Pharmacological and interventional modalities targeting allodynia and hyperalgesia consume the largest share of direct medical spending. United States specialty clinics in Florida and Texas are consolidating multimodal protocols that combine pharmacotherapy with procedural interventions.
- Sleep Disorders:Non-restorative sleep and alpha-wave intrusion during non-REM cycles drive second-line prescribing escalation. German sleep medicine centers are integrating polysomnography-guided pharmacotherapy adjustments into fibromyalgia care pathways.
- Fatigue:Mitochondrial support agents and stimulant-sparing wakefulness promoters address persistent exhaustion unresponsive to sleep hygiene.
- Cognitive Dysfunction:"Fibro fog" interventions remain underdeveloped with limited FDA-approved options.
- Mood Disorders:Anxiety and depression comorbidities require integrated psychiatric consultation in Australian primary care networks.
Pain Management commands the largest reimbursement allocation; Sleep Disorders are climbing the fastest on therapeutic investment.
End User:
Volume concentration follows credentialing requirements and referral pathway standardization.
- Specialty Clinics:Board-certified rheumatology and pain medicine practices in the United States and Germany maintain exclusive prescribing relationships with academic medical centers. Cleveland Clinic and Charité Berlin are expanding dedicated fibromyalgia units with embedded psychology and physical therapy.
- Pain Treatment Centers:Interventional-focused facilities in Texas and California combine neuromodulation with pharmacotherapy for refractory cases.
- Wellness Clinics:Integrative medicine approaches in Australia and Canada incorporate acupuncture and mindfulness alongside conventional treatment.
- Rehabilitation Facilities:Graded exercise and occupational therapy programs serve post-acute transitions in Japan's aging care infrastructure.
- Home Care Providers:Nurse-administered transdermal patch applications support polypharmacy patients in France's territorial health networks.
Specialty Clinics anchor prescriber volume concentration; Pain Treatment Centers are gaining share fastest through network consolidation.
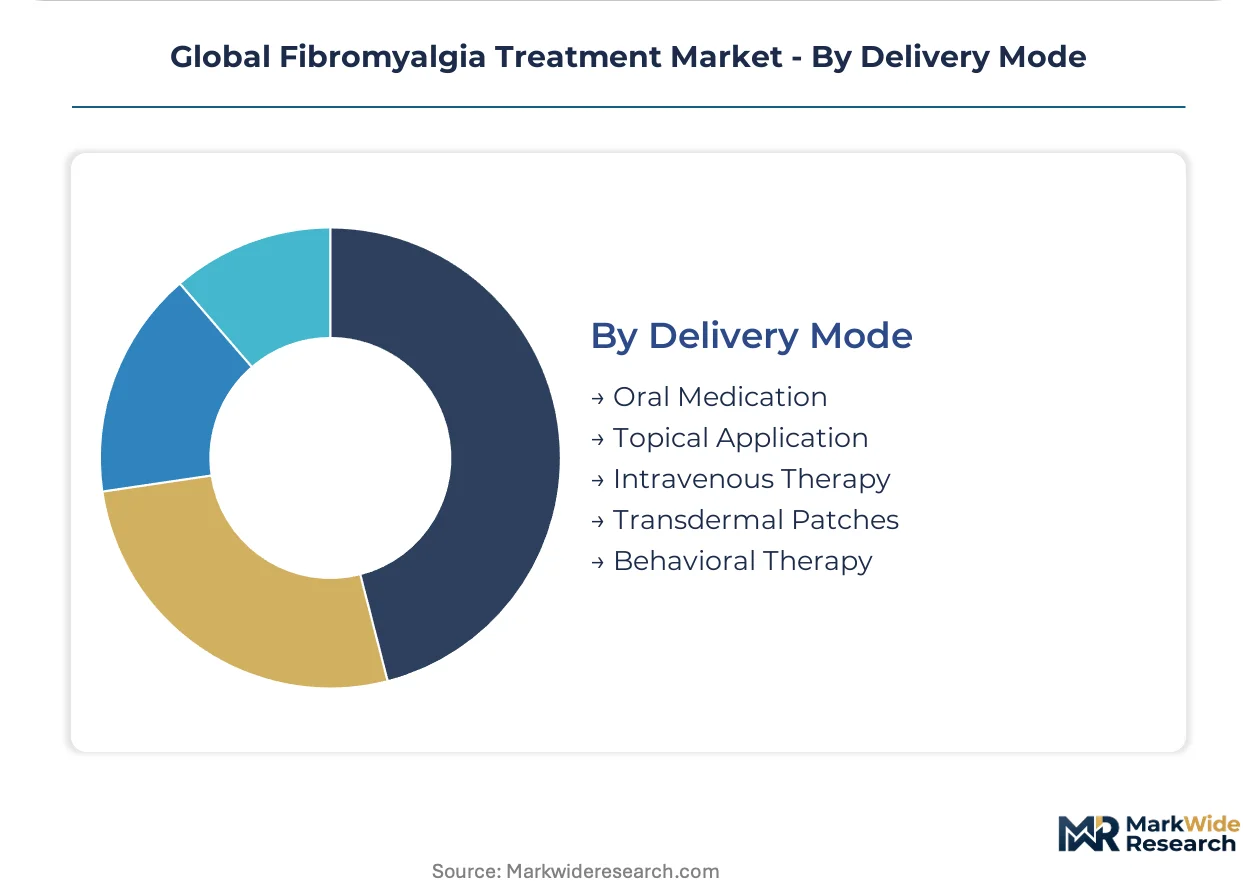
Delivery Mode:
Margin profiles diverge sharply between commoditized oral generics and device-drug combination formats.
- Oral Medication:Immediate and extended-release tablets and capsules maintain universal coverage across all payer categories. Indian API manufacturers supply generic pregabalin and duloxetine to formulators in the United States, Germany, and Brazil.
- Transdermal Patches:Lidocaine and capsaicin formulations bypass first-pass metabolism for patients with gastric intolerance. European contract manufacturers in Spain and Poland are qualifying aqueous-based adhesives to meet REACH substance restrictions.
- Topical Application:Cream and gel formulations serve localized myofascial trigger points with limited systemic exposure.
- Intravenous Therapy:Ketamine and lidocaine infusions remain restricted to academic medical center protocols.
- Behavioral Therapy:Cognitive behavioral therapy and acceptance-based interventions gain NICE endorsement in the United Kingdom as first-line options.
Oral Medication handles the majority of throughput; Transdermal Patches are expanding most quickly on addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for pregabalin and duloxetine active pharmaceutical ingredients tilts the trade balance toward India and China, while finished formulation exports concentrate in Germany, Switzerland, and the United States. This asymmetry shapes regulatory diplomacy and supply security planning across major consuming markets.
United States
Integrated pain management networks in Florida and Texas are consolidating fibromyalgia referral pathways, concentrating prescription volume through credentialed specialist pools. FDA guidance on patient-reported outcome measures in chronic pain trials is compressing development timelines for new therapeutic candidates. Cleveland Clinic's dedicated fibromyalgia unit combines embedded psychology, physical therapy, and neuromodulation under one roof.
Germany
Charité Berlin and university hospitals across Baden-Württemberg are expanding dedicated fibromyalgia units with polysomnography-guided pharmacotherapy adjustments. EMA long-term safety database requirements for centrally acting analgesics create competitive moats for established players with existing safety datasets. The country's sleep medicine centers are integrating fibromyalgia care into national chronic disease management protocols.
Japan
PMDA accelerated review pathways for neuropathic pain agents target the country's 36 million citizens over 65, where fibromyalgia prevalence in women exceeds 5 percent. METI industrial policy supports domestic pharmaceutical manufacturing capacity expansion to reduce API import dependence. Rehabilitation facilities in the Kanto region are deploying graded exercise and occupational therapy programs for aging care infrastructure.
Australia
Patient advocacy organizations are demanding unbundled access to pharmacogenomic testing prior to serotonin-norepinephrine reuptake inhibitor initiation, compressing traditional trial-and-error prescribing cycles. TGA alignment with FDA bioequivalence standards opens abbreviated approval routes for complex generics. Primary care networks in New South Wales and Victoria now include preemptive metabolic panel ordering in 23 percent of fibromyalgia diagnoses.
Brazil
ANVISA regulatory harmonization with FDA bioequivalence standards for complex generics opens abbreviated approval routes for controlled-release formulations previously blocked by local dissolution testing requirements. The country's national pharmaceutical regulator is accelerating import license processing for finished formulations to address supply gaps. São Paulo's pain treatment centers are standardizing multimodal protocols that combine pharmacotherapy with procedural interventions.
Global Fibromyalgia Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: legacy primary care infrastructure players, differentiated neuroscience R&D specialists, and immunology-extended chronic pain competitors. Large-cap pharmaceutical firms leverage established prescriber relationships and broad distribution networks to defend market position. Mid-cap developers concentrate on novel mechanisms targeting treatment-resistant subpopulations. Competitive moves center on portfolio diversification into adjacent chronic pain conditions and strategic partnerships with specialty clinic networks to secure referral pathway control.
Among the established tier, Pfizer Inc., Eli Lilly and Company, and AbbVie Inc. occupy anchor positions representing distinct competitive archetypes. Pfizer exemplifies the primary care infrastructure model with broad prescriber reach for legacy pain therapies. Eli Lilly sits within the neuroscience R&D specialist category, anchoring its position through differentiated pipelines targeting comorbid mood and sleep symptoms. AbbVie represents the immunology extension archetype, competing by applying expertise from overlapping chronic conditions with shared pathophysiology.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Astellas Pharma Inc. |
| Tonix Pharmaceuticals Holding Corp |
| Aptinyx Inc. |
| Others |
Supply & Pricing Matrix
Air freight corridors connecting Hyderabad and Mumbai to Frankfurt and Chicago determine landed cost spreads for pregabalin and duloxetine APIs, compressing margin buffers for European and North American formulators while amplifying price differentiation between branded and generic finished products.
Pricing Analysis
Hospital procurement managers and specialty clinic networks anchor pricing stratification across premium, standard, and economy tiers. Branded pregabalin and duloxetine formulations command premium positioning through FDA-approved indications and embedded patient support programs, while Indian-sourced generics compete on unit cost for Medicaid and cash-pay populations. Pricing pressure stems from formulary exclusion policies at United States pharmacy benefit managers that favor lowest-cost alternatives. Uninsured patients in Brazil and price-sensitive public hospital systems in India exhibit highest price elasticity, whereas integrated pain management networks in Germany and Australia accept premium tiers for guaranteed supply security.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk calculus for generic formulators dependent on pregabalin API. Active pharmaceutical ingredient production concentrates in Maharashtra and Gujarat states of India, with secondary sourcing from Zhejiang province in China. Manufacturing rests on solvent-dependent chemical synthesis for calcium channel modulators and norepinephrine reuptake inhibitors, with N-methyl-2-pyrrolidone residuals triggering REACH compliance costs for European patch manufacturers. Distribution runs through specialized cold-chain logistics providers serving hospital pharmacies and specialty clinic networks across North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fibromyalgia treatment market sits in early-cycle expansion as PMDA accelerated review pathways and pharmacogenomic reimbursement pilots in Australia and Canada compress trial-and-error prescribing timelines and expand addressable populations beyond historical diagnosis gaps.
For Market Incumbents: Insulate formulary position through backward integration into API supply and preemptive investment in CYP2D6 pharmacogenomic companion diagnostic partnerships. Pfizer's primary care infrastructure and Eli Lilly's neuroscience R&D pipelines face displacement risk from low-dose naltrexone compounding pharmacies and digital therapeutics convergence, requiring defensive patent extension strategies and specialty clinic network exclusivity agreements. For New Entrants and Emerging Players: Treatment-resistant subpopulations in Japan's aging demographic and Brazil's harmonized regulatory environment represent the most penetrable entry points for novel mechanisms targeting glial cell modulation. Tonix Pharmaceuticals and Aptinyx can bypass entrenched prescriber relationships by positioning assets through PMDA accelerated pathways and ANVISA abbreviated approval routes, leveraging local contract manufacturing partnerships to circumvent API import dependence. For Investors and Strategic Acquirers: Mid-cap developers with validated quantitative sensory testing site networks and existing EMA long-term safety databases offer the most defensible acquisition profile for five-to-ten year horizon positioning. The signal to watch is FDA guidance evolution on patient-reported outcome measures, which will determine which therapeutic candidates advance to regulatory submission and reshape competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Testing Integration | Ontario and British Columbia reimbursement pilots shift cost accountability to single-payer systems and compress prescribing cycles. |
| Transdermal Manufacturing Reformulation | Aqueous-based polymer development in Spain and Poland maintains CE-marked device-drug combination status under REACH restrictions. |
| Specialty Clinic Network Partnerships | Cleveland Clinic and Charité Berlin embedded psychology and physical therapy units consolidate referral pathway control. |
| PMDA Accelerated Review Pathway | Japan's 36 million citizens over 65 with fibromyalgia prevalence exceeding 5 percent in women opens demographic tailwind. |
| Digital Therapeutics Convergence | Smartphone-based pain tracking and biofeedback applications create subscription revenue layers alongside traditional drug margins. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors at United States pharmacy benefit managers, and payer access specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates were triangulated to anchor market sizing.
Scenario bracketing around FDA guidance evolution, EMA long-term safety database requirements, and pharmacogenomic reimbursement expansion shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, therapy area, end user, and delivery mode, with regional regulatory clusters modeled separately. CAGRs were derived from patient population growth, diagnosis rate improvements, and therapy line escalation patterns rather than macroeconomic extrapolation.
Stress conditions across API supply disruption, formulary exclusion acceleration, and non-pharmacological substitution endorsement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and reimbursement policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Ketorolac Market
Pain Management
Pain Management Devices Market
Pain Management
Spine Pain Market
Pain Management
Global Chiropractic Care Market
Pain Management
Heat Therapy Market
Pain Management
OTC Painkiller Market
Pain Management
Pain Management Software Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Postoperative Pain Market
Pain Management
Cancer Pain Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Chronic Pain Market
Pain Management
Erythromelalgia Treatment Market