
 Arthralgia Management Market | 2026-2036
Arthralgia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Arthralgia Management Market Outlook
Multi-source API procurement for NSAID and corticosteroid active ingredients is consolidating around qualified suppliers with FDA and EMA audit histories. Pfizer Inc. leverages its vertically integrated manufacturing network to secure raw material continuity for oral analgesic portfolios. Novartis AG anchors its position through specialized rheumatology franchises and sustained investment in disease-modifying antirheumatic drug pipelines. Johnson & Johnson competes across hospital and home care channels with differentiated topical and transdermal delivery platforms.
Arthralgia management encompasses pharmacological and non-pharmacological interventions targeting joint pain of inflammatory, degenerative, or post-traumatic origin, with oral NSAIDs typically formulated as 200-400 mg ibuprofen equivalents or 50 mg diclofenac salts for acute symptom control. The primary commercial purpose centers on reducing pain scores, preserving joint function, and delaying surgical intervention in osteoarthritis and rheumatoid arthritis populations. Analgesics and NSAIDs dominate current prescription volumes, though transdermal delivery modes are capturing faster growth as clinicians seek to minimize systemic exposure and gastrointestinal complications. Injectable corticosteroids retain concentrated margin pools in orthopedics and pain management settings where rapid intra-articular relief commands premium positioning.
FDA opioid prescribing guidelines and EMA pharmacovigilance requirements for NSAID cardiovascular risk labeling are tightening formulation standards and pushing developers toward novel mechanisms with cleaner safety profiles. The WHO Essential Medicines List criteria and national reimbursement formularies in Germany, Japan, and the United States determine market access tiers for new entrants. Stakeholders must monitor evolving non-opioid pain targets and regulatory differentiation between acute and chronic arthralgia indications to align pipeline investments with payer prioritization.
Market Dynamics
FDA opioid prescribing guidelines and EMA pharmacovigilance requirements are compressing demand for conventional analgesics while accelerating investment in non-opioid mechanisms and localized delivery systems. This regulatory pivot is restructuring R&D priorities across the pharmaceutical value chain.
Growth Catalysts
- Aging demographics in Germany, Japan, and the United States:Expanding osteoarthritis and rheumatoid arthritis patient pools sustain chronic pain management demand and reimbursement continuity for disease-modifying therapies.
- EMA accelerated approval pathways for non-opioid analgesics:Compressed regulatory timelines incentivize developers to prioritize novel mechanisms with cardiovascular and gastrointestinal safety advantages over traditional NSAIDs.
- Biologic-sparing protocols in rheumatology clinics:Oral small-molecule JAK inhibitors and targeted synthetic DMARDs are capturing patient volumes previously directed toward injectable biologics, expanding addressable markets for oral formulations.
Market Restraints
- API supply concentration in India and China:Multi-source procurement for ibuprofen, diclofenac, and corticosteroid actives faces qualification bottlenecks as FDA and EMA audit backlogs delay new supplier entry.
- Cardiovascular risk labeling mandates:EMA requirements for NSAID cardiovascular warnings and FDA boxed warning expansions constrain prescribing latitude in hypertensive and coronary artery disease populations.
- Generic erosion of oral NSAID franchises:Patent expirations for celecoxib and meloxicam formulations have compressed branded pricing power in primary care channels.
Strategic Opportunities
- Transdermal delivery platform expansion:Topical diclofenac patches and lidocaine formulations command premium positioning in orthopedics and sports medicine by minimizing systemic exposure.
- Japan's super-aged society and METI chronic disease management incentives:Government reimbursement for home-based pain monitoring creates demand for patient-administered non-opioid interventions.
- Digital therapeutics integration with pharmacological regimens:FDA breakthrough device designation pathways enable software-based cognitive behavioral therapy adjuncts to capture formulary slots alongside traditional analgesics.
Industry Challenges
- Specialized formulation expertise scarcity:Transdermal and intra-articular depot development requires polymer science and controlled-release capabilities concentrated among limited contract development organizations.
- Reimbursement evidence generation timelines:Payers in Germany's G-BA and Japan's Chuikyo demand head-to-head non-inferiority data against standard-of-care NSAIDs, extending commercialization cycles.
- Legacy manufacturing asset reconfiguration:Oral solid dose capacity must retrofit for continuous manufacturing and real-time release testing to meet FDA quality metrics guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthralgia Management Market |
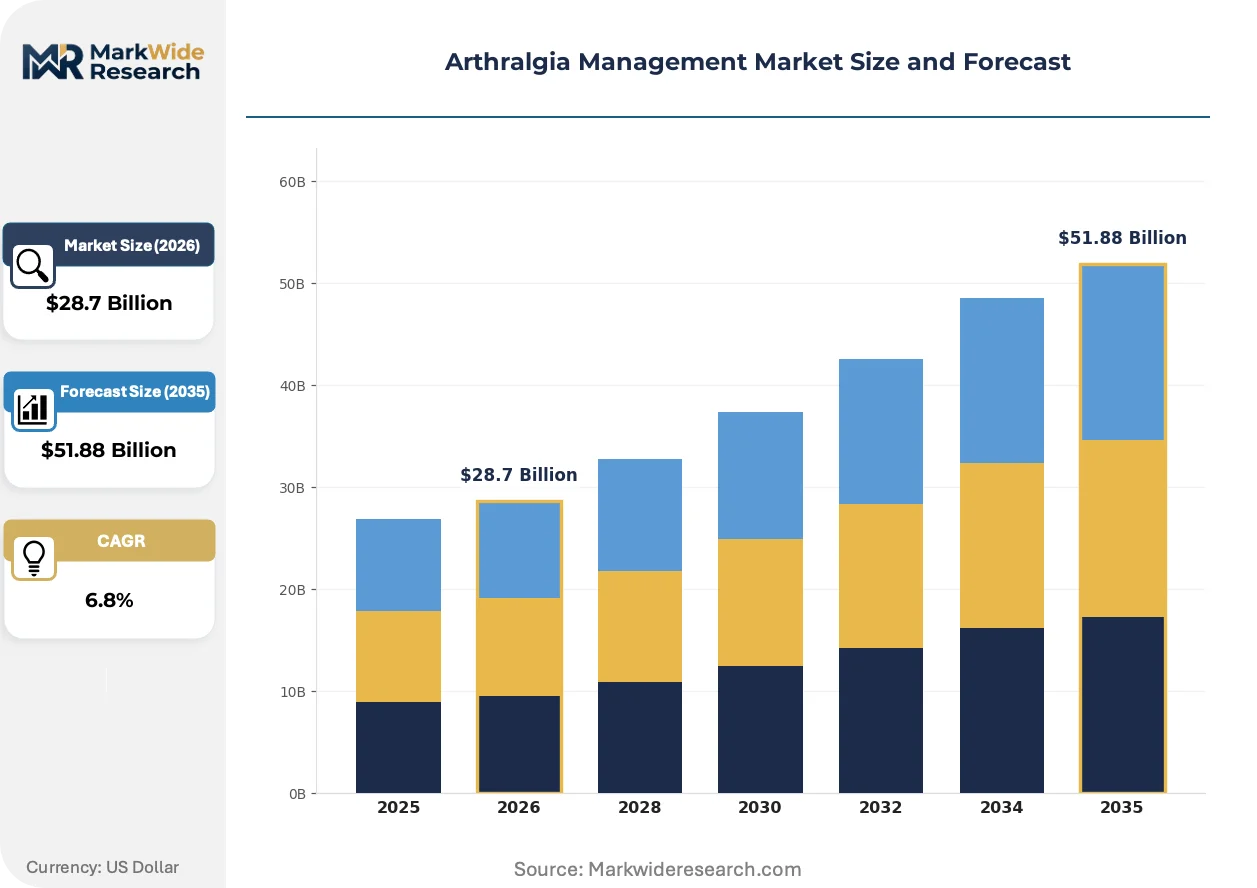
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, NSAIDs, Corticosteroids, Disease-Modifying Antirheumatic Drugs Delivery Mode: Oral, Topical, Injectable, Transdermal Therapy Area: Rheumatology, Orthopedics, Pain Management, Rehabilitation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Novartis AG, GlaxoSmithKline plc, Sanofi, Boehringer Ingelheim, AstraZeneca, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthralgia Management Market Strategic Shifts
Novel non-opioid mechanisms and localized drug delivery are displacing systemic analgesia as the default therapeutic paradigm. Developers are prioritizing tissue-specific targeting to circumvent the safety liabilities that have constrained conventional NSAID growth.
Transdermal iontophoresis and microneedle arrays for intra-articular corticosteroid delivery are rewriting the competitive map in orthopedics. Academic medical centers in the United States and specialized rheumatology clinics in Germany are piloting these platforms for post-arthroscopy pain management. The technology is compressing hospital length-of-stay metrics while creating premium pricing tiers distinct from generic oral alternatives.
EMA's tightened cardiovascular risk assessment requirements for NSAID renewals are forcing reformulation investments across the European Union. Manufacturers must now generate long-term safety data for existing products to maintain market authorization. Small-cap developers without legacy portfolio exposure are capturing EMA scientific advice slots to position novel COX-2 selective inhibitors ahead of incumbent re-registration cycles.
Hospital formulary committees are unbundling analgesic procurement from surgical supply contracts, creating direct purchasing relationships with specialty pharmaceutical manufacturers. This disintermediation of group purchasing organizations is most advanced in United States health systems with captive insurance plans. German hospital networks are replicating the model through regional procurement cooperatives that negotiate indication-specific contracts rather than broad therapeutic class agreements.
Arthralgia Management Market Segmentation
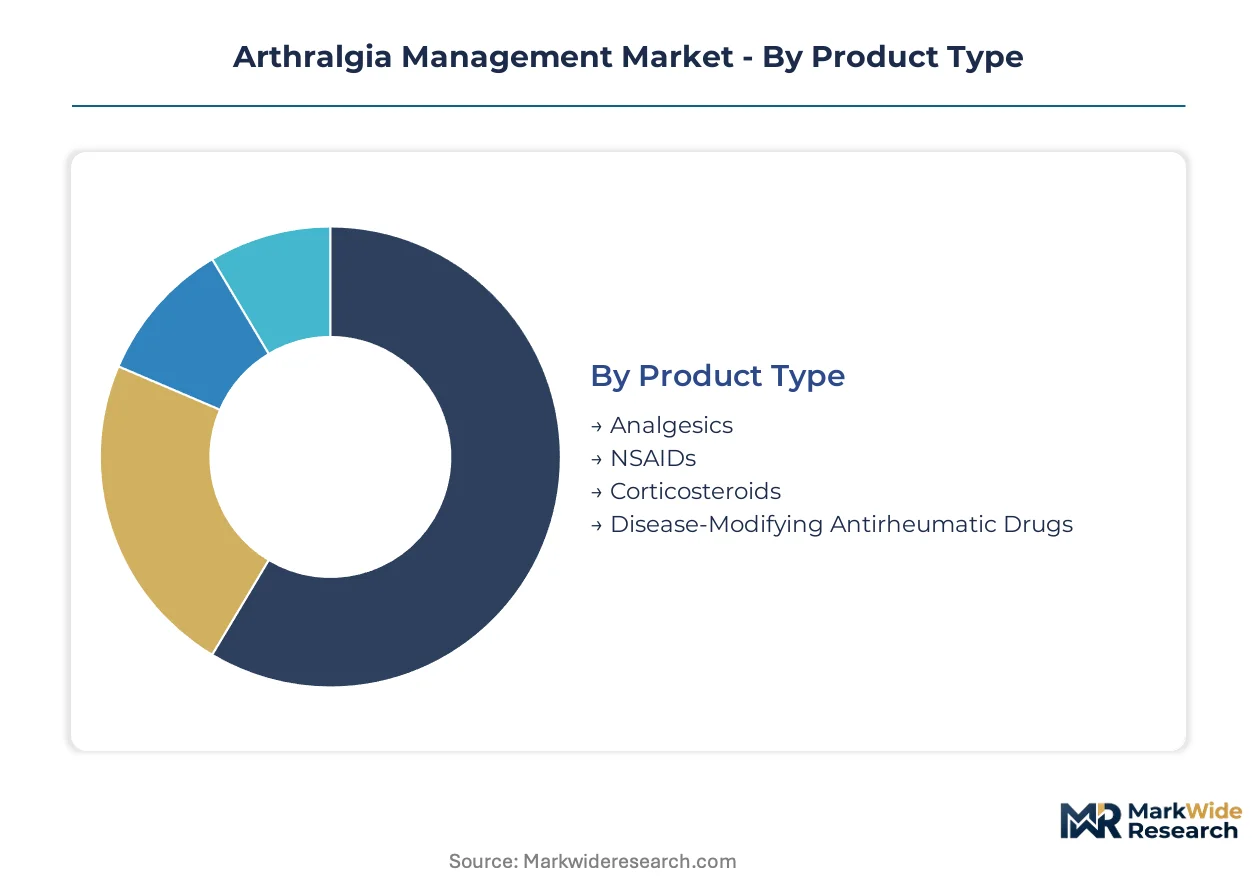
Arthralgia management markets stratify across therapeutic mechanism, delivery technology, clinical specialty, and care setting. Each dimension carries distinct margin profiles, regulatory pathways, and competitive intensity that shape portfolio allocation decisions.
Product Type:
Replacement cycles in arthralgia pharmacology accelerate as cardiovascular safety labeling erodes confidence in legacy NSAID platforms.
- Analgesics:Non-opioid oral formulations including acetaminophen and tramadol combinations address mild-to-moderate joint pain in primary care settings. Demand concentrates in United States Medicare populations where opioid avoidance protocols drive formulary preference for non-controlled alternatives.
- NSAIDs:Oral and topical formulations of ibuprofen, diclofenac, and naproxen dominate prescription volumes for acute inflammatory flares. EMA cardiovascular risk labeling mandates and FDA boxed warning expansions constrain prescribing latitude in hypertensive populations, compressing growth in Germany and United States hospital formularies.
- Corticosteroids:Intra-articular depot injections of triamcinolone and methylprednisolone command premium positioning in orthopedics.
- Disease-Modifying Antirheumatic Drugs:Oral JAK inhibitors and biologic agents target disease progression in rheumatoid arthritis populations.
NSAIDs sit at the top of the volume ranking, with Disease-Modifying Antirheumatic Drugs climbing the fastest.
Delivery Mode:
Cost tier differentiation separates commodity oral solids from premium localized delivery platforms requiring specialized manufacturing capabilities.
- Oral:Immediate-release and extended-release tablets and capsules constitute the baseline cost tier, manufactured through high-volume solid dose processes. United States and German primary care channels drive volume, though generic erosion has compressed branded pricing power across ibuprofen and naproxen franchises.
- Topical:Gels, creams, and patches deliver diclofenac and lidocaine directly to affected joints with minimized systemic exposure. Orthopedics and sports medicine clinics in Japan and United States health systems prioritize these formulations for post-arthroscopy protocols.
- Injectable:Intra-articular corticosteroid suspensions and hyaluronic acid formulations require sterile manufacturing and cold chain distribution.
- Transdermal:Iontophoresis and microneedle array technologies enable controlled drug release through intact skin.
Oral formulations retain volume leadership, while Transdermal platforms gain share fastest on safety differentiation.
Therapy Area:
Application concentration varies by clinical specialty, with rheumatology driving biologic utilization and orthopedics anchoring procedural pain protocols.
- Rheumatology:Systemic immunomodulation for inflammatory arthropathies including rheumatoid arthritis, psoriatic arthritis, and ankylosing spondylitis. Academic medical centers in Germany and Japan prioritize biologic-sparing protocols using JAK inhibitors to reduce infusion center burden.
- Orthopedics:Post-surgical and degenerative joint pain management in hip, knee, and shoulder populations. United States ambulatory surgery centers drive demand for rapid-onset intra-articular interventions that compress length-of-stay metrics.
- Pain Management:Multimodal approaches integrating pharmacological and interventional techniques for chronic joint pain.
- Rehabilitation:Adjunctive pharmacotherapy supporting physical therapy protocols for functional recovery.
Rheumatology leads by revenue concentration, with Orthopedics expanding most quickly on procedural volume growth.
End User:
Customer type determines procurement modality, with hospitals consolidating purchasing power and home care opening direct-to-patient channels.
- Hospitals:Inpatient and surgical settings requiring formulary-standardized analgesic protocols for joint replacement and arthroscopy procedures. United States health systems with captive insurance plans increasingly disintermediate group purchasing organizations for direct manufacturer negotiation.
- Clinics:Outpatient rheumatology and pain management practices prescribing maintenance therapy for chronic conditions. German regional procurement cooperatives negotiate indication-specific contracts for these settings.
- Home Care:Patient-administered oral and topical formulations supported by remote monitoring technologies.
- Rehabilitation Centers:Post-acute facilities integrating pharmacological adjuncts with physical therapy protocols.
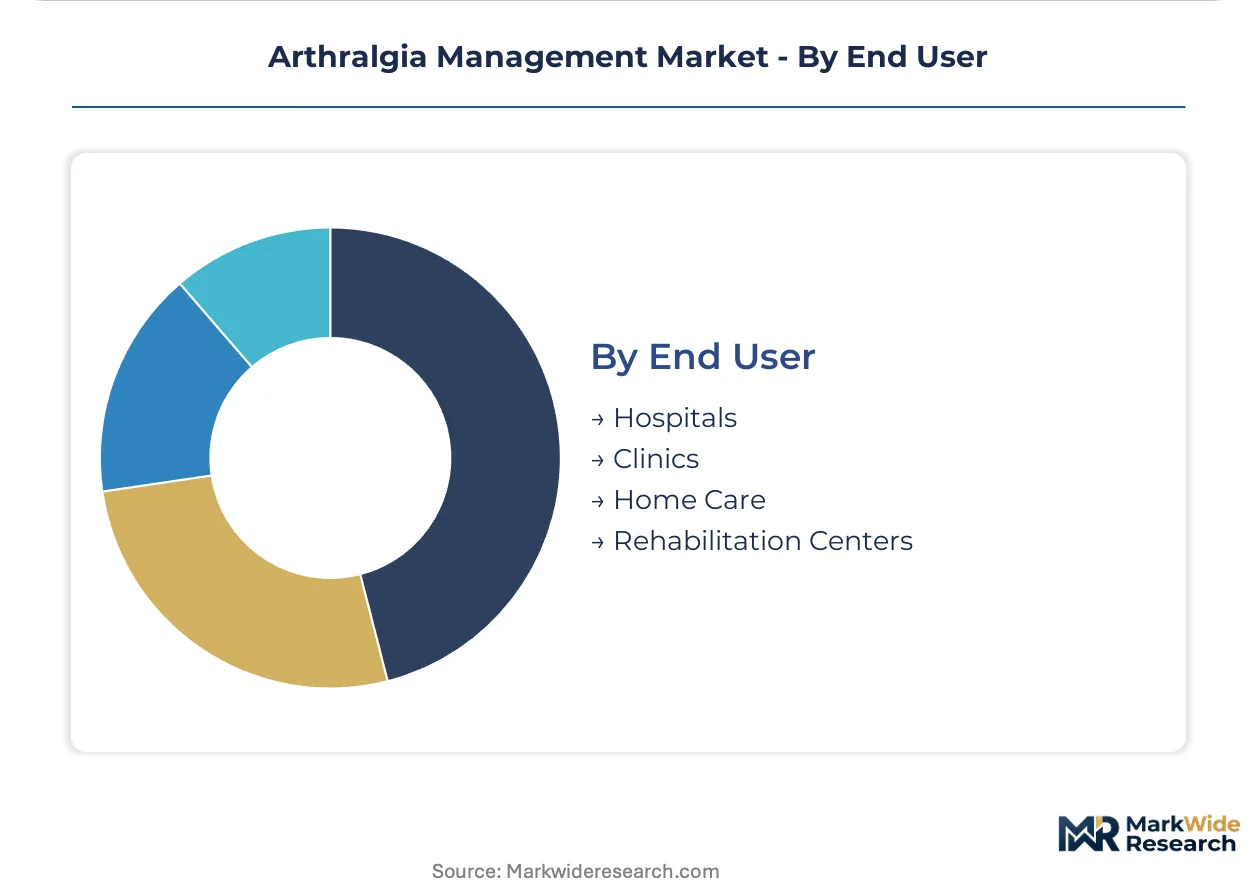
Hospitals dominate procurement volume, with Home Care gaining traction fastest on Japan's METI chronic disease management incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors pharmaceutical innovation in arthralgia therapeutics, hosting specialized contract research organizations that accelerate clinical trial timelines for novel non-opioid mechanisms. Market demand concentrates in aging societies with established chronic pain reimbursement frameworks.
United States
Medicare Part D formularies and commercial payer opioid restriction protocols drive demand for non-controlled analgesic alternatives in osteoarthritis populations. The FDA breakthrough therapy designation pathway compresses development timelines for JAK inhibitors targeting rheumatoid arthritis. The Research Triangle Park cluster in North Carolina hosts specialized pharmacovigilance operations monitoring cardiovascular safety signals for NSAID portfolios.
Germany
The G-BA benefit assessment framework determines reimbursement tiers for new arthralgia interventions entering Europe's largest pharmaceutical market. EMA centralized procedures for NSAID cardiovascular risk labeling mandate long-term safety database maintenance by marketing authorization holders. The Rhine-Main region around Frankfurt concentrates pharmacoeconomic modeling consultancies that generate health technology assessment submissions for innovative analgesics.
Japan
METI chronic disease management incentives expand home-based pain monitoring infrastructure for the super-aged population. PMDA sakigake designation accelerates regulatory review for novel mechanisms addressing unmet needs in refractory joint pain. The Kansai pharmaceutical manufacturing belt around Osaka maintains specialized capacity for transdermal patch formulations serving domestic and export markets.
United Kingdom
NICE technology appraisals set cost-effectiveness thresholds that determine NHS England commissioning decisions for biologic and targeted synthetic DMARDs. The MHRA post-Brexit recognition framework maintains parallel EMA regulatory alignment for arthralgia therapeutics seeking dual market access. The Golden Triangle cluster spanning London, Oxford, and Cambridge hosts early-phase clinical units specializing in inflammatory arthritis biomarker development.
India
CDSCO accelerated approval pathways for fixed-dose NSAID combinations address domestic demand from the expanding osteoarthritis patient pool. The country's national pharmaceutical regulator mandates bioequivalence documentation for generic diclofenac and ibuprofen formulations entering the market. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient manufacturing for corticosteroid intermediates supplying European and North American formulation facilities.
Arthralgia Management Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue localized delivery technologies and digital therapeutics integration. The market structure reflects moderate consolidation among multinational pharmaceutical corporations with legacy pain franchises, while specialized biotechnology developers capture niche segments through mechanism differentiation. Three archetypes dominate: vertically integrated incumbents with manufacturing network control, mid-cap specialists in transdermal and intra-articular platforms, and digital health developers seeking adjunctive therapy positioning. Competitive intensity centers on portfolio diversification into biologic-sparing protocols and strategic partnerships with hospital systems for formulary access.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Novartis AG, and Johnson & Johnson exemplify distinct strategic positions within the arthralgia management value chain. Pfizer occupies a position anchored by manufacturing network control over oral analgesic supply continuity. Novartis represents the specialized rheumatology franchise archetype with sustained pipeline investment in disease-modifying mechanisms. Johnson & Johnson sits within the delivery technology differentiation tier, competing across hospital and home care channels with topical and transdermal platforms. These three entities collectively illustrate the competitive spectrum from upstream API security through clinical specialization to patient-administered modality innovation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi |
| Boehringer Ingelheim |
| AstraZeneca |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Continuous manufacturing adoption for oral solid dose analgesics is compressing unit economics while concentrating API procurement power among qualified suppliers with FDA and EMA audit histories. This production-method transition simultaneously reduces per-tablet costs and raises barriers for new entrants lacking legacy supplier relationships.
Pricing Analysis
API cost pass-through from ibuprofen and diclofenac active ingredient markets governs margin dynamics across oral NSAID tiers. Three-tier pricing structure across premium, standard, and economy levels separates patented JAK inhibitors from branded NSAID formulations and commodity generics. Pricing pressure stems from generic erosion of oral NSAID franchises in United States and German primary care channels. Hospital procurement committees exhibit lowest price sensitivity for intra-articular corticosteroid depots, while Medicare Part D plans drive aggressive rebate negotiations for maintenance oral therapies.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceutical manufacturing are reshaping sourcing patterns for corticosteroid intermediates and NSAID actives. Supply concentration rests on India and China for ibuprofen, diclofenac, and corticosteroid APIs, with United States maintaining specialized capacity for controlled-release formulations. Raw material dependencies include ketoprofen intermediates, naproxen sodium salts, and hyaluronic acid derivatives. Single-source vulnerability characterizes the transdermal polymer supply tier. Distribution runs through regional hospital procurement cooperatives in Germany and United States health systems with direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arthralgia management market represents a late-cycle quality story as patient volumes shift toward biologic-sparing protocols demanding higher-specification oral small-molecule formulations.
For Market Incumbents: Anticipate formulary displacement of legacy NSAIDs by novel non-opioid mechanisms with cleaner cardiovascular profiles. Anchor backward integration into corticosteroid API supply to defend margin position against Indian and Chinese supplier qualification bottlenecks. Prioritize certification investment for continuous manufacturing platforms to meet FDA quality metrics guidance. For New Entrants and Emerging Players: Begin with Japan's home-based pain monitoring infrastructure, where METI incentives create reimbursement pathways for patient-administered non-opioid interventions. Target transdermal delivery platform development for orthopedics and sports medicine clinics seeking systemic exposure minimization. Pursue FDA breakthrough device designation for digital therapeutic adjuncts to capture formulary slots alongside pharmacological regimens. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap transdermal specialists lacking hospital system partnerships but possessing polymer science capabilities. Long-term viability hinges on positioning within biologic-sparing rheumatology protocols over the next decade. Watch EMA scientific advice slot allocation to novel COX-2 selective inhibitors as the inflection signal for incumbent re-registration cycle disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA accelerated approval for non-opioid analgesics compresses development timelines versus standard NSAID re-registration. |
| Manufacturing Scale-Up | Continuous manufacturing retrofit for oral solid dose capacity aligns with FDA quality metrics guidance and reduces per-unit costs. |
| Pipeline Diversification | JAK inhibitor investment captures rheumatology patient volumes shifting from injectable biologics to oral small-molecule alternatives. |
| Strategic Partnership | Direct contracts with United States health systems bypass group purchasing organization intermediation and secure formulary access. |
| Licensing Agreement | Transdermal iontophoresis technology licensing from academic medical centers enables premium positioning in post-arthroscopy protocols. |
Study Parameters
Coverage spans the United States, Germany, Japan, and India, with primary inputs from each market cluster. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing triangulate to produce convergent estimates.
Granularity-level framing applies treatment line, dosage form, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs derive from epidemiological trend extrapolation, pricing trajectory analysis, and therapy substitution elasticity modeling. Forecast inputs incorporate rheumatology clinic patient volume data, biologic-sparing protocol adoption curves, and transdermal delivery platform penetration assumptions.
Several conditions sit outside the modeled scope, including patent litigation outcomes, unforeseen regulatory safety withdrawals, and macroeconomic disruptions to API trade flows. Forecasts reflect documented assumptions regarding reimbursement continuity and regulatory pathway stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cancer Pain Management Market
Pain Management
Global Pain Management Market
Pain Management
Global Chiropractic Care Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Chronic Pain Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Cold Pain Therapy Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Spine Pain Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Pain Therapeutic Injectables Market