
 Global Surgical Scissors Market | 2026-2036
Global Surgical Scissors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Scissors Market Foresight
The EU Medical Device Regulation is consolidating the cost-of-entry calculus for surgical scissors manufacturers seeking CE marking in European markets. B. Braun Melsungen AG leverages its vertically integrated German manufacturing base to sustain compliance economies that smaller rivals cannot match. Stryker Corporation anchors its position through R&D intensity focused on advanced metallurgy for extended instrument life cycles.
Surgical scissors are precision cutting instruments manufactured from hardened stainless steel, titanium, or tungsten carbide alloys, typically featuring ring handles and tapered blades ground to specific angles for tissue dissection or suture cutting in sterile operative fields. The material dimension shows stainless steel dominating hospital procurement budgets while titanium variants command premium positioning in microsurgical applications where reduced hand fatigue matters. Operating scissors and micro scissors represent the fastest-growing type categories as ophthalmic and neurological procedures expand in specialized surgical centers.
The FDA enforces 510(k) clearance pathways for reusable surgical instruments while ISO 13485 quality management standards govern manufacturing consistency across export-oriented suppliers. Japan's PMDA and South Korea's MFDS maintain parallel registration frameworks that shape market access timelines for Western manufacturers. Stakeholders must monitor how evolving sterilization validation requirements from regulators in China and India will reshape sourcing strategies for high-volume instrument categories.
Market Dynamics
The EU Medical Device Regulation is compressing manufacturer margins while simultaneously consolidating procurement authority within hospital systems, creating a bifurcation between compliance-capable suppliers and price-competitive challengers.
Growth Catalysts
- Minimally invasive procedure expansion:Ambulatory surgery centers in Germany and the United States are retrofitting suites with micro scissors and dissecting instruments optimized for laparoscopic and endoscopic workflows.
- EMA sterilization validation protocols:Tighter reprocessing standards under the EU MDR are accelerating replacement cycles for reusable metal instruments in French and Italian hospital networks.
- Titanium alloy metallurgy:Reduced instrument weight is extending surgeon operative stamina in ophthalmic and neurological microsurgery suites across Japan and South Korea.
Market Restraints
- Tungsten carbide input volatility:Mining concentration in select geographies creates price instability for premium blade tip materials essential to extended-use instruments.
- FDA 510(k) pathway friction:Incremental device modifications now trigger substantial equivalence reviews that extend time-to-revenue for iterative product improvements.
- Single-use polymer substitutes:Disposable scissor alternatives in emergency and field medicine applications are capturing volume in cost-constrained procurement environments.
Strategic Opportunities
- India CDSCO registration acceleration:Streamlined medical device import pathways are opening private hospital procurement channels in Mumbai and Delhi surgical clusters.
- Robotic surgical system integration:Instrument interfaces compatible with da Vinci and competitor platforms represent attach-rate expansion potential in tertiary care centers.
- ISO 13485 certification arbitrage:Quality management standardization is enabling mid-tier manufacturers to access previously restricted Western European distributor networks.
Industry Challenges
- CE marking technical documentation:Clinical evaluation report requirements under MDR Article 61 are consuming 18-24 month compliance timelines for legacy product portfolios.
- Autoclave-compatible coating durability:Surface treatment technologies must survive thousands of sterilization cycles without degradation, constraining material science innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Scissors Market |
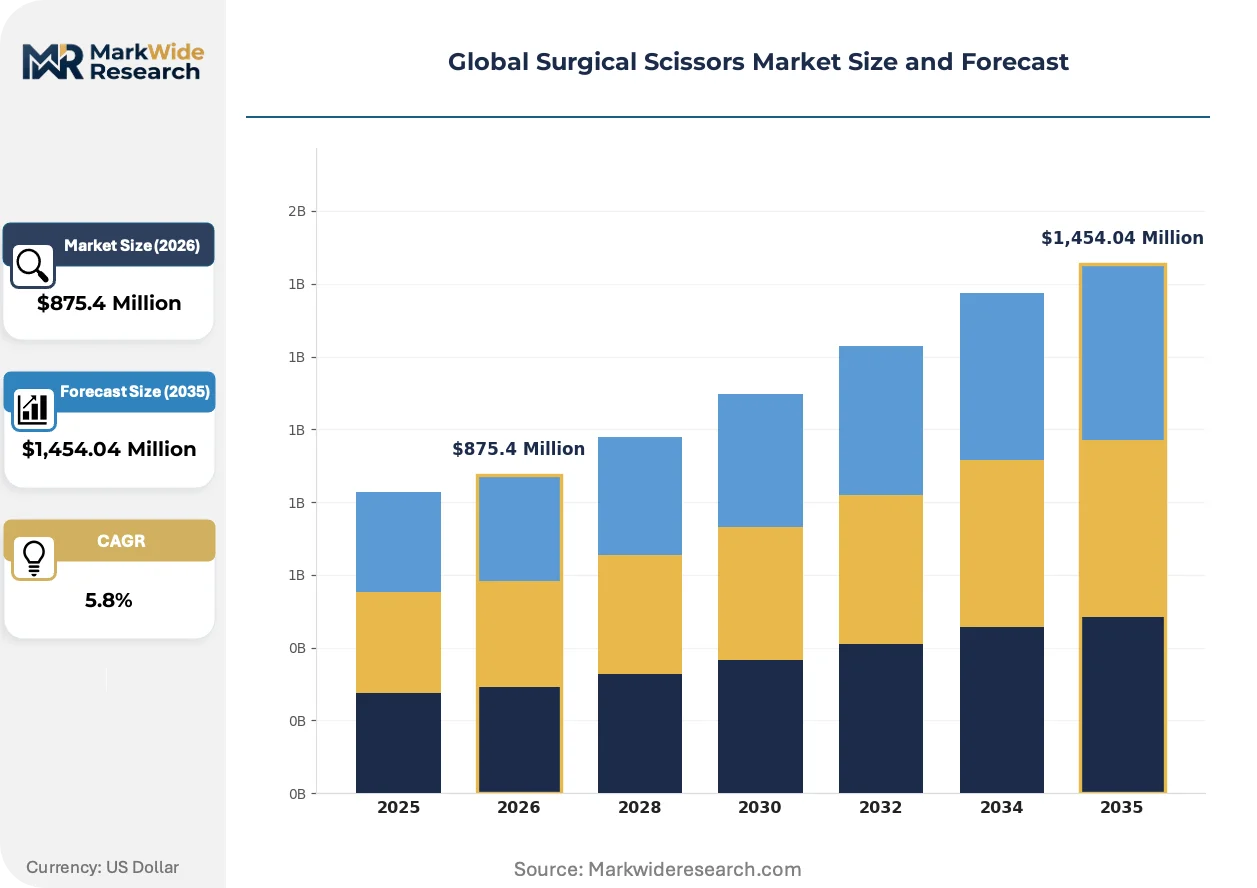
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,454.04 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard, Micro, Operating, Suture, Dissecting, Bandage Material: Stainless Steel, Titanium, Carbon Steel, Ceramic, Tungsten Carbide Application: Cardiac Surgery, Neurological Procedures, Ophthalmic Surgery, Plastic Surgery, Dental Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Laboratories |
| Companies Covered | B. Braun Melsungen AG, Stryker Corporation, Arthrex, Inc., Scanlan International, BD, Teleflex Incorporated, Integra LifeSciences Corporation, Olympus Corporation, Purple Surgical International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Scissors Market Shifts & Advancements
Precision manufacturing and regulatory harmonization are compressing product development timelines while elevating performance benchmarks for cutting edge retention and ergonomic design.
Superelastic nickel-titanium alloys are unifying shape-memory properties with traditional stainless steel durability in micro scissors destined for neurovascular procedures. German and Swiss instrument manufacturers are adopting these materials for aneurysm clipping and microvascular anastomosis suites. The technology is unifying previously separate instrument categories into modular platforms that reduce hospital SKU complexity.
Japan's PMDA revised medical device registration guidelines are mandating biocompatibility testing expansion for instruments contacting mucosal membranes. Domestic manufacturers in Osaka and Tokyo surgical instrument clusters are absorbing additional validation costs into premium pricing tiers. Ophthalmic scissors with extended blade profiles are experiencing the longest review backlogs as regulators scrutinize corneal incision safety profiles.
Hospital procurement departments are consolidating vendor panels around full-line surgical instrument suppliers capable of meeting ISO 17664 reprocessing documentation requirements. Independent German distributors serving ambulatory surgery centers are losing shelf space to manufacturer-direct service contracts. The compression is most visible in Bavaria and North Rhine-Westphalia where hospital procurement cooperatives negotiate system-wide pricing agreements.
Global Surgical Scissors Market Segmentation
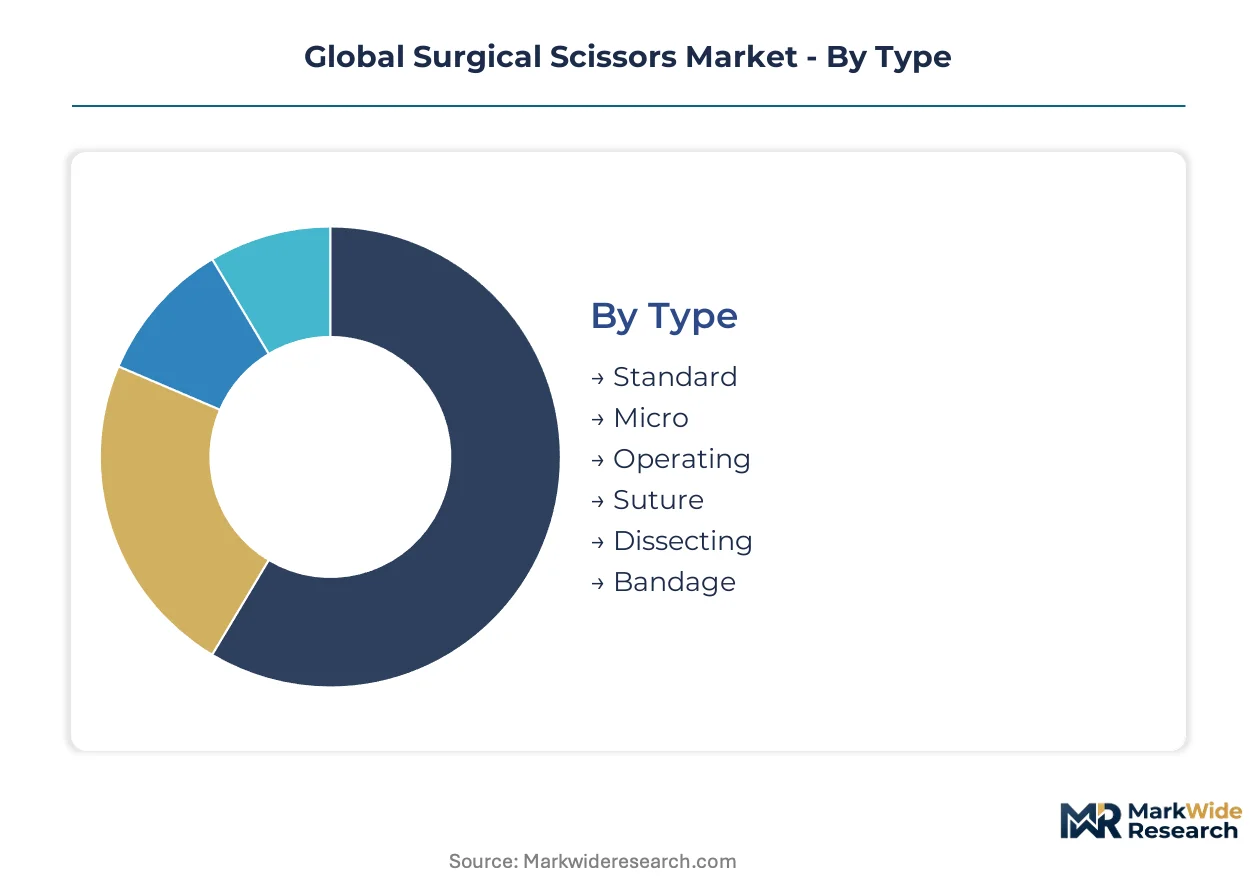
Surgical scissors segmentation reveals divergent compliance burdens across material grades and end-use settings. FDA 510(k) pathways vary by blade geometry while EU MDR clinical evaluation requirements intensify for instruments destined for sterile body cavities.
Type:
Scissor type determines regulatory pathway complexity: micro and operating variants face heightened sterilization validation under EMA protocols, while standard and bandage categories navigate lighter conformity assessments.
- Standard:General-purpose ring-handled instruments for tissue cutting and suture removal in open procedures. German hospital procurement cooperatives in Bavaria favor these for high-volume general surgery suites where replacement cycles align with autoclave reprocessing schedules.
- Micro:Fine-tipped instruments with reduced blade mass for ophthalmic and neurovascular dissection. Japanese PMDA review timelines extend longest for these variants as regulators scrutinize corneal incision safety profiles in Tokyo and Osaka surgical clusters.
- Operating:Robust construction for dense tissue cutting in abdominal and thoracic procedures.
- Suture:Blunt-tipped variants optimized for stitch removal without tissue trauma.
- Dissecting:Tapered blades for precise tissue plane separation in plastic and reconstructive workflows.
- Bandage:Utility-grade instruments for dressing changes and non-sterile applications.
Leading the category by volume: Standard. Growing fastest: Micro.
Material:
Material selection drives cost tier stratification and determines reprocessing durability thresholds under ISO 17664 documentation requirements.
- Stainless Steel:Martensitic and austenitic grades dominate hospital procurement budgets with proven autoclave compatibility across thousands of cycles. French and Italian hospital networks specify this grade for reusable instrument portfolios subject to EU MDR technical documentation.
- Titanium:Reduced density extends surgeon operative stamina in microsurgical applications. South Korean MFDS-registered variants command premium positioning in Seoul neurological centers where hand fatigue reduction justifies procurement outlays.
- Carbon Steel:Higher hardness enables sharper edge retention in disposable instrument categories.
- Ceramic:Non-metallic composition eliminates MRI interference in specialized surgical environments.
- Tungsten Carbide:Carbide insert tips extend cutting edge longevity in high-throughput cardiac surgery suites.
Stainless steel captures dominant procurement volume. Titanium demonstrates steepest expansion trajectory in microsurgical segments.
Application:
Procedure-specific risk profiles shape biocompatibility testing expansion under Japan's revised PMDA guidelines for mucosal-contacting instruments.
- Cardiac Surgery:Sternum shears and vascular scissors require carbide-reinforced edges for calcified tissue penetration. Mumbai and Delhi private hospital clusters drive import demand for CDSCO-registered cardiac instrument sets.
- Neurological Procedures:Superelastic nickel-titanium alloys enable aneurysm clipping and microvascular anastomosis in German and Swiss manufacturing clusters. These instruments unify shape-memory properties with traditional durability.
- Ophthalmic Surgery:Extended blade profiles face prolonged regulatory review due to corneal safety scrutiny.
- Plastic Surgery:Dissecting scissors with fine taper ratios support aesthetic tissue plane development.
- Dental Surgery:Crown and bridge scissors navigate lighter regulatory pathways for non-sterile applications.
Cardiac surgery anchors procurement volume. Neurological procedures gain share fastest.
End User:
Customer type determines service contract complexity: hospital systems negotiate manufacturer-direct agreements while ambulatory centers rely on distributor networks.
- Hospitals:Tertiary care centers in North Rhine-Westphalia consolidate vendor panels around full-line suppliers capable of ISO 17664 reprocessing documentation. System-wide pricing agreements compress independent distributor margins.
- Ambulatory Surgery Centers:German ASCs in Bavaria retrofit suites with micro scissors optimized for laparoscopic workflows. Stricter EU MDR sterilization protocols accelerate instrument replacement cycles.
- Specialty Clinics:Ophthalmic and dental practices favor procedure-specific instrument sets over general surgery portfolios.
- Diagnostic Laboratories:Specimen processing scissors occupy lower regulatory classification tiers.
Hospitals dominate procurement volume. Ambulatory surgery centers expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement in Germany absorbs the largest share of precision surgical instrument imports, while ambulatory surgery centers in the United States and Japan drive incremental demand for microsurgical variants. Regulatory divergence between the FDA, EU MDR, and Japan's PMDA creates distinct compliance cost structures that reshape competitive positioning across manufacturing clusters.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia are retrofitting suites with micro scissors optimized for laparoscopic workflows. The EU Medical Device Regulation imposes 18-24 month clinical evaluation timelines for legacy instrument portfolios. Tuttlingen and Solingen surgical instrument clusters sustain vertical manufacturing integration that smaller rivals cannot replicate.
United States
Tertiary care centers consolidate vendor panels around full-line suppliers capable of ISO 17664 reprocessing documentation. FDA 510(k) clearance pathways for reusable instruments now trigger substantial equivalence reviews for incremental modifications. Minneapolis and Boston surgical device corridors anchor R&D intensity in advanced metallurgy for extended instrument life cycles.
Japan
Ophthalmic and neurological microsurgery suites in Tokyo and Osaka command premium titanium variants where reduced hand fatigue justifies procurement outlays. PMDA revised guidelines mandate expanded biocompatibility testing for instruments contacting mucosal membranes. Extended blade profiles face prolonged regulatory review due to corneal incision safety scrutiny.
India
Private hospital clusters in Mumbai and Delhi drive import demand for CDSCO-registered cardiac instrument sets. Streamlined medical device import pathways are opening procurement channels previously restricted to domestic suppliers. Ahmedabad and Chennai manufacturing zones absorb ISO 13485 certification costs to access Western European distributor networks.
South Korea
Seoul neurological centers prioritize titanium alloy instruments that extend surgeon operative stamina in microsurgical applications. MFDS registration frameworks shape market access timelines for Western manufacturers seeking premium positioning. Busan-Ulsan surgical instrument clusters specialize in superelastic nickel-titanium alloys for neurovascular procedures.
Global Surgical Scissors Market Competitive Landscape
German producers anchor the premium tier through vertically integrated manufacturing bases that sustain EU MDR compliance economies; United States specialists hold scale advantages in R&D-intensive metallurgy segments. The vendor structure bifurcates between full-line surgical instrument suppliers capable of system-wide hospital contracts and regional fabricators serving ambulatory surgery centers through distributor networks. Three archetypes dominate: integrated German manufacturers with captive steel processing, United States-based technology licensors focused on advanced alloys, and Asian contract manufacturers absorbing ISO certification costs to access export markets. Competitive moves concentrate on M&A to consolidate reprocessing documentation capabilities and strategic partnerships with robotic surgical platform developers.
Within the integrated manufacturing tier, B. Braun Melsungen AG exemplifies the vertically structured archetype that compliance-heavy regulatory environments favor. Stryker Corporation occupies a position representing R&D-intensive metallurgy specialists. Among precision instrument fabricators, Scanlan International and Arthrex, Inc. sit within the specialized tier serving procedure-specific surgical workflows.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Stryker Corporation |
| Arthrex, Inc. |
| Scanlan International |
| BD |
| Teleflex Incorporated |
| Integra LifeSciences Corporation |
| Olympus Corporation |
| Purple Surgical International |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidations in Germany and the United States are compressing vendor panels and forcing suppliers to absorb reprocessing documentation costs into pricing structures. This demand-side concentration rewards manufacturers with captive steel processing and ISO 17664 certification capabilities while marginalizing distributor-dependent competitors.
Pricing Analysis
Volume procurement by hospital systems concentrates in stainless steel standard scissors, while titanium micro variants sustain premium positioning through reduced surgeon fatigue claims. Price differentiation hinges on EU MDR certification tier and autoclave cycle durability guarantees, with German tertiary centers least sensitive and Indian private hospitals most price-responsive. Cost compression in the standard tier intensifies as CDSCO-registered imports from Ahmedabad and Chennai manufacturing zones expand.
Supply Chain Analysis
Workforce availability in Solingen and Tuttlingen sustains Germany's precision grinding expertise, while Busan-Ulsan clusters in South Korea feed superelastic alloy production. Raw material supply draws from Swedish stainless steel mills, Chinese tungsten carbide processors, and Japanese titanium refiners. Single-source vulnerability concentrates in carbide insert tips essential for cardiac surgery instruments. Distribution runs through manufacturer-direct service contracts with North Rhine-Westphalia hospital cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance timelines are consolidating surgical scissors manufacturing into vertically integrated players capable of sustaining 18-24 month clinical evaluation investments. Smaller fabricators without captive metallurgy operations face forced exit or acquisition.
For Market Incumbents: Hedge against single-use polymer substitution by embedding reprocessing service contracts into hospital system agreements. Deepen backward integration into nickel-titanium alloy production to secure superelastic supply for neurovascular portfolios. Prioritize robotic surgical platform interface development with da Vinci-compatible instrument attach rates. For New Entrants and Emerging Players: The mid-tier pricing gap between B. Braun's premium German manufacturing and Indian ISO 13485-certified economy producers offers white-space entry. Target CDSCO-registered cardiac instrument sets for Mumbai and Delhi private hospital clusters. Pursue distributor partnerships with Bavarian ambulatory surgery centers retrofitting laparoscopic suites. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with incomplete EU MDR technical documentation facing liquidity pressure. Long-term viability centers on acquiring reprocessing documentation capabilities and sterilization validation expertise. Watch FDA 510(k) substantial equivalence review backlogs as inflection signal for iterative product improvement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 61 compliance unlocks Bavaria and North Rhine-Westphalia hospital procurement. |
| Hospital System Partnership | Manufacturer-direct contracts with German cooperatives displace independent distributor networks. |
| Backward Integration | Captive steel processing in Solingen sustains margin against tungsten carbide price volatility. |
| Software Companion Development | Instrument tracking systems satisfy ISO 17664 reprocessing documentation requirements. |
| Reimbursement Strategy | PMDA biocompatibility validation supports premium positioning in Tokyo ophthalmic centers. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and regulatory submission records underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and surgical instrument distributors combined with secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and CDSCO registration databases. Bottom-up instrument shipment analysis and top-down healthcare expenditure triangulation anchored volume estimates.
Rate-of-change decomposition across the analysis window applied procedure volume growth, instrument replacement cycle compression, and regulatory compliance cost absorption. Segmentation modeling incorporated scissor type, material grade, application specialty, and end-user setting dimensions. CAGR derivation rested on hospital capital expenditure patterns and ambulatory surgery center expansion trajectories, with sterilization protocol tightening and minimally invasive procedure adoption as primary forecast inputs.
Inputs from PMDA review timelines and EMA sterilization validation protocols were available through the study window; gaps in private hospital procurement data from tier-2 Indian cities introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory harmonization pace and raw material price stability. Material deviation in EU MDR enforcement intensity or tungsten carbide supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Surgical Rasps Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market