
 Veterinary Ultrasound Market | 2026-2036
Veterinary Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Ultrasound Market Outlook
Buyer concentration among corporate veterinary groups and multi-site animal hospital chains is hardening as independent clinics face capital constraints. GE Healthcare leverages its installed base in human healthcare to cross-sell veterinary modalities through shared service contracts. Siemens Healthineers anchors its position with advanced Doppler platforms tailored for cardiology workflows in academic veterinary centers. Esaote SpA specializes in compact, field-durable systems that dominate equine and farm animal segments across Southern Europe.
Veterinary ultrasound employs piezoelectric transducers emitting high-frequency sound waves between 2 and 15 MHz to generate real-time anatomical images of soft tissues, organ systems, and developing fetuses in companion and production animals. The technology serves diagnostic imaging, reproductive monitoring, and interventional guidance in clinical and field settings. Portable ultrasound systems occupy the fastest-expanding product tier as mobile veterinary services and rural large-animal practitioners prioritize equipment mobility over cart-based throughput. Doppler imaging commands premium positioning within the technology stack, with color flow mapping becoming standard in cardiac and vascular assessments at specialty animal hospitals.
FDA Center for Veterinary Medicine oversees device safety labeling and manufacturing quality for equipment entering the United States, while the EU MDR framework imposes clinical evidence and post-market surveillance obligations on manufacturers distributing in Europe. China's NMPA implements GB standards for imported medical devices, creating registration barriers that domestic manufacturers such as Shenzhen Mindray Bio-Medical Electronics navigate with localized certification strategies. Stakeholders must monitor regulatory divergence between major markets, as divergent electromagnetic compatibility and biocompatibility testing requirements threaten to fragment product development roadmaps and inflate compliance budgets.
Market Dynamics
Point-of-care diagnostic migration is compressing referral volumes and forcing equipment manufacturers to prioritize portability over throughput in their product roadmaps.
Growth Catalysts
- EU MDR framework:Harmonized clinical evidence requirements for veterinary devices are elevating quality benchmarks and accelerating consolidation among compliant manufacturers distributing across European veterinary networks.
- Companion animal cardiology:Color Doppler imaging is becoming standard diagnostic protocol at specialty hospitals, pulling premium system upgrades through cardiac workflow specialization.
- China's livestock productivity programs:Provincial agricultural bureaus are subsidizing imaging equipment for large-animal reproductive monitoring in dairy and swine operations.
Market Restraints
- Piezoelectric crystal supply:Concentrated sourcing of high-purity lead zirconate titanate from specialized Japanese and German suppliers creates input cost volatility and allocation risk.
- FDA Center for Veterinary Medicine clearance timelines:Extended pre-market review periods for novel transducer designs delay product launches by 12-18 months versus human-device pathways.
- Referral network consolidation:Independent imaging centers face margin compression as corporate veterinary groups bring diagnostics in-house, shrinking addressable market for standalone service providers.
Strategic Opportunities
- Telemedicine-integrated ultrasound:Cloud-connected portable systems enable remote specialist interpretation, opening rural and mobile veterinary service models previously constrained by specialist availability.
- India's BIS certification pathway:Streamlined standards for imported veterinary devices reduce registration barriers for manufacturers targeting emerging companion animal practices in tier-2 cities.
- Artificial intelligence-assisted measurement:Automated biometric extraction from fetal and cardiac imaging is reducing operator dependency and expanding usable talent pools.
Industry Challenges
- Sonographer training pipelines:Accredited veterinary imaging certification programs remain concentrated at academic centers, creating bottlenecks for practice expansion.
- Legacy system interoperability:DICOM compliance gaps between field-portable units and hospital PACS networks complicate image archiving and multi-site record integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Ultrasound Market |
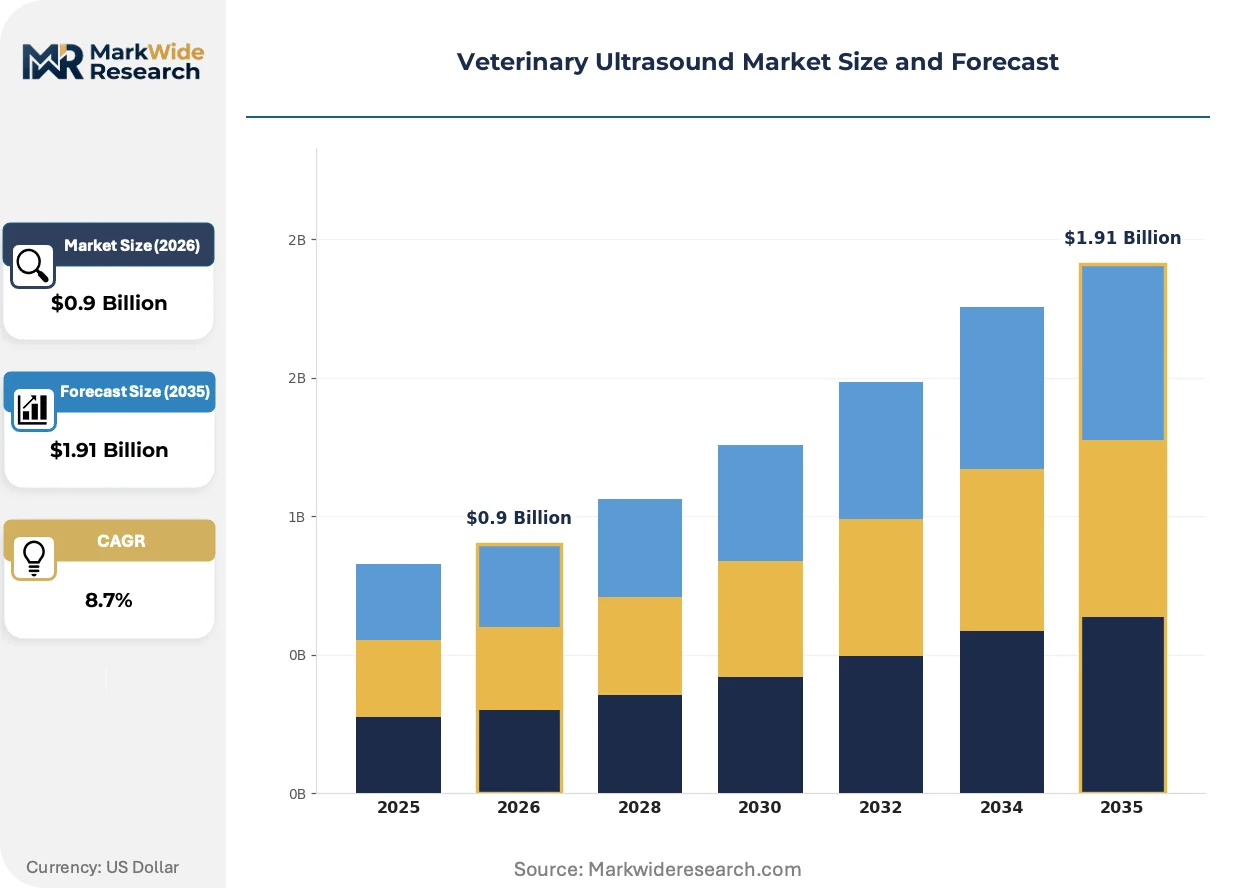
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Digital Ultrasound, Cart-Based Ultrasound, High-Frequency Ultrasound Application: Cardiology, Orthopedic, Obstetrics, Abdominal End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Contrast Ultrasound |
| Companies Covered | Siemens Healthineers, Heska Corporation, GE Healthcare, IMV Imaging, Samsung Medison Co. Ltd., Esaote SpA, FUJIFILM Holdings Corporation, Diagnostic Imaging Systems, Shenzhen Mindray Bio-Medical Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Ultrasound Market Strategic Shifts
Hardware miniaturization and software-enabled remote diagnostics are redrawing competitive boundaries between premium cart-based systems and emerging portable platforms.
Wireless probe technology is eliminating cable constraints that previously limited operator positioning and patient access. Mobile large-animal practitioners and ambulatory equine services are adopting battery-powered transducers at accelerating rates. This capability is decentralizing diagnostic capacity from fixed imaging suites into field settings, compressing the addressable market for traditional cart-based equipment.
China's NMPA has implemented enhanced GB electromagnetic compatibility testing for imported veterinary devices, raising technical barriers for non-domestic manufacturers. The regulation is forcing product redesign cycles and localized certification strategies. European and North American exporters are responding by establishing in-country testing partnerships and modified hardware configurations.
Subscription-based service models are displacing traditional capital purchase structures among multi-site veterinary groups. Equipment-as-a-service arrangements bundle hardware, maintenance, and software updates into per-procedure or monthly fees. This shift is most visible in the United States and Germany, where corporate veterinary chains prioritize operational expenditure flexibility over asset ownership.
Veterinary Ultrasound Market Segmentation
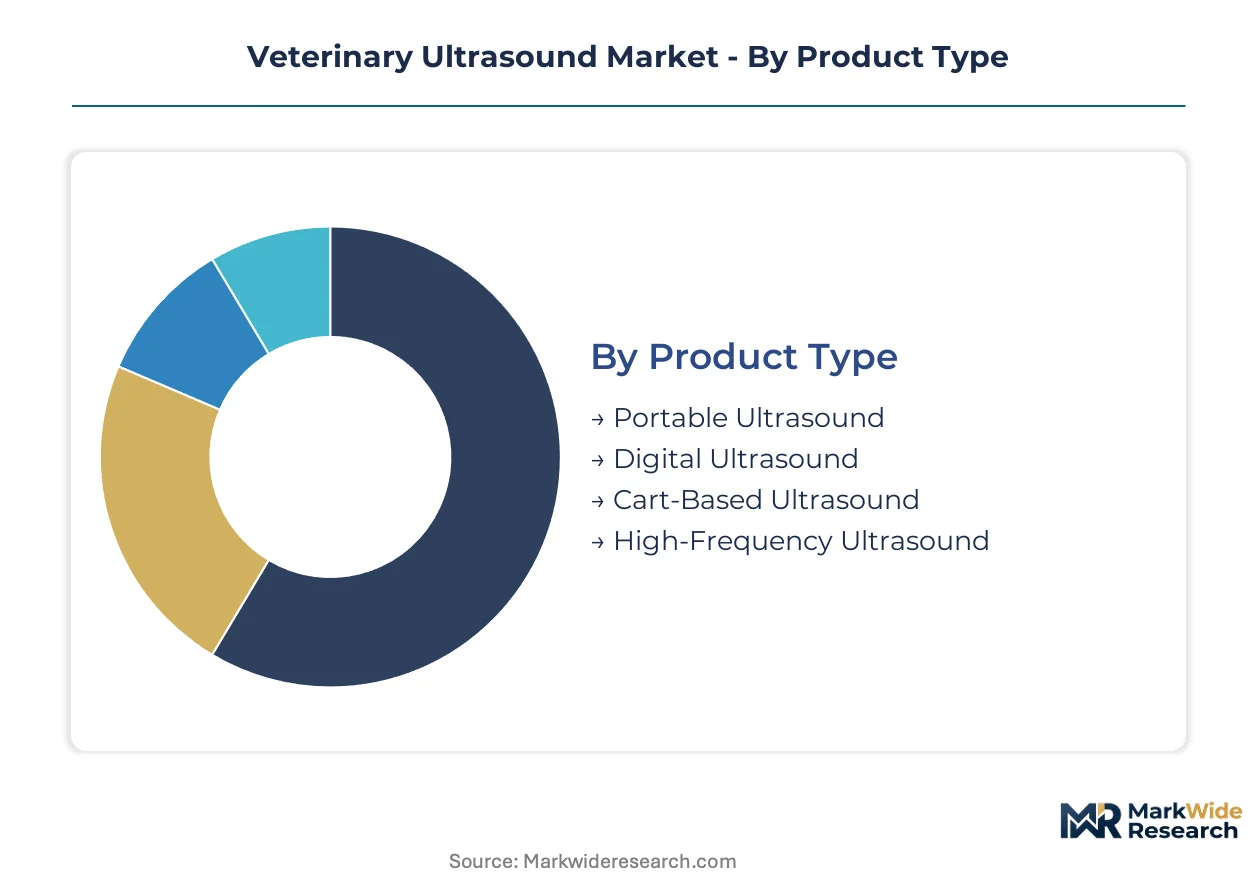
Veterinary ultrasound equipment segments diverge sharply across mobility requirements, clinical specialization depth, and capital intensity. Manufacturers configure transducer arrays, processing architectures, and software workflows to match distinct diagnostic protocols across companion animal practices, equine field services, and livestock reproductive programs.
Product Type:
Portability specifications and power architecture differentiate equipment tiers across ambulatory, clinic-based, and hospital-grade deployments.
- Portable Ultrasound:Battery-powered systems with sealed transducer connectors and ruggedized housings withstand field conditions in equine and farm animal settings. Mobile veterinary services in the United States and Germany are standardizing on sub-5kg units with wireless probe compatibility to eliminate cable failures during ambulatory examinations.
- Digital Ultrasound:Fully digitized beamforming architectures replace analog signal chains, enabling software-defined frequency compounding and harmonic imaging. Academic veterinary centers prioritize these platforms for research reproducibility and multi-site protocol standardization.
- Cart-Based Ultrasound:High-channel-count systems with dedicated GPU arrays support advanced Doppler quantification and strain analysis. These units anchor fixed imaging suites at specialty animal hospitals where throughput justifies capital investment.
- High-Frequency Ultrasound:Linear transducers operating above 10 MHz resolve superficial structures in ophthalmic, dermatologic, and musculoskeletal examinations. Small animal orthopedic practices deploy these for tendon sheath and ligament assessments.
Mature deployment sits with cart-based systems at established specialty hospitals. Newer deployment is concentrated in portable configurations for expanding mobile and rural veterinary networks.
Application:
Clinical workflow specialization drives transducer selection, preset optimization, and measurement package configuration across diagnostic domains.
- Cardiology:Spectral and color Doppler protocols quantify valvular regurgitation, pulmonary hypertension, and systolic function in companion animals. Specialty animal hospitals require continuous-wave Doppler capability for accurate pressure gradient estimation across stenotic lesions.
- Obstetrics:Transabdominal and transrectal approaches monitor fetal viability, litter count, and gestational aging in breeding programs. China's provincial livestock productivity programs subsidize obstetric ultrasound for dairy herd reproductive management.
- Orthopedic:Musculoskeletal imaging identifies tendon disruption, joint effusion, and ligamentous injury in athletic and working animals. Equine sports medicine practices rely on high-frequency linear arrays for superficial digital flexor tendon evaluation.
- Abdominal:Convex transducers penetrate to image liver, spleen, kidney, and gastrointestinal pathology across species weights. General veterinary clinics utilize abdominal presets as the primary revenue-generating application for ultrasound investment.
Cardiology applications command premium system configurations with specialized measurement packages. Obstetric imaging is expanding most quickly through subsidized livestock programs and companion animal breeding services.
End User:
Capital availability, case volume, and specialist staffing determine equipment tier selection across practice ownership models.
- Veterinary Clinics:Independent and corporate-owned general practices balance equipment cost against referral retention for complex cases. Mid-tier portable systems dominate this segment with shared service contracts reducing upfront capital requirements.
- Animal Hospitals:Multi-specialty institutions maintain dedicated imaging suites with cart-based platforms for cardiology, surgery, and internal medicine departments. These facilities require PACS integration and DICOM compliance for multi-modality record management.
- Research Institutions:Academic veterinary schools and pharmaceutical testing facilities prioritize imaging reproducibility, measurement precision, and regulatory documentation. Equipment selections emphasize software validation and calibration traceability.
- Mobile Veterinary Services:Ambulatory practitioners serving equine, farm animal, and home-bound companion animal cases demand battery operation, rapid startup, and vehicle-mount compatibility. This segment is gaining share fastest as practice models shift toward convenience and reduced patient transport stress.
Animal hospitals represent the most mature installed base with established replacement cycles. Mobile veterinary services are capturing newer equipment deployments as entrepreneurial practitioners exit fixed-facility constraints.
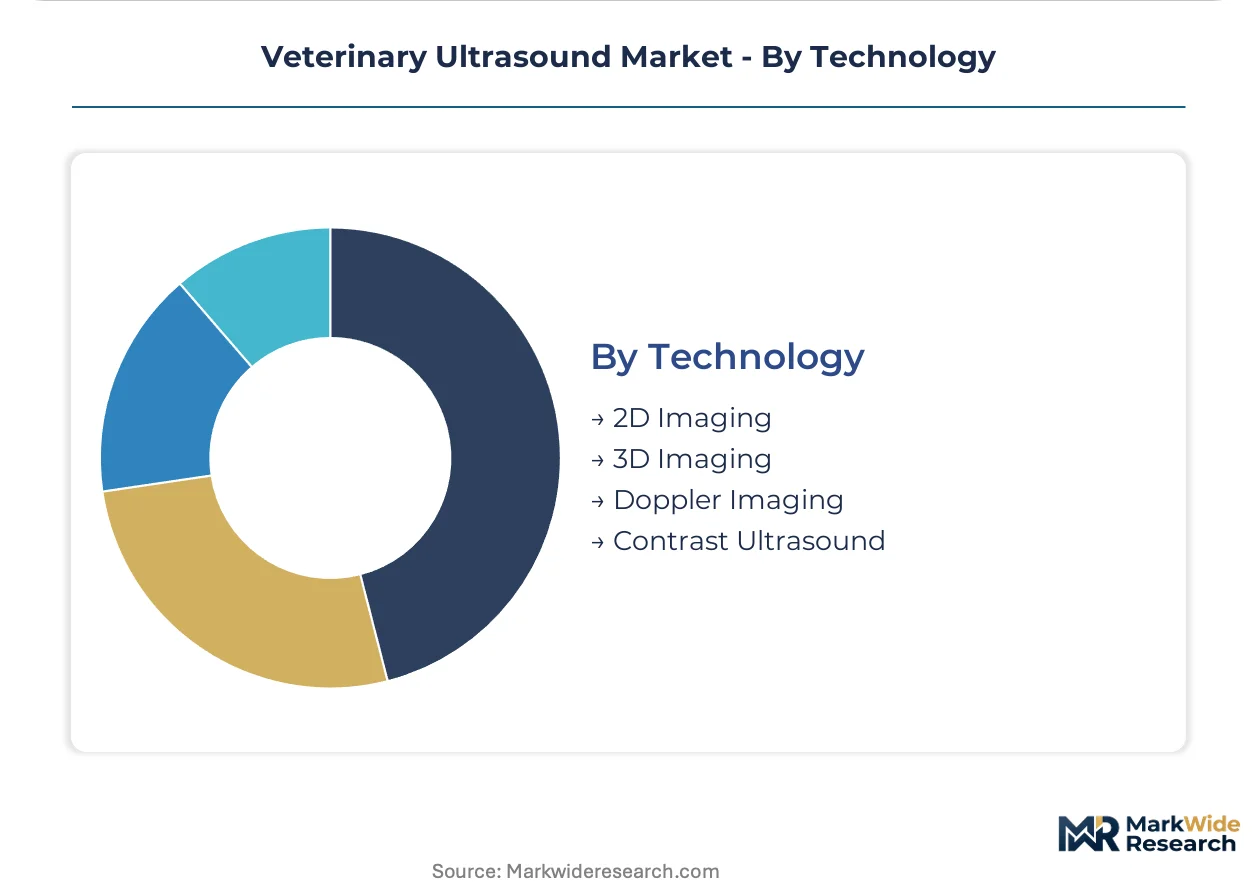
Technology:
Image formation algorithms and contrast mechanisms define diagnostic capability boundaries across equipment generations.
- 2D Imaging:Conventional grayscale B-mode remains the foundational modality for anatomical survey and guided interventions. All market tiers maintain 2D capability as the default operating mode.
- Doppler Imaging:Pulsed-wave, continuous-wave, and color flow mapping enable hemodynamic assessment without contrast administration. This technology anchors cardiology workflow differentiation and commands substantial price premiums.
- 3D Imaging:Volume acquisition and multiplanar reconstruction facilitate complex spatial relationships in cardiac and fetal examinations. Adoption concentrates at academic centers with dedicated sonographer training programs.
- Contrast Ultrasound:Microbubble enhancement agents improve perfusion visualization and lesion characterization in hepatic and splenic pathology. Regulatory pathways for veterinary contrast agents lag human medicine, constraining deployment.
2D imaging represents the most mature technology layer with universal deployment. Doppler imaging is capturing newer capability investments as cardiology specialization penetrates general veterinary practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance penetration and livestock productivity programs concentrate equipment procurement in the United States, Germany, and China. Veterinary groups in these markets justify capital investment through measurable diagnostic revenue and subsidized agricultural imaging programs.
United States
Corporate veterinary chains and multi-site animal hospitals drive premium system upgrades through shared service contracts. The FDA Center for Veterinary Medicine oversees device safety labeling and manufacturing quality for imported equipment. Specialty cardiology practices in the Greater Boston and Pacific Northwest clusters standardize on advanced Doppler platforms for valvular assessment protocols.
Germany
Equine sports medicine and large-animal reproductive services sustain demand for field-durable portable systems. The EU MDR framework imposes clinical evidence and post-market surveillance obligations on manufacturers distributing across European veterinary networks. Munich and Hanover anchor academic veterinary centers that prioritize imaging reproducibility for research applications.
China
Provincial agricultural bureaus subsidize obstetric ultrasound for dairy herd reproductive management in dairy and swine operations. The NMPA implements GB standards for imported medical devices, creating registration barriers that domestic manufacturers navigate with localized certification strategies. Shenzhen and Beijing concentrate manufacturing capacity for compact systems targeting rural veterinary networks.
Japan
Companion animal specialty hospitals in Tokyo and Osaka deploy high-frequency linear transducers for orthopedic and ophthalmic examinations. METI standards for electromagnetic compatibility testing shape product specifications for equipment entering the domestic market. Academic veterinary schools in Tsukuba prioritize measurement precision and calibration traceability for pharmaceutical imaging studies.
United Kingdom
Independent veterinary practices balance equipment cost against referral retention for complex cardiac and abdominal cases. The Veterinary Medicines Directorate aligns with EU MDR quality benchmarks for devices distributed across British veterinary networks. London and the Southeast cluster mobile veterinary services adopting battery-powered transducers for home-bound companion animal care.
Veterinary Ultrasound Market Competitive Environment
North American and European producers anchor the premium equipment tier; Chinese specialists hold the portable and mid-market segments. The vendor base concentrates around diversified healthcare conglomerates with cross-selling capabilities and regional specialists with species-specific expertise. Three archetypes dominate: human-healthcare cross-sellers leveraging installed base relationships, dedicated veterinary imaging specialists with field-service networks, and emerging Asian manufacturers with cost-optimized production. Consolidation through corporate veterinary group procurement contracts and technology licensing partnerships represent the dominant competitive moves reshaping market access.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare exemplify the cross-selling archetype by extending human-medical imaging platforms into veterinary workflows. Esaote SpA represents the dedicated specialist model with focused expertise in compact, field-durable configurations. Shenzhen Mindray Bio-Medical Electronics Co. Ltd. anchors the emerging manufacturer tier with localized certification strategies for price-sensitive veterinary networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Heska Corporation |
| GE Healthcare |
| IMV Imaging |
| Samsung Medison Co. Ltd. |
| Esaote SpA |
| FUJIFILM Holdings Corporation |
| Diagnostic Imaging Systems |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA-cleared premium systems and unregistered economy imports creates divergent pricing architectures and sourcing strategies across the veterinary ultrasound market. Tier-one manufacturers absorb extended FDA Center for Veterinary Medicine pre-market review costs into subscription-based service bundles, while price-sensitive rural practitioners in emerging markets source non-certified equipment through gray-channel distributors.
Pricing Analysis
Volume concentration in corporate veterinary groups compresses margins on standard-tier portable systems while preserving premium pricing for advanced Doppler configurations at academic centers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-cleared cardiology platforms commanding substantial service-contract premiums over CE-marked field units. Pricing pressure stems from China's domestic manufacturers flooding mid-market segments with localized NMPA-certified alternatives. Independent clinics exhibit highest price sensitivity, deferring upgrades until equipment failure forces replacement.
Supply Chain Analysis
Specialized piezoelectric crystal fabrication expertise concentrates in Japan and Germany, constraining transducer production capacity for premium veterinary applications. High-purity lead zirconate titanate sourcing draws from specialized chemical suppliers in Osaka and Munich, with GPU array procurement tethered to Taiwan semiconductor foundries. Single-source vulnerability in Japanese crystal supply creates allocation risk during demand surges. Distribution runs through regional imaging equipment distributors with field-service capabilities, bypassing direct manufacturer relationships for all but the largest hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory-compliant manufacturers as EU MDR enforcement and FDA clearance timelines eliminate marginal competitors lacking certification infrastructure. Weaker players face exit pressure from capital requirements for clinical evidence generation and post-market surveillance systems.
For Market Incumbents: Acquire field-service network assets in equine-dense geographies to lock out emerging Asian competitors lacking ambulatory support infrastructure. Backward integration into transducer crystal supply through offtake agreements with Japanese chemical specialists reduces input cost volatility. Defensive patent filings around AI-assisted measurement algorithms block new entrant software differentiation.
For New Entrants and Emerging Players: India's BIS certification pathway opens a window for compact portable systems targeting tier-2 city companion animal practices with streamlined registration timelines. White-space concentration sits with wireless probe technology for mobile large-animal services in Brazil and Australia, where regulatory barriers remain lower than EU or US markets. Go-to-market execution should prioritize veterinary telemedicine platform partnerships to bypass established distributor relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with dedicated veterinary imaging specialists given corporate veterinary group procurement consolidation favoring single-source equipment contracts. Long-term viability hinges on software-enabled recurring revenue streams displacing capital purchase models. Acquisition target archetype: mid-market portable system manufacturers with established EU MDR technical documentation and installed base in Germany or France. Signal to watch: corporate group RFPs mandating cloud-connected PACS integration as table-stake requirement.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence packages unlock European veterinary network access previously blocked to non-compliant manufacturers. |
| Cloud-Connected Portable System Launch | Telemedicine integration enables remote specialist interpretation for rural mobile veterinary services. |
| Field-Service Network Expansion | Ambulatory support capabilities differentiate premium positioning in equine and farm animal segments. |
| AI-Assisted Measurement Software Development | Automated biometric extraction reduces operator dependency and expands addressable talent pools. |
| Subscription-Based Service Model Transition | Per-procedure fee structures align with corporate veterinary group preference for operational expenditure flexibility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this veterinary ultrasound market assessment. Primary interviews with veterinary practice owners, biomedical equipment procurement managers, distributor sales directors, and regulatory affairs specialists at imaging manufacturers validated demand-side assumptions. Secondary sources encompassed FDA 510(k) clearance databases, EU MDR notified body certificates, NMPA registration records, and import-export statistics from veterinary equipment trade flows. Bottom-up equipment shipment analysis triangulated against top-down diagnostic service revenue estimates across major national markets.
Granularity-level modeling operated at product-type, application, technology, and end-user dimensions across the projection horizon. Portable, cart-based, digital, and high-frequency system configurations were tracked separately with distinct replacement cycle assumptions. Cardiology, obstetrics, orthopedic, and abdominal applications carried species-specific penetration rates. CAGRs derived from logistic curve fitting to historical adoption patterns with elasticity adjustments for pet insurance penetration and livestock subsidy program announcements. Forecast inputs incorporated Doppler imaging upgrade cycles at specialty hospitals and wireless probe adoption trajectories in mobile services.
The model assumes a particular technology adoption path; alternative pathways for battery-powered wireless transducers would alter the outlook if power density improvements accelerate faster than projected. Forecasts reflect assumptions regarding regulatory clearance timeline stability and corporate veterinary group consolidation velocity. Material deviation in FDA pre-market review duration or EU MDR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Thermography Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Mastitis Market
Veterinary
USA Animal Model Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Clonorchiasis Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Veterinary Scales Market
Veterinary
Vet Software Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Global Veterinary Rapid Test Market