
 Animal Microchip Implant Market | 2026-2036
Animal Microchip Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Microchip Implant Market Outlook
Veterinary technician training capacity is reorganizing how quickly clinics can adopt universal scanning protocols. Merck & Co., Inc. (HomeAgain) leverages its established veterinary channel relationships to sustain brand presence in companion animal practices. Datamars SA anchors livestock intelligence applications with embedded RFID systems that dominate cattle traceability programs. Virbac Corporation competes through geographic diversification across European and Latin American veterinary markets.
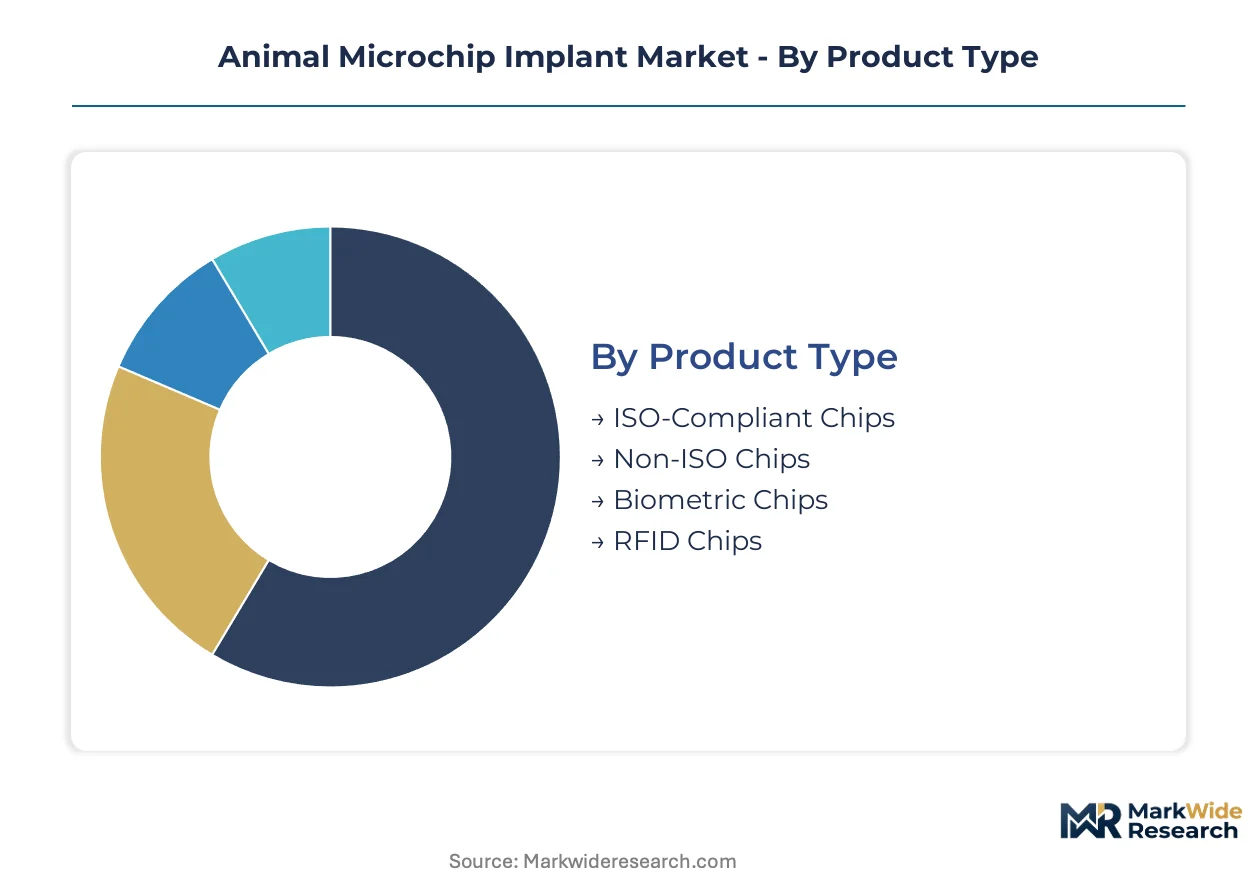
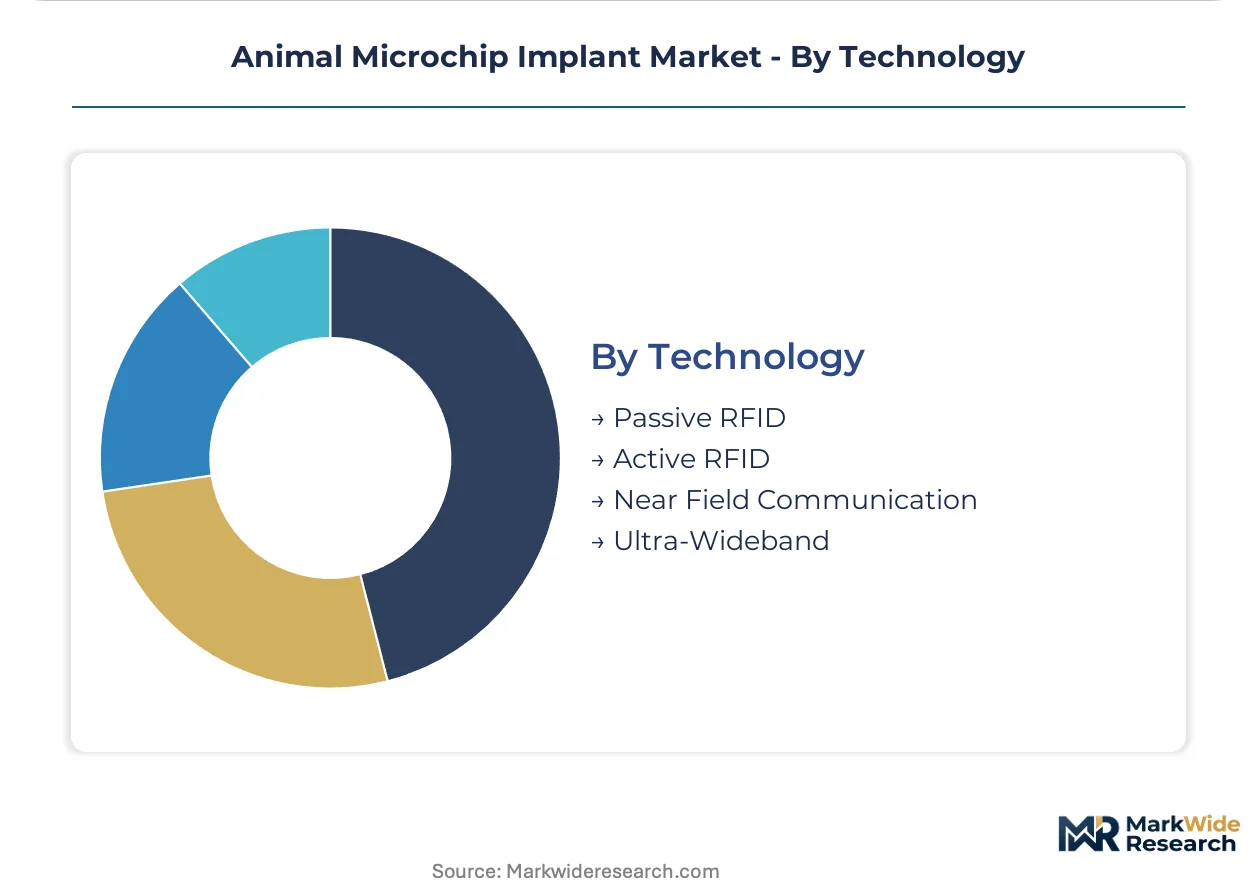
Animal microchip implants are biocompatible glass-encapsulated transponders, typically 11-14 millimeters in length, that transmit unique identification codes via radio frequency when activated by a scanner; they serve primarily to establish permanent, tamper-resistant identity linkage between individual animals and centralized registry databases. ISO-compliant chips hold structural precedence in regions where veterinary regulators mandate interoperability, while biometric chips represent the fastest-growing segment as temperature-sensing and health-monitoring functionalities expand beyond pure identification. Passive RFID technology occupies the dominant share of unit economics due to minimal power requirements and decades of manufacturing scale, though near field communication integration is gaining traction in premium pet recovery applications.
The USDA's National Animal Identification System guidelines, the UK's compulsory microchipping regulations enforced by local authorities, and Brazil's MAPA livestock traceability mandates collectively shape product standards and registry interoperability requirements across major demand centers. ISO 11784/11785 compliance functions as a de facto market access filter, excluding non-standard chip formats from government-procured veterinary programs. Stakeholders must monitor how emerging data privacy frameworks for animal registry databases reshape liability structures for manufacturers and veterinary service providers.
Market Dynamics
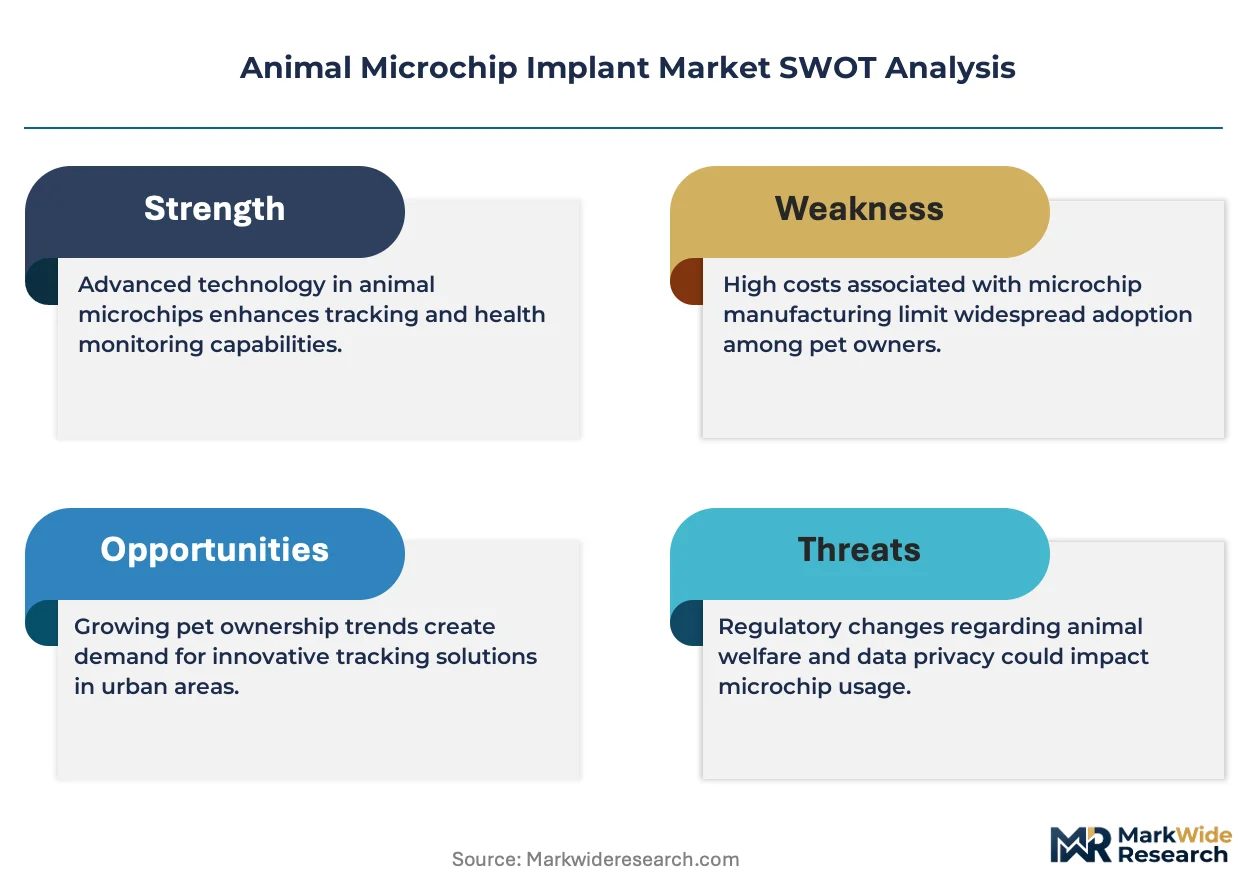
Mandatory pet registration laws and livestock traceability mandates are compressing adoption timelines across veterinary clinics and agricultural operations, while ISO 11784/11785 compliance requirements are filtering non-standard chip formats from government procurement channels.
Growth Catalysts
- USDA National Animal Identification System guidelines:Federal procurement standards for cattle traceability are accelerating RFID infrastructure deployment across American feedlots and slaughter facilities.
- Biometric chip functionality expansion:Temperature-sensing transponders are penetrating premium companion animal segments as veterinarians integrate continuous health monitoring into routine wellness protocols.
- United Kingdom compulsory microchipping enforcement:Local authority mandates for dog registration are standardizing scanner interoperability requirements across British veterinary practices and animal control operations.
Market Restraints
- Biocompatible glass encapsulation cost volatility:Specialized borosilicate supply concentration in German and Japanese manufacturing clusters creates input price instability for transponder producers.
- Proprietary format lock-in:Legacy non-ISO chip installations in existing companion animal populations create registry fragmentation that complicates universal scanner deployment.
- Near field communication power requirements:Active RFID alternatives face battery lifespan limitations that constrain deployment in free-ranging livestock applications.
Strategic Opportunities
- Brazil MAPA livestock traceability expansion:Federal mandates for cattle movement documentation are opening embedded RFID procurement channels across Latin American ranching operations.
- Veterinary technician training capacity expansion:Accelerated certification programs for universal scanning protocols are reducing clinic adoption friction in underpenetrated rural markets.
- Data privacy framework emergence:Emerging liability structures for animal registry databases are creating compliance service opportunities for manufacturers and veterinary software providers.
Industry Challenges
- Scanner-implant frequency calibration:Multi-frequency reader deployment requires technical retraining of veterinary staff that strains clinic operational bandwidth.
- Registry database interoperability:Fragmented data exchange protocols between national identification systems complicate cross-border livestock movement documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Microchip Implant Market |
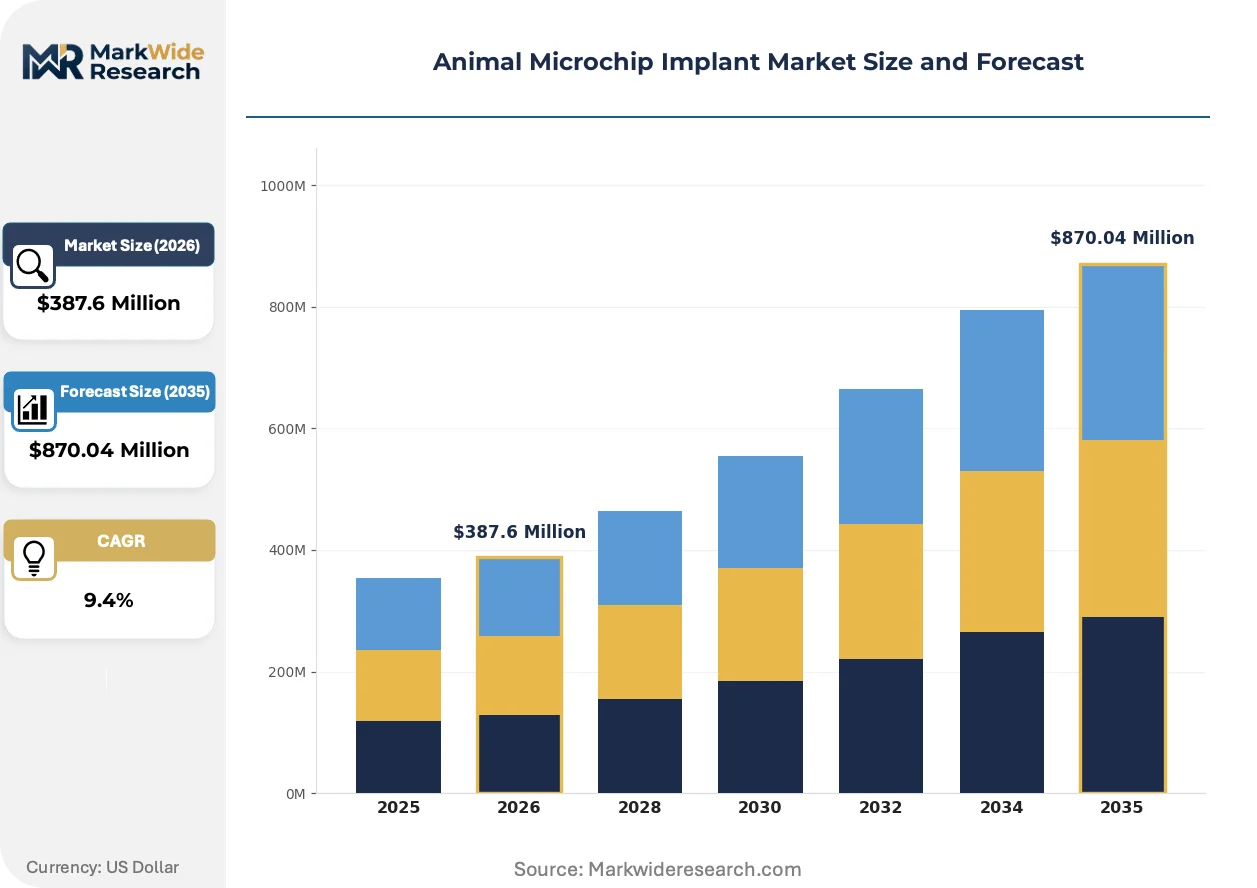
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ISO-Compliant Chips, Non-ISO Chips, Biometric Chips, RFID Chips End User: Veterinary Clinics, Animal Shelters, Pet Owners, Wildlife Organizations Application: Pet Identification, Lost Pet Recovery, Animal Registration, Wildlife Tracking Technology: Passive RFID, Active RFID, Near Field Communication, Ultra-Wideband |
| Companies Covered | Trovan Ltd., Virbac Corporation, Merck & Co., Inc. (HomeAgain), Pethealth Inc., Elanco Animal Health Incorporated, Datamars SA, Avid Identification Systems, Inc., PetLink (InfoPet), Allflex Livestock Intelligence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Microchip Implant Market Strategic Shifts
Radio frequency identification technology is fragmenting into specialized functional tiers as passive transponders, biometric sensors, and near field communication systems pursue distinct application pathways across companion animal and livestock verticals.
Passive RFID transponder architecture is bifurcating into basic identification and health-monitoring variants as temperature-sensing biocompatible chips penetrate premium veterinary wellness programs. Large companion animal practices in metropolitan United States markets are piloting continuous physiological data streams. The technology is bifurcating pure identification economics from recurring diagnostic revenue models.
REACH substance restrictions on heavy metals in electronic components are forcing reformulation of transponder antenna alloys and encapsulation materials for European market access. German veterinary distributors are demanding full material disclosure documentation. Small transponder manufacturers without compliance engineering capacity are exiting continental procurement channels.
After-sales service unbundling is separating microchip registration from implantation procedures as third-party registry platforms displace veterinary clinic-managed databases. Direct-to-consumer subscription models for pet recovery services are capturing recurring revenue streams. This pattern concentrates in United Kingdom and Australian markets where microchip compliance is already mandatory.
Animal Microchip Implant Market Segmentation
Segmentation in animal microchip implants reveals how regulatory mandates and application requirements fragment procurement patterns across veterinary channels. Product standards, end-user infrastructure, and technology lifecycles each create distinct competitive arenas with divergent margin structures.
Product Type:
ISO-compliant formats dominate government procurement in the United States, United Kingdom, and Brazil, while proprietary legacy chips persist in closed-loop companion animal registries. Export-led demand concentrates on standardized transponders; domestic veterinary clinics show mixed adoption.
- ISO-Compliant Chips:These transponders adhere to ISO 11784/11785 frequency and data structure standards, enabling cross-platform scanner compatibility. USDA procurement guidelines and UK compulsory microchipping regulations mandate this format, concentrating volume in North American and European veterinary programs. Manufacturing scale in German and Japanese glass-encapsulation facilities reinforces cost competitiveness.
- Biometric Chips:Temperature-sensing transponders embed thermistors within biocompatible glass capsules, transmitting continuous physiological data alongside identification codes. Metropolitan United States veterinary practices in California and Texas are piloting these for premium wellness monitoring, driven by recurring diagnostic revenue models. The steepest expansion trajectory runs through this segment as health-monitoring functionalities extend beyond pure identification.
- Non-ISO Chips:Legacy proprietary formats remain installed in existing companion animal populations, particularly in early-adopter US markets with clinic-specific registries.
- RFID Chips:General-purpose radio frequency identification transponders serve non-standard applications where interoperability requirements remain unspecified.
ISO-Compliant Chips command the established base. The steepest expansion runs through Biometric Chips.
End User:
Customer infrastructure maturity determines adoption velocity: institutional buyers with scanning hardware deploy fastest, while individual pet owners rely on intermediary services. Cost tiers separate subscription-based recovery platforms from one-time implantation fees.
- Veterinary Clinics:Primary implantation sites with established scanner infrastructure and technician training capacity. United States and UK practices face mandatory interoperability requirements, compressing procurement timelines for universal readers. Clinic density in urban corridors drives volume concentration.
- Animal Shelters:High-throughput scanning operations with standardized intake protocols. Brazilian municipal shelters and UK local authority facilities are expanding chip-checking mandates, creating bulk procurement channels.
- Pet Owners:End beneficiaries of recovery services, increasingly targeted by direct-to-consumer registry subscriptions in Australian and UK markets.
- Wildlife Organizations:Specialized users deploying transponders for population monitoring and migration tracking, with demand concentrated in research grant-funded programs.
Veterinary Clinics anchor procurement volume. Animal Shelters are expanding most quickly as mandatory scanning laws spread.
Application:
Application segmentation tracks how identity verification extends from companion animal recovery into regulatory compliance and ecological research. Maturity varies: pet identification is saturated in mandated markets, while wildlife tracking remains nascent.
- Pet Identification:Core application establishing permanent linkage between individual animals and centralized registries. UK compulsory microchipping for dogs and emerging US state-level mandates standardize this as baseline veterinary care.
- Lost Pet Recovery:Recovery service subscriptions monetize identification infrastructure, with third-party platforms displacing clinic-managed databases in United Kingdom and Australian markets.
- Animal Registration:Government-mandated documentation for breeding, travel, and public health tracking, concentrated in EU member states with harmonized veterinary passport systems.
- Wildlife Tracking:Ecological research applications requiring specialized transponder durability and extended read ranges, with procurement tied to conservation grant cycles.
Pet Identification commands the established base. Lost Pet Recovery is gaining share fastest through subscription revenue models.
Technology:
Technology segmentation reflects power-source economics: passive systems dominate unit volumes through minimal maintenance requirements, while active alternatives target premium applications where continuous transmission justifies battery replacement costs.
- Passive RFID:Dominant architecture using reader-activated electromagnetic induction, eliminating onboard power requirements. Decades of manufacturing scale and ISO standardization entrench this technology across veterinary and livestock applications.
- Active RFID:Battery-powered transponders with extended read ranges, constrained in free-ranging livestock by battery lifespan limitations and replacement logistics.
- Near Field Communication:Short-range communication protocol gaining traction in premium pet recovery applications, enabling smartphone-based scanner functionality.
- Ultra-Wideband:Precision location technology with minimal penetration in animal applications due to cost and power requirements.
Passive RFID commands the established base. Near Field Communication is climbing the fastest as smartphone integration reduces scanner hardware barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA guidelines for cattle traceability and the United Kingdom's compulsory microchipping enforcement are compressing procurement timelines across veterinary and agricultural channels. Regulatory momentum concentrates demand in markets with established scanning infrastructure and mandatory registration frameworks.
United States
Federal feedlot traceability mandates and metropolitan veterinary wellness programs are expanding chip deployment. USDA procurement standards for cattle identification accelerate RFID infrastructure across slaughter facilities. Large companion animal practices in California and Texas pilot temperature-sensing biometric chips for premium health monitoring.
United Kingdom
Local authority enforcement of compulsory dog microchipping standardizes scanner interoperability requirements. British veterinary practices face mandatory compliance deadlines that compress universal reader adoption. London and Southeast England clinics drive volume concentration through high pet ownership density and regulatory proximity.
Brazil
MAPA federal mandates for cattle movement documentation open embedded RFID procurement across ranching operations. Livestock traceability requirements extend from breeding through slaughter chain documentation. São Paulo and Rio Grande do Sul agricultural clusters anchor embedded system deployment for export compliance.
Germany
REACH substance restrictions on heavy metals force transponder material reformulation for European market access. German veterinary distributors demand full material disclosure documentation. Manufacturing clusters in Baden-Württemberg and Bavaria concentrate biocompatible glass encapsulation capacity for ISO-compliant chip production.
Australia
Direct-to-consumer registry subscriptions capture recurring revenue in markets with mature microchip compliance. Third-party pet recovery platforms displace clinic-managed databases. New South Wales and Victoria metropolitan corridors concentrate subscription service adoption among digitally engaged pet owners.
Animal Microchip Implant Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the animal microchip implant market. Merck & Co., Inc. (HomeAgain) and Datamars SA occupy positions with established veterinary channel relationships and livestock intelligence applications respectively. Virbac Corporation and Elanco Animal Health Incorporated represent pharmaceutical-origin diversification into identification systems. Competitive moves concentrate on geographic diversification across European and Latin American markets and backward integration into biocompatible encapsulation materials.
Within the pharmaceutical-diversified tier, Merck & Co., Inc. (HomeAgain) and Virbac Corporation exemplify companies leveraging existing veterinary distribution networks to sustain brand presence in companion animal practices. Datamars SA occupies a position anchoring livestock intelligence applications with embedded RFID systems. These three entities represent distinct strategic archetypes: veterinary channel leverage, geographic diversification, and agricultural traceability specialization.
| Leading Market Players |
|---|
| Trovan Ltd. |
| Virbac Corporation |
| Merck & Co., Inc. (HomeAgain) |
| Pethealth Inc. |
| Elanco Animal Health Incorporated |
| Datamars SA |
| Avid Identification Systems, Inc. |
| PetLink (InfoPet) |
| Allflex Livestock Intelligence |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for biocompatible glass encapsulation from Baden-Württemberg suppliers concentrate pricing power with German and Japanese manufacturers, while veterinary clinics face compressed procurement timelines under mandatory scanning laws. This inventory dynamic tightens margin structures for transponder producers unable to secure captive borosilicate supply.
Pricing Analysis
Geographic price spreads of 15-25 percent separate North American veterinary procurement from Brazilian livestock channels, reflecting ISO certification premiums and after-sales service bundling. Three-tier pricing structure across premium biometric, standard ISO-compliant, and economy non-ISO tiers segments buyer segments, with municipal shelters exhibiting highest price sensitivity and metropolitan wellness clinics showing lowest. Pricing pressure stems from REACH compliance costs forcing material reformulation for European market access. Volume scale and certification grade serve as primary price differentiation drivers across procurement channels.
Supply Chain Analysis
Inventory concentration in German and Japanese glass-encapsulation clusters creates single-source vulnerability for biocompatible transponder substrates. Manufacturing draws from specialized borosilicate, antenna-grade copper alloys, and thermistor components as critical inputs. Tariff exposure on electronic components threatens margin stability for distributors serving cross-border veterinary markets. Distribution runs through veterinary distributor networks and direct livestock intelligence channels to end-user clinics and ranching operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocompatible encapsulation engineering capacity sits scarce relative to accelerating RFID deployment mandates, constraining supply response to veterinary clinic procurement surges. Manufacturers with captive glass-forming capabilities command structural advantage in cost and delivery reliability.
For Market Incumbents: Consolidate backward integration into biocompatible encapsulation materials to defend against borosilicate supply concentration risks. Secure long-term offtake agreements with German and Japanese substrate producers before capacity constraints intensify. Channel control through exclusive veterinary distributor relationships remains essential as third-party registry platforms displace clinic-managed databases.
For New Entrants and Emerging Players: Lead with biometric temperature-sensing transponders targeting metropolitan United States wellness practices seeking recurring diagnostic revenue models. Brazilian MAPA livestock traceability expansion offers the most penetrable geography for embedded RFID specialists. Partner with agricultural cooperatives for direct ranching channel access rather than competing through established veterinary distributors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because mandatory pet registration and livestock traceability laws create irreversible demand for identification systems. Acquisition targets should display veterinary channel relationships or livestock intelligence software integration. Watch USDA cattle traceability mandate enforcement timelines as the critical inflection signal for American feedlot RFID deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatible Encapsulation Backward Integration | Captive borosilicate supply from Baden-Württemberg manufacturers reduces input cost volatility for ISO-compliant chip producers. |
| Biometric Sensor Platform Launch | Temperature-sensing transponders unlock recurring diagnostic revenue streams in California and Texas metropolitan veterinary markets. |
| Universal Scanner Certification Program | Accelerated technician training reduces clinic adoption friction in underpenetrated rural United States markets. |
| MAPA Livestock Channel Partnership | Direct relationships with São Paulo and Rio Grande do Sul ranching cooperatives secure embedded RFID procurement preference. |
| REACH Compliance Engineering Investment | Material disclosure documentation capabilities preserve European market access as ECHA restrictions tighten on heavy metals. |
Study Parameters
A spread of perspectives from veterinary practice managers, livestock intelligence procurement officers, biocompatible materials engineers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with clinic owners and agricultural cooperative buyers alongside secondary validation through USDA procurement guidelines, ANVISA regulatory filings, customs trade data on electronic component imports, and veterinary distributor sales records. Bottom-up clinic deployment estimates triangulated against top-down livestock population statistics.
Segmentation dimensions modeled include product type tier, end-user infrastructure maturity, application pathway, and technology architecture across the projection horizon. CAGRs derived from installation base expansion rates, replacement cycles for legacy non-ISO chips, and biometric functionality penetration curves. Forecast inputs incorporated veterinary technician training capacity constraints and MAPA mandate enforcement schedules without specifying implementation dates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of compulsory microchipping would require recalibration of adoption velocity assumptions. Forecasts reflect documented assumptions regarding ISO standardization prevalence and scanner interoperability deployment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Milking Salve Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Veterinary Excipients Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Spay and Neuter Market
Veterinary
Bovine Collagen Market
Veterinary
Otc Pet Medication Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Veterinary Progesterone Testing Market