
 Veterinary and Animal Healthcare Logistics Market | 2026-2036
Veterinary and Animal Healthcare Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary and Animal Healthcare Logistics Market Insights
North American pharmaceutical-grade cold storage infrastructure is expanding to accommodate temperature-sensitive veterinary biologics. Zoetis Inc. leverages vertically integrated distribution networks spanning farm-to-clinic channels. Merck Animal Health anchors its logistics footprint through regional distribution centers positioned near major livestock production belts. Boehringer Ingelheim Animal Health differentiates via specialized vaccine logistics protocols that exceed standard cold-chain baselines.
Veterinary and animal healthcare logistics encompasses the temperature-controlled transport, warehousing, and inventory management of medicines, vaccines, nutraceuticals, and medical equipment intended for clinical and production animal populations, requiring validated cold-chain maintenance between two and eight degrees Celsius for most biologics. The primary commercial purpose centers on preserving therapeutic efficacy from manufacturer through administration point while minimizing spoilage-related losses. Transportation services command the dominant service-type position due to the specialized refrigerated vehicle fleets and air freight capacity required for international vaccine movement. Pharmaceutical companies represent the fastest-growing end-user category as these firms internalize direct-to-farm distribution to bypass intermediary markups. Inventory management systems are capturing expanding margin pools through real-time temperature monitoring and predictive demand analytics.
The FDA enforces current Good Distribution Practice standards that mandate documented temperature controls throughout veterinary pharmaceutical transit, while the USDA regulates interstate movement of certain biological products through permitting and facility inspection protocols. EMA's Veterinary International Conference on Harmonisation guidelines further shape cross-border product registration and logistics documentation requirements for firms operating in European markets. Stakeholders must monitor evolving serialization mandates and track-and-trace regulations that will reshape compliance investments across multi-modal distribution networks.
Market Dynamics
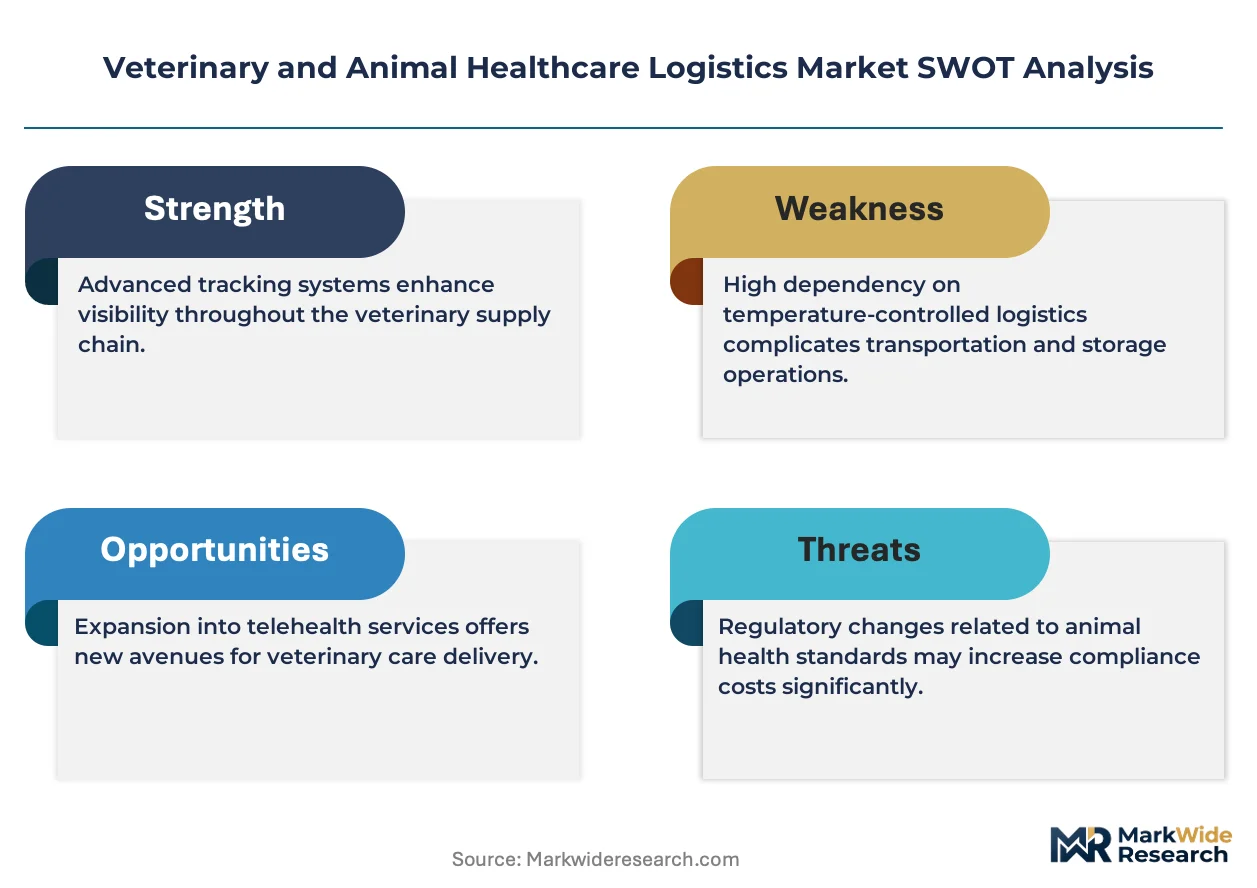
Cold-chain validation requirements from the FDA and EMA are forcing logistics providers to retrofit warehouse networks with continuous temperature-monitoring infrastructure, compressing margins for operators lacking capital reserves.
Growth Catalysts
- EMA Veterinary International Conference on Harmonisation guidelines:Standardized cross-border documentation protocols reduce customs clearance friction for vaccine shipments entering European markets.
- IoT-enabled sensor networks:Real-time temperature tracking during transit cuts spoilage rates for high-value biologics moving through Brazil's cattle vaccination corridors.
- India's PLI scheme for animal health:Domestic manufacturing incentives attract cold-storage infrastructure investment near pharmaceutical clusters in Hyderabad and Pune.
Market Restraints
- Dry ice supply concentration:Dependence on industrial gas suppliers in Germany and the US Midwest creates vulnerability for international vaccine air freight during peak agricultural seasons.
- USDA interstate permitting protocols:Facility inspection backlogs delay regional distribution center openings by six to eighteen months in high-growth livestock belts.
- Liquid nitrogen cost volatility:Energy price spikes in European manufacturing hubs compress margins for cryogenic transport of cellular therapies.
Strategic Opportunities
- Vietnam's dairy expansion zones:Underpenetrated cold-chain infrastructure around Ho Chi Minh City logistics corridors offers first-mover positioning for biologics distributors.
- Drone last-mile delivery:Regulatory sandbox programs in Rwanda and Kenya enable pilot networks reaching remote pastoral regions unreachable by refrigerated road transport.
- EU Green Deal sustainable cooling mandates:Phase-down of hydrofluorocarbon refrigerants creates replacement demand for CO2-based systems in veterinary pharmaceutical warehousing.
Industry Challenges
- Qualified Person certification scarcity:EMA-mandated signatories for batch release are concentrated in Western European labor markets, constraining expansion timelines.
- Legacy ERP integration:Temperature-monitoring platforms require costly middleware development to interface with decades-old inventory systems at regional veterinary distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary and Animal Healthcare Logistics Market |
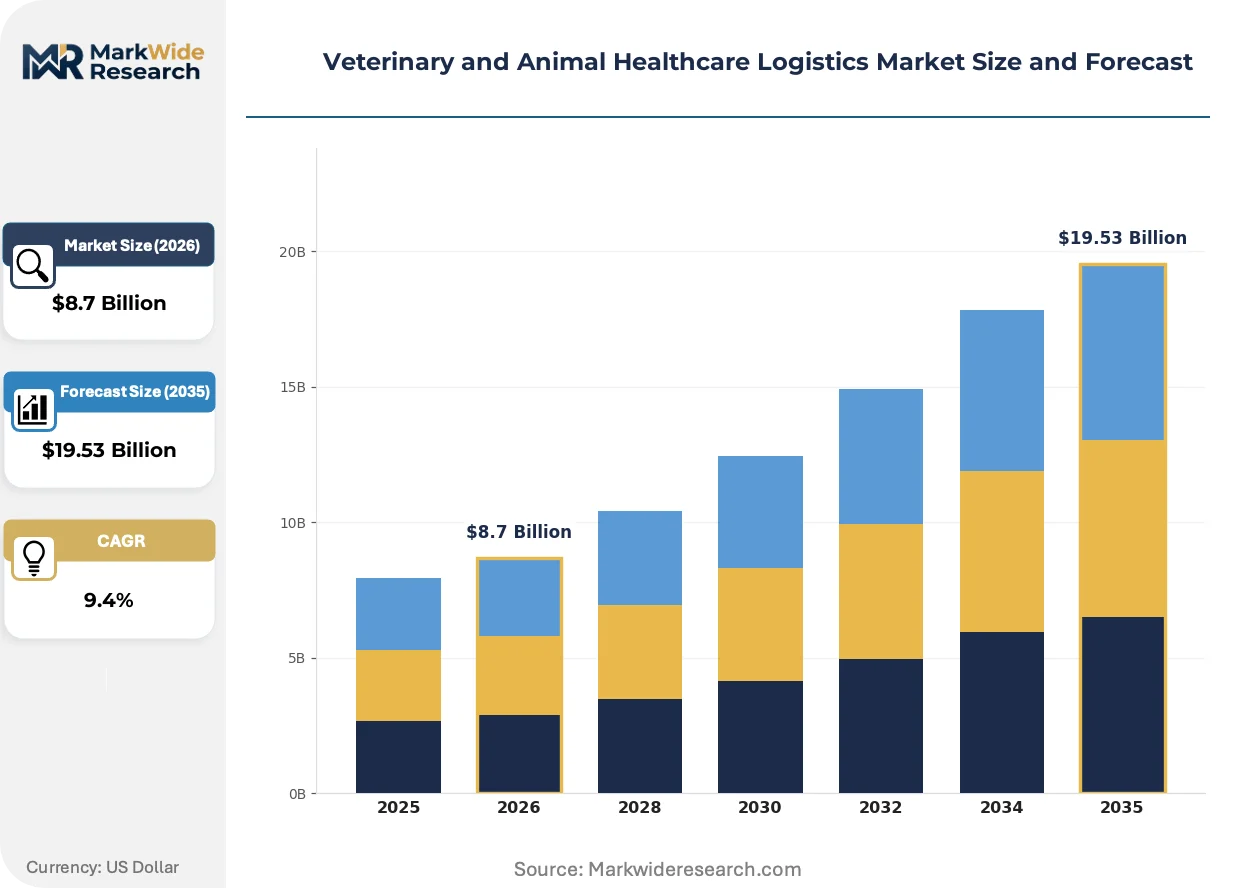
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management End User: Veterinary Clinics, Animal Hospitals, Research Organizations, Pharmaceutical Companies Product Type: Medicines, Vaccines, Nutraceuticals, Medical Equipment Delivery Mode: Ground Transport, Air Freight, Sea Freight, Drop Shipping |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Vetoquinol, Dechra Pharmaceuticals, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary and Animal Healthcare Logistics Market Trends and Innovations
Digital twin modeling and predictive analytics are compressing planning cycles for temperature-sensitive distribution networks, enabling dynamic rerouting around weather disruptions and customs delays.
Blockchain-based chain-of-custody documentation is converging with automated IoT sensor feeds to create immutable temperature records for regulatory audits. Pharmaceutical manufacturers in the Netherlands and Denmark are piloting these integrated systems for high-value equine plasma shipments. The convergence is compressing insurance premiums and accelerating claims resolution for spoiled product disputes.
REACH restrictions on fluorinated greenhouse gases are mandating refrigerant transitions across European cold-storage facilities. Warehouse operators in Germany and France face retrofit deadlines that favor ammonia-CO2 cascade systems over conventional HFC equipment. Veterinary biologics distributors with multi-country footprints must harmonize equipment specifications across national regulatory timelines.
Direct-to-farm procurement models are displacing traditional wholesale veterinary distributor networks in North American cattle operations. Large integrated protein producers in Nebraska and Texas are contracting directly with vaccine manufacturers for scheduled delivery to feedlot sites. This channel shift concentrates volume with vertically integrated logistics providers capable of farm-gate temperature compliance.
Veterinary and Animal Healthcare Logistics Market Segmentation
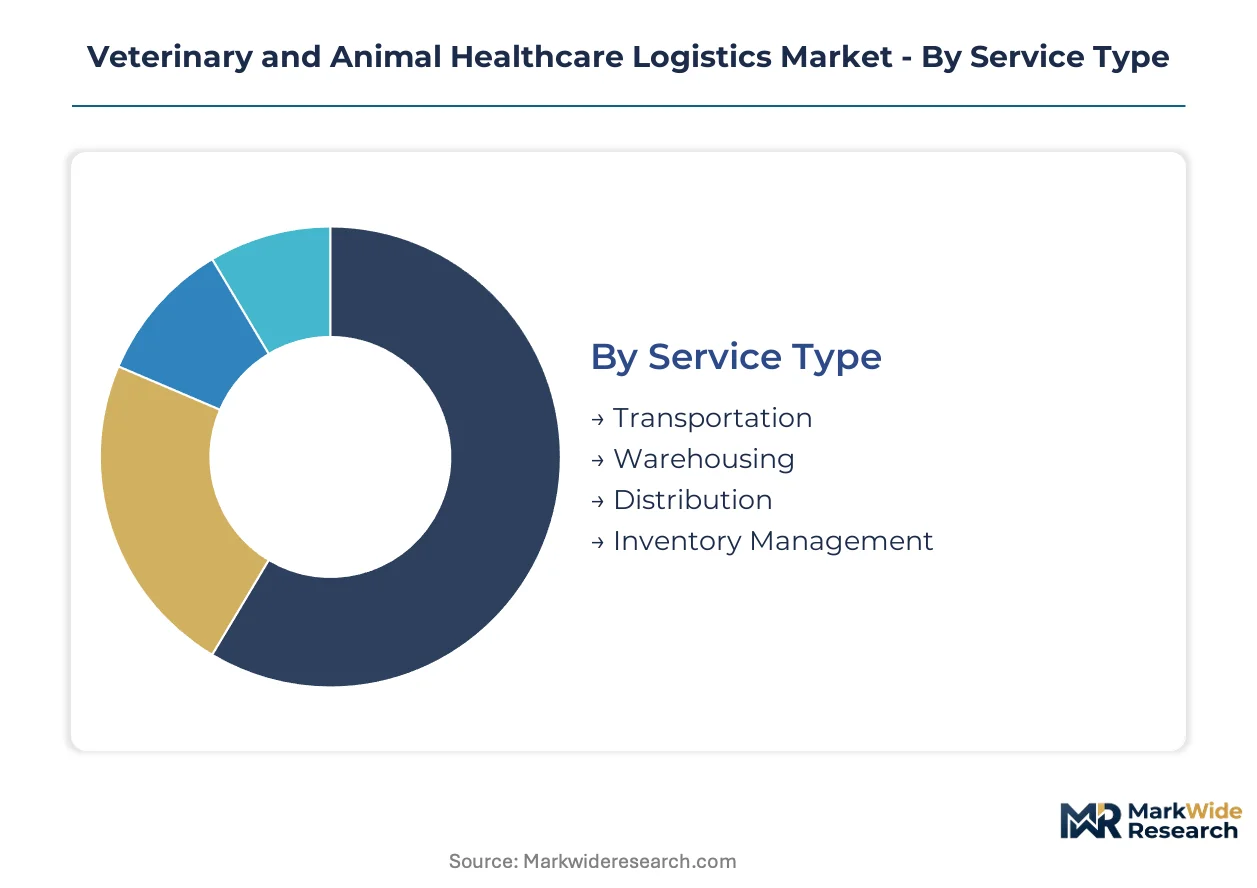
Segmentation in veterinary logistics reveals where capital concentrates and where compliance costs bite hardest. Service type and end-user splits expose divergent margin structures across temperature-controlled networks.
Service Type:
Volume-heavy segments dominate revenue tonnage while premium-margin services capture expanding profit pools.
- Transportation:Refrigerated vehicle fleets and specialized air freight capacity move temperature-sensitive biologics across international corridors. Demand concentrates in Brazil's cattle vaccination networks where cold-chain gaps create spoilage risk for high-value vaccine shipments.
- Inventory Management:Real-time temperature monitoring platforms and predictive demand analytics reduce working capital requirements for distributors. Pharmaceutical manufacturers in the Netherlands and Denmark deploy these systems for equine plasma tracking, cutting insurance premiums through immutable sensor records.
- Warehousing:FDA-validated cold storage facilities with continuous monitoring infrastructure.
- Distribution:Regional hub networks positioned near livestock production belts.
Today's leader: Transportation. Tomorrow's challenger: Inventory Management.
End User:
Customer type determines contract structure, with direct procurement displacing traditional wholesale channels.
- Pharmaceutical Companies:Manufacturers internalizing direct-to-farm distribution to bypass intermediary markups and capture margin. Large integrated protein producers in Nebraska and Texas now contract directly for scheduled vaccine delivery to feedlot sites.
- Veterinary Clinics:Small-batch, high-frequency ordering patterns requiring flexible last-mile networks.
- Animal Hospitals:Emergency biologics procurement with stringent temperature documentation requirements.
- Research Organizations:Cryogenic transport for cellular therapies with liquid nitrogen dependency.
Direct procurement models favor pharmaceutical companies. Traditional distributors serve clinics and hospitals.
Product Type:
Regulatory stringency varies sharply across product categories, shaping logistics provider specialization.
- Vaccines:Two-to-eight-degree Celsius cold-chain mandates from FDA and EMA drive specialized handling protocols. Boehringer Ingelheim Animal Health exceeds baseline requirements through validated distribution networks.
- Medicines:Therapeutic pharmaceuticals with moderate temperature sensitivity and established distribution pathways.
- Medical Equipment:Capital goods with lower compliance burden but higher damage liability.
- Nutraceuticals:Supplement products with relaxed cold-chain requirements expanding in emerging agricultural economies.
Vaccines command premium logistics pricing. Nutraceuticals offer volume growth in price-sensitive markets.
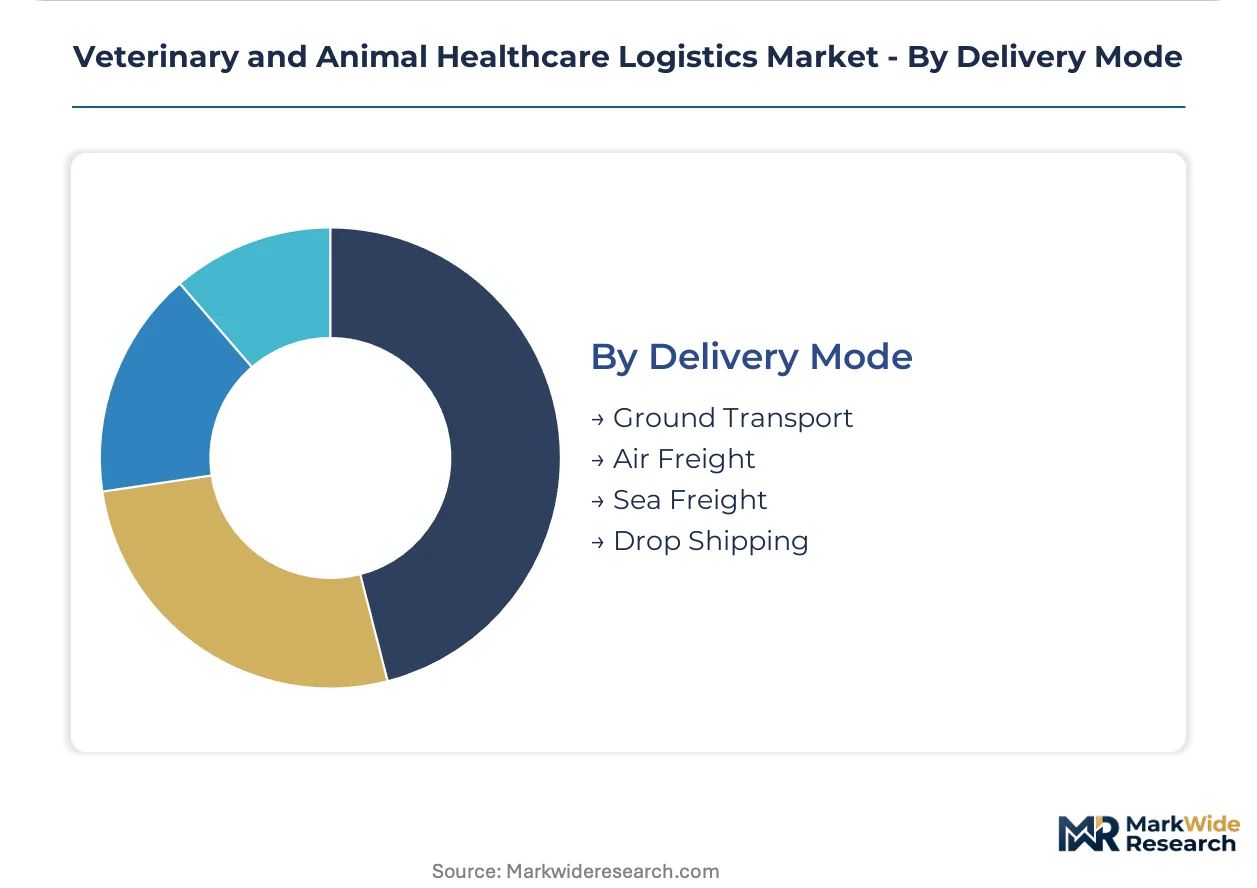
Delivery Mode:
Modal choice reflects speed-cost tradeoffs and infrastructure availability across geographies.
- Air Freight:International vaccine movement dependent on dry ice supply concentrated in Germany and the US Midwest. Peak agricultural seasons expose vulnerability when industrial gas suppliers face capacity constraints.
- Ground Transport:Dominant mode for domestic distribution with refrigerated fleet requirements.
- Sea Freight:Bulk pharmaceutical movement with extended transit times limiting biologics applicability.
- Drop Shipping:Direct-to-farm models displacing traditional veterinary distributor networks in North American cattle operations.
Ground transport anchors domestic volume. Air freight captures premium international vaccine flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cattle vaccination corridors are expanding faster than Germany's pharmaceutical-grade cold storage networks, reflecting divergent investment priorities across agricultural and industrial economies.
United States
Large integrated protein producers in Nebraska and Texas are contracting directly with vaccine manufacturers for scheduled delivery to feedlot sites. The FDA enforces current Good Distribution Practice standards that mandate documented temperature controls throughout veterinary pharmaceutical transit. Cold-chain infrastructure investment concentrates around regional distribution centers positioned near major livestock production belts.
Germany
Industrial gas suppliers face capacity constraints that expose vulnerability for international vaccine air freight during peak agricultural seasons. The EMA's Veterinary International Conference on Harmonisation guidelines shape cross-border product registration and logistics documentation requirements. Warehouse operators in Germany face retrofit deadlines that favor ammonia-CO2 cascade systems over conventional HFC equipment.
Brazil
Livestock vaccine distribution networks are broadening across emerging agricultural economies with demand concentrating in expanding cattle vaccination corridors. Cold-chain gaps create spoilage risk for high-value vaccine shipments moving through underpenetrated regions. IoT-enabled sensor networks are cutting spoilage rates for biologics in transit across domestic logistics corridors.
India
Domestic manufacturing incentives under the PLI scheme for animal health are attracting cold-storage infrastructure investment near pharmaceutical clusters. The CDSCO regulates veterinary pharmaceutical distribution through facility licensing and batch release protocols. Hyderabad and Pune are emerging as concentration points for temperature-controlled warehousing capacity expansion.
Netherlands
Pharmaceutical manufacturers are piloting blockchain-based chain-of-custody documentation integrated with automated IoT sensor feeds for high-value equine plasma shipments. EMA-mandated Qualified Person certification requirements for batch release are concentrated in Western European labor markets. Rotterdam's logistics hub is capturing expanding flows of temperature-sensitive veterinary biologics entering European distribution networks.
Veterinary and Animal Healthcare Logistics Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through regulatory compliance depth. The market structure reflects moderate consolidation around vertically integrated pharmaceutical manufacturers alongside fragmented regional logistics providers. Three archetypes dominate: captive distribution arms of major vaccine manufacturers, third-party cold-chain specialists with multi-modal capabilities, and veterinary distributor networks adapting to direct-to-farm displacement. Competitive moves concentrate on M&A to secure regional hub capacity and strategic partnerships to access last-mile drone delivery pilots.
Within the captive distribution tier, Zoetis Inc. and Merck Animal Health exemplify vertically integrated network control spanning manufacturer-to-farm channels. Boehringer Ingelheim Animal Health occupies a position defined by specialized vaccine logistics protocols that exceed baseline regulatory requirements. These three entities represent the dominant competitive anchors against which third-party providers and traditional distributors must differentiate.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Phibro Animal Health Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive distribution networks at Zoetis Inc., Merck Animal Health, and Boehringer Ingelheim Animal Health anchor pricing power through direct-to-farm channels that bypass intermediary markups. This backward integration into last-mile delivery compresses margins for third-party cold-chain specialists while concentrating volume with operators capable of farm-gate temperature compliance.
Pricing Analysis
Capacity additions in India's PLI-driven pharmaceutical clusters are reshaping price floors for temperature-controlled warehousing services. Contract-based long-term offtake dominates as large integrated protein producers in Nebraska and Texas negotiate scheduled vaccine delivery agreements directly with manufacturers. Price differentiation separates FDA-validated cold storage from standard refrigerated facilities, with certification tier and geographic delivery cost as primary drivers. Cost compression in third-party logistics is intensifying because EMA-mandated continuous temperature-monitoring infrastructure requires capital reserves that fragmented regional operators lack. Small veterinary clinics exhibit highest price sensitivity; pharmaceutical manufacturers with captive networks show lowest.
Supply Chain Analysis
Dry ice supply rests on industrial gas producers concentrated in Germany and the US Midwest, creating geographic concentration risk for international vaccine air freight. Liquid nitrogen for cryogenic cellular therapy transport draws from energy-intensive manufacturing hubs in Germany and France. Specialized refrigerants for cold-chain equipment hinge on European chemical producers facing REACH-mandated phase-down timelines. Single-source vulnerability in industrial gas supply exposes vaccine shipments to capacity constraints during peak agricultural seasons. Distribution runs through vertically integrated manufacturer networks and third-party cold-chain specialists with multi-modal capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because livestock vaccine demand concentrates in expanding agricultural economies with underpenetrated cold-chain infrastructure. Regulatory tightening on temperature compliance creates durable barriers that favor capital-rich operators.
For Market Incumbents: Lock in regional hub capacity through targeted facility investments near Brazil's cattle vaccination corridors and India's pharmaceutical clusters. Consolidate position by acquiring third-party cold-chain specialists lacking capital for FDA and EMA compliance retrofitting. Channel control through direct-to-farm contracts with large protein producers defends against margin compression from intermediary displacement.
For New Entrants and Emerging Players: Remote pastoral regions in Rwanda and Kenya present underserved buyer archetypes reachable through regulatory sandbox drone delivery programs. Vietnam's dairy expansion zones around Ho Chi Minh City offer white-space positioning for biologics distributors ahead of infrastructure maturation. Specialist positioning in CO2-based sustainable cooling systems addresses EU Green Deal retrofit demand.
For Investors and Strategic Acquirers: Roll-up economics work for regional cold-chain specialists because EMA Qualified Person certification scarcity constrains organic expansion timelines. Mid-cap targets with validated temperature-monitoring infrastructure and existing pharmaceutical manufacturer relationships offer platform consolidation potential. Watch dry ice supply concentration and industrial gas capacity announcements as inflection indicators for international vaccine freight economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Last-Mile Delivery | Direct-to-farm contracts with Nebraska and Texas protein producers bypass distributor markups. |
| CO2-Based Refrigerant System Retrofit | German and French warehouse operators meet EU Green Deal hydrofluorocarbon phase-down deadlines. |
| Drone Delivery Network Pilot | Rwanda and Kenya regulatory sandboxes enable reach into remote pastoral regions. |
| IoT Sensor Platform Deployment | Real-time temperature tracking cuts spoilage rates for Brazilian cattle vaccination corridors. |
| Qualified Person Certification Investment | EMA-mandated batch release signatories accelerate European market entry timelines. |
Research Methodology
Direct dialogue with veterinary pharmaceutical logistics directors, cold-chain operations managers, regulatory affairs specialists at EMA and FDA, and procurement leads at integrated protein producers grounded qualitative assessment. Secondary validation drew from FDA current Good Distribution Practice guidance documents, EMA Veterinary International Conference on Harmonisation guidelines, USDA interstate movement permitting records, and customs trade data on veterinary biologics flows. Bottom-up service-type segmentation triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Segment-level value outputs across transportation, inventory management, warehousing, and distribution services were modeled against end-user procurement patterns and product-type regulatory stringency variations. CAGRs were derived from growth driver elasticity analysis applied to baseline capacity and demand estimates. Modeled dimensions included service type, end-user category, product type, delivery mode, and regional regulatory cluster. Forecast inputs incorporated cold-chain infrastructure investment pipelines, livestock population growth projections, and regulatory compliance cost trajectories.
Inputs from pharmaceutical manufacturer disclosures and logistics operator facility announcements were available through the study window; gaps in private contract pricing and spoilage rate data introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions on regulatory timeline adherence and infrastructure investment execution. Disease outbreak frequency, energy price volatility, and trade restriction implementation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Europe Veterinarians Market
Veterinary
Global Dog Vaccines Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Otc Pet Medication Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Spay and Neuter Market