
 Global Hematology Analyzers and Reagents Market | 2026-2036
Global Hematology Analyzers and Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematology Analyzers and Reagents Market Foresight
High-throughput 5-part differential specification is collapsing the cost barrier between reference laboratories and mid-tier diagnostic chains. Sysmex Corporation leverages its laser-based optical scatter technology to sustain premium positioning in automated cell counting. Danaher Corporation anchors its hematology portfolio through Beckman Coulter's installed base of impedance analyzers across North American health networks. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes aggressively on instrument placement economics in emerging markets.
Hematology analyzers and reagents constitute automated diagnostic systems that quantify blood cell populations through flow cytometry, impedance, or optical light scattering methods, typically processing 60–120 samples per hour with CVs below 3% for critical parameters; their primary purpose is enabling rapid complete blood count determination for anemia, infection, and malignancy screening. The analyzer hardware segment dominates capital expenditure cycles with replacement-driven revenue, while flow cytometry technology leads growth due to expanding leukemia and lymphoma diagnostic protocols. Reagent consumables capture recurring margin pools as test volumes scale faster than instrument placements across diagnostic labs and blood donation centers.
FDA clearance pathways for Class II hematology devices and IVDR technical documentation requirements in Europe impose substantial validation burdens that filter smaller reagent suppliers from commercial access. ISO 15189 accreditation standards for medical laboratories in Asia-Pacific markets are accelerating demand for integrated quality control materials and calibrator packages. WHO prequalification initiatives for essential diagnostics in low-resource settings are opening procurement channels for compact analyzer platforms. Stakeholders must weigh regulatory compliance investment against the volume economics of emerging market expansion where national tender processes favor bundled reagent contracts.
Market Dynamics
Automated 5-part differential hematology analyzers are collapsing the historical price-performance gap between reference laboratories and mid-tier diagnostic chains, forcing reagent suppliers to rebundle consumable contracts around throughput tiers rather than instrument class.
Growth Catalysts
- India's district-level diagnostic expansion:National health missions are deploying compact CBC platforms to sub-district hospitals, creating instrument placement volume that locks in multi-year reagent commitments.
- IVDR-equivalent FDA enforcement:The FDA's alignment with European quality documentation standards is filtering substandard reagent suppliers from commercial access, consolidating margin pools among qualified manufacturers.
- Laser-based optical scatter adoption:Flow cytometry-enhanced analyzers are penetrating community laboratory networks previously served by impedance-only systems, expanding addressable test menus.
Market Restraints
- Reagent input concentration:High-purity flurochromes and monoclonal antibody conjugates for 5-part differential testing concentrate among Japanese and German chemical suppliers, exposing margins to currency and logistics volatility.
- Capital intensity of analyzer replacement:Six-to-eight-year depreciation cycles for installed impedance systems delay upgrade revenue, compressing near-term hardware revenue pools.
- Substitution by point-of-care devices:Handheld CBC platforms for emergency and resource-limited settings are capturing screening volumes that previously flowed to centralized laboratories.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Streamlined registration for WHO-prequalified diagnostics is opening procurement channels for compact analyzer platforms in Latin America's largest public health system.
- AI-assisted morphological review:Integration of automated digital microscopy with analyzer output is creating premium service tiers for oncology screening protocols.
- Direct-to-laboratory reagent distribution:E-procurement platforms are disintermediating traditional distributor networks in Southeast Asian markets, capturing margin through volume aggregation.
Industry Challenges
- ISO 15189 calibration complexity:Asia-Pacific laboratory accreditation mandates are forcing reagent manufacturers to supply integrated quality control packages, extending validation timelines.
- Legacy system integration friction:Middleware compatibility between new optical scatter analyzers and existing laboratory information systems requires costly customization for mid-tier chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematology Analyzers and Reagents Market |
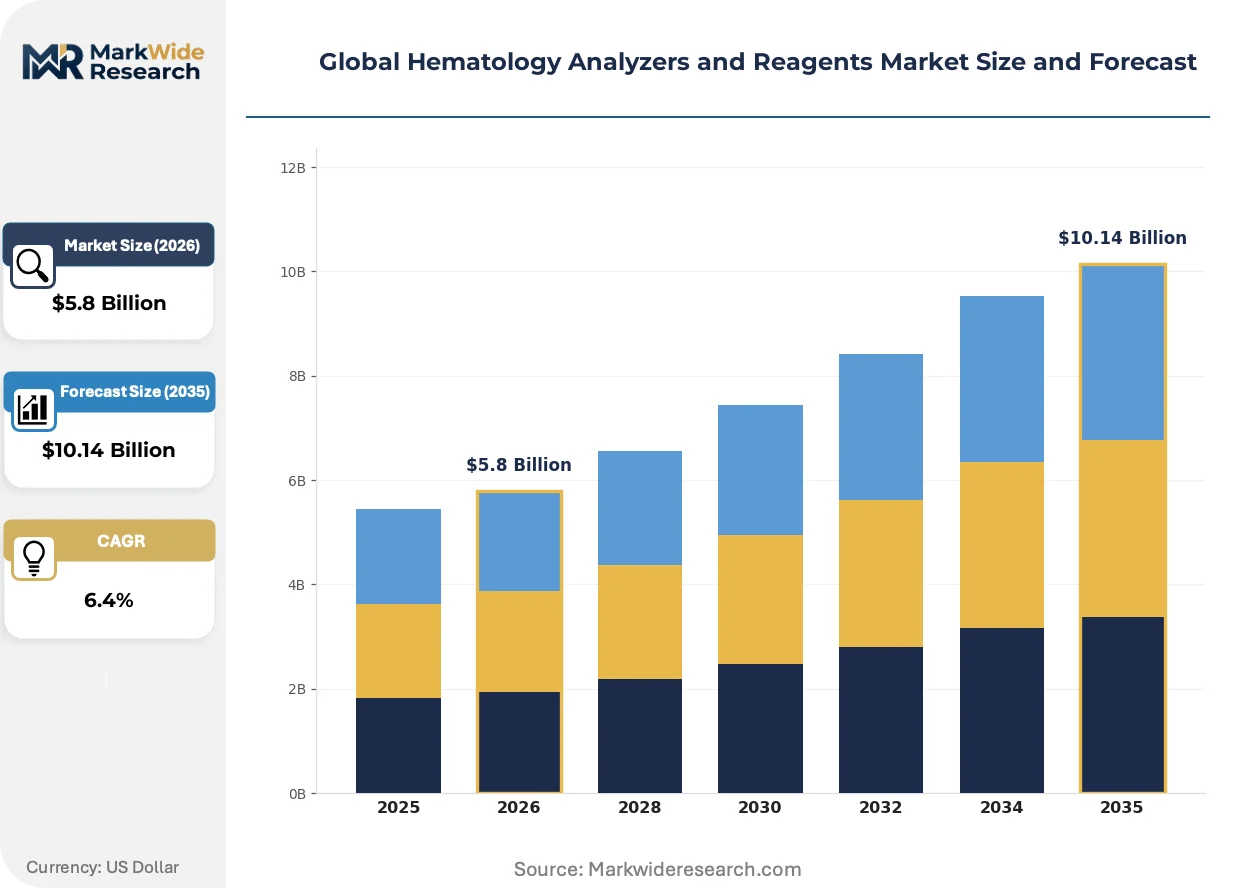
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Reagents, Control Materials, Calibrators Application: Clinical Diagnostics, Blood Banks, Research Laboratories, Pharmaceutical Testing End User: Diagnostic Labs, Blood Donation Centers, Academic Institutions, Contract Research Organizations Technology: Flow Cytometry, Impedance, Optical Light Scattering, Laser-Based |
| Companies Covered | Abbott Laboratories, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Sysmex Corporation, Horiba Ltd., Bio-Rad Laboratories, Danaher Corporation, F. Hoffmann-La Roche Ltd., Nihon Kohden Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematology Analyzers and Reagents Market Shifts & Advancements
Digital morphology and artificial intelligence are converging to automate peripheral blood smear review, compressing turnaround times for abnormal flag follow-up while reducing skilled technologist dependency in high-volume settings.
Microfluidic sample processing is fragmenting the traditional analyzer-reagent pairing model. Disposable cartridge-based systems integrate fluidics, reagents, and waste containment into single-use consumables. Community laboratories in India and Indonesia are adopting these platforms for remote deployment. The technology is fragmenting capital expenditure structures by converting fixed instrument costs into variable per-test economics.
Europe's MDR technical documentation requirements are extending validation timelines for hematology reagent kits. Manufacturers must submit clinical performance data for each antibody clone and fluorochrome combination. The regulation is compressing the supplier base as smaller reagent blenders exit rather than absorb compliance costs.
Hospital networks are consolidating reagent procurement through centralized tenders that bundle CBC, coagulation, and chemistry consumables under multi-year sole-source agreements. Diagnostic chains in Germany and France are responding by demanding price-volume guarantees and dedicated field service commitments. The shift is concentrating purchasing leverage among the largest health system buyers.
Global Hematology Analyzers and Reagents Market Segmentation
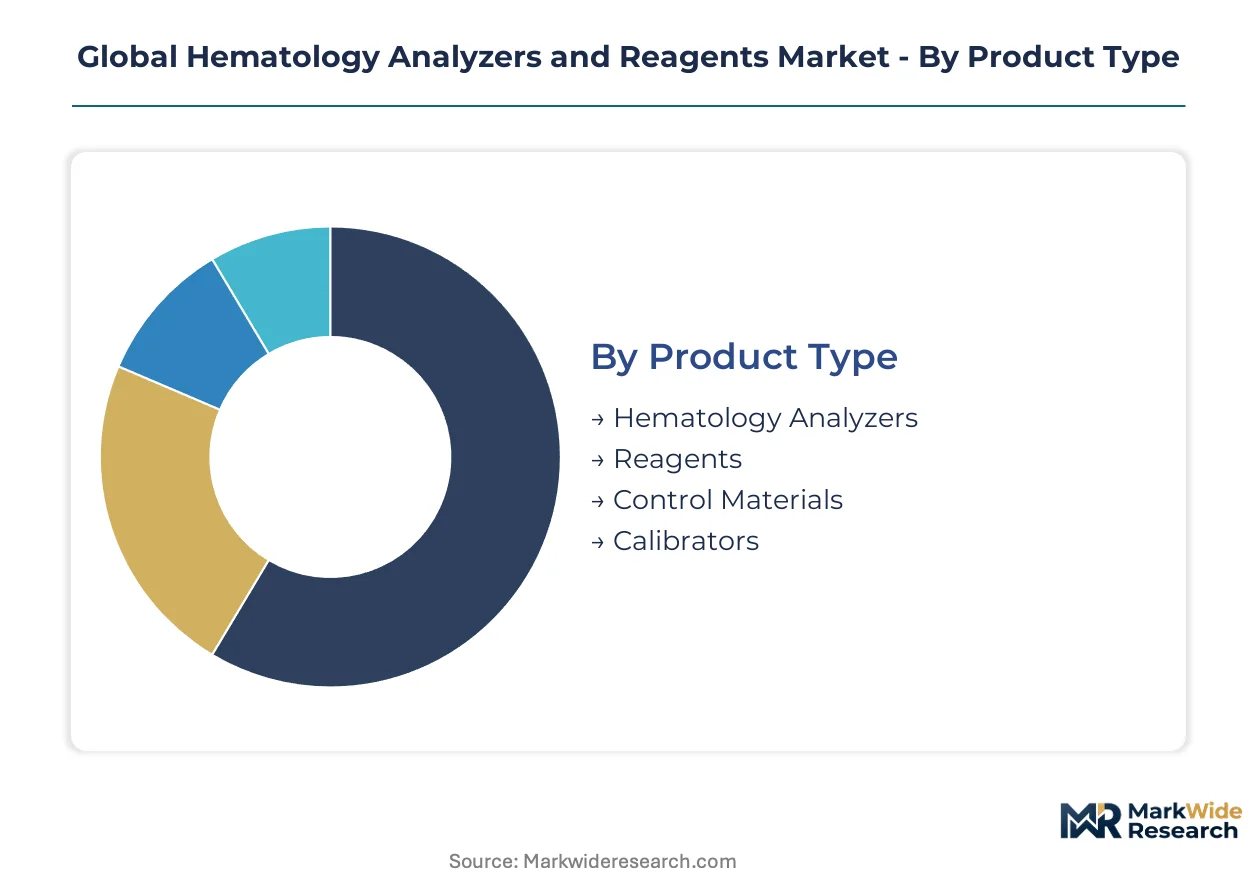
Hematology market segmentation reflects divergent regulatory burdens and capital intensity across hardware and consumable categories. Product type and technology classifications determine compliance pathways, while application and end-user dimensions shape procurement concentration and reagent contract structures.
Product Type:
FDA Class II device clearances and IVDR technical documentation requirements create tiered barriers to entry across hardware and consumable segments.
- Hematology Analyzers:Automated cell counting platforms integrate fluidics, optics, and software modules for 60–120 samples per hour throughput. Hospital networks in Germany and France are consolidating procurement through multi-year sole-source agreements that bundle hardware with captive reagent commitments.
- Reagents:High-purity fluorochromes and monoclonal antibody conjugates for 5-part differential testing demand validated antibody clone documentation under MDR requirements. CDSCO registration mandates in India are filtering substandard suppliers from district-level diagnostic tenders.
- Control Materials:Stabilized blood cell suspensions and synthetic analogs verify analyzer precision across daily quality control protocols.
- Calibrators:Certified reference materials traceable to international standards anchor measurement accuracy for accredited laboratories.
Established volume favors analyzers; emerging adoption favors reagents.
Application:
Test volume concentration and reimbursement structures differentiate revenue stability across clinical and non-clinical use cases.
- Clinical Diagnostics:Complete blood count determination for anemia, infection, and malignancy screening constitutes the core workload for hospital laboratories and diagnostic chains. India's national health missions are deploying compact CBC platforms to sub-district hospitals, locking in instrument placement volume.
- Blood Banks:Donor screening and component processing require high-throughput platforms with extended linearity ranges for extreme cell counts. WHO prequalification initiatives are opening procurement channels for compact analyzer platforms in resource-limited settings.
- Research Laboratories:Investigational protocols demand flexible analyzer configurations with customizable gating parameters.
- Pharmaceutical Testing:Toxicology and hematology safety studies drive demand for GLP-compliant systems with audit trail documentation.
Clinical diagnostics captures the largest revenue pool; blood banks are climbing the fastest.
End User:
Accreditation requirements and procurement scale fragment customer economics across institutional categories.
- Diagnostic Labs:High-throughput reference laboratories and mid-tier chains operate under ISO 15189 mandates requiring integrated quality control packages. E-procurement platforms in Southeast Asia are disintermediating traditional distributor networks, capturing margin through volume aggregation.
- Blood Donation Centers:National blood service networks prioritize instrument reliability and rapid turnaround for donor eligibility screening.
- Academic Institutions:Teaching hospitals balance research flexibility with clinical service obligations.
- Contract Research Organizations:Central laboratory services for multi-site trials demand harmonized protocols across geographic locations.
Diagnostic labs dominate instrument placements; blood donation centers concentrate reagent volume.
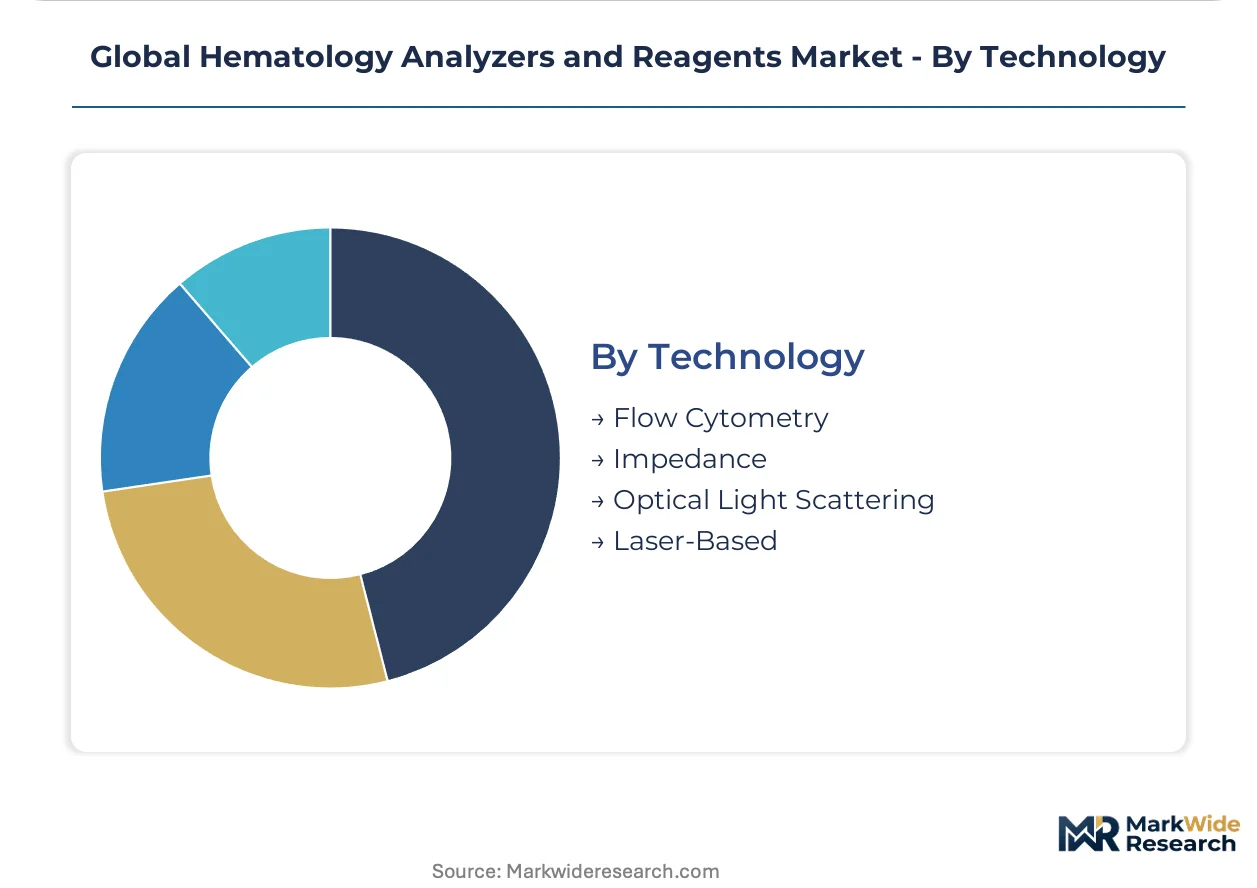
Technology:
Detection method determines specification tier, throughput ceiling, and competitive replacement dynamics.
- Flow Cytometry:Fluorescence-activated cell sorting enables 5-part leukocyte differential and reticulocyte enumeration with high precision. Laser-based optical scatter systems are penetrating community laboratory networks previously served by impedance-only platforms.
- Impedance:Coulter principle cell counting remains the cost-optimized foundation for high-volume screening in resource-constrained settings.
- Optical Light Scattering:Multi-angle detection discriminates cell populations by volume and internal complexity.
- Laser-Based:Solid-state laser excitation paired with photomultiplier detection achieves the lowest coefficient of variation for critical parameters.
Impedance retains the largest installed base; laser-based platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German precision optics suppliers concentrate high-purity fluorochrome production, exposing reagent margins to currency volatility while Indian instrument deployment accelerates fastest. National procurement frameworks and laboratory accreditation mandates are fragmenting competitive access across major healthcare markets.
United States
Hospital network consolidation drives multi-year sole-source reagent contracts bundling CBC, coagulation, and chemistry consumables. FDA enforcement of IVDR-equivalent quality standards filters substandard suppliers from commercial access. The Research Triangle and Greater Boston clusters anchor GLP-compliant system development for pharmaceutical toxicology applications.
Germany
Diagnostic chains demand price-volume guarantees and dedicated field service commitments under centralized tenders. MDR technical documentation requirements extend validation timelines for hematology reagent kits. The Rhine-Main and Bavarian industrial corridors concentrate high-purity monoclonal antibody conjugate manufacturing for 5-part differential testing.
India
National health missions deploy compact CBC platforms to sub-district hospitals, locking in instrument placement volume with multi-year reagent commitments. CDSCO registration mandates filter suppliers from district-level diagnostic tenders. Maharashtra and Karnataka clusters manufacture cost-optimized impedance analyzers for domestic and Southeast Asian export markets.
Japan
Laser-based optical scatter technology sustains premium positioning in automated cell counting for reference laboratories. PMDA quality documentation requirements align with MDR-equivalent standards for reagent validation. The Kanto region around Tokyo anchors solid-state laser and photomultiplier component supply chains.
Brazil
ANVISA fast-track pathways for WHO-prequalified diagnostics open procurement channels in Latin America's largest public health system. Blood donation centers prioritize instrument reliability for rapid donor eligibility screening. São Paulo and Rio de Janeiro clusters service regional distribution networks for compact analyzer platforms.
Global Hematology Analyzers and Reagents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with laser-based optical scatter specialists commanding premium positioning while impedance-focused manufacturers compete on instrument placement economics. The market structures around three tiers: integrated multinationals with captive reagent portfolios, regional specialists leveraging regulatory fast-tracks, and emerging market challengers optimizing per-test economics. Consolidation pressure intensifies as hospital networks bundle procurement across diagnostic modalities. Strategic moves center on backward integration into fluorochrome supply and geographic expansion through WHO prequalification channels.
Among precision optics and diagnostics multinationals, Sysmex Corporation exemplifies technology-driven premium positioning, while Danaher Corporation anchors scale through installed base leverage. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies the emerging market cost-optimization archetype. These three represent the dominant competitive vectors: optical innovation, portfolio breadth, and placement economics.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Sysmex Corporation |
| Horiba Ltd. |
| Bio-Rad Laboratories |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Nihon Kohden Corporation |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Microfluidic cartridge systems displacing traditional analyzer-reagent pairings simultaneously concentrate supply geography in Japanese and German precision optics corridors while fragmenting pricing economics into variable per-test models across Indian and Indonesian community laboratories.
Pricing Analysis
IVDR-equivalent FDA enforcement dictates the pricing tier structure across hematology reagent markets. Three-tier pricing structure across premium laser-based optical scatter, standard impedance, and economy compact cartridge systems separates Sysmex-level precision from mid-tier diagnostic chains and emerging market point-of-care deployments. Cost compression in economy tiers is intensifying because Brazilian and Indian national tenders favor bundled multi-year reagent contracts. Hospital networks in Germany and France exhibit lowest price sensitivity due to sole-source bundling leverage, while district-level diagnostic labs in India face acute budget constraints.
Supply Chain Analysis
Shanghai-to-Rotterdam maritime transit underwrites fluorochrome and monoclonal antibody logistics for European reagent manufacturers. High-purity fluorochrome production concentrates in Japan and Germany; impedance analyzer assembly anchors in China and India. Raw material dependencies include solid-state laser components, photomultiplier tubes, and validated antibody clones. Single-source vulnerability persists for Japanese-sourced optical scatter modules. Distribution runs through hospital network centralized procurement offices and Southeast Asian e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instrument placement volume in India's district-level diagnostic expansion signals early-cycle penetration tailwinds for automated CBC platforms, with reagent contract lock-in creating predictable recurring revenue pools.
For Market Incumbents: Fortify captive reagent portfolios through backward integration into fluorochrome supply chains threatened by Japanese and German chemical supplier concentration. Anchor installed base leverage via middleware compatibility investments that raise switching costs for mid-tier diagnostic chains confronting legacy system integration friction. For New Entrants and Emerging Players: Brazil's ANVISA fast-track pathway for WHO-prequalified diagnostics opens procurement channels in Latin America's largest public health system with streamlined registration timelines. Target compact analyzer placements in blood donation centers prioritizing instrument reliability over premium specification. Pursue direct-to-laboratory e-procurement distribution in Southeast Asian markets to disintermediate traditional distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic chains in Germany and France consolidating procurement through centralized tenders demanding price-volume guarantees. Long-term viability centers on reagent consumable recurring revenue stability rather than hardware replacement cycles. Monitor AI-assisted morphological review adoption rates as inflection indicator for premium service tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Opens procurement channels for compact analyzers in resource-limited settings under national health missions. |
| Backward Integration into Fluorochromes | Captures margin pools concentrated among Japanese and German chemical suppliers for 5-part differential testing. |
| AI-Assisted Morphology Integration | Creates premium service tiers for oncology screening protocols in reference laboratory networks. |
| E-Procurement Platform Development | Disintermediates distributor networks in Southeast Asia through volume aggregation and direct laboratory relationships. |
| Middleware Compatibility Investment | Reduces legacy system integration friction for optical scatter analyzers in mid-tier diagnostic chains. |
Research Methodology
The analysis maps hematology analyzers, reagent consumables, control materials, and calibrator segments, each validated through laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Primary interview findings triangulate against FDA 510(k) filings, IVDR technical documentation databases, CDSCO registration records, and WHO prequalification lists. Bottom-up instrument placement and reagent volume estimates reconcile with top-down diagnostic laboratory expenditure data.
Consistency checks validate volume and value outputs against hospital capital expenditure disclosures, national health mission procurement announcements, and blood bank operational statistics across the analysis window. Segmentation dimensions span product type, technology tier, application, and end-user accreditation level. CAGRs derive from instrument replacement cycle modeling and reagent consumption per installed base unit. Forecast inputs incorporate district-level diagnostic expansion timelines and MDR/IVDR compliance cost absorption curves.
Decision-makers should treat outputs as directional under assumptions of sustained national health mission funding and stable fluorochrome supply logistics; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as point-of-care substitution rates and AI-assisted morphology adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Global Graduated Cylinder Market