
 Japan Veterinary Healthcare Market | 2026-2036
Japan Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Veterinary Healthcare Market Foresight
The revised Japanese Agricultural Standards for veterinary biologics is repositioning domestic manufacturing requirements, forcing new entrants to absorb higher validation costs before commercialization. MSD Animal Health leverages its Osaka production base to sustain JAS-certified output for the domestic livestock sector. Nippon Zenyaku Kogyo anchors its position through deep ties with prefectural agricultural cooperatives. Zoetis competes by controlling import channels for novel therapeutics not yet manufactured locally.
Japan veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion and production animals, spanning biologics with specified antigen purity thresholds, small-molecule pharmaceuticals, and in-clinic diagnostic platforms calibrated to domestic breed reference ranges. The sector serves commercial livestock operations, companion animal households, and zoological institutions requiring species-specific therapeutic protocols. Pharmaceutical and vaccine segments command the deepest margin pools due to multi-year development timelines and limited generic substitution. Diagnostic imaging and wearable devices are expanding fastest as metropolitan clinics invest in predictive health monitoring for aging companion animal populations. Telemedicine adoption remains structurally constrained by regulatory limits on remote prescribing authority.
PMDA batch-release requirements and METI quality management directives shape product registration timelines and post-market surveillance obligations for all marketed veterinary therapeutics. JIS standards for diagnostic equipment interoperability further constrain vendor selection for clinic networks seeking integrated data architectures. Prefectural veterinary medical associations administer continuing education mandates that influence technology uptake velocity across sub-regions. Stakeholders must monitor whether METI expands telemedicine reimbursement codes beyond the current pilot prefectures, as this would reshape capital allocation across service delivery models.
Market Dynamics
METI's digital health record mandate is compressing clinic technology refresh cycles, forcing independent operators in Kanto and Kansai to consolidate or partner with platform vendors for compliance.
Growth Catalysts
- Pet insurance density:Household penetration in Tokyo's 23 wards exceeds national averages by a factor of three, generating predictable reimbursement flows that subsidize advanced diagnostic procedures.
- JAS biologics standards:Revised antigen purity thresholds are redirecting procurement toward domestic-certified manufacturers, insulating local production from import volatility.
- Prefectural specialist networks:Osaka and Aichi have established formal referral protocols linking primary clinics to university hospitals, concentrating complex caseloads and equipment utilization.
Market Restraints
- Import API concentration:Active pharmaceutical ingredients for novel therapeutics originate from a narrow supplier base in East Asia, exposing formulators to shipping disruptions and customs delays.
- PMDA batch-release timelines:Extended laboratory validation for imported biologics stretches working capital cycles for distributors serving livestock cooperatives.
- Telemedicine prescribing limits:METI's current framework restricts remote prescription authority to pilot prefectures, capping service model innovation for multi-location clinic groups.
Strategic Opportunities
- Kyushu corridor expansion:Fukuoka's companion animal household growth outpaces clinic infrastructure, creating first-mover advantages for diagnostic platform deployment.
- Wearable-predictive convergence:Integration of continuous glucose monitors with AI alert systems is opening subscription revenue streams for aging pet management.
- Prefectural telemedicine pilots:METI's planned reimbursement code expansion beyond Tokyo and Osaka would unlock capital-light service delivery for rural veterinary networks.
Industry Challenges
- Diagnostic equipment interoperability:JIS standards for data exchange between imaging systems and practice management software are fragmenting vendor selection for clinic networks.
- Specialist credentialing timelines:Prefectural veterinary medical association continuing education mandates are lengthening certification pathways for advanced surgical and imaging competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Veterinary Healthcare Market |
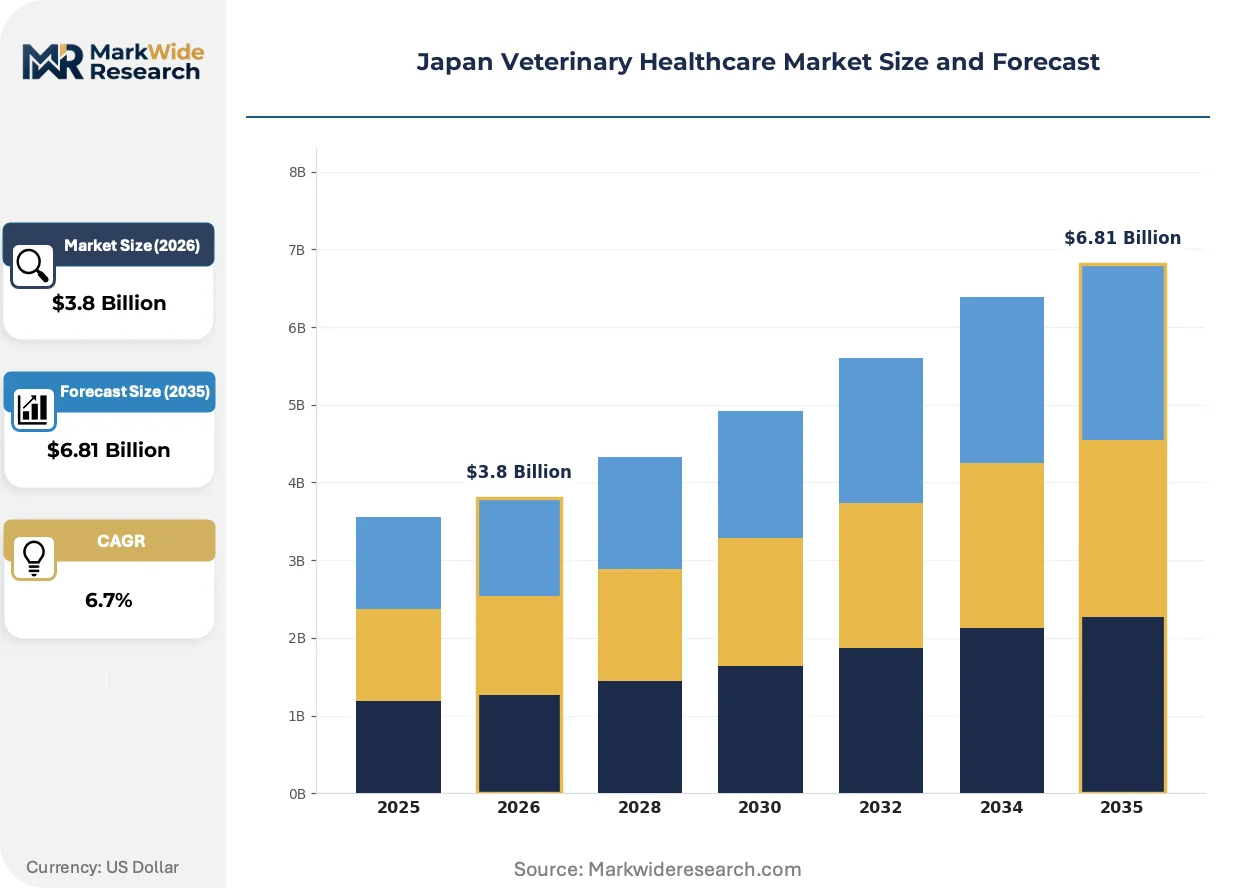
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Pharmaceuticals, Consumables, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Zoos Technology: Genetic Engineering, Telemedicine, Wearable Devices, Diagnostic Imaging Service Type: Consultation, Surgical Procedures, Preventive Care, Emergency Services |
| Companies Covered | Elanco Animal Health Incorporated, Merck & Co., Inc. (MSD Animal Health), Zoetis Inc., Nippon Zenyaku Kogyo Co., Ltd., Nihon Nohyaku Co., Ltd., Kyoritsu Seiyaku Corporation, FUJIFILM Holdings Corporation, Nisseiken Co., Ltd., Boehringer Ingelheim GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Veterinary Healthcare Market Shifts & Advancements
Diagnostic platforms and data infrastructure are displacing reactive treatment models across Japan's metropolitan clinic networks, with capital allocation shifting toward predictive health monitoring and integrated record systems.
Artificial intelligence algorithms for radiographic interpretation are integrating into ultrasound and CT workflows at university-affiliated hospitals in Tokyo and Hokkaido. Large companion animal clinics with monthly caseloads exceeding 500 patients are adopting these tools to compress specialist review times. The technology is integrating routine screening into standard wellness protocols, elevating early disease detection rates without proportional staffing increases.
METI's quality management directives for veterinary digital health records are mandating encrypted cloud storage and standardized data fields across all licensed clinics. The regulation forces legacy server-based practices to migrate or face inspection penalties. Livestock-focused operators in Tohoku are responding fastest, driven by agricultural cooperative pressure for traceable treatment histories in export-certified herds.
Subscription-based preventive care packages are replacing episodic billing at companion animal clinics in Kanto. Younger pet owners in Saitama and Chiba prefectures are purchasing annual wellness contracts bundling vaccinations, blood panels, and telehealth consultations. This behavioral shift concentrates revenue predictability for clinic operators while compressing traditional fee-for-service margins on routine procedures.
Japan Veterinary Healthcare Market Segmentation
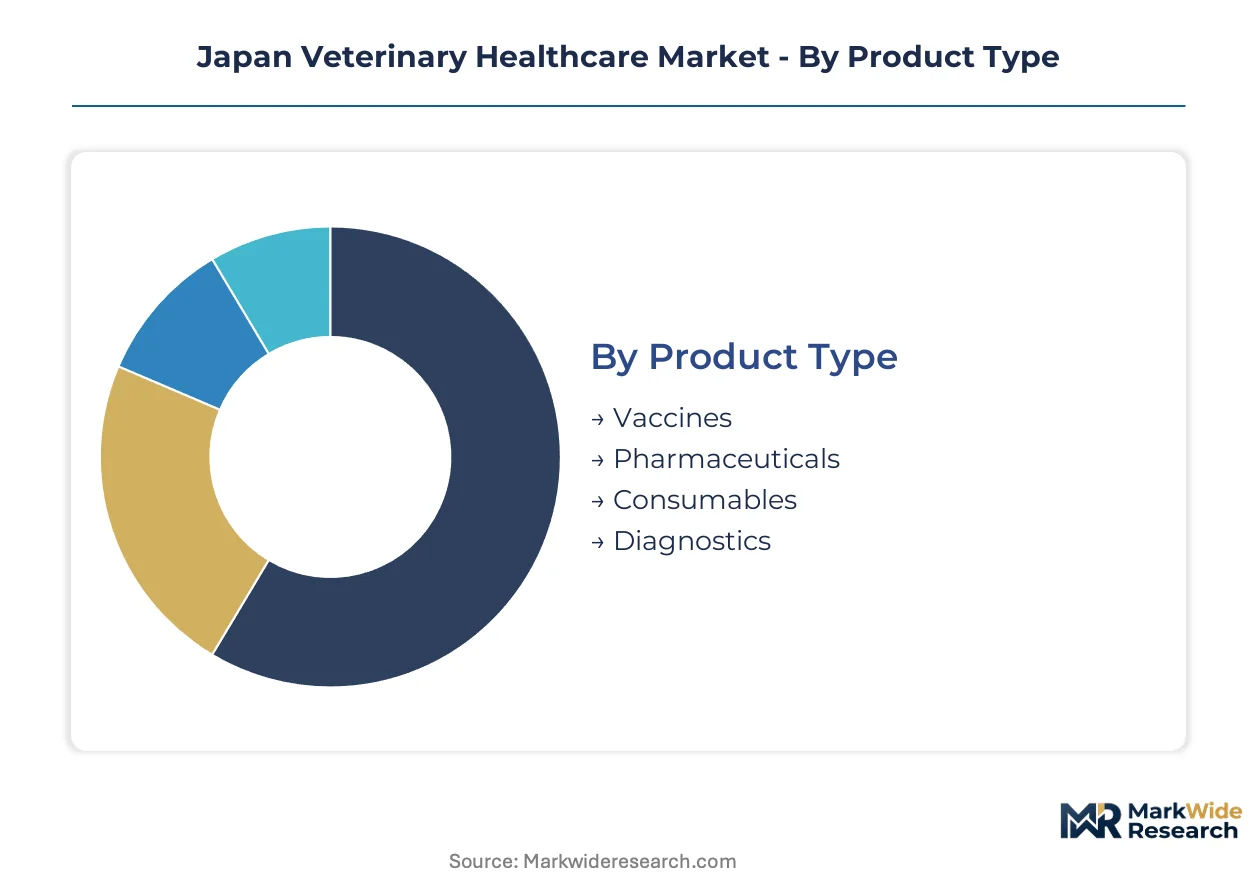
Segmentation in Japan's veterinary healthcare market reveals how regulatory frameworks, reimbursement structures, and species-specific demands fragment procurement patterns across product and service categories. Understanding these divisions clarifies where METI mandates and prefectural veterinary association protocols concentrate investment.
Product Type:
The customization-vs-standardization spectrum runs from bespoke biologics requiring JAS-certified antigen purity to commoditized consumables governed by volume procurement contracts.
- Vaccines:JAS-certified biologics with specified antigen thresholds command premium positioning through domestic manufacturing requirements. Prefectural agricultural cooperatives in Tohoku and Hokkaido anchor demand for livestock immunization programs, with PMDA batch-release timelines stretching working capital cycles for imported alternatives.
- Pharmaceuticals:Small-molecule therapeutics span novel compounds under patent protection and established generics with limited substitution pressure. Tokyo and Osaka companion animal clinics drive consumption of advanced therapeutics not yet manufactured locally, exposing formulators to API supply concentration from East Asian suppliers.
- Consumables:Syringes, surgical sutures, and wound care materials flow through volume-based procurement agreements with clinic networks.
- Diagnostics:In-clinic platforms calibrated to domestic breed reference ranges require JIS-standardized interoperability for network integration.
Leading the category by volume: Pharmaceuticals. Growing fastest: Diagnostics.
End User:
Customer concentration tilts toward metropolitan service providers where pet insurance density and specialist referral infrastructure enable advanced procedure reimbursement.
- Veterinary Clinics:Independent operators across Kanto and Kansai face METI digital health record mandates compressing technology refresh cycles. Subscription-based preventive care packages are displacing episodic billing in Saitama and Chiba prefectures, concentrating revenue predictability for operators.
- Animal Hospitals:University-affiliated facilities in Tokyo and Hokkaido integrate AI-assisted radiographic interpretation into ultrasound and CT workflows. Monthly caseloads exceeding 500 patients justify capital deployment for predictive health monitoring platforms serving aging companion animal populations.
- Research Institutes:Prefectural agricultural experiment stations validate biologics efficacy for JAS certification pathways.
- Zoos:Species-specific therapeutic protocols require customized pharmaceutical compounding and specialist veterinary consultation.
Highest margin concentration: Animal Hospitals. Expanding most quickly: Veterinary Clinics.
Technology:
Maturity gradients separate established platforms with defined regulatory pathways from emerging modalities facing METI pilot constraints.
- Genetic Engineering:Recombinant vaccine production and gene therapy development operate under PMDA biologics oversight with extended validation timelines.
- Telemedicine:METI's current framework restricts remote prescription authority to pilot prefectures, capping service model innovation for multi-location clinic groups seeking capital-light rural expansion.
- Wearable Devices:Continuous glucose monitors with AI alert systems are opening subscription revenue streams for aging pet management in metropolitan markets.
- Diagnostic Imaging:AI algorithms for radiographic interpretation compress specialist review times at high-volume clinics, integrating routine screening into standard wellness protocols without proportional staffing increases.
Widest installed base: Diagnostic Imaging. Steepest expansion trajectory: Wearable Devices.
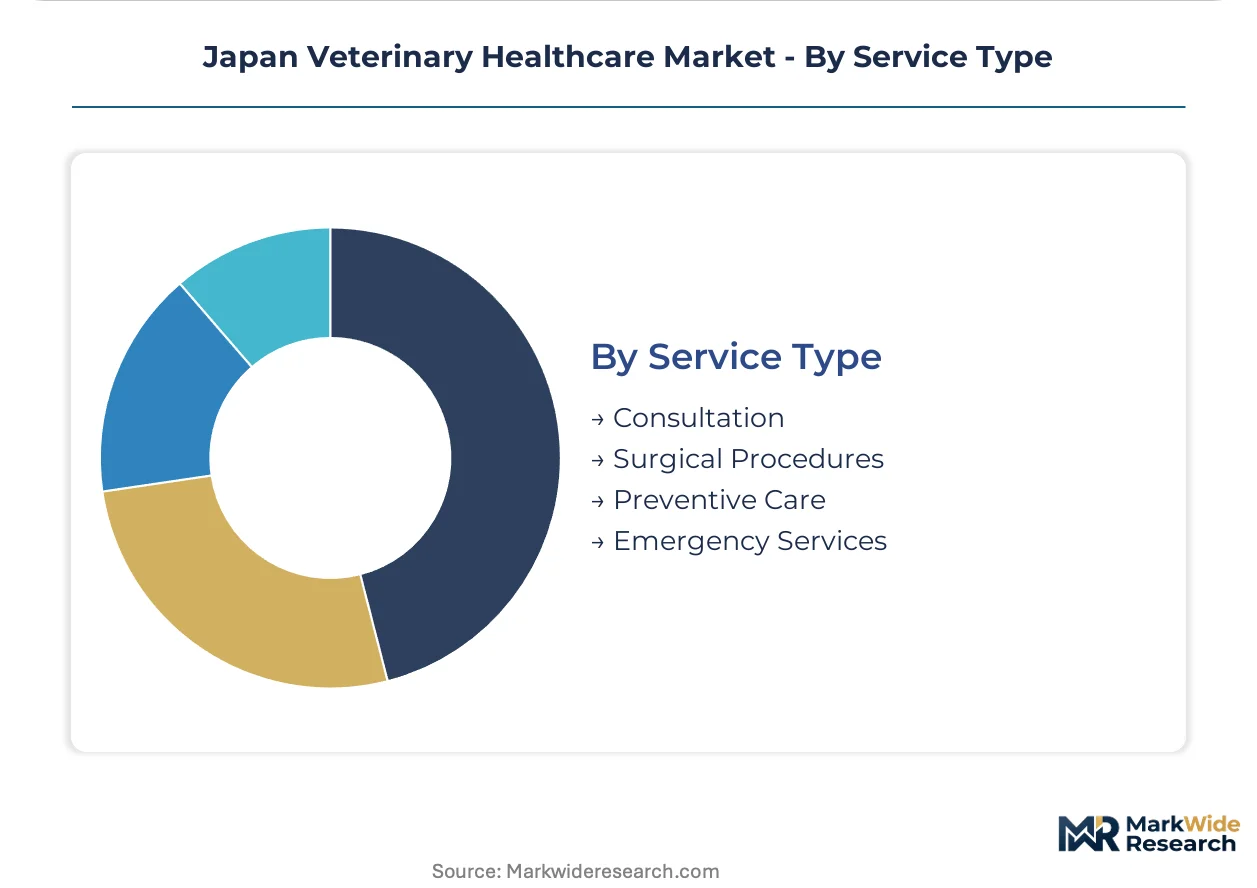
Service Type:
Revenue stability varies from predictable preventive contracts to episodic emergency interventions with irregular demand patterns.
- Consultation:Telehealth consultations bundled into annual wellness contracts are shifting service delivery toward remote channels where regulatory permits.
- Surgical Procedures:Complex interventions concentrate at university hospitals linked through Osaka and Aichi prefectural referral protocols, concentrating equipment utilization and specialist credentialing requirements.
- Preventive Care:Vaccination and wellness screening generate recurring revenue streams subsidized by pet insurance penetration rates exceeding national averages threefold in Tokyo's 23 wards.
- Emergency Services:After-hours critical care demands 24-hour staffing infrastructure with uneven utilization across rural prefectures.
Most stable revenue: Preventive Care. Highest per-transaction value: Surgical Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance density and specialist referral infrastructure concentrate demand in Japan's metropolitan corridors, with METI digital health mandates accelerating platform investments across prefectural networks.
Kanto/Tokyo
Tokyo's 23 wards exhibit pet insurance penetration exceeding national averages threefold, generating predictable reimbursement flows that subsidize advanced diagnostic procedures. METI's digital health record mandate compresses technology refresh cycles for independent operators across Saitama and Chiba prefectures. University-affiliated hospitals in the capital integrate AI-assisted radiographic interpretation into ultrasound and CT workflows.
Kansai/Osaka
Osaka anchors formal referral protocols linking primary clinics to university hospitals, concentrating complex caseloads and equipment utilization. Prefectural specialist networks established here channel aging companion animal populations toward predictive health monitoring platforms. MSD Animal Health leverages its Osaka production base to sustain JAS-certified output for domestic livestock operations.
Chubu/Nagoya
Aichi prefecture mirrors Osaka's referral infrastructure, directing specialist caseloads through university hospital linkages. Agricultural cooperatives in surrounding prefectures anchor demand for livestock immunization programs with traceable treatment histories. PMDA batch-release timelines stretch working capital cycles for distributors serving these cooperative networks.
Kyushu
Fukuoka's companion animal household growth outpaces clinic infrastructure, creating first-mover advantages for diagnostic platform deployment. Prefectural veterinary medical associations here administer continuing education mandates influencing technology uptake velocity. Agricultural experiment stations validate biologics efficacy for JAS certification pathways serving export-certified herds.
Hokkaido
Livestock-focused operators in Hokkaido respond fastest to METI quality management directives, driven by agricultural cooperative pressure for traceable treatment histories. University hospitals here integrate AI algorithms into radiographic workflows for high monthly caseloads. JAS biologics standards redirect procurement toward domestic-certified manufacturers insulating local production from import volatility.
Japan Veterinary Healthcare Market Competitive Landscape
Domestic producers anchor one tier; multinational specialists hold another through import channel control and novel therapeutic access. The market structures around JAS-certified manufacturing requirements, PMDA batch-release capabilities, and prefectural cooperative relationships. Three archetypes dominate: domestic biologics manufacturers with agricultural cooperative ties, multinational pharmaceutical houses with import licensing infrastructure, and diversified chemical conglomerates with diagnostic platform portfolios. Competitive moves concentrate on strategic partnerships with clinic networks and backward integration into API sourcing.
Among domestic pharmaceutical specialists, Nippon Zenyaku Kogyo Co., Ltd. and Nihon Nohyaku Co., Ltd. occupy positions exemplifying deep ties with prefectural agricultural cooperatives. Merck & Co., Inc. (MSD Animal Health) and Zoetis Inc. represent the multinational tier, anchoring access to novel therapeutics and controlled import channels. These named entities illustrate how competitive positioning fragments across certification compliance, distribution reach, and species-specific protocol development.
| Leading Market Players |
|---|
| Elanco Animal Health Incorporated |
| Merck & Co., Inc. (MSD Animal Health) |
| Zoetis Inc. |
| Nippon Zenyaku Kogyo Co., Ltd. |
| Nihon Nohyaku Co., Ltd. |
| Kyoritsu Seiyaku Corporation |
| FUJIFILM Holdings Corporation |
| Nisseiken Co., Ltd. |
| Boehringer Ingelheim GmbH |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap pharmaceutical formulators anchor procurement patterns across Japan's veterinary healthcare supply base, connecting PMDA batch-release timelines to working capital cycles that discipline pricing power at the distributor tier. Their embedded relationships with prefectural agricultural cooperatives insulate domestic JAS-certified biologics from import price volatility while compressing margins on non-certified alternatives.
Pricing Analysis
Premium pricing for short lead times dominates procurement decisions, with clinics paying markups to secure PMDA-released biologics against batch-validation delays. Three-tier pricing structure across JAS-certified premium, standard imported, and economy generic tiers differentiates offerings, with certification grade and volume scale as primary drivers. Cost compression in the standard tier is intensifying because API sourcing concentrates in East Asian suppliers exposed to shipping disruptions. Prefectural livestock cooperatives exhibit highest price sensitivity due to thin margins on export-certified herds, while Tokyo companion animal clinics show least sensitivity given pet insurance reimbursement density.
Supply Chain Analysis
Domestic-content mandates under revised JAS biologics standards are reshaping sourcing toward Japan-certified antigen production, redirecting procurement from import-dependent channels. Active pharmaceutical ingredients draw from concentrated supplier bases in China, South Korea, and India, with recombinant vaccine substrates and diagnostic platform sensors as critical component dependencies. Single-source vulnerability runs through East Asian API channels exposed to customs delays and geopolitical friction. Distribution runs through agricultural cooperative networks for livestock products and clinic platform vendors for companion animal diagnostics, with METI digital health record mandates accelerating consolidated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's veterinary healthcare market reads as supply-constrained, with PMDA batch-release bottlenecks for imported biologics propping pricing power for domestic JAS-certified manufacturers.
For Market Incumbents: Extend platform investments into predictive health monitoring to capture subscription revenue from aging companion animal populations. Deepen backward integration into API sourcing to mitigate East Asian supply concentration risks. Defensive consolidation through acquisition of distressed independent clinics in Kanto accelerates METI compliance scale while locking out emerging platform competitors. For New Entrants and Emerging Players: Agricultural cooperative procurement managers represent the most accessible channel partner type for JAS-certified biologics entry. White-space targets concentrate in Kyushu's underbuilt clinic infrastructure and wearable-predictive convergence for diabetic pet management. Fukuoka's companion animal household growth outpaces service capacity, offering first-mover positioning for diagnostic platform deployment through subscription-based preventive care contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap domestic formulators with dormant JAS certifications in Tohoku and Hokkaido, where agricultural cooperative relationships provide embedded distribution. Long-term viability hinges on telemedicine reimbursement code expansion beyond pilot prefectures. The signal to watch is METI's planned extension of remote prescribing authority, which would unlock capital-light rural service models and revalue clinic network assets.| Strategic Initiative | Industry Significance |
|---|---|
| JAS Biologics Certification Investment | Domestic antigen purity compliance insulates MSD Animal Health and Nippon Zenyaku Kogyo from import volatility. |
| Digital Health Record Platform Migration | METI-mandated encrypted cloud storage forces legacy server-based clinics toward vendor consolidation or partnership. |
| Prefectural Telemedicine Pilot Expansion | Remote prescribing authority beyond Tokyo and Osaka would restructure capital allocation across rural veterinary networks. |
| AI-Assisted Diagnostic Imaging Integration | University hospitals in Hokkaido compress specialist review times without proportional staffing increases. |
| Subscription Preventive Care Packaging | Annual wellness contracts in Saitama and Chiba concentrate revenue predictability while compressing fee-for-service margins. |
Research Methodology
Independent corroboration across veterinary clinic operators, pharmaceutical procurement leads, agricultural cooperative managers, and PMDA regulatory specialists underwrites the qualitative findings. Primary interviews with prefectural veterinary medical association administrators and livestock cooperative technical directors combined with secondary validation from METI quality management directives, JAS biologics standards documentation, and PMDA batch-release procedural filings. Bottom-up clinic capacity estimates and top-down pharmaceutical shipment data triangulate market sizing.
Comparable-period anchoring to historical pet insurance penetration trajectories and diagnostic equipment installation cycles structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology maturity, and service delivery mode, with species-specific protocol requirements and prefectural regulatory cluster as industry-specific overlays. CAGRs derive from trend extrapolation adjusted for METI mandate implementation pacing and JAS certification pathway timelines.
Caveats apply where PMDA batch-release timeline extensions, telemedicine regulatory reversals, or API supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding METI digital health record compliance deadlines and agricultural cooperative procurement consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Isoxazoline Market
Veterinary
Veterinary Hospitals Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Canine Parvovirus Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Veterinary Healthcare Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market