
 US Surgical Pet Collar Market | 2026-2036
US Surgical Pet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
US Surgical Pet Collar Market Intelligence
Domestic manufacturing for specialized pet recovery products is shifting towards higher-value, comfort-oriented designs. This transition favors producers with strong material science and ergonomic design capabilities. KONG Company leverages its brand recognition in the broader pet products space to gain market share. KVP International specializes in a wide range of veterinary supplies, anchoring its position through distribution to clinics.
A surgical pet collar is a protective medical device designed to prevent an animal from licking or biting a post-surgical wound, injury, or skin irritation. These collars, often made from materials like rigid PVC or soft polyester fabrics, create a physical barrier around the pet's head. While traditional Elizabethan collars maintain a significant volume share, inflatable collars and recovery suits represent the fastest-growing product types. Sales through veterinary clinics remain dominant, but the pet owner channel is expanding via e-commerce platforms.
While not strictly regulated as medical devices, surgical pet collars fall under the general safety purview of the US Consumer Product Safety Commission (CPSC) regarding material hazards. The FDA's Center for Veterinary Medicine (CVM) provides guidance that influences material choices for products used in clinical settings. Future product development will hinge on balancing the cost of advanced, hypoallergenic materials against the clear benefits of improved pet comfort and owner compliance.
Market Dynamics
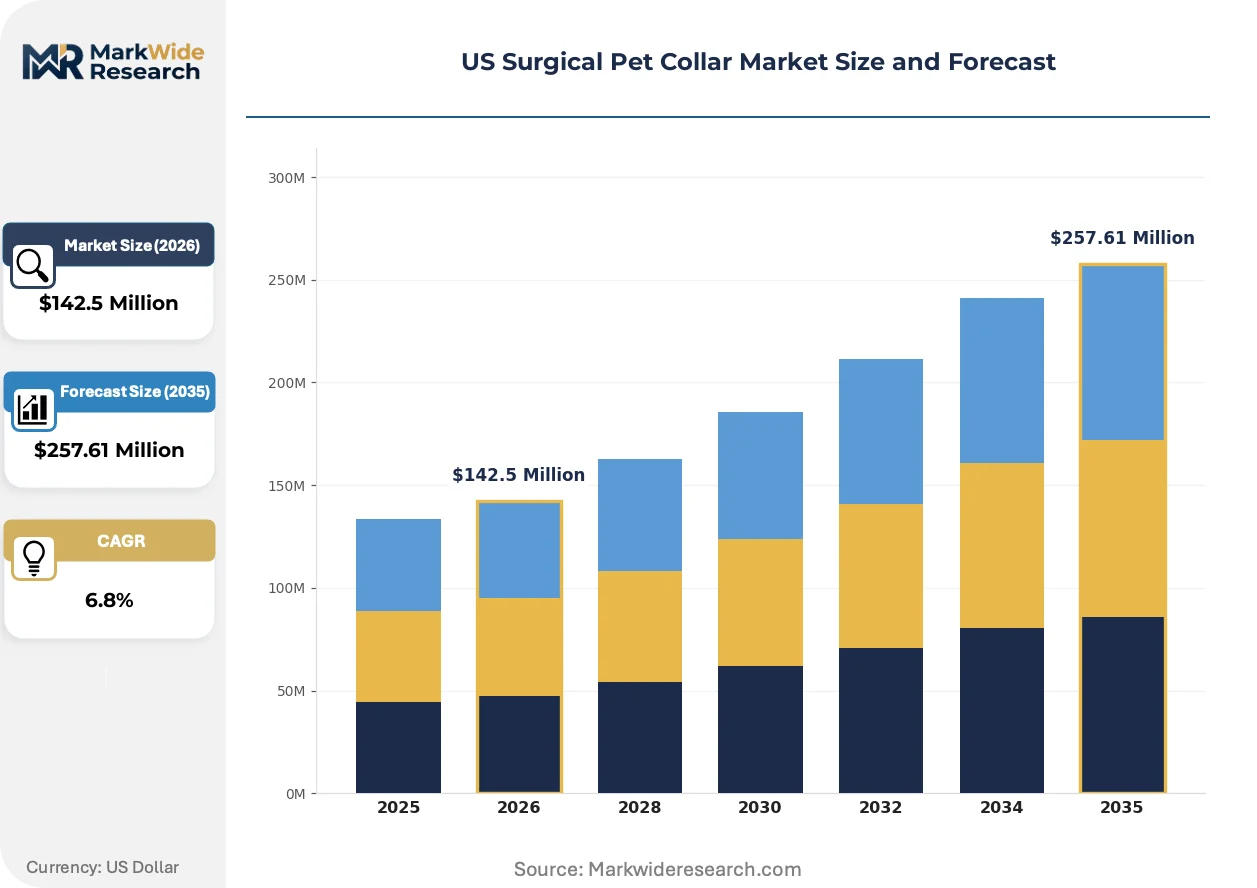
The market's central dynamic is the tension between traditional, low-cost Elizabethan collars and the rising demand for premium, comfort-focused alternatives. This shift is driven by evolving veterinary care standards and pet owner sentiment, prioritizing patient compliance and reduced recovery stress.
Growth Catalysts
- Evolving Veterinary Standards:Post-operative care protocols within US veterinary clinics increasingly favor products that minimize patient stress and improve compliance, directly supporting the adoption of softer, less obstructive recovery collars.
- Material Science Innovation:The development of breathable, lightweight, and hypoallergenic materials like specialized neoprene and polyester blends enables manufacturers to produce collars that enhance comfort without sacrificing protective function.
- Pet Humanization:A cultural trend of viewing pets as family members fuels owner willingness to invest in higher-cost, premium wellness products, particularly in states with high disposable income like California and Texas.
Market Restraints
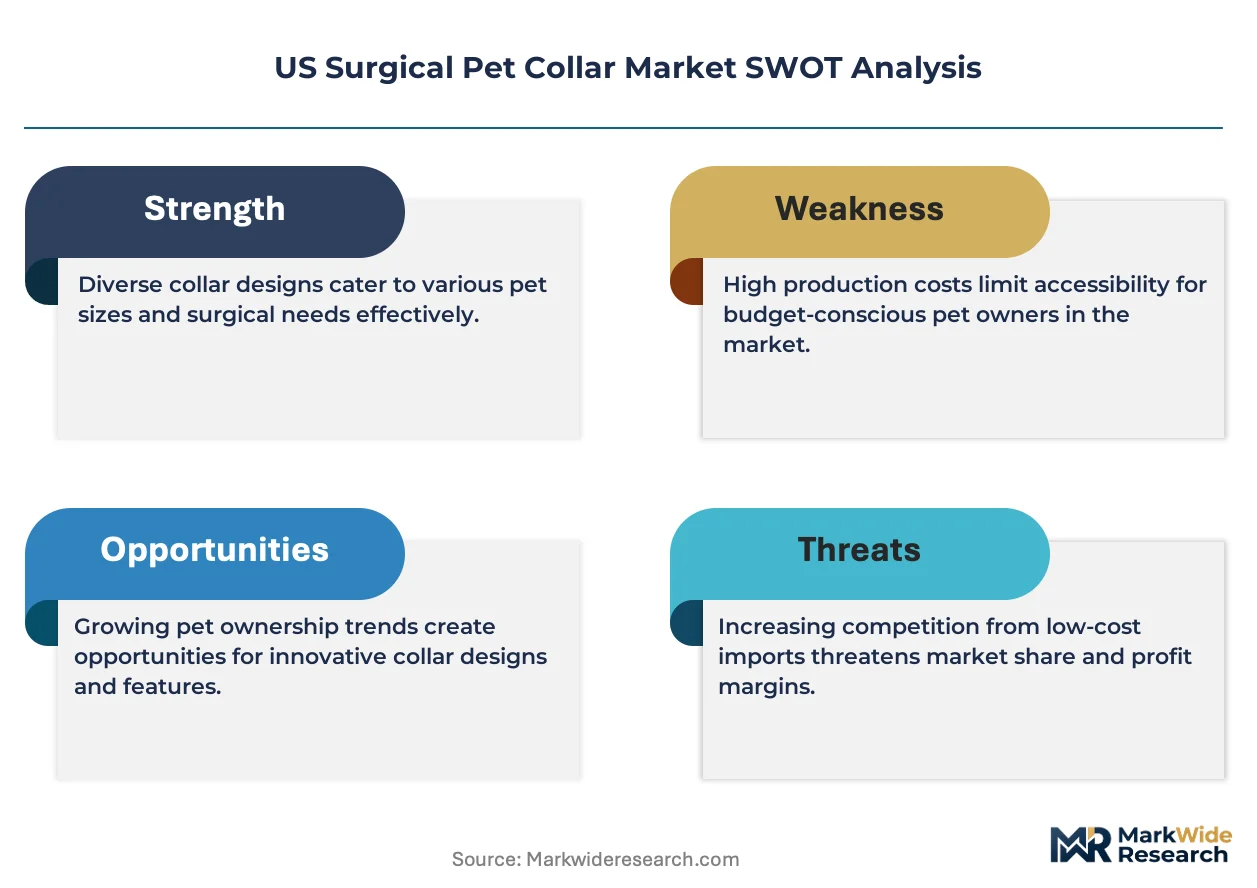
- Material Cost Pressures:The significant cost difference between advanced, hypoallergenic fabrics and traditional rigid PVC plastic creates a price barrier, limiting adoption among budget-conscious consumers and smaller veterinary practices.
- Threat of Substitution:The growing availability and acceptance of full-body recovery suits as an alternative to collars poses a direct substitution threat, especially for animals recovering from abdominal or torso procedures.
- Lack of Specific Regulation:While falling under the CPSC's general safety oversight, the absence of specific medical device standards for these products leads to inconsistent quality and complicates clinical efficacy claims.
Strategic Opportunities
- Direct-to-Consumer E-commerce:Expanding sales through online platforms allows brands to directly engage with pet owners who actively research and purchase post-operative care items, bypassing traditional veterinary distribution gatekeepers.
- Anatomical Specialization:A market exists for recovery collars specifically designed for the unique anatomies of non-canine and non-feline pets, such as rabbits, guinea pigs, and birds, representing an underserved niche.
- Smart Technology Integration:Incorporating lightweight sensors for activity or lick detection into collars offers a new value proposition, providing veterinarians with post-operative monitoring data and owners with enhanced peace of mind.
Industry Challenges
- Consumer Education Gap:A primary operational hurdle is educating pet owners on the functional and comfort benefits of modern collar designs compared to the inexpensive, traditional Elizabethan collars they are more familiar with.
- Complex Sizing and Inventory:Managing the logistics of supplying a vast network of veterinary clinics with a wide array of sizes and collar types for immediate, post-surgical use presents a significant inventory and distribution challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Surgical Pet Collar Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Collar, Elizabethan Collar, Recovery Suit, Soft Cone Material: Polyester, Neoprene, PVC, Cotton Size: Small, Medium, Large, Extra Large End User: Pet Owners, Veterinary Clinics, Animal Shelters, Breeders |
| Companies Covered | KONG Company, Acorn Pet Products, Remedy+Recovery, ZenPet, All Four Paws, Campbell Pet Company, Trimline Inc., KVP International, Lomir Biomedical Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Surgical Pet Collar Market Strategic Shifts & Innovations
Product evolution in the surgical pet collar market is moving beyond simple physical barriers. The convergence of material science, ergonomic design, and pet owner demands for improved welfare is creating a new class of recovery aids focused on comfort and compliance.
Antimicrobial fabrics represent a significant product evolution. These materials, often infused with silver ions, inhibit bacterial growth on the collar surface, reducing the risk of secondary skin infections around the neck. Veterinary surgical specialists and referral hospitals are the primary adopters, seeking to improve post-operative outcomes. This innovation is electrifying the premium segment, creating a new tier of products differentiated by clinical benefits.
Guidance from the FDA's Center for Veterinary Medicine (CVM) is influencing material choices, even without direct regulatory mandates. This guidance on materials appropriate for animal contact encourages manufacturers to use biocompatible polymers and avoid certain chemicals. To secure distribution through veterinary channels, producers are increasingly aligning their product specifications and safety data with CVM's implicit standards.
A notable behavioral shift is the rise of the pet owner as an independent researcher, using online resources to select recovery products. This trend disrupts the traditional veterinarian-led selection process, as owners may bring pre-purchased, comfort-oriented collars to their pet's surgical appointment. This pattern is most visible in urban and suburban areas of the US with a strong pet wellness culture.
US Surgical Pet Collar Market Segmentation
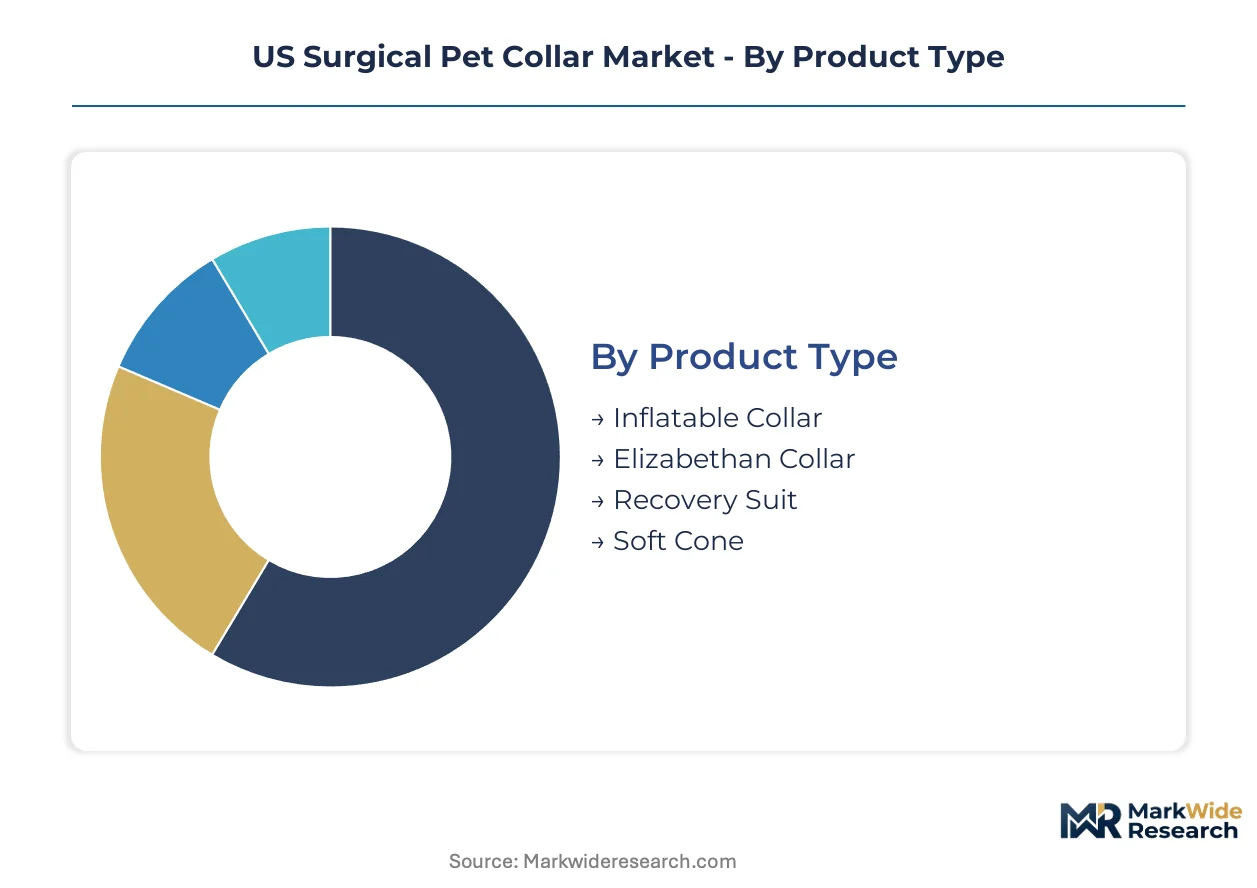
Market segmentation for US surgical pet collars reveals critical distinctions in product design, material science, and end-user procurement channels. Understanding these segments helps manufacturers align product development with evolving veterinary standards and pet owner preferences. This analysis dissects the market across key dimensions, highlighting areas of concentrated demand and innovation.
Product Type:
The various product types for pet recovery collars primarily function as standalone protective devices, each offering distinct levels of comfort and physical restriction.
- Inflatable Collar:These collars feature an internal inflatable bladder, providing a soft, cushion-like barrier that prevents pets from reaching wounds without obstructing peripheral vision. Demand concentrates in urban areas with high disposable income, driven by pet owners prioritizing comfort and reduced stress during recovery.
- Elizabethan Collar:Traditional Elizabethan collars, often made from rigid PVC, form a cone shape around the pet's head to create a physical barrier. Veterinary clinics maintain significant volume for these cost-effective and highly effective protective devices, particularly for immediate post-operative use.
- Recovery Suit:Recovery suits offer full-body coverage, protecting wounds on the torso or abdomen by encasing the pet's body in fabric, often reducing the need for a collar.
- Soft Cone:Soft cones are flexible, fabric-based collars that provide a less rigid alternative to traditional Elizabethan collars, enhancing pet comfort while still offering wound protection.
Elizabethan collars lead volumes today; recovery suits are gaining share fastest.
Material:
Material selection directly influences a surgical pet collar's comfort, durability, and hypoallergenic properties, impacting both veterinary recommendation and pet owner acceptance.
- Neoprene:Neoprene is a synthetic rubber known for its softness, flexibility, and water resistance, making it suitable for comfortable and durable recovery collars. Manufacturers in California are increasingly adopting neoprene for premium products, driven by its hypoallergenic qualities and breathability.
- PVC:Polyvinyl chloride (PVC) is a rigid, inexpensive plastic commonly used for traditional Elizabethan collars due to its structural integrity and ease of cleaning. Its low cost makes it a preferred material for high-volume production, particularly for veterinary practices seeking economical options.
- Polyester:Polyester fabrics offer breathability and light weight, making them a common choice for soft cones and recovery suits that prioritize comfort and airflow.
- Cotton:Cotton provides a natural, soft, and breathable option for pet collars, often used in less rigid designs or as an inner lining for enhanced comfort.
Demand for PVC is robust, while cotton appeals to niche applications.
Size:
Sizing options for surgical pet collars are crucial for ensuring proper fit and effectiveness across the diverse range of canine and feline breeds, directly impacting compliance and comfort.
- Medium:Medium-sized collars cater to a broad spectrum of common dog breeds like Beagles and Cocker Spaniels, and larger cat breeds, representing a significant portion of the pet population. Veterinary clinics across Texas report consistent demand for medium sizes due to the prevalence of mid-sized companion animals.
- Large:Large collars are designed for bigger dog breeds such as Labradors, German Shepherds, and Golden Retrievers, requiring robust construction to provide adequate protection. Manufacturers focus on durable materials for large sizes, recognizing the increased strength and potential for resistance from larger animals.
- Small:Small collars are tailored for smaller dog breeds, cats, and puppies, requiring lightweight and less obtrusive designs to ensure pet comfort and mobility.
- Extra Large:Extra-large collars accommodate giant dog breeds, demanding specialized designs that provide extensive coverage without hindering the animal's movement.
The medium segment accounts for the largest volume, while extra large addresses specific demographic needs.
End User:
End-user segments dictate distinct procurement and distribution dynamics for surgical pet collars, influencing product features and sales channels.
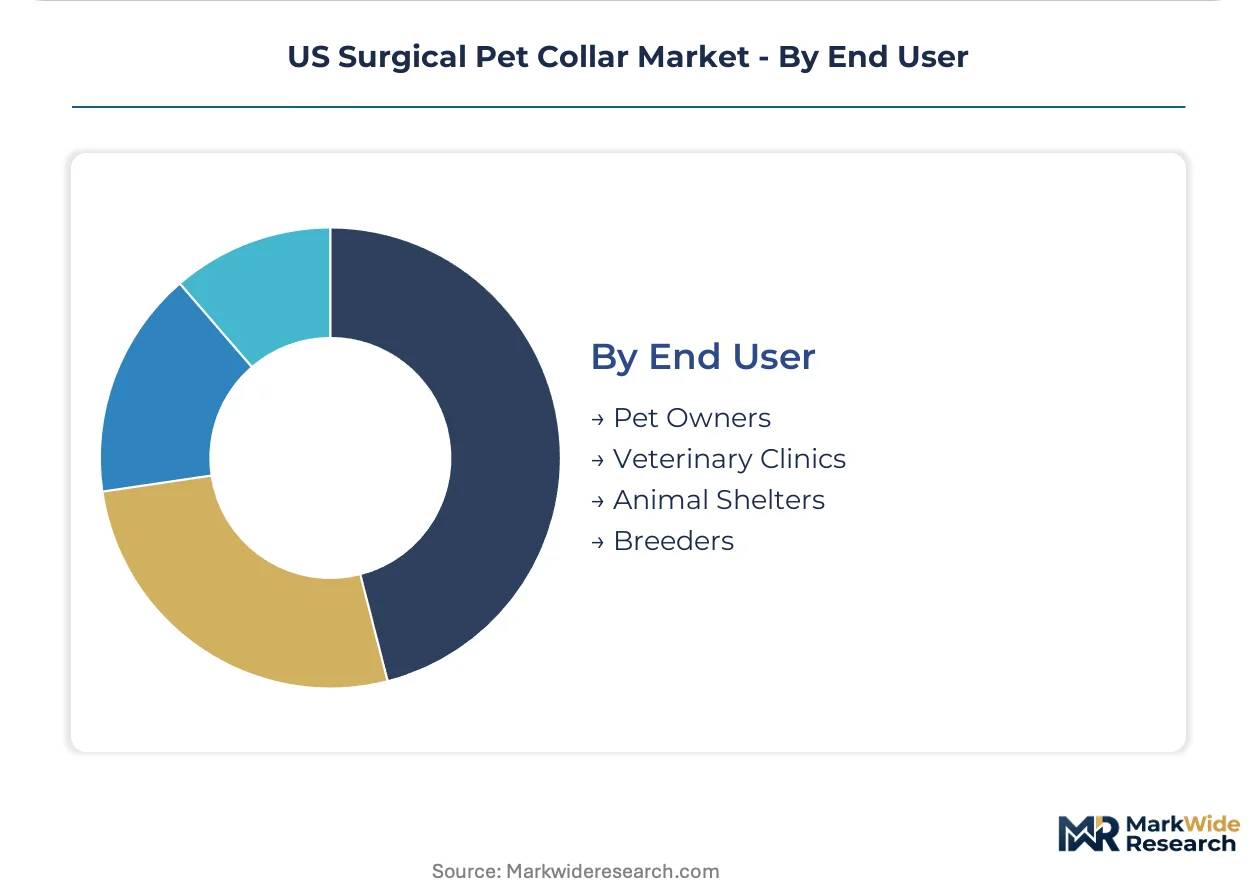
- Veterinary Clinics:Veterinary clinics serve as primary distributors, purchasing collars in bulk for immediate post-operative application and offering professional guidance on selection. These clinics prioritize efficacy and durability, influencing manufacturer focus on clinical-grade materials and reliable designs.
- Pet Owners:Pet owners increasingly purchase collars directly through online channels, often seeking comfort-oriented and aesthetically pleasing alternatives to traditional clinic-provided options. Demand from pet owners is concentrated in states like California, where pet humanization trends drive premium product adoption.
- Animal Shelters:Animal shelters procure cost-effective and versatile collars to manage post-surgical recovery for a high volume of animals, prioritizing functionality and affordability.
- Breeders:Breeders utilize collars for specific post-natal or minor surgical needs, often requiring specialized sizes for puppies or particular breed anatomies.
Veterinary clinics remain a foundational channel, but the pet owner segment demonstrates significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory differences across US states, particularly concerning material safety and disposal, create a compliance cost arbitrage that influences manufacturing and distribution strategies for pet collars. This dynamic encourages some producers to optimize operations in states with more favorable regulatory environments. The US Consumer Product Safety Commission (CPSC) provides general oversight, but state-level interpretations can vary.
California
Pet humanization trends and high disposable income in California drive demand for premium, comfort-oriented surgical pet collars. The California Air Resources Board (CARB) regulations on material emissions implicitly encourage manufacturers to use safer, less volatile compounds. Los Angeles and San Francisco metropolitan areas exhibit concentrated demand for innovative, aesthetically pleasing pet recovery products.
Texas
A large and growing pet population, coupled with a strong network of veterinary clinics, generates consistent demand for both traditional and advanced recovery solutions in Texas. The Texas Department of State Health Services (DSHS) oversees veterinary practice standards, influencing product recommendations. Houston and Dallas veterinary clinics represent significant procurement hubs for diverse collar types.
New York Metro
Affluent pet owners within the New York metropolitan area prioritize high-end, easily applicable recovery solutions for their companion animals. The New York State Department of Health's veterinary guidelines encourage optimal post-operative care, favoring effective and comfortable options. Manhattan's dense urban environment fosters robust e-commerce penetration for specialized pet items.
Pacific Northwest
A robust pet wellness culture and an outdoor-oriented lifestyle in the Pacific Northwest fuel demand for durable, comfortable, and often eco-friendly collar options. State environmental regulations in Oregon and Washington promote sustainable material sourcing and manufacturing practices. Seattle and Portland exhibit strong pet owner engagement with premium, ethically produced brands.
Southeast
The growing elderly population with companion animals across states like Florida and Georgia drives demand for easily applicable and comfortable recovery collars. Florida's Animal Industry Technical Council provides guidance on animal health, affecting veterinary choices and product recommendations. Atlanta's burgeoning pet supply distribution networks serve a wide regional market, including numerous veterinary practices.
US Surgical Pet Collar Market Key Industry Players
US producers anchor one tier, focusing on domestic distribution and evolving material science; international suppliers hold another, often leveraging cost efficiencies or specialized product lines. The market structure is tiered, with established players focusing on broad veterinary distribution and newer entrants targeting direct-to-consumer channels. Strategic archetypes include diversified pet product conglomerates, specialized medical device manufacturers, and e-commerce-first comfort solution providers. Dominant competitive moves involve portfolio diversification into comfort-oriented designs and strategic partnerships with veterinary practice groups.
Within the established brand tier, KONG Company exemplifies leveraging strong brand recognition across broader pet product categories to gain market share in recovery solutions. KVP International anchors the veterinary supply archetype, specializing in wide-ranging veterinary products and maintaining strong distribution channels to clinics. Companies like All Four Paws represent the segment of manufacturers focused on comfort-oriented designs, catering to pet owners seeking premium alternatives through direct-to-consumer channels.
| Leading Market Players |
|---|
| KONG Company |
| Acorn Pet Products |
| Remedy+Recovery |
| ZenPet |
| All Four Paws |
| Campbell Pet Company |
| Trimline Inc. |
| KVP International |
| Lomir Biomedical Inc. |
Cost & Logistics Intelligence
Veterinary clinics, as a concentrated buyer archetype, influence pricing models through bulk procurement and a preference for cost-effective, yet clinically effective, solutions. This concentration shapes transactional pricing, balancing immediate post-operative needs with budget constraints.
Pricing Analysis
Distributor margins significantly impact final product pricing within the US surgical pet collar market. Per-unit transactional sales dominate, driven by immediate post-operative needs. Price differentiation stems from material quality, such as hypoallergenic properties, and established brand recognition. Pricing softness reflects the widespread availability of low-cost traditional Elizabethan collars. Animal shelters and smaller veterinary practices are most price-sensitive, while affluent pet owners prioritize comfort and are less sensitive to price.
Supply Chain Analysis
Workforce availability in manufacturing geographies like the US, China, and Vietnam influences production capacity for pet collars. The supply chain draws from key raw materials including PVC resins, specialized neoprene, polyester fabrics, and advanced antimicrobial agents. Commodity price volatility for these specialized materials poses a structural risk. Distribution runs through a dual channel, utilizing established veterinary supply distributors and expanding direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion is occurring through a premium-tier shift towards comfort-oriented and technologically advanced products, justifying strategic investment in this evolving market.
For Market Incumbents:Anticipate the substitution threat from recovery suits by diversifying product portfolios into full-body solutions and advanced collar designs. Invest in material science R&D for hypoallergenic and antimicrobial fabrics to enhance product differentiation. Form strategic partnerships with large veterinary clinic groups to secure preferred supplier status for new, comfort-focused recovery aids. Focus on demonstrating clinical efficacy to reinforce veterinary recommendations.
For New Entrants and Emerging Players:Capture white-space opportunities by targeting direct-to-consumer e-commerce channels with innovative products. Develop specialized designs for underserved non-canine and non-feline pets, addressing unique anatomical needs. The most penetrable segment lies within urban and suburban areas of California and New York, where pet humanization trends are strong. Emphasize comfort, aesthetic appeal, and unique features like smart technology integration in go-to-market strategies.
For Investors and Strategic Acquirers:Diversified pet product conglomerates are the most active acquirers in this space, seeking to expand their premium recovery solution offerings. The market demonstrates strong long-term viability over the next 5-10 years, driven by evolving veterinary care standards and pet owner willingness to invest in pet wellness. Target specialized medical device manufacturers with strong material science capabilities or e-commerce-first comfort solution providers. Increased CVM guidance formalization for material standards is the signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expands market reach into premium comfort segments, attracting affluent pet owners. |
| E-commerce Channel Development | Bypasses traditional distribution, directly engaging pet owners and building brand loyalty. |
| Material Science R&D Investment | Enhances product differentiation through superior comfort, breathability, and antimicrobial properties. |
| Veterinary Clinic Partnerships | Secures distribution and recommendation channels, reinforcing clinical adoption of new designs. |
| Smart Technology Integration | Creates a new value proposition with post-operative monitoring data for veterinarians and owners. |
Research Approach
Coverage spans US states including California, Texas, New York Metro, Pacific Northwest, and the Southeast, with primary inputs from each region. The analysis combines in-depth interviews with veterinary clinic managers, pet product manufacturers, e-commerce platform executives, and material science engineers. Secondary data sources include CPSC safety reports, FDA CVM guidance documents, veterinary association publications, and pet industry trade statistics. This approach enables robust bottom-up and top-down triangulation.
Rate-of-change decomposition frames the analytical framework across the modeling period. Segmentation dimensions modeled include product type, material, size, end user, and regional pet population density. Compound annual growth rates were derived from historical growth patterns and future demand projections. Key forecast inputs include pet ownership demographics and veterinary procedure volumes across the US.
Underlying measurement precision varies by segment; established Elizabethan collars and veterinary clinics carry tighter precision than emerging smart collars. Forecasts reflect assumptions regarding pet humanization trends and material science advancements. Unforeseen CPSC or CVM regulatory shifts represent a material deviation that warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Global Animal Sedative Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
France Veterinary Healthcare Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Veterinary Monitoring Equipment Market