
 Global Livestock Vaccines Market | 2026-2036
Global Livestock Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Livestock Vaccines Market Foresight
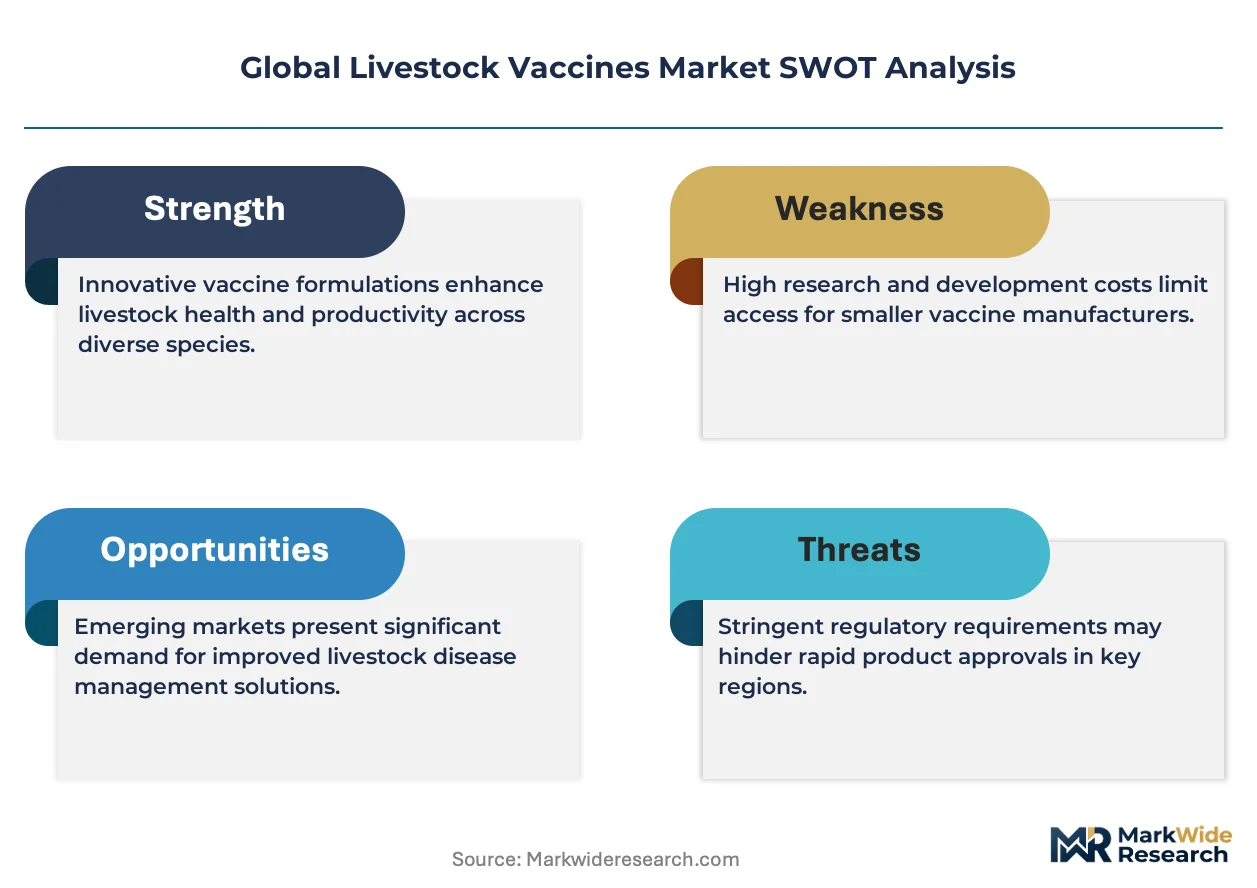
Project finance partnerships between vaccine developers and commercial farm consortiums is rewriting competitive entry requirements for regional players. Zoetis Services LLC leverages its vertically integrated manufacturing footprint across multiple continents to sustain supply security for high-volume poultry contracts. Boehringer Ingelheim International GmbH anchors its position through specialized recombinant platforms that command premium positioning in European cattle operations. Merck & Co., Inc. competes by controlling distribution partnerships with government animal husbandry departments in emerging markets.
Livestock vaccines are biologically active preparations containing attenuated, inactivated, or recombinant antigenic components that stimulate protective immune responses in food-producing and companion farm animals, typically requiring cold-chain storage at two to eight degrees Celsius to maintain titer potency. These products serve the primary commercial purpose of preventing epidemic disease outbreaks that would otherwise devastate concentrated animal feeding operations and trigger trade embargoes on meat exports. The inactivated vaccine category dominates current revenue pools due to established regulatory pathways and conservative veterinarian prescribing habits, while recombinant platforms represent the fastest-expanding segment as developers pursue differentiation through marker vaccine capabilities that enable serological distinction between infected and vaccinated animals. DNA vaccines occupy a niche but strategically significant position where margin pools concentrate around intellectual property licensing rather than manufacturing scale.
The USDA Center for Veterinary Biologics enforces stringent potency and purity standards that shape product development timelines and compliance costs for developers seeking US market access, while the EU Veterinary Medicines Regulation mandates environmental risk assessments that filter novel adjuvants and delivery systems. India's CDSCO and the country's animal husbandry departments coordinate parallel approval tracks that accelerate indigenous vaccine commercialization for priority diseases like lumpy skin disease. Stakeholders must monitor how evolving regulatory science around gene-edited vaccines will reshape the competitive boundary between pharmaceutical innovators and generic manufacturers.
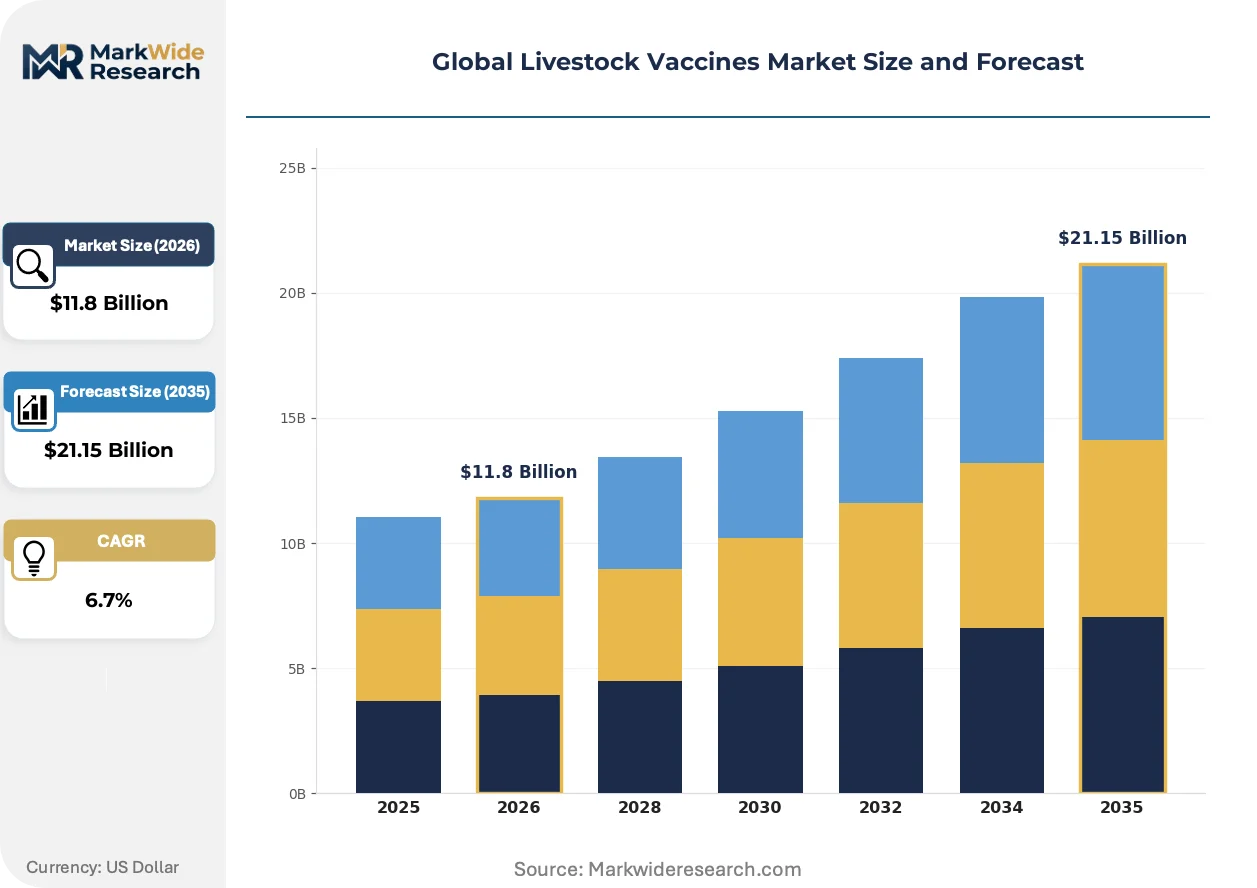
Market Dynamics
mRNA platform migration is redirecting R&D budgets toward novel vector approaches while recombinant antigen production scales reshape manufacturing footprints across veterinary pharmaceutical operations.
Growth Catalysts
- Brazilian eradication protocols:Foot-and-mouth disease elimination mandates under national agricultural policy are expanding commercial farm vaccination coverage across São Paulo and Mato Grosso cattle operations.
- India's cold-chain expansion:Government-backed livestock health campaigns are extending refrigerated distribution infrastructure into rural veterinary networks previously unreachable by temperature-sensitive biologics.
- Marker vaccine differentiation:DIVA-capable recombinant platforms enable serological distinction between infected and vaccinated animals, satisfying export certification requirements for trade-sensitive protein commodities.
Market Restraints
- Adjuvant input volatility:Saponin and oil-in-water emulsion component costs fluctuate with agricultural commodity markets, compressing formulation margins for inactivated vaccine producers.
- Regulatory pathway friction:USDA Center for Veterinary Biologics potency verification timelines extend development cycles, delaying market entry for novel platform developers seeking US commercialization.
- Substitution pressure from biosecurity hardware:Automated disinfection systems and quarantine infrastructure investments compete for capital allocation against preventive pharmaceutical programs in integrated pork operations.
Strategic Opportunities
- Rural India penetration:Indigenous vaccine commercialization through CDSCO-Animal Husbandry parallel approval tracks accelerates lumpy skin disease product deployment in underserved dairy belts.
- Gene-edited vaccine platforms:CRISPR-based antigen design converges with synthetic biology manufacturing, creating intellectual property licensing revenue pools distinct from bulk biological production.
- Direct-to-farm digital channels:Tele-veterinary platforms bypass traditional distributor markups, enabling price-transparent procurement for mid-scale poultry layer operations in Southeast Asian markets.
Industry Challenges
- Cold-chain engineering talent scarcity:Veterinary biologics logistics specialists capable of maintaining two-to-eight-degree Celsius integrity across last-mile distribution remain concentrated in urban pharmaceutical hubs.
- Legacy serology infrastructure incompatibility:Marker vaccine adoption requires laboratory retooling for differential diagnostic protocols, creating adoption friction among conservative veterinary practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Livestock Vaccines Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Recombinant, DNA, Toxoid Target Animal: Cattle, Poultry, Swine, Aquaculture, Small Ruminants, Equine Application: Disease Prevention, Growth Promotion, Reproductive Health, Parasitic Control, Zoonotic Disease Management End User: Veterinary Clinics, Commercial Farms, Research Institutions, Animal Husbandry Departments, Feedlots |
| Companies Covered | Zoetis Services LLC, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco, Ceva Santé Animale, Virbac, Dechra Pharmaceuticals PLC, Phibro Animal Health Corporation, HIPRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Livestock Vaccines Market Shifts & Advancements
Platform technology substitution is compressing development timelines while regulatory science around gene-edited products redraws competitive boundaries between innovator and generic manufacturers.
Recombinant subunit vaccines are migrating from experimental niche applications toward mainstream cattle respiratory disease prevention as Brazilian and Australian feedlot operators adopt DIVA-compliant protocols to maintain beef export eligibility. Large-scale fermentation infrastructure investments by contract manufacturing organizations enable cost parity with traditional inactivated platforms, accelerating segment penetration.
EU Veterinary Medicines Regulation environmental risk assessment mandates are filtering novel adjuvant chemistries from commercial pipelines, forcing developers toward biodegradable delivery systems and aqueous formulations. Aquaculture vaccine applicants face heightened ecotoxicological scrutiny for marine discharge scenarios, compressing viable product candidates in European salmonid markets.
Consolidated animal feeding operations are unbundling preventive health programs from integrated service contracts, creating standalone procurement categories that attract specialized vaccine suppliers. Brazilian commercial farm consortiums now negotiate direct supply agreements with platform technology developers, bypassing traditional veterinary distributor networks that previously captured margin through bundled pharmaceutical and equipment sales.
Global Livestock Vaccines Market Segmentation
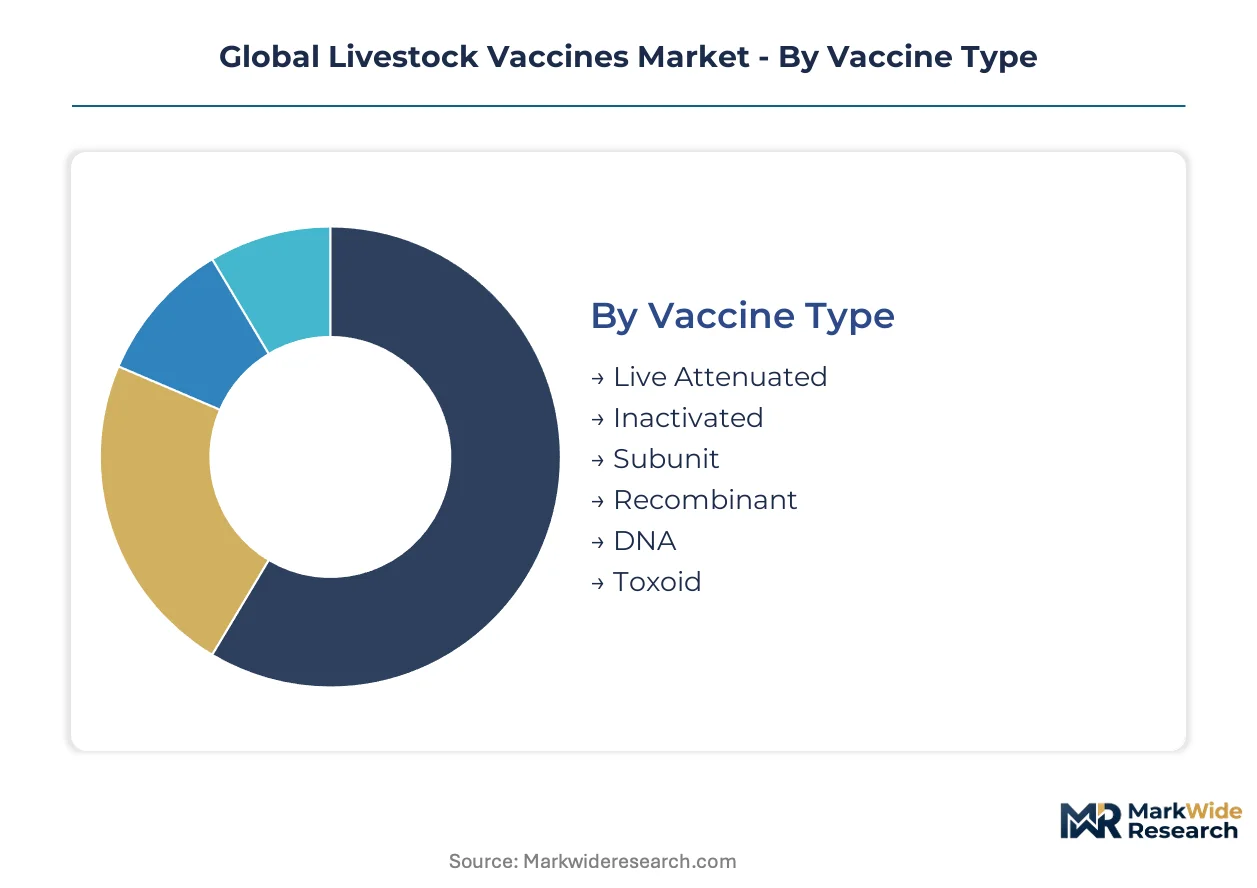
Segmentation in livestock vaccines reveals how formulation technology, target species, and procurement channel economics create distinct competitive arenas. Each dimension carries unique margin structures and regulatory compliance burdens that reshape strategic positioning.
Vaccine Type:
Formulation chemistry spans from classical live-virus preparations to synthetic nucleic acid platforms, with each tier commanding different manufacturing scale economies and cold-chain tolerances.
- Inactivated:Chemically or thermally treated pathogens retain immunogenicity without replication risk. Conservative veterinarian prescribing habits in US cattle operations sustain demand despite longer dosing schedules.
- Recombinant:Genetically engineered subunit antigens enable DIVA-compliant serological distinction. Brazilian and Australian feedlot operators adopt these platforms to maintain beef export certification eligibility.
- Live Attenuated:Weakened pathogen strains induce robust cellular immunity with single-dose convenience. Poultry broiler operations favor these for respiratory disease protection in high-density housing.
- Subunit:Purified protein fragments minimize adverse reaction risk. Aquaculture salmonid producers specify these for water-borne delivery systems.
- DNA:Plasmid-encoded antigens trigger endogenous protein synthesis. Intellectual property licensing concentrates margin pools around synthetic biology patents rather than biological manufacturing.
- Toxoid:Bacterial exotoxin inactivation generates protective antibodies against toxin-mediated diseases. Equine operations in Kentucky and Florida maintain tetanus and botulism coverage protocols.
The dominant share belongs to Inactivated platforms, while Recombinant formulations are closing the gap fastest.
Target Animal:
Species-specific immunology and production economics segment demand across divergent farm enterprise scales and biosecurity protocols.
- Cattle:Large-animal dosing volumes and extended reproductive cycles concentrate value in respiratory and clostridial protection. São Paulo dairy cooperatives negotiate direct supply agreements bypassing distributor markups.
- Poultry:Short production cycles and vertical integration create high-frequency vaccination schedules. Layer operations in India's Andhra Pradesh and Telangana states drive volume through government-backed health campaigns.
- Swine:Porcine reproductive and respiratory syndrome complexity sustains premium pricing for multivalent formulations. Integrated pork operations in Denmark and the Netherlands prioritize marker vaccine differentiation for export compliance.
- Aquaculture:Marine and freshwater species require immersion or injection delivery adapted to aquatic environments. Norwegian salmonid producers face EU Veterinary Medicines Regulation ecotoxicological scrutiny.
- Small Ruminants:Sheep and goat operations in Rajasthan and Gujarat states demand lumpy skin disease coverage as pastoral herding integrates with commercial dairy supply chains.
- Equine:Companion and racing segments sustain premium positioning through individualized veterinary protocols. Kentucky Derby circuit operations maintain stringent infectious disease screening.
Cattle retains volume leadership, though Poultry climbs fastest as Southeast Asian layer capacity expands.
Application:
Functional purpose determines regulatory pathway complexity and reimbursement economics across preventive versus therapeutic positioning.
- Disease Prevention:Core epidemic protection against foot-and-mouth disease and avian influenza dominates procurement budgets. Brazil's national eradication mandates enforce mandatory coverage across Mato Grosso feedlots.
- Growth Promotion:Metabolic enhancement through immune modulation faces tightening antibiotic-alternative scrutiny. EU restrictions on antimicrobial growth promoters redirect investment toward vaccine-mediated performance optimization.
- Reproductive Health:Fertility protection against bovine viral diarrhea and porcine parvovirus secures genetic investment value. Artificial insemination centers specify certified disease-free semen sourcing.
- Parasitic Control:Anti-tick and anti-worm vaccines reduce chemical acaricide dependence. Australian cattle stations trial novel antigen targets against Rhipicephalus microplus infestation.
- Zoonotic Disease Management:Brucellosis and rabies vaccination protects human health workers and food supply chains. India's CDSCO coordinates with state animal husbandry departments on One Health surveillance integration.
Disease Prevention commands the largest allocation, with Zoonotic Disease Management gaining policy priority fastest.
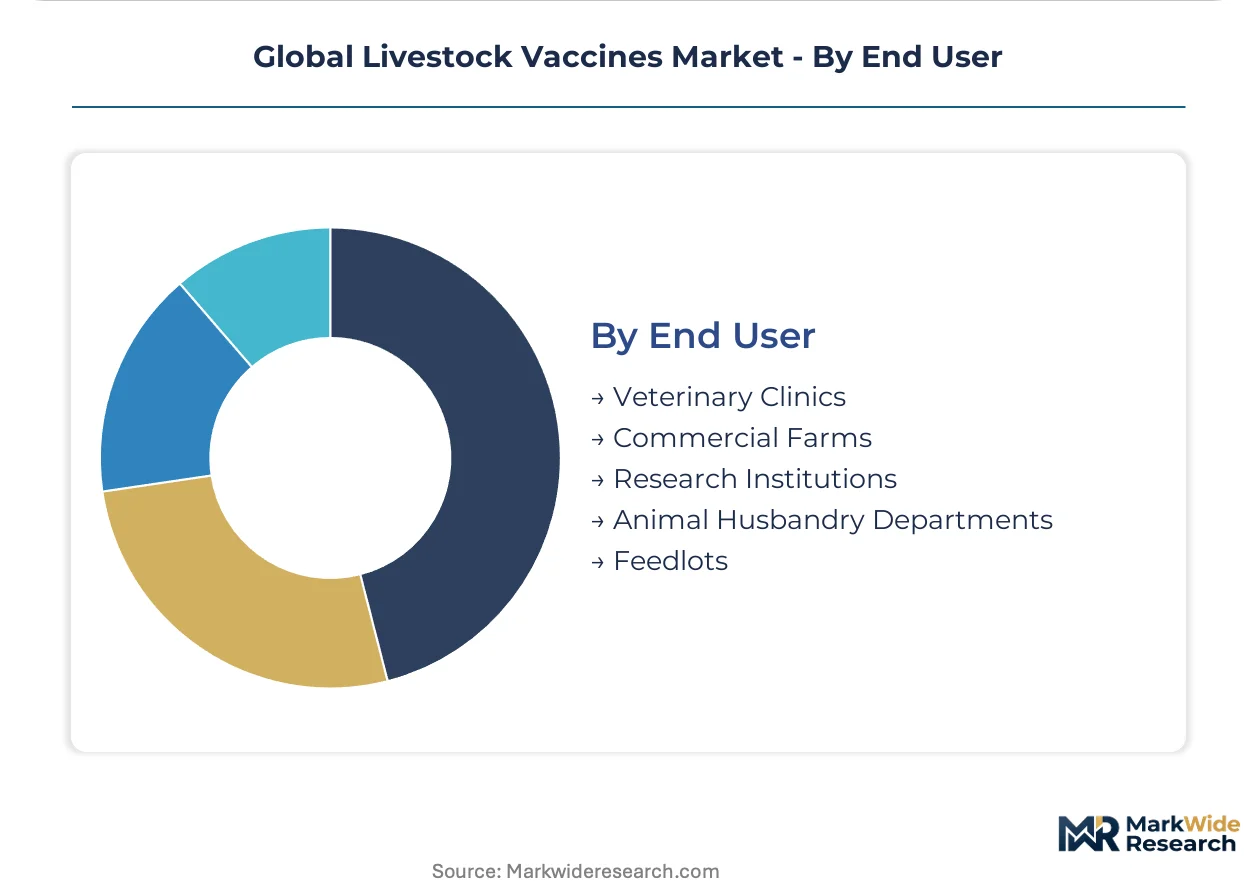
End User:
Procurement authority and technical capability segment distribution channel economics from centralized government tenders to individual farm decisions.
- Commercial Farms:Scale economies enable direct manufacturer negotiation and cold-chain infrastructure investment. Brazilian consortiums now unbundle preventive health from integrated service contracts.
- Veterinary Clinics:Technical advisory relationships sustain premium product placement. Mixed-animal practices in rural Texas and Kansas serve as gatekeepers for producer recommendations.
- Animal Husbandry Departments:Government procurement channels aggregate demand for national disease control programs. India's state-level livestock directorates coordinate cold-chain extension into previously unreachable districts.
- Feedlots:Concentrated finishing operations require rapid- onset respiratory protection upon arrival. US Plains feedlots specify modified-live viral vaccines for bovine respiratory disease complex.
- Research Institutions:Experimental product evaluation and field trial execution support regulatory submission packages. University veterinary schools in São Paulo and Queensland maintain challenge-study capabilities.
Commercial Farms hold procurement dominance, while Animal Husbandry Departments are expanding fastest through subsidized national health campaigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National eradication mandates and subsidized livestock health campaigns are redirecting procurement volumes across concentrated agricultural zones. Government-backed cold-chain investments in emerging economies compete with private direct-to-farm channels in mature markets. Regulatory divergence between USDA potency verification and EU environmental risk assessments fragments product development priorities.
Brazil
Foot-and-mouth disease elimination protocols under national agricultural policy are expanding mandatory vaccination coverage across São Paulo and Mato Grosso cattle operations. ANVISA coordinates with the Ministry of Agriculture on parallel approval tracks for indigenous recombinant platforms. Commercial farm consortiums in the Cerrado belt negotiate direct supply agreements that bypass traditional veterinary distributor networks.
India
CDSCO and state animal husbandry departments are accelerating lumpy skin disease vaccine deployment through subsidized rural health campaigns. Cold-chain infrastructure extension into Rajasthan and Gujarat dairy belts enables temperature-sensitive biologics reach previously underserved pastoral herding zones. The Andhra Pradesh and Telangana layer operations drive poultry vaccine volume through government procurement aggregation.
United States
USDA Center for Veterinary Biologics potency verification timelines shape development cycles for novel platform developers seeking commercialization. Kansas and Texas mixed-animal practices serve as gatekeepers for producer recommendations in cattle-dense Plains states. Modified-live viral vaccines for bovine respiratory disease complex dominate feedlot procurement specifications upon arrival.
Germany
EU Veterinary Medicines Regulation environmental risk assessment mandates filter novel adjuvant chemistries from commercial pipelines. Bavarian and Lower Saxony integrated pork operations prioritize marker vaccine differentiation for export compliance with Danish and Dutch trade requirements. EMA guidelines on gene-edited products reshape competitive boundaries between innovator and generic manufacturers.
Australia
TGA oversight converges with export certification requirements for beef eligibility in Asian protein markets. Queensland and New South Wales cattle stations trial novel antigen targets against Rhipicephalus microplus infestation in acaricide-reduction programs. Feedlot operators adopt DIVA-compliant protocols to maintain serological distinction capabilities for trade-sensitive shipments.
Global Livestock Vaccines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement authority structures. Consolidated animal health conglomerates leverage vertically integrated manufacturing footprints to sustain supply security for high-volume contracts, while recombinant platform specialists capture premium positioning through differentiated antigen engineering. The market structures around three archetypes: scale-driven biological manufacturers, precision platform technologists, and regional formulation distributors. Dominant competitive moves include backward integration into fermentation infrastructure and strategic partnerships with government animal husbandry departments.
Within the scale-driven tier, Zoetis Services LLC and Boehringer Ingelheim International GmbH exemplify channel-controlling positions through multi-continent manufacturing presence. Merck & Co., Inc. occupies a position anchored in emerging market distribution partnerships with state livestock directorates. These three entities represent contrasting geographic origination patterns—US-based corporate structures, German GmbH entities, and diversified pharmaceutical conglomerates—while converging on direct procurement relationships that disintermediate traditional veterinary supply chains.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Elanco |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals PLC |
| Phibro Animal Health Corporation |
| HIPRA |
| Others |
Supply & Pricing Matrix
Brazilian saponin harvest concentration and Indian oil-in-water emulsion production anchor upstream adjuvant supply, concentrating margin capture with formulation specialists who control cold-chain distribution into Mato Grosso feedlots and Andhra Pradesh layer operations. Price differentiation between DIVA-certified recombinant platforms and conventional inactivated vaccines reflects this upstream bottleneck structure.
Pricing Analysis
Certification level (USDA-CVB potency verification versus ANVISA fast-track approval) creates the primary spread between premium recombinant platforms and standard inactivated formulations. Three-tier pricing structure across premium, standard, and economy levels segments by cold-chain reliability guarantees and DIVA compliance documentation. Pricing pressure stems from adjuvant input volatility in agricultural commodity markets, compressing formulation margins for inactivated vaccine producers. Government procurement channels in India and Brazil exhibit highest price sensitivity, while Brazilian commercial farm consortiums negotiating direct supply agreements show lowest sensitivity due to unbundled preventive health budgets.
Supply Chain Analysis
Lonza, Boehringer Ingelheim's Biberach facility, and Zoetis' global manufacturing network hold dominant contract manufacturing capacity for veterinary biologics fermentation. Supply concentrates in Germany, the United States, and Brazil for active ingredient production, with fill-finish operations distributed across regional hubs. Raw material dependencies center on saponin extracts, aluminum hydroxide gel, and specialized cell culture media. Single-source vulnerability in saponin supply from Quillaja saponaria Chilean plantations poses structural risk. Distribution runs through veterinary distributor networks in mature markets, while direct-to-farm digital channels emerge in Southeast Asian poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in livestock vaccines are approaching an inflection as gene-edited antigen design and synthetic biology manufacturing converge, creating intellectual property licensing revenue pools distinct from bulk biological production and unbundling preventive health from integrated service contracts.
For Market Incumbents: Insulate recombinant platform margins through captive supply of CRISPR-edited antigen cell lines and backward integration into cold-chain logistics infrastructure. The threat of mRNA platform substitution by novel vector approaches demands accelerated DIVA-compliant product registration in Brazilian ANVISA parallel tracks. Certification investment in USDA-CVB potency verification timelines defends position against emerging generic manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's lumpy skin disease vaccine deployment through CDSCO-Animal Husbandry parallel approval coordination, bypassing entrenched distributor networks. Rural Rajasthan and Gujarat dairy belts represent the most penetrable geography, with government-subsidized cold-chain extension de-risking last-mile distribution. Tele-veterinary platform partnerships enable price-transparent procurement for mid-scale poultry layer operations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed recombinant platform specialists holding DIVA-capable antigen engineering IP. Long-term viability hinges on gene-edited vaccine platform convergence with synthetic biology manufacturing, creating licensing revenue streams decoupled from fermentation scale. Watch for regulatory science clarity on gene-edited products as the inflection indicator reshaping competitive boundaries between innovator and generic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Edited Platform Development | CRISPR-based antigen design enables serological distinction capabilities for export certification. |
| Cold-Chain Infrastructure Expansion | Rural India penetration requires refrigerated distribution into previously unreachable veterinary networks. |
| DIVA-Compliant Recombinant Scale-Up | Brazilian feedlot operators adopt marker vaccines to maintain beef export eligibility. |
| Direct-to-Farm Digital Channels | Tele-veterinary platforms bypass traditional distributor markups in Southeast Asian poultry markets. |
| Regulatory Parallel Track Navigation | CDSCO-Animal Husbandry coordination accelerates indigenous vaccine commercialization timelines. |
Research Methodology
Desk research of USDA Center for Veterinary Biologics regulatory filings, ANVISA approval databases, and EU Veterinary Medicines Regulation environmental risk assessments preceded structured interviews with vaccine development executives, regulatory affairs leads at animal health conglomerates, state livestock directorate procurement managers, and contract manufacturing organization technical directors. Secondary validation drew from customs and trade data for veterinary biologics, SEC 10-K filings of listed animal health companies, and CDSCO vaccine approval registers. Bottom-up volume estimates by species and formulation type were triangulated against top-down market sizing from government livestock health campaign budgets.
Assumptions held fixed include current regulatory pathway timelines for novel platform developers and existing cold-chain infrastructure penetration rates, while variables included gene-edited vaccine approval science evolution and adjuvant input commodity price trajectories. Segmentation dimensions modeled span vaccine type, target animal species, application purpose, and end-user procurement authority across the analysis window. CAGRs were derived from government health campaign expenditure projections and commercial farm consortium direct supply agreement trends, with veterinary biologics logistics specialist scarcity and legacy serology infrastructure retooling costs as industry-specific forecast inputs.
Stress conditions across saponin supply disruption, Brazilian foot-and-mouth disease eradication protocol acceleration, and Indian cold-chain extension pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with gene-edited regulatory science clarity and mRNA platform substitution velocity as specific risk factors that could revise projections. Quarterly review of ANVISA approval velocity and CDSCO rural campaign disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Otc Pet Medication Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Animal Model Market
Veterinary
Veterinary Software Market
Veterinary
USA Animal Model Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Global Animal Vaccine Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Canine Arthritis Market
Veterinary
Milking Salve Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
CBD Pet Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Veterinary Endotracheal Tubes Market