
 Spain Veterinary Healthcare Market | 2026-2036
Spain Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Veterinary Healthcare Market Analytics
Preventive care service revenue is reshaping margin distribution across Spain's veterinary healthcare landscape. Zoetis leverages its vaccine manufacturing scale to dominate companion animal immunization protocols nationwide. HIPRA anchors its position through in-house production of livestock biologics from its Girona headquarters. Boehringer Ingelheim competes via specialized parasiticide formulations tailored to Iberian climate conditions.
Veterinary healthcare encompasses the diagnosis, treatment, and prevention of disease in animals, utilizing pharmaceutical actives with defined purity grades, adjuvanted vaccine formulations, and implantable medical devices with biocompatible coatings to maintain animal productivity and welfare. Pharmaceuticals command the deepest margin pools among product types due to chronic condition management in aging companion animals. Diagnostics within service types records the fastest structural expansion as molecular testing migrates from reference labs into pet clinic workflows. Farm operators represent the most price-sensitive end user segment, though volume commitments offset thinner per-unit margins.
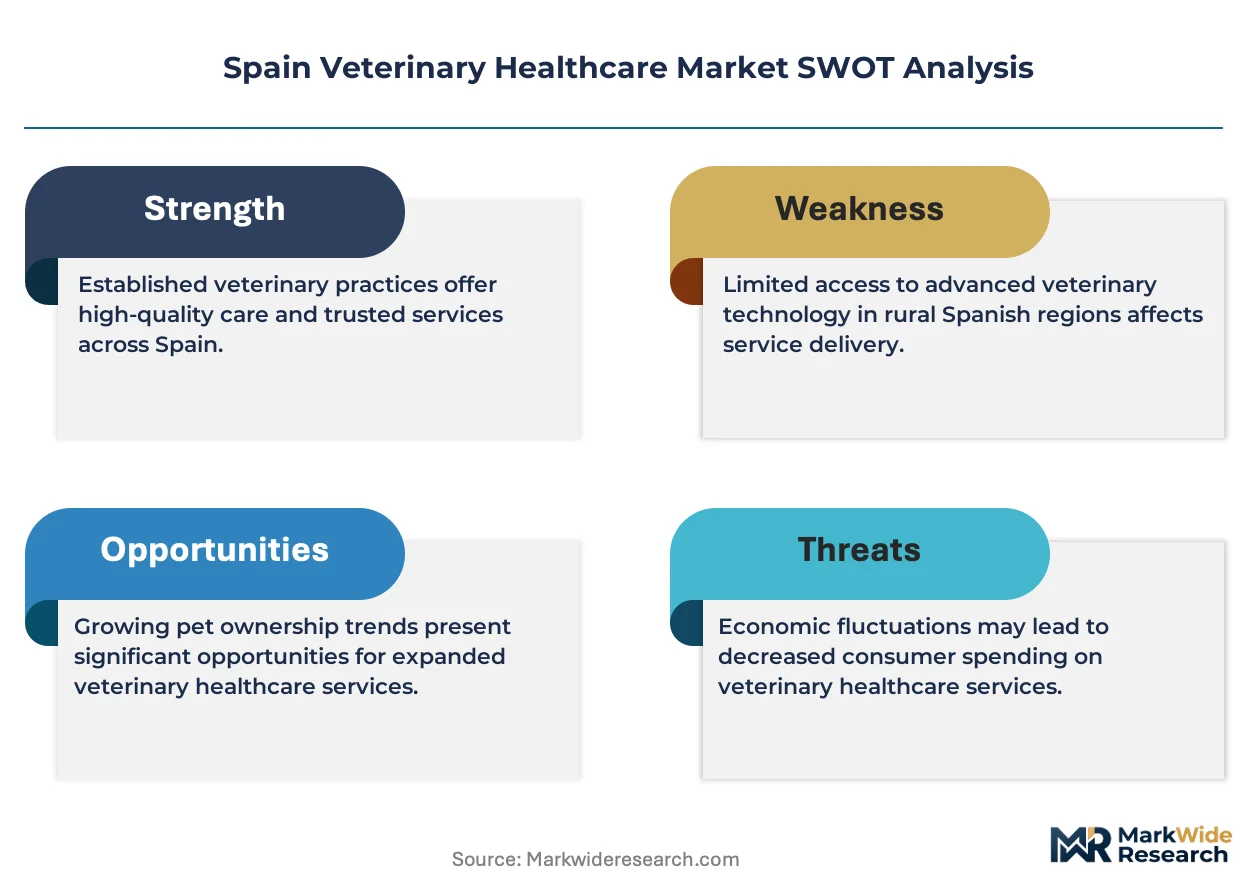
Spain's national pharmaceutical regulator enforces veterinary medicine traceability through the Royal Decree framework, while the EU Green Deal's farm-to-fork strategy tightens residue monitoring across livestock supply chains. The Spanish Agency for Medicines and Health Products coordinates with EMA guidelines to harmonize antimicrobial stewardship requirements. Stakeholders must monitor how decentralized diagnostic authorization at regional level alters clinic procurement patterns and service bundling economics.
Market Dynamics
Spain's Royal Decree on veterinary medicines traceability is compressing distribution layers and forcing wholesalers to consolidate warehousing networks, while companion animal owners in Madrid and Barcelona accelerate demand for point-of-care diagnostics.
Growth Catalysts
- EU Green Deal farm-to-fork strategy:Residue monitoring mandates across Andalusian livestock supply chains are expanding diagnostic testing volumes at slaughterhouses and dairy cooperatives.
- Companion animal aging demographics:Chronic condition management in dogs and cats over eight years old is extending prescription durations for anti-inflammatory and metabolic pharmaceuticals.
- Catalonia veterinary clinic consolidation:Multi-site practice groups in Barcelona province are centralizing procurement of vaccines and parasiticides, creating volume commitments that attract manufacturer direct contracts.
Market Restraints
- API import concentration:Active pharmaceutical ingredient sourcing for generic veterinary drugs remains concentrated among Asian suppliers, exposing formulators in Spain to currency volatility and shipping delays.
- Antimicrobial stewardship compliance costs:EMA guidelines on veterinary antimicrobial use are requiring Spanish farm operators to implement prescription audit trails, adding administrative overhead to preventive health programs.
- Biologics cold chain infrastructure gaps:Temperature-controlled distribution to rural Extremadura and Castile-La Mancha livestock operations limits same-day vaccine delivery and increases spoilage risk.
Strategic Opportunities
- Telemedicine platform integration:Remote consultation workflows are penetrating Galicia and Asturias veterinary practices, enabling triage services that reduce unnecessary clinic visits while capturing prescription revenue.
- Point-of-care molecular testing:PCR-based pathogen detection is migrating from reference laboratories into Madrid companion animal clinics, compressing diagnostic turnaround from days to hours.
- Regional diagnostic authorization decentralization:Autonomous community-level licensing of in-clinic laboratory tests is reducing regulatory lag for new assay introductions in Andalusia and Valencia.
Industry Challenges
- Veterinary specialist workforce scarcity:Board-certified surgeons and internal medicine practitioners are concentrated in Madrid and Barcelona, leaving Basque Country and Murcia clinics dependent on locum staffing.
- Legacy practice management system fragmentation:Independent clinics in smaller Castilian cities operate disconnected electronic health record platforms that resist integration with national traceability databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Veterinary Healthcare Market |
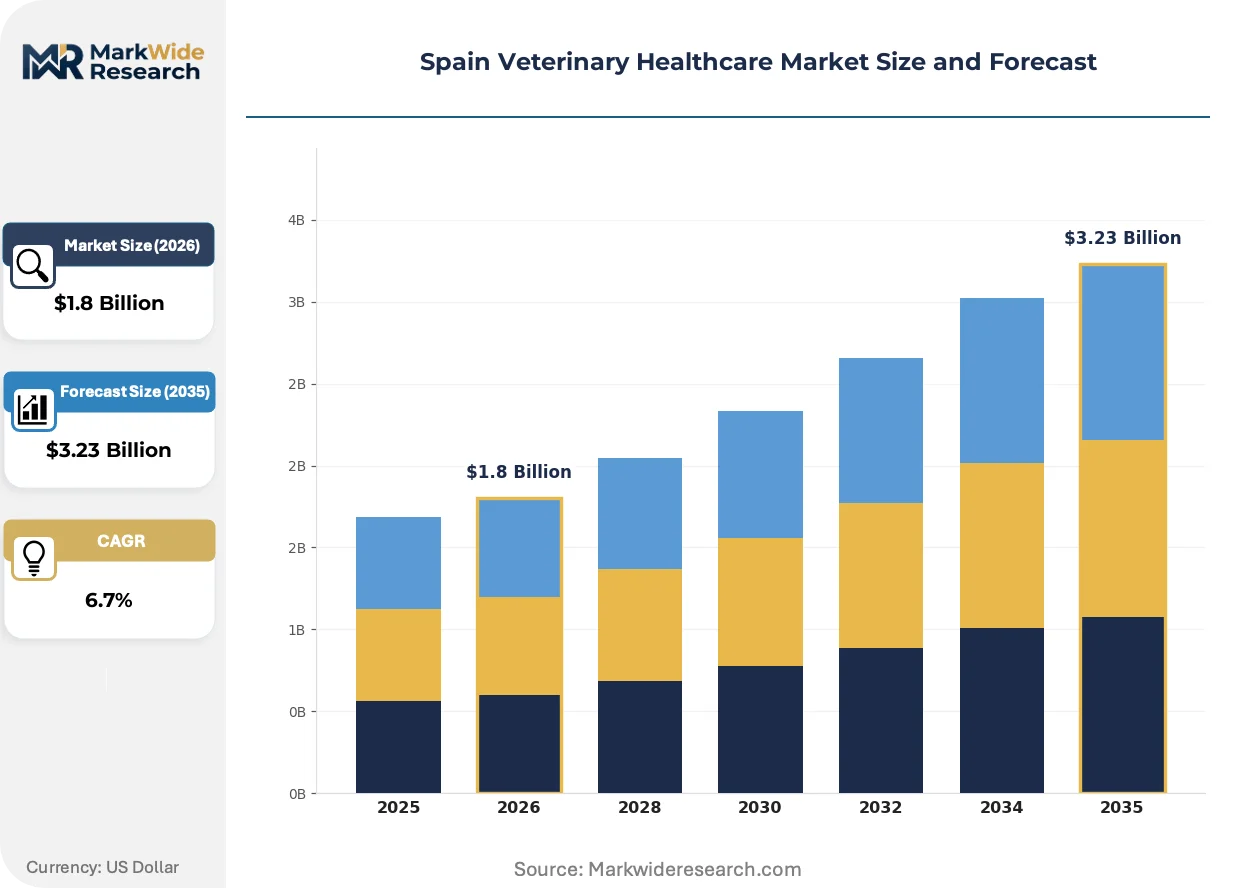
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Nutraceuticals, Medical Devices End User: Pet Clinics, Veterinary Hospitals, Animal Shelters, Farm Operators Delivery Mode: Oral, Injectable, Topical, Intranasal Service Type: Preventive Care, Surgical Services, Diagnostics, Emergency Care |
| Companies Covered | Elanco Animal Health, HIPRA, Zoetis, IVC Evidensia, Laboratorios Syva, Boehringer Ingelheim, IDEXX Laboratories, AniCura, Ceva Santé Animale, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Veterinary Healthcare Market Evolving Landscape
Artificial intelligence and connected diagnostics are compressing decision cycles in Spanish veterinary practice, while regulatory pressure on antimicrobial use is redirecting R&D investment toward preventive biologics and non-pharmaceutical interventions.
Point-of-care analyzers with cloud-connected result interpretation are digitizing hematology and biochemistry workflows in companion animal clinics across Madrid and Barcelona. Small animal practices with three or more veterinarians are adopting these platforms within eighteen months of market introduction. This digitization is reducing referral dependency on external laboratories and capturing margin previously lost to reference testing.
EMA antimicrobial stewardship guidelines are tightening prescription requirements for veterinary fluoroquinolones and third-generation cephalosporins across Spanish livestock operations. Farm veterinarians must now document clinical justification for each systemic antimicrobial course, creating documentation burdens that slow treatment protocols. Pig and poultry producers in Catalonia are responding by expanding vaccination programs and installing enhanced biosecurity infrastructure to reduce infectious disease pressure.
Subscription-based preventive care packages are displacing fee-for-service billing in urban companion animal practices. Young pet owners in Valencia and Seville are selecting monthly wellness plans that bundle vaccinations, parasiticide prophylaxis, and routine screening diagnostics. This consumption-pattern shift is smoothing clinic revenue seasonality while locking in patient loyalty against competing practices.
Spain Veterinary Healthcare Market Segmentation
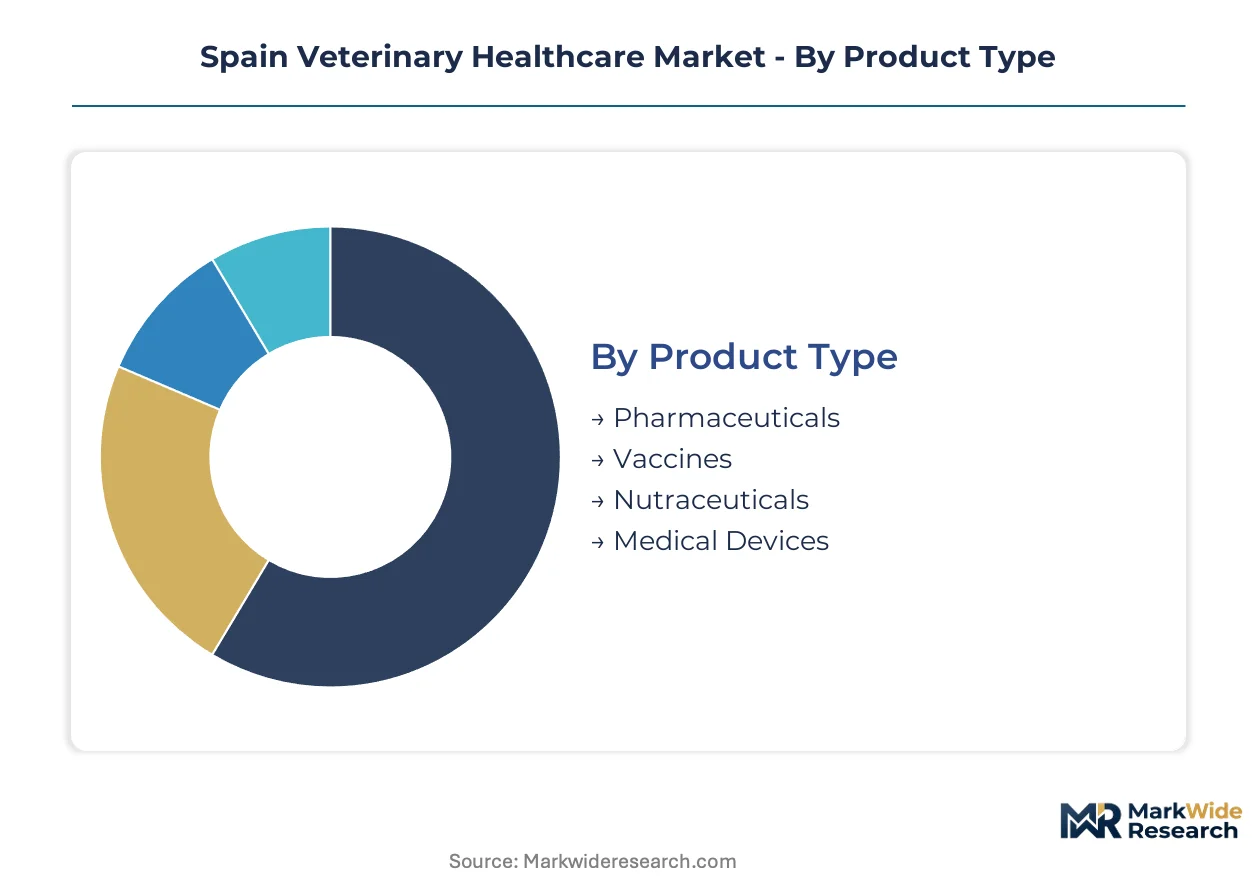
Segmentation reveals how margin pools and procurement cycles diverge across Spain's veterinary healthcare landscape. Product type determines inventory turnover velocity, while end-user concentration shapes distribution network design and service bundling economics.
Product Type:
Pharmaceuticals turn inventory slowest due to chronic prescription patterns, while vaccines and nutraceuticals cycle faster through seasonal demand spikes and routine preventive protocols.
- Pharmaceuticals:Anti-inflammatory agents, metabolic regulators, and antimicrobial formulations with defined purity grades command the deepest margin pools. Chronic condition management in aging companion animals across Madrid and Barcelona extends prescription durations and locks in recurring revenue streams for dispensing clinics.
- Vaccines:Adjuvanted formulations for companion animal core immunization and livestock preventive protocols require strict cold chain maintenance. Farm operators in Andalusia concentrate demand for bulk livestock biologics, while pet clinics in Catalonia prioritize single-dose companion animal vials with extended stability profiles.
- Nutraceuticals:Dietary supplements and functional feeds support joint health, digestive function, and coat condition in companion animals.
- Medical Devices:Implantable hardware with biocompatible coatings and surgical instruments serve orthopedic and soft-tissue procedures.
Pharmaceuticals anchors the volume base while vaccines gains share at the steepest rate.
End User:
Customer type stratifies by price sensitivity and procurement sophistication, with institutional buyers extracting volume discounts unavailable to fragmented independents.
- Pet Clinics:Small animal practices with one to three veterinarians dominate companion animal therapeutics procurement. Multi-site groups in Barcelona province centralize purchasing of vaccines and parasiticides, creating volume commitments that attract manufacturer direct contracts and compress distributor margins.
- Farm Operators:Pig and poultry producers in Catalonia and dairy cooperatives in Galicia represent the most price-sensitive segment. Volume commitments for preventive livestock vaccines offset thinner per-unit margins, while EU Green Deal residue monitoring mandates expand diagnostic testing volumes at slaughterhouses.
- Veterinary Hospitals:Referral centers with specialist capabilities capture complex surgical and emergency cases.
- Animal Shelters:Municipal and nonprofit facilities prioritize low-cost sterilization and core vaccination protocols.
Farm operators anchors the volume base while pet clinics gains share at the steepest rate.
Delivery Mode:
Route of administration determines formulation complexity and cold chain requirements, with parenteral options demanding stricter handling protocols than enteral alternatives.
- Injectable:Parenteral formulations including depot preparations and adjuvanted vaccines require sterile manufacturing and temperature-controlled distribution. Rural Extremadura and Castile-La Mancha livestock operations face same-day delivery constraints that increase spoilage risk for heat-sensitive biologics.
- Oral:Tablets, chewables, and medicated feeds offer compliance advantages in companion animal chronic disease management. Young pet owners in Valencia and Seville favor palatable formulations that simplify home administration of metabolic and anti-inflammatory protocols.
- Topical:Transdermal parasiticides and dermatological preparations provide localized therapeutic action.
- Intranasal:Mucosal vaccine delivery induces local immunity for respiratory pathogens.
Injectable anchors the volume base while oral gains share at the steepest rate.
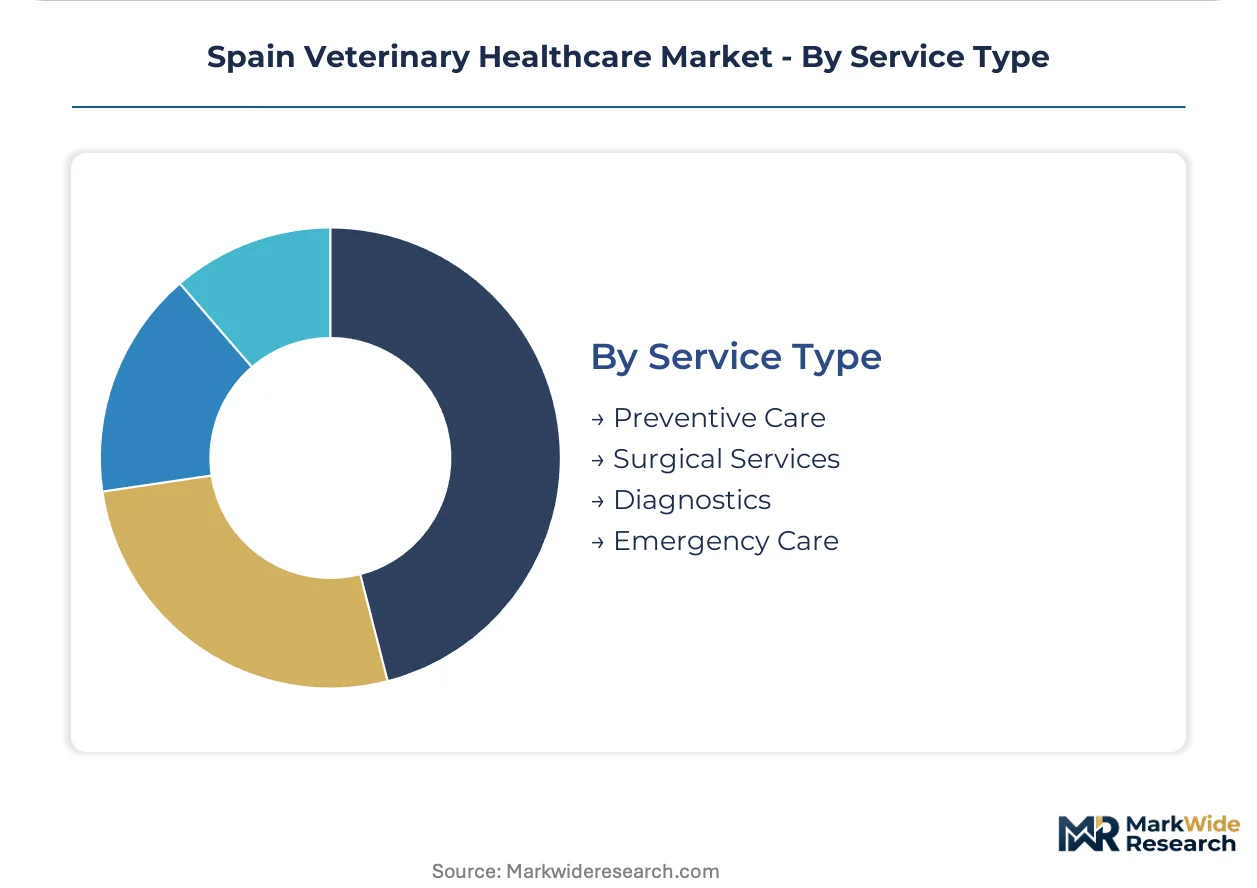
Service Type:
Service revenue stratifies by capital intensity and labor specialization, with procedural services commanding premium pricing over commodity preventive protocols.
- Diagnostics:Molecular testing and point-of-care analyzers are migrating from reference laboratories into clinic workflows. PCR-based pathogen detection in Madrid companion animal clinics compresses turnaround from days to hours, capturing margin previously lost to external laboratories.
- Preventive Care:Subscription-based wellness packages bundle vaccinations, parasiticide prophylaxis, and routine screening. This consumption-pattern shift smooths clinic revenue seasonality and locks patient loyalty against competing practices in urban centers.
- Surgical Services:Soft-tissue and orthopedic procedures require specialist training and capital equipment.
- Emergency Care:After-hours critical services concentrate in Madrid and Barcelona referral hospitals.
Preventive care anchors the volume base while diagnostics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Spain's autonomous communities diverge sharply between intensive livestock regions and urban companion animal centers, with diagnostic intensity and procurement sophistication varying by end-user concentration.
Catalonia
Pig and poultry producers in Lleida and Girona provinces drive demand for preventive livestock vaccines and biosecurity infrastructure. The autonomous community's regional veterinary authority enforces decentralized diagnostic authorization that accelerates in-clinic test licensing. Barcelona's multi-site veterinary groups centralize procurement of parasiticides and vaccines, attracting manufacturer direct contracts.
Madrid
Companion animal clinics in the capital concentrate demand for point-of-care molecular diagnostics and chronic disease pharmaceuticals. The Spanish Agency for Medicines and Health Products coordinates EMA antimicrobial stewardship guidelines from its Madrid headquarters, tightening prescription audit requirements. Referral hospitals in the metro area capture complex surgical cases from surrounding Castile-La Mancha and Extremadura regions.
Andalusia
Dairy cooperatives in Seville and Córdoba and extensive pig operations in Huelva generate volume demand for bulk livestock biologics. EU Green Deal farm-to-fork residue monitoring mandates expand diagnostic testing at slaughterhouses across the region. Farm veterinarians face administrative burdens from prescription documentation requirements for systemic antimicrobials.
Galicia
Dairy cattle density in A Coruña and Lugo provinces sustains demand for reproductive health services and metabolic disease management. Telemedicine platforms penetrate rural veterinary practices, enabling remote triage that reduces unnecessary clinic visits. The region's cooperative structures support consolidated vaccine procurement for dispersed livestock operations.
Basque Country
Specialist veterinary workforce scarcity leaves clinics in Bilbao and San Sebastián dependent on locum staffing for surgical and internal medicine referrals. Regional health authorities coordinate with Madrid on traceability database integration for independent practices. Small animal clinics adopt subscription-based preventive care packages to smooth revenue seasonality.
Spain Veterinary Healthcare Market Competitive Landscape
Capability concentration sits with research-intensive biologics developers; scale advantage sits with diversified animal health conglomerates. The market structures around three tiers: multinational pharmaceutical manufacturers with vaccine manufacturing scale, regional specialists with in-house production of livestock biologics, and consolidating veterinary service operators with multi-site procurement leverage. Dominant competitive moves include backward integration into vaccine manufacturing and geographic expansion through clinic group acquisitions.
Within the multinational tier, Zoetis and Boehringer Ingelheim occupy positions anchored by companion animal immunization and parasiticide portfolios. HIPRA exemplifies the regional specialist archetype through its Girona-based livestock biologics production. Elanco Animal Health represents the diversified pharmaceutical manufacturer with chronic disease management formulations. These three entities collectively span the capability-scale spectrum that defines competitive positioning in Spanish veterinary healthcare.
| Leading Market Players |
|---|
| Elanco Animal Health |
| HIPRA |
| Zoetis |
| IVC Evidensia |
| Laboratorios Syva |
| Boehringer Ingelheim |
| IDEXX Laboratories |
| AniCura |
| Ceva Santé Animale |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asian API manufacturing is compressing formulation margins for Spanish veterinary drug producers while simultaneously extending payment terms for bulk vaccine purchasers. Utilization rates below nameplate capacity among active pharmaceutical ingredient suppliers in India and China are forcing price concessions downstream, yet cold chain logistics costs for temperature-sensitive biologics are absorbing these gains.
Pricing Analysis
Long-term offtake contracts dominate vaccine procurement between livestock cooperatives and biologics manufacturers, while spot purchasing persists for generic pharmaceutical formulations. Price differentiation hinges on volume scale and cold chain certification tier, with EU GDP-compliant distribution commanding premiums over standard logistics. Cost compression in generic anti-infectives is intensifying because API import concentration exposes formulators to currency volatility. Farm operators in Andalusia represent the most price-sensitive buyer archetype, whereas referral hospitals in Madrid exhibit lowest sensitivity due to captive patient flows.
Supply Chain Analysis
EU dual-use export controls on biotechnology manufacturing equipment are constraining capacity expansion for domestic vaccine producers. Active pharmaceutical ingredient sourcing draws from India, China, and limited European capacity, while adjuvant chemistry and sterile filling equipment rest on German and Swiss suppliers. Single-source vulnerability in mRNA lipid nanoparticle inputs presents structural risk for next-generation veterinary vaccine developers. Distribution runs through temperature-controlled networks with regional consolidation points in Barcelona and Madrid before final-mile delivery to rural livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's veterinary healthcare market sits in early-cycle expansion as subscription-based preventive care packages accelerate penetration among urban companion animal owners. Point-of-care diagnostic adoption in Madrid and Barcelona clinics is creating durable revenue streams that outpace traditional fee-for-service models.
For Market Incumbents: Insulate vaccine margin pools through captive cold chain infrastructure investments in Extremadura and Castile-La Mancha, where biologics spoilage risk currently cedes share to oral pharmaceutical alternatives. Deepen backward integration into adjuvant chemistry production to offset API import volatility that threatens generic formulation profitability. Regulatory pressure from EMA antimicrobial stewardship guidelines is accelerating substitution toward preventive biologics; incumbents controlling livestock vaccine manufacturing scale will capture this shift.
For New Entrants and Emerging Players: Build out telemedicine-enabled prescription workflows targeting Galicia and Asturias, where rural veterinary practice fragmentation creates whitespace for remote triage services that capture pharmaceutical revenue without physical clinic investment. The most penetrable segment lies in point-of-care molecular diagnostics for companion animal infectious disease, where regional authorization decentralization in Catalonia and Andalusia reduces regulatory lag versus reference laboratory competition. A direct-to-clinic distribution model bypassing traditional wholesale layers aligns with procurement centralization trends among Barcelona multi-site practice groups.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-site veterinary service operators with subscription wellness plan penetration above fifty percent of active patients. Five-to-ten year viability favors platforms consolidating independent clinics in secondary Castilian cities, where legacy practice management system fragmentation creates integration upside for standardized electronic health record deployments. Acquisition targets should demonstrate regional diagnostic authorization licenses or cold chain distribution assets with same-day rural coverage capability. The signal to watch is decentralized licensing velocity for in-clinic PCR assays across autonomous communities, which would accelerate diagnostic margin capture and validate platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adjuvant Chemistry | Captive supply of vaccine formulation inputs reduces exposure to German and Swiss supplier concentration. |
| Regional Diagnostic Authorization Licensing | Autonomous community-level approvals in Catalonia accelerate PCR assay commercialization versus national pathways. |
| Cold Chain Infrastructure Expansion | Temperature-controlled distribution to rural Extremadura livestock operations addresses same-day delivery constraints. |
| Multi-Site Clinic Consolidation | Centralized procurement leverage attracts manufacturer direct contracts and compresses distributor margins. |
| Telemedicine Platform Integration | Remote consultation workflows in Galicia capture prescription revenue while reducing physical clinic overhead. |
Research Methodology
The analysis maps companion animal therapeutics, livestock biologics, diagnostic services, and preventive care protocols, each validated through veterinary practice owners, pharmaceutical procurement managers, farm cooperative veterinarians, and regulatory affairs specialists at the Spanish Agency for Medicines and Health Products. Primary fieldwork combined structured interviews with secondary validation against EMA guideline publications, EU Green Deal farm-to-fork strategy documents, autonomous community veterinary authority licensing records, and cold chain logistics operator disclosures. Bottom-up clinic and farm operator demand estimates triangulated against top-down manufacturer shipment data.
Assumptions held fixed include EMA antimicrobial stewardship compliance timelines, EU GDP cold chain standards, and regional diagnostic authorization decentralization velocity across autonomous communities. The analytical framework modeled product type, end user concentration, delivery mode, and service type dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific inputs encompassed livestock herd size projections from agricultural ministry statistics and companion animal demographic aging patterns from veterinary insurance enrollment data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian API suppliers to establish European formulation partnerships would shift outcomes. Material shifts in EMA residue monitoring enforcement intensity or autonomous community diagnostic licensing reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Antibiotics Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Canine Arthritis Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Global Animal Vaccine Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Veterinary Lasers Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Global Dog Vaccines Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market