
 Veterinary Immunodiagnostics Market | 2026-2036
Veterinary Immunodiagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Immunodiagnostics Market Intelligence
A shift from single-source reagent supply toward multi-source procurement is rebalancing vendor relationships across veterinary laboratories. IDEXX Laboratories, Inc. anchors its position through captive distribution into reference labs and in-clinic analyzers. Zoetis Services LLC differentiates via species-specific assay portfolios spanning livestock and companion animals. Thermo Fisher Scientific Inc. extends its reach through private-label partnerships with regional diagnostic manufacturers.
Veterinary immunodiagnostics encompasses antigen-antibody detection systems engineered for pathogen identification, immune status evaluation, and disease surveillance in animal populations. ELISA reagents and lateral flow assays constitute the core consumable layers, with chemiluminescence platforms gaining traction in high-throughput reference settings. Antibody kits and rapid test strips command the largest revenue pools due to recurring consumable pull from clinics performing routine heartworm, parvovirus, and feline leukemia screening. Immunoassay analyzers represent the fastest-growing capital segment as practices automate workflow to offset labor constraints.
The FDA Center for Veterinary Medicine and USDA APHIS impose parallel validation requirements on commercial assay kits, creating dual-track compliance burdens for manufacturers seeking US market access. ISO 17025 accreditation and the EU In Vitro Diagnostic Regulation shape laboratory quality standards across European diagnostic networks. Stakeholders must monitor evolving harmonization efforts between national veterinary drug regulators and human diagnostic frameworks that increasingly inform animal health policy.
Market Dynamics
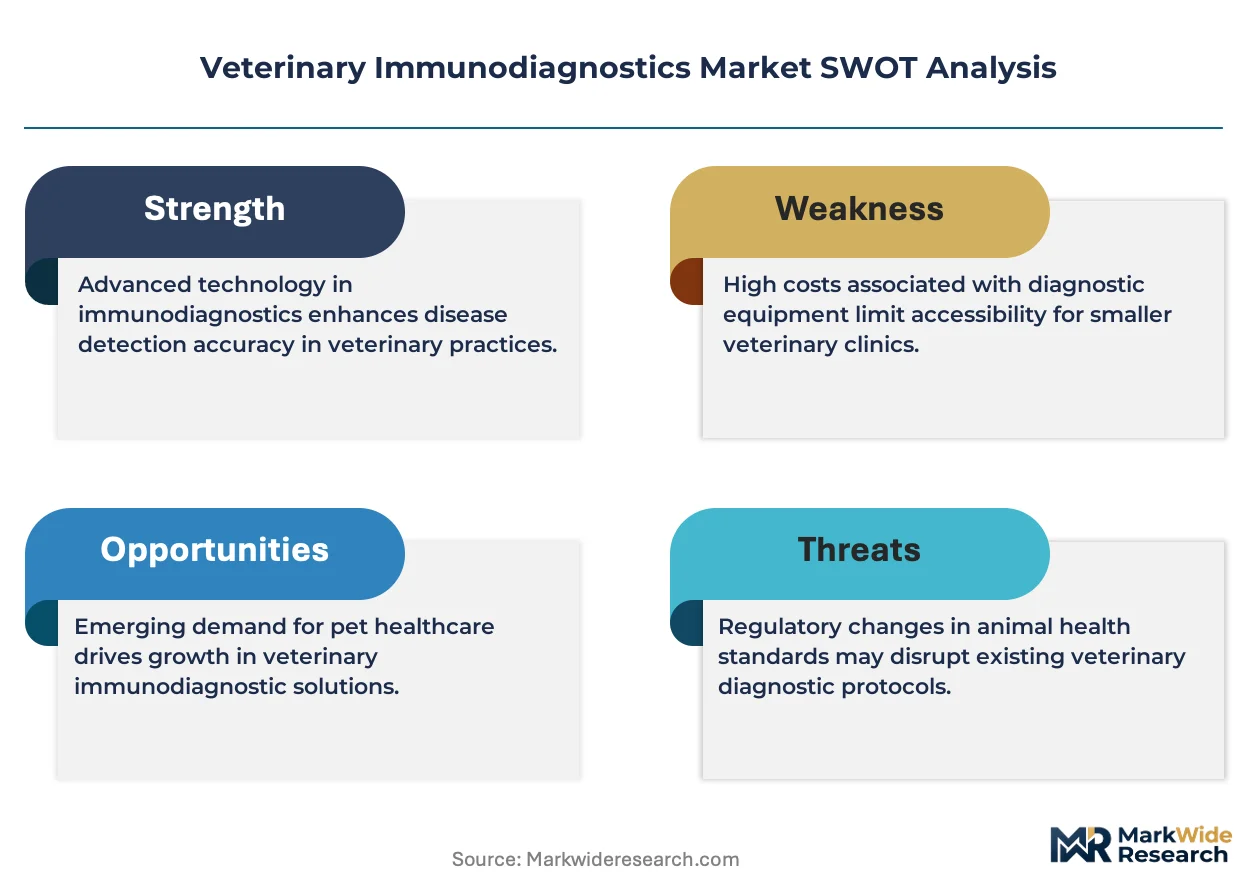
Laboratory automation is compressing turnaround times for veterinary diagnostics while simultaneously elevating capital requirements for independent practices seeking to retain referral revenue.
Growth Catalysts
- USDA APHIS surveillance mandates:Federal pathogen monitoring programs in livestock operations generate recurring bulk orders for ELISA panels and bulk reagent contracts.
- Point-of-care analyzer penetration:Companion animal clinics are installing compact immunoassay platforms to capture same-day diagnostic revenue previously lost to reference laboratories.
- Pet insurance normalization:Reimbursement coverage for diagnostic testing in North American and Western European markets removes price sensitivity from clinical decision-making.
Market Restraints
- Dual-track validation costs:FDA Center for Veterinary Medicine and USDA APHIS impose parallel premarket submission requirements that extend commercialization timelines for assay developers.
- Reagent supply concentration:Monoclonal antibody production for veterinary diagnostics clusters among contract biologics manufacturers in select OECD jurisdictions.
- Lateral flow sensitivity ceilings:Rapid test strip technology faces inherent detection limits that prevent substitution for laboratory-grade quantification in regulatory export certification.
Strategic Opportunities
- EU In Vitro Diagnostic Regulation harmonization:IVDR classification pathways for veterinary devices create clarity for manufacturers seeking CE-marked entry into European diagnostic networks.
- Aquaculture disease surveillance:Farmed salmon and shrimp operations in Norway and Chile represent underpenetrated end-use verticals with unconsolidated testing protocols.
- Telemedicine integration:Remote consultation platforms are creating demand for home-sample collection kits paired with mail-in lateral flow screening.
Industry Challenges
- Veterinary pathologist scarcity:Reference laboratories face recruitment bottlenecks for board-certified diagnosticians capable of complex immunohistochemistry interpretation.
- Legacy analyzer interoperability:Proprietary reagent lock-in from installed base equipment complicates multi-vendor procurement strategies for mid-sized clinic chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Immunodiagnostics Market |
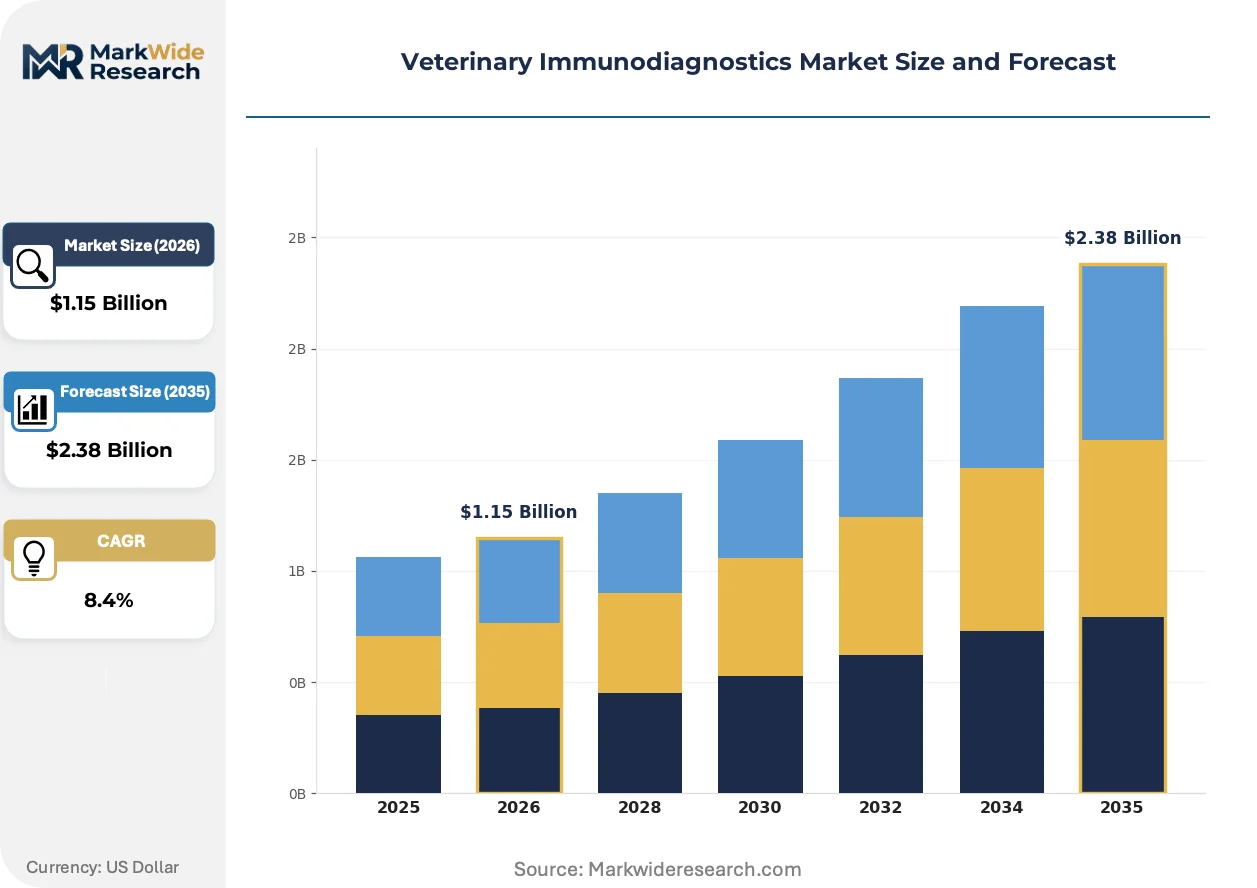
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibody Kits, ELISA Reagents, Immunoassay Analyzers, Rapid Test Strips, Lateral Flow Assays Technology: Enzyme-Linked Immunosorbent Assay, Immunofluorescence, Chemiluminescence, Western Blotting, Radioimmunoassay Application: Infectious Disease Detection, Parasitic Diagnosis, Allergy Testing, Hormonal Analysis, Autoimmune Disorder Identification End User: Veterinary Clinics, Diagnostic Laboratories, Research Institutions, Pharmaceutical Manufacturers |
| Companies Covered | Antech Diagnostics, Inc., Neogen Corporation, IDEXX Laboratories, Inc., Virbac, Bio-Rad Laboratories, Inc., Zoetis Services LLC, bioMérieux, Heska Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Immunodiagnostics Market Strategic Shifts & Innovations
Chemiluminescence platforms are migrating from human clinical laboratories into veterinary reference settings, altering competitive dynamics between capital equipment tiers.
Multiplexed bead-based immunoassays are absorbing demand from single-analyte ELISA workflows in high-volume reference laboratories. Large diagnostic networks in the United States and Germany are consolidating cardiac, endocrine, and infectious disease panels onto unified platforms. This technology is absorbing capital budgets previously allocated to discrete analyzer purchases while compressing per-test operational costs.
The EU In Vitro Diagnostic Regulation is reclassifying veterinary immunodiagnostic devices according to risk-based categories that mirror human medical device frameworks. Manufacturers must now compile clinical performance data for CE marking submissions that previously required only self-certification. Reference laboratories in France and the Netherlands are prioritizing IVDR-compliant suppliers in procurement tenders to preempt supply continuity risks.
Subscription-based reagent procurement is displacing transactional purchase orders in multi-site veterinary practice groups. Corporate-owned clinic chains in the United Kingdom and Australia are negotiating all-inclusive per-test pricing that bundles analyzer placement, maintenance, and consumable supply. This model concentrates purchasing authority at regional headquarters and marginalizes independent distributors.
Veterinary Immunodiagnostics Market Segmentation
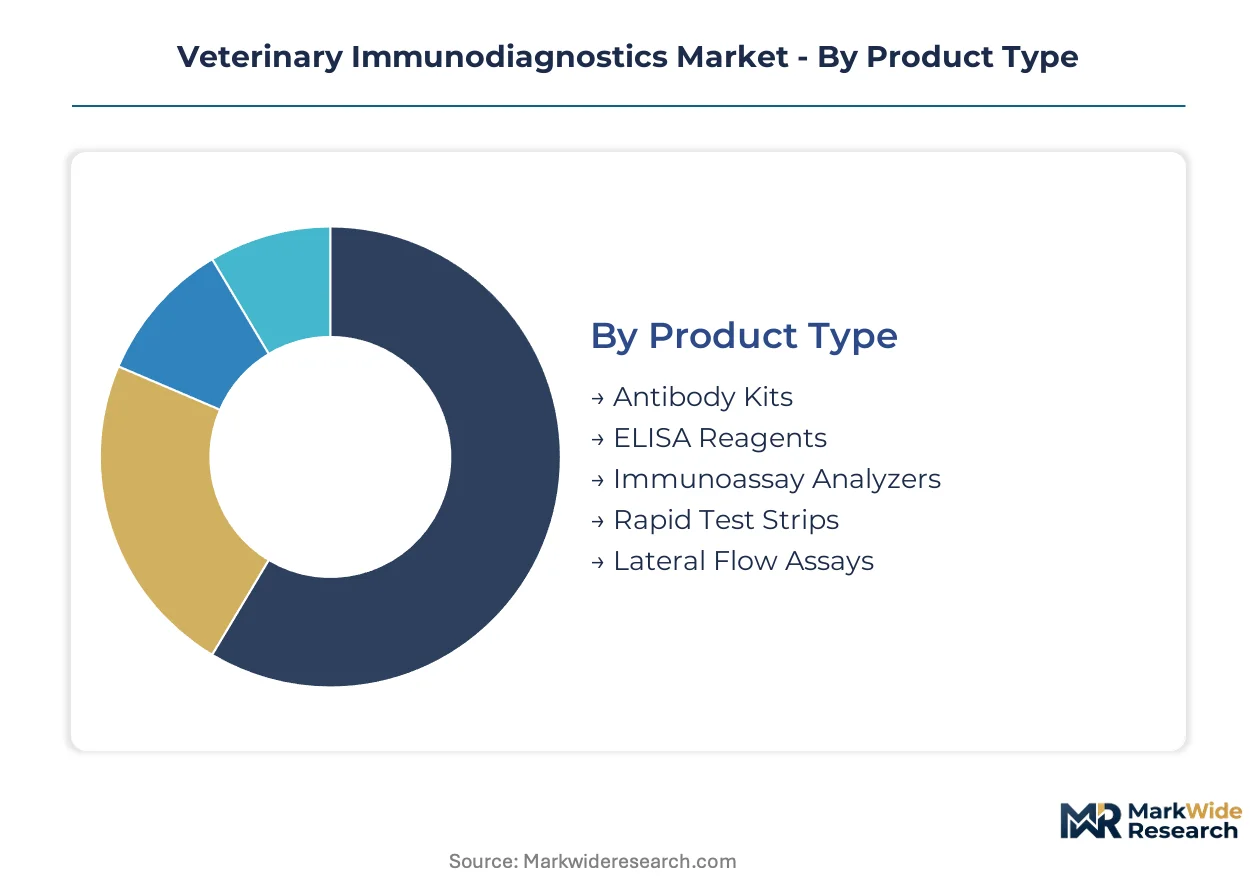
Veterinary immunodiagnostics segments along four intersecting dimensions that determine procurement patterns and upgrade cycles. Product type and technology choices drive capital allocation, while application and end-user categories shape recurring consumable demand across companion and livestock settings.
Product Type:
Replacement cycles for consumables compress as clinics automate workflows and consolidate vendor relationships around integrated platform ecosystems.
- Antibody Kits:Polyclonal and monoclonal antibody preparations enable pathogen-specific detection in serum, plasma, and tissue samples. Demand concentrates in North American reference laboratories performing USDA APHIS-mandated livestock screening, where bulk reagent contracts lock in multi-year supply relationships.
- Rapid Test Strips:Single-use lateral flow devices deliver qualitative results for heartworm, parvovirus, and feline leukemia at the point of care. Companion animal clinics in Germany and the United Kingdom deploy these for same-day client consultations, capturing diagnostic revenue previously referred to external laboratories.
- ELISA Reagents:Microplate-based detection systems for quantitative antibody and antigen measurement in high-throughput settings.
- Immunoassay Analyzers:Automated benchtop and floor-standing instruments processing chemiluminescence and fluorescence signals.
- Lateral Flow Assays:Membrane-based immunochromatographic tests for field-deployable disease surveillance in remote agricultural regions.
Antibody kits sit at the top of the volume ranking, with immunoassay analyzers climbing the fastest.
Technology:
Platform migration decisions hinge on sensitivity requirements, throughput needs, and compatibility with existing laboratory information management systems.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection in 96-well microplate formats remains the workhorse for bulk infectious disease screening. USDA APHIS surveillance programs in cattle feedlots and swine operations generate recurring demand for validated ELISA panels with documented analytical performance.
- Chemiluminescence:Acridinium ester and alkaline phosphatase substrates deliver picogram-level sensitivity for endocrine and cardiac biomarker quantification. Reference laboratories in France and the Netherlands are consolidating hormone testing onto unified chemiluminescence platforms to reduce per-test operational costs.
- Immunofluorescence:Fluorophore-conjugated antibody detection for cellular and tissue-based diagnostics requiring morphological correlation.
- Western Blotting:Electrophoretic protein separation combined with antibody probing for confirmatory testing in regulatory export certification.
- Radioimmunoassay:Isotope-labeled competitive binding assays for specialized endocrine diagnostics in research settings.
ELISA commands the largest installed base, though chemiluminescence is gaining share fastest among capital replacement decisions.
Application:
Test menu breadth determines client retention for multi-site practice groups negotiating corporate procurement contracts.
- Infectious Disease Detection:Viral and bacterial pathogen identification dominates routine screening protocols. Point-of-care platforms in United States companion animal clinics now cover canine parvovirus, feline leukemia virus, and heartworm antigen detection, reducing referral dependency.
- Parasitic Diagnosis:Antibody and antigen detection for vector-borne pathogens including Ehrlichia, Anaplasma, and Leishmania species. Veterinary diagnostic networks in Spain and Italy face elevated demand from Mediterranean climate expansion of tick habitats.
- Allergy Testing:IgE-specific serological panels for environmental and food allergen identification in atopic companion animals.
- Hormonal Analysis:Quantitative cortisol, thyroxine, and progesterone measurement for endocrine disorder management and breeding optimization.
- Autoimmune Disorder Identification:Autoantibody profiling for immune-mediated hemolytic anemia and thrombocytopenia in canine and feline patients.
Infectious disease detection leads procedure volume, with parasitic diagnosis expanding most quickly in climate-affected geographies.
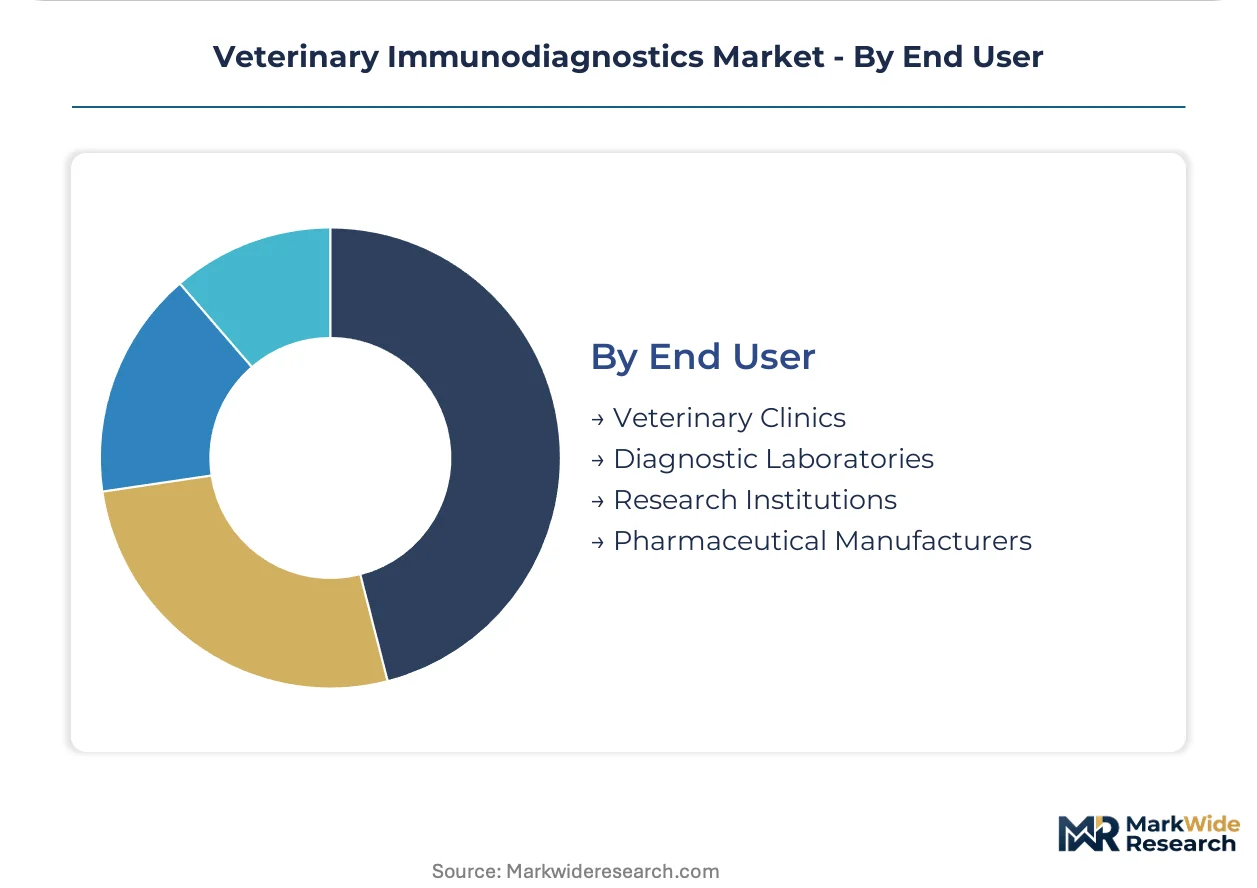
End User:
Procurement authority concentrates as corporate consolidation reshapes purchasing relationships across veterinary service delivery.
- Veterinary Clinics:Companion animal practices ranging from single-doctor operations to corporate-owned multi-site chains. Mars Veterinary Health and IVC Evidensia in the United Kingdom negotiate enterprise-level analyzer placements with bundled reagent pricing that marginalizes independent distributors.
- Diagnostic Laboratories:Reference and regional laboratories processing samples from multiple submitting clinics. Antech Diagnostics and IDEXX Reference Laboratories in the United States compete on turnaround time and test menu breadth, driving automation investment.
- Research Institutions:Academic veterinary schools and government agricultural research centers developing novel assay methodologies.
- Pharmaceutical Manufacturers:Vaccine and therapeutic developers requiring immunogenicity and safety testing for regulatory submission packages.
Veterinary clinics account for the largest end-user segment by test volume, with diagnostic laboratories showing the steepest expansion trajectory in capital equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as assay developers relocate production to jurisdictions with streamlined veterinary device pathways. The United States maintains the strictest dual-agency oversight, while European markets offer harmonized CE marking under IVDR classifications.
United States
Companion animal insurance penetration drives diagnostic spending in metropolitan veterinary networks. The FDA Center for Veterinary Medicine and USDA APHIS impose parallel premarket validation requirements that extend commercialization timelines. Boston and San Diego host concentrated biotechnology clusters where contract manufacturers produce monoclonal antibody reagents for domestic assay kit assembly.
Germany
Reference laboratories in Munich and Hamburg are consolidating cardiac and endocrine panels onto unified chemiluminescence platforms. The EU In Vitro Diagnostic Regulation reclassifies veterinary devices according to risk-based categories mirroring human medical frameworks. The Baden-Württemberg region anchors precision instrument manufacturing for automated immunoassay analyzers serving European diagnostic networks.
France
Laboratories in Lyon and Paris prioritize IVDR-compliant suppliers in procurement tenders to preempt supply continuity risks. ANSM oversight aligns with EU harmonized standards while maintaining national pharmacovigilance requirements. The Île-de-France cluster supports reagent production for livestock disease surveillance programs serving Mediterranean agricultural operations.
China
Domestic manufacturers are capturing share in aquaculture disease testing for farmed shrimp and tilapia operations. NMPA regulatory pathways for veterinary diagnostics are converging with human IVD frameworks under revised classification rules. The Yangtze River Delta concentration of biologics contractors supplies antibody raw materials to regional assay developers.
Brazil
Livestock export certification requirements generate demand for validated ELISA panels in cattle and poultry operations. ANVISA regulatory alignment with OIE standards supports regional assay kit registration for foot-and-mouth disease surveillance. São Paulo state hosts the principal veterinary diagnostic laboratory network serving Mercosur agricultural trade compliance.
Veterinary Immunodiagnostics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue point-of-care platform specialization and aquaculture assay development. The market exhibits consolidated reference laboratory channels alongside fragmented in-clinic analyzer placement. Three archetypes dominate: integrated life science conglomerates with captive reagent supply, species-focused animal health specialists, and contract manufacturing organizations serving private-label regional brands. Competitive maneuvering concentrates on analyzer placement contracts with bundled consumable pricing and IVDR compliance certification for European market access.
Within the integrated diagnostics tier, IDEXX Laboratories, Inc. and Thermo Fisher Scientific Inc. exemplify scale-driven platform ecosystems spanning reagent production to analyzer distribution. Zoetis Services LLC occupies a position representing species-specific portfolio breadth across livestock and companion animal applications. These three entities anchor the competitive structure through captive supply relationships and reference laboratory integration.
| Leading Market Players |
|---|
| Antech Diagnostics, Inc. |
| Neogen Corporation |
| IDEXX Laboratories, Inc. |
| Virbac |
| Bio-Rad Laboratories, Inc. |
| Zoetis Services LLC |
| bioMérieux |
| Heska Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Monoclonal antibody production costs in contract biologics facilities cascade through three distinct pricing tiers for veterinary diagnostic reagents, with US and European manufacturers absorbing premium-grade certification overhead while Asian producers capture economy-tier volume through less stringent validation pathways.
Pricing Analysis
Input-cost pass-through from purified antibody raw materials and specialized assay substrates drives pricing stratification across premium, standard, and economy tiers. Premium-tier reagents carry FDA Center for Veterinary Medicine and USDA APHIS dual-validation documentation, while standard-tier products meet ISO 17025 laboratory accreditation without premarket submission overhead. Pricing pressure stems from corporate clinic chains consolidating procurement authority through subscription-based per-test bundling. Independent companion animal practices in North America exhibit highest price sensitivity due to unbundled capital expenditure exposure, whereas reference laboratories demonstrate lowest sensitivity through amortized high-throughput volume.
Supply Chain Analysis
Direct-to-reference-laboratory channels handle bulk reagent contracts for USDA APHIS surveillance programs, while distributor networks serve fragmented clinic demand across rural geographies. Antibody raw material production concentrates in the United States, Germany, and China, with final assay kit assembly distributed across regional manufacturing hubs to satisfy local validation requirements. Supply chain vulnerability rests on single-source dependencies for high-affinity monoclonal antibody clones produced at select OECD contract biologics facilities. Distribution runs through captive direct sales forces for integrated diagnostic conglomerates, independent veterinary distributors for mid-tier manufacturers, and private-label partnerships for regional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary immunodiagnostics has matured into a late-cycle quality market where IVDR compliance certification and chemiluminescence platform precision now determine procurement decisions ahead of raw price competition.
For Market Incumbents: To counter subscription-based procurement consolidation by corporate clinic chains, deepen captive reagent supply through backward integration into monoclonal antibody production and secure IVDR-compliant manufacturing capacity in European Union jurisdictions ahead of tender qualification deadlines. For New Entrants and Emerging Players: Begin with aquaculture disease surveillance in Norway and Chile, where unconsolidated testing protocols and absence of entrenched reference laboratory networks create white-space entry conditions for species-specific assay development. For Investors and Strategic Acquirers: Consolidation pressure builds where IVDR compliance costs exceed standalone revenue bases, favoring acquisition targets with validated chemiluminescence platforms and existing European diagnostic network relationships. Monitor harmonization progress between FDA Center for Veterinary Medicine and USDA APHIS validation pathways as signal for regulatory arbitrage opportunity contraction.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Certification | CE marking under EU In Vitro Diagnostic Regulation unlocks procurement tenders from French and Dutch reference laboratories. |
| Chemiluminescence Platform Migration | Consolidated cardiac and endocrine testing onto unified analyzers reduces per-test operational costs in German diagnostic networks. |
| Subscription-Based Reagent Procurement | Corporate clinic chains in the United Kingdom negotiate bundled per-test pricing that marginalizes independent distributors. |
| Monoclonal Antibody Backward Integration | In-house biologics production insulates margin from contract manufacturer concentration in select OECD jurisdictions. |
| Aquaculture Assay Development | Farmed salmon and shrimp operations in Norway and Chile represent underpenetrated verticals with unconsolidated testing protocols. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reference laboratory directors, veterinary clinic procurement managers, contract biologics manufacturing executives, and regulatory affairs specialists at assay developers with secondary validation against FDA Center for Veterinary Medicine premarket submission databases, USDA APHIS surveillance program procurement records, EU IVDR classification guidance documents, and ISO 17025 accreditation registries. Bottom-up segment sizing triangulated against top-down macroeconomic veterinary expenditure trends.
Segment-weighting across product type, technology platform, application category, and end-user archetype determined revenue allocation through the projection horizon. CAGRs derived from historical trajectory analysis modified by technology substitution rates and regulatory compliance cost absorption curves. Forecast inputs incorporated pet insurance penetration trajectories in North American and Western European markets alongside automation adoption curves for point-of-care analyzer placement.
Several conditions sit outside the modeled scope, including emergent zoonotic pathogen outbreaks requiring emergency assay validation, abrupt harmonization or divergence between FDA and USDA regulatory pathways, and trade restriction impacts on monoclonal antibody raw material flows. Forecasts reflect documented assumptions subject to revision from these factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Disinfectants Market
Veterinary
Veterinary Consumables Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Animal Model Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Global Swine Vaccines Market
Veterinary
Milking Salve Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
United Kingdom Veterinary Healthcare Market