
 Global Veterinary Drugs Market | 2026-2036
Global Veterinary Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Drugs Market Foresight
China's manufacturing corridor for active pharmaceutical ingredients is reconfiguring supply dynamics for veterinary formulations worldwide. Zoetis Inc. leverages its biologics platform to sustain leadership in vaccine production across multiple species. Boehringer Ingelheim GmbH anchors its competitive position through deep R&D investment in antiparasitic pipelines. Merck & Co. Inc. differentiates via integrated health monitoring tools bundled with pharmaceutical portfolios.
Veterinary drugs comprise pharmacologically active substances formulated for disease prevention, diagnosis, and treatment in animals, including small-molecule antibiotics, recombinant vaccines, and hormonal regulators synthesized through fermentation, chemical synthesis, or biotechnological methods; these agents modulate physiological functions to maintain productivity in food animals and extend lifespans in companion species. Antiparasitics command substantial margin pools due to recurring prophylactic dosing cycles in livestock operations. Vaccines represent the fastest-expanding category as producers shift toward preventive health frameworks. Companion animal facilities drive premium pricing for nutritional supplements formulated with species-specific bioavailability profiles.
The FDA's Center for Veterinary Medicine enforces strict approval pathways for new animal drug applications, while the EMA's veterinary medicines committee harmonizes safety standards across European jurisdictions. China's NMPA and Ministry of Agriculture and Rural Affairs coordinate oversight of veterinary drug production licenses and residue monitoring programs. Stakeholders must monitor evolving antimicrobial stewardship mandates that restrict conventional therapeutic options and redirect investment toward novel modalities.
Market Dynamics
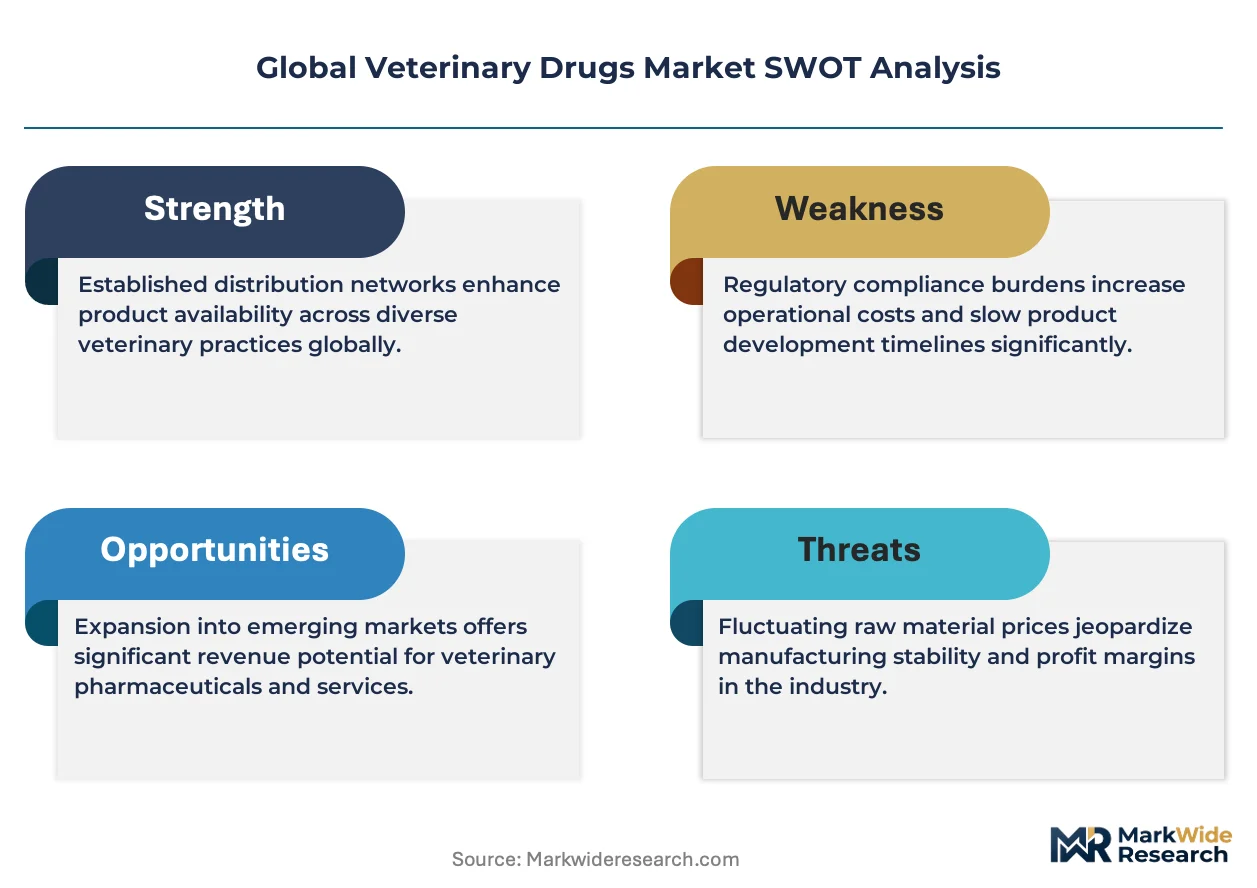
Antimicrobial stewardship mandates are compressing conventional therapeutic pipelines while redirecting R&D investment toward novel biologic modalities and precision delivery systems.
Growth Catalysts
- EU Veterinary Medicines Regulation:Tightened residue limits are accelerating adoption of preventive vaccine protocols across European livestock operations.
- Precision livestock farming:Sensor-integrated health monitoring systems in Brazil's cattle-producing states are driving pharmaceutical procurement for targeted intervention.
- Biologics platform expansion:Recombinant vaccine manufacturing advances are enabling multi-species protection with reduced dosing frequency.
Market Restraints
- Active pharmaceutical ingredient concentration:China's manufacturing corridor controls critical fermentation capacity, creating supply vulnerability for non-integrated formulators.
- Antimicrobial resistance protocols:FDA Center for Veterinary Medicine restrictions on growth-promoting antibiotics are eliminating historical revenue streams in feed-grade segments.
- Protein input cost volatility:Serum-dependent cell culture media for vaccine production faces price instability from bovine sourcing constraints.
Strategic Opportunities
- Companion animal nutrition:Species-specific bioavailability supplements for aging pet populations command premium positioning in North American veterinary clinics.
- Digital therapeutics convergence:Integration of pharmacological agents with wearable diagnostics creates subscription-based preventive health models.
- Southern China pork operations:Intensive biosecurity upgrades following disease outbreaks are expanding vaccine procurement budgets for herd immunity protocols.
Industry Challenges
- Veterinary biostatistics expertise:Field trial design for novel antiparasitic candidates requires specialized talent pools concentrated in limited academic centers.
- Multi-jurisdiction dossier preparation:Divergent data requirements between EMA veterinary medicines committee and China's NMPA extend approval timelines for global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Drugs Market |
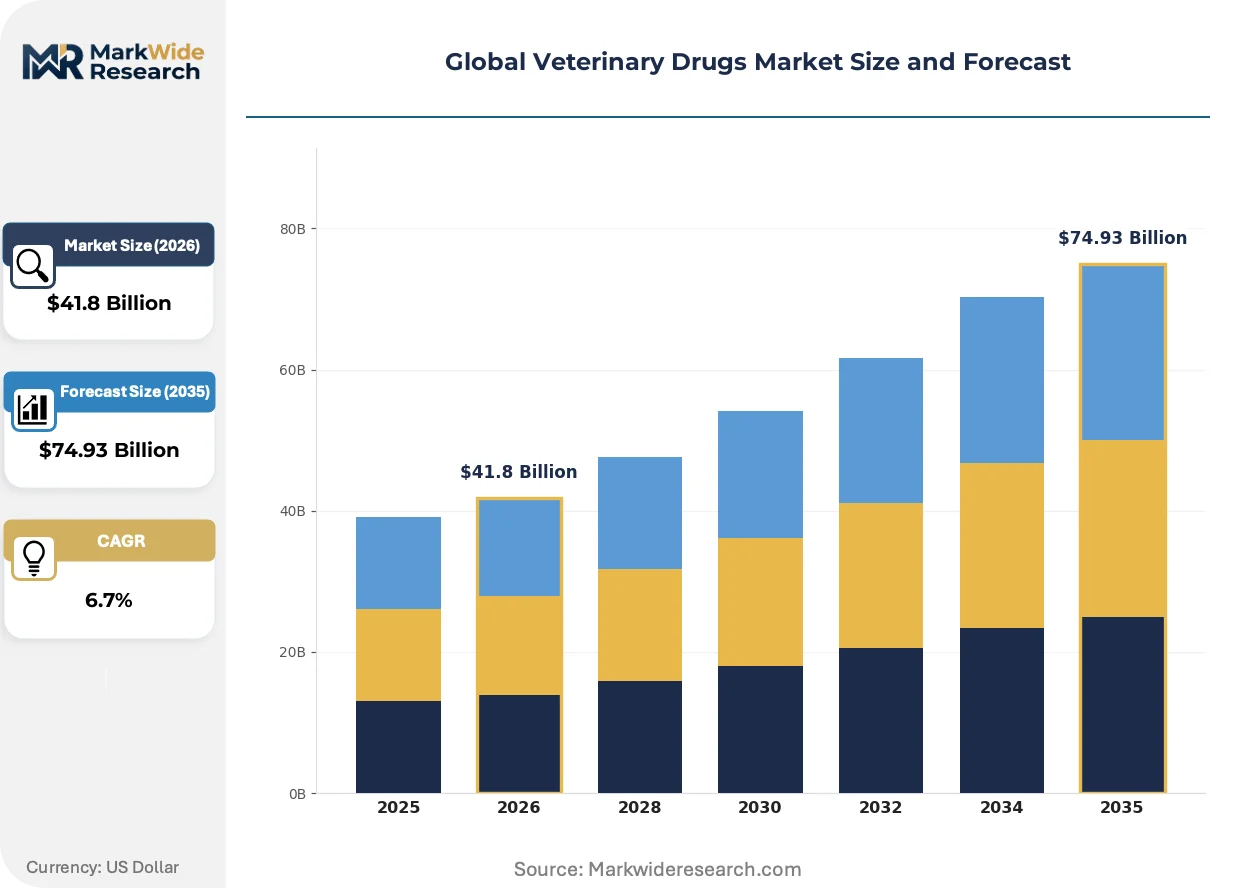
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $74.93 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiparasitics, Vaccines, Hormones, Nutritional Supplements Therapy Area: Infectious Diseases, Reproductive Health, Metabolic Disorders, Skin Conditions, Respiratory Disorders End User: Veterinary Clinics, Animal Pharmacies, Research Institutions, Livestock Farms, Companion Animal Facilities Distribution Channel: Direct Sales, Online Pharmacies, Veterinary Distributors, Retail Pharmacies, Institutional Procurement |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim GmbH, Merck & Co. Inc., Elanco Animal Health, Ceva Santé Animale, Virbac, Dechra Pharmaceuticals PLC, Phibro Animal Health Corporation, Vetoquinol S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Drugs Market Shifts & Advancements
Biotechnology advances and regulatory pressure are converging to transform product portfolios from commodity therapeutics toward differentiated preventive platforms with embedded monitoring capabilities.
mRNA vaccine platforms adapted from human medicine are rendering obsolete conventional inactivated viral preparations for respiratory pathogens in swine and poultry operations. Large integrated protein producers in the United States and Brazil are piloting these modalities for rapid strain-matched protection. The technology is compressing development timelines from years to months while eliminating egg-based production bottlenecks.
REACH authorization requirements for veterinary pharmaceutical manufacturing are forcing reformulation of solvent-based parasiticide pour-ons across European markets. The regulation is driving investment in water-soluble delivery systems and biodegradable excipient research. Cattle ectoparasiticide segments in Germany and France are experiencing accelerated product substitution as legacy registrations expire.
Direct purchasing agreements between livestock conglomerates and API manufacturers are disintermediating traditional distributor networks for antiparasitic bulk orders. Southern Brazil's feedlot operators now negotiate annual volume contracts with fermentation facilities, bypassing wholesale veterinary supply channels. This pattern is compressing margin structures for regional distributors while rewarding manufacturers with captive supply integration.
Global Veterinary Drugs Market Segmentation
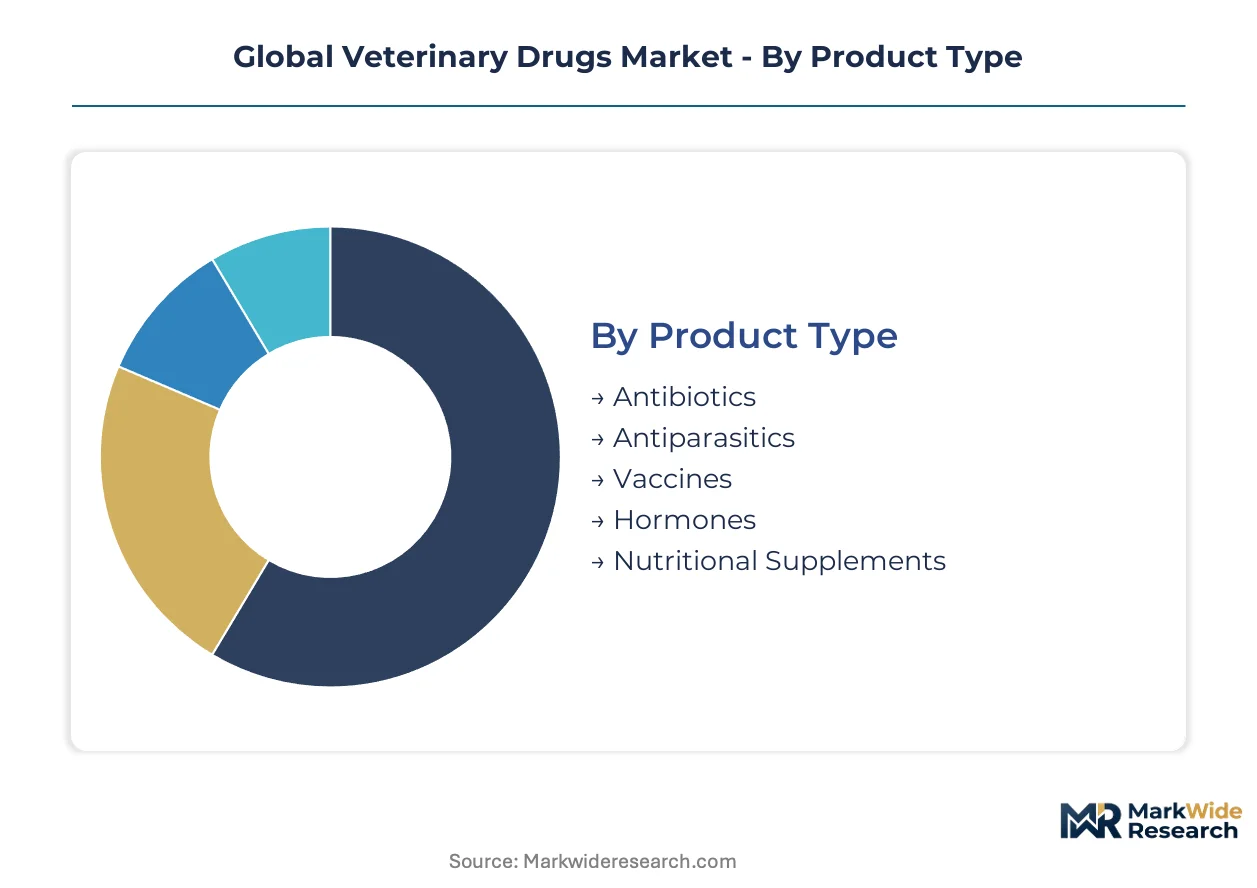
Veterinary drugs fragment across four distinct taxonomies that govern procurement patterns and margin structures. Product type determines manufacturing complexity and regulatory pathway intensity. Therapy area and end-user configurations shape pricing power and customer retention economics.
Product Type:
Mature fermentation-derived antibiotics anchor volume throughput while recombinant biologics emerge as the margin-expansion frontier.
- Antibiotics:Small-molecule bactericidal and bacteriostatic agents synthesized through fermentation or chemical modification. Demand concentrates in Brazil's cattle-producing states where liver fluke co-infections necessitate broad-spectrum prophylaxis; FDA Center for Veterinary Medicine restrictions on growth-promoting indications are eliminating feed-grade revenue streams.
- Antiparasitics:Macrocyclic lactones, benzimidazoles, and ectoparasiticide formulations targeting endo- and ectoparasite burdens. Southern China's intensive pork operations drive procurement for acaricide-integrated protocols following regional disease outbreaks; recurring prophylactic dosing cycles sustain premium margin pools.
- Vaccines:Inactivated, attenuated, and recombinant antigen preparations stimulating adaptive immunity. mRNA platform advances are compressing strain-matched development timelines for swine and poultry respiratory pathogens.
- Hormones:Steroidal and protein-based regulators of reproductive cycles and growth rates. Regulatory bans in EU jurisdictions restrict deployment to therapeutic indications only.
- Nutritional Supplements:Species-specific bioavailability formulations addressing micronutrient deficiencies in aging companion animal populations. North American veterinary clinics command premium positioning for geriatric pet formulations.
Antibiotics handles the majority of throughput; vaccines is the fastest mover on share.
Therapy Area:
Cost tier stratification separates commodity infectious disease management from high-value metabolic and reproductive interventions.
- Infectious Diseases:Antimicrobial and antiviral protocols targeting bacterial, viral, and fungal pathogens. Livestock farms in Germany and France prioritize respiratory and enteric infection control under tightened EU Veterinary Medicines Regulation residue protocols.
- Reproductive Health:Hormonal synchronization, fertility enhancement, and obstetric therapeutics. Large-scale dairy operations in the Netherlands and Denmark drive demand for timed artificial insemination programs.
- Metabolic Disorders:Transition period calcium regulators, ketosis preventatives, and rumen acidosis correctors. Intensive feedlot systems in Texas and Nebraska require continuous metabolic monitoring.
- Skin Conditions:Dermatological antibiotics, antifungals, and anti-inflammatory preparations. Companion animal facilities in urban Japan and South Korea generate premium pricing for atopic dermatitis biologics.
- Respiratory Disorders:Bronchodilators, mucolytics, and anti-inflammatory agents for bovine and equine populations. Seasonal patterns in Argentina's Pampas region concentrate procurement timing.
Infectious diseases commands the largest addressable base; reproductive health is climbing the fastest as herd genetic improvement intensifies.
End User:
Customer type fragmentation creates distinct purchasing behaviors ranging from spot procurement to integrated health system contracts.
- Veterinary Clinics:Primary care and specialty referral facilities delivering diagnostic and therapeutic services. Companion animal facilities in metropolitan Australia and Canada drive premium pricing for nutritional supplements with species-specific bioavailability profiles.
- Animal Pharmacies:Dispensing operations providing prescription fulfillment and over-the-counter therapeutics. Brazil's state-level pharmacy networks are consolidating procurement volume for antiparasitic bulk orders.
- Research Institutions:Academic and contract research organizations conducting preclinical and field efficacy studies. Veterinary biostatistics expertise shortages concentrate trial design capabilities in limited US and European academic centers.
- Livestock Farms:Commercial cattle, swine, and poultry operations managing herd health at scale. Direct purchasing agreements with API manufacturers in southern Brazil are disintermediating traditional distributor networks.
- Companion Animal Facilities:Boarding, grooming, and wellness centers extending pharmaceutical distribution reach. Aging pet demographics in Italy and Spain are expanding geriatric care service bundles.
Livestock farms generate the dominant procurement volume; companion animal facilities is expanding most quickly on margin contribution.
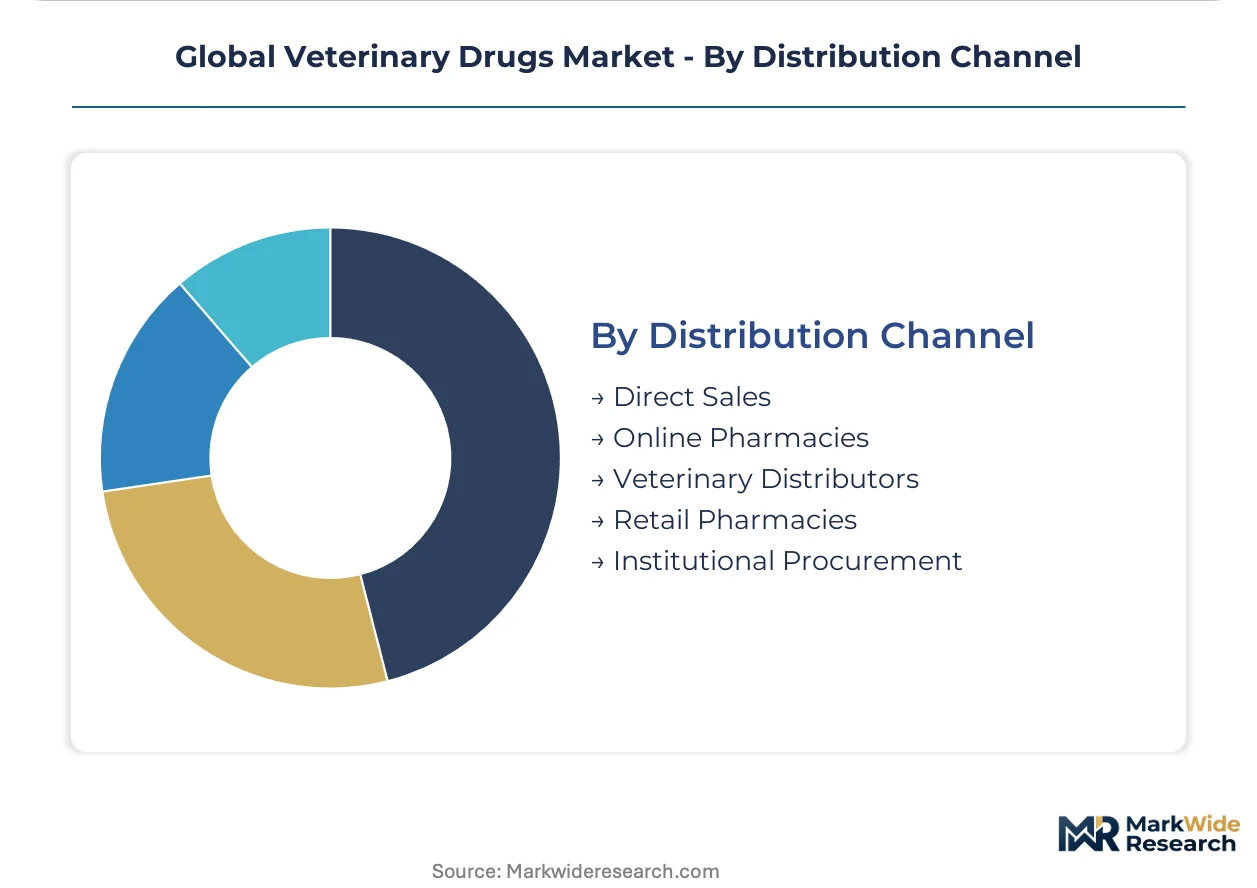
Distribution Channel:
Supply concentration in China's API manufacturing corridor is forcing channel restructuring toward direct manufacturer-procurement relationships.
- Direct Sales:Manufacturer-to-end-user contracts bypassing intermediary markups. Large integrated protein producers in the United States negotiate annual volume agreements for vaccine bulk orders.
- Online Pharmacies:Digital platforms enabling prescription verification and home delivery. Regulatory divergence between EMA veterinary medicines committee and China's NMPA creates compliance complexity for cross-border fulfillment.
- Veterinary Distributors:Regional and national wholesalers maintaining cold-chain logistics networks. Margin compression from direct sales growth is forcing consolidation among mid-tier distributors.
- Retail Pharmacies:Human pharmacy chains with veterinary product extensions. Limited formulary depth restricts penetration beyond companion animal OTC segments.
- Institutional Procurement:Centralized purchasing for research universities and government veterinary services. Tender-based pricing eliminates premium positioning for differentiated formulations.
Veterinary distributors still handles the majority of throughput; direct sales is gaining share fastest as livestock conglomerates consolidate purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing corridor for active pharmaceutical ingredients dominates upstream supply for veterinary formulations worldwide. Brazil's cattle-producing states and southern China's intensive pork operations anchor downstream demand concentration. Regulatory divergence between the FDA, EMA, and China's NMPA is fragmenting approval pathways across major jurisdictions.
United States
Large integrated protein producers in Texas and Nebraska drive pharmaceutical procurement for feedlot metabolic management. The FDA's Center for Veterinary Medicine enforces strict approval pathways for new animal drug applications while restricting growth-promoting antibiotic indications. Midwestern dairy operations in Wisconsin and Minnesota prioritize reproductive health therapeutics for herd genetic improvement programs.
Germany
REACH authorization requirements are forcing reformulation of solvent-based parasiticide pour-ons across cattle ectoparasiticide segments. The EMA's veterinary medicines committee harmonizes safety standards while tightening residue limits for livestock operations. Bavarian and Lower Saxony feedlot systems are accelerating adoption of preventive vaccine protocols under regulatory pressure.
Brazil
Southern feedlot operators in Rio Grande do Sul and Paraná negotiate direct purchasing agreements with API manufacturers, bypassing traditional distributor networks. ANVISA coordinates oversight of veterinary drug production licenses alongside residue monitoring programs. São Paulo state's expanding livestock farms are consolidating procurement volume for antiparasitic bulk orders.
China
Southern pork operations in Guangdong and Fujian provinces are expanding vaccine procurement budgets for herd immunity protocols following disease outbreaks. The NMPA and Ministry of Agriculture and Rural Affairs coordinate dual oversight of manufacturing licenses and residue monitoring. Yangtze River Delta fermentation facilities control critical capacity for global veterinary API supply.
Netherlands
Large-scale dairy operations drive demand for timed artificial insemination programs and reproductive health therapeutics. EU Veterinary Medicines Regulation protocols are eliminating historical revenue streams in feed-grade antibiotic segments. Randstad region veterinary clinics command premium positioning for companion animal nutritional supplements with species-specific bioavailability profiles.
Global Veterinary Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and antigen production. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with biologics platforms, mid-cap regional formulators with distribution depth, and API manufacturers with captive fermentation capacity. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships for mRNA platform licensing.
Among US-based pharmaceutical conglomerates, Zoetis Inc. and Merck & Co. Inc. occupy positions as platform integrators with multi-species vaccine portfolios. Boehringer Ingelheim GmbH represents the German GmbH-structured archetype with deep R&D positioning in antiparasitic pipelines. These three entities exemplify the competitive structure where geographic origin and corporate form signal strategic orientation toward biologics investment, precision delivery systems, or integrated health monitoring bundling.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim GmbH |
| Merck & Co. Inc. |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals PLC |
| Phibro Animal Health Corporation |
| Vetoquinol S.A. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors impose cost premiums on temperature-controlled shipments of fermentation-derived APIs, compressing margins for European formulators while amplifying price differentiation between captive-integrated manufacturers and spot-market buyers. This logistics chokepoint concentrates pricing power among Yangtze-based fermentation facilities serving Brazil's feedlot operators and southern China's pork conglomerates.
Pricing Analysis
EU Veterinary Medicines Regulation dictates the pricing tier structure across European livestock operations, with REACH-compliant solvent-free parasiticide formulations commanding premium positioning against legacy pour-on registrations. Price differentiation centers on residue certification tiers and cold-chain delivery guarantees, with Brazilian cattle producers showing highest sensitivity to unit economics while North American companion animal clinics absorb premium markups for species-specific bioavailability supplements. Cost compression in feed-grade antibiotic segments is intensifying as FDA growth-promotion restrictions eliminate historical revenue streams.
Supply Chain Analysis
Export-control scrutiny on recombinant protein production technology limits flow of mRNA platform equipment to non-integrated formulators, reinforcing concentration in China's Yangtze River Delta fermentation corridor. Active pharmaceutical ingredient supply draws from China, India, and select European fermentation facilities, with bovine serum-dependent cell culture media and specialized antigen substrates anchoring raw material dependencies. Single-source vulnerability concentrates in China's API manufacturing corridor, where distribution runs through direct manufacturer-to-livestock conglomerate contracts disintermediating traditional veterinary distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global veterinary drugs sit in early-cycle expansion as preventive vaccine protocols displace reactive antimicrobial frameworks across intensive livestock operations worldwide.
For Market Incumbents: Pre-empt mRNA platform commoditization by locking exclusive strain-matched development partnerships with Brazil's largest integrated protein producers. Backward integration into captive bovine serum sourcing hedges against protein input cost volatility threatening vaccine manufacturing economics.
For New Entrants and Emerging Players: Pursue white-space positioning in companion animal digital therapeutics convergence, where wearable diagnostic integration with pharmacological agents remains underdeveloped outside North American metropolitan clinics. Target southern China's intensive pork operations with rapid-response mRNA vaccine services following regional disease outbreak patterns.
For Investors and Strategic Acquirers: Regional formulators with ANVISA-licensed manufacturing in Brazil's Rio Grande do Sul corridor offer acquisition exposure to direct-purchasing agreement growth bypassing distributor networks. Watch for inflection in FDA Center for Veterinary Medicine novel biologic approval velocity as signal for platform-technology valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| mRNA Platform Licensing | Compresses strain-matched vaccine development timelines from years to months for swine respiratory pathogens. |
| Backward Integration into Fermentation | Captures margin pools in China's API manufacturing corridor while securing supply continuity for European formulators. |
| REACH-Compliant Reformulation | Preserves market access in Germany and France as legacy solvent-based parasiticide registrations expire. |
| Direct Purchasing Agreements | Disintermediates distributor networks for southern Brazil feedlot operators negotiating annual antiparasitic volume contracts. |
| Digital Therapeutics Integration | Creates subscription-based preventive health models bundling pharmacological agents with wearable diagnostics in North American clinics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across veterinary pharmaceutical manufacturing, livestock farm management, and companion animal clinic operations. Primary interviews captured perspectives from fermentation facility technical directors, regulatory affairs leads at multi-species vaccine producers, feedlot procurement managers in Brazil's cattle-producing states, and veterinary clinic formulary directors in North American metropolitan markets. Secondary validation drew from FDA Center for Veterinary Medicine filings, EMA veterinary medicines committee submissions, ANVISA production license databases, and customs records tracking API trade flows. Bottom-up volume estimates triangulated against top-down market sizing across product type, therapy area, and end-user configurations.
Calibration anchored historical shipment data to disclosed manufacturing capacity and procurement budget trajectories across the projection horizon. Segmentation modeling spanned product type, therapy area, end-user category, and regional regulatory cluster dimensions. CAGRs derived from slope analysis of adoption curves for preventive vaccine protocols and antimicrobial stewardship compliance trajectories, with inputs including livestock herd expansion rates in Brazil and China, companion animal demographic aging patterns in developed markets, and mRNA platform technology transfer velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by API manufacturers toward forward integration into finished dose formulation would shift outcomes from baseline projections. Material shifts in EU Veterinary Medicines Regulation residue limit enforcement stringency or FDA novel biologic approval pathway modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Mastitis Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Bovine Mastitis Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Scales Market
Veterinary
Clonorchiasis Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Veterinary Ultrasound Market