
 Asia-Pacific Veterinary Vaccine Market | 2026-2036
Asia-Pacific Veterinary Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Veterinary Vaccine Market Outlook
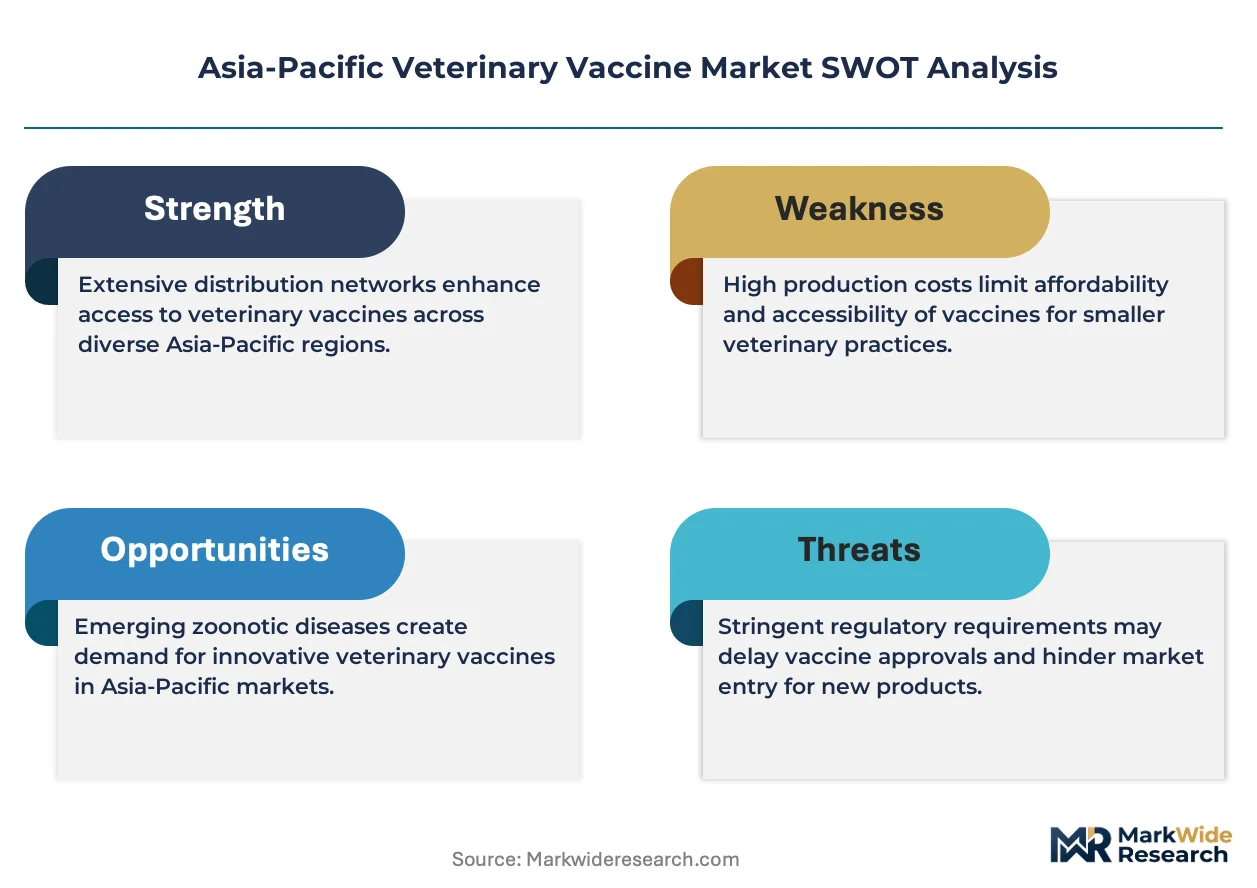
Preventive health subscription models for commercial livestock operations is hardening as a core revenue layer across the Asia-Pacific veterinary vaccine industry. Zoetis Inc. leverages its diagnostics-to-vaccine integrated platform to lock in recurring herd-health contracts with large-scale dairy and poultry producers. Hester Biosciences Ltd anchors its position through cost-competitive inactivated vaccines tailored to India's foot-and-mouth disease control programs. Ceva Santé Animale specializes in hatchery vaccination services, extending its technical reach into Southeast Asian broiler supply chains.
Veterinary vaccines are biologically active preparations containing attenuated, inactivated, or recombinant antigenic components designed to stimulate protective immunity in target animal species, with stability requirements typically spanning cold-chain maintenance between two and eight degrees Celsius. Their primary purpose is disease prevention in food-producing and companion animals, reducing antimicrobial dependence and securing protein supply chains. Attenuated vaccines occupy the largest value share due to durable cellular immunity and single-dose efficacy in ruminant applications, while DNA vaccines represent the fastest-expanding category as platforms for emerging avian influenza strains. Livestock farms command the dominant end-user volume, though veterinary clinics capture disproportionate margin pools through premium companion-animal protocols.
India's CDSCO mandates batch-release testing for all imported veterinary biologicals, creating compliance barriers that favor domestic manufacturers with in-house quality infrastructure. Australia's TGA enforces PIC/S-aligned GMP standards that shape export eligibility for regional suppliers targeting Oceania. China's NMPA and agricultural ministry jointly oversee veterinary vaccine licensing, with accelerated pathways for products addressing notifiable diseases like African swine fever. Stakeholders must monitor regulatory divergence on nucleic acid vaccine platforms, as approval timelines and field-trial requirements vary sharply across these three jurisdictions and will determine which product formats achieve scalable market access.
Market Dynamics
Preventive health subscription models are hardening as the dominant commercial structure across Asia-Pacific livestock operations, locking vaccine suppliers into multi-year herd-health contracts that bundle diagnostics, vaccination protocols, and field technical support.
Growth Catalysts
- CDSCO batch-release mandates:India's import testing requirements for veterinary biologicals accelerate domestic manufacturing capacity expansion as foreign suppliers face compliance delays.
- Integrated dairy cooperatives:Gujarat and Maharashtra's clustered dairy operations drive volume procurement of foot-and-mouth disease vaccines through collective purchasing agreements.
- Nucleic acid platforms:DNA vaccine technologies for emerging avian influenza strains attract accelerated regulatory review pathways and R&D investment across Southeast Asian hatcheries.
Market Restraints
- Cold-chain infrastructure gaps:Two-to-eight-degree Celsius stability requirements strain last-mile distribution networks in Indonesia's archipelago and India's rural hinterlands.
- TGA GMP alignment costs:Australia's PIC/S-equivalent standards impose capital-intensive facility upgrades on regional suppliers seeking Oceania export eligibility.
- Antigen production concentration:Bulk biologicals manufacturing clusters in select Indian and Chinese contract facilities, creating single-source vulnerability for downstream formulation.
Strategic Opportunities
- Vietnam's livestock modernization:Industrial broiler and swine operations in the Mekong Delta remain undersupplied with hatchery vaccination services relative to production scale.
- NMPA accelerated pathways:China's joint agricultural-ministry review process for African swine fever vaccines compresses time-to-market for notifiable disease products.
- Diagnostics-vaccine integration:Serological monitoring platforms bundled with preventive protocols enable outcome-based pricing models for large-scale cattle and poultry producers.
Industry Challenges
- Veterinary immunology specialization:Shortage of trained field vaccinators and cold-chain technicians constrains rollout of complex multi-dose regimens in remote Australian stations and Indonesian smallholdings.
- Regulatory divergence on novel platforms:Inconsistent field-trial requirements and approval timelines for mRNA and viral-vector vaccines across CDSCO, TGA, and NMPA jurisdictions fragment development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Veterinary Vaccine Market |
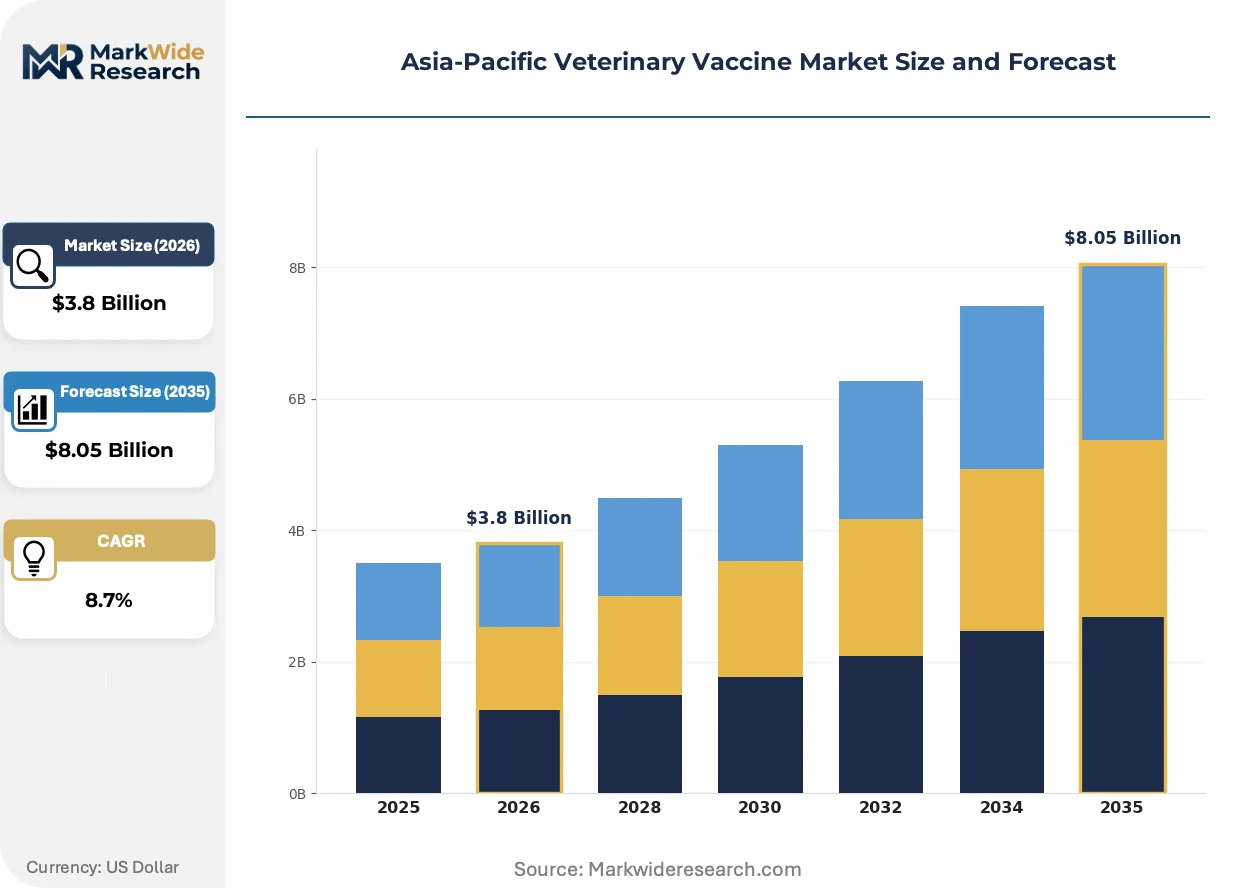
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Attenuated Vaccines, Subunit Vaccines, DNA Vaccines End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Livestock Farms Animal Type: Dogs, Cats, Livestock, Poultry Distribution Channel: Direct Sales, Distributors, Retail Pharmacies, Online Sales |
| Companies Covered | Boehringer Ingelheim International GmbH, Zoetis Inc., Merck & Co. Inc., Virbac SA, Elanco, Ceva Santé Animale, Hester Biosciences Ltd, HIPRA, Phibro Animal Health Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Veterinary Vaccine Market Strategic Shifts
Platform technologies and service-model reinvention are compressing traditional vaccine development cycles while rewiring how livestock producers procure preventive health. Three forces merit close tracking.
Recombinant vector platforms are consolidating technical leadership in avian influenza response across Southeast Asian broiler supply chains. These engineered viral backbones express protective antigens without live-pathogen handling risks. Major integrated poultry operations in Thailand and Vietnam are transitioning flock vaccination schedules toward these formats. The technology is consolidating market share previously fragmented across inactivated whole-virus alternatives by reducing required doses and simplifying hatchery logistics.
TGA's PIC/S-aligned GMP enforcement is reshaping export eligibility criteria for regional manufacturers. The standard requires documented process analytical technology and continuous manufacturing verification. Indian and Chinese suppliers targeting Australian and New Zealand markets must retrofit legacy batch-release systems. Small-to-mid-scale biologicals producers face disproportionate compliance burdens relative to integrated multinationals with captive quality infrastructure.
Subscription-based herd health contracts are displacing transactional vaccine purchasing among large-scale dairy and poultry operations. These agreements bundle diagnostics, scheduled vaccination, and technical field support into annual per-animal fees. Australian feedlot operators and Indian dairy cooperatives pioneered the model. The shift is most visible in Maharashtra's cooperative network, where preventive health spending now flows through consolidated procurement committees rather than individual farm-level transactions.
Asia-Pacific Veterinary Vaccine Market Segmentation
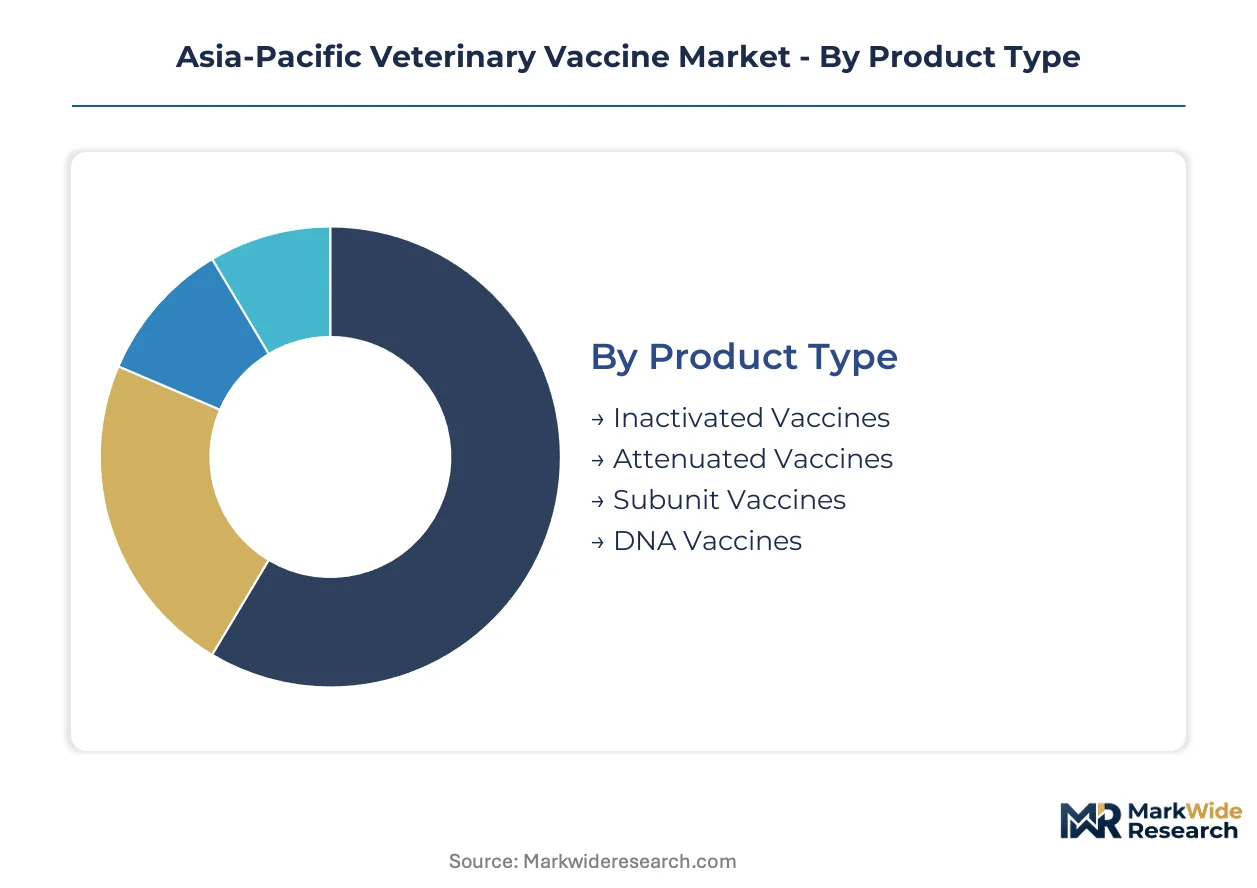
Veterinary vaccine procurement patterns diverge sharply across product formats, end-user settings, and animal categories. Understanding these segment boundaries clarifies where formulation complexity, cold-chain intensity, and regulatory compliance burdens concentrate.
Product Type:
Immunological platform selection determines manufacturing infrastructure requirements, stability profiles, and approval pathway complexity across Asia-Pacific regulatory jurisdictions.
- Inactivated Vaccines:Chemically or heat-killed pathogen preparations requiring adjuvant enhancement and multi-dose regimens. Gujarat's integrated dairy cooperatives procure these in bulk for foot-and-mouth disease control programs, with CDSCO batch-release testing adding compliance lead time for imported formulations.
- Attenuated Vaccines:Live-weakened pathogen strains delivering durable cellular immunity and single-dose efficacy in ruminant applications. Australia's extensive cattle stations favor these for remote mustering logistics where revaccination access is limited.
- Subunit Vaccines:Purified antigen preparations excluding live pathogen components. Thailand's broiler hatcheries integrate these into automated in-ovo injection systems.
- DNA Vaccines:Plasmid-based platforms encoding protective antigens for emerging avian influenza strains. Southeast Asian poultry operations are piloting these for accelerated strain-matched response.
Attenuated vaccines lead on scale; DNA vaccines lead on momentum.
End User:
Procurement authority and technical sophistication vary dramatically across institutional settings, rewiring how suppliers structure service relationships and pricing architectures.
- Livestock Farms:Commercial cattle feedlots, dairy cooperatives, and broiler operations purchasing vaccines through collective procurement committees. Maharashtra's cooperative network bundles diagnostics, scheduled vaccination, and field technical support into annual per-animal fees.
- Veterinary Clinics:Companion animal practices capturing disproportionate margin pools through premium protocols for dogs and cats. Urban centers in Australia's capital cities concentrate this demand.
- Animal Hospitals:Referral institutions handling complex multi-dose regimens and adverse event management. These facilities anchor cold-chain integrity in Vietnam's Mekong Delta livestock corridor.
- Research Institutes:Academic and government facilities conducting field trials for novel platform approvals. CDSCO, TGA, and NMPA divergence on nucleic acid vaccine requirements shapes their study portfolios.
Livestock farms dominate procurement volume; veterinary clinics dominate margin extraction.
Animal Type:
Disease risk profiles and production economics create distinct vaccine specification requirements across companion and food-producing species.
- Poultry:Broiler and layer operations requiring hatchery vaccination services and in-ovo delivery systems. Vietnam's industrial operations in the Mekong Delta remain undersupplied relative to production scale.
- Livestock:Cattle and swine herds driving demand for foot-and-mouth disease and African swine fever vaccines. China's NMPA accelerated pathways compress time-to-market for notifiable disease products in this segment.
- Dogs:Companion animal protocols emphasizing rabies and combination core vaccines. Urban veterinary clinics in Indian metropolitan areas concentrate this demand.
- Cats:Feline-specific formulations with smaller dose volumes and differentiated adjuvant systems. Premium positioning in Australian companion animal practices supports price realization.
Poultry commands the steepest volume trajectory; livestock anchors regulatory prioritization.
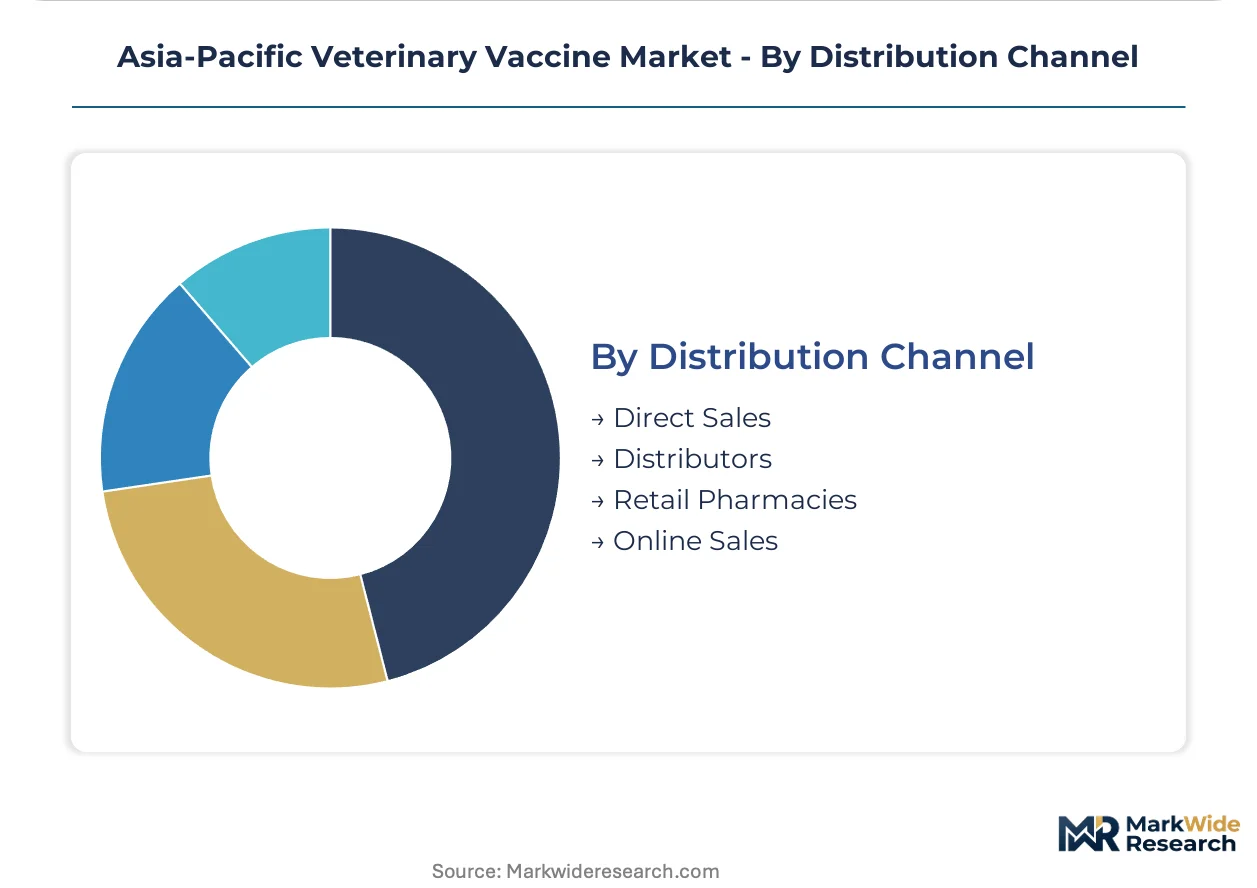
Distribution Channel:
Channel selection reflects cold-chain capability, transaction scale, and technical support requirements across diverse geographic and operational contexts.
- Direct Sales:Manufacturer-to-producer relationships for large-scale dairy cooperatives and integrated poultry operations. Zoetis and Ceva Santé Animale deploy field technical teams to support these accounts.
- Distributors:Regional wholesalers bridging last-mile gaps in Indonesia's archipelago and India's rural hinterlands. Cold-chain infrastructure strain concentrates risk in this channel.
- Retail Pharmacies:Point-of-sale access for companion animal owners and smallholder livestock producers. Urban concentration limits rural penetration.
- Online Sales:Emerging platform for standardized vaccine orders with documented cold-chain tracking. Regulatory verification of storage conditions remains inconsistent across Asia-Pacific jurisdictions.
Direct sales captures the largest accounts; online channels are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions where batch-release testing and GMP compliance costs diverge sharply. India's CDSCO mandates create protective moats for domestic formulators, while Australia's TGA alignment with PIC/S standards filters export eligibility. Production capacity is concentrating where these compliance gaps intersect with clustered livestock demand.
India
Gujarat and Maharashtra's integrated dairy cooperatives drive bulk procurement of foot-and-mouth disease vaccines through collective purchasing committees. CDSCO batch-release testing requirements for imported veterinary biologicals impose compliance delays that favor domestic manufacturers with captive quality infrastructure. Hester Biosciences anchors production in Ahmedabad with cost-competitive inactivated vaccine capacity serving government control programs.
China
Industrial swine operations in Sichuan and Henan provinces sustain demand for African swine fever vaccines under NMPA accelerated approval pathways. The joint agricultural ministry review process compresses time-to-market for notifiable disease products. Pearl River Delta biologicals manufacturing clusters supply downstream formulation across Southeast Asian markets.
Australia
Extensive cattle stations in Queensland and Western Australia favor attenuated vaccines for remote mustering logistics where revaccination access is limited. TGA enforces PIC/S-aligned GMP standards that shape export eligibility for regional suppliers targeting Oceania. Melbourne and Sydney veterinary clinics capture premium companion-animal margin pools through rabies and core combination protocols.
Vietnam
Industrial broiler and swine operations in the Mekong Delta remain undersupplied with hatchery vaccination services relative to production scale. Ceva Santé Animale extends technical reach into Vietnamese supply chains through automated in-ovo delivery systems. Ho Chi Minh City anchors cold-chain distribution for southern livestock corridors.
Thailand
Integrated poultry operations in the Central Plains region transition flock vaccination schedules toward recombinant vector platforms for avian influenza response. Subunit vaccine formats integrate into automated hatchery systems serving Bangkok-centered processing networks. Domestic formulators face pressure from Chinese and Indian contract suppliers on cost-competitive inactivated alternatives.
Asia-Pacific Veterinary Vaccine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding subscription-based herd-health contracts and domestic formulators capturing government tender volumes. The vendor base concentrates around three strategic archetypes: diagnostics-to-vaccine integrated platforms, cost-optimized regional manufacturers, and hatchery service specialists. Competitive moves center on backward integration into bulk antigen production and geographic licensing partnerships to bypass regulatory bottlenecks.
Within the integrated platform tier, Zoetis Inc. and Merck & Co. Inc. exemplify multinational structures bundling diagnostics, scheduled vaccination, and field technical support into recurring revenue contracts with large-scale producers. Boehringer Ingelheim International GmbH occupies a position among German-based pharmaceutical conglomerates with veterinary biologicals divisions. Ceva Santé Animale represents the hatchery service specialist archetype, while Hester Biosciences Ltd anchors the domestic cost-competitive tier within Indian limited company structures.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Zoetis Inc. |
| Merck & Co. Inc. |
| Virbac SA |
| Elanco |
| Ceva Santé Animale |
| Hester Biosciences Ltd |
| HIPRA |
| Phibro Animal Health Corp. |
| Others |
Value Chain & Pricing Dynamics
Subscription-based herd health contracts across Maharashtra's dairy cooperatives and Australian feedlot operations are compressing transactional pricing flexibility, forcing suppliers to absorb cold-chain logistics costs into bundled per-animal fees while extracting margin through diagnostics integration.
Pricing Analysis
Distributor margins spanning Indonesia's archipelago and India's rural hinterlands absorb the steepest cost layers, with cold-chain handling fees adding disproportionate markup to last-mile delivery. Pricing stratifies across premium recombinant vector platforms, standard inactivated formulations, and economy-tier government tender supplies. Cost compression in standard-tier vaccines is intensifying as Indian and Chinese contract manufacturers expand bulk antigen capacity. Government procurement committees in Gujarat and Maharashtra exhibit highest price sensitivity, while Australian companion animal clinics show lowest sensitivity to premium positioning.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City, Mumbai, and Bangkok anchor hub-and-spoke patterns radiating into Mekong Delta broiler operations and Maharashtra dairy corridors. Bulk biologicals manufacturing draws from Pearl River Delta clusters, Ahmedabad formulation facilities, and Sichuan swine vaccine plants. Single-source vulnerability concentrates in attenuated strain production for Australia's remote cattle stations. Distribution runs through direct sales for integrated multinationals, distributor networks for fragmented smallholdings, and emerging online channels with inconsistent cold-chain verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Poultry operations across Thailand and Vietnam are shifting flock vaccination schedules toward recombinant vector platforms with superior strain-matched response and simplified hatchery logistics.
For Market Incumbents: Deploy diagnostics-to-vaccine integration as the anchor lever for multi-year subscription renewals. Lock in backward integration into bulk antigen production to offset CDSCO batch-release delays threatening imported formulation margins. Counter emerging DNA vaccine specialists by accelerating regulatory dossier submissions across TGA, CDSCO, and NMPA jurisdictions simultaneously. For New Entrants and Emerging Players: NMPA accelerated pathways in China open a window for African swine fever vaccine developers to compress time-to-market against entrenched incumbents. Vietnam's Mekong Delta industrial broiler operations remain the most penetrable geography, with hatchery vaccination services running 30-40 percent below production scale requirements. Pursue automated in-ovo delivery system partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic Indian formulators possessing captive CDSCO-compliant quality infrastructure and government tender relationships. Five-to-ten year viability hinges on nucleic acid platform approval convergence across Asia-Pacific regulators. Watch for TGA PIC/S alignment enforcement triggering consolidation among sub-scale regional suppliers unable to fund facility retrofit costs.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostics-Vaccine Platform Integration | Zoetis and Merck bundle serological monitoring with preventive protocols to enable outcome-based pricing for Australian feedlots. |
| Regulatory Dossier Harmonization | Simultaneous CDSCO, TGA, and NMPA submissions compress approval timelines for recombinant vector platforms in Southeast Asian hatcheries. |
| Cold-Chain Infrastructure Partnership | Ceva Santé Animale extends automated in-ovo systems into Vietnam's Mekong Delta, anchoring technical service relationships. |
| Bulk Antigen Backward Integration | Hester Biosciences and Pearl River Delta manufacturers secure captive supply for foot-and-mouth disease and African swine fever formulations. |
| Subscription-Based Herd Health Contracts | Maharashtra's cooperative network consolidates procurement through annual per-animal fees bundling vaccination, diagnostics, and field support. |
Study Parameters
Direct dialogue with veterinary vaccine manufacturing executives, regulatory affairs specialists at CDSCO and TGA, dairy cooperative procurement committees, and hatchery operations managers across Thailand and Vietnam grounded qualitative findings. Secondary validation drew from CDSCO batch-release databases, TGA GMP inspection records, NMPA accelerated pathway announcements, and customs data on veterinary biologicals trade flows. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Bottom-up volume projections aggregated segment-level procurement patterns by product type, end-user setting, and animal category, while top-down validation cross-referenced regulatory filing trends and manufacturing capacity announcements. Segmentation dimensions spanned immunological platform, procurement authority, species-specific disease risk, and distribution channel cold-chain capability. CAGRs were derived from fitted growth curves incorporating livestock herd expansion rates, regulatory approval velocity, and substitution dynamics between attenuated and nucleic acid platforms. Industry-specific inputs included CDSCO batch-release queue lengths, TGA PIC/S audit schedules, and Mekong Delta hatchery automation penetration.
Revisions become necessary when regulatory divergence on mRNA and viral-vector vaccine field-trial requirements sharpens, when African swine fever strain mutations obsolete existing antigen formulations, or when cold-chain infrastructure investments in Indonesia's outer islands accelerate beyond modeled timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Canine Arthritis Market
Veterinary
CBD Pet Market
Veterinary
Companion Animal Drugs Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
USA Animal Model Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Milking Salve Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Australia Veterinary Healthcare Market