
 Global Type 1 Diabetes (T1D) Market | 2026-2036
Global Type 1 Diabetes (T1D) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Type 1 Diabetes (T1D) Market Intelligence
Revenue from standalone blood glucose meters is narrowing as integrated continuous glucose monitoring (CGM) systems capture greater value. Medtronic plc leverages its broad device portfolio to offer integrated solutions. Dexcom, Inc. specializes in CGM technology, competing on data accuracy and interoperability. Abbott Laboratories sustains market presence with its popular FreeStyle Libre system, extending its reach in both CGM and traditional monitoring segments.
The Type 1 Diabetes market encompasses therapies and devices for managing an autoimmune condition characterized by pancreatic beta-cell destruction and absolute insulin deficiency. Management requires lifelong exogenous insulin administration to maintain glycemic control, typically measured by HbA1c levels. Within product types, automated insulin delivery systems represent the fastest-growing category, displacing traditional meters. Demand from pediatric clinics and endocrinology centers for improved glycemic control therapies continues to shape product development priorities.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) govern device approval and post-market surveillance. ISO 15197 standards for blood-glucose monitoring systems further define product accuracy requirements for market access. The critical decision for device manufacturers now revolves around building open-platform ecosystems versus proprietary closed-loop systems for automated insulin delivery.
Market Dynamics
The central structural force shaping the Type 1 Diabetes market is the convergence of continuous glucose monitoring with automated insulin delivery. This integration creates intelligent, closed-loop systems that are fundamentally changing therapeutic goals from manual intervention to autonomous glycemic management.
Growth Catalysts
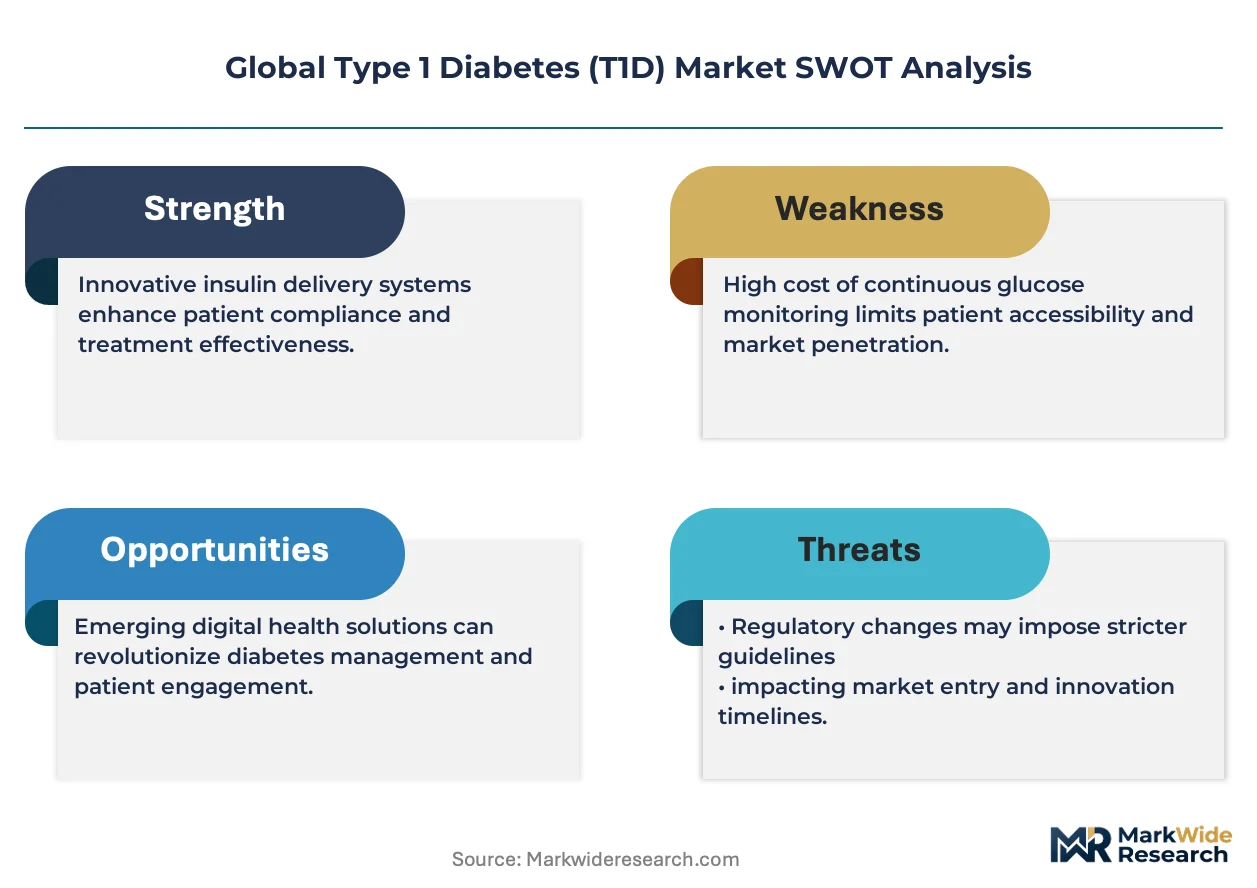
- Advanced Algorithms:The incorporation of predictive algorithms in automated insulin delivery systems improves time-in-range for patients, a key metric sought by endocrinology centers in the United States and Germany.
- Regulatory Pathways:Expedited device review programs from agencies like the US FDA and Japan's PMDA reduce the time-to-market for innovative closed-loop systems, encouraging investment in research and development.
- Pediatric End-Use Demand:Strong demand from pediatric clinics for therapies that lessen the daily management burden on children and their caregivers drives adoption of automated systems over traditional insulin injection regimens.
Market Restraints
- Reimbursement Barriers:Inconsistent reimbursement policies for CGM and insulin pump supplies across national healthcare systems, including some in Europe, limit patient access based on geography and socioeconomic status.
- Interoperability Limitations:The persistence of proprietary, closed-loop systems creates technical and data silos, restricting patient choice and preventing seamless integration of preferred devices from different manufacturers.
- Cybersecurity Vulnerabilities:The connectivity of diabetes devices introduces risks of data breaches and unauthorized device control, necessitating complex security measures that increase development costs under frameworks like HIPAA.
Strategic Opportunities
- Non-Invasive Monitoring:Significant opportunity exists in the research and development of non-invasive glucose monitoring technologies, such as those using optical or electromagnetic sensors, to eliminate the need for skin-penetrating devices.
- Emerging Market Penetration:Expansion into large, underserved patient populations in countries like Brazil and India offers substantial growth potential for manufacturers of both advanced and traditional diabetes management devices.
- Data Monetization Platforms:Developing secure platforms that aggregate anonymized patient data can create new revenue streams through partnerships with researchers, public health organizations, and pharmaceutical companies to improve population health insights.
Industry Challenges
- Specialized Talent Acquisition:A persistent challenge is the recruitment and retention of software developers and data scientists who possess a rare combination of expertise in medical device software, AI, and regulatory compliance.
- EHR System Integration:The operational complexity of ensuring seamless and secure data flow from patient devices into diverse and often outdated electronic health record (EHR) systems used by clinics remains a significant hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Type 1 Diabetes (T1D) Market |
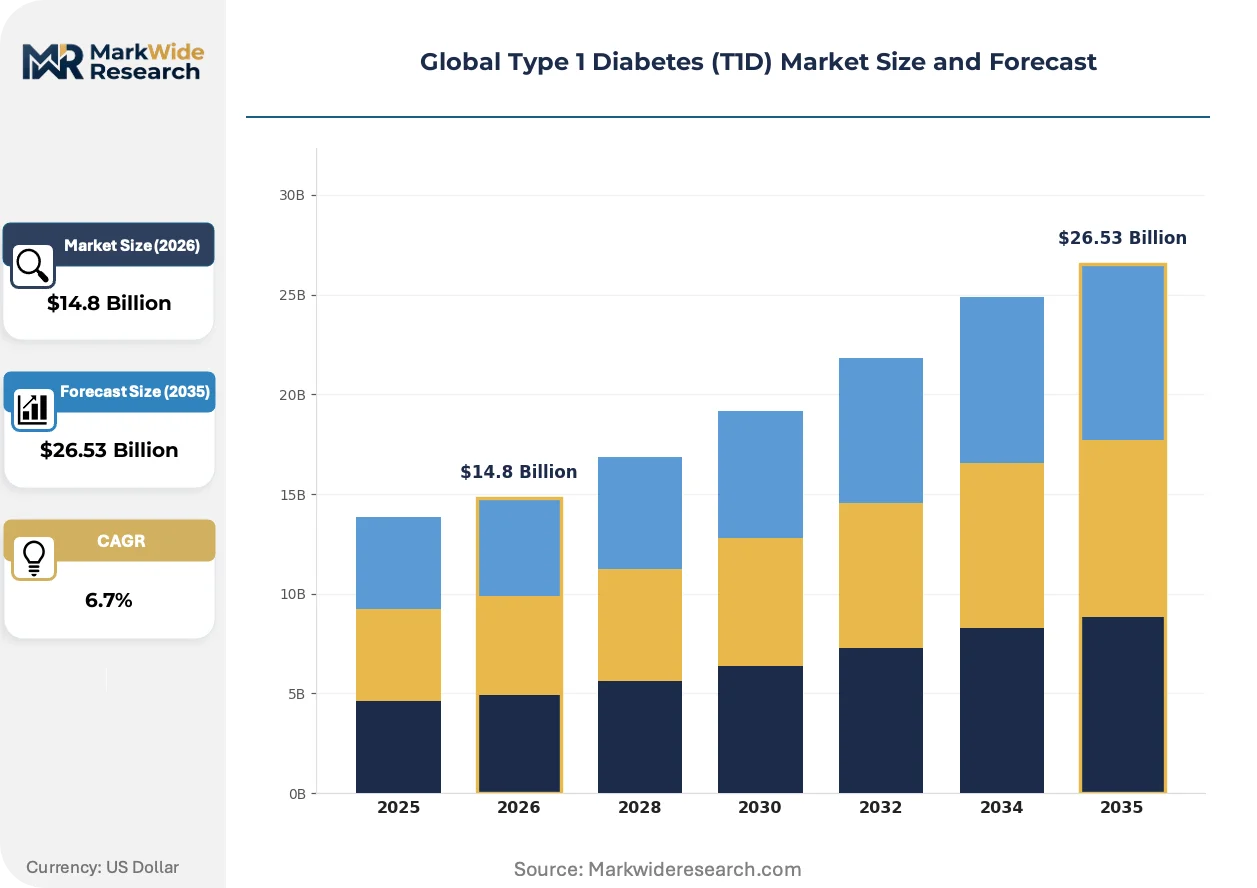
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Insulin Analogues, Blood Glucose Meters, Automated Insulin Delivery Therapy Area: Autoimmune Management, Beta Cell Regeneration, Glycemic Control, Hypoglycemia Prevention, Ketoacidosis Treatment End User: Pediatric Clinics, Endocrinology Centers, Diabetes Care Facilities, Community Health Centers, Research Institutions Distribution Channel: Pharmacies, Online Retailers, Hospitals, Homecare Providers, Specialty Clinics |
| Companies Covered | Abbott Laboratories, Tandem Diabetes Care, Inc., Eli Lilly and Company, AstraZeneca, Dexcom, Inc., Novo Nordisk A/S, Medtronic plc, Johnson & Johnson, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Type 1 Diabetes (T1D) Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift toward data-driven, personalized therapy. Innovations are focused on creating more autonomous and less intrusive systems that improve not just clinical outcomes but also the daily quality of life for individuals with T1D.
Technology Evolution
Smart insulin pens and connected CGM devices capture and transmit dosing and glucose data automatically. Patients and endocrinologists in developed healthcare systems like those in Canada and France are adopting these tools for more precise therapy adjustments. This technology is digitizing the manual logbook, creating a rich dataset that enables superior remote patient monitoring and evidence-based clinical decisions.
Regulatory Shift
The European Union's Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence and post-market surveillance. This regulation directly increases compliance costs and extends development timelines for all device manufacturers seeking a CE marking. Software as a Medical Device (SaMD), particularly the algorithms driving automated insulin delivery, faces the most intense scrutiny, demanding rigorous validation.
Demand-Side Shift
Patient preference is moving decisively toward devices that offer greater discretion and lifestyle compatibility, such as tubeless patch pumps and smaller CGM sensors. This behavioral change is eroding the market for larger, more conspicuous insulin pumps that can hinder physical activity. The trend is most pronounced among pediatric and young adult populations in the United States who value discretion and convenience.
Global Type 1 Diabetes (T1D) Market Segmentation
Understanding the Type 1 Diabetes market through segmentation reveals distinct value pools and growth trajectories. This granular breakdown helps stakeholders identify specific patient needs and technological advancements driving adoption. Manufacturers can tailor product development and market entry strategies by analyzing these discrete segments.
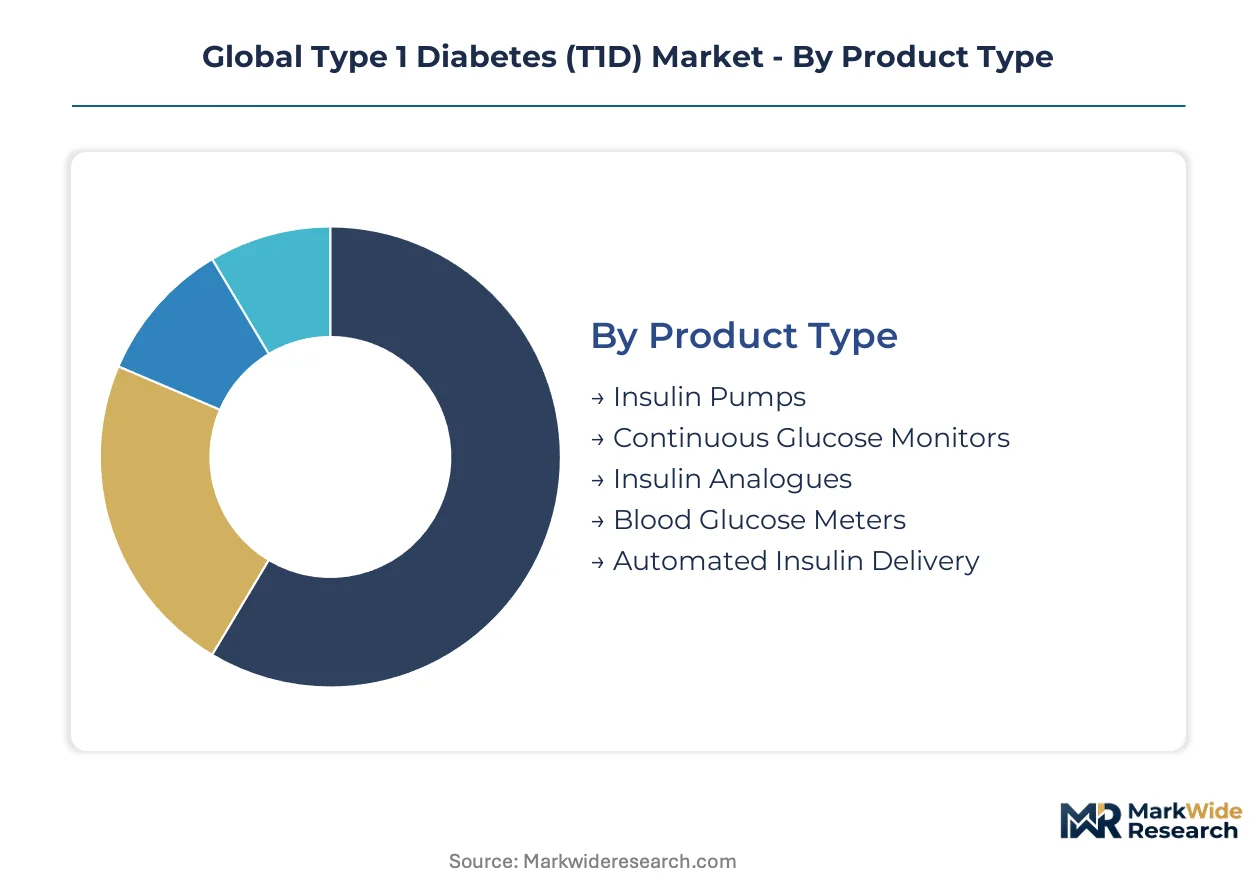
Product Type:
The product dimension highlights the diverse technologies available for managing Type 1 Diabetes, from traditional tools to advanced automated systems.
- Continuous Glucose Monitors:These devices offer real-time glucose readings, eliminating frequent fingersticks and improving glycemic trend analysis. Demand is concentrating in developed healthcare systems like the United States and Germany, driven by patient preference for non-invasive monitoring.
- Automated Insulin Delivery:These integrated systems combine CGM data with insulin pumps, using algorithms to automatically adjust insulin dosage. Their adoption is gaining share rapidly among pediatric populations in Canada, reducing the burden of daily diabetes management for children and caregivers.
- Insulin Pumps:These devices deliver continuous insulin through a cannula, providing more precise dosing than multiple daily injections.
- Insulin Analogues:These modified insulin formulations offer improved pharmacokinetic profiles, crucial for effective glycemic control.
- Blood Glucose Meters:Traditional handheld devices measure glucose levels from a drop of blood, serving as a baseline for many patients.
Blood Glucose Meters holds installed capacity. Automated Insulin Delivery is rotating up the share rankings.
Therapy Area:
The application of T1D therapies spans critical aspects of disease management, from immediate glycemic control to long-term prevention strategies.
- Glycemic Control:This area focuses on maintaining blood glucose levels within a target range to prevent acute and chronic complications. Demand is concentrated in endocrinology centers across Europe, driven by clinical guidelines emphasizing tight control.
- Hypoglycemia Prevention:Therapies in this segment aim to mitigate dangerous low blood sugar episodes, a significant concern for insulin-dependent patients. Advanced algorithms in automated systems are specifically targeting this risk, especially in countries with high rates of intensive insulin therapy.
- Autoimmune Management:This segment explores interventions to modulate the immune response causing beta-cell destruction in T1D.
- Beta Cell Regeneration:Research in this area seeks to restore insulin-producing cells, offering a potential cure for Type 1 Diabetes.
- Ketoacidosis Treatment:This segment addresses the acute complication of diabetic ketoacidosis, requiring emergency insulin and fluid management.
Glycemic Control remains the foundational therapeutic goal. Beta Cell Regeneration exhibits a steep expansion trajectory.
End User:
The customer type for Type 1 Diabetes management solutions varies across specialized medical facilities and community-based care settings.
- Pediatric Clinics:These specialized centers cater to children and adolescents with T1D, focusing on age-appropriate management and family education. Demand for user-friendly, discreet devices is particularly high among this demographic in the United States.
- Endocrinology Centers:These facilities provide comprehensive care for adults with T1D, offering advanced diagnostic and therapeutic interventions. These centers in France prioritize integrated systems for improved patient outcomes and data management.
- Diabetes Care Facilities:These broader centers offer general diabetes management, including education and support services for patients.
- Community Health Centers:These centers provide accessible primary care, often serving underserved populations with basic diabetes management tools.
- Research Institutions:These organizations conduct clinical trials and develop new therapies and devices for Type 1 Diabetes.
Endocrinology Centers drive significant technological adoption. Pediatric Clinics are increasingly influencing product design preferences.
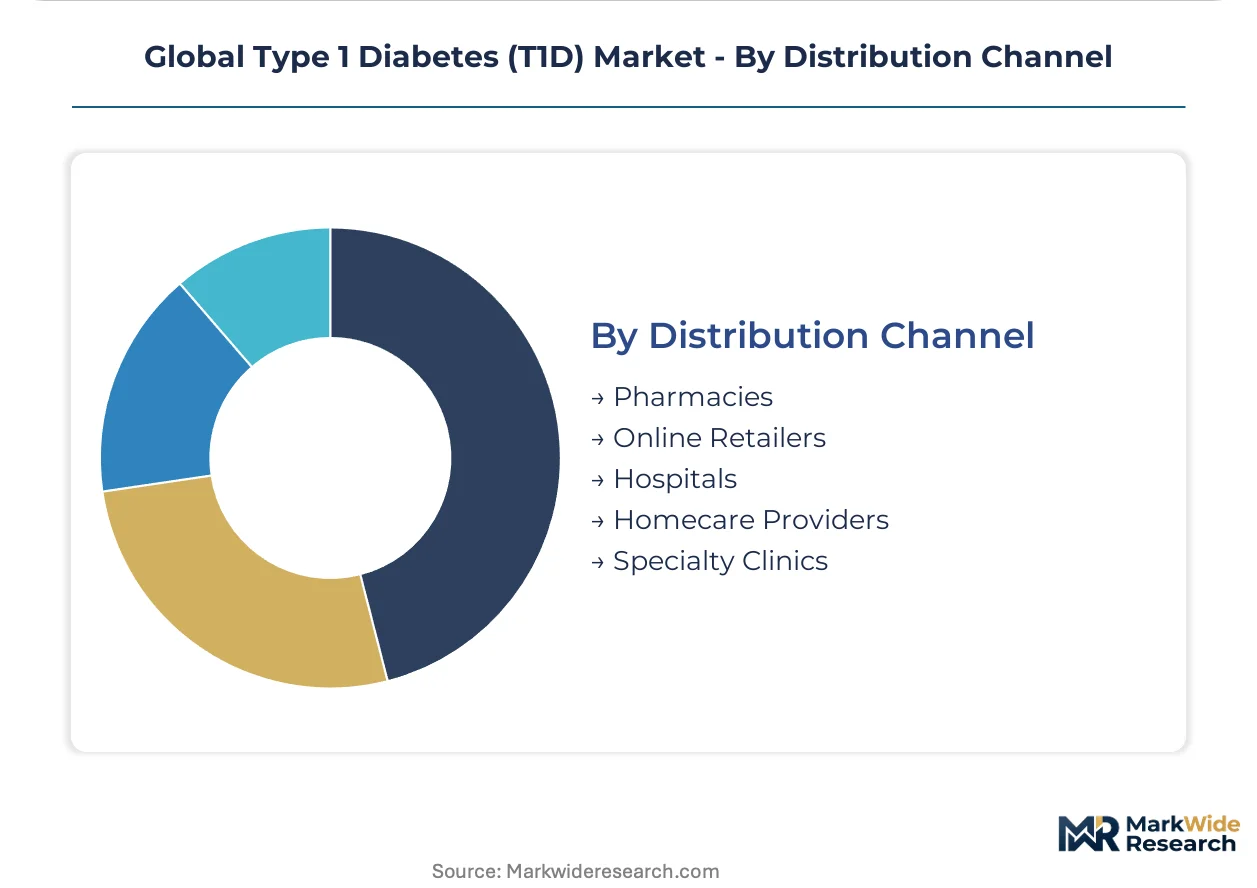
Distribution Channel:
The distribution channels for T1D products ensure patient access through both traditional retail and specialized healthcare networks.
- Pharmacies:These outlets serve as a primary point of access for insulin, syringes, and some monitoring supplies, offering convenience to patients. Their reach is extensive across countries like India and Brazil, providing essential medication access.
- Online Retailers:This channel provides a convenient and often cost-effective way to purchase diabetes supplies, including CGMs and pump accessories. The shift to e-commerce is pronounced in the United States, driven by consumer preference and broader product availability.
- Hospitals:Hospitals manage acute diabetes complications and initiate therapy for newly diagnosed patients, particularly for insulin pumps.
- Homecare Providers:These services deliver medical supplies and support to patients in their homes, enhancing convenience and adherence.
- Specialty Clinics:These clinics offer focused diabetes care and often dispense advanced devices directly to patients.
Pharmacies maintain broad geographic coverage. Online Retailers are climbing the fastest in terms of market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the global Type 1 Diabetes market. Patients in developed economies often prioritize advanced, integrated systems, exhibiting lower price sensitivity for innovative solutions. Conversely, emerging markets balance clinical efficacy with affordability, driving demand for cost-effective management tools.
United States
Demand for automated insulin delivery systems is high, especially among pediatric patients seeking to lessen the daily management burden. The US FDA's expedited review pathways accelerate market access for innovative closed-loop systems. Boston and Silicon Valley serve as innovation hubs, driving research into advanced algorithms and device integration.
Germany
Glycemic control therapies see strong demand from endocrinology centers for managing Type 1 Diabetes efficiently. European Medical Device Regulation (MDR) ensures rigorous standards for device approval and post-market surveillance. Munich and Berlin are centers for medical technology development, attracting specialized software and data science talent.
Canada
Pediatric clinics in Canada show significant demand for automated systems, reducing daily management burdens on children and caregivers. Health Canada facilitates device approvals, focusing on patient safety and efficacy for advanced diabetes technologies. Toronto and Montreal host significant biotech clusters, fostering medical device innovation and clinical trials.
Japan
Predictive algorithms in automated insulin delivery systems are increasingly sought after to improve time-in-range for patients. Japan's PMDA expedites time-to-market for innovative closed-loop systems, encouraging foreign investment. Tokyo and Osaka are key centers for medical device manufacturing and research and development activities in diabetes care.
India
Patient populations in India represent substantial growth potential for both advanced and traditional diabetes management devices. CDSCO regulations govern the import and manufacturing of medical devices, influencing local market entry strategies for global players. Bangalore and Hyderabad are emerging as hubs for health tech startups and device distribution networks.
Global Type 1 Diabetes (T1D) Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The global Type 1 Diabetes market features a dynamic mix of established pharmaceutical and medical device giants alongside specialized technology innovators. Strategic archetypes include integrated solution providers offering broad portfolios and focused technology specialists driving innovation in specific areas like CGM. Companies are actively pursuing strategic partnerships and portfolio diversification to enhance their market reach and address diverse patient needs globally.
Integrated solution providers such as Medtronic plc leverage their extensive device portfolios to offer comprehensive Type 1 Diabetes management, spanning advanced insulin pumps and continuous glucose sensors. Dexcom, Inc. exemplifies a specialized technology focus, competing primarily on continuous glucose monitoring data accuracy, interoperability, and user experience for patients and clinicians. Abbott Laboratories occupies a strong market position with its popular FreeStyle Libre system, anchoring its presence in both CGM and traditional monitoring segments across various geographies. These prominent players continually innovate to meet the evolving demands for more autonomous and less intrusive diabetes management solutions, influencing market direction.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Tandem Diabetes Care, Inc. |
| Eli Lilly and Company |
| AstraZeneca |
| Dexcom, Inc. |
| Novo Nordisk A/S |
| Medtronic plc |
| Johnson & Johnson |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Manufacturing concentration in China and the United States for advanced medical electronics strongly influences the margin capture for integrated device providers.
Pricing Analysis
After-sales services and consumable supplies form a significant recurring revenue stream for T1D device manufacturers. Pricing models for automated insulin delivery systems often incorporate a subscription or SaaS-tiered approach for software algorithms, alongside transactional sales for hardware. Price differentiation is driven by FDA/CE marking certification levels and brand premium, particularly for advanced continuous glucose monitoring devices. Pricing pressure stems from inconsistent reimbursement policies across European national healthcare systems, impacting patient access. Emerging markets like India exhibit the most price-sensitive buyer segments, while pediatric clinics in the United States show less sensitivity for advanced technologies.
Supply Chain Analysis
Extended payment terms for device components and specialized raw materials present a common supplier-financing arrangement within the T1D market. Geographic supply concentrations include China for microprocessors and electronic components, Germany for precision engineering, and the United States for advanced software development. Raw material dependencies encompass specialized medical-grade plastics for device casings and highly purified insulin APIs. Single-source vulnerability for critical microcontrollers represents a structural supply chain risk. Distribution runs through online retailers for accessories, hospitals for initial pump placements, and specialty clinics for advanced device dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The T1D market presents fragmentation opportunities as patient preference shifts towards discreet, lifestyle-compatible devices, creating specific niches.
For Market Incumbents: Pre-empt emerging non-invasive monitoring technologies by aggressively investing in optical sensor research and development. Consolidate diverse device platforms to offer seamlessly integrated solutions, leveraging existing regulatory pathways like the US FDA's expedited review programs. This strategy mitigates the threat from specialized technology startups and reinforces market leadership through advanced algorithms.
For New Entrants and Emerging Players: Underpenetrated emerging markets like Brazil and India represent the most penetrable entry points for cost-effective, traditional diabetes management tools. Focus on developing localized versions of blood glucose meters and essential insulin delivery devices. Strategic partnerships with pharmacies for broad geographic distribution offer a viable go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed firms specializing in niche medical device software, offering long-term viability in data-driven therapy. Focus on acquiring companies with strong intellectual property in AI-driven glycemic control algorithms or novel sensor technologies. Increasing regulatory approvals for Software as a Medical Device (SaMD) acts as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introducing non-invasive glucose monitoring devices addresses patient demand for less intrusive solutions. |
| Platform Integration | Integrating CGM data with automated insulin delivery systems enhances patient outcomes and clinical decision-making. |
| Geographic Expansion | Penetrating underserved patient populations in Brazil and India expands market reach for diabetes management devices. |
| Software Companion Development | Developing secure data monetization platforms creates new revenue streams with research and public health organizations. |
| Regulatory Approval Pathway | Navigating the EU MDR process ensures market access for innovative medical devices across European healthcare systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory submissions, clinical trial databases, and medical device registries. This involved in-depth interviews with endocrinologists, pediatricians, medical device engineers, and payer access specialists. Triangulation of bottom-up market sizing with top-down validation ensured data robustness.
Forecast inputs considered include product type adoption rates, therapy area demand shifts, and end-user preferences across the analysis window. The analytical framework models market growth by segmenting product types, end-users, and geographies. Compound annual growth rates were derived from historical trends and projected technological advancements. Specific forecast inputs included insulin pump penetration rates and CGM sensor replacement cycles.
Practitioners should monitor evolving regulatory frameworks, particularly the EU MDR, for early signals of market shifts. Forecasts reflect assumptions documented at the time of publication. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Latin America Insulin Infusion Pump Market