
 Continuous Glucose Monitoring in Philippines Market | 2026-2036
Continuous Glucose Monitoring in Philippines Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Glucose Monitoring in Philippines Market Insights
Hospital procurement departments is bifurcating from individual out-of-pocket purchases as the dominant demand channel for CGM systems in the Philippines. Dexcom, Inc. sustains technology leadership through its factory-calibrated sensor platforms that reduce clinic dependency for Filipino patients in remote provinces. Abbott Laboratories anchors market penetration via pharmacy-led distribution networks that extend into secondary cities beyond Metro Manila.
Continuous glucose monitoring comprises electrochemical sensor arrays that interstitial fluid glucose levels through enzymatic reactions, transmitting data to receivers or smartphones for real-time glycemic tracking. Wearable devices dominate current volume as patients prefer discreet patch-based sensors over handheld meters for daily glucose surveillance. Flash glucose monitoring technology leads adoption growth due to its factory-calibrated design that eliminates fingerstick calibration requirements, while data analytics solutions represent the fastest-emerging segment as endocrinologists demand predictive glycemic pattern recognition.
The Food and Drug Administration Philippines regulates CGM devices as Class B or Class C medical devices requiring pre-market notification, while the Department of Health's PhilHealth circulars increasingly influence reimbursement eligibility for diabetes management technologies. The Bureau of Product Standards enforces electrical safety and electromagnetic compatibility standards that shape import requirements for international manufacturers. Stakeholders must monitor PhilHealth benefit package expansions and local clinical validation requirements as the decisive variables for market access scale in the Philippine archipelago.
Market Dynamics
The Philippine CGM market is bifurcating between hospital procurement systems and direct-to-consumer channels as PhilHealth reimbursement pathways mature, creating divergent demand patterns across Metro Manila's private networks and provincial diabetes centers.
Growth Catalysts
- PhilHealth Circular Expansion:The national health insurer's benefit package revisions for non-communicable diseases are accelerating wearable glucose sensor eligibility, pulling device volumes into formal reimbursement channels.
- Flash Glucose Monitoring:Factory-calibrated sensor designs eliminate fingerstick calibration requirements, expanding addressable patient populations beyond endocrinology clinics into primary care settings.
- Provincial Care Networks:Emerging diabetes centers in Cebu and Davao are generating concentrated demand for remote monitoring capabilities that reduce specialist travel burdens.
Market Restraints
- Import Duty Structure:Philippine tariff classifications for Class B and Class C medical devices impose cost premiums on electrochemical sensor arrays that limit price competitiveness against conventional glucometers.
- Metro Manila Supply Concentration:Distribution infrastructure for CGM systems clusters in the capital region, creating logistics friction for patients in Visayas and Mindanao archipelago provinces.
- Sensor Longevity Limitations:Current enzymatic glucose oxidase formulations degrade in tropical humidity conditions, compressing effective wear duration versus temperate climate performance benchmarks.
Strategic Opportunities
- Telemedicine Integration:Convergence of CGM data streams with remote consultation platforms enables endocrinologists to manage glycemic patterns across the Philippine archipelago without physical clinic visits.
- Pharmacy Channel Expansion:Secondary city drugstore networks in Iloilo, Bacolod, and Cagayan de Oro represent underpenetrated points of patient access for over-the-counter sensor purchases.
- Department of Health Procurement Mandates:Universal health coverage integration creates institutional purchasing pathways for government hospital networks seeking population-scale diabetes management tools.
Industry Challenges
- Biomedical Engineer Scarcity:Calibration-free sensor deployment requires trained technicians for patient onboarding, a skillset concentrated in Metro Manila's tertiary hospitals with limited provincial availability.
- PhilHealth Documentation Burden:Reimbursement claims for continuous monitoring devices demand extensive glycemic justification paperwork that delays provider compensation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Glucose Monitoring in Philippines Market |
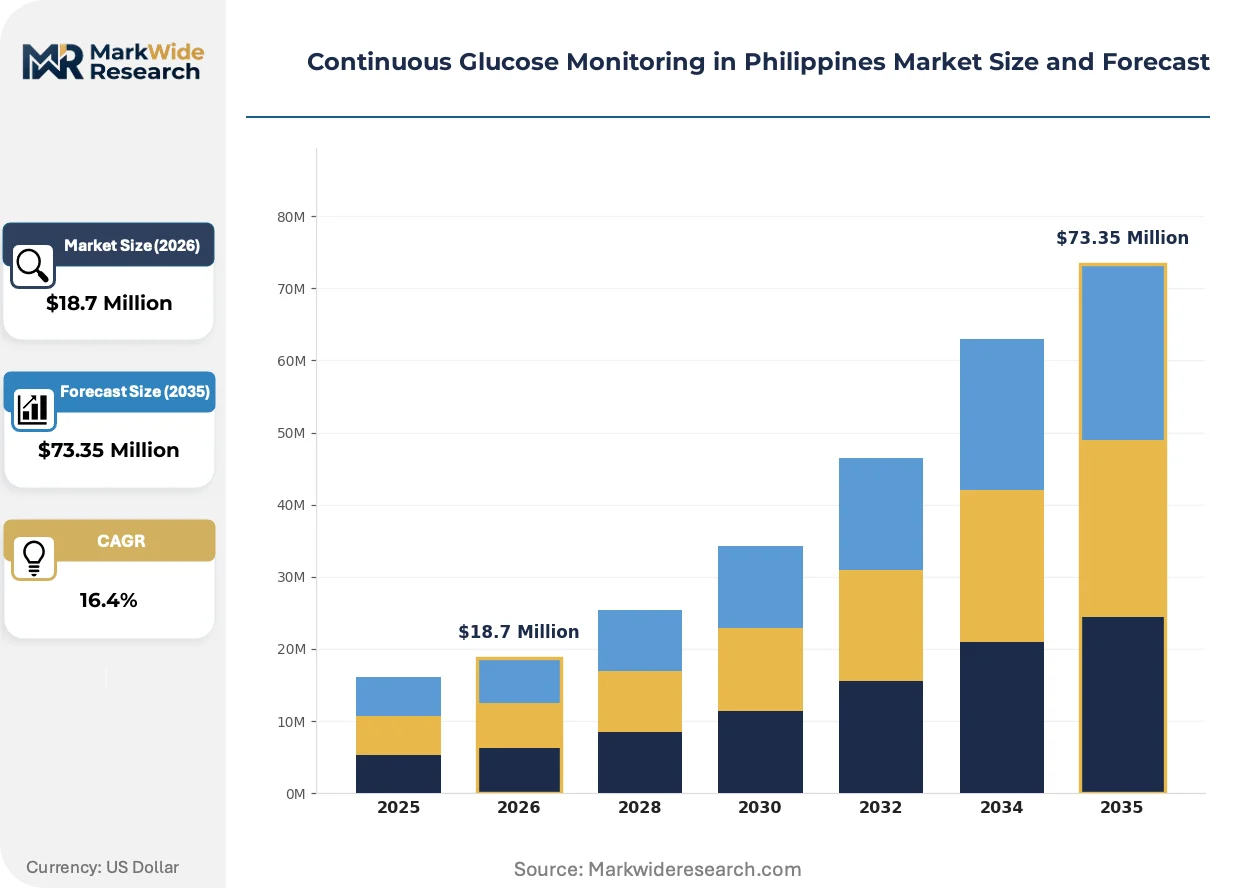
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $73.35 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Handheld Meters, Integrated Systems, Mobile Apps Technology: Flash Glucose Monitoring, Continuous Glucose Sensors, Transmitter Technology, Data Analytics Solutions End User: Individuals with Diabetes, Healthcare Providers, Diabetes Educators, Researchers Distribution Channel: Retail Pharmacies, Online Retailers, Hospitals, Medical Supply Stores |
| Companies Covered | Dexcom, Inc., Abbott Laboratories, Medtronic plc, F. Hoffmann-La Roche Ltd, Senseonics Holdings, Inc., Ascensia Diabetes Care Holdings AG, Insulet Corporation, Novo Nordisk A/S, Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Glucose Monitoring in Philippines Market Trends and Innovations
Wearable glucose surveillance is fragmenting across multiple technology trajectories as Filipino patients demand discreet form factors and real-time data autonomy independent of clinic-based calibration protocols.
Electrochemical sensor miniaturization is decomposing the traditional handheld meter market by embedding glucose oxidase chemistry into flexible patch substrates. Endocrinology practices in Makati Medical Center and St. Luke's Medical Center are deploying these platforms for continuous outpatient monitoring. The technology is decomposing clinic visit frequency requirements for stable Type 2 patients, compressing revenue per patient for traditional consultation models while expanding total addressable monitoring volume.
Food and Drug Administration Philippines pre-market notification pathways for Class C medical devices are tightening electromagnetic compatibility documentation requirements for wireless glucose transmitters. Manufacturers must now submit expanded electrical safety testing for tropical climate operation. The regulatory shift most affects importers of European and North American sensor platforms originally validated for temperate zone performance specifications.
Direct-to-consumer pharmacy purchases are displacing prescription-locked distribution for factory-calibrated flash glucose systems. Mercury Drug and Watsons pharmacy chains are expanding dedicated diabetes care sections in flagship Metro Manila locations. The behavioral shift is most visible among employed Filipino professionals aged 35-55 who prioritize glycemic autonomy without employer health plan intermediation.
Continuous Glucose Monitoring in Philippines Market Segmentation
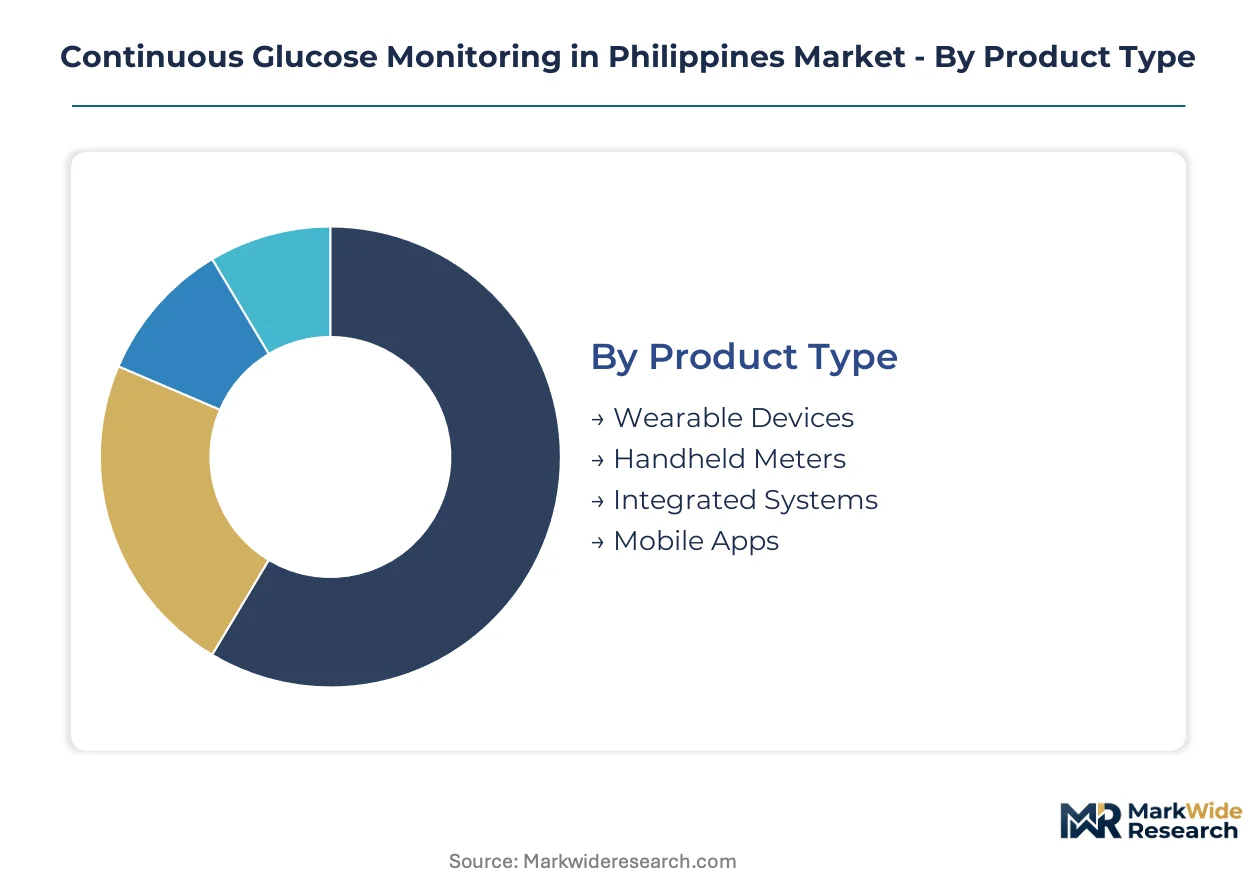
Segmentation patterns in the Philippine CGM market reveal how reimbursement pathways, tropical climate constraints, and archipelago geography reshape demand across product categories. Channel bifurcation between hospital procurement and direct-to-consumer purchases creates distinct segment performance profiles.
Product Type:
Wearable devices dominate hospital procurement channels in Metro Manila's private networks, while handheld meters persist in provincial primary care settings where calibration-free deployment remains limited.
- Wearable Devices:Patch-based electrochemical sensors embed glucose oxidase chemistry into flexible substrates for continuous interstitial fluid monitoring. Demand concentrates in Makati Medical Center and St. Luke's Medical Center networks where endocrinologists deploy remote outpatient surveillance. PhilHealth reimbursement eligibility for factory-calibrated systems accelerates volume through formal procurement channels.
- Integrated Systems:Transmitter-receiver combinations with smartphone connectivity enable real-time data sharing between patients and clinicians. Adoption clusters in Cebu and Davao diabetes centers seeking to reduce specialist travel burdens across Visayas and Mindanao provinces. Tropical humidity degradation of enzymatic formulations compresses effective sensor longevity versus temperate benchmarks.
- Handheld Meters:Conventional fingerstick glucometers retain volume in government health facilities with limited biomedical engineering support.
- Mobile Apps:Software platforms aggregate glucose data streams for pattern recognition and patient coaching.
By volume, Wearable Devices leads. By growth pace, Integrated Systems is expanding most quickly.
Technology:
Cost tier stratification separates premium factory-calibrated platforms from calibration-dependent alternatives, with price sensitivity most acute in out-of-pocket provincial purchases.
- Flash Glucose Monitoring:Factory-calibrated sensor designs eliminate fingerstick calibration through proprietary glucose oxidase formulations. Mercury Drug and Watsons pharmacy chains in Metro Manila flagship locations stock these systems for direct-to-consumer purchase. Employed professionals aged 35-55 drive volume as they prioritize glycemic autonomy without employer plan intermediation.
- Data Analytics Solutions:Predictive glycemic pattern recognition algorithms process continuous glucose streams for endocrinologist decision support. Makati Medical Center deploys these platforms for population-scale diabetes management. PhilHealth documentation burdens for reimbursement claims create implementation friction that delays provider compensation cycles.
- Continuous Glucose Sensors:Electrochemical arrays with 7-14 day wear duration form the core sensing element across device categories.
- Transmitter Technology:Wireless data relay modules must meet FDA Philippines electromagnetic compatibility requirements for tropical climate operation.
Flash Glucose Monitoring captures the dominant revenue share. Data Analytics Solutions shows the steepest expansion trajectory.
End User:
Customer type determines device complexity requirements, with individual patients favoring discreet autonomous systems while healthcare providers demand clinical-grade data integration.
- Individuals with Diabetes:Filipino patients across Type 1 and Type 2 spectrums seek wearable form factors that minimize social visibility of glucose management. Direct-to-consumer pharmacy purchases displace prescription-locked distribution as factory-calibrated systems enable self-initiated monitoring.
- Healthcare Providers:Endocrinologists in tertiary hospitals require continuous data streams with electronic medical record integration for remote consultation platforms. Biomedical engineer scarcity outside Metro Manila limits deployment reach into provincial networks.
- Diabetes Educators:Certified professionals in community health centers train patients on sensor application and data interpretation protocols.
- Researchers:Academic medical centers conduct local clinical validation studies required for FDA Philippines Class C device registration.
Individuals with Diabetes generate the highest absolute volume. Healthcare Providers are climbing the fastest as telemedicine integration matures.
Distribution Channel:
Supply concentration in Metro Manila creates logistics friction for archipelago distribution, with channel selection directly tied to reimbursement pathway access.
- Hospitals:Private hospital networks in Metro Manila anchor institutional procurement through Department of Health universal health coverage integration. Government hospital mandates for population-scale diabetes management tools create tender-based volume concentration.
- Retail Pharmacies:Mercury Drug and Watsons chains extend into Iloilo, Bacolod, and Cagayan de Oro with dedicated diabetes care sections. Secondary city drugstore networks represent underpenetrated access points for over-the-counter sensor purchases.
- Online Retailers:E-commerce platforms circumvent geographic supply constraints for patients in Visayas and Mindanao provinces.
- Medical Supply Stores:Specialized distributors serve clinic-based diabetes educators with training materials and replacement sensors.
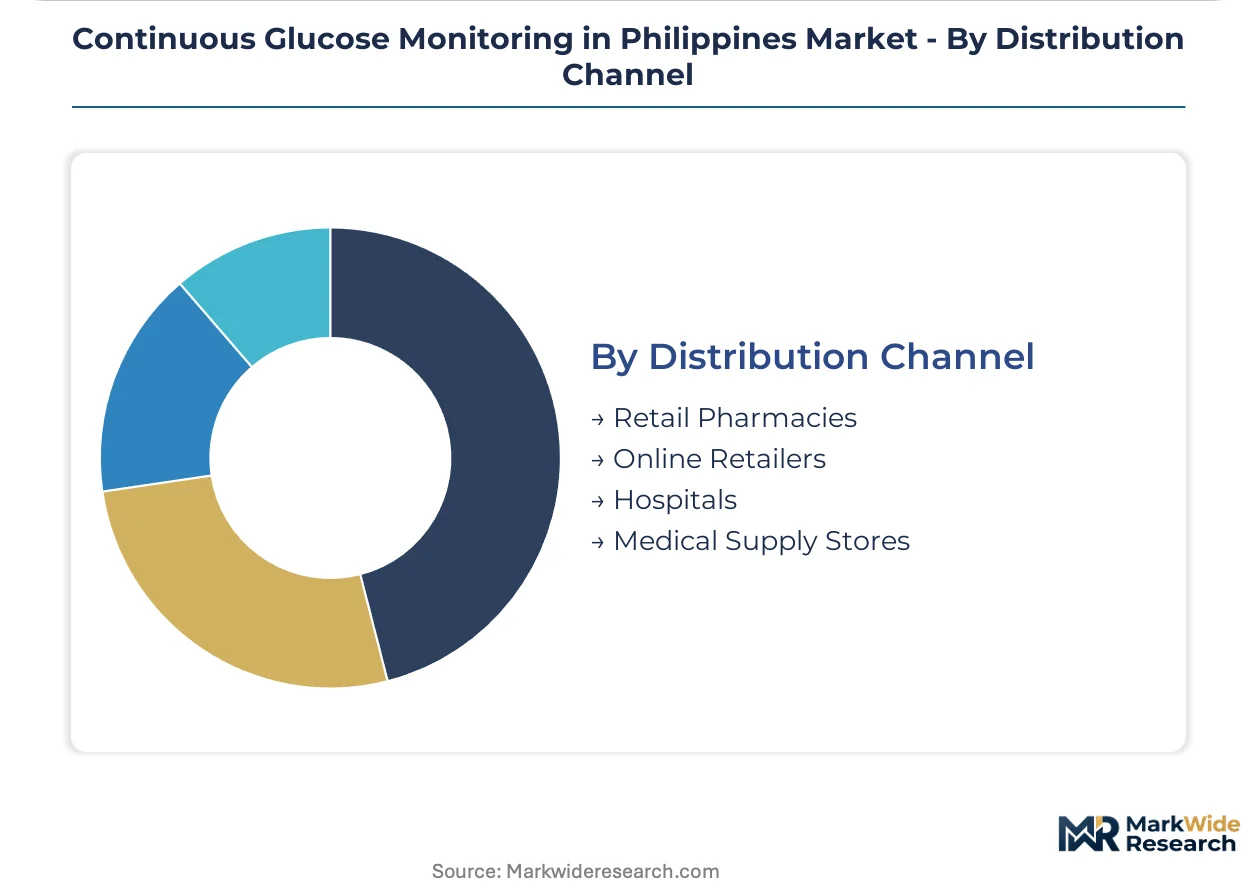
Hospitals lead by current volume. Retail Pharmacies are gaining share fastest as direct-to-consumer channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CGM distribution infrastructure clusters in Metro Manila while provincial networks in Visayas and Mindanao face persistent supply friction. PhilHealth reimbursement pathways and tropical climate validation requirements shape regional deployment patterns across the Philippine archipelago.
Metro Manila
Private hospital networks in Makati Medical Center and St. Luke's Medical Center anchor institutional procurement volume. FDA Philippines Class C pre-market notification requirements for wireless glucose transmitters concentrate regulatory expertise in the capital. Mercury Drug and Watsons pharmacy chains operate flagship diabetes care sections in Quezon City and Pasig.
Central Luzon
Provincial diabetes centers in Angeles City and San Fernando generate emerging demand for remote monitoring capabilities. Department of Health universal health coverage integration creates government hospital procurement pathways in Bulacan and Pampanga. Biomedical engineer scarcity limits factory-calibrated sensor deployment outside tertiary facilities.
Visayas
Cebu anchors regional demand as emerging diabetes care centers reduce specialist travel burdens across the central islands. Online retailers circumvent geographic supply constraints for patients in Iloilo and Bacolod. Tropical humidity degradation of enzymatic formulations compresses effective sensor longevity versus Metro Manila benchmarks.
Mindanao
Davao concentrates southern Philippines demand for wearable glucose surveillance. Cagayan de Oro represents underpenetrated pharmacy channel expansion potential for direct-to-consumer sensor purchases. Import duty structures for Class B and Class C medical devices impose cost premiums that limit price competitiveness against conventional glucometers.
Calabarzon
Manufacturing zones in Laguna and Cavite generate employed professional demand for discreet glycemic autonomy. Factory-calibrated flash glucose systems enable self-initiated monitoring without employer health plan intermediation. Secondary city drugstore networks in Batangas and Lipa City lag Metro Manila flagship locations in dedicated diabetes care infrastructure.
Continuous Glucose Monitoring in Philippines Market Competitive Landscape
Concentration sits with multinational medical technology conglomerates that anchor hospital procurement channels and pharmacy distribution networks. Dexcom, Inc. and Abbott Laboratories occupy dominant positions through divergent channel strategies—direct institutional sales versus retail pharmacy penetration. Medtronic plc and F. Hoffmann-La Roche Ltd represent integrated diabetes care portfolios that bundle insulin delivery with glucose sensing. Competitive moves center on telemedicine platform partnerships and tropical climate validation studies for FDA Philippines registration.
Within the multinational conglomerate tier, Dexcom, Inc. and Abbott Laboratories exemplify divergent market access strategies—hospital-centric versus pharmacy-led. Among European-headquartered diversified health companies, F. Hoffmann-La Roche Ltd and Sanofi occupy positions that span pharmaceutical and device domains. Medtronic plc represents the integrated medical technology archetype with diabetes-specific vertical focus. These named entities anchor competitive dynamics without exclusive claim to segment ownership.
| Leading Market Players |
|---|
| Dexcom, Inc. |
| Abbott Laboratories |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Senseonics Holdings, Inc. |
| Ascensia Diabetes Care Holdings AG |
| Insulet Corporation |
| Novo Nordisk A/S |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with Mercury Drug and Watsons pharmacy chains lock in sensor allocation visibility while insulating manufacturers from spot-market volatility in Metro Manila's concentrated distribution nodes. These arrangements bind Abbott Laboratories and Dexcom to volume commitments that stabilize landed cost structures despite Philippine import duty premiums on Class C medical devices.
Pricing Analysis
PhilHealth circulars dictate the pricing tier structure across hospital procurement and direct-to-consumer channels, stratifying reimbursement-eligible factory-calibrated systems from out-of-pocket calibration-dependent alternatives. Premium tiers attach to FDA Philippines Class C registrations with tropical climate validation, while standard tiers serve government facilities with simplified documentation. Cost compression in the direct-to-consumer segment intensifies as pharmacy chains expand dedicated diabetes care sections. Individual patients aged 35-55 in Metro Manila show lowest price sensitivity due to employment-based purchasing power, while provincial Type 2 populations in Visayas and Mindanao exhibit acute sensitivity to sensor replacement frequency costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement channels, while strategic stockpiling characterizes pharmacy distribution given tropical humidity degradation risks for enzymatic sensor formulations. Electrochemical sensor arrays draw from manufacturing concentrations in the United States, Ireland, and Malaysia, with glucose oxidase chemistry resting on pharmaceutical-grade substrate suppliers in Germany and Japan. Single-source vulnerability concentrates in wireless transmitter modules validated for FDA Philippines electromagnetic compatibility. Distribution runs through temperature-controlled logistics networks anchored in Metro Manila, with secondary hub development in Cebu and Davao reducing archipelago delivery friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as telemedicine data interoperability becomes the decisive patient retention mechanism, with endocrinology practices demanding seamless electronic medical record integration that fragments standalone device vendors.
For Market Incumbents: Secure tropical climate validation studies for FDA Philippines Class C renewals before humidity-adjusted sensor longevity requirements tighten. Backward integration into enzymatic formulation production insulates margin structures from pharmaceutical-grade substrate volatility. Channel control through exclusive Mercury Drug and Watsons capacity reservation agreements limits pharmacy-led entrant access to Metro Manila's highest-value patient cohorts. For New Entrants and Emerging Players: Provincial biomedical engineer scarcity creates a service-layer gap where incumbents under-serve patient onboarding and calibration-free deployment training. White-space concentration sits with government hospital networks in Central Luzon and Calabarzon seeking population-scale diabetes management tools under Department of Health universal health coverage mandates. A go-to-market angle through telemedicine platform partnerships bypasses capital-intensive pharmacy channel buildouts. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sensor manufacturers with captive enzymatic chemistry production and existing FDA Philippines registrations. Long-term viability across the analysis window hinges on reimbursement strategy execution rather than device innovation alone. The signal to watch is PhilHealth benefit package expansion velocity for continuous monitoring categories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Philippines Class C Renewal Pathway | Tropical climate validation documentation secures market access continuity for wireless glucose transmitters. |
| PhilHealth Reimbursement Strategy | Benefit package alignment pulls device volumes into formal procurement channels with price stability. |
| Hospital System Partnership | Makati Medical Center and St. Luke's networks anchor institutional volume for remote outpatient surveillance. |
| Software Companion Development | Predictive glycemic pattern recognition algorithms differentiate endocrinologist decision support offerings. |
| Geographic Expansion | Cebu and Davao diabetes centers reduce specialist travel burdens across Visayas and Mindanao provinces. |
Research Methodology
Desk research of FDA Philippines pre-market notification databases, PhilHealth circular archives, and hospital procurement records preceded structured interviews with endocrinology department heads, biomedical engineering directors, pharmacy chain category managers, and GPO contracts specialists. Primary fieldwork with diabetes care center administrators in Metro Manila, Cebu, and Davao validated secondary estimates of sensor utilization patterns. Bottom-up patient population modeling triangulated against top-down manufacturer shipment data through the analysis window.
Variance decomposition across product type, technology tier, end user category, and distribution channel dimensions shaped the quantitative framework. CAGRs were derived from segmented growth trajectory analysis incorporating PhilHealth reimbursement elasticity assumptions and tropical climate sensor degradation adjustments. Forecast inputs included provincial care network expansion timelines and import duty structure stability projections.
Underlying assumptions cover PhilHealth benefit package continuity and enzymatic formulation supply stability, with deviation risk concentrated in FDA Philippines electromagnetic compatibility documentation tightening and tropical humidity validation requirement changes. Revision becomes warranted when reimbursement eligibility thresholds cross utilization intensity benchmarks or when secondary city pharmacy infrastructure penetration accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market