
 Diabetic Ketoacidosis Treatment Market | 2026-2036
Diabetic Ketoacidosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Ketoacidosis Treatment Market Outlook
The United States is tilting toward expanded insulin manufacturing capacity and emergency care infrastructure investments. Pfizer Inc. leverages its established injectables network to sustain hospital supply agreements across North American markets. Novo Nordisk anchors the rapid-acting insulin segment through specialized fermentation and purification platforms. Eli Lilly and Company differentiates via integrated diabetes care portfolios that extend beyond acute DKA into chronic management.
Diabetic ketoacidosis treatment encompasses the pharmacologic and fluid resuscitation interventions required to correct hyperglycemia, ketosis, and metabolic acidosis in diabetic patients, typically involving intravenous regular insulin at 0.1 units per kilogram per hour alongside isotonic saline replacement. The primary purpose is to restore euglycemia, correct electrolyte imbalances, and prevent cerebral edema or mortality in acute presentations. Insulin products command the largest value share within the product type dimension, while fluid replacement therapies generate steady volume demand driven by protocol standardization. Intravenous delivery mode dominates acute settings, though subcutaneous alternatives are gaining traction in step-down and home care transitions where patient stability permits.
FDA oversight of insulin biosimilar interchangeability and EMA's MDR requirements for infusion devices shape product development timelines and market access conditions. The EU F-Gas Regulation also influences cold chain logistics for temperature-sensitive biologics distributed across European markets. Stakeholders must monitor evolving reimbursement frameworks for home-based DKA prevention technologies and the regulatory trajectory of closed-loop insulin delivery systems.
Market Dynamics
Protocol standardization across hospital emergency departments is compressing variation in insulin delivery and fluid resuscitation practices, locking in preferred supplier relationships and raising switching costs for acute care procurement teams.
Growth Catalysts
- FDA Biosimilar Interchangeability Pathway:Accelerated approval timelines for insulin alternatives are expanding therapeutic options within hospital formularies and reducing single-source dependency.
- Closed-Loop Algorithm Integration:Automated glucose monitoring paired with predictive insulin dosing is digitizing step-down care transitions and enabling earlier patient discharge protocols.
- Emergency Department Consolidation:Integrated health systems in the United States are mandating uniform DKA order sets, creating captive demand for protocol-aligned product bundles.
Market Restraints
- Biologic Cold Chain Fragility:Temperature excursions during transport degrade insulin potency, requiring validated packaging that adds 12-18% to landed costs for rural hospital networks.
- Fermentation Capacity Concentration:Active pharmaceutical ingredient production clusters in Denmark and the United States, exposing buyers to single-source geographic risk during supply disruptions.
- EMA MDR Infusion Device Recertification:Extended technical documentation requirements for electronic insulin pumps are delaying product launches and freezing upgrade cycles.
Strategic Opportunities
- Home-Based DKA Prevention Monitoring:Remote ketone tracking combined with telemedicine triage is opening reimbursement pathways under Medicare remote patient monitoring codes.
- Subcutaneous Rapid-Acting Analogs:Ultra-fast insulin formulations are enabling safe transition from intravenous to subcutaneous delivery in observation units, shortening length-of-stay metrics.
- EU Green Deal Cold Chain Incentives:Grants for sustainable refrigeration infrastructure are subsidizing district-level distribution hubs in member states with fragmented rural access.
Industry Challenges
- Specialized Endocrinology Nursing Shortage:Competency gaps in DKA protocol execution are forcing hospitals to rely on traveling nurse staffing at 40-60% premium rates.
- Interoperability Certification Burden:EHR integration testing for smart infusion pumps requires 14-18 month validation cycles before hospital IT departments approve deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Ketoacidosis Treatment Market |
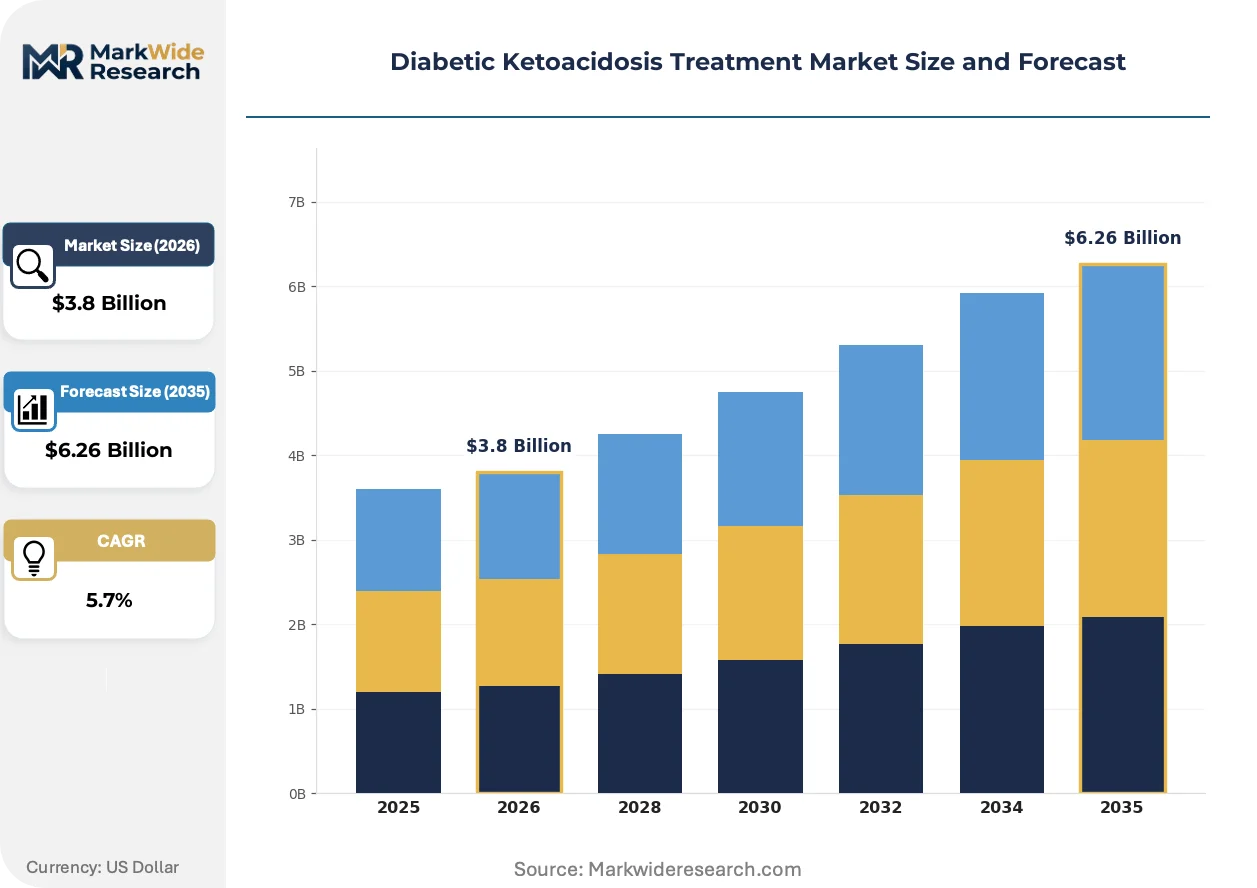
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Fluid Replacement, Electrolyte, Bicarbonate Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Clinics, Home Care, Emergency Departments Application: Emergency Care, Continuous Glucose Monitoring, Patient Education, Clinical Trials |
| Companies Covered | Pfizer Inc., B. Braun Melsungen AG, Novo Nordisk, Hikma Pharmaceuticals, Fresenius Kabi, Eli Lilly and Company, Baxter International Inc., Biocon, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Ketoacidosis Treatment Market Strategic Shifts
Real-time glucose telemetry and algorithmic insulin dosing are converging to reshape acute metabolic crisis management, compressing the window between detection and intervention while redrawing the boundary between inpatient and ambulatory care settings.
Continuous glucose monitoring paired with predictive analytics platforms is digitizing the transition from critical care to step-down units. Hospital systems in the United States are deploying these systems in emergency departments to flag DKA risk before laboratory confirmation. The structural consequence is a compression in admission-to-treatment initiation times and reduced reliance on manual point-of-care testing.
EMA's Medical Device Regulation is forcing recertification of all legacy infusion pumps with software-controlled dosing capabilities. Manufacturers must submit enhanced clinical evidence and post-market surveillance plans. The insulin delivery device segment is responding by consolidating product lines and accelerating cybersecurity hardening investments.
Buying committees are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party preventive maintenance providers. This procurement model change is disrupting traditional manufacturer service revenue streams. The pattern is most visible in United States academic medical centers where total cost-of-ownership metrics dominate capital allocation decisions.
Diabetic Ketoacidosis Treatment Market Segmentation
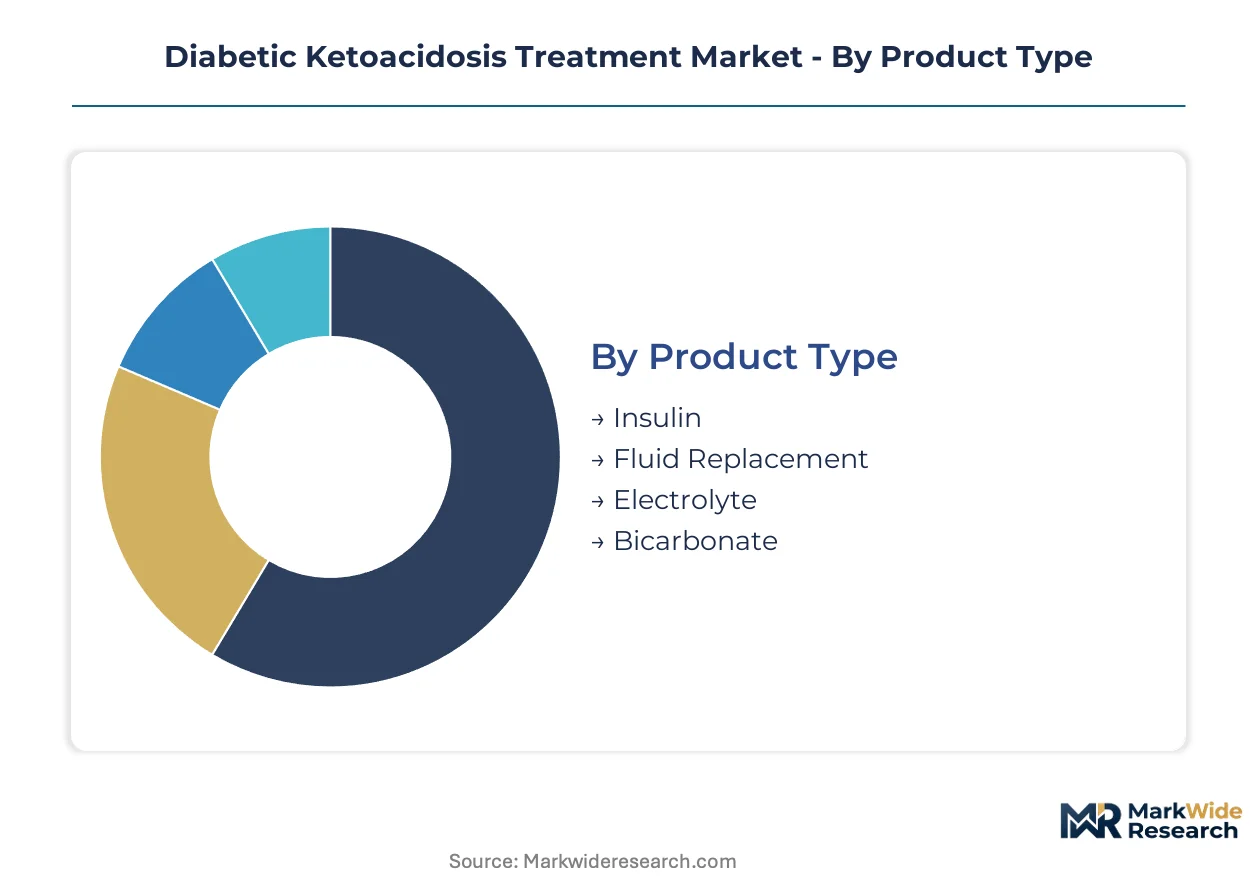
DKA treatment markets fragment across pharmacologic intervention types, delivery technologies, and care settings. Each dimension shapes procurement patterns, reimbursement pathways, and competitive positioning differently.
Product Type:
Cost tier differentiation across product categories reflects raw material complexity, manufacturing scale, and cold chain requirements.
- Insulin:Human and analog formulations manufactured via recombinant DNA fermentation in controlled bioreactor environments. Hospital emergency departments in the United States absorb the majority of volume, driven by protocol mandates for intravenous regular insulin at standardized dosing. FDA biosimilar interchangeability rulings are expanding formulary options and compressing unit pricing.
- Fluid Replacement:Isotonic saline and balanced crystalloid solutions for volume resuscitation. Demand concentrates in integrated health systems with standardized order sets, where procurement teams negotiate multi-year supply agreements. EMA quality standards for large-volume parenterals shape supplier qualification timelines.
- Electrolyte:Potassium and phosphate replacement formulations correcting DKA-induced deficiencies. Compounding pharmacies in academic medical centers produce patient-specific admixtures.
- Bicarbonate:Sodium bicarbonate infusions reserved for severe acidosis cases with pH below 6.9. Restricted use patterns limit volume relative to other categories.
Insulin holds installed capacity. Fluid replacement is rotating up the share rankings.
Delivery Mode:
Application context determines delivery technology selection, with acute stabilization requiring distinct approaches from transition and maintenance phases.
- Intravenous:Precision infusion via smart pumps enabling titrated dosing during critical metabolic correction. United States hospital networks prioritize devices with EHR interoperability and dose-error reduction software. EMA MDR recertification requirements are extending upgrade cycles and freezing capital budgets.
- Subcutaneous:Rapid-acting analog injections facilitating step-down from critical care to observation units. Ultra-fast formulations are shortening length-of-stay metrics in United States health systems targeting throughput optimization.
- Oral:Fluid and electrolyte administration for alert patients with intact airway reflexes. Limited role in severe DKA presentations.
- Inhalation:Investigational insulin delivery routes under evaluation in clinical trial protocols. Not yet incorporated into standard-of-care guidelines.
Intravenous maintains protocol dominance. Subcutaneous is climbing the fastest as observation-unit pathways expand.
End User:
Customer type segmentation reveals divergent purchasing authority, technical sophistication, and reimbursement access across care settings.
- Hospitals:Centralized pharmacy and therapeutics committees governing formulary decisions. United States integrated delivery networks leverage volume aggregation to extract preferential pricing from insulin manufacturers.
- Clinics:Outpatient facilities managing DKA risk in established diabetes populations. Medicare remote patient monitoring codes are subsidizing ketone tracking technology deployment.
- Home Care:Emerging setting for stable patients transitioning from acute intervention. Reimbursement frameworks for home-based DKA prevention remain fragmented across United States payers.
- Emergency Departments:Frontline diagnostic and stabilization hubs where protocol standardization drives product bundle selection. Academic medical centers unbundle service contracts from capital equipment purchases.
Hospitals command procurement volume. Emergency departments are gaining influence over upstream supplier selection.
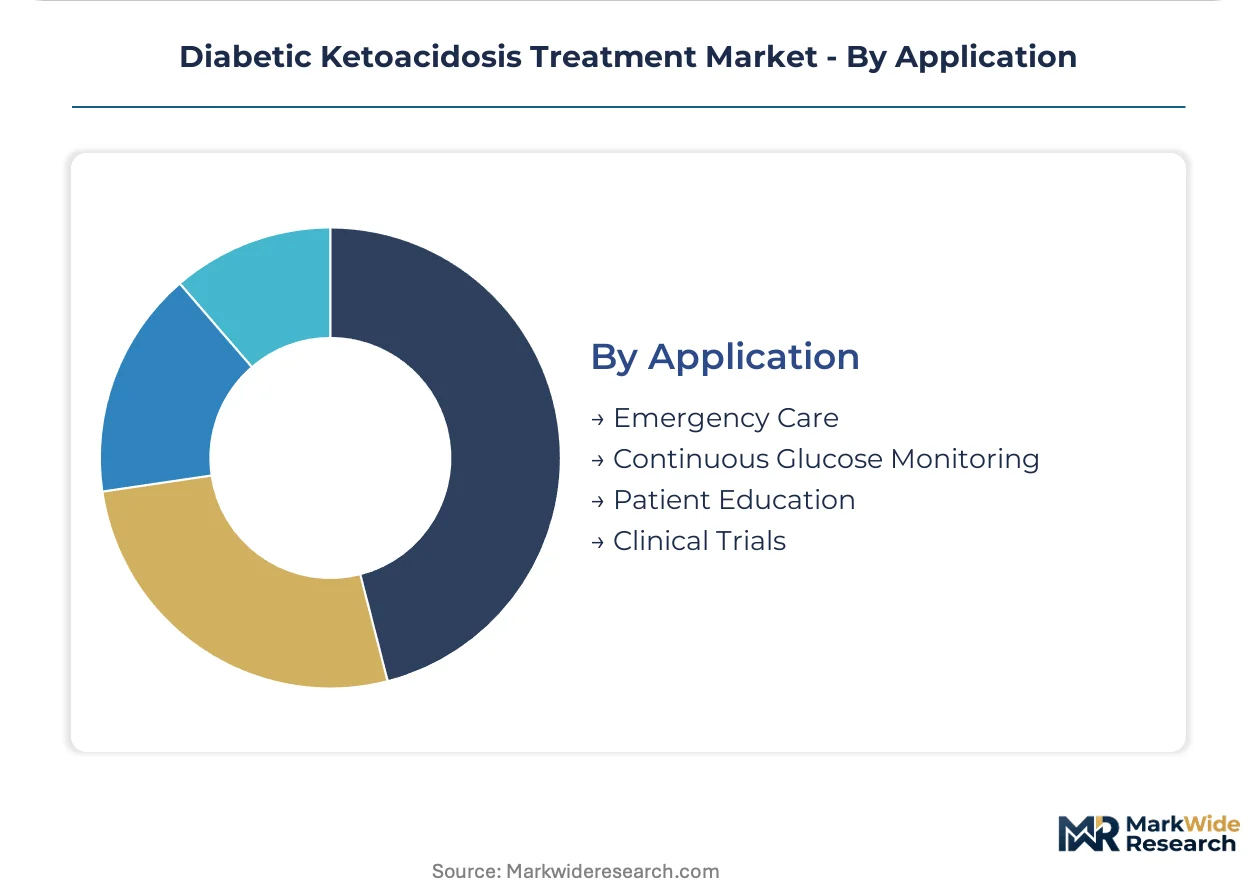
Application:
Maturity stage across application areas spans established clinical practice through emerging digital and research frontiers.
- Emergency Care:Acute metabolic crisis management with established insulin and fluid protocols. United States emergency medicine societies publish updated guidelines shaping hospital compliance requirements.
- Continuous Glucose Monitoring:Real-time telemetry with predictive analytics flagging DKA risk before laboratory confirmation. FDA clearance pathways for algorithm-integrated systems are accelerating hospital adoption.
- Patient Education:Structured programs reducing DKA recurrence in Type 1 diabetes populations. Endocrinology nursing shortages limit program scalability in rural United States markets.
- Clinical Trials:Research infrastructure evaluating novel insulin formulations and closed-loop delivery systems. Academic medical centers with established diabetes research programs anchor investigator-initiated studies.
Emergency care holds protocol authority. Continuous glucose monitoring is expanding most quickly as digital infrastructure penetrates acute settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insulin API fermentation clusters in Denmark and the United States concentrate manufacturing capacity, exposing downstream markets to geographic single-source risk during supply disruptions. Hospital procurement networks in advanced economies negotiate multi-year supply agreements that lock in preferred vendor relationships. Regulatory divergence between FDA biosimilar pathways and EMA MDR requirements is fragmenting product launch timelines across Atlantic markets.
United States
Integrated health systems in Texas, California, and the Northeast Corridor mandate standardized DKA order sets across emergency departments, creating captive demand for protocol-aligned insulin bundles. FDA biosimilar interchangeability rulings expand hospital formulary options while compressing unit pricing for rapid-acting analogs. Indianapolis anchors Eli Lilly's fermentation and purification infrastructure serving North American acute care networks.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive adoption of closed-loop glucose management systems in emergency settings. EMA MDR recertification requirements extend validation cycles for smart infusion pumps, freezing capital equipment budgets in academic medical centers. The Frankfurt-Rhine-Main logistics corridor supports cold chain distribution of temperature-sensitive biologics to Central European markets.
Denmark
Novo Nordisk's specialized fermentation platforms in the Copenhagen metropolitan area supply rapid-acting insulin to European and Asian hospital networks. EU F-Gas Regulation compliance costs add 12-18% to landed biologic costs for rural distribution points. The Øresund Region clusters pharmaceutical manufacturing expertise with Nordic health technology innovation hubs.
India
Biocon's Bangalore-based biologics manufacturing serves domestic hospital networks and export markets across Southeast Asia and Africa. CDSCO accelerated approval pathways for biosimilar insulins expand access in tier-2 and tier-3 city hospital systems. Maharashtra's Mumbai-Pune pharmaceutical corridor concentrates injectables formulation capacity for acute metabolic crisis interventions.
United Kingdom
NHS England's national DKA protocol standardization drives formulary convergence across emergency departments in London, Birmingham, and Manchester. MHRA post-Brexit regulatory divergence from EMA MDR timelines creates parallel certification requirements for infusion device manufacturers. The Oxford-Cambridge-London golden triangle anchors clinical trial infrastructure evaluating novel insulin delivery technologies.
Diabetic Ketoacidosis Treatment Market Competitive Environment
Integrated pharmaceutical conglomerates and specialized biologics manufacturers split the market across acute care and chronic disease management vectors. Hospital procurement committees prioritize suppliers with validated cold chain infrastructure and EHR-interoperable delivery devices. Three archetypes dominate: fermentation-scale insulin producers with captive API supply, diversified critical care injectables suppliers with fluid replacement portfolios, and emerging biosimilar specialists leveraging accelerated regulatory pathways. Competitive dynamics center on backward integration into fermentation capacity and geographic expansion of distribution hubs.
Among North American pharmaceutical conglomerates, Pfizer Inc. and Eli Lilly and Company occupy positions spanning hospital emergency department supply agreements and integrated diabetes care portfolios. Novo Nordisk anchors the European rapid-acting insulin segment through specialized bioreactor platforms. B. Braun Melsungen AG, Fresenius Kabi, and Baxter International Inc. represent the critical care fluids and infusion technology tier, with hospital contracting networks spanning European and North American acute care markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| B. Braun Melsungen AG |
| Novo Nordisk |
| Hikma Pharmaceuticals |
| Fresenius Kabi |
| Eli Lilly and Company |
| Baxter International Inc. |
| Biocon |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Bioreactor undercapacity in Denmark and the United States is tightening insulin API availability, forcing hospital procurement teams toward multi-year offtake commitments and compressing margin flexibility for rapid-acting analog formulations. FDA biosimilar interchangeability rulings and EMA MDR device recertification cycles are amplifying supplier concentration effects across acute care networks.
Pricing Analysis
FDA biosimilar interchangeability dictates the pricing tier structure across hospital formularies, with three-tier pricing separating originator analogs from interchangeable biosimilars and non-interchangeable follow-ons. Price differentiation hinges on cold chain certification grade and EHR interoperability bundling. Cost compression in the biosimilar tier is intensifying because formulary committees are expanding therapeutic substitution protocols. Academic medical centers exhibit highest price sensitivity due to total cost-of-ownership metrics, while rural critical access hospitals show lowest sensitivity because of limited supplier alternatives.
Supply Chain Analysis
Contract manufacturing concentration rests with Novo Nordisk's Copenhagen bioreactor platforms and Eli Lilly's Indianapolis fermentation complexes, with Thermo Fisher and Catalent holding fill-finish capacity for third-party biologics. Active pharmaceutical ingredient production draws from Denmark, the United States, and India, while purification resins and single-use bioreactor bags source from Germany and Japan. Single-source geographic vulnerability during transport disruptions represents the dominant structural risk. Distribution runs through integrated health system central warehouses in the United States and district-level cold chain hubs in the European Union.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop glucose management platforms are reconfiguring DKA treatment economics around algorithm-integrated ecosystems rather than discrete product sales, with EHR interoperability emerging as the decisive switching cost mechanism.
For Market Incumbents: Insulate fermentation capacity through captive bioreactor expansion in the United States and Denmark, locking in API supply security against biosimilar entrants. Secure EHR interoperability certifications for smart infusion pumps ahead of EMA MDR recertification deadlines, raising rival switching costs for hospital procurement committees. For New Entrants and Emerging Players: Build out remote patient monitoring infrastructure for home-based DKA prevention, exploiting reimbursement pathway fragmentation across United States Medicare Advantage plans. Target tier-2 Indian city hospital systems with biosimilar rapid-acting insulin, leveraging CDSCO accelerated approval timelines and local compounding pharmacy partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among closed-loop algorithm developers with hospital system SaaS contracts, positioning these archetypes for durable cash flow quality across the medium-term horizon. Monitor FDA breakthrough device designations for predictive DKA risk algorithms as the primary inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Bioreactor expansion in Copenhagen and Indianapolis secures captive API supply for rapid-acting insulin analogs. |
| Regulatory Approval Pathway | FDA biosimilar interchangeability submissions unlock formulary access across United States integrated health systems. |
| Hospital System Partnership | EHR-integrated smart pump deployments create protocol lock-in through emergency department order set standardization. |
| Software Companion Development | Predictive DKA risk algorithms paired with continuous glucose monitors enable earlier intervention and reduced admission rates. |
| Reimbursement Strategy | Medicare remote patient monitoring code capture subsidizes home-based ketone tracking technology deployment. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and clinical trial registries. Primary interviews engaged endocrinology nursing directors, hospital pharmacy and therapeutics committee chairs, biomedical engineers, and insulin manufacturing supply chain executives. Bottom-up volume modeling triangulated against top-down expenditure analysis across acute care settings.
Forecast inputs incorporate insulin fermentation capacity utilization, EHR interoperability adoption curves, and biosimilar interchangeability rulings across the projection horizon. Segmentation dimensions span product type, delivery mode, end user facility type, and regional regulatory cluster. CAGRs derive from spline-interpolated growth trajectory fitting calibrated to hospital admission data and pharmaceutical pricing indices.
Stress conditions across bioreactor contamination events, cold chain excursion frequency, and endocrinology nursing shortage severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline stability and reimbursement code permanence. Quarterly review of FDA biosimilar approval velocity and EMA MDR recertification completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
APAC Insulin Infusion Pumps Market