
 GCC in-Vitro Diagnostic Devices Market | 2026-2036
GCC in-Vitro Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
GCC in-Vitro Diagnostic Devices Market Intelligence
Project finance and leasing arrangements for high-throughput analyzers is narrowing the competitive field to capital-backed operators. Roche Diagnostics leverages its installed base of chemistry and immunoassay platforms to sustain service contracts across Gulf hospital networks. Abbott Laboratories anchors its position through point-of-care instruments deployed in Saudi primary care centers. Siemens Healthineers competes on imaging-integrated diagnostics workflows that appeal to UAE's large private hospital groups.
In-vitro diagnostic devices comprise reagents, assays, instruments, and software used to detect diseases, conditions, or infections from biological specimens outside the living organism, typically operating through automated optical, electrochemical, or molecular detection principles with throughput ranging from single-test point-of-care units to systems processing thousands of samples daily. Their primary commercial purpose is enabling clinical decision-making through standardized, reproducible biomarker quantification at scale. Reagents and assays generate recurring revenue streams that outperform instrument sales on margin durability, while molecular diagnostics represents the fastest-expanding technology segment as Gulf health systems prioritize genomic and PCR-based pathogen identification. Laboratory-based delivery still dominates transaction volume, though point-of-care deployment is accelerating in emergency and perioperative settings where turnaround time directly affects patient triage.
SFDA enforces medical device registration and post-market surveillance requirements that filter out uncertified suppliers, while MOHAP in the UAE mandates specific clinical evidence standards for novel diagnostic platforms seeking market access. BIS-equivalent conformity processes in Kuwait and Qatar add further layers of technical documentation that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor how Gulf harmonization initiatives reshape registration reciprocity and whether local manufacturing incentives redirect procurement preferences toward domestic production partnerships.
Market Dynamics
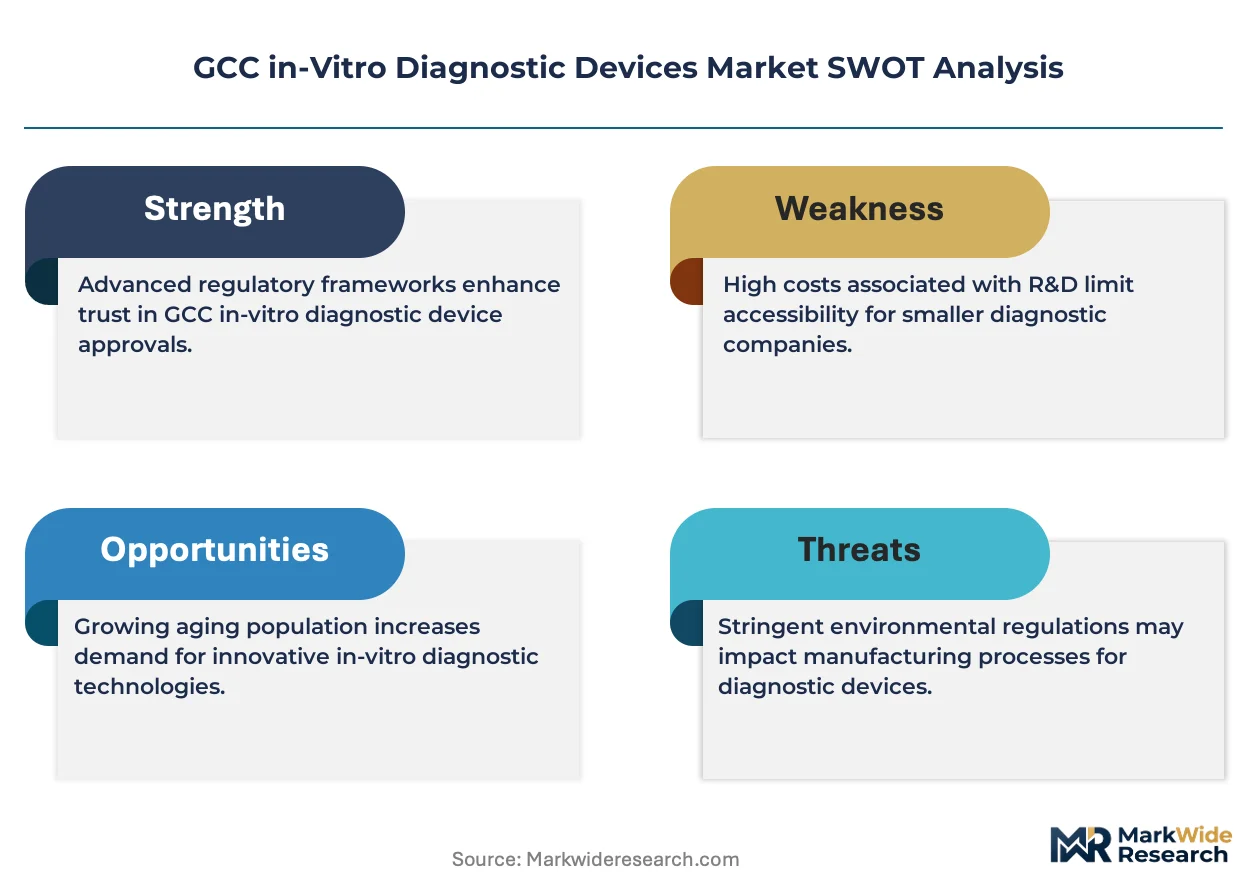
SFDA and MOHAP registration pathway tightening is compressing the supplier base, favoring capital-backed operators capable of sustaining multi-year compliance investments and localized technical support infrastructure.
Growth Catalysts
- Chronic disease surveillance mandates:Saudi Arabia's Ministry of Health directives on diabetes and cardiovascular screening are expanding molecular testing capacity across hospital networks.
- Reagent kit localization incentives:Domestic production partnerships in the UAE now receive procurement preference under MOHAP's revised tender evaluation frameworks.
- PCR platform standardization:Gulf health systems are prioritizing genomic pathogen identification as the core capability for infectious disease response.
Market Restraints
- Import dependency for optical components:High-throughput analyzer manufacturers rely on German and Japanese precision lens suppliers, exposing margins to euro-yen volatility.
- SFDA post-market surveillance burden:Mandatory adverse event reporting and batch-level traceability requirements extend compliance costs for reagent importers.
- Point-of-care substitution pressure:Bedside immunoassay devices are capturing low-complexity testing previously routed to centralized laboratories.
Strategic Opportunities
- Kuwait's underpenetrated private lab sector:BIS-equivalent conformity processes have delayed multinational entry, creating first-mover advantage for compliant operators.
- AI-integrated image analysis:Machine learning algorithms paired with digital pathology workflows are opening premium service tiers in UAE private hospital groups.
- Emergency department rapid triage:Perioperative settings across Saudi Arabia's hospital modernization program are accelerating point-of-care deployment.
Industry Challenges
- Clinical laboratory technologist shortages:Molecular diagnostics specialization requires training pipelines that Gulf universities have not yet scaled to match instrument installation rates.
- Legacy LIS integration complexity:Hospital information systems in established Saudi facilities use proprietary data formats that resist seamless connectivity with new analyzer generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC in-Vitro Diagnostic Devices Market |
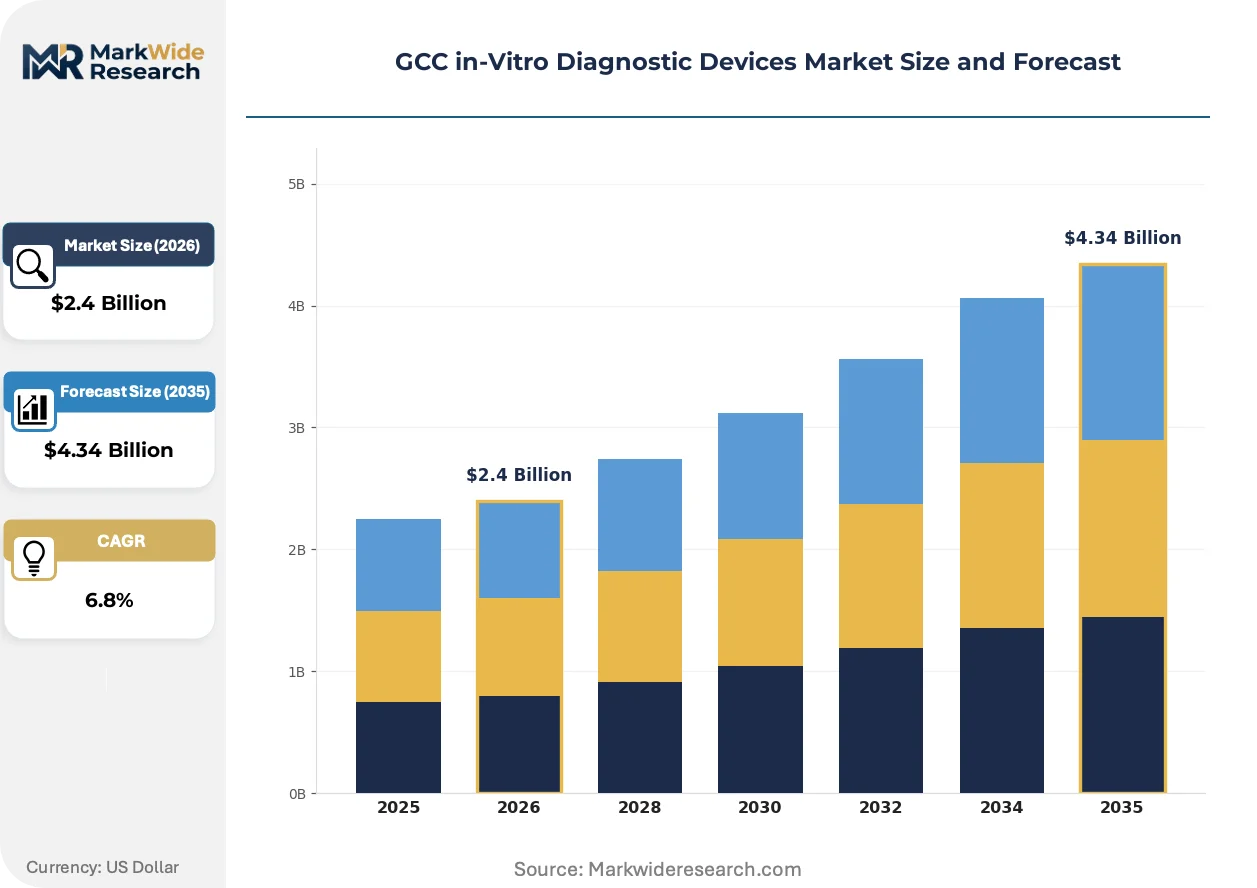
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Software Delivery Mode: Point-of-Care, Laboratory-Based, Home Use, Telemedicine End User: Hospitals, Clinics, Diagnostic Labs, Research Institutes Technology: Molecular Diagnostics, Immunoassays, Microarrays, Others |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Beckman Coulter, Danaher Corporation, Becton, Dickinson and Company, Sysmex Corporation, Al-Borg Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC in-Vitro Diagnostic Devices Market Strategic Shifts & Innovations
Automation architecture and regulatory digitization are compressing traditional competitive advantages in the GCC diagnostic landscape, while procurement centralization reconfigures vendor relationships.
Digital PCR and next-generation sequencing platforms are collapsing the cost-per-test economics of centralized reference laboratories. Saudi Arabia's National Guard Health Affairs and UAE's largest private hospital groups are consolidating send-out testing volumes onto in-house high-throughput systems. This technology shift is collapsing the historical revenue base of independent reference laboratories that built franchises on esoteric test access.
MOHAP's electronic registration portal and SFDA's Saudi Drug and Food Authority medical device tracking system are mandating real-time post-market data submission. These digitized surveillance frameworks compress approval timelines for compliant applicants while extending exclusion periods for documentation-deficient suppliers. Reagent manufacturers with established Gulf regulatory affairs teams are capturing expanded shelf space as competitors withdraw from the compliance burden.
Consolidated procurement through Ministry of Health tendering platforms is compressing vendor counts per category. Saudi Arabia's hospital network modernization and Qatar's Hamad Medical Corporation standardization initiatives are awarding multi-year exclusive supply contracts to single-source providers. This buyer concentration is most visible in chemistry and immunoassay platform categories, where installed base lock-in now determines competitive survival.
GCC in-Vitro Diagnostic Devices Market Segmentation
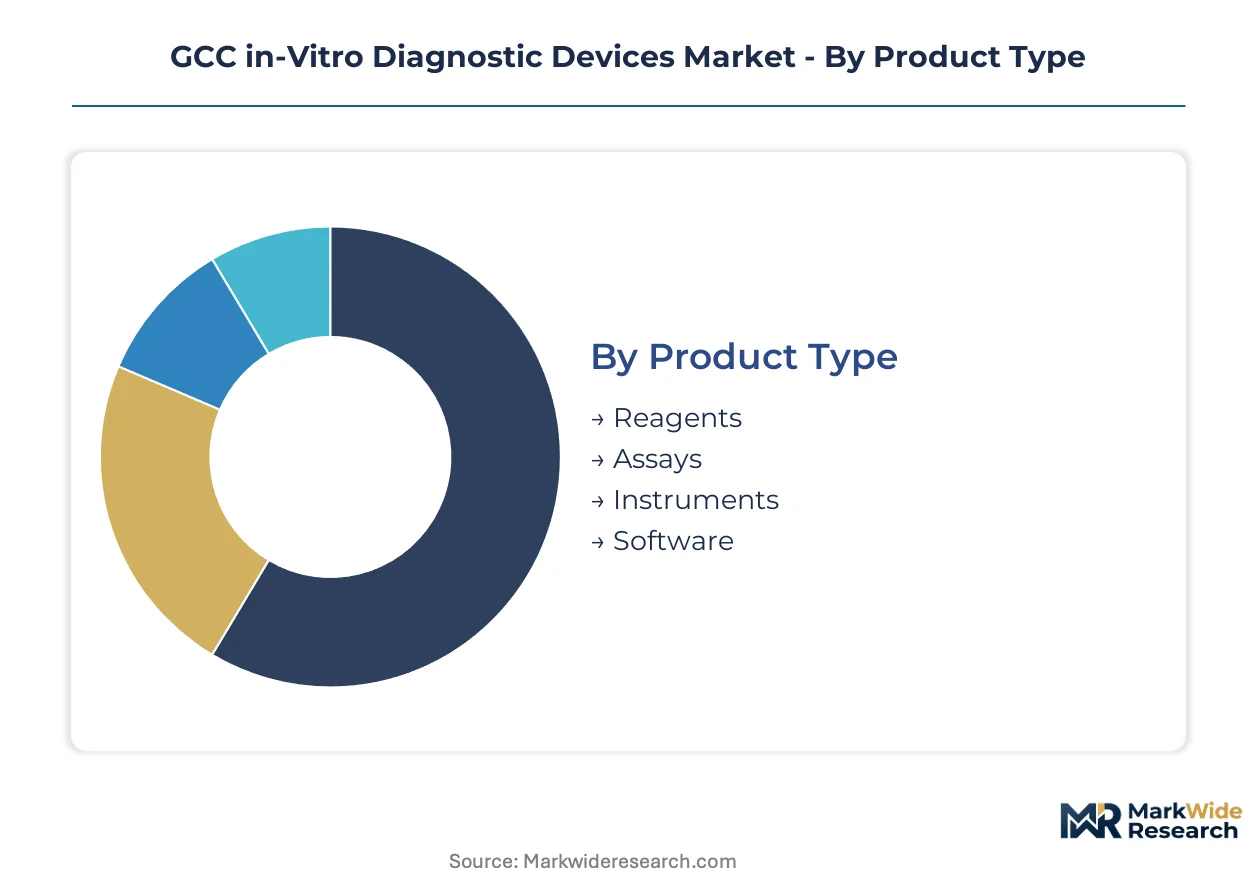
Diagnostic procurement across Saudi Arabia and the UAE follows distinct technical and operational logics that reshape how reagent manufacturers and platform vendors allocate commercial resources. Segmentation clarity enables suppliers to match product configurations against specific compliance burdens and throughput requirements.
Product Type:
Use-case spectrum spans disposable consumables with recurring revenue profiles to capital-intensive platforms requiring multi-year financing structures.
- Reagents:Liquid and lyophilized formulations enable enzymatic, immunologic, or nucleic acid detection reactions on automated analyzers. Demand concentrates in Saudi Arabia's hospital network modernization where batch-level SFDA traceability requirements favor suppliers with localized quality control infrastructure.
- Assays:Pre-configured test kits combine reagents, calibrators, and controls for specific biomarker quantification. UAE diagnostic lab privatization drives procurement of cardiac and diabetes panels that integrate with existing chemistry platforms.
- Instruments:Automated analyzers range from compact point-of-care units to high-throughput systems processing thousands of samples daily. SFDA registration pathway tightening compresses the competitive field to operators capable of sustaining localized technical support teams.
- Software:Laboratory information system modules and data management platforms ensure regulatory compliance and workflow optimization. MOHAP's electronic registration portal mandates real-time post-market data submission capabilities.
Established volume favors reagents; emerging adoption favors software.
Delivery Mode:
Cost tier separation distinguishes capital-intensive centralized infrastructure from distributed low-complexity deployment.
- Point-of-Care:Bedside and near-patient devices deliver rapid results in emergency and perioperative settings. Saudi primary care centers are accelerating deployment of immunoassay instruments for diabetes and cardiovascular screening.
- Laboratory-Based:Centralized facilities with trained technologists and quality control systems handle high-complexity molecular diagnostics. UAE private hospital groups are consolidating send-out testing onto in-house high-throughput systems.
- Home Use:Self-testing devices for glucose monitoring and infectious disease screening. Regulatory frameworks for direct-to-consumer diagnostics remain underdeveloped across Gulf health systems.
- Telemedicine:Remote diagnostic workflows integrating digital pathology and virtual consultation platforms. AI-integrated image analysis is opening premium service tiers in UAE private hospital networks.
Capital deployment concentrates in laboratory-based infrastructure; patient convenience pressures are expanding point-of-care.
End User:
Customer type determines procurement authority structure and contract duration expectations.
- Hospitals:Integrated health systems with consolidated procurement through Ministry of Health tendering platforms. Saudi Arabia's National Guard Health Affairs awards multi-year exclusive supply contracts to single-source providers.
- Clinics:Outpatient facilities with lower testing volumes and limited capital budgets. Point-of-care substitution is capturing low-complexity testing previously routed to centralized laboratories.
- Diagnostic Labs:Independent reference laboratories and hospital-affiliated facilities. Digital PCR and next-generation sequencing platforms are collapsing the historical revenue base of esoteric test franchises.
- Research Institutes:Academic and translational research centers with specialized assay requirements. Molecular diagnostics specialization requires training pipelines that Gulf universities have not yet scaled to match instrument installation rates.
Procurement scale favors hospitals; flexibility requirements favor diagnostic labs.
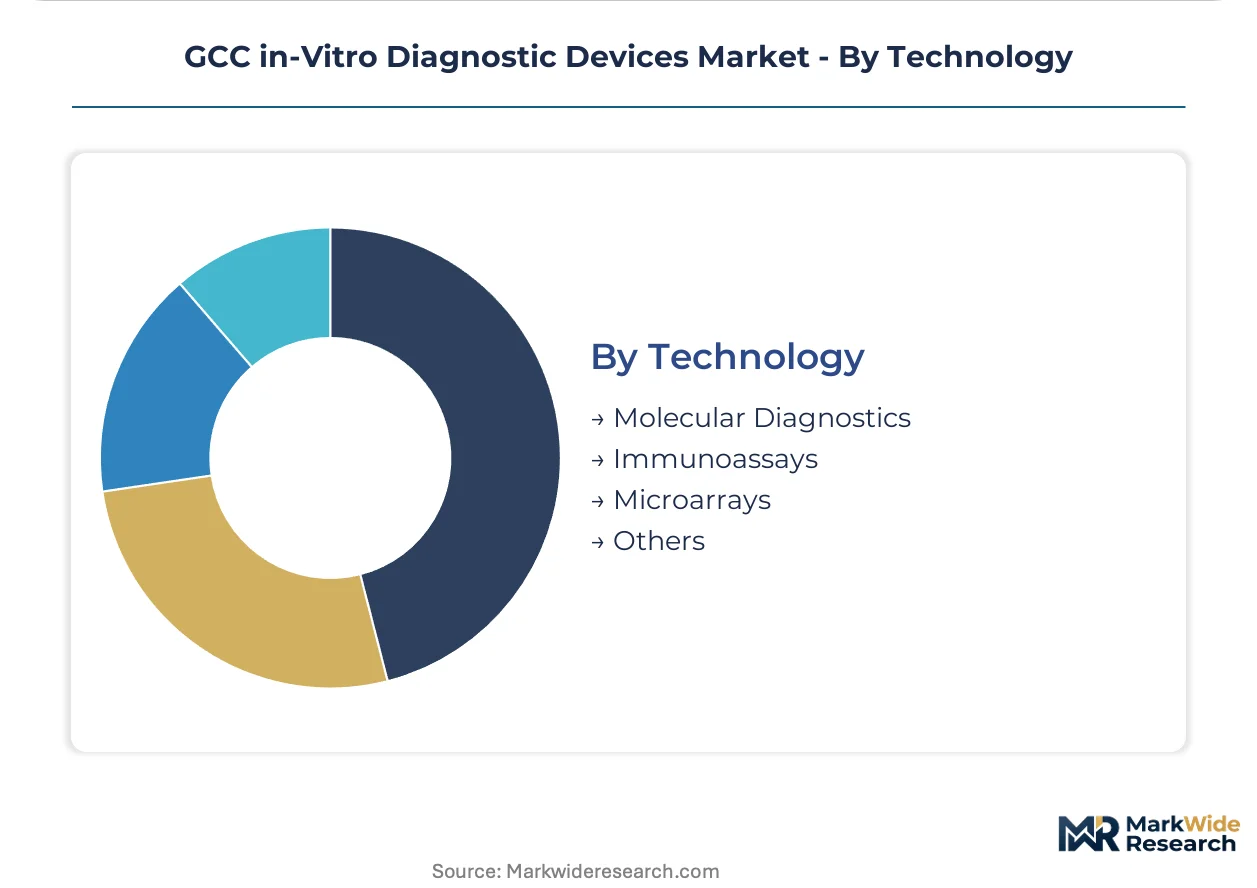
Technology:
Maturity gradient separates established immunochemistry from emerging genomic platforms.
- Molecular Diagnostics:PCR, digital PCR, and next-generation sequencing platforms for nucleic acid detection. Gulf health systems are prioritizing genomic pathogen identification as the core capability for infectious disease response.
- Immunoassays:Antibody-antigen binding reactions for protein and hormone quantification. Chemistry and immunoassay platform categories show the most visible buyer concentration through installed base lock-in.
- Microarrays:High-density probe arrays for multiplexed genetic analysis. Applications in pharmacogenomics and oncology biomarker profiling remain limited by reimbursement frameworks.
- Others:Cytometry, mass spectrometry, and electrochemical detection systems. BIS-equivalent conformity processes in Kuwait and Qatar delay multinational entry for novel platform categories.
Revenue stability favors immunoassays; steepest expansion trajectory belongs to molecular diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration pathway tightening and MOHAP procurement centralization are redistributing diagnostic device demand across Gulf health systems. National modernization programs in Saudi Arabia and the UAE absorb the majority of capital deployment, while smaller markets present first-mover openings for compliant operators.
Saudi Arabia
Hospital network modernization under the Ministry of Health drives demand for high-throughput molecular analyzers and chemistry platforms. SFDA enforces batch-level traceability requirements for reagent imports, filtering out uncertified suppliers. Riyadh and the Eastern Province concentrate instrument installation as National Guard Health Affairs consolidates testing volumes onto in-house systems.
United Arab Emirates
Diagnostic lab privatization and MOHAP's revised tender evaluation frameworks favor reagent kit localization partnerships. The electronic registration portal mandates real-time post-market data submission capabilities for market access. Dubai and Abu Dhabi private hospital groups are consolidating send-out testing through imaging-integrated diagnostics workflows.
Kuwait
BIS-equivalent conformity processes have delayed multinational entry, leaving the private lab sector underpenetrated relative to regional peers. The national pharmaceutical regulator maintains technical documentation requirements that favor established operators with dedicated regulatory affairs teams. Kuwait City medical districts show accelerating demand for point-of-care deployment in emergency settings.
Qatar
Hamad Medical Corporation standardization initiatives award multi-year exclusive supply contracts to single-source providers in chemistry and immunoassay categories. The central health authority prioritizes PCR platform standardization for infectious disease response capabilities. Doha medical city clusters concentrate high-complexity molecular diagnostics capacity.
Oman
Ministry of Health directives on chronic disease surveillance are expanding diabetes and cardiovascular screening programs into primary care networks. Procurement centralization through national tendering platforms compresses vendor counts per diagnostic category. Muscat and surrounding governorates anchor laboratory infrastructure development as health system modernization extends beyond capital cities.
GCC in-Vitro Diagnostic Devices Market Key Industry Players
On the supply side, the industry is consolidating around capital-backed operators capable of sustaining multi-year compliance investments across SFDA and MOHAP jurisdictions. Three archetypes dominate: multinational platform manufacturers leveraging installed base lock-in, regional distributors with localized technical support infrastructure, and emerging domestic production partnerships capturing reagent localization incentives. Competitive survival depends on securing exclusive supply contracts through Ministry tendering platforms and defending service relationships against point-of-care substitution.
Within the multinational tier, Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers occupy positions shaped by platform-specific installed bases and imaging-integrated workflow capabilities. These companies exemplify the capital-backed operator archetype that Gulf procurement centralization favors, anchoring their market presence through multi-year service contracts rather than episodic instrument sales. Regional specialists including Al-Borg Diagnostics represent the localization-focused tier, capturing procurement preferences under revised UAE tender frameworks.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Beckman Coulter |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Sysmex Corporation |
| Al-Borg Diagnostics |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Import dependency for German and Japanese precision optical components exposes analyzer margins to euro-yen volatility, compressing pricing spreads between premium CE-IVD certified systems and standard-grade alternatives while simultaneously forcing distributors toward multi-year service bundling to stabilize revenue streams.
Pricing Analysis
Certification level creates the primary spread between SFDA-registered premium tiers and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects batch-level traceability compliance costs and localized technical support infrastructure investments. Cost compression in the standard tier is intensifying because MOHAP's electronic registration portal extends exclusion periods for documentation-deficient suppliers. Hospital procurement committees exhibit the lowest price sensitivity due to multi-year exclusive supply contract structures, while independent diagnostic labs face acute margin pressure from point-of-care substitution.
Supply Chain Analysis
Precision lens manufacturing feeds from German and Japanese optical component suppliers, with reagent formulation chemistry anchored in US and European specialty chemical production. German and Japanese suppliers dominate high-throughput analyzer optical subsystems, while reagent raw materials draw from US enzymatic substrate and European antibody production. Single-source vulnerability concentrates in precision lens supply, where limited qualified vendors create procurement bottlenecks during currency volatility episodes. Distribution runs through Ministry of Health tendering platforms and private hospital group consolidated procurement offices, with regional distributors maintaining localized quality control infrastructure for SFDA batch traceability compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization through Ministry tendering platforms is concentrating buyer power among a shrinking cohort of capital-backed hospital networks and private lab groups, fragmenting vendor access for mid-tier suppliers unable to sustain multi-year compliance investments.
For Market Incumbents: Build installed base lock-in through exclusive multi-year service contracts spanning chemistry and immunoassay platform categories. Deepen backward integration into reagent manufacturing partnerships in the UAE to capture localization incentives under MOHAP's revised tender frameworks. Defend against point-of-care substitution by integrating emergency department rapid triage workflows into existing laboratory information system architectures. For New Entrants and Emerging Players: Establish a beachhead in Kuwait's underpenetrated private lab sector where BIS-equivalent conformity processes have delayed multinational entry. Target AI-integrated digital pathology workflows in UAE private hospital groups as the most penetrable premium service tier. Pursue regulatory affairs team acquisition as the critical go-to-market angle to compress SFDA approval timelines against documentation-deficient competitors. For Investors and Strategic Acquirers: SFDA and MOHAP harmonization initiatives reshaping registration reciprocity reshape the acquisition landscape toward regulatory affairs capability scarcity. Long-term viability across the analysis window hinges on securing exclusive supply relationships with National Guard Health Affairs or Hamad Medical Corporation standardization programs. Acquisition target archetype: regional distributors with established Gulf regulatory affairs teams and localized quality control infrastructure. Watch for PCR platform standardization mandates as the inflection signal indicating infectious disease response budget allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Batch-level traceability compliance filters out uncertified competitors from Saudi hospital procurement. |
| Reagent Kit Localization Partnership | MOHAP's revised tender evaluation frameworks award procurement preference to domestic production alliances. |
| AI-Integrated Diagnostics Workflow Development | Machine learning algorithms paired with digital pathology open premium service tiers in UAE private hospital groups. |
| Point-of-Care Emergency Department Deployment | Perioperative rapid triage instruments capture testing volumes from centralized laboratories in Saudi modernization programs. |
| Multi-Year Exclusive Supply Contract Negotiation | Ministry tendering platform consolidation awards single-source relationships that determine competitive survival. |
Research Approach
The analysis maps reagent manufacturing, instrument platforms, software modules, and service contracts, each validated through laboratory directors, biomedical engineers, hospital purchasing committees, and regulatory affairs specialists. Primary interviews with GPO contracts managers and diagnostic lab procurement leads combined with secondary validation against SFDA registration databases, MOHAP electronic portal filings, hospital procurement records, and Gulf customs trade data. Bottom-up reagent volume modeling and top-down analyzer installation forecasts were triangulated against service contract disclosure patterns.
Assumptions held fixed include SFDA and MOHAP regulatory pathway stability, euro-yen exchange rate bands within historical volatility ranges, and chronic disease surveillance mandate continuity across Gulf health ministries. Segmentation dimensions modeled span product type, delivery mode, end user category, and technology maturity tier alongside molecular diagnostics specialization depth. CAGRs were derived from instrument installation rate projections and reagent consumption per analyzer metrics, with PCR platform standardization timelines and point-of-care substitution velocity as key forecast inputs.
Stress conditions across currency volatility, regulatory approval timeline extension, and point-of-care technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of procurement centralization continuity and chronic disease surveillance mandate persistence, with revision risk from Gulf harmonization initiative acceleration or molecular diagnostics training pipeline scaling failures. Cross-checking against hospital capital expenditure disclosure patterns and Ministry of Health tender award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Febrile Antigen Kits Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Extraction Kits Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market