
 France Continuous Glucose Monitoring Market | 2026-2036
France Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
France Continuous Glucose Monitoring Market Insights
France's Medical Device Regulation (MDR) alignment with EU MDR is restructuring the cost-of-entry calculus for glucose monitoring manufacturers seeking CE marking renewal. Abbott Laboratories leverages its FreeStyle Libre manufacturing footprint to sustain pharmacy channel dominance across French regions. Dexcom Inc. anchors its competitive position through specialized distribution partnerships with hospital procurement networks. Medtronic plc competes by integrating its CGM platform with automated insulin delivery systems for Type 1 diabetes management.
Continuous glucose monitoring comprises wearable sensor systems that measure interstitial glucose levels via enzymatic electrochemical reactions, typically sampling every one to fifteen minutes and transmitting data to receivers or smartphones for real-time glycemic management. Flash glucose monitoring occupies the largest installed base among French patients due to reimbursement familiarity and pharmacy accessibility, while real-time continuous glucose monitoring represents the fastest-expanding category as closed-loop insulin delivery gains traction in hospital settings. Proprietary algorithms differentiate performance tiers, with cloud-based solutions emerging as a margin pool for data analytics and remote patient monitoring services.
ANSM enforces post-market surveillance obligations that shape product lifecycle requirements for glucose sensors marketed in France, while HAS evaluates clinical benefit ratings that directly determine reimbursement levels and patient access. The EU AI Act will impose additional conformity obligations on algorithm-driven glucose prediction features, affecting development timelines for next-generation systems. Stakeholders must monitor evolving reimbursement criteria for non-invasive sensor technologies and prepare for potential MDR audit intensification affecting legacy device certifications.
Market Dynamics
The France Continuous Glucose Monitoring Market pivots on the HAS reimbursement framework's expansion of real-time system coverage, which is accelerating hospital procurement cycles and compressing the adoption gap between flash and continuous monitoring modalities.
Growth Catalysts
- HAS Reimbursement Expansion:The French national health authority's clinical benefit ratings for diabetes technology are unlocking broader patient access to real-time glucose sensors through updated reimbursement tiers.
- Hospital Procurement Networks:Specialist diabetes centers in the Paris-Ile-de-France corridor are consolidating purchasing power and driving volume commitments for integrated CGM-insulin delivery systems.
- Closed-Loop Algorithm Maturation:Predictive glucose control software is enabling automated insulin adjustment protocols that reduce hypoglycemic events in Type 1 diabetes management.
Market Restraints
- MDR Certification Costs:EU MDR alignment requirements for glucose sensor CE marking renewal are elevating regulatory compliance expenditures and extending time-to-market for next-generation devices.
- Sensor Manufacturing Concentration:Enzymatic electrochemical sensor production relies on specialized contract manufacturers concentrated in Western European supply clusters, creating single-source vulnerability.
- Flash Glucose Familiarity:Pharmacy-channel accessibility and established patient workflows around intermittent scanning systems create inertia against real-time continuous monitoring migration.
Strategic Opportunities
- Remote Patient Monitoring Services:Cloud-based glucose data analytics platforms are opening recurring revenue streams through subscription models for endocrinology practices and telemedicine providers.
- EU AI Act Algorithm Certification:Early compliance with forthcoming conformity obligations for glucose prediction features will create first-mover positioning in algorithm-driven device categories.
- Non-Invasive Sensor Pathways:Optical and microwave sensing technologies under HAS pilot evaluation protocols represent white-space expansion beyond current enzymatic electrochemical standards.
Industry Challenges
- Data Science Talent Scarcity:Algorithm development for glucose prediction requires specialized machine learning expertise that competes with broader medtech and pharmaceutical hiring pools.
- Legacy System Interoperability:Integration of new CGM platforms with existing hospital electronic health record architectures and insulin pump fleets demands customized middleware development.
- Post-Market Surveillance Burden:ANSM adverse event reporting obligations for glucose sensors impose ongoing clinical data collection costs that scale with installed base expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Continuous Glucose Monitoring Market |
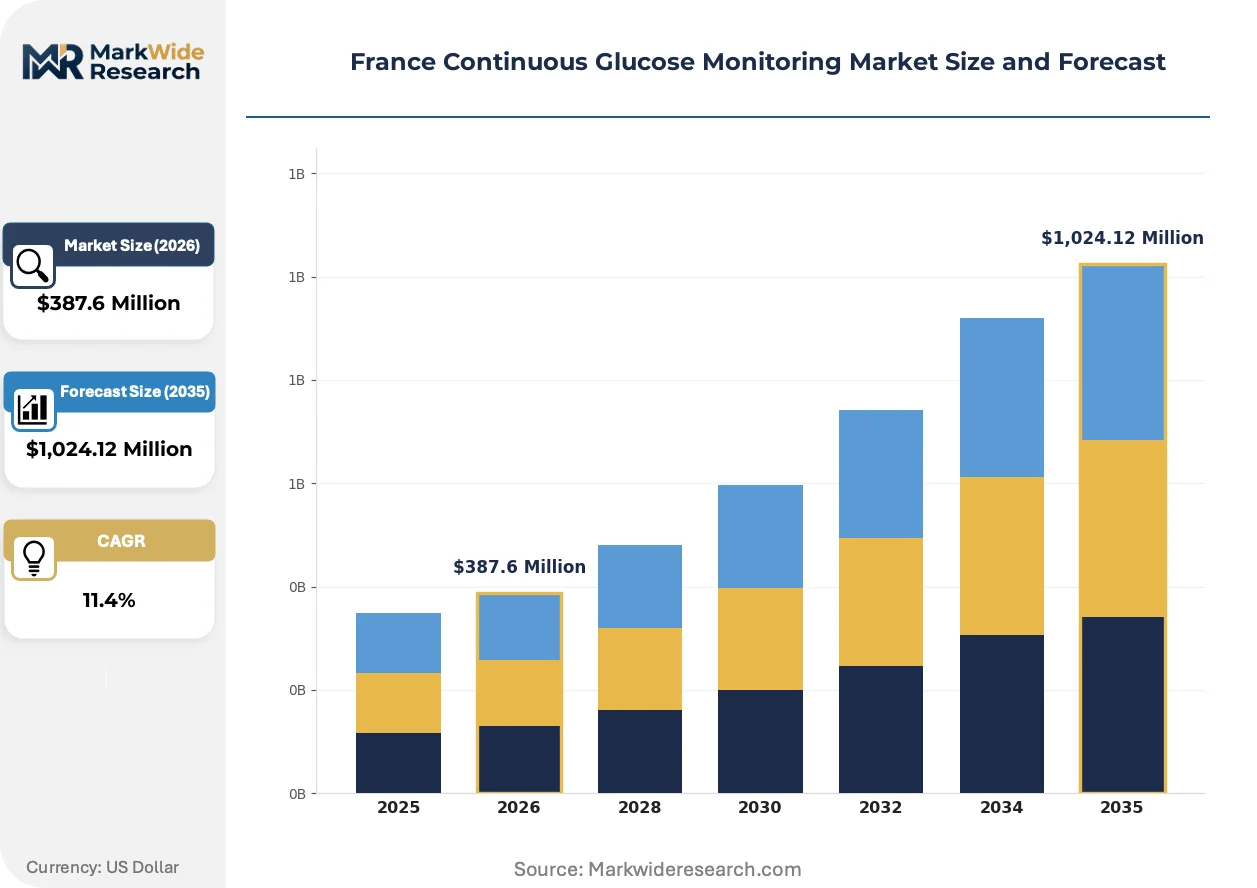
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitoring, Real-Time Continuous Glucose Monitoring, Wearable Sensors, Mobile Applications End User: Hospitals, Clinics, Homecare, Diabetes Patients Technology: Non-Invasive Sensors, Invasive Sensors, Cloud-Based Solutions, Proprietary Algorithms Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Distributors |
| Companies Covered | Abbott Laboratories, Dexcom Inc., Medtronic plc, Ascensia Diabetes Care, Glysens, Roche Diabetes Care Inc., Insulet Corporation, Senseonics Holdings Inc., Tandem Diabetes Care Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Continuous Glucose Monitoring Market Trends and Innovations
Algorithmic glucose prediction and cloud-native data architectures are displacing standalone receiver hardware, while regulatory frameworks for artificial intelligence reshape development roadmaps and reimbursement criteria evolve to capture remote monitoring value.
Real-time continuous glucose monitoring systems are expanding into hospital-based automated insulin delivery protocols. Endocrinology departments in French tertiary care centers are adopting these platforms for inpatient glycemic management. The technology is expanding into closed-loop systems that compress nursing workload and reduce adverse event liability.
The EU AI Act imposes conformity assessment obligations on machine learning-driven glucose prediction features. Manufacturers must document algorithm training datasets and performance validation protocols for notified body review. French CGM developers are responding by restructuring quality management systems to incorporate AI lifecycle documentation ahead of implementation deadlines.
Pharmacy distribution for flash glucose systems is facing pressure from direct-to-patient subscription models for real-time continuous monitoring. Hospital procurement networks are consolidating vendor relationships through specialized distribution partnerships that bypass traditional wholesale channels. This channel rotation is most visible in the Paris-Ile-de-France metropolitan corridor where specialist diabetes centers cluster and purchasing coordination is strongest.
France Continuous Glucose Monitoring Market Segmentation
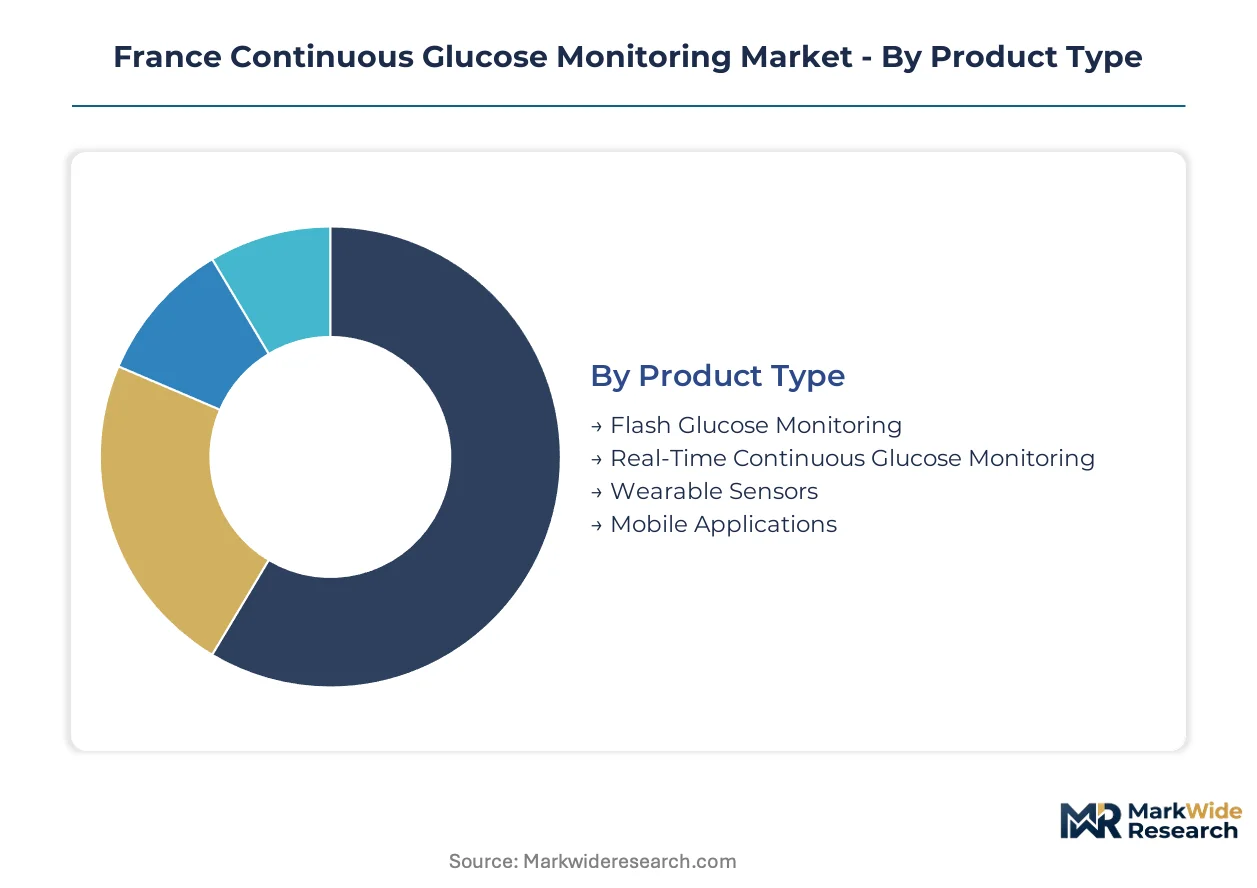
Segmentation reveals how HAS reimbursement tiers and patient access pathways split demand across device categories. Hospital procurement networks and pharmacy channel dynamics create divergent growth trajectories within each dimension.
Product Type:
Replacement cycles accelerate as patients migrate from intermittent scanning toward automated glucose control systems.
- Flash Glucose Monitoring:Enzymatic electrochemical sensors store glucose readings for retrospective review via handheld reader or smartphone scan. Pharmacy-channel accessibility across French regions sustains the largest installed patient base, though reimbursement familiarity now creates inertia against real-time migration.
- Real-Time Continuous Glucose Monitoring:Systems transmit glucose data every one to fifteen minutes to receivers or smartphones without patient-initiated scanning. Hospital end users in the Paris-Ile-de-France corridor are consolidating purchasing power around these platforms for closed-loop insulin delivery protocols.
- Wearable Sensors:Adhesive patch form factors integrate transmitter electronics with enzymatic sensing elements.
- Mobile Applications:Software platforms aggregate glucose data streams and generate predictive alerts for hypoglycemic events.
Volume placements concentrate in Flash Glucose Monitoring; the faster expansion belongs to Real-Time Continuous Glucose Monitoring.
End User:
Cost tiers separate institutional procurement from out-of-pocket patient spending.
- Hospitals:Tertiary care centers and specialist diabetes units deploy integrated CGM-insulin delivery systems for inpatient glycemic management. The Paris-Ile-de-France metropolitan corridor clusters the highest concentration of these adoption sites.
- Clinics:Endocrinology practices prescribe CGM systems and bill through HAS reimbursement frameworks.
- Homecare:Patients manage diabetes outside clinical settings using pharmacy-dispensed sensors.
- Diabetes Patients:Individual consumers purchase devices through direct-to-patient subscription models or retail channels.
Procurement volumes cluster in Hospitals; Homecare represents the broadest addressable population base.
Technology:
Application requirements determine sensor invasiveness and data processing architecture.
- Invasive Sensors:Subcutaneous needle-based probes measure interstitial glucose via enzymatic electrochemical reaction. HAS reimbursement coverage for these devices drives hospital procurement decisions across French diabetes centers.
- Proprietary Algorithms:Machine learning models predict glucose trajectories and automate insulin dosing recommendations. ANSM post-market surveillance obligations and forthcoming EU AI Act conformity requirements are extending development timelines for French manufacturers.
- Non-Invasive Sensors:Optical and microwave sensing technologies remain under HAS pilot evaluation protocols.
- Cloud-Based Solutions:Remote data architectures enable telemedicine integration and recurring analytics subscriptions.
Installed base dominance sits with Invasive Sensors; Proprietary Algorithms are climbing the fastest as closed-loop systems mature.
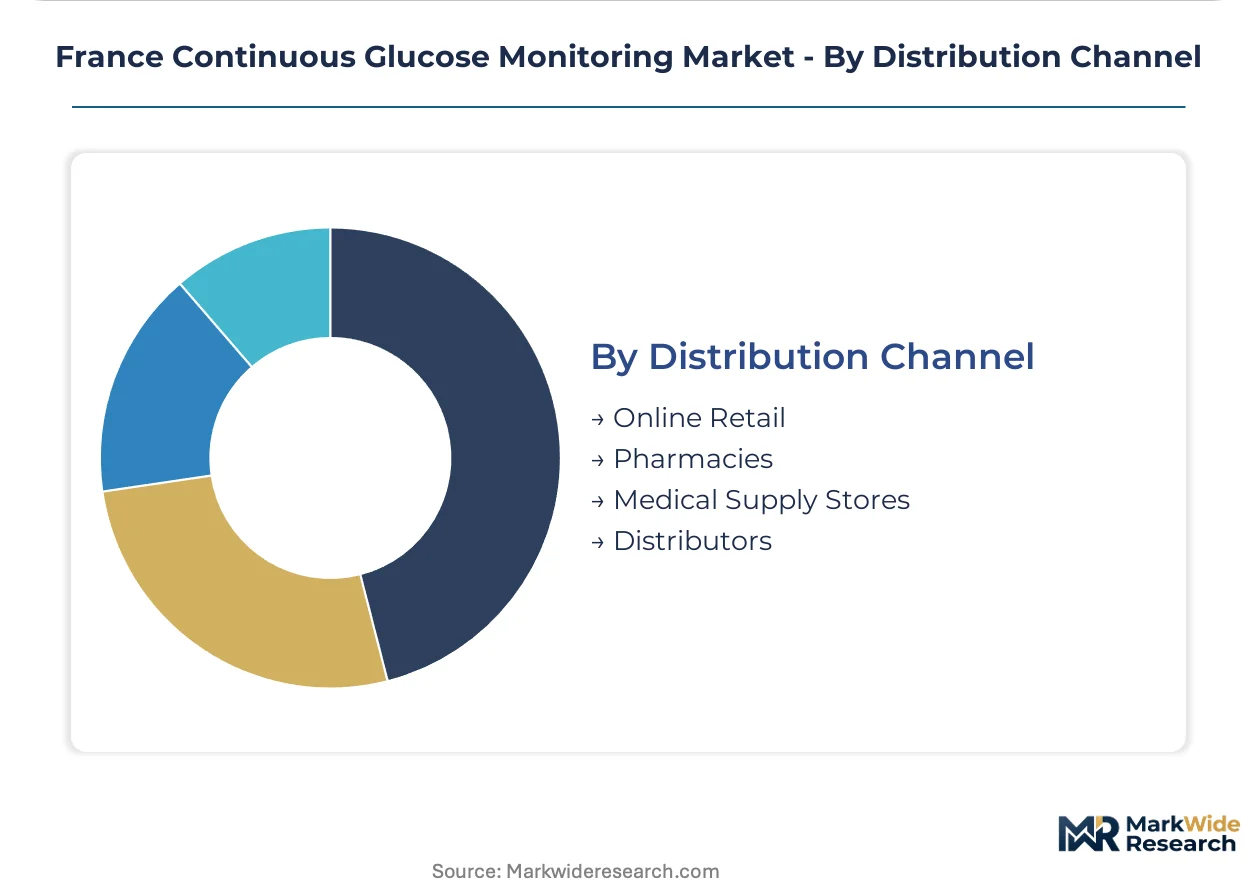
Distribution Channel:
Customer type and purchase scale rotate channel selection.
- Pharmacies:Community retail outlets dispense flash glucose sensors with HAS reimbursement processing. Established patient workflows and pharmacist counseling relationships sustain channel loyalty despite emerging subscription alternatives.
- Distributors:Specialized medical supply wholesalers serve hospital procurement networks with volume pricing and logistics coordination. These partnerships bypass traditional retail channels in the Paris-Ile-de-France corridor where purchasing consolidation is strongest.
- Online Retail:E-commerce platforms enable direct-to-patient sensor replenishment.
- Medical Supply Stores:Regional outlets provide equipment and patient education services.
Transaction volume flows through Pharmacies; Distributors capture the highest-value institutional contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand concentrates in metropolitan corridors where specialist diabetes centers cluster and HAS reimbursement frameworks operate most efficiently. Regional adoption patterns diverge based on hospital procurement network density and pharmacy channel penetration.
Île-de-France
The Paris metropolitan corridor hosts France's densest concentration of tertiary diabetes centers and endocrinology research hospitals. HAS reimbursement processing operates with maximum efficiency here, accelerating real-time CGM adoption for closed-loop insulin delivery protocols. Hospital procurement networks in Paris and surrounding departments consolidate purchasing power around integrated CGM-insulin systems.
Auvergne-Rhône-Alpes
Lyon anchors the second-largest regional cluster of diabetes specialists and medical device distribution infrastructure. The region's hospital networks participate in national HAS pilot programs for next-generation glucose monitoring technologies. Grenoble's medical technology research ecosystem supports algorithm development for predictive glucose control systems.
Provence-Alpes-Côte d'Azur
Marseille and Nice maintain significant endocrinology patient populations with strong pharmacy-channel penetration for flash glucose systems. Regional hospitals are expanding real-time CGM procurement for inpatient glycemic management. ANSM post-market surveillance obligations apply uniformly across this southern corridor.
Hauts-de-France
Lille's university hospital system drives institutional adoption of continuous glucose monitoring for Type 1 diabetes management. The region exhibits growing demand for remote patient monitoring services linked to cloud-based glucose data platforms. Specialized distributors serve hospital procurement networks across the northern departments.
Nouvelle-Aquitaine
Bordeaux's diabetes care infrastructure supports balanced adoption across flash and real-time monitoring modalities. Regional endocrinology practices bill through HAS reimbursement frameworks with varying coverage tiers. The area represents emerging demand for non-invasive sensor technologies under pilot evaluation protocols.
France Continuous Glucose Monitoring Market Competitive Landscape
US-based producers anchor one tier of the market structure; European specialists hold differentiated positions through regulatory proximity and reimbursement relationships. The competitive field organizes around three strategic archetypes: integrated medtech conglomerates with automated insulin delivery platforms, standalone CGM specialists with algorithm-intensive offerings, and diabetes care divisions of broader pharmaceutical groups. Dominant competitive moves include specialized distribution partnerships with hospital procurement networks and restructuring of quality management systems to incorporate EU AI Act lifecycle documentation.
Among US-based medical technology groups, Abbott Laboratories, Dexcom Inc., and Medtronic plc occupy anchor positions that exemplify contrasting strategic postures. Abbott represents the pharmacy-channel dominance archetype through manufacturing footprint advantages. Dexcom exemplifies the hospital-network specialization model through targeted distribution partnerships. Medtronic sits within the integrated-systems tier by combining glucose monitoring with automated insulin delivery platforms. These three entities collectively represent the competitive spectrum from intermittent scanning familiarity to closed-loop automation maturity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| Medtronic plc |
| Ascensia Diabetes Care |
| Glysens |
| Roche Diabetes Care Inc. |
| Insulet Corporation |
| Senseonics Holdings Inc. |
| Tandem Diabetes Care Inc. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement network consolidation across the Paris-Ile-de-France corridor is compressing vendor margins and forcing manufacturers to restructure production economics around volume-commitment contracts.
Pricing Analysis
Volume commitments in hospital procurement networks trade margin for installed base expansion, while pharmacy-channel flash systems sustain premium per-unit economics through patient self-pay segments. Price differentiation hinges on HAS reimbursement tier alignment and algorithm-driven predictive capability certification. Pricing pressure stems from MDR compliance cost recovery requirements passed through to institutional buyers. Homecare patients exhibit highest price sensitivity; tertiary care centers demonstrate lowest sensitivity due to bundled procurement budgets.
Supply Chain Analysis
Direct-to-hospital distribution channels handle institutional volume demand, bypassing wholesale intermediaries in concentrated metropolitan corridors. Sensor manufacturing concentrates in Germany, Ireland, and the Netherlands, with enzymatic electrode production anchored in specialized Western European contract facilities. Raw material dependencies include platinum-group catalysts, medical-grade adhesives, and biocompatible polymers. Single-source vulnerability in electrochemical sensor membrane supply creates exposure to batch contamination events. Distribution runs through specialized medical supply wholesalers serving consolidated hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time continuous glucose monitoring systems are displacing flash glucose familiarity as closed-loop insulin delivery protocols mature in French tertiary care settings.
For Market Incumbents: Extend manufacturing footprint flexibility to absorb MDR audit intensification costs without pricing disruption. Deepen backward integration into enzymatic sensor component production to reduce single-source membrane supply exposure. Anchor capacity in Western European regulatory proximity zones to compress CE marking renewal timelines. For New Entrants and Emerging Players: EU AI Act algorithm certification requirements in Europe open a window for first-mover positioning in predictive glucose control software categories. Target cloud-based remote patient monitoring services as the most penetrable white-space segment, where subscription economics bypass established pharmacy channel loyalty. Pursue specialized distribution partnerships with hospital procurement networks in the Auvergne-Rhône-Alpes corridor as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-intensive CGM specialists given EU AI Act conformity timeline acceleration. Long-term viability across the projection horizon favors developers with integrated quality management systems incorporating AI lifecycle documentation. Acquisition target archetype: standalone software platforms with validated glucose prediction algorithms and ANSM adverse event reporting infrastructure. Monitor HAS pilot program outcomes for non-invasive sensor technologies as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithm Certification | Early conformity documentation accelerates notified body review timelines for predictive glucose features. |
| Hospital System Partnership | Specialized distribution agreements with Paris-Ile-de-France procurement networks secure volume commitments. |
| Software Companion Development | Cloud-native analytics platforms unlock recurring revenue through endocrinology practice subscriptions. |
| CE Marking Pathway | MDR alignment for glucose sensor renewal determines time-to-market for next-generation device launches. |
| Reimbursement Strategy | HAS clinical benefit rating optimization directly expands patient access to real-time monitoring systems. |
Research Methodology
Independent corroboration across hospital procurement managers, endocrinology practice administrators, biomedical engineers, and GPO contracts specialists underwrites the qualitative findings. Secondary validation draws from ANSM post-market surveillance databases, HAS reimbursement registry filings, EU MDR notified body documentation, and hospital equipment procurement records. Bottom-up installed base estimates triangulate against top-down HAS expenditure flows.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon. Segmentation modeling incorporates product type, end user institution tier, technology invasiveness level, and distribution channel structure. CAGRs derive from patient population growth, reimbursement tier expansion velocity, and technology substitution rates. Forecast inputs include HAS pilot program enrollment trajectories and EU AI Act implementation timeline assumptions.
Caveats apply where MDR audit intensification delays or HAS reimbursement tier revisions could materially shift the outlook. Forecasts reflect base-case assumptions regarding algorithm validation pathway clarity and hospital procurement network stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Russia Diabetes Care Devices Market