
 Surgical Robot Accessories Market | 2026-2036
Surgical Robot Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Robot Accessories Market Analytics
Hospital procurement of robotic surgical suites is consolidating around multi-specialty platforms, with fewer buyers commanding larger contract volumes. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring revenue from proprietary end effectors. Stryker anchors its position through Mako platform accessories that dominate orthopedic robotics. Medtronic competes via its Hugo ecosystem, which navigates open-console architectures to differentiate service models.
Surgical robot accessories encompass the disposable and reusable components that interface with robotic manipulators, including end effectors fabricated from surgical-grade stainless steel and polymer composites rated for autoclave sterilization cycles exceeding 500 uses, serving to translate surgeon hand motions into precise instrument articulation during minimally invasive procedures. End effectors capture the dominant margin pool due to their disposable nature and procedure-specific designs, while camera systems lead replacement velocity as 4K and 3D visualization standards displace legacy optics. Instrument trays retain structural importance in orthopedic applications where sterilization logistics and tray configuration complexity create switching costs for integrated systems.
FDA 510(k) clearance requirements govern accessory compatibility claims in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for CE marking of robotic surgical components. ISO 13485 quality management standards shape supplier qualification across both jurisdictions, filtering contract manufacturers by traceability and risk management capabilities. Stakeholders must monitor how FDA breakthrough device designations for autonomous subsystems may reclassify accessory interfaces and alter competitive moats around proprietary instrument ecosystems.
Market Dynamics
Hospital procurement consolidation around multi-specialty robotic platforms is compressing vendor ecosystems and amplifying switching costs for disposable instrument lines. This structural concentration rewards integrated accessory portfolios while marginalizing point-solution suppliers.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for predicate-based accessory submissions accelerate product iteration cycles and reduce time-to-revenue for instrument manufacturers targeting the United States.
- Academic medical center replacement demand:Aging da Vinci Si and X systems at tier-one hospitals drive synchronized refresh cycles for end effectors, camera heads, and sterilization containers.
- Polymer composite sterilization durability:Next-generation PEEK and carbon-fiber reinforced instruments rated for 500+ autoclave cycles reduce per-procedure material costs and extend instrument life.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and molybdenum input cost swings compress margin stability for instrument fabricators locked into multi-year hospital contracts.
- EU MDR clinical evidence thresholds:Stricter CE marking requirements for Class IIa and IIb robotic accessories extend validation timelines and elevate regulatory compliance expenditures.
- Open-source console architectures:Medtronic Hugo and competitive open-platform systems threaten proprietary instrument lock-in that sustains recurring revenue for integrated ecosystem vendors.
Strategic Opportunities
- India CDSCO regulatory harmonization:Convergence with IMDRF standards creates pathway for US-cleared accessories to enter Asia-Pacific's fastest-expanding robotic surgery market with reduced duplicate trials.
- Single-port instrument miniaturization:Next-generation 5mm end effectors for reduced-port procedures command premium positioning as surgeons pursue scar-minimization outcomes.
- Hospital-at-home reimbursement expansion:CMS innovation center waivers for outpatient robotic procedures in ambulatory surgical centers displace inpatient volume and concentrate demand for portable, sterilizable instrument sets.
Industry Challenges
- ISO 13485 supplier qualification bottlenecks:Traceability and risk management capability gaps among contract manufacturers delay component sourcing for new instrument launches.
- Cross-platform interoperability certification:Validating mechanical and electrical interfaces across da Vinci, Mako, and emerging Chinese robotic systems fragments engineering resources and extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Robot Accessories Market |
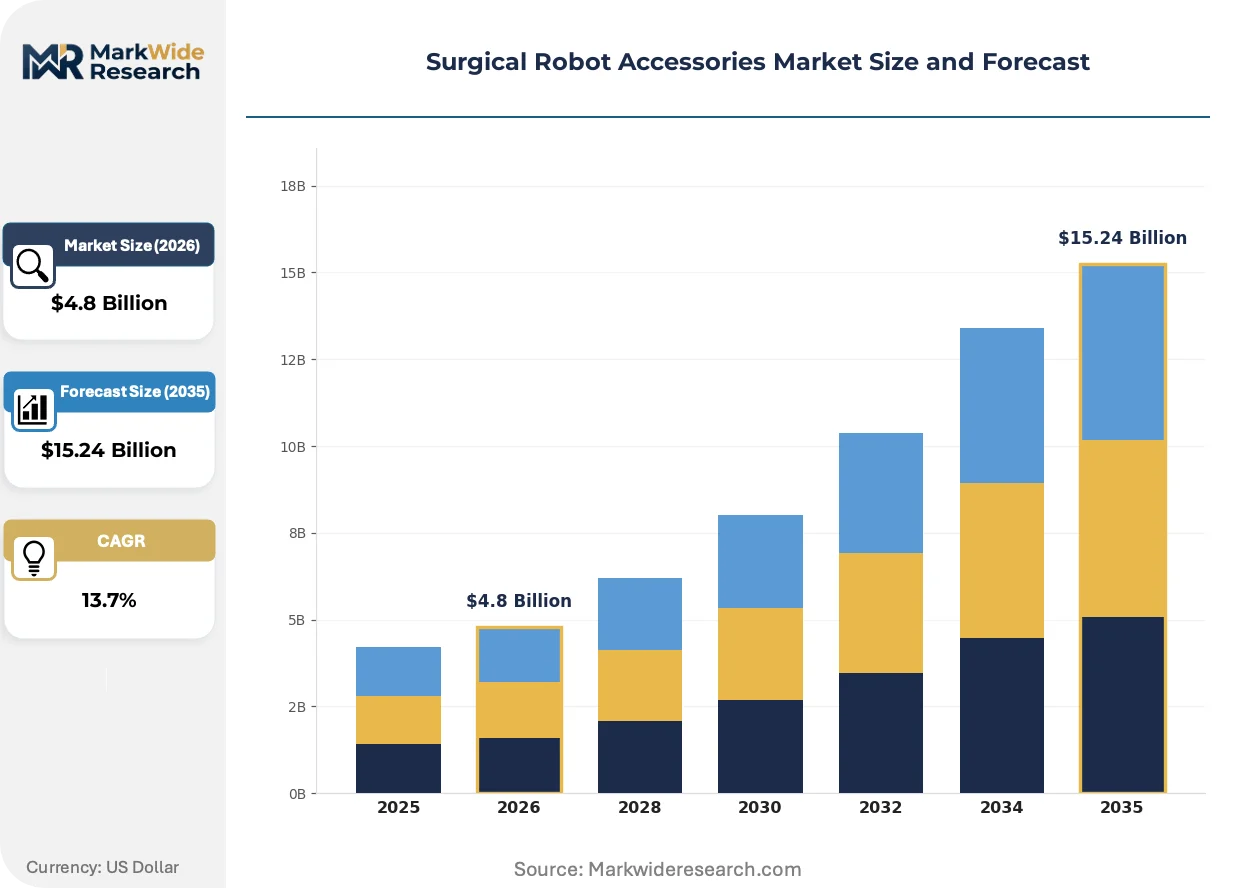
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End Effectors, Camera Systems, Instrument Trays, Control Consoles Technology: Robotic Systems, Visualization Tools, Surgical Software, Feedback Mechanisms End User: Hospitals, Outpatient Clinics, Surgical Centers, Research Institutions Application: Orthopedic Surgery, Urological Procedures, General Surgery, Cardiovascular Operations |
| Companies Covered | Intuitive Surgical, Stryker, Medtronic, Johnson & Johnson, Zimmer Biomet, Smith & Nephew, CMR Surgical, Asensus Surgical, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Robot Accessories Market Evolving Landscape
Haptic feedback integration and autonomous suturing subsystems are redefining instrument intelligence requirements. These developments compress the boundary between disposable accessories and capital equipment, forcing suppliers to recalibrate R&D allocation and service model architecture.
Force-sensing end effectors with sub-millimeter tactile resolution are absorbing precision-demanding procedures from open surgery into robotic platforms. Academic medical centers in the United States and Germany are piloting these instruments for microvascular anastomosis and nerve-sparing prostatectomy. The technology is absorbing high-complexity cases that previously required direct manual palpation, expanding addressable procedure volume for robotic systems.
EU Medical Device Regulation Article 10 clinical evaluation requirements are tightening post-market surveillance obligations for reusable instrument trays. Manufacturers must now maintain systematic literature review protocols and periodic safety update reports for orthopedic robotics accessories. The regulation is compressing competitive position for suppliers lacking dedicated clinical affairs infrastructure, favoring larger portfolio holders with established EU notified body relationships.
Consolidated purchasing through integrated delivery networks is displacing individual hospital procurement autonomy for robotic instrument contracts. IDNs in Texas, California, and Ohio are centralizing vendor selection and standardizing across multiple surgical service lines. This concentration is amplifying price transparency and compressing contract negotiation leverage for accessory suppliers serving fragmented independent hospitals.
Surgical Robot Accessories Market Segmentation
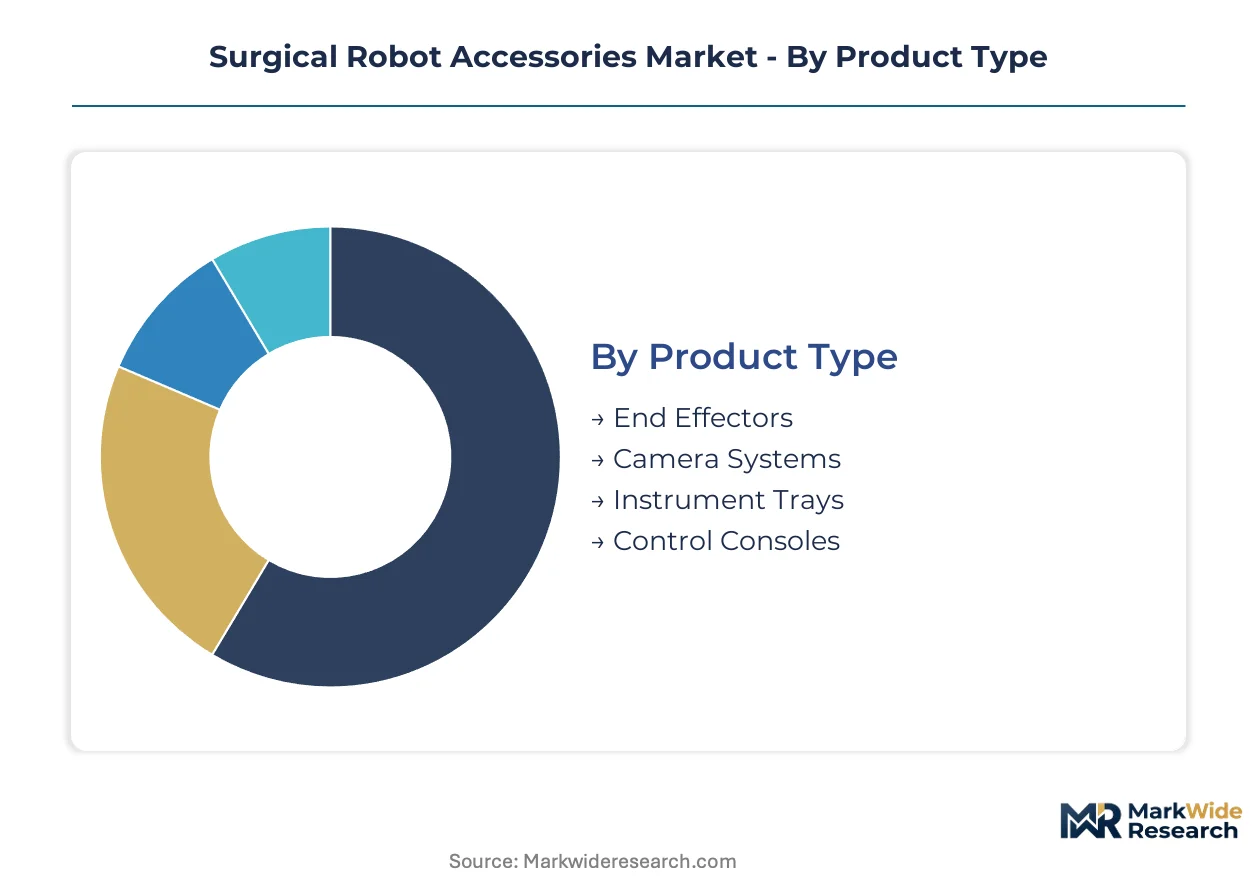
Accessory segmentation in surgical robotics determines procurement bundling strategies and regulatory pathways. Each dimension—product type, technology, end user, and application—carries distinct margin profiles and replacement velocities that shape supplier prioritization.
Product Type:
Supply concentration clusters around disposable instrument lines with recurring revenue models, while reusable capital components anchor platform lock-in.
- End Effectors:Fabricated from surgical-grade stainless steel and polymer composites rated for 500+ autoclave cycles, these instruments translate surgeon hand motions into precise articulation. Demand concentrates at academic medical centers in the United States where da Vinci system density drives synchronized replacement cycles for procedure-specific jaws and graspers.
- Camera Systems:4K and 3D visualization heads with autoclavable sterilization ratings displace legacy optics through replacement velocity. German university hospitals anchor European demand as visualization standards tighten for minimally invasive procedures.
- Instrument Trays:Sterilization logistics and tray configuration complexity create switching costs in orthopedic applications.
- Control Consoles:Surgeon interface hardware with haptic feedback integration spans capital equipment and accessory boundaries.
End effectors absorb the bulk of installed capacity; camera systems are expanding most quickly as visualization standards upgrade.
Technology:
Cost tier differentiation separates premium integrated platforms from modular point solutions, with software and feedback layers commanding recurring revenue premiums.
- Robotic Systems:Manipulator arms and joint assemblies with ISO 13485-certified component traceability. Japanese medical device manufacturers drive precision motor and sensor sourcing for next-generation platforms.
- Visualization Tools:4K and 3D camera heads with fluorescence imaging capabilities. South Korean display technology suppliers are gaining share in OLED surgical monitor integration.
- Surgical Software:Pre-operative planning and intraoperative navigation algorithms with FDA 510(k) predicate requirements.
- Feedback Mechanisms:Force-sensing and haptic subsystems with sub-millimeter tactile resolution for microvascular procedures.
Robotic systems capture the dominant capital allocation; feedback mechanisms are climbing the fastest as autonomy requirements intensify.
End User:
Volume concentration follows integrated delivery network consolidation, with procurement autonomy shifting from individual facilities to centralized contracting entities.
- Hospitals:Multi-specialty robotic suites with dedicated sterile processing departments and instrument inventory management. Texas and California IDNs anchor United States demand through standardized vendor selection across surgical service lines.
- Surgical Centers:Ambulatory facilities with CMS innovation center waivers for outpatient robotic procedures. These settings concentrate demand for portable, sterilizable instrument sets with rapid turnover protocols.
- Outpatient Clinics:Limited-procedure settings with rental and leasing models for capital equipment access.
- Research Institutions:Preclinical validation sites for breakthrough device designation pathways and autonomous subsystem development.
Hospitals retain the bulk of installed capacity; surgical centers are gaining share fastest as reimbursement shifts toward ambulatory settings.
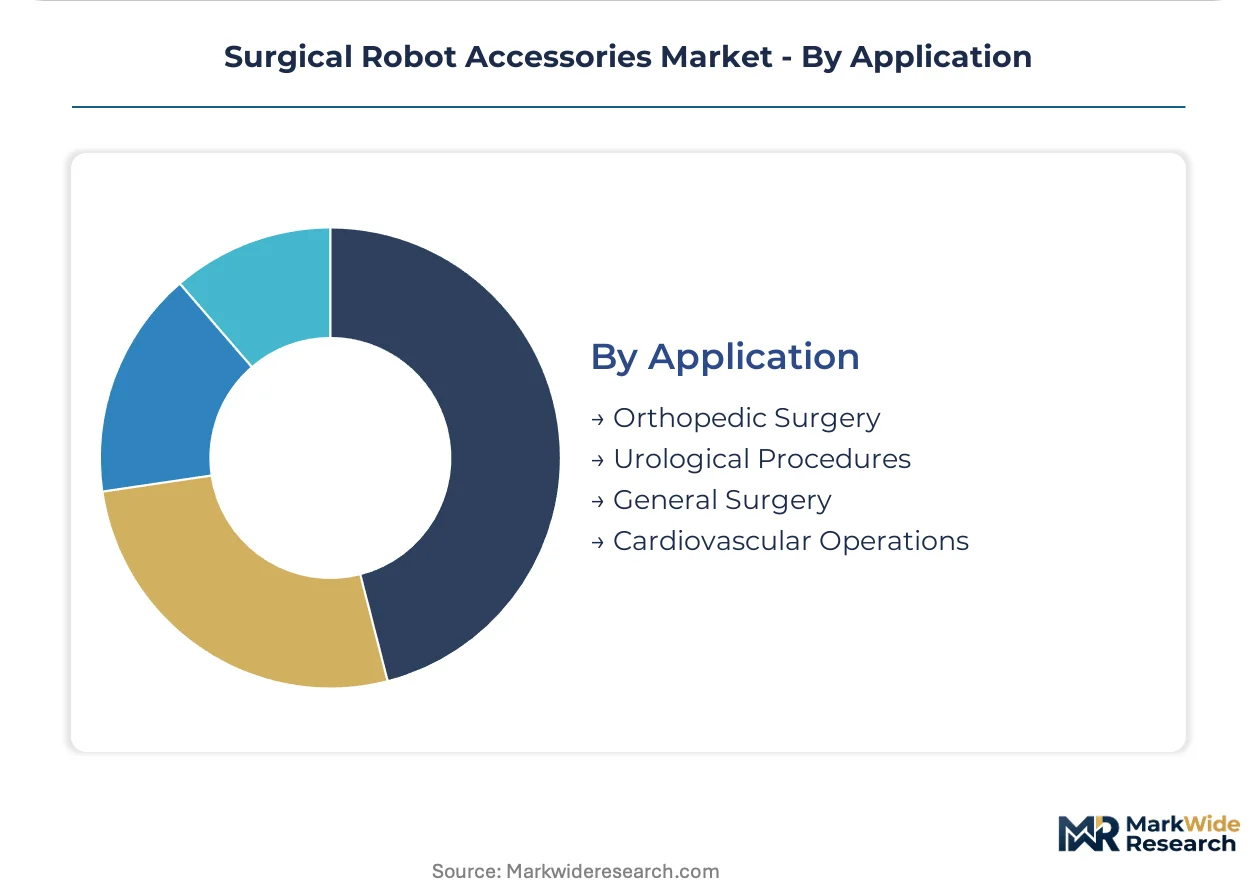
Application:
Margin tier stratification reflects procedure complexity and reimbursement intensity, with cardiac and urological applications supporting premium instrument pricing.
- Orthopedic Surgery:Mako platform accessories with patient-specific cutting guides and sterilization container systems. Stryker's integrated ecosystem dominates instrument tray configuration and logistics.
- Urological Procedures:Nerve-sparing prostatectomy instruments with force-sensing capabilities for tactile feedback. German academic centers pilot microvascular anastomosis applications.
- General Surgery:Broad-procedure instrument sets with standardized configurations across cholecystectomy and hernia repair.
- Cardiovascular Operations:Micro-instrumentation for closed-chest cardiac procedures with stringent sterilization and traceability requirements.
Orthopedic surgery absorbs the bulk of platform-specific investment; cardiovascular operations are expanding most quickly as robotic coronary bypass gains clinical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement for robotic surgical suites concentrates heavily in the United States, where academic medical centers drive synchronized replacement cycles for end effectors and visualization systems. Germany and Japan anchor European and Asian demand through precision manufacturing clusters and stringent regulatory environments. Emerging markets in India and South Korea are expanding installed base capacity through government healthcare modernization programs.
United States
Academic medical centers in Texas and California anchor replacement demand for da Vinci system accessories through integrated delivery network consolidation. FDA 510(k) clearance requirements govern predicate-based accessory submissions, streamlining market entry for instrument manufacturers. The Greater Boston cluster hosts preclinical validation sites for force-sensing end effectors targeting microvascular procedures.
Germany
German university hospitals drive European demand for 4K and 3D camera systems as visualization standards tighten for minimally invasive procedures. EU Medical Device Regulation Article 10 imposes stricter clinical evidence thresholds for CE marking of reusable instrument trays. The Baden-Württemberg precision engineering corridor supplies surgical-grade stainless steel components rated for 500+ autoclave cycles.
Japan
Japanese medical device manufacturers dominate precision motor and sensor sourcing for next-generation robotic manipulator arms. PMDA regulatory harmonization with IMDRF standards accelerates approval timelines for US-cleared accessories entering the domestic market. The Nagoya-Chubu industrial cluster specializes in polymer composite fabrication for sterilization-durable instrument housings.
India
India's fastest-expanding robotic surgery market attracts accessory suppliers through CDSCO regulatory convergence with international standards. Government PLI scheme incentives for medical device manufacturing reduce import dependency for surgical instrument components. The Maharashtra-Gujarat pharmaceutical and medtech corridor hosts contract manufacturers qualifying for ISO 13485 supplier networks.
South Korea
South Korean display technology suppliers gain share in OLED surgical monitor integration for visualization systems. MFDS breakthrough device designations for autonomous subsystems create regulatory pathways for haptic feedback instrument interfaces. The Seoul Capital Area concentrates robotic surgery training centers driving standardized instrument procurement protocols.
Surgical Robot Accessories Market Competitive Landscape
United States producers anchor the premium integrated-platform tier; European and Asian specialists hold modular component positions. Market structure rewards consolidated accessory portfolios while marginalizing point-solution suppliers lacking sterile processing logistics capabilities. Three archetypes dominate: ecosystem-integrated incumbents with proprietary instrument lock-in, contract manufacturers with ISO 13485 traceability certification, and open-platform navigators challenging proprietary boundaries. Competitive dynamics center on M&A consolidation of sterilization logistics capabilities and strategic partnerships bridging hardware-software boundaries.
Within the ecosystem-integrated tier, Intuitive Surgical and Stryker exemplify contrasting platform strategies—one leveraging installed base density for recurring instrument revenue, the other anchoring orthopedic robotics through patient-specific cutting guide integration. Medtronic occupies a position navigating open-console architectures to differentiate service models from proprietary lock-in structures. These three represent the dominant competitive archetypes shaping vendor selection criteria for hospital procurement committees.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Smith & Nephew |
| CMR Surgical |
| Asensus Surgical |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Surgical-grade stainless steel and nickel-titanium alloy input costs cascade through three pricing tiers before reaching hospital procurement committees, with Baden-Württemberg precision mills feeding premium instrument lines while Indian contract manufacturers anchor economy-grade polymer composite sourcing.
Pricing Analysis
High-volume disposable end effectors sacrifice margin for installed base lock-in while low-volume haptic feedback instruments capture premium positioning. Pricing stratifies across FDA-breakthrough-designation tiers, ISO 13485 certification grades, and bundled sterilization service levels. Cost compression in standard reusable trays intensifies because IDN consolidation forces multi-year contract commitments. Ambulatory surgical centers exhibit acute price sensitivity; academic medical centers with dedicated research budgets show relative inelasticity for next-generation visualization systems.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing is forcing accessory suppliers to rebalance sourcing away from concentrated German and Japanese precision component clusters. Supply chains draw from Baden-Württemberg for surgical-grade stainless steel, Nagoya-Chubu for polymer composite housings, and Maharashtra-Gujarat for emerging ISO 13485-qualified contract manufacturing. Single-source vulnerability concentrates in Japanese precision motor and sensor sourcing for force-sensing subsystems. Distribution runs through integrated delivery network central procurement offices rather than individual hospital materials management departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
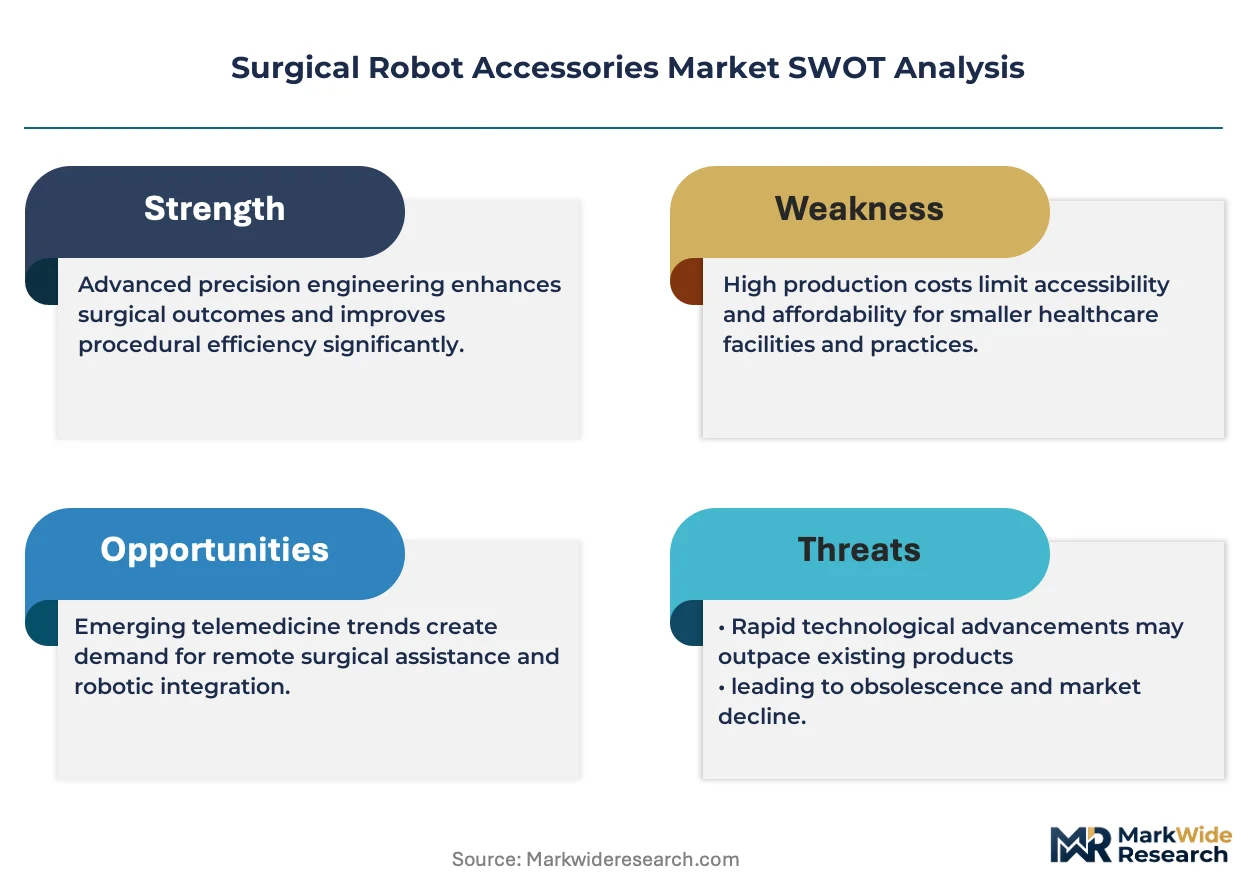
The surgical robot accessories market is becoming a vertical-integration race where control over sterile processing logistics and proprietary instrument interfaces determines recurring revenue capture. Players are pursuing backward integration into polymer composite fabrication and forward integration into hospital inventory management software.
For Market Incumbents: Lock in proprietary ecosystem boundaries by accelerating haptic feedback patent filings and acquiring ISO 13485-certified sterilization logistics providers before open-platform architectures erode instrument lock-in. Medtronic Hugo's console-agnostic service models threaten recurring revenue streams that sustain integrated vendors. Prioritize captive supply of PEEK and carbon-fiber reinforced polymers rated for 500+ autoclave cycles.
For New Entrants and Emerging Players: CDSCO regulatory harmonization with IMDRF standards in India opens a window for US-cleared accessories to enter Asia-Pacific's fastest-expanding robotic surgery market with reduced duplicate trials. Target single-port instrument miniaturization for reduced-port procedures where scar-minimization outcomes command premium positioning. Pursue direct hospital-at-home reimbursement expansion through CMS innovation center partnerships for ambulatory surgical center instrument sets.
For Investors and Strategic Acquirers: FDA breakthrough device designations for autonomous suturing subsystems is the leading indicator that haptic feedback instrument interfaces will reclassify accessory boundaries and create acquisition premiums for force-sensing technology specialists. Long-term viability hinges on identifying contract manufacturers with established EU notified body relationships before MDR Article 10 compliance costs filter out smaller portfolio holders. Watch for synchronized replacement cycle announcements from Texas and California IDNs as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Supplier Qualification | Traceability certification filters contract manufacturers for instrument launch timelines. |
| FDA 510(k) Predicate Pathway | Expedited clearance accelerates end effector iteration cycles for US market entry. |
| Hospital System Partnership | IDN consolidation rewards vendors with integrated sterile processing logistics capabilities. |
| Software Companion Development | Haptic feedback algorithms differentiate instrument intelligence beyond hardware specifications. |
| Reimbursement Strategy | CMS waivers for outpatient robotic procedures shift volume toward ambulatory instrument sets. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and sterile processing department heads underwrites the qualitative findings. Primary fieldwork with da Vinci system coordinators and Mako platform specialists combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up instrument shipment tracking and top-down robotic suite installation data triangulate market sizing.
Rate-of-change decomposition separates replacement cycle velocity from new installation demand across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user facility classification, and application specialty. CAGRs derive from procedure volume elasticity to installed base expansion and instrument life extension from polymer composite sterilization durability improvements. Force-sensing adoption curves and single-port miniaturization penetration serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous suturing subsystems would alter the outlook for haptic feedback instrument pricing tiers. Forecasts reflect assumptions about IDN consolidation velocity and regulatory harmonization timelines that could compress or extend market entry windows. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
US Contact Lenses Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market