
 Global Tea Market | 2026-2036
Global Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tea Market Intelligence
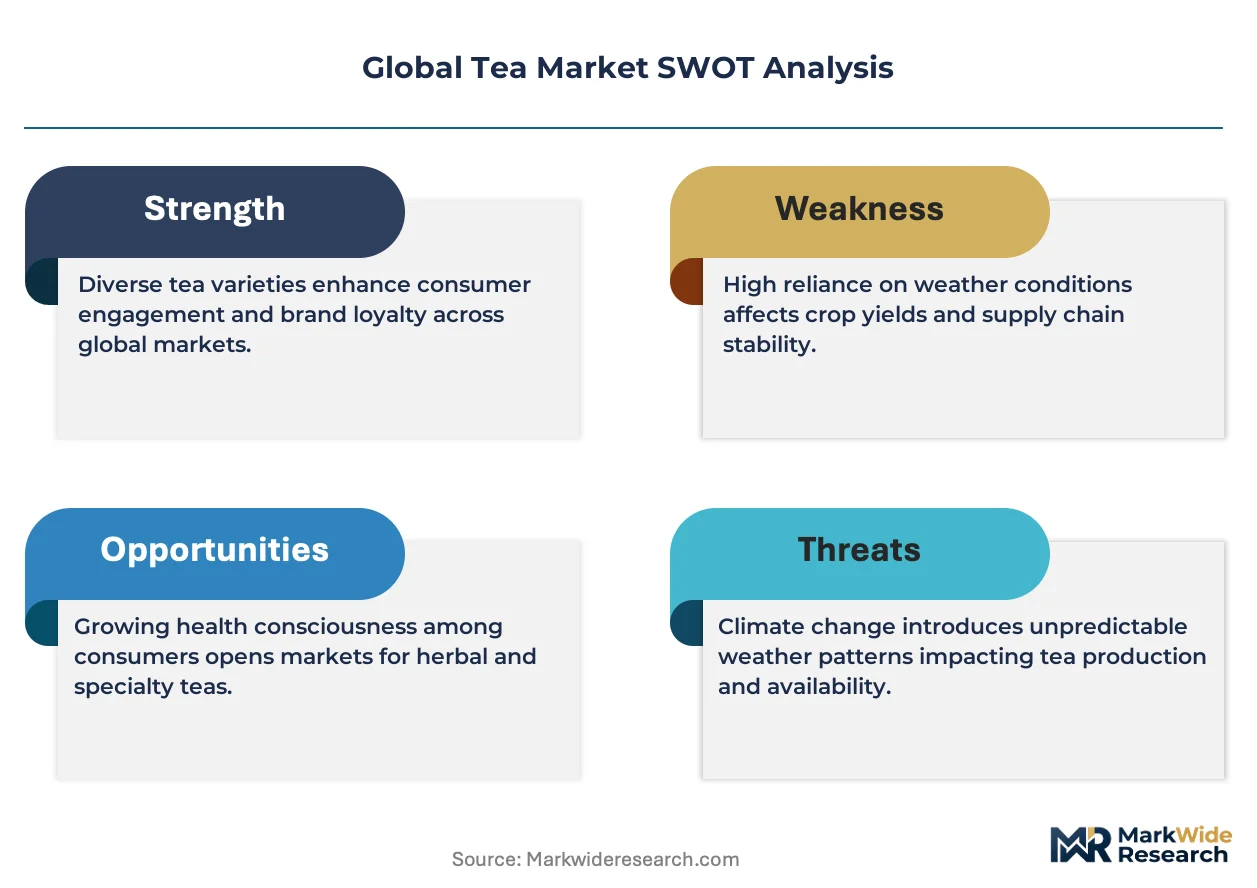
A wide capital-intensity divergence between plantation-owning multinationals and boutique blenders is bifurcating competitive dynamics in tea. Unilever Plc leverages its vertically integrated East African estates to sustain bulk black tea supply contracts with major retailers. Tata Consumer Products Ltd anchors its position through deep distribution across Indian households and expanding shelf space in British supermarkets. ITO EN, Ltd differentiates via proprietary cold-brew extraction technology and dominates Japan's ready-to-drink green tea segment.
Tea comprises processed leaves of Camellia sinensis, typically dried to moisture content below 5 percent and oxidized to varying degrees to produce distinct color, tannin profile, and caffeine concentration for beverage consumption. Black tea undergoes full enzymatic oxidation, yielding theaflavins and thearubigins that create its characteristic amber liquor and longer shelf stability. Green tea retains higher catechin content through steam fixation, commanding premium positioning in functional wellness channels. Herbal tea, which uses non-Camellia botanicals such as chamomile and rooibos, occupies the fastest-growing margin pool as caffeine-free alternatives expand in European and North American specialty retail.
FDA oversight of health claims and import residue limits shapes product formulation and market access for tea entering the United States, while EFSA novel food evaluations and EU Green Deal sustainability disclosures constrain packaging and agricultural sourcing across European supply chains. China's SAMR enforces GB standards for pesticide maximum residue limits that directly determine export eligibility for Yunnan and Anhui producers. Stakeholders must monitor tightening phytosanitary protocols and carbon-footprint traceability requirements as these will determine which origin countries retain preferred supplier status in premium channels.
Market Dynamics
Climate volatility in Assam and Kenya is compressing harvest windows and forcing estate operators toward precision irrigation and shade-management investments. This pressure is reshaping cost structures across the bulk black tea segment while accelerating consolidation among mid-sized plantation holders.
Growth Catalysts
- Cold-chain packaging standards:The EU's F-Gas Regulation and REACH compliance protocols are mandating biodegradable refrigerant systems for temperature-sensitive tea extracts, opening premium positioning for extract suppliers who retrofit first.
- Functional wellness channels:Green tea catechin retention through steam fixation is commanding shelf-space premiums in Japanese and South Korean pharmacy retail, pulling demand from conventional beverage aisles.
- Pu-erh and oolong clusters:Production gravity in China's Yunnan and Fujian provinces anchors global supply for aged and semi-oxidized categories, creating origin-authentication premiums that resist commodity pricing.
Market Restraints
- Input cost volatility:Natural gas price swings directly impact withering and drying energy costs at Kenyan and Sri Lankan processing facilities, compressing margins for non-integrated operators.
- Supply concentration risk:East African bulk tea auctions in Mombasa and Colombo concentrate price discovery for CTC grades, exposing buyers to single-point logistics disruptions during monsoon flooding.
- Regulatory friction:China's SAMR enforcement of GB pesticide maximum residue limits creates export eligibility bottlenecks for smallholder Yunnan and Anhui producers lacking testing infrastructure.
Strategic Opportunities
- Caffeine-free alternatives:Rooibos and chamomile botanicals occupy underpenetrated margin pools in European specialty retail, where EFSA novel food evaluations are streamlining entry for South African and Egyptian suppliers.
- Ready-to-drink cold brew:Proprietary extraction technology convergence with nitrogen dosing systems is creating ambient-stable premium formats for Japanese convenience store channels.
- Carbon-footprint traceability:EU Green Deal sustainability disclosure mandates are rewarding early adopters of blockchain-verified origin tracking across Fujian and Darjeeling supply chains.
Industry Challenges
- Phytosanitary certification timelines:USDA APHIS import protocols and FDA residue limit testing create 90-120 day entry delays for new harvest shipments into US distribution.
- Skill gaps in oxidation control:Master tea makers capable of consistent theaflavin development in orthodox black tea are aging out of Assam and Nilgiri estates faster than apprenticeship programs replenish.
- Legacy auction system integration:Direct-to-brand contracting platforms are fragmenting price transparency mechanisms that Mombasa and Colombo exchanges have operated for decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tea Market |
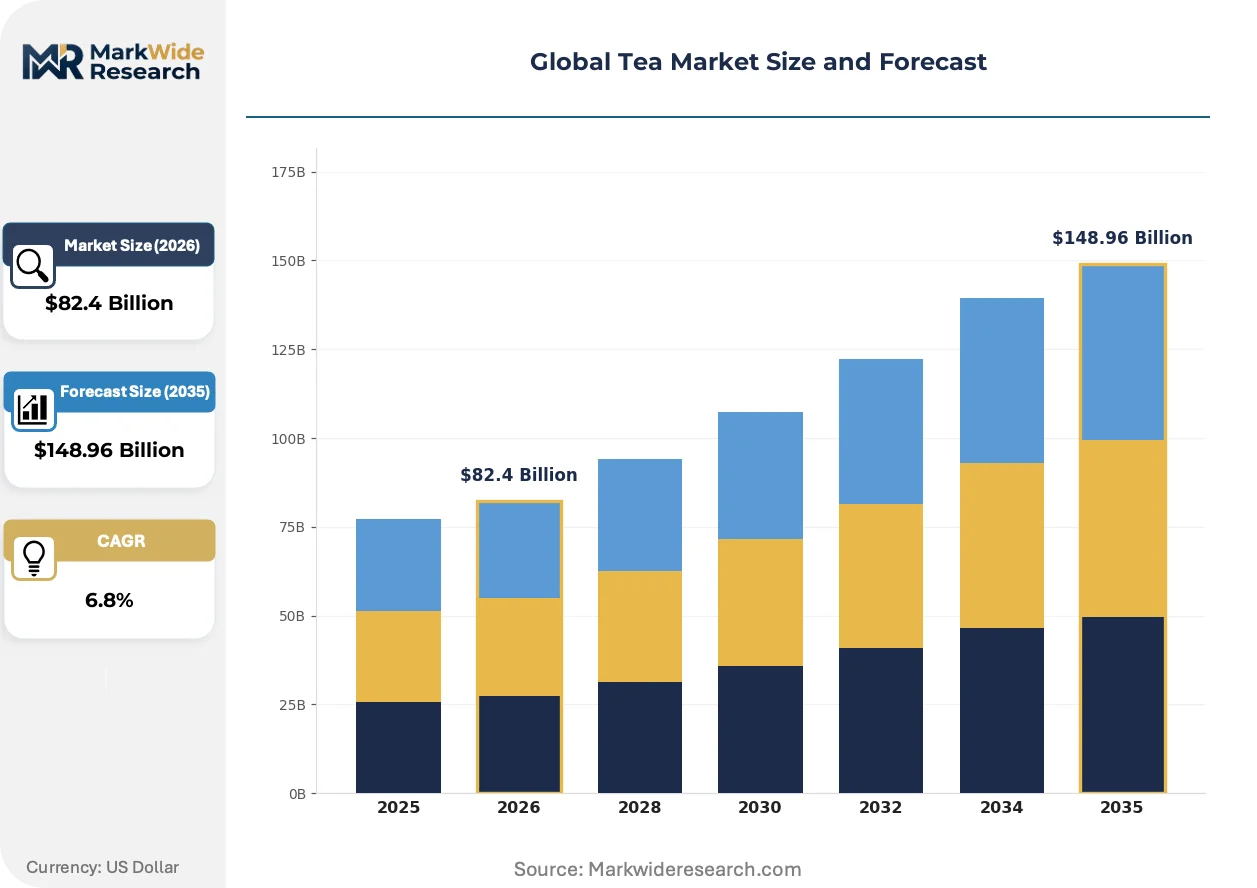
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Oolong Tea, White Tea, Herbal Tea, Pu-erh Tea Packaging Format: Loose Leaf, Tea Bags, Pyramid Bags, Sachets, Canisters, Tins Sales Channel: Supermarkets & Hypermarkets, Online Retail, Specialty Stores, Convenience Stores, Food Service, Direct Sales End User: Households, Hotels & Resorts, Cafes & Restaurants, Corporate Offices, Educational Institutions |
| Companies Covered | Associated British Foods plc, Hain Celestial Group Inc, Unilever Plc, TAETEA, Barry's Tea, Nestle S.A., ITO EN, Ltd, PepsiCo Inc, Tata Consumer Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tea Market Strategic Shifts & Innovations
Precision fermentation and cellular agriculture are beginning to intersect with traditional Camellia sinensis cultivation, creating parallel production pathways that threaten to bifurcate the authenticity-premium structure of origin-labeled teas.
Enzymatic bioprocessing for theaflavin isolation is decomposing the traditional harvest-to-cup value chain by enabling flavor compound synthesis independent of leaf oxidation. Biotech ingredient suppliers in South Korea and Singapore are adopting this platform for functional beverage fortification. This technology is compressing the premium that orthodox black tea estates command for their oxidation expertise.
REACH substance restrictions and the EU F-Gas Regulation are mandating refrigerant transitions in cold-chain logistics for temperature-sensitive extracts. Industrial consequence includes accelerated capital rotation toward CO2-based refrigeration systems at Rotterdam and Hamburg transshipment hubs. Japanese and Taiwanese extract suppliers are responding fastest, securing preferred supplier status with premium hospitality chains.
Certification-driven preference shifts are redirecting procurement toward Rainforest Alliance and Fairtrade-labeled origins in British and German supermarket channels. Specialty retailers in London and Berlin are displacing conventional bulk offerings with single-origin transparency formats. This rotation is most visible in the United Kingdom, where Tesco and Sainsbury's shelf-space reallocation is compressing volumes for non-certified East African auction grades.
Global Tea Market Segmentation
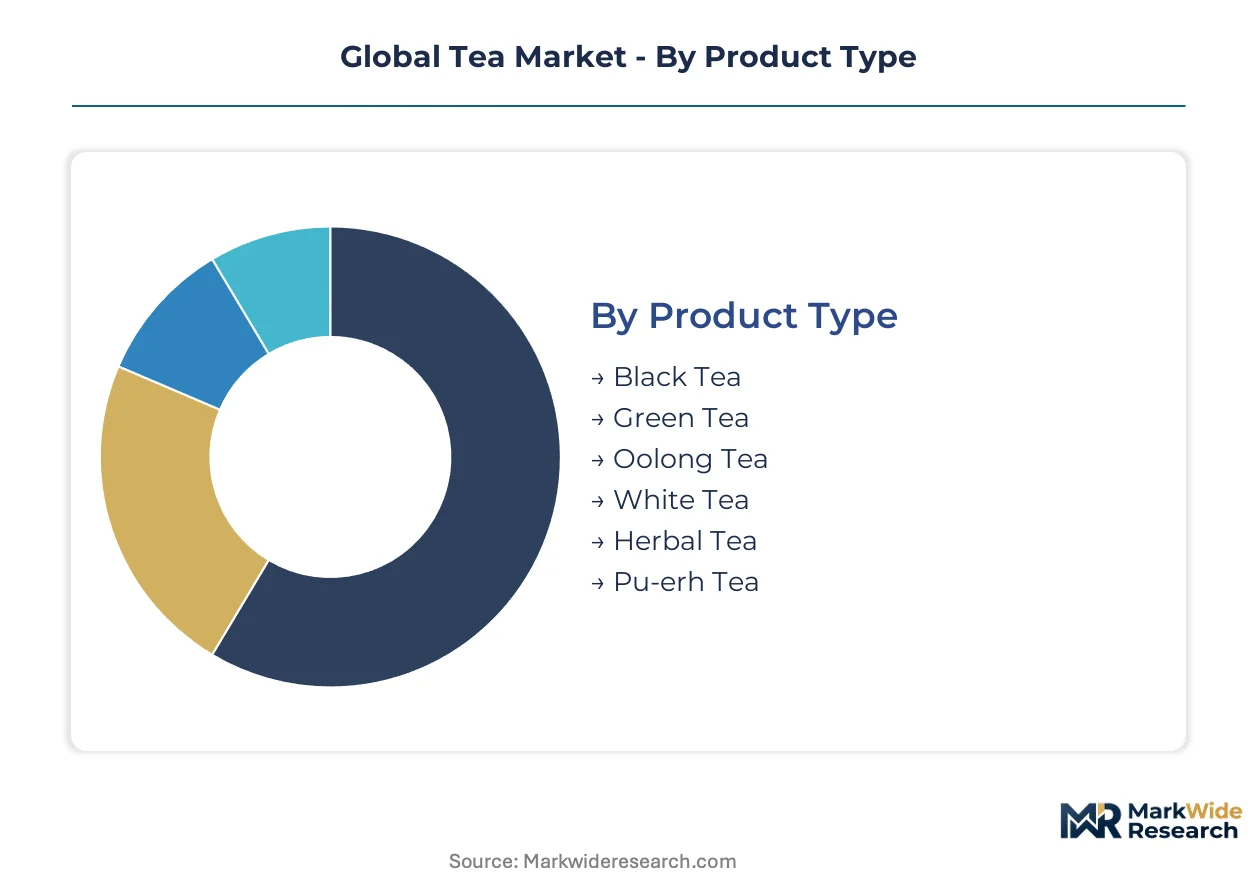
Tea market segmentation reveals distinct channel affinities and margin structures. Product type determines oxidation investment and shelf stability requirements. Packaging format shapes logistics costs and premium positioning potential.
Product Type:
Channel-mix patterns diverge sharply across oxidation categories, with mass retail favoring stable formats and specialty channels rewarding artisan production.
- Black Tea:Full enzymatic oxidation produces theaflavins and thearubigins that deliver amber liquor color and extended shelf stability. Demand concentrates in British and German supermarket channels where CTC grades dominate private-label procurement, though Kenyan auction price volatility compresses margins for non-integrated blenders.
- Green Tea:Steam fixation preserves epigallocatechin gallate and other catechin compounds, creating functional wellness positioning in Japanese pharmacy retail and South Korean convenience channels. Premium matcha grades command specialty cafe placement in London and New York.
- Oolong Tea:Semi-oxidized leaves from Fujian and Taiwan occupy mid-premium positioning in Chinese diaspora communities and specialty importers.
- White Tea:Minimal processing of young buds and leaves limits scale, restricting volume to boutique direct-to-consumer channels.
- Herbal Tea:Rooibos and chamomile botanicals bypass Camellia sinensis supply constraints, expanding fastest in European caffeine-free segments.
- Pu-erh Tea:Post-fermented cakes from Yunnan provinces anchor collector markets and aged-tea investment channels.
By volume, Black Tea leads. By growth pace, Herbal Tea is expanding most quickly.
Packaging Format:
Cost tier stratification separates commodity convenience formats from origin-transparent premium presentations.
- Loose Leaf:Uncompressed whole leaves preserve aromatic oil integrity and enable visual quality assessment. Demand concentrates in specialty retailers across Berlin and Melbourne where single-origin transparency commands price premiums, though humidity-controlled logistics add handling costs.
- Tea Bags:Standardized paper or filter-paper sachets dominate mass retail velocity in British and American supermarkets, with fannings and dust grades optimizing extraction speed for food service.
- Pyramid Bags:Three-dimensional nylon or biodegradable mesh structures accommodate whole-leaf expansion, bridging premium positioning and convenience formats.
- Sachets:Individually wrapped servings target hospitality minibars and airline catering contracts.
- Canisters:Airtight metal packaging protects light-sensitive green and white teas in Japanese gift channels.
- Tins:Decorative metal containers serve collectible and ceremonial markets in Chinese and Taiwanese distribution.
By volume, Tea Bags dominate procurement. By margin contribution, Loose Leaf generates superior returns.
Sales Channel:
Customer type fragmentation separates routine replenishment from discovery-driven and ceremonial purchase occasions.
- Supermarkets & Hypermarkets:High-velocity shelf space in Tesco, Sainsbury's, and Walmart channels concentrates volume for certified bulk grades. ESG disclosure requirements under EU Green Deal procurement standards are displacing non-certified East African auction lots.
- Online Retail:Direct-to-consumer platforms enable origin storytelling and subscription replenishment models, with Chinese cross-border e-commerce accelerating pu-erh and aged oolong access to European collectors.
- Specialty Stores:Curated assortments in London's Fortnum & Mason and Berlin's Paper & Tea emphasize single-producer transparency and seasonal harvest timing.
- Convenience Stores:Ready-to-drink and instant formats dominate Japanese 7-Eleven and FamilyMart channels.
- Food Service:B2B supply contracts with hotel chains and airline caterers prioritize consistent extraction profiles over origin specificity.
- Direct Sales:Estate-owned boutiques and tasting rooms in Darjeeling and Uji capture full margin on limited-production lots.
By transaction volume, Supermarkets & Hypermarkets lead. By value growth, Online Retail is climbing the fastest.
End User:
Application maturity varies from saturated household penetration to underdeveloped institutional channels.
- Households:Daily consumption across Indian, Chinese, and British markets anchors baseline demand, with premiumization visible in loose-leaf adoption among urban professionals.
- Hotels & Resorts:In-room amenity programs and afternoon tea services in Mandarin Oriental and Aman properties emphasize regional origin stories and ceremonial presentation.
- Cafes & Restaurants:Specialty coffee chains in Seoul and Melbourne are expanding tea menu depth to capture non-caffeine occasions.
- Corporate Offices:Pantry service contracts prioritize cost efficiency and brand recognition over origin specificity.
- Educational Institutions:University catering and vending contracts represent emerging volume for functional wellness positioning.
By consumption volume, Households lead. By premiumization pace, Hotels & Resorts is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in processed Camellia sinensis leaves show persistent export surpluses in origin markets against import dependence in consumption centers. China's Fujian and Yunnan provinces anchor outbound volume, while British and German buyers concentrate procurement through Mombasa and Colombo auction channels.
China
Pu-erh aging investment and oolong ceremonial consumption sustain premium pricing power in domestic and diaspora channels. SAMR enforces GB pesticide maximum residue limits that determine export eligibility for Anhui and Yunnan producers. Production clusters in Xishuangbanna and Anxi are retrofitting carbon-footprint traceability systems to meet EU Green Deal procurement standards.
India
Household penetration exceeds ninety percent while urban professionals drive loose-leaf premiumization in Mumbai and Delhi. FSSAI fortification guidelines and BIS packaging standards constrain ready-to-drink formulation. Assam's Brahmaputra Valley estates are consolidating under integrated processors to offset climate-compressed harvest windows.
United Kingdom
Supermarket private-label procurement dominates volume, though specialty retailers in London displace conventional grades with Rainforest Alliance-certified alternatives. REACH substance restrictions and EFSA novel food evaluations shape extract import protocols. British blenders are negotiating direct-to-estate contracts to bypass Mombasa auction volatility.
Japan
Ready-to-drink green tea saturates convenience store channels while matcha grades command pharmacy retail premiums. METI energy efficiency standards and PMDA functional claim oversight constrain processing facility upgrades. Uji and Shizuoka prefectures are deploying proprietary cold-brew extraction systems for ambient-stable premium formats.
Kenya
CTC black tea exports supply British and German bulk procurement, though auction price transparency is fragmenting under direct-contracting pressure. Natural gas price swings impact withering and drying energy costs at processing facilities. The Rift Valley and Nandi Hills clusters are investing in precision irrigation to stabilize yields against monsoon variability.
Global Tea Market Key Industry Players
Concentration sits with vertically integrated plantation operators and multinational consumer goods conglomerates that control upstream supply and downstream distribution simultaneously. The vendor base separates into estate-owning processors, boutique blenders, and ready-to-drink format specialists. Strategic moves center on backward integration into cultivation assets and certification-driven procurement to secure premium channel placement.
Among diversified consumer goods conglomerates, Unilever Plc and Nestle S.A. exemplify scale-driven archetypes with captive supply arrangements across East African origins. Tata Consumer Products Ltd represents the integrated plantation-to-retail model with deep distribution in Indian household channels. ITO EN, Ltd anchors the ready-to-drink technology tier through proprietary extraction platforms serving Japanese convenience retail.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Hain Celestial Group Inc |
| Unilever Plc |
| TAETEA |
| Barry's Tea |
| Nestle S.A. |
| ITO EN, Ltd |
| PepsiCo Inc |
| Tata Consumer Products Ltd |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-twenty-day phytosanitary certification timelines for US-bound shipments compress working capital cycles and amplify pricing power for integrated estate operators with in-house testing infrastructure. This lead-time band concentrates margin capture among Kenyan and Sri Lankan processors who control both cultivation and export documentation, while fragmenting price discovery for smallholder-dependent blenders.
Pricing Analysis
Customization-premium spreads between single-origin loose-leaf contracts and commodity CTC auction grades now exceed three-to-one in British supermarket procurement. Three-tier pricing structure across premium, standard, and economy levels anchors contract negotiations, with Rainforest Alliance certification and estate-specific traceability commanding the upper tier. Pricing pressure stems from natural gas cost volatility at Kenyan withering facilities, compressing margins for non-integrated processors. Bulk black tea buyers at Mombasa auctions exhibit highest price sensitivity, while Japanese pharmacy retail channels show lowest sensitivity for cold-brew matcha formats.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg transshipment hubs are accelerating under EU F-Gas refrigerant retrofit mandates, advantaging Japanese and Taiwanese extract suppliers with CO2-based cold-chain systems already deployed. Production gravity centers on China, India, and Kenya, with Fujian oolong and Assam orthodox grades drawing from distinct terroir clusters. Raw material dependencies include Camellia sinensis leaf stock, nitrogen dosing systems for ambient-stable formats, and biodegradable packaging substrates. Single-source vulnerability concentrates in Yunnan pu-erh aging warehouses for collector-grade supply. Distribution runs through Mombasa and Colombo auction exchanges for bulk grades, while direct-to-brand contracting platforms fragment price transparency for specialty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as blockchain-verified origin tracking systems achieve interoperability across Fujian, Darjeeling, and Uji supply chains, transforming certification data into tradable network assets.
For Market Incumbents: Secure backward integration into precision irrigation assets across Assam and Kenya to offset climate-compressed harvest windows. Lock in Rainforest Alliance certification coverage before EU Green Deal procurement standards displace non-compliant auction grades. Channel control through direct-to-estate contracting platforms defends margin position against Mombasa price volatility. For New Entrants and Emerging Players: Anchor in European caffeine-free specialty retail where rooibos and chamomile botanicals face streamlined EFSA novel food pathways. Target South African and Egyptian supplier relationships for white-space capture in Berlin and London curated retail. Go-to-market angle centers on nitrogen-dosed ambient-stable cold brew for Japanese convenience store penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer conglomerates seeking to divest non-core plantation assets amid energy cost compression. Long-term viability favors vertically integrated processors with captive cold-brew extraction technology and carbon-footprint traceability infrastructure already deployed. Signal to monitor: fragmentation velocity at Mombasa and Colombo auction exchanges as direct-contracting platforms gain share.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Irrigation | Climate adaptation investments in Assam and Kenya stabilize yield against monsoon variability. |
| Cold-Chain Refrigerant Retrofit | CO2-based systems at Rotterdam and Hamburg secure preferred supplier status with EU hospitality chains. |
| Blockchain Origin Tracking Deployment | Fujian and Darjeeling producers meet EU Green Deal disclosure mandates ahead of competitors. |
| Direct-to-Brand Contracting Platform | British blenders bypass Mombasa auction volatility through Kenyan estate relationships. |
| Nitrogen-Dosed Extraction Scale-Up | Japanese convenience store channels reward ambient-stable premium format innovation. |
Research Approach
The analysis maps oxidation categories, packaging formats, and sales channel dynamics, each validated through plantation operations directors, specialty retail buyers, cold-chain logistics coordinators, and regulatory compliance officers across origin and consumption markets. Primary interview data triangulates against customs trade records, FDA import refusal databases, EFSA novel food registers, and EU F-Gas implementation reports. Bottom-up volume modeling from estate-level production data converges with top-down expenditure analysis from retail audit panels.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include oxidation degree, packaging preservation requirements, channel certification standards, and regional regulatory clusters. CAGRs derive from recursive modeling of harvest volume trends, price elasticity coefficients in auction versus direct-contract channels, and premiumization velocity in pharmacy and specialty retail. Industry-specific inputs encompass climate-adjusted yield projections for Assam and Kenya, and SAMR enforcement intensity for GB pesticide residue compliance.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal procurement standard rollout and stable phytosanitary certification timelines; material deviation in either would warrant model refresh. Forecasts embed assumptions regarding natural gas price trajectories at processing facilities and blockchain traceability adoption curves across origin clusters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Global Catechin Market
Tea
APAC RTD Tea Market
Tea
New Style Tea Drink Market
Tea
Black Tea Market
Tea
Moringa Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Green Tea Leaves Market
Tea
North America Tea Market
Tea
Natural Tea Extract Market
Tea
Europe Green Tea Market
Tea
Pyramid Tea Bags Market
Tea
Tea Subscription Market
Tea
Africa Ready to Drink Tea Market
Tea
Tea Concentrate Market
Tea
Out of Home Tea Market