
 North America Food and Beverage Filling and Capping Machines Market | 2026-2036
North America Food and Beverage Filling and Capping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food and Beverage Filling and Capping Machines Market Intelligence
The expansion of equipment leasing programs and asset-light operational models is fragmenting the competitive landscape for food and beverage packaging machinery in North America. ProMach leverages its extensive portfolio to cater to a wide array of packaging needs. Barry-Wehmiller Group specializes in providing fully integrated, end-to-end line solutions. Sidel Group differentiates with its expertise in aseptic and hot-fill technologies for the beverage sector.
Food and beverage filling and capping machines in North America are engineered systems that dispense precise product volumes and apply secure closures, ensuring integrity via hermetic seals. Their industrial purpose is to automate packaging lines, boosting throughput and maintaining hygienic conditions. Automatic systems represent the dominant technology segment due to efficiency in high-speed operations. Beverage manufacturers, a key end-user, drive demand for equipment tailored to applications like juices and dairy products.
The US Food and Drug Administration (FDA) enforces hygienic design standards through its Food Safety Modernization Act (FSMA). Health Canada maintains parallel regulations for equipment to prevent food contamination. These rules mandate specific material grades and clean-in-place capabilities for machinery sold in North America. The key decision for processors is balancing automation capital expenditure with operational efficiency gains and compliance mandates.
Market Dynamics
The primary force shaping the North America food and beverage filling and capping machine market is the dual pressure from stringent food safety regulations and the rapid proliferation of new beverage product lines, compelling manufacturers to invest in automated, hygienic, and flexible packaging systems.
Growth Catalysts
- Regulatory Mandates:The US FDA's Food Safety Modernization Act (FSMA) and parallel Health Canada regulations require equipment with advanced hygienic design and clean-in-place capabilities, directly stimulating machinery upgrades.
- End-User Expansion:Strong demand from beverage manufacturers, particularly those introducing new product lines like functional juices and dairy alternatives, necessitates investment in specialized and high-throughput filling equipment.
- Processing Hub Investment:Concentrated capital investment within established food processing corridors, such as the US Midwest and California, creates a consistent replacement and expansion cycle for packaging machinery.
Market Restraints
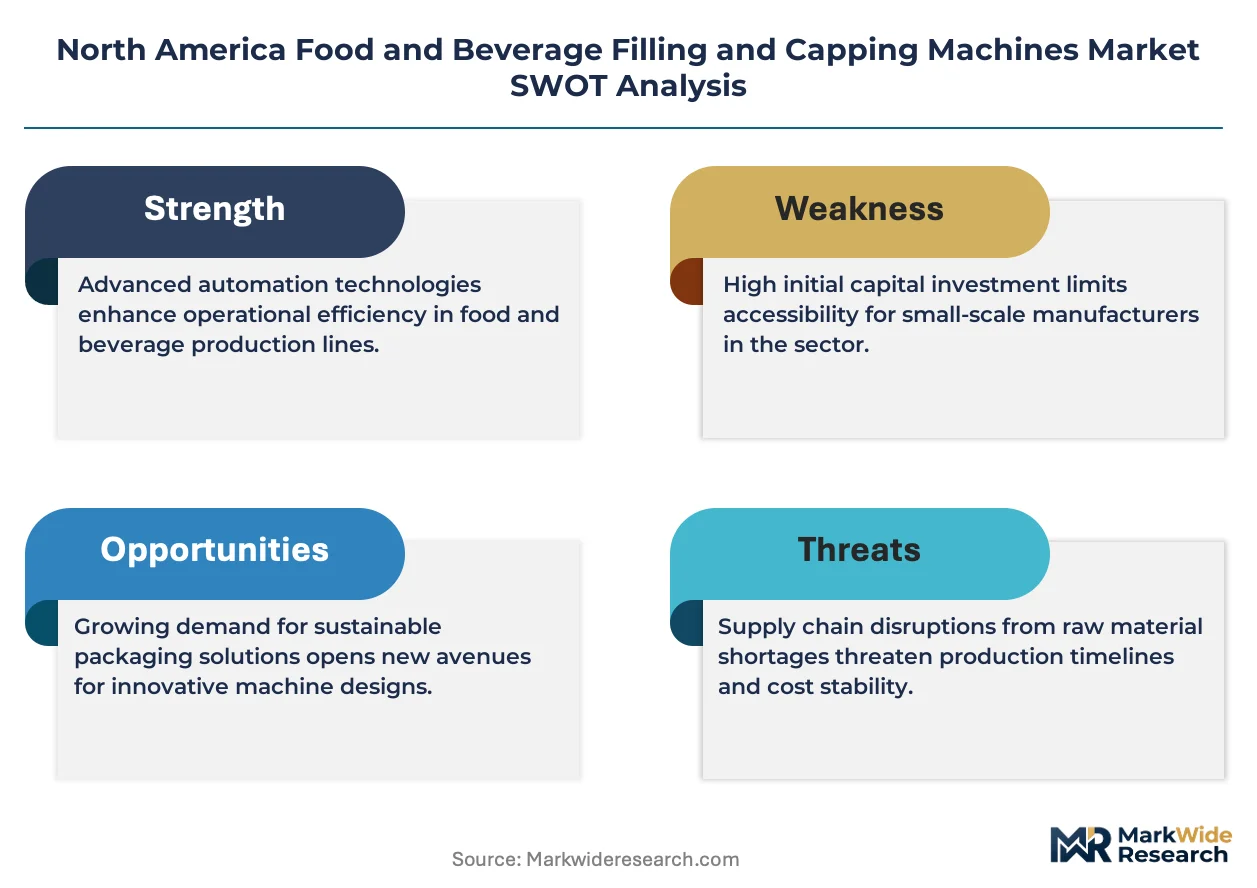
- Capital Intensity:The significant upfront capital expenditure required for automated, hygienically-designed filling and capping systems presents a substantial barrier for small and medium-sized enterprises.
- Integration with Legacy Systems:Technical challenges and costs associated with integrating new, smart machinery with older existing equipment on a packaging line can limit adoption and create bottlenecks.
- Component Sourcing:Dependence on a concentrated base of suppliers for critical components like servo motors and control systems creates vulnerability to supply chain disruptions and price volatility.
Strategic Opportunities
- Plant-Based Beverages:Developing filling and capping solutions specifically tailored for the unique viscosity and handling requirements of plant-based milks and alternative dairy products opens a significant new application segment.
- Service Model Innovation:Offering equipment-as-a-service (EaaS) models, bundling machinery with predictive maintenance and operational support, can attract customers hesitant about large capital outlays.
- Mexican Market Modernization:Targeting food and beverage producers in Mexico who are upgrading their facilities to meet stringent export requirements for the US market provides a key geographic growth avenue.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with the expertise to operate, service, and maintain increasingly complex and automated packaging machinery hampers operational efficiency.
- System Interoperability:Achieving seamless data communication and physical integration between filling machines and other third-party equipment on a packaging line remains a significant operational hurdle for processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food and Beverage Filling and Capping Machines Market |
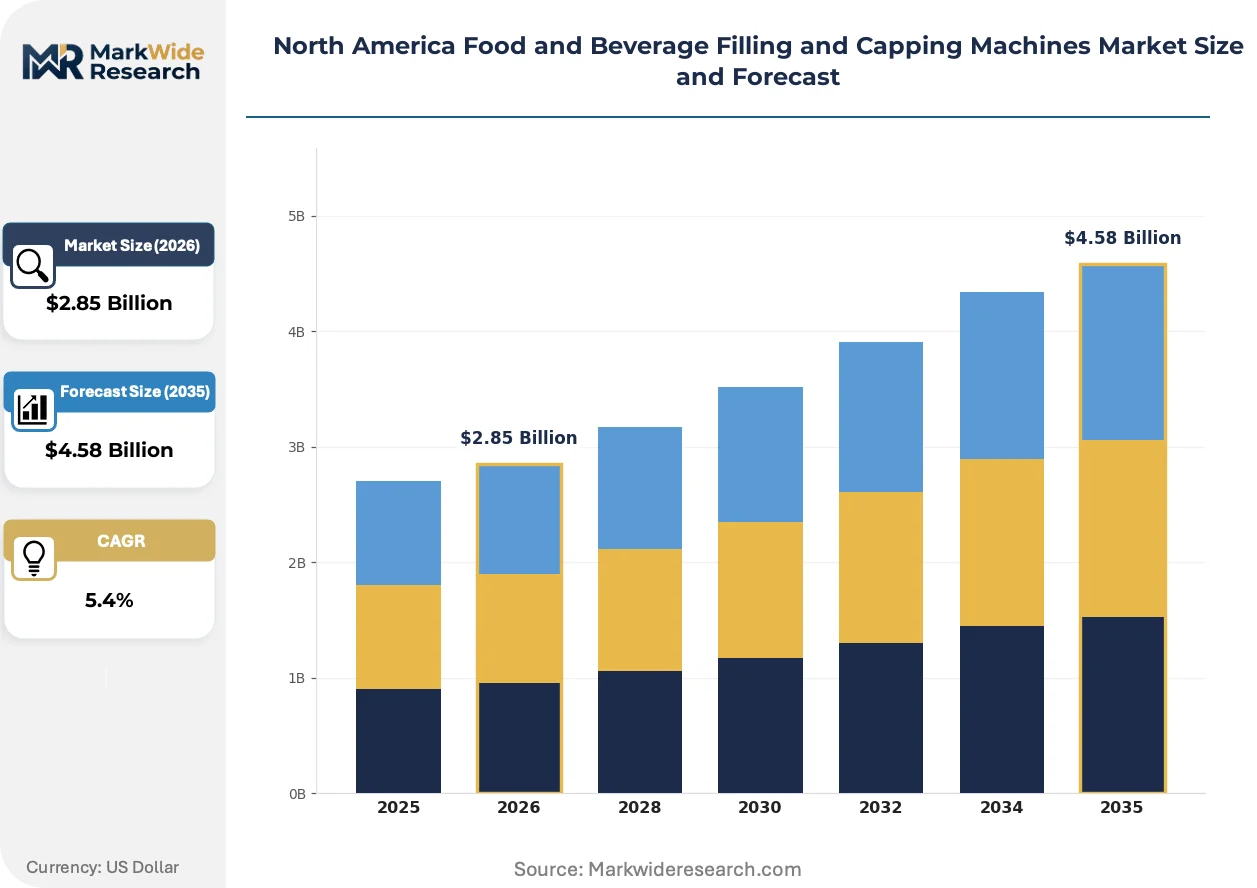
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Bottle Cappers, Pouch Fillers, Capsule Fillers End User: Beverage Manufacturers, Food Processors, Pharmaceutical Companies, Cosmetic Firms Technology: Automatic, Semi-Automatic, Manual, Vacuum Application: Carbonated Beverages, Juices, Sauces, Dairy Products |
| Companies Covered | ProMach, Barry-Wehmiller Group, Duravant, KHS Group, SIG, Tetra Laval International S.A., Coesia S.p.A., Sidel Group, Accutek Packaging Equipment Companies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food and Beverage Filling and Capping Machines Market Strategic Shifts & Innovations
Innovation in the North American market is driven by the pursuit of greater operational efficiency and sustainability. Equipment design increasingly focuses on reducing material waste, accommodating lighter-weight packaging, and integrating digital technologies for enhanced process control and predictive maintenance.
Aseptic and hot-fill technologies enable the packaging of preservative-free, shelf-stable products like juices and dairy alternatives. Beverage manufacturers are the primary adopters of these systems to meet consumer demand for healthier options. The market is migrating from traditional cold-fill processes, which necessitate a costly refrigerated supply chain, toward aseptic solutions that reduce logistical expenses and extend product shelf life.
The US Food and Drug Administration's Food Safety Modernization Act (FSMA) is a significant regulatory driver. Its emphasis on preventative controls for food safety is forcing processors to invest in equipment with validated clean-in-place (CIP) and sterilize-in-place (SIP) functionalities. Dairy and fresh juice producers are most impacted, accelerating the retirement of older equipment that cannot meet the stringent hygienic design and documentation standards.
A shift toward flexible equipment leasing and rental programs is altering procurement patterns, especially among new entrants. This model disrupts the traditional high-cost, one-time capital equipment sale, allowing smaller companies to access advanced technology without prohibitive upfront investment. This trend is particularly evident within the dynamic craft beverage sector in the United States, where producers require scalable solutions to manage growth.
North America Food and Beverage Filling and Capping Machines Market Segmentation
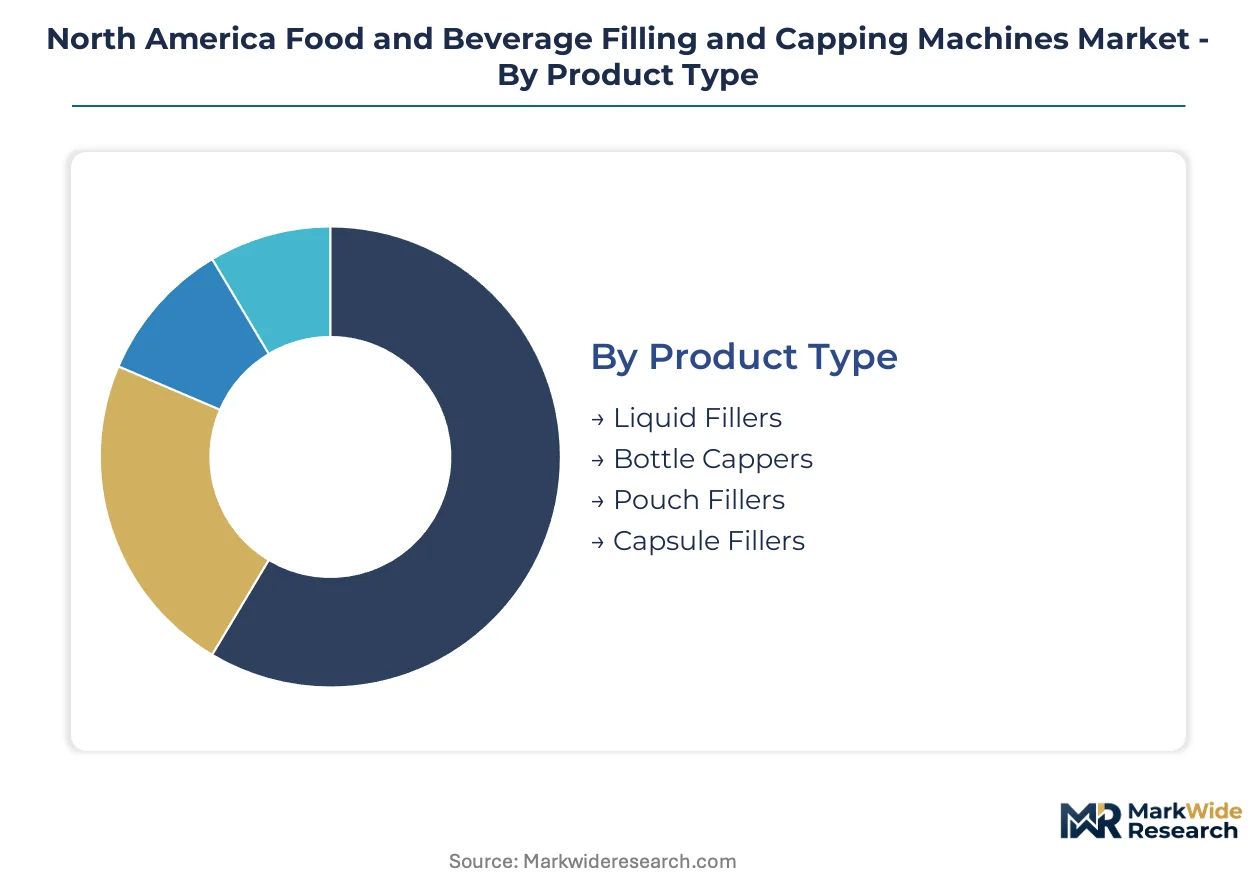
Understanding the segmentation within the North America food and beverage filling and capping machines market reveals how different product types, end-users, technologies, and applications shape demand and innovation. This granular view helps processors identify optimal equipment investments and suppliers tailor their offerings to specific industry needs.
Product Type:
The after-sales service intensity for food and beverage filling and capping machines varies significantly across different product types, directly influencing operational uptime and maintenance costs for North American manufacturers.
- Liquid Fillers:These machines dispense precise volumes of liquid products into various container types, including bottles, pouches, and cartons. Demand from beverage manufacturers for high-speed lines drives continuous maintenance and calibration service requirements across the US Midwest.
- Bottle Cappers:Equipment designed to apply and securely fasten closures onto bottles, ensuring product integrity and preventing contamination. Beverage and dairy industries require frequent adjustments and part replacements due to diverse cap types and high production speeds in California.
- Pouch Fillers:Systems that fill and seal flexible pouches with a range of food and beverage products. The dynamic craft beverage sector in the United States increasingly uses these for innovative packaging formats.
- Capsule Fillers:Machines that accurately load precise doses of powders or liquids into capsules, primarily for nutraceuticals or specialized food additives. Pharmaceutical and health supplement firms in Canada employ these for specific product lines.
Liquid Fillers hold the largest share; momentum sits with Pouch Fillers.
End User:
The application-specific requirements of various end-user segments dictate the specialized features and configurations of filling and capping machinery in the North American market.
- Beverage Manufacturers:These companies produce a wide array of drinks, including carbonated soft drinks, juices, and dairy alternatives. These users require high-throughput, aseptic, and hot-fill systems to meet consumer demand for diverse product lines.
- Food Processors:Firms that prepare and package solid, semi-solid, and liquid food items for retail and foodservice. Their demand focuses on flexible machines capable of handling varying viscosities and container types, particularly for sauces and ready meals.
- Pharmaceutical Companies:Organizations that package medicines and health supplements, requiring sterile and highly precise filling and capping solutions. Stringent regulatory compliance from the US FDA and Health Canada impacts equipment selection.
- Cosmetic Firms:Businesses that fill and cap creams, lotions, and other personal care products. These companies prioritize aesthetic packaging and precise dosing for premium brands.
Beverage Manufacturers drive the majority of demand within this segment.
Technology:
The cost tier of filling and capping technology profoundly impacts initial investment and long-term operational expenditure for North American processors across different scales.
- Automatic:These systems operate continuously without human intervention for filling and capping processes. High-speed automatic systems are critical for large-scale beverage manufacturers and food processors to achieve throughput and cost efficiency.
- Semi-Automatic:Machines that require operator interaction for loading or unloading containers but automate the filling or capping action. Small to medium-sized enterprises and craft beverage producers utilize these for flexibility and lower capital outlay.
- Manual:These systems involve operators performing all filling and capping tasks directly. Very small-scale producers or specialized niche operations employ manual systems for limited production runs.
- Vacuum:Technology that utilizes negative pressure to draw product into containers, ensuring accurate fill levels for specific liquid types. These systems are suitable for thin, non-foaming liquids in glass containers.
Automatic systems lead the market due to their efficiency and scalability.
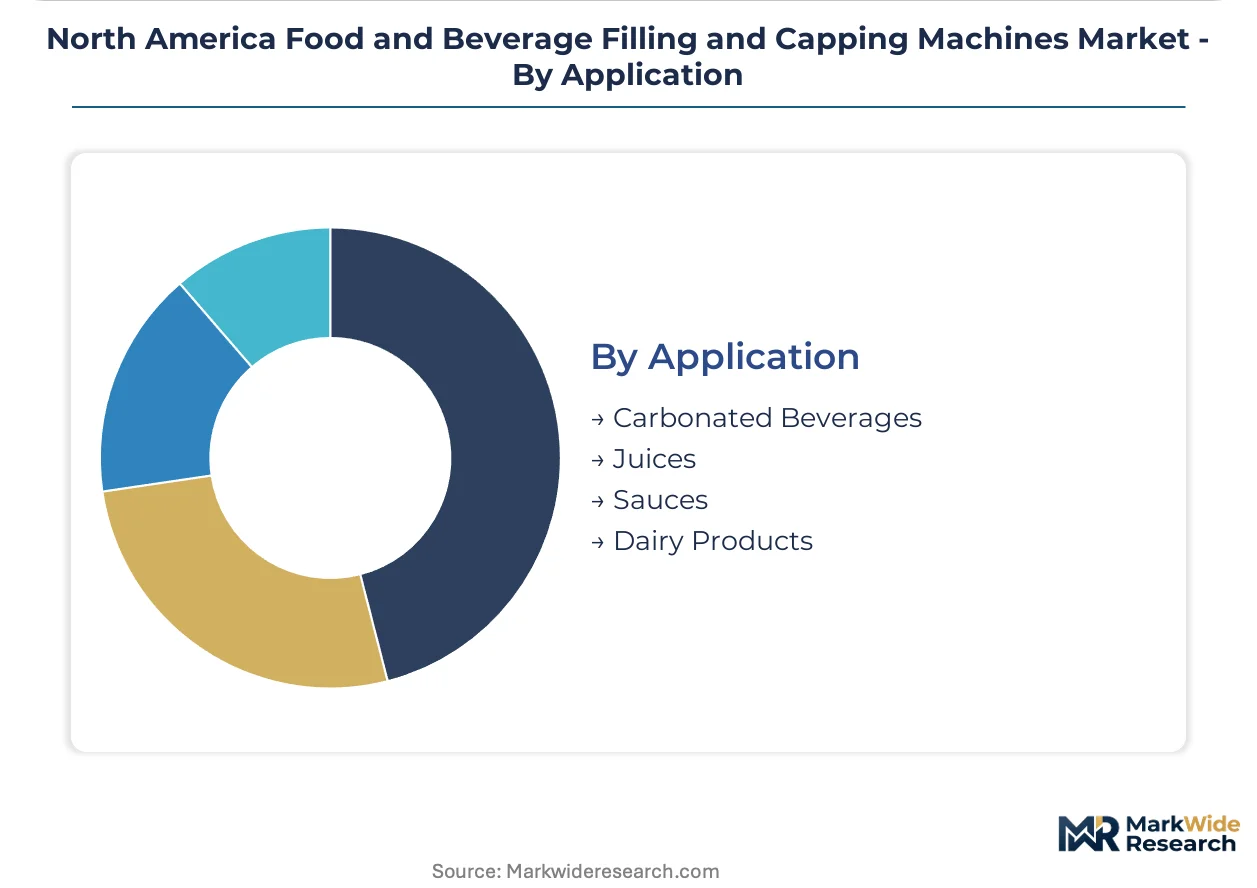
Application:
The volume requirements of different product applications directly influence the capacity and speed specifications for filling and capping machinery in North America.
- Carbonated Beverages:This segment includes soft drinks and sparkling waters, requiring specialized counter-pressure fillers to prevent foaming and retain carbonation. Large-scale beverage companies in North America maintain significant investments in these high-speed lines.
- Juices:This category encompasses fruit, vegetable, and functional juices, often requiring aseptic or hot-fill technologies to ensure shelf stability without preservatives. Consumer demand for healthier, natural options drives innovation in juice filling equipment.
- Sauces:This application includes condiments, dressings, and viscous food products, necessitating piston fillers or volumetric systems. Food processors require machines capable of handling varying viscosities and particulate matter.
- Dairy Products:This segment covers milk, yogurt, and plant-based dairy alternatives, demanding ultra-hygienic and often aseptic filling environments. Health Canada regulations mandate strict clean-in-place capabilities for dairy processing equipment.
Juices and Dairy Products together represent the fastest-growing application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers, a primary buyer archetype, drive significant demand for filling and capping machinery across North America. Their continuous introduction of new product lines, especially functional beverages, necessitates investment in flexible and hygienic packaging systems. This market concentration influences regional investment patterns.
United States
Demand for automated filling and capping solutions stems from large-scale food processors and expanding craft beverage sectors. The US FDA's Food Safety Modernization Act (FSMA) mandates upgrades to hygienic equipment. Established food processing corridors throughout the Midwest continue to see consistent machinery replacement and expansion cycles.
Canada
Health Canada regulations for food safety and the growth in dairy alternatives propel investments in advanced filling and capping technologies. Canadian producers require clean-in-place capabilities for compliance. Pharmaceutical and health supplement firms in Ontario and Quebec employ specialized capsule fillers for precise dosing.
Mexico
Modernization efforts by food and beverage producers targeting export markets for the US fuel demand for high-speed and automated systems. Stringent import requirements from the US FDA influence equipment selection. Industrial clusters in Nuevo León and Jalisco are upgrading facilities to enhance packaging quality and efficiency.
US Midwest
Investment in the US Midwest is driven by the region's robust dairy and meat processing industries, requiring high-throughput liquid fillers. The USDA's inspection requirements enforce strict sanitary design for all food contact equipment. Major food manufacturing hubs in Illinois and Ohio frequently upgrade lines for increased automation and speed.
California
The diverse beverage market in California, including juices, wines, and plant-based milks, creates strong demand for flexible filling and capping machines. State-level environmental regulations encourage the adoption of packaging equipment compatible with lighter-weight materials. The Central Valley's agricultural processing facilities continuously invest in machinery for fresh produce and dairy products.
North America Food and Beverage Filling and Capping Machines Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered competitive landscape for North America's filling and capping machines. The market exhibits a blend of large, diversified corporations offering extensive portfolios and niche firms focusing on specific technologies or applications. Strategic archetypes include integrated solution providers, technology specialists, and broad-line equipment suppliers. Portfolio diversification and strategic partnerships are dominant competitive moves among these entities.
Integrated solution providers such as ProMach and Barry-Wehmiller Group exemplify the strategy of offering comprehensive packaging line capabilities. These entities leverage extensive product portfolios to cater to diverse customer needs across various end-user segments, from liquid fillers to bottle cappers. Their operational models often involve bundling machinery with services, appealing to a broad customer base. Sidel Group represents a specialist archetype, known for its deep expertise in aseptic and hot-fill technologies, particularly for the demanding beverage sector. These firms occupy distinct positions within the North American market structure, reflecting their strategic focus and operational scale.
| Leading Market Players |
|---|
| ProMach |
| Barry-Wehmiller Group |
| Duravant |
| KHS Group |
| SIG |
| Tetra Laval International S.A. |
| Coesia S.p.A. |
| Sidel Group |
| Accutek Packaging Equipment Companies |
| Others |
Cost & Logistics Intelligence
US Midwest food processing corridors, with their consistent replacement and expansion cycles, exert significant influence over downstream pricing power for high-throughput liquid fillers. Their concentrated demand often leads to favorable long-term contract pricing for packaging machinery.
Pricing Analysis
Cost-plus contract patterns, frequently indexed to stainless steel and specialized component costs, define pricing for filling and capping systems. Pricing stratifies across premium, standard, and economy tiers based on automation level and hygienic design specifications. Price differentiation stems from customization levels for unique product lines and integrated after-sales service packages. Pricing pressure stems from intense competition among equipment providers and the capital intensity faced by small and medium-sized enterprises. Large beverage manufacturers are least price-sensitive due to high throughput requirements, while craft beverage producers exhibit greater price sensitivity.
Supply Chain Analysis
Equipment supply concentrates among major North American and European manufacturers like ProMach and Barry-Wehmiller Group, holding significant production capacity. The supply chain draws from critical components such as servo motors, control systems, and specialized hygienic materials. Dependence on a concentrated base of suppliers for these components creates vulnerability to supply chain disruptions and price volatility. Distribution runs through direct sales forces and regional distributors, often bundling machinery with installation and ongoing maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a cyclical recovery driven by continuous regulatory upgrade cycles and new product line proliferation. Processors must balance compliance with operational efficiency to capitalize on this growth.
For Market Incumbents: Pre-empt competitive threats from specialized technology providers by accelerating R&D into flexible, aseptic, and hot-fill solutions. Consolidate market share through strategic acquisitions of niche technology firms focusing on plant-based alternatives. Invest in advanced manufacturing capabilities in the US Midwest to reinforce regional supply chain control and reduce lead times for high-throughput lines. This strategy mitigates margin pressure from new entrants offering asset-light operational models.
For New Entrants and Emerging Players: The dynamic craft beverage sector in the United States represents a highly penetrable entry point for flexible filling and capping solutions. Target producers requiring scalable equipment for diverse packaging formats, such as pouch fillers for innovative products. Offer equipment-as-a-service (EaaS) models to lower upfront capital outlays for smaller companies. This go-to-market angle addresses capital intensity restraints and attracts customers hesitant about large capital expenditures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated solution providers capable of delivering comprehensive packaging line capabilities. Long-term viability rests on the continued demand for automated, hygienic, and flexible systems driven by regulatory mandates and consumer trends. Target acquisition archetypes include specialized technology firms with expertise in aseptic or hot-fill processes, and companies offering predictive maintenance and digital integration platforms. M&A activity in automation and digital solutions serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Aseptic Filling Platforms | This enhances product shelf life for dairy and juice manufacturers, meeting consumer demand for preservative-free options. |
| Expand Equipment-as-a-Service (EaaS) Offerings | This lowers capital barriers for craft beverage producers, enabling access to advanced filling technology. |
| Invest in AI-Powered Predictive Maintenance | This optimizes operational uptime for large-scale food processors by anticipating machinery failures. |
| Acquire Pouch Filling Technology Specialists | This expands portfolio capabilities for innovative packaging formats, particularly in the dynamic craft beverage sector. |
| Strengthen Hygienic Design Certification | This ensures compliance with US FDA and Health Canada regulations, crucial for dairy and juice processing equipment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of US FDA guidance, Health Canada regulations, and industry association reports. Primary interviews engaged food processing executives, beverage plant managers, equipment design engineers, and regulatory compliance officers across North America. This approach ensured a robust understanding of market dynamics from both supply and demand perspectives, triangulating data through bottom-up market sizing and top-down validation.
Forecast inputs considered consumer demand shifts, regulatory enforcement trends, and capital expenditure cycles over the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-user, technology, application, and container type. Compound annual growth rates were derived from historical data analysis and projected market drivers, incorporating industry-specific forecast inputs like new product launch rates and equipment replacement cycles across the region.
Macroeconomic conditions sit as an overlay; deviation in inflation or interest rates would shift the trajectory of capital investment. Forecasts reflect assumptions regarding stable regulatory environments and sustained consumer demand for convenience and health-oriented products. Quarterly review of new product launches, regulatory enforcement actions, and industry M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Nut Processing Machine Market