
 White Tea Extract Market | 2026-2036
White Tea Extract Market Size, Share, and Industry Trends Forecast 2026-2036
White Tea Extract Market Analytics
Green tea extract is rebalancing toward white tea derivatives as manufacturers seek lower-caffeine, higher-polyphenol alternatives for premium skincare and nutraceutical lines. Kemin Industries leverages its botanical extraction infrastructure to supply standardized catechin profiles for cosmetics clients across North America. Martin Bauer Group anchors European supply through its vertically integrated raw material sourcing from certified tea gardens. Sabinsa Corporation differentiates via its patented bioavailability enhancement technologies for dietary supplement applications.
White tea extract comprises aqueous or solvent-derived concentrates of Camellia sinensis leaves harvested before full oxidation, typically yielding elevated epigallocatechin gallate (EGCG) levels alongside L-theanine and minimal caffeine content. The extract serves primarily as an antioxidant active in topical formulations, functional beverages, and encapsulated wellness products. Powder formats dominate pharmaceutical and supplement manufacturing due to dosing precision and extended shelf stability, while liquid extracts lead food and beverage integration for flavor uniformity. Cosmetics applications are expanding fastest as formulators replace synthetic preservatives with natural polyphenol systems.
FDA oversight of dietary supplement Good Manufacturing Practices shapes purity testing protocols for U.S.-bound white tea extract shipments, while EFSA novel food evaluations govern European market entry for concentrated botanical actives. China's NMPA and GB standards regulate residual solvent limits and pesticide thresholds in exported extract batches. Stakeholders must monitor evolving maximum residue limits across multiple jurisdictions to avoid supply chain disruptions.
Market Dynamics
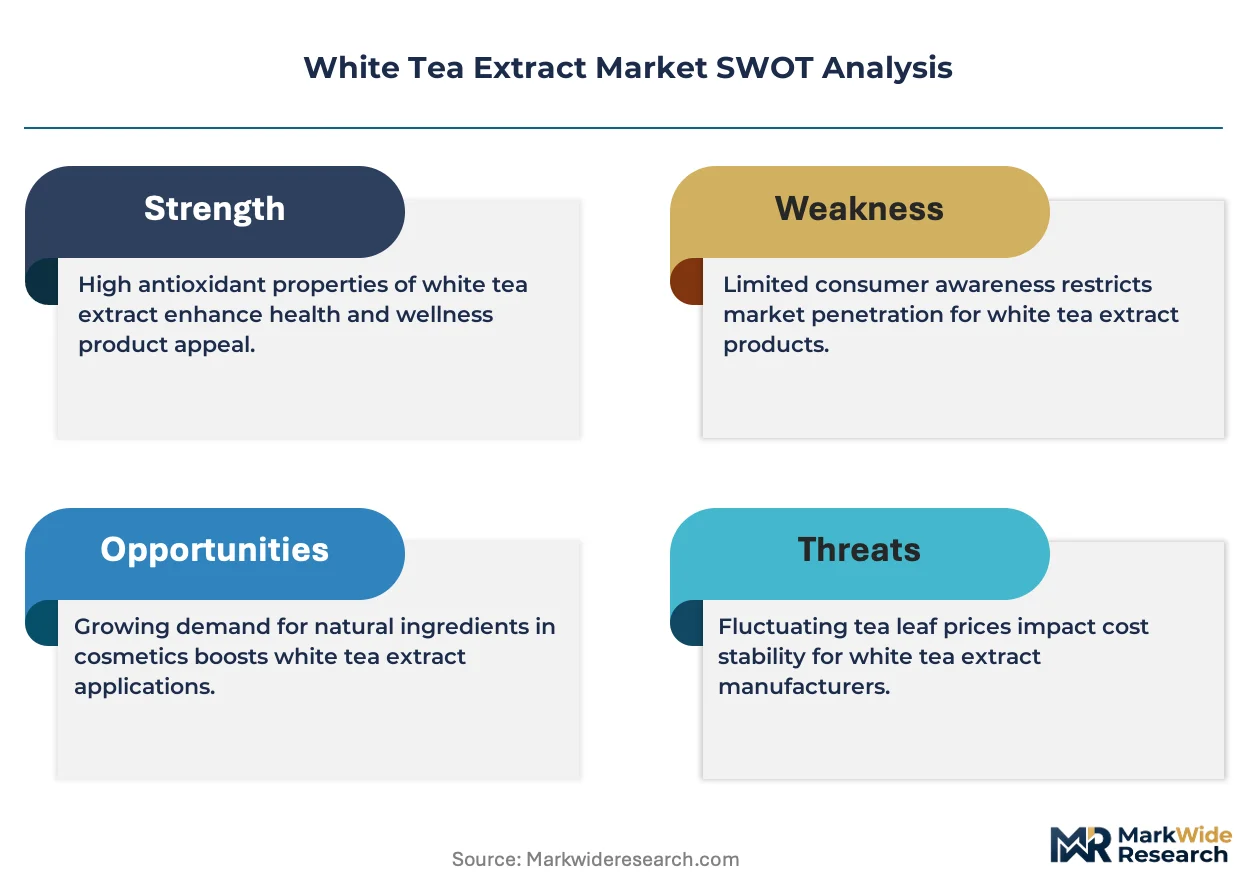
Cosmetic formulators are accelerating their shift from synthetic antioxidants to polyphenol-rich botanical actives, compressing procurement cycles for Fujian-sourced white tea extract and forcing extraction facilities to expand capacity ahead of certified garden output.
Growth Catalysts
- EU Green Deal botanical sourcing mandates:Cosmetics manufacturers across Germany and France must now document sustainable cultivation chains, elevating demand for certified organic white tea leaf from traceable Fujian gardens.
- Anti-aging skincare formulation chemistry:Epigallocatechin gallate (EGCG) standardization protocols now enable precise antioxidant dosing in premium topical products, pulling compound annual procurement volumes upward.
- China:Domestic nutraceutical brands are expanding encapsulated wellness lines featuring L-theanine and minimal-caffeine positioning, consuming larger shares of Ningde and Fuding harvests.
Market Restraints
- Raw material geographic concentration:Overreliance on Fujian Province's early-spring bud harvests creates weather-dependent supply volatility that propagates through global extraction facilities.
- Residual solvent compliance costs:China's GB standards and EFSA novel food evaluations impose divergent testing protocols, forcing dual-certification investments for cross-border shipments.
- Green tea extract substitution pressure:Lower-cost Camellia sinensis derivatives with comparable catechin profiles capture mid-tier functional beverage formulations.
Strategic Opportunities
- India:FSSAI's expanding novel food approvals create entry pathways for standardized white tea extract in domestic ayurvedic and wellness product lines.
- Clean-label preservative systems:Natural polyphenol complexes are displacing synthetic antioxidants in European and North American cosmetic preservation, opening premium positioning for high-EGCG concentrates.
- Supercritical CO2 and ultrasonic extraction convergence:Combined processing technologies are yielding higher bioavailability fractions suitable for pharmaceutical-grade encapsulation.
Industry Challenges
- Skilled extraction technician scarcity:Facilities struggle to hire operators proficient in both solvent recovery systems and catechin chromatography analysis.
- Multi-jurisdiction pesticide residue alignment:Harmonizing maximum residue limits across FDA, EFSA, and NMPA testing regimes extends batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Tea Extract Market |
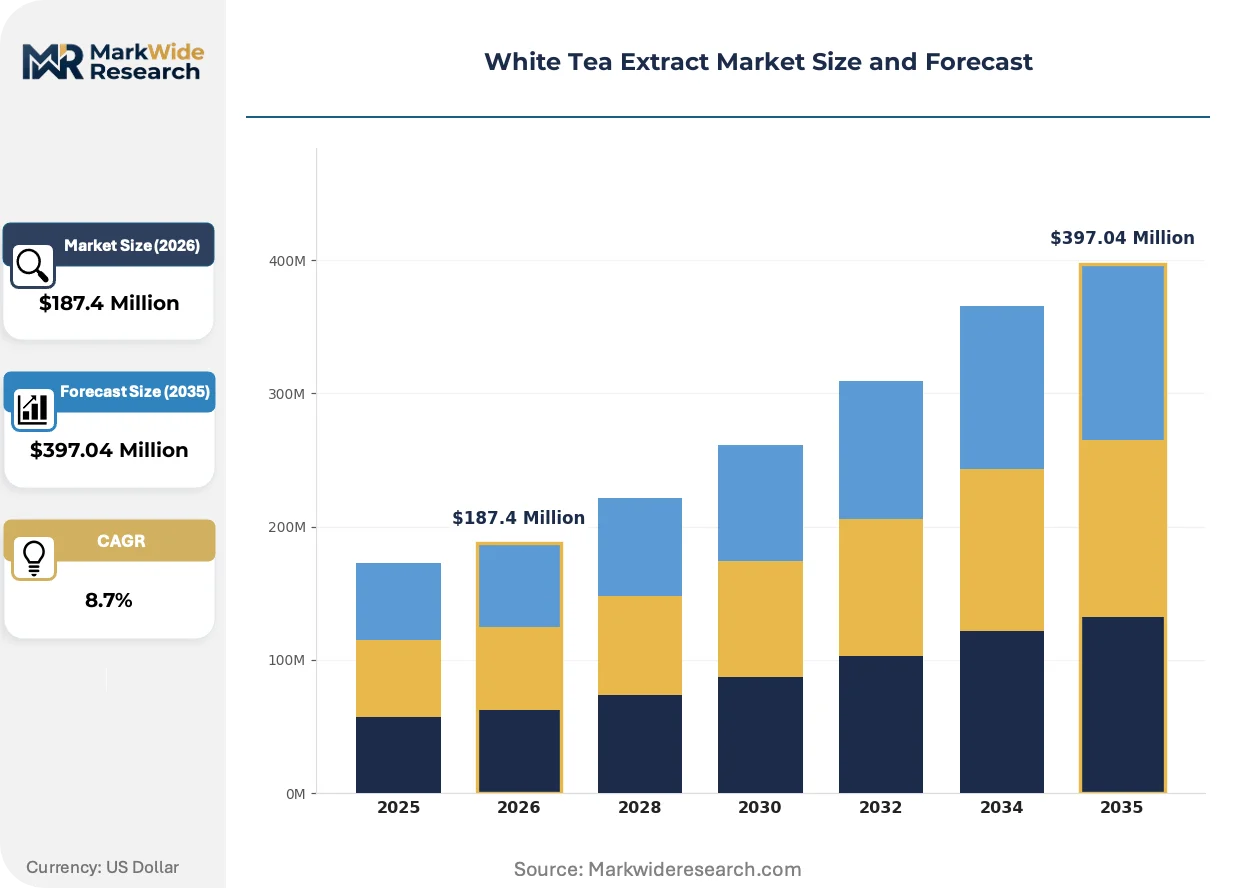
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tea Bags Application: Cosmetics, Food & Beverage, Dietary Supplements, Pharmaceuticals Packaging Type: Bottles, Sachets, Jars, Pouches Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Kemin Industries, ET-Chem, Organicway, Indena, NATURALIN Bio-Resources, Happy Herbalist, Sabinsa Corporation, Martin Bauer Group, TONYMOLY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Tea Extract Market Evolving Landscape
Extraction technology and regulatory chemistry are converging to redefine competitive positioning in white tea derivative supply chains.
Supercritical carbon dioxide extraction is integrating into mid-scale processing facilities to replace traditional solvent-based methods. Premium cosmetics manufacturers in South Korea and Japan are adopting CO2-derived concentrates for their cleaner label profiles. This shift is compressing margins for conventional ethanol-extraction operations while rewarding capital-intensive equipment investments.
EFSA's evolving novel food evaluation frameworks for concentrated botanical actives are tightening purity documentation requirements. European import clearance now demands batch-level heavy metal and pesticide certificates that many Asian suppliers cannot readily produce. Dietary supplement distributors are responding by consolidating procurement around vertically integrated extractors with in-house analytical laboratories.
Ingredient sourcing decisions are migrating from procurement departments to formulation R&D teams as brands compete on bioactive standardization claims. North American clean-beauty retailers now specify minimum EGCG percentages and caffeine thresholds in supplier contracts. This behavioral shift is most visible in California and New York, where direct-to-consumer skincare brands bypass traditional distributors to contract directly with Fujian-based extraction facilities.
White Tea Extract Market Segmentation
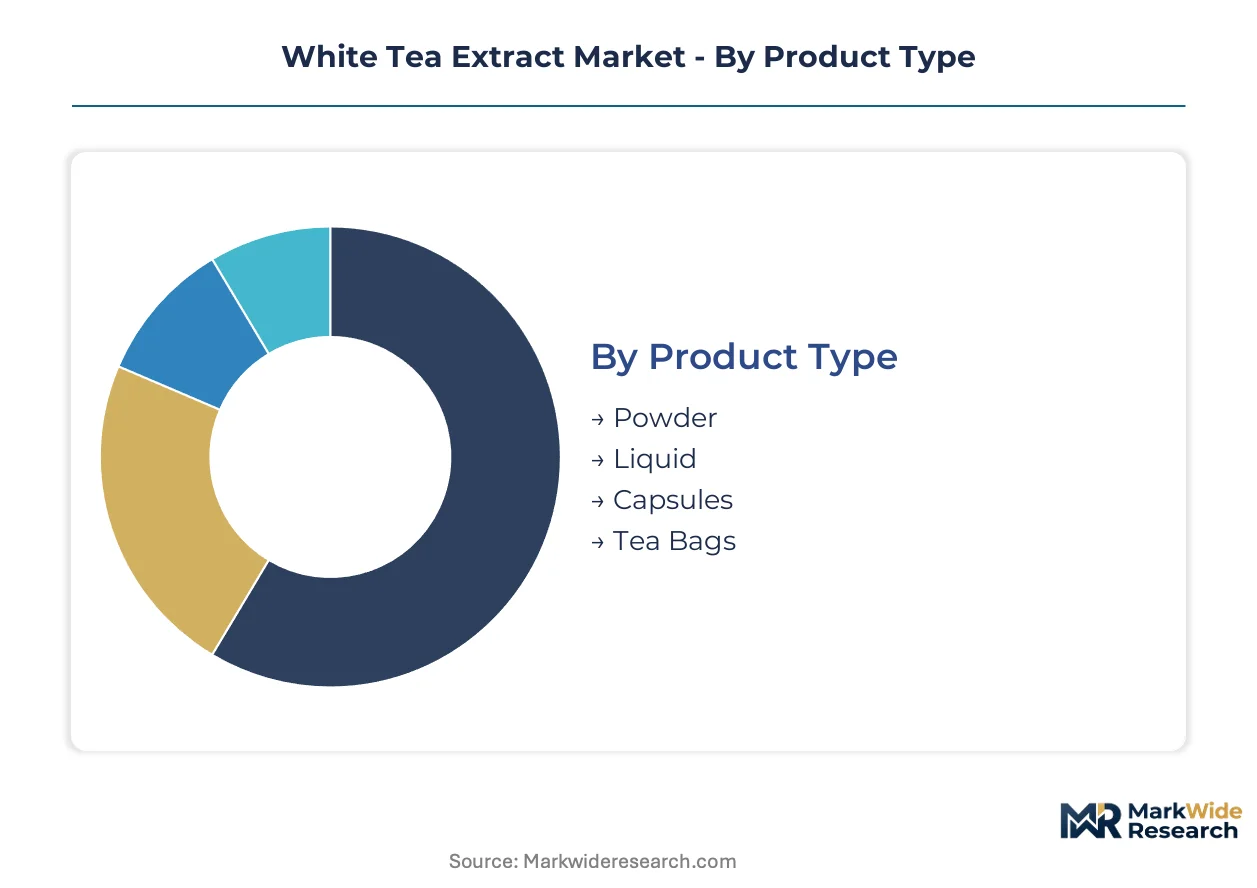
White tea extract procurement patterns diverge sharply across product formats and end-use channels. Cosmetics manufacturers prioritize standardized powder specifications, while beverage brands favor liquid concentrates for flavor integration. Understanding these segment boundaries reveals where margin pools concentrate and which formats face substitution pressure.
Product Type:
Powder and liquid formats dominate commercial procurement, with capsules and tea bags occupying distinct use-case niches rather than bulk ingredient flows.
- Powder:Spray-dried or freeze-dried concentrates with defined EGCG percentages and extended shelf stability. Dietary supplement encapsulation lines in North America and Europe standardize procurement around this format for dosing precision and powder flow properties in high-speed tableting equipment.
- Liquid:Aqueous or hydroalcoholic extracts standardized for polyphenol content and microbial specifications. Ready-to-drink functional beverage manufacturers in South Korea and Japan integrate these concentrates directly into bottling lines, where batch-to-batch consistency governs formulation chemistry.
- Capsules:Pre-encapsulated single-serve units for direct-to-consumer wellness brands.
- Tea Bags:Whole-leaf or cut-leaf formats for premium loose-tea retail channels.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
End-use segmentation tracks how extract specifications adapt to regulatory boundaries and formulation requirements across consumer categories.
- Cosmetics:Topical actives requiring low-caffeine, high-EGCG standardization for anti-aging and preservative-free positioning. South Korean formulators in Seoul's Gangnam district specify supercritical CO2-derived concentrates for clean-label claims, pulling procurement toward certified organic Fujian gardens with full pesticide documentation.
- Food & Beverage:Flavor-forward concentrates for functional drinks and fortified food matrices. Chinese domestic brands in Shanghai and Hangzhou are expanding L-theanine positioning for relaxation beverages, consuming larger shares of early-spring bud harvests from Ningde.
- Dietary Supplements:Encapsulated wellness products with bioavailability enhancement.
- Pharmaceuticals:Investigational and approved drug applications requiring GMP-grade extraction.
Cosmetics commands the largest revenue pool; Dietary Supplements is climbing the fastest as encapsulated wellness lines proliferate.
Packaging Type:
Packaging selection reflects shelf-life requirements, dosing convenience, and brand positioning across retail and professional channels.
- Bottles:Amber glass or PET containers for liquid extracts and bulk powder, dominant in professional and clinical procurement where light protection and resealability matter.
- Sachets:Single-serve foil laminates for hospitality and travel retail, gaining traction in Japanese convenience channels.
- Jars:Wide-mouth containers for bulk cosmetic raw material supply to formulators.
- Pouches:Flexible stand-up bags for economy-tier powder in emerging market retail.
Bottles anchor professional channel volume; Sachets is expanding most quickly in Asian travel retail.
Distribution Channel:
Channel structure determines pricing transparency, certification documentation flows, and minimum order quantities for extract procurement.
- Online Retail:Direct-to-consumer platforms enabling specification transparency and subscription models. California-based clean-beauty brands now bypass distributors to contract Fujian extraction facilities directly, compressing margin layers and demanding batch-level certificates of analysis.
- Specialty Stores:Premium health and beauty retailers with trained staff and sampling infrastructure.
- Supermarkets:Mass-market retail with private-label expansion in European markets.
- Direct Sales:B2B bulk supply to cosmetics manufacturers and beverage formulators.
Direct Sales handles the largest tonnage; Online Retail is gaining share fastest as specification transparency becomes a competitive weapon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian Province's agricultural processing zones concentrate raw material supply, while extraction facilities cluster near Ningde and Fuding under provincial tax incentives for botanical processing.
China
Domestic nutraceutical brands in Shanghai and Hangzhou expand encapsulated wellness lines featuring L-theanine positioning, consuming larger shares of Ningde and Fuding harvests. NMPA and GB standards regulate residual solvent limits and pesticide thresholds in exported extract batches. Fuzhou's extraction corridor hosts supercritical CO2 processing investments serving South Korean cosmetics clients.
United States
California-based clean-beauty retailers specify minimum EGCG percentages and caffeine thresholds in supplier contracts, compressing procurement cycles for standardized concentrates. FDA oversight of dietary supplement Good Manufacturing Practices shapes purity testing protocols for inbound shipments. Los Angeles and New York direct-to-consumer skincare brands bypass traditional distributors to contract directly with Fujian-based extraction facilities.
South Korea
Seoul's Gangnam district formulators specify supercritical CO2-derived concentrates for clean-label claims, pulling procurement toward certified organic Fujian gardens with full pesticide documentation. MFDS cosmetic ingredient regulations tighten documentation requirements for botanical actives. Incheon's import clearance hubs demand batch-level heavy metal certificates that consolidate procurement around vertically integrated extractors.
Germany
Cosmetics manufacturers across Germany must document sustainable cultivation chains under EU Green Deal botanical sourcing mandates, elevating demand for certified organic white tea leaf. EFSA novel food evaluations govern European market entry for concentrated botanical actives. Hamburg's botanical extraction distributors consolidate procurement around suppliers with in-house analytical laboratories.
India
FSSAI's expanding novel food approvals create entry pathways for standardized white tea extract in domestic ayurvedic and wellness product lines. Mumbai and Bangalore nutraceutical formulators experiment with L-theanine positioning for stress-relief supplements. Pune's contract manufacturing organizations build extraction capacity to serve European cosmetics clients seeking alternative sourcing beyond Fujian.
White Tea Extract Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with extraction technology capabilities determining tier placement more than scale alone. The vendor base organizes around three strategic archetypes: vertically integrated botanical houses with certified garden networks, technology licensors specializing in bioavailability enhancement, and regional processors serving domestic cosmetics formulators. Competitive moves concentrate on supercritical CO2 equipment investments and direct contracting relationships that bypass distributor layers.
Within the vertically integrated tier, Martin Bauer Group and Kemin Industries exemplify the garden-to-extraction model, while Sabinsa Corporation occupies a position emphasizing patented delivery technologies. These three anchors represent contrasting pathways to premium positioning—European sourcing certification, North American botanical infrastructure, and bioavailability intellectual property respectively.
| Leading Market Players |
|---|
| Kemin Industries |
| ET-Chem |
| Organicway |
| Indena |
| NATURALIN Bio-Resources |
| Happy Herbalist |
| Sabinsa Corporation |
| Martin Bauer Group |
| TONYMOLY |
| Others |
Value Network & Pricing Analysis
Premium cosmetics manufacturers in Seoul's Gangnam district and California-based clean-beauty brands command pricing power through direct contracting with Fujian extraction facilities, compressing margin layers for distributor-dependent suppliers and rewarding certified garden networks with traceable organic documentation.
Pricing Analysis
Short lead-time premiums dominate procurement economics as South Korean formulators pay 15-25% markups for certified organic concentrates with batch-level heavy metal certificates delivered within 30 days. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2-derived extracts with full EU Green Deal documentation from conventional ethanol-extracted volumes and unstandardized commodity grades. Cost compression in mid-tier liquid concentrates is intensifying because Indian contract manufacturers are expanding capacity to serve European clients seeking alternative sourcing beyond Fujian. Beverage brands in China's domestic market exhibit highest price sensitivity, while pharmaceutical encapsulation lines in North America prioritize purity certification over unit cost.
Supply Chain Analysis
Raw white tea leaf supply rests on Fujian Province's Ningde and Fuding agricultural zones, with secondary processing clusters in Fuzhou and emerging capacity in India's Pune corridor. Early-spring bud harvests, supercritical CO2 processing equipment, and chromatography-grade solvent recovery systems constitute the critical input triad. Single-source vulnerability concentrates in Fujian's weather-dependent early-spring harvest window, where frost or excessive rainfall propagates through global extraction facilities with no geographic hedge. Distribution runs through vertically integrated botanical houses with in-house analytical laboratories, bypassing traditional trader layers as batch-level certification requirements tighten.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in white tea extract supply chains hinges on backward integration into certified organic garden networks, as EFSA novel food evaluations and FDA dietary supplement GMP protocols reward players with captive control over cultivation documentation and pesticide compliance testing.
For Market Incumbents: Lock in multi-year offtake agreements with Fujian's certified organic gardens before EU Green Deal botanical sourcing mandates fully phase in, insulating procurement from weather-driven harvest volatility. Expand supercritical CO2 capacity in Fuzhou's extraction corridor to capture premium positioning from Seoul and Tokyo cosmetics formulators abandoning solvent-derived alternatives. Distributor disintermediation by direct-to-consumer brands in California and New York threatens traditional margin structures; respond by building proprietary analytical laboratories capable of batch-level heavy metal and pesticide documentation that independent traders cannot replicate. For New Entrants and Emerging Players: The premium-economy price gap in Indian domestic nutraceuticals offers fertile entry terrain, as FSSAI novel food approvals create regulatory pathways for standardized white tea extract in ayurvedic stress-relief formulations where incumbent presence remains thin. Target Mumbai and Bangalore wellness brands with L-theanine positioning and encapsulated delivery formats, leveraging Pune's emerging extraction infrastructure to bypass Fujian supply concentration. A contract manufacturing go-to-market angle minimizes capital requirements while building formulation chemistry relationships with domestic brands before vertical integration investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale extraction facilities with installed supercritical CO2 capacity and dormant EU organic certification in China's secondary processing zones, where provincial tax incentive exhaustion and technician scarcity are compressing valuations. Long-term viability over the coming decade rests on regulatory chemistry capabilities—players with in-house analytical laboratories and multi-jurisdiction compliance expertise will consolidate share as batch documentation requirements tighten. Watch EFSA's evolving maximum residue limit harmonization proposals as the critical inflection signal; alignment across FDA, EFSA, and NMPA regimes would abruptly consolidate procurement around laboratories with cross-jurisdiction testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Gardens | EU Green Deal mandates reward traceable organic sourcing from Fujian's Ningde and Fuding zones. |
| Supercritical CO2 Capacity Expansion | Seoul and Tokyo formulators specify cleaner-label extraction methods for premium cosmetic actives. |
| In-House Analytical Laboratory Investment | Batch-level heavy metal certificates now required at Incheon import clearance hubs. |
| Direct-to-Brand Distribution Bypass | California clean-beauty retailers contract Fujian facilities directly, eliminating margin layers. |
| India Market Entry via FSSAI Pathway | Novel food approvals open ayurvedic and wellness product lines in Mumbai and Bangalore. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction facility managers, cosmetics formulation chemists in Seoul and Los Angeles, dietary supplement procurement leads, and botanical distributor principals in Hamburg. NMPA GB standard documentation, EFSA novel food evaluation frameworks, and FDA dietary supplement GMP guidance formed the regulatory backbone. Bottom-up volume triangulation across powder and liquid format shipments reconciled with top-down value estimates from certified organic premium tiers.
Granularity-level modeling distinguished product format specifications, application chemistry requirements, and packaging type shelf-life economics across the projection horizon. Segmentation dimensions included extraction technology tier, end-use regulatory cluster, and geographic certification burden. CAGRs were derived from slope analysis of annual procurement volume trajectories, with cross-validation against garden harvest yield projections and supercritical CO2 equipment installation pipelines.
Inputs from Fujian provincial agricultural bureaus and South Korean MFDS cosmetic ingredient registries were available through the study window; gaps in real-time batch-level pesticide residue testing data introduce uncertainty bands around near-term supply volatility estimates. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and FSSAI novel food approval timelines. Weather-driven harvest disruption in Fujian and EFSA maximum residue limit harmonization proposals warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Matcha Market
Tea
US RTD Organic Tea Market
Tea
Organic Tea Market
Tea
Herbal Tea Market
Tea
Probiotic Tea Market
Tea
Slimming Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Pu-Erh Tea Market
Tea
Green Tea Market
Tea
Global Tea Extract Market
Tea
Tea Concentrate Market
Tea
Global Catechin Market
Tea
Asia-Pacific Organic Tea Market
Tea
Africa Ready to Drink Tea Market