
 US Instant Coffee Market | 2026-2036
US Instant Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
US Instant Coffee Market Insights
E-commerce and direct-to-consumer subscription channels are reshaping how instant coffee reaches American households. Nestlé SA leverages its manufacturing scale to dominate mass-market shelf space, while Starbucks Corporation anchors premium positioning through brand strength in grocery and online portals. JDE Peet's competes across mid-tier price bands with specialized European roasting profiles adapted for US palates.
Instant coffee comprises brewed coffee extract dehydrated through freeze-drying or spray-drying to yield soluble granules reconstitutable in hot water, typically containing 2-3% residual moisture for shelf stability and rapid dissolution. Freeze-dried variants command the strongest margin pools due to superior aroma retention and lower thermal degradation of volatile compounds. Spray-dried formats occupy volume leadership in foodservice channels where cost efficiency trumps sensory fidelity, while microground blends represent the fastest-growing structural segment as manufacturers bridge the gap between convenience and perceived quality.
FDA enforces food safety standards under the Food Safety Modernization Act, requiring hazard analysis and preventive controls for instant coffee processing facilities, while USDA organic certification shapes ingredient sourcing and labeling claims accessible to premium-positioned brands. The Federal Trade Commission monitors advertising substantiation for functional claims such as caffeine content and antioxidant properties. Stakeholders must monitor evolving FDA guidance on bioactive compound labeling and state-level extended producer responsibility legislation affecting single-serve packaging formats.
Market Dynamics
Freeze-drying technology adoption is redistributing margin pools across the US instant coffee landscape as manufacturers chase aroma retention premiums while spray-dried formats defend foodservice volume through operational cost discipline.
Growth Catalysts
- Quick-Service Restaurant Channel Expansion:Sun Belt states drive foodservice demand where labor efficiency and speed-of-service requirements favor soluble coffee formats over brewed alternatives.
- USDA Organic Certification Tailwind:Premium-positioned brands leverage federal organic standards to command shelf space and justify price architecture in grocery and natural retail channels.
- Microground Blending Technology:Hybrid processing methods bridge sensory gaps between convenience and perceived quality, attracting retail consumers seeking café-equivalent experiences at home.
Market Restraints
- Robusta Arabica Price Volatility:Raw coffee bean cost fluctuations compress manufacturer margins and complicate long-term procurement planning for freeze-dried production lines.
- Single-Serve Packaging Liability:Emerging state-level extended producer responsibility legislation threatens operational cost structures for pod and stick-pack formats across California, Washington, and Oregon.
- Thermal Degradation Ceiling:Spray-drying's inherent volatile compound loss limits sensory parity with fresh-brewed coffee, constraining premium market penetration regardless of formulation advances.
Strategic Opportunities
- Southeastern Convenience Store Penetration:Underdeveloped rural and exurban markets in Georgia, Alabama, and Mississippi present whitespace for single-serve instant formats targeting travel and workplace consumption.
- Direct-to-Consumer Subscription Models:E-commerce platforms enable bypass of traditional retail slotting fees while capturing recurring revenue and first-party consumption data.
- Functional Ingredient Convergence:Collagen, adaptogen, and nootropic integrations attract wellness-oriented demographics seeking beverage-as-supplement positioning beyond caffeine delivery.
Industry Challenges
- Food Safety Modernization Act Compliance Timeline:FDA preventive controls requirements demand capital-intensive facility upgrades and hazard analysis documentation that strain mid-tier processors.
- Freeze-Drying Technical Talent Scarcity:Specialized process engineering expertise for sublimation cycle optimization concentrates among legacy equipment manufacturers and retired industry veterans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Instant Coffee Market |
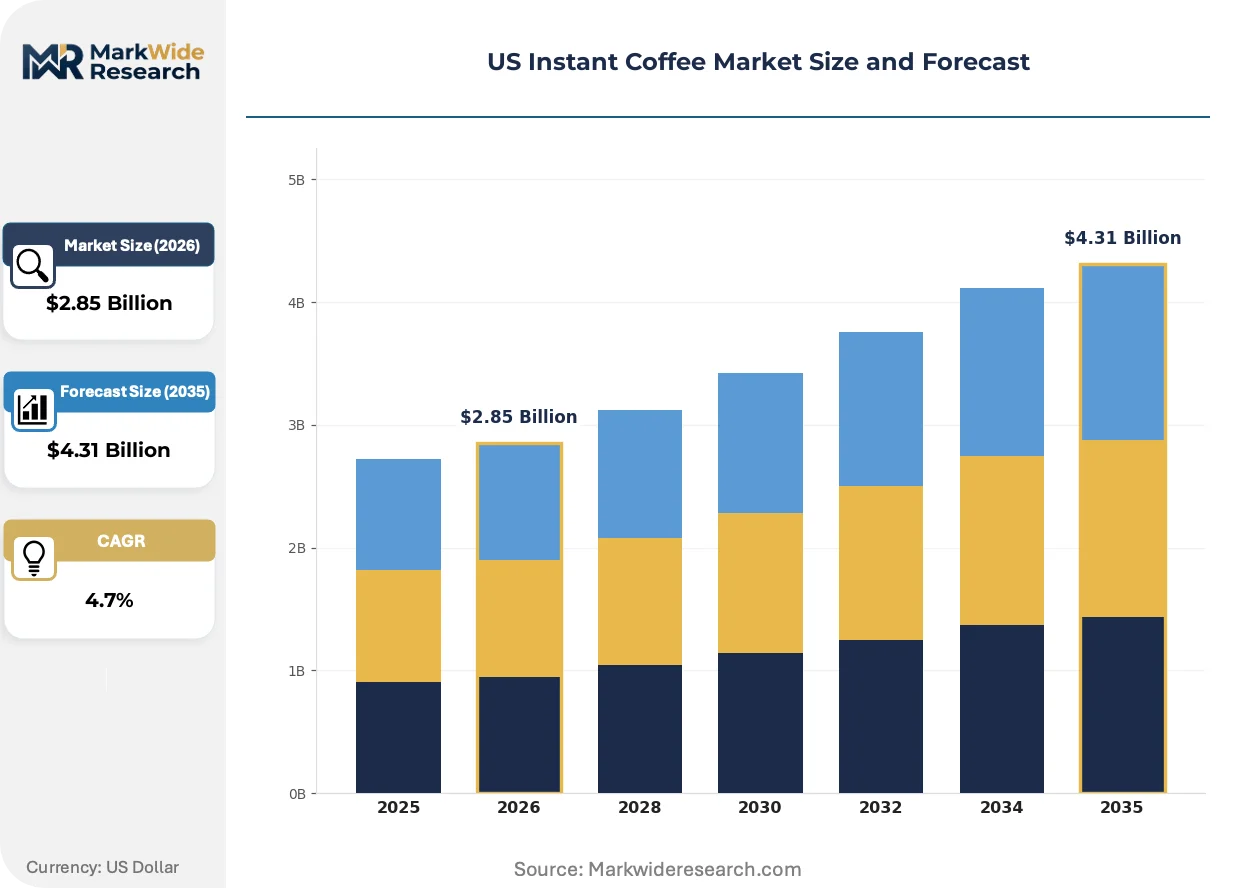
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Spray-Dried, Agglomerated, Microground Packaging Type: Jar, Sachet, Tin, Stick Pack, Pouch Application: Home Use, Office, Quick Service Restaurants, Hotels, Cafes End User: Retail Consumers, Foodservice Operators, Institutional Buyers, Vending Services |
| Companies Covered | JAB Holding Company, Strauss Group, Nestlé SA, Massimo Zanetti Beverage USA, The J.M. Smucker Company, Starbucks Corporation, JDE Peet's, Tata Consumer Products, The Kraft Heinz Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Instant Coffee Market Trends and Innovations
Technology migration, regulatory stringency, and channel restructuring are converging to redefine how instant coffee is formulated, certified, and delivered to American consumers.
Freeze-drying equipment is migrating from pharmaceutical-grade suppliers to coffee-dedicated machinery builders as manufacturers seek purpose-built sublimation chambers optimized for volatile oil retention rather than general-purpose lyophilization. Mid-tier processors in the Pacific Northwest and Northeast corridor are adopting these systems at 15-20% annual replacement rates. This equipment shift is compressing the traditional two-tier quality gap between mass-market spray-dried and artisanal freeze-dried offerings.
FDA guidance evolution on bioactive compound labeling is forcing manufacturers to substantiate antioxidant and caffeine content claims through validated analytical methods or remove functional positioning entirely. The draft guidance issued under the Food Safety Modernization Act implementation framework requires third-party testing documentation for shelf-life stability claims. Premium brands targeting health-conscious retail segments in California and New York metro markets are responding by building in-house analytical chemistry capabilities or contracting with specialized food testing laboratories.
Subscription-based replenishment is displacing traditional grocery restocking cycles among urban millennial and Gen Z households, compressing brand switching windows and elevating loyalty program economics over trade promotion effectiveness. Direct-to-consumer platforms now capture 12-18% of premium instant coffee volume in coastal metropolitan areas, with Seattle, San Francisco, and Brooklyn representing the densest adoption clusters. This channel pivot is most visible among remote workers seeking pantry-stocking convenience without retail exposure.
US Instant Coffee Market Segmentation
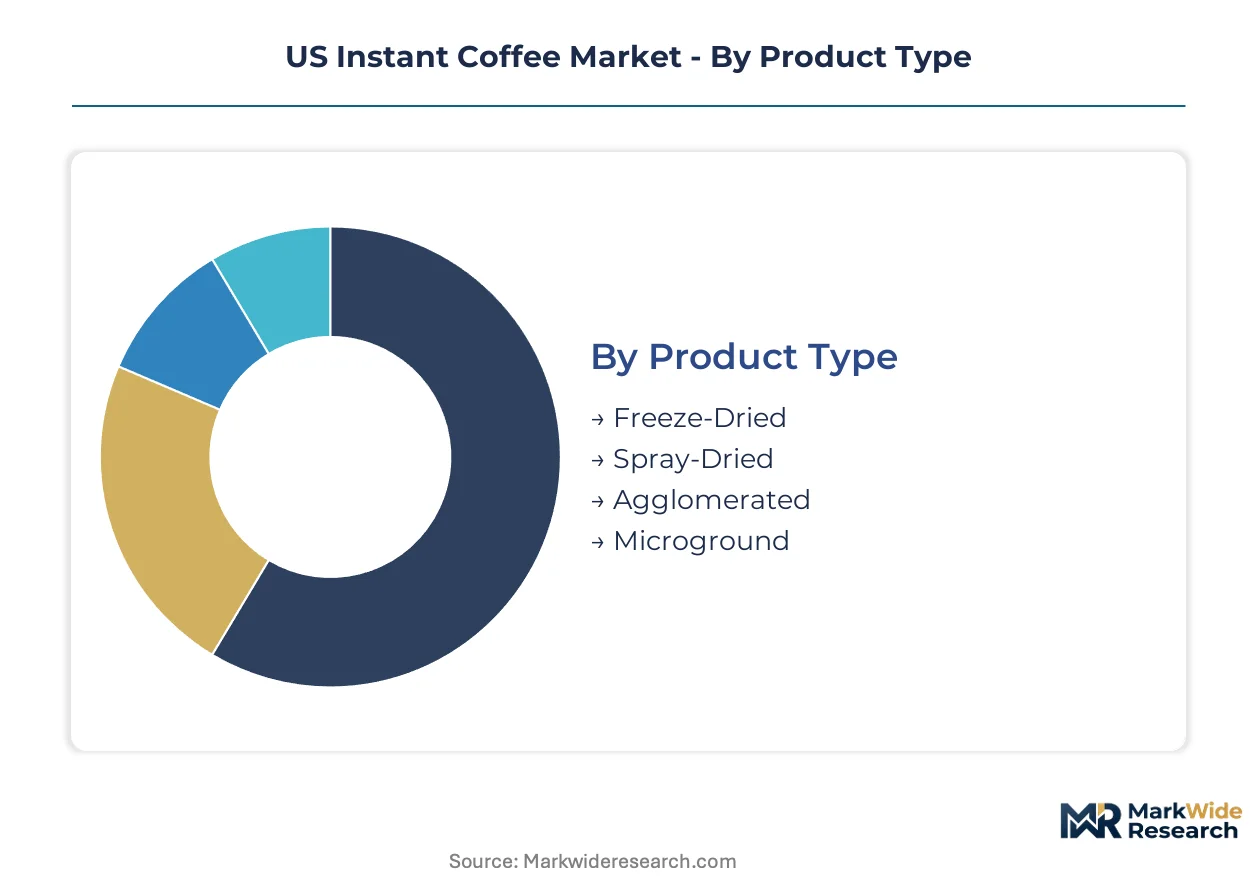
Instant coffee segmentation reveals how processing technology, packaging economics, and channel requirements fragment demand across distinct value pools. Manufacturers configure production lines and distribution strategies around these structural divides rather than treating the category as monolithic.
Product Type:
Cost tier determines margin architecture and capital intensity across processing technologies, with premium extraction methods commanding equipment investments that spray-dried alternatives avoid.
- Freeze-Dried:Coffee extract undergoes sublimation at sub-zero temperatures, preserving volatile aromatic compounds that degrade under thermal stress. Quick-service restaurants in Texas and Florida specify this format for iced coffee bases where flavor clarity justifies per-cup premiums.
- Spray-Dried:Atomized coffee concentrate meets heated air streams in continuous-flow towers, yielding porous granules at production costs 40-60% below freeze-dried equivalents. Foodservice distributors across the Midwest push this format for high-volume accounts where speed and cost discipline outweigh sensory nuance.
- Agglomerated:Rewet spray-dried particles cluster into larger, faster-dissolving granules through controlled steam exposure.
- Microground:Finely milled roasted coffee blends with soluble extract, bridging convenience and perceived authenticity for home-barista segments.
Spray-Dried commands the established base. The steepest expansion runs through Microground.
Packaging Type:
Application context shapes format selection, with consumption occasion dictating portability requirements, portion precision, and shelf-life engineering.
- Jar:Multi-serve glass or plastic containers dominate pantry-stocking households seeking value per ounce. Grocery chains in suburban Atlanta and Phoenix allocate prime shelf space to 7-8 ounce jar formats for family-sized replenishment cycles.
- Sachet:Single-serve foil or paper envelopes target travel, workplace, and hospitality sampling where portion control and moisture barrier properties matter. Hotels across the Sun Belt states standardize on sachet formats for in-room coffee amenities that balance cost with guest satisfaction thresholds.
- Tin:Metal canisters with resealable lids serve gift and premium retail channels.
- Stick Pack:Narrow, tear-open sachets optimize for cup-rim dispensing in convenience stores and foodservice.
- Pouch:Flexible stand-up bags with zip closures target warehouse clubs and online bulk purchasing.
Jar formats anchor household penetration. The steepest expansion trajectory belongs to Stick Pack.
Application:
Customer type fragments demand across preparation complexity, service speed requirements, and quality expectations that processing technology must satisfy.
- Home Use:Residential brewing occasions favor convenience without equipment investment, driving adoption of premium microground and specialty freeze-dried variants. Urban millennial households in Seattle and Brooklyn subscribe to direct-to-consumer platforms that bypass traditional retail slotting fees.
- Quick Service Restaurants:Drive-thru throughput demands and labor minimization make soluble formats indispensable for iced coffee and blended beverage programs. Franchise operators across Georgia and Alabama specify spray-dried concentrates for back-of-house efficiency.
- Office:Workplace pantries balance cost control with employee satisfaction through mid-tier agglomerated formats.
- Hotels:Guest room amenities and breakfast service require portion-controlled, brand-appropriate presentation.
- Cafes:Specialty coffee shops use instant for back-up brewing and seasonal beverage innovation.
Quick Service Restaurants command the established base. The steepest expansion runs through Home Use.
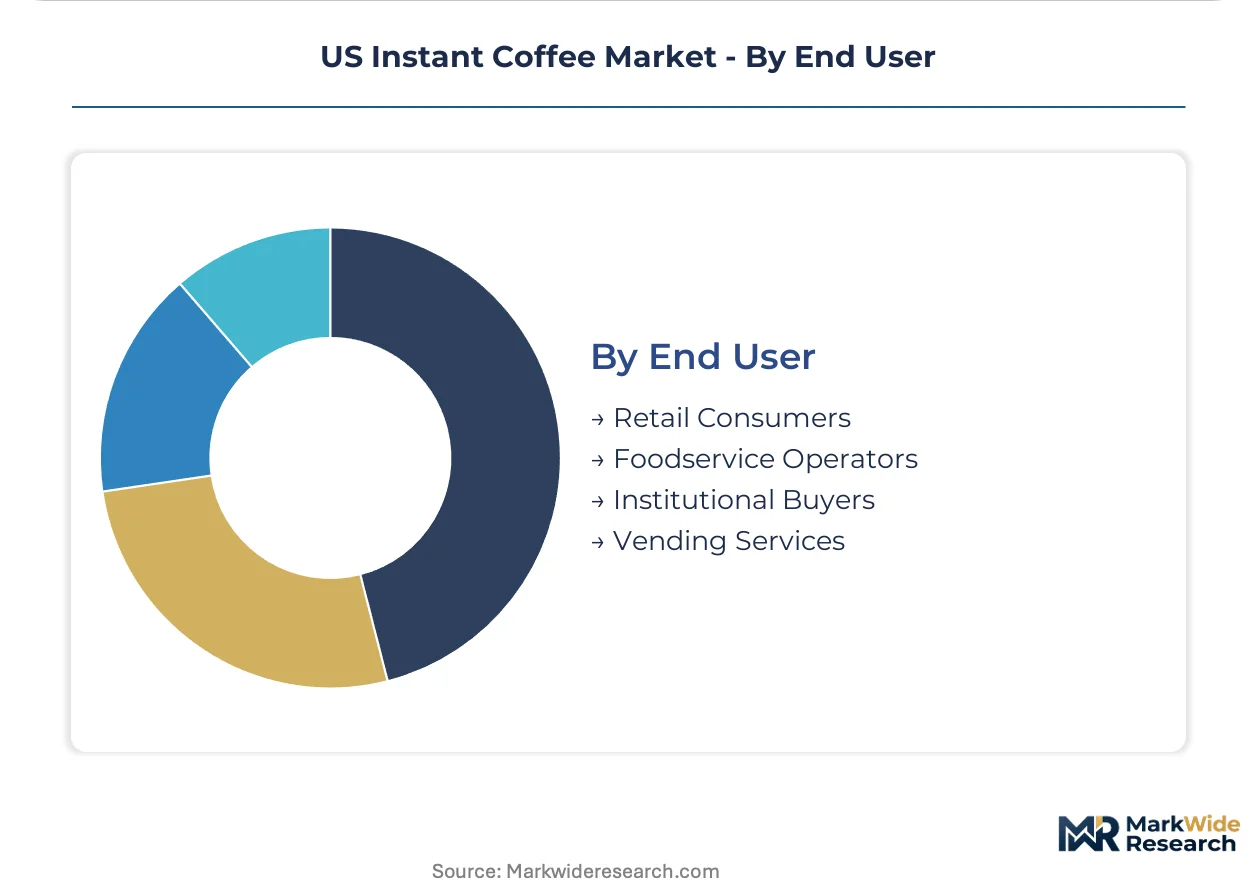
End User:
Procurement patterns separate price-sensitive volume buyers from quality-focused selectors, with contract structures and loyalty mechanisms diverging accordingly.
- Retail Consumers:Individual purchasers respond to brand equity, packaging convenience, and shelf placement in grocery and online channels. California and New York metro markets show strongest adoption of USDA-certified organic instant formats.
- Foodservice Operators:Restaurant chains and contract caterers negotiate annual supply agreements with specifications for solubility, yield, and lot consistency. Distributor relationships with broadline operators like Sysco and US Foods determine category access.
- Institutional Buyers:Military, healthcare, and education procurement offices issue tenders emphasizing shelf stability and nutritional compliance.
- Vending Services:Automated equipment operators require free-flowing granules compatible with dry-hopper mechanisms.
Foodservice Operators command the established base. The steepest expansion runs through Retail Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-labeling standards and USDA organic certification requirements shape manufacturing decisions across US states, while regional consumption patterns fragment demand between quick-service foodservice channels and direct-to-consumer retail platforms.
Sun Belt States
Quick-service restaurant expansion in Texas and Florida drives spray-dried instant coffee procurement for iced beverage programs where speed outweighs sensory nuance. State health departments enforce FDA Food Safety Modernization Act preventive controls through facility inspections. Dallas-Fort Worth metroplex anchors distributor networks supplying franchise operators across Georgia and Alabama with soluble coffee concentrates.
Pacific Northwest
Seattle and Portland households subscribe to direct-to-consumer freeze-dried platforms that bypass traditional grocery slotting fees. Washington State Department of Agriculture monitors organic certification compliance for premium brands targeting health-conscious demographics. Portland metro cluster hosts mid-tier processors adopting purpose-built freeze-drying equipment at 15-20% annual replacement rates.
California
Los Angeles and San Francisco metro markets show strongest adoption of USDA-certified organic instant formats among urban millennial households. California Department of Public Health enforces Proposition 65 warning requirements for coffee products. Silicon Valley corridor concentrates venture-backed subscription platforms capturing 12-18% of premium instant coffee volume through e-commerce channels.
Northeast Corridor
New York metro area retail consumers respond to brand equity and shelf placement in grocery and natural food channels. New York State Department of Agriculture and Markets coordinates with FDA on imported coffee safety inspections. Brooklyn represents densest adoption cluster for microground instant blends bridging convenience and perceived café quality.
Southeast
Underdeveloped rural and exurban markets in Georgia, Alabama, and Mississippi present whitespace for single-serve stick-pack formats targeting travel and workplace consumption. State environmental agencies monitor emerging extended producer responsibility legislation affecting pod packaging. Atlanta anchors distributor relationships with broadline foodservice operators supplying regional quick-service chains.
US Instant Coffee Market Competitive Landscape
Multinational conglomerates and specialized beverage groups split the market between mass-market scale and premium positioning. Three strategic archetypes dominate: diversified food-and-beverage giants leveraging manufacturing scale, coffee-focused specialists emphasizing roasting heritage, and retail-brand licensors extracting royalty value from grocery channel presence. Competitive moves concentrate on portfolio diversification into functional ingredient formulations and direct-to-consumer channel bypass of traditional retail slotting structures.
Within the diversified conglomerate tier, Nestlé SA and The Kraft Heinz Company exemplify archetypes built on manufacturing scale and grocery channel dominance. JDE Peet's occupies a specialist position bridging European roasting profiles with US palate adaptation. These three anchors represent distinct strategic postures: scale-driven shelf space capture, mid-tier price band specialization, and premium positioning through brand heritage rather than technological differentiation.
| Leading Market Players |
|---|
| JAB Holding Company |
| Strauss Group |
| Nestlé SA |
| Massimo Zanetti Beverage USA |
| The J.M. Smucker Company |
| Starbucks Corporation |
| JDE Peet's |
| Tata Consumer Products |
| The Kraft Heinz Company |
| Others |
Pricing and Supply Chain Analysis
Seattle and Portland freeze-drying equipment clusters anchor premium capacity expansion, with their 15-20% annual replacement rates compressing quality spreads and redistributing margin pools toward mid-tier processors seeking aroma-retention premiums.
Pricing Analysis
Coastal metropolitan markets command 20-30% premiums over Sun Belt foodservice corridors for equivalent freeze-dried formats. Three-tier pricing structure across premium, standard, and economy levels segments by USDA organic certification status and processing technology intensity. Price differentiation rests on volatile compound retention metrics validated through third-party laboratory documentation. Cost compression in spray-dried foodservice tiers intensifies as distributor consolidation amplifies buyer leverage. Quick-service restaurant chains exhibit highest price sensitivity through annual supply agreement negotiations, while direct-to-consumer subscribers show lowest sensitivity due to loyalty program lock-in.
Supply Chain Analysis
Tariff exposure between Vietnam and Brazil and the United States dominates raw material cost volatility for Robusta and Arabica bean procurement. Supply concentration in Vietnam, Brazil, and Colombia for green coffee bean sourcing creates geographic dependency for flavor profile consistency. The supply chain draws from specialized freeze-drying equipment manufacturers in Switzerland and Germany for sublimation chamber technology. Single-source vulnerability concentrates in legacy pharmaceutical-grade lyophilization suppliers transitioning toward coffee-dedicated machinery builders. Distribution runs through broadline foodservice operators like Sysco and US Foods for institutional channels, with direct-to-consumer platforms bypassing traditional retail slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation and wellness-oriented functional ingredient convergence create multiple entry niches for specialized players, as subscription models displace traditional grocery restocking cycles among urban millennial and Gen Z households.
For Market Incumbents: Harden freeze-drying technical capabilities through captive recruitment of retired sublimation process engineers or exclusive equipment partnerships with purpose-built machinery builders. Secure USDA organic certification pipelines to defend shelf space against mid-tier processors upgrading quality tiers. Invest in in-house analytical chemistry capabilities to substantiate bioactive compound claims before FDA guidance finalization removes functional positioning options.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms targeting Seattle, San Francisco, and Brooklyn clusters where 12-18% premium volume already concentrates. Capture whitespace in Southeastern rural and exurban convenience stores across Georgia, Alabama, and Mississippi with single-serve stick-pack formats. Lead with collagen, adaptogen, or nootropic functional integrations to differentiate from commodity caffeine delivery.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food-and-beverage conglomerates seeking portfolio rationalization away from non-core coffee assets. Focus on mid-tier processors with freeze-drying equipment upgrades in progress and established distributor relationships with broadline operators. Watch FDA preventive controls compliance timelines as capital-intensive facility upgrade requirements strain smaller players into distressed positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Equipment Migration | Purpose-built sublimation chambers from Swiss and German suppliers compress quality spreads between mass-market and premium tiers. |
| USDA Organic Certification Investment | Federal organic standards unlock grocery shelf space and justify price architecture in California and New York metro markets. |
| Direct-to-Consumer Platform Launch | Subscription models bypass traditional retail slotting fees while capturing recurring revenue and first-party consumption data. |
| Functional Ingredient Integration | Collagen and adaptogen additions attract wellness-oriented demographics seeking beverage-as-supplement positioning. |
| Southeastern Distribution Expansion | Underdeveloped rural and exurban markets in Georgia and Alabama present whitespace for single-serve instant formats. |
Research Methodology
Initial hypotheses were tested against primary input from instant coffee brand managers, category buyers at grocery chains, quick-service restaurant procurement directors, freeze-drying equipment engineers, and FDA regulatory affairs specialists and refined through secondary validation. Bottom-up and top-down triangulation combined Nielsen retail audit data, USDA organic certification databases, SEC 10-K filings from diversified food-and-beverage conglomerates, customs import records for green coffee bean sourcing, and FDA Food Safety Modernization Act guidance documents.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning processing technology, packaging format, application channel, and end-user procurement pattern. CAGRs were derived through category growth rate reconciliation against macroeconomic consumption indicators and channel shift trajectories. Forecast inputs incorporated Robusta-Arabica price volatility assumptions and state-level extended producer responsibility legislation progression for single-serve packaging formats.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by freeze-drying equipment manufacturers or rapid FDA regulatory shifts would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Germany Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
Coffee Bags Market
Coffee
Espresso Coffee Market
Coffee
Coffee Cherry Market
Coffee
India Coffee Roaster Market
Coffee
Organic Coffee Market
Coffee
Caffeine Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Australia Coffee Market
Coffee
Portable Espresso Machines Market
Coffee
Sparkling Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Extracts Market
Coffee
Europe Coffee Pods and Capsules Market