
 Out of Home Tea Market | 2026-2036
Out of Home Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Out of Home Tea Market Analysis
Multi-source procurement for premium tea leaves is realigning supply strategies across the out-of-home channel. Tata Consumer Products Limited leverages its integrated estate network to secure consistent orthodox leaf supply for foodservice clients. Starbucks Corporation anchors its tea platform through controlled sourcing partnerships that emphasize traceability and seasonal rotation. Ito En Ltd specializes in Japanese green tea varietals, competing primarily on cultivar authenticity and cold-brew processing expertise.
Out of home tea encompasses brewed and ready-to-serve tea beverages prepared and sold outside residential settings, typically requiring water temperature control between 175°F and 212°F depending on oxidization level and intended extraction profile. The category serves commercial refreshment needs across hospitality, workplace, and transit environments where convenience and experiential quality converge. Black tea maintains the largest volume share within product type segmentation, though specialty tea commands disproportionate margin contribution through limited-origin positioning and ceremonial service formats. Ready-to-drink bottled formats within packaging type segmentation are expanding fastest in vending machine and corporate end user channels, driven by grab-and-go consumption patterns in transit hubs and office complexes.
FDA food facility registration and Hazard Analysis Critical Control Point protocols govern processing standards for ready-to-distribute tea concentrates in the United States, while EFSA novel food assessments shape ingredient approval pathways for botanical infusions across European Union member states. China's SAMR enforces GB standards for tea product classification and residue limits that directly affect import eligibility for foreign suppliers targeting foodservice distributors. Stakeholders must monitor evolving caffeine disclosure mandates and single-use packaging restrictions that threaten to alter formulation priorities and serving formats across key demand corridors.
Market Dynamics
Wellness-oriented beverage preferences are restructuring procurement priorities across foodservice channels, forcing operators to source traceable orthodox leaf and certified botanical infusions at premium contract terms.
Growth Catalysts
- Cold-brew processing infrastructure:Quick-service restaurants deploy nitrogen-chilled extraction systems to serve unsweetened Japanese green tea varietals on tap, capturing transit-hub traffic.
- FDA food facility registration:Concentrate suppliers achieving Hazard Analysis Critical Control Point certification gain preferential access to US corporate vending channels and institutional foodservice contracts.
- China's GB standards alignment:Foreign leaf processors certifying residue compliance under SAMR enforcement protocols unlock distribution through domestic foodservice distributors serving ceremonial tea houses.
Market Restraints
- Orthodox leaf supply concentration:Premium estate output from Assam and Darjeeling clusters faces climate volatility, compressing margin buffers for blended product lines.
- Single-use packaging restrictions:EU member states implementing extended producer responsibility mandates threaten ready-to-drink bottle economics in vending and grab-and-go channels.
- Caffeine disclosure mandates:Evolving labeling requirements across multiple jurisdictions force reformulation of energy-positioned tea concentrates and botanical blends.
Strategic Opportunities
- Workplace refreshment modernization:Corporate campus contracts for temperature-controlled brewing equipment create recurring revenue streams beyond commodity leaf sales.
- Botanical infusion approvals:EFSA novel food assessments for adaptogenic ingredients open formulation pathways for wellness-positioned ready-to-serve lines.
- Transit hub automation:Airports and rail terminals in China deploy robotic brewing stations serving traditional oolong and pu-erh formats to captive passenger flows.
Industry Challenges
- Certified tea sommelier scarcity:Foodservice operators struggle to staff ceremonial service formats requiring precise water temperature control and origin storytelling.
- Cold chain capex intensity:Ready-to-drink distribution into corporate channels demands refrigerated last-mile infrastructure that strains mid-cap supplier balance sheets.
- Dual carbon compliance:China's MEE enforcement of energy efficiency standards in processing facilities forces retrofit investments for export-oriented concentrate plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out of Home Tea Market |
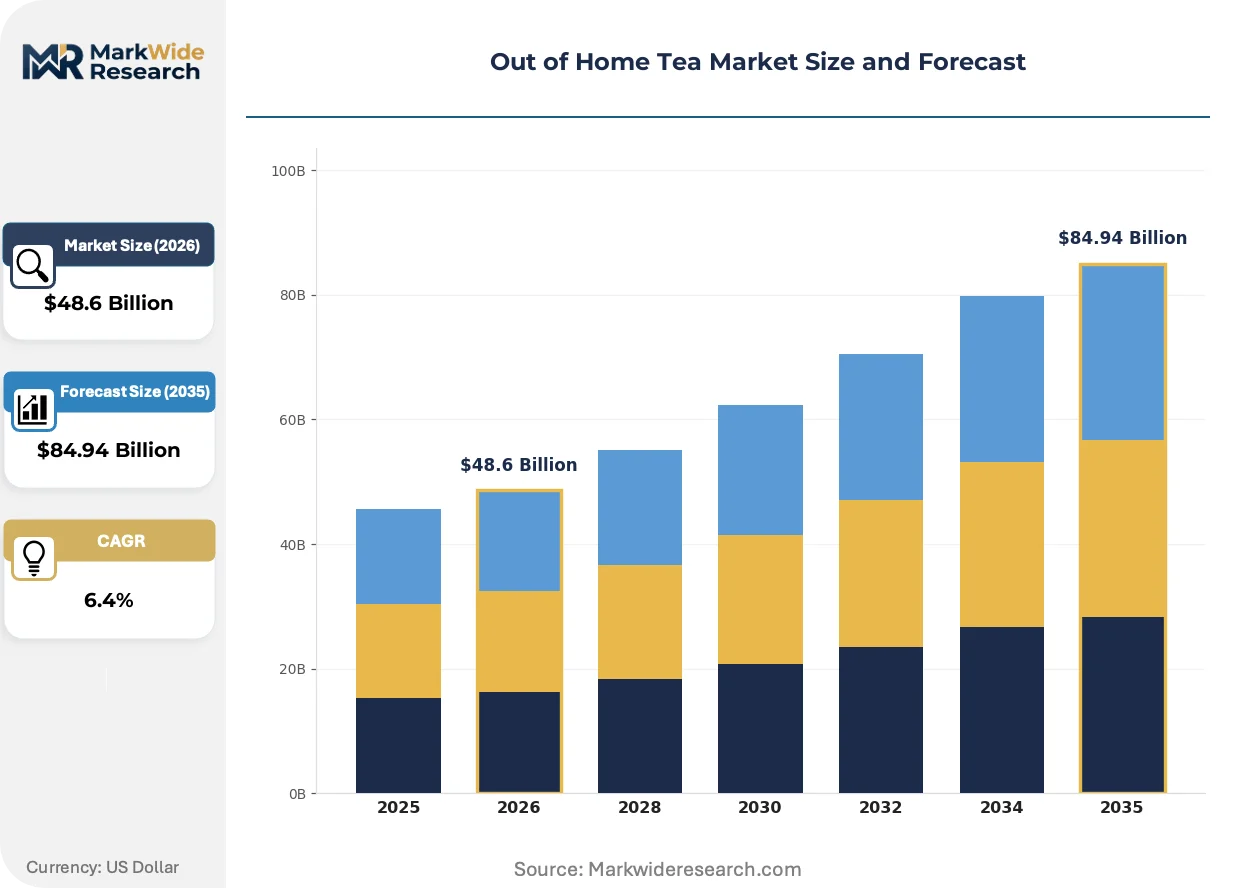
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Specialty Tea Distribution Channel: Cafes, Restaurants, Vending Machines, Events End User: Individuals, Corporates, Students, Tourists Packaging Type: Loose Leaf, Tea Bags, Ready-to-Drink, Bottled |
| Companies Covered | Unilever Plc, Tata Consumer Products Limited, Nestle S.A., Associated British Foods, Ito En Ltd, Starbucks Corporation, The Republic of Tea, Barry’s Tea, Celestial Seasonings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out of Home Tea Market Emerging Trajectories
Digital traceability platforms and automated extraction systems are compressing the gap between estate harvest and cup service, while regulatory pressure on packaging and disclosure reshapes formulation roadmaps.
Nitrogen-chilled cold-brew systems are consolidating control over flavor stability and shelf-life extension in ready-to-serve formats. Airport concessionaires and corporate campus operators adopt these units fastest, replacing traditional hot-brew dispensers. This hardware shift is consolidating supplier power among equipment-integrated concentrate providers who bundle leasing with exclusive leaf contracts.
EFSA novel food assessments for botanical adaptogens are tightening ingredient approval timelines across European Union member states. Concentrate formulators must submit comprehensive safety dossiers before marketing wellness-positioned infusions. Ready-to-drink brands targeting German and French foodservice distributors now pre-validate ingredient portfolios eighteen months ahead of launch cycles.
Corporate procurement departments are consolidating beverage contracts under single-source facility management agreements. This bundle compresses vendor counts from multiple tea, coffee, and juice suppliers to one integrated refreshment provider. The pattern is most visible in US Class-A office complexes where landlords specify certified sustainable sourcing across all on-premise offerings.
Out of Home Tea Market Segmentation
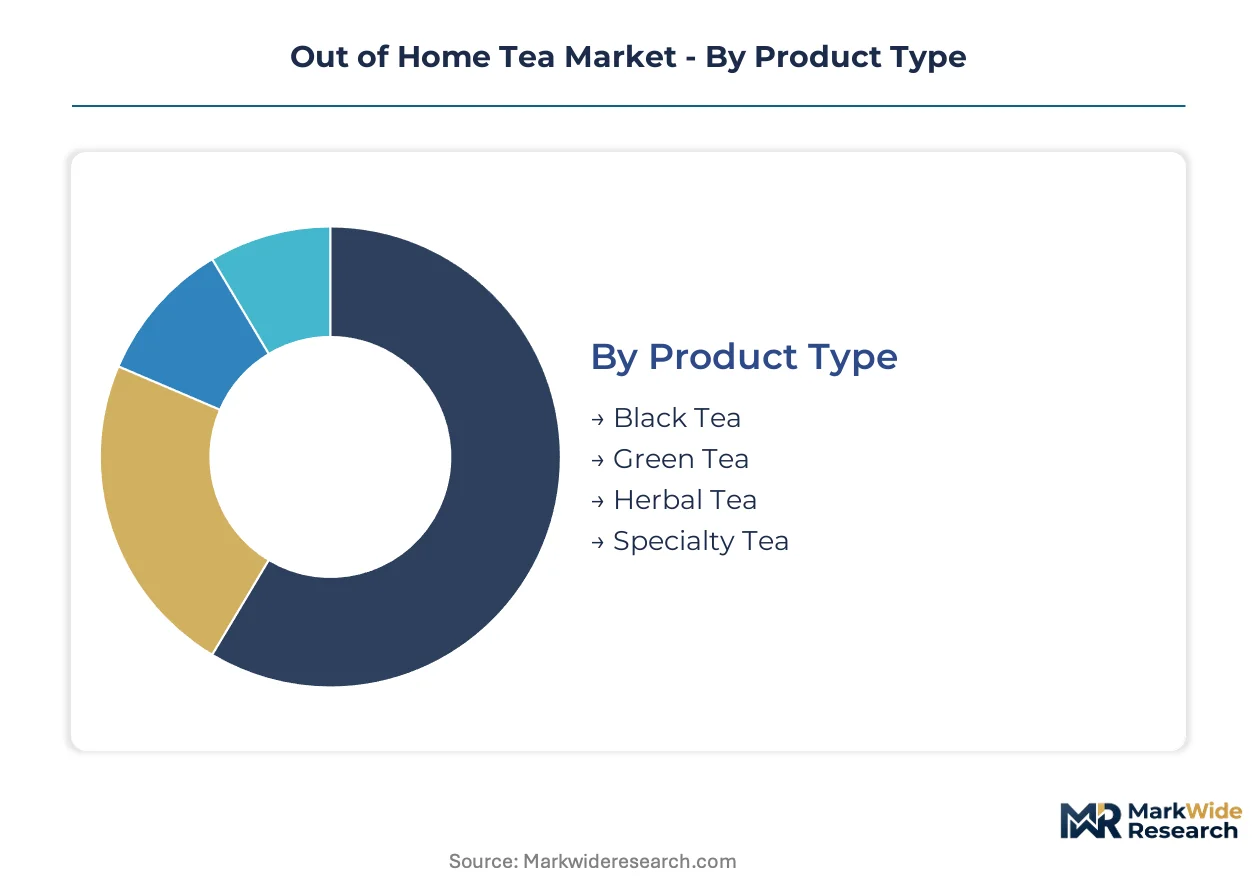
Out of home tea procurement patterns diverge sharply across preparation formats and consumption contexts. Operators configure equipment and sourcing contracts around distinct temperature, volume, and speed-of-service requirements. Understanding segment boundaries clarifies where capital deployment concentrates and where margin compression threatens.
Product Type:
Extraction temperature and oxidization level define equipment specifications and staff training protocols across commercial installations.
- Black Tea:Fully oxidized leaves require water heated to 212°F for proper tannin release, making these systems the default in high-throughput cafeterias and hotel breakfast services. Demand concentrates in India's chai-forward foodservice clusters where Assam and Nilgiri estates supply orthodox grades under long-term procurement contracts.
- Green Tea:Unoxidized varietals demand precise temperature control between 175°F and 185°F to prevent astringency, driving adoption of programmable dispensers in Japanese and Chinese corporate campuses. Cold-brew Japanese formats are gaining share fastest in airport concessions seeking extended shelf stability without refrigeration.
- Herbal Tea:Caffeine-free botanical infusions require separate brewing vessels to prevent cross-contamination, limiting deployment in smaller operators.
- Specialty Tea:Limited-origin lots and ceremonial grades command dedicated service protocols and certified staff, restricting penetration beyond premium hospitality.
Mature deployment sits with Black Tea. Newer deployment is concentrated in Green Tea.
Distribution Channel:
Channel selection determines capital intensity, labor requirements, and regulatory exposure for concentrate suppliers and equipment providers.
- Cafes:Third-wave coffee chains expanding tea menus drive demand for dual-temperature brewing systems and origin-traceable loose leaf. Staff training costs and certified sommelier scarcity constrain rapid rollout beyond flagship locations.
- Restaurants:Full-service operators integrate tea into beverage programs through controlled sourcing partnerships with estate-direct suppliers. Quick-service chains favor concentrate formats to reduce preparation time and labor dependency.
- Vending Machines:Automated dispensers in transit hubs and corporate lobbies require shelf-stable concentrates and minimal maintenance protocols.
- Events:Temporary installations favor pre-brewed bulk formats with thermal dispensing equipment, prioritizing speed over customization.
Volume concentrates in Restaurants. Margin expansion is strongest in Cafes.
End User:
User type shapes pricing tolerance, consumption occasion, and loyalty program design across out-of-home operators.
- Individuals:Solo consumers purchasing on impulse or habit generate the highest frequency but lowest per-transaction value, concentrating in urban cafe clusters and transit vending.
- Corporates:Workplace refreshment contracts bundle tea with coffee and water services under facility management agreements, creating multi-year recurring revenue streams for integrated suppliers.
- Students:Price-sensitive campus populations favor value-tier bagged formats and self-serve dispensers in library and union locations.
- Tourists:Experiential seekers in destination cities drive demand for ceremonial service formats and origin storytelling, particularly in China's traditional tea house districts.
Contract stability sits with Corporates. Discretionary spending growth is concentrated in Tourists.
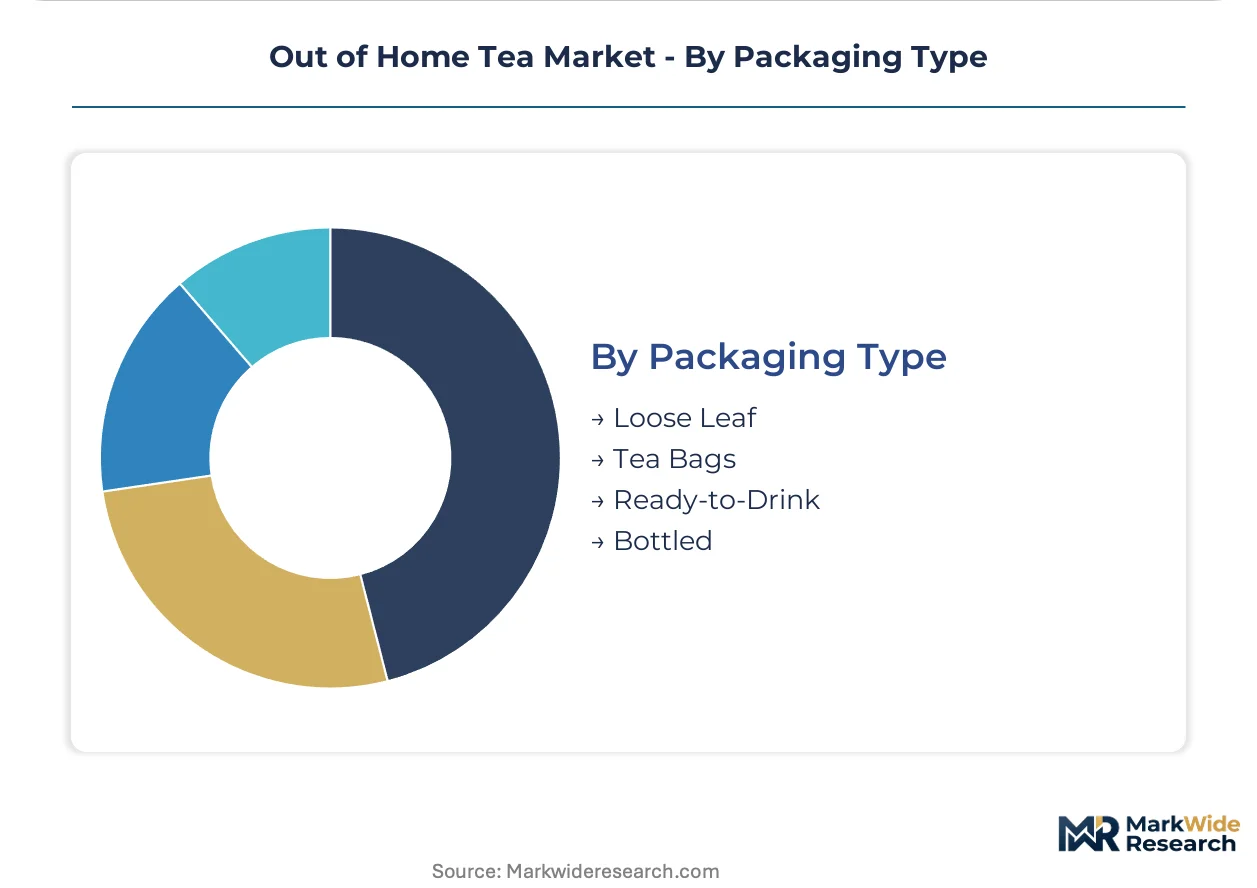
Packaging Type:
Packaging format dictates supply chain configuration, shelf-life requirements, and waste management compliance obligations.
- Loose Leaf:Bulk orthodox grades require precise portion control and trained preparation staff, limiting deployment to premium hospitality and specialty cafes with certified baristas.
- Tea Bags:Standardized single-serve formats dominate institutional foodservice and mid-tier restaurants seeking labor efficiency and portion consistency.
- Ready-to-Drink:Pre-brewed concentrates in bag-in-box or keg formats are expanding most quickly in corporate vending and airport concessions where speed and minimal waste are paramount.
- Bottled:Individual serving bottles face mounting pressure from EU single-use packaging restrictions and extended producer responsibility mandates, compressing economics in grab-and-go channels.
Operational simplicity sits with Tea Bags. Equipment-integrated formats are climbing the fastest in Ready-to-Drink.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates out-of-home tea demand through ceremonial tea houses and modern vending formats. Traditional consumption patterns intersect with automated retail expansion in transit hubs.
China
SAMR enforces GB standards for residue limits and product classification that govern import eligibility for foreign leaf suppliers. Robotic brewing stations deploy in airports and rail terminals serving oolong and pu-erh to captive passenger flows. Shanghai and Beijing anchor premium ceremonial formats while tier-two cities expand automated dispensing.
United States
Corporate campus refreshment contracts and quick-service restaurant expansion drive concentrate demand. FDA food facility registration plus HACCP certification gates access to institutional vending channels. New York and Los Angeles metro areas concentrate third-wave cafe tea menu expansion requiring dual-temperature brewing systems.
Japan
Cold-brew Japanese green tea formats gain share in airport concessions seeking shelf stability without refrigeration. METI standards shape processing equipment specifications for commercial installations. Tokyo and Osaka corporate campuses deploy programmable dispensers with precise temperature control between 175°F and 185°F.
Germany
EFSA novel food assessments for botanical adaptogens tighten ingredient approval timelines for wellness-positioned concentrates. Extended producer responsibility mandates under EU packaging regulations compress ready-to-drink bottle economics. Berlin and Munich foodservice distributors pre-validate ingredient portfolios eighteen months ahead of launch cycles.
India
Chai-forward foodservice clusters in urban centers drive orthodox leaf procurement from Assam and Nilgiri estates. FSSAI standards govern packaged tea concentrate safety for commercial distribution. Mumbai and Delhi hospitality markets expand specialty tea programs requiring certified sommelier staffing.
Out of Home Tea Market Vendor Landscape
Backward integration into estate networks dominates the current landscape as suppliers secure leaf supply against climate volatility. The vendor base separates into three tiers: multinational FMCG conglomerates with diversified beverage portfolios, integrated estate-to-cup specialists controlling orthodox leaf sourcing, and regional concentrate formulators serving institutional channels. Strategic archetypes include equipment-integrated concentrate providers bundling leasing with exclusive contracts, and certification-focused suppliers prioritizing traceability platforms. Competitive moves center on M&A to capture estate assets and strategic partnerships with quick-service chains for menu placement.
Within the integrated estate tier, Tata Consumer Products Limited exemplifies upstream control through captive orthodox leaf supply for foodservice clients. Starbucks Corporation occupies a position emphasizing controlled sourcing partnerships with traceability requirements. Ito En Ltd represents cultivar authenticity specialization competing on Japanese green tea varietals and cold-brew processing expertise.
| Leading Market Players |
|---|
| Unilever Plc |
| Tata Consumer Products Limited |
| Nestle S.A. |
| Associated British Foods |
| Ito En Ltd |
| Starbucks Corporation |
| The Republic of Tea |
| Barry's Tea |
| Celestial Seasonings Inc. |
| Others |
Supply Flow & Price Mechanics
Assam and Darjeeling orthodox leaf auction prices cascade through three distinct procurement tiers, with estate-direct contracts commanding premium positioning while spot-market purchases feed economy-grade concentrate production. This raw-material cost structure stratifies foodservice pricing across ceremonial service formats, automated vending channels, and institutional bagged offerings.
Pricing Analysis
Volume concentrates in black tea bagged formats serving institutional cafeterias, while margin expansion runs through limited-origin specialty grades requiring certified sommelier service. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price erosion runs through ready-to-drink bottled formats facing EU single-use packaging compliance costs. Corporate campus buyers exhibit lowest price sensitivity due to bundled facility management contracts, while student segments in campus environments drive procurement toward economy-tier bagged products.
Supply Chain Analysis
Direct-to-foodservice channels handle estate-direct orthodox leaf demand from premium hospitality clients, while concentrate suppliers serve quick-service chains through distributor intermediaries. Geographic supply concentration centers on India, China, and Kenya for raw leaf, with Japanese green tea varietals drawing from domestic cultivar specialists. Raw material dependencies include nitrogen-chilled extraction equipment, temperature-controlled brewing hardware, and shelf-stable packaging formats. Single-source vulnerability threatens Assam and Darjeeling estate output given climate volatility exposure. Distribution runs through regional foodservice distributors holding SAMR, FDA, and EFSA compliance certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
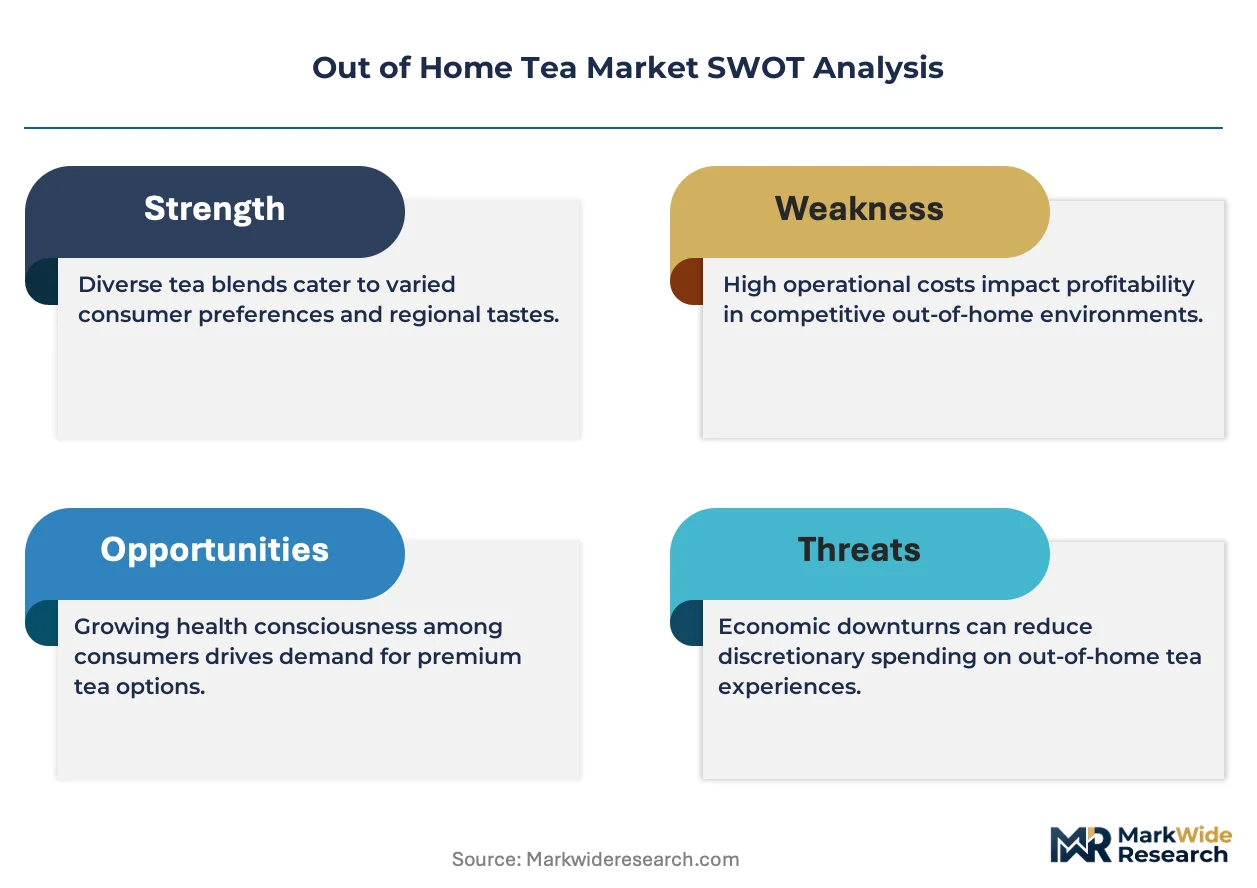
This market reads as a cost-of-compliance story where FDA food facility registration and HACCP certification create barrier-to-entry moats for concentrate suppliers targeting US institutional channels. Regulatory capital requirements favor incumbent players with established quality infrastructure.
For Market Incumbents: Extend backward integration into estate networks to secure orthodox leaf supply against climate volatility in Assam and Darjeeling clusters. Deepen equipment-integrated concentrate offerings bundling nitrogen-chilled brewing hardware with exclusive leaf contracts to lock in corporate campus refreshment agreements. Counter emerging cold-brew processing specialists by accelerating certified sommelier training programs that defend premium ceremonial service formats.
For New Entrants and Emerging Players: Enter via botanical infusion concentrates targeting EFSA novel food approval pathways for adaptogenic ingredients, where pre-validation timelines deter established players. Exploit underpenetrated tier-two Chinese cities expanding automated robotic brewing stations in transit hubs. Pursue white-label concentrate supply partnerships with regional quick-service chains seeking menu differentiation without estate-direct procurement complexity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap estate-to-cup specialists with captive orthodox leaf supply and existing SAMR GB standards compliance in China. Long-term viability hinges on climate-resilient sourcing diversification across multiple growing regions. Monitor EFSA novel food assessment timelines as inflection indicator for wellness-positioned concentrate valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Estate Network Acquisition | Captive orthodox leaf supply secures margin buffers against climate volatility in Assam clusters. |
| Cold-Brew Equipment Integration | Nitrogen-chilled extraction systems bundle hardware leasing with exclusive concentrate contracts in corporate channels. |
| EFSA Novel Food Pre-Validation | Adaptogenic ingredient dossiers submitted eighteen months ahead of German and French distributor launch cycles. |
| Certified Sommelier Training Programs | Staff credentialing defends premium ceremonial formats requiring precise water temperature control protocols. |
| Robotic Brewing Station Deployment | Automated oolong and pu-erh service captures captive passenger flows in Shanghai and Beijing transit hubs. |
Methodological Framework
Document review covered customs trade data for orthodox leaf imports, FDA food facility registration databases, EFSA novel food assessment records, and corporate refreshment contract disclosures, complemented by interviews with foodservice procurement directors, estate operations managers, concentrate formulators, and certified tea sommeliers. Secondary validation drew from SAMR GB standards documentation, METI processing equipment specifications, and trade association harvest reports. Bottom-up segment sizing triangulated against top-down market aggregation across product type, distribution channel, and regional regulatory clusters.
Segmentation outputs modeled black tea, green tea, herbal tea, and specialty tea extraction formats alongside cafes, restaurants, vending machines, and events distribution channels. CAGRs derived from volume trajectory analysis incorporating cold-brew adoption curves, workplace refreshment modernization spend, and transit hub automation deployment rates. Inputs included estate yield volatility indices, regulatory compliance cost burdens, and equipment-integrated contract pricing structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate disruption scenarios affecting Assam and Darjeeling harvests or accelerated EU single-use packaging restriction implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Edible Tea Market
Tea
Slimming Tea Market
Tea
Global Tea Bag Market
Tea
Butterfly Pea Flower Tea Market
Tea
Green Tea Bag Market
Tea
Black Tea Extracts Market
Tea
Mate Tea Market
Tea
Tea Essence Market
Tea
Smart Tea Set Market
Tea
Bottled Tea Market
Tea
Instant Tea Market
Tea
Green Tea Extract Market
Tea
Tea Subscription Market
Tea
Tea Concentrate Market
Tea
APAC RTD Tea Market
Tea
Asia-Pacific Tea Market