
 Green Tea Leaves Market | 2026-2036
Green Tea Leaves Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Leaves Market Foresight
Specialty tea retail channels is reconfiguring how green tea leaves reach end consumers, with direct-to-consumer platforms and boutique loose-leaf shops gaining shelf space against traditional grocery. Unilever plc leverages its multi-brand portfolio to sustain volume across bagged and premium segments in Western markets. Tata Consumer Products Limited anchors South Asian supply through integrated estate operations and branded retail dominance. Ito En, Ltd. competes in Japan and North America with cold-brew RTD lines that source whole-leaf grades.
Green tea leaves are the minimally processed foliage of Camellia sinensis, steamed or pan-fired to arrest oxidation and preserve catechins, with EGCG concentrations typically exceeding those of black tea by 30–40 percent. The primary commercial purpose spans beverage infusion, nutraceutical extraction, and cosmeceutical active sourcing. Loose leaf and whole leaf grades occupy the highest margin pools in specialty retail and foodservice channels, while powdered matcha and extracts are expanding fastest through nutraceutical and functional food applications. Bagged tea dominates unit volume in conventional retail but faces compression as organic and premium grades capture value growth in e-commerce and exporter segments.
The FDA oversees pesticide residue tolerances and health claim substantiation for green tea products entering United States commerce, while the EFSA evaluates novel food and botanical safety dossiers for European market access. Japan's Ministry of Agriculture, Forestry and Fisheries enforces JAS organic certification that shapes premium export eligibility from Chinese and Indian origins. Stakeholders must monitor evolving maximum residue limits in multiple jurisdictions and align procurement with emerging regenerative agriculture standards before certification mandates harden.
Market Dynamics
Functional beverage manufacturers are pulling green tea extract procurement toward regenerative-certified origins as EU Green Deal agricultural standards tighten import eligibility for European-bound shipments.
Growth Catalysts
- Regenerative Agriculture Mandates:The EU Green Deal and F-Gas Regulation are accelerating demand for residue-compliant leaf grades across German, French, and Dutch import channels.
- Whole-Leaf RTD Formulation:Cold-brew extraction technology is expanding addressable volume for minimally processed Camellia sinensis in North American convenience retail.
- China:Domestic consumption of premium loose-leaf varieties is rising alongside export growth, concentrating procurement power with estate-integrated suppliers.
Market Restraints
- Input Cost Volatility:Fertilizer and energy price swings compress margins for smallholder growers in Zhejiang and Anhui provinces.
- Supply Concentration Risk:Three provinces dominate China's export-grade output, creating vulnerability to regional climate anomalies.
- Substitution Threat:Yerba mate and guayusa extracts are capturing functional beverage formulation slots previously reserved for EGCG-rich green tea.
Strategic Opportunities
- Underpenetrated Geography:Vietnam and Indonesia offer untapped estate capacity for organic certification pivots serving EU and Japanese buyers.
- Regulatory Tailwind:Japan's JAS organic certification creates premium export eligibility arbitrage for Chinese and Indian origins meeting its residue protocols.
- Channel Innovation:Direct-to-consumer subscription platforms are bypassing traditional auction systems, capturing margin from specialty loose-leaf buyers in urban US and UK markets.
Industry Challenges
- Certification Timeline Compression:Regenerative and organic audit backlogs delay market access for estate operators pivoting from conventional cultivation.
- Skill Scarcity in Sensory Grading:Experienced tea masters capable of distinguishing whole-leaf quality tiers are retiring faster than training programs replace them.
- Legacy Auction System Integration:Digital procurement platforms face resistance from Colombo and Mombasa trading houses with century-old relational contract structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Leaves Market |
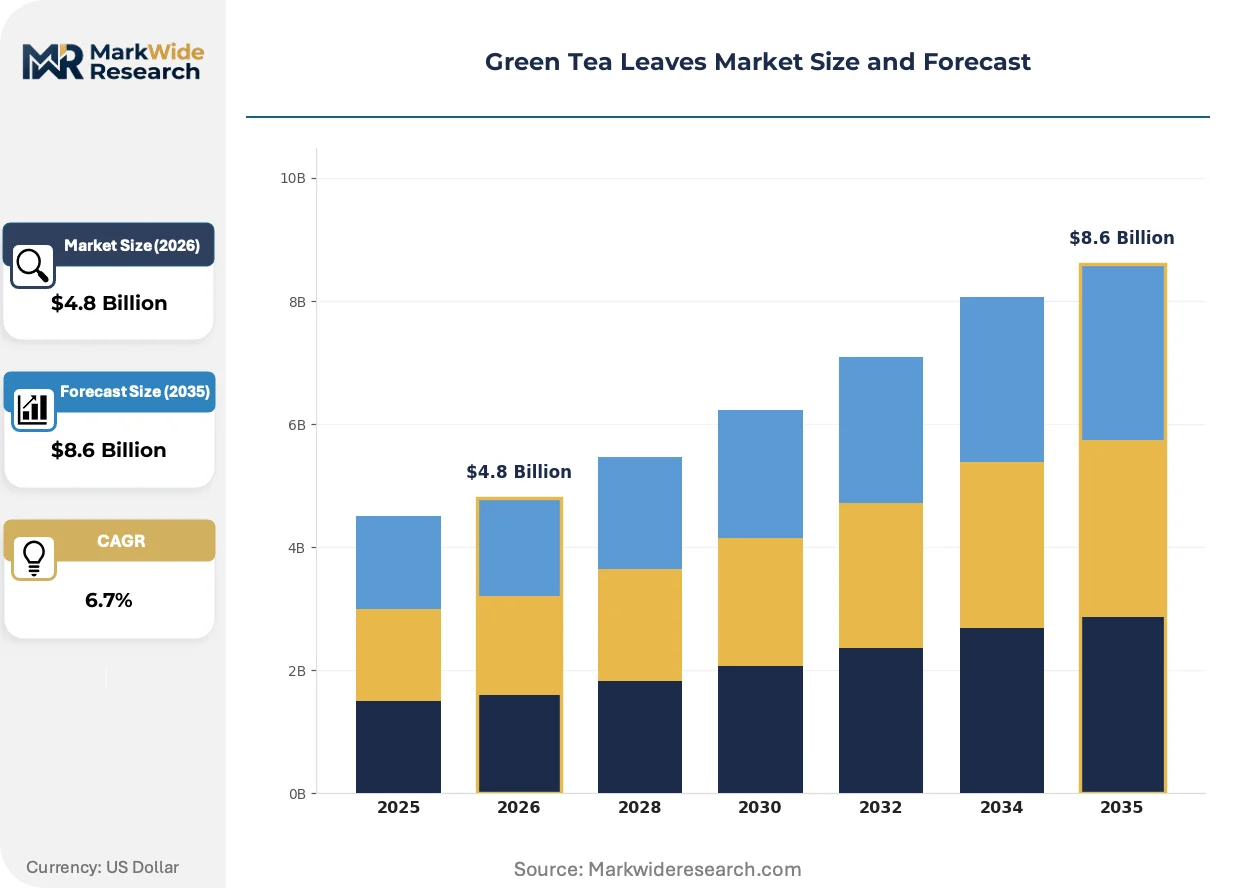
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Bagged Tea, Powdered, Extracts Grade: Premium, Organic, Conventional, Specialty End User: Foodservice, Retail, E-Commerce, Exporters Form: Whole Leaf, Broken Leaf, Fannings, Dust |
| Companies Covered | Unilever plc, Tata Consumer Products Limited, Associated British Foods plc, Ito En, Ltd., The Bigelow Tea Company, Numi, Inc., The Republic of Tea, Inc., East West Tea Company, LLC, Typhoo Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Leaves Market Shifts & Advancements
Processing technology and certification protocols are restructuring how green tea leaf quality is verified, traded, and formulated into downstream products across beverage and nutraceutical value chains.
Blockchain-enabled provenance tracking is digitizing estate-to-cup traceability for premium loose-leaf grades. Japanese and German buyers are mandating distributed-ledger documentation for organic and fair-trade claims. This transparency architecture is digitizing quality premiums previously captured by opaque auction intermediaries.
The EU F-Gas Regulation and accompanying Green Deal agricultural standards are tightening maximum residue limits for tea imports entering Rotterdam and Hamburg ports. Estate operators in China and India are retrofitting cold-storage facilities and switching input regimes to maintain access. Organic-certified whole-leaf grades face the steepest compliance investment requirements.
Specialty buyers are consolidating procurement through vertically integrated direct-trade relationships, displacing traditional broker networks. Boutique roasters and functional beverage startups in California and New York are signing multi-year offtake agreements with single-estate suppliers. This relationship-based sourcing is most visible in matcha and ceremonial-grade segments where origin storytelling commands retail price multiples.
Green Tea Leaves Market Segmentation
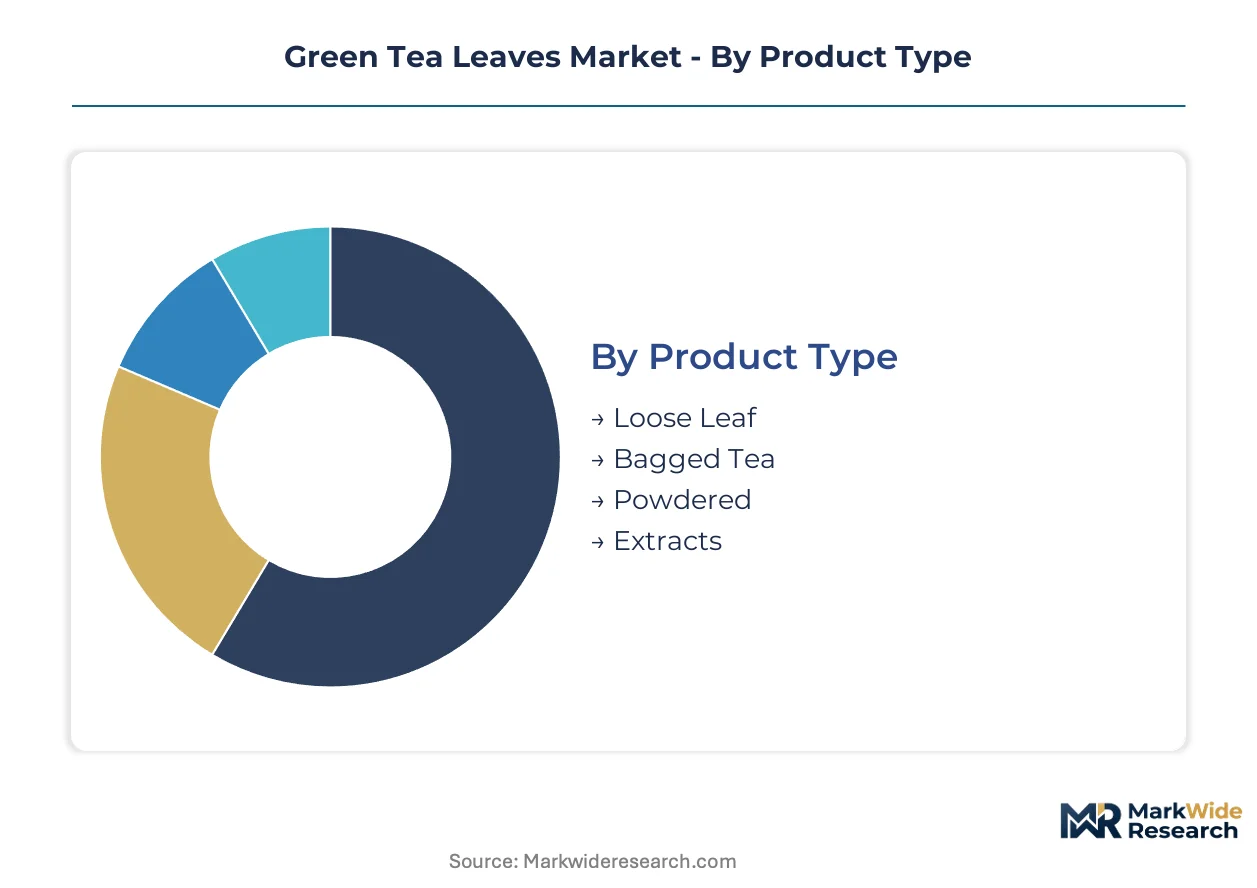
Green tea leaf value pools diverge sharply across processing intensity and distribution channel. Procurement patterns for minimally processed grades bear little resemblance to extract demand from nutraceutical formulators.
Product Type:
Cost tier stratification separates commodity convenience formats from premium unprocessed grades commanding multiple price multiples.
- Loose Leaf:Minimally processed whole foliage sold in bulk or boutique packaging, with EGCG preservation highest in steamed Japanese-style processing. Specialty retailers in Germany and Japan concentrate procurement here, driven by origin-verification requirements under JAS organic and EU Green Deal standards.
- Bagged Tea:Standardized cut-tear-curl grades in paper or mesh sachets, optimized for brewing consistency. Conventional retail channels in the United States and United Kingdom move volume here, though private-label compression erodes branded margins.
- Powdered:Stone-ground matcha and instant-dissolve formulations for beverage and bakery applications.
- Extracts:Concentrated catechin isolates for nutraceutical capsules and functional beverage fortification.
Bagged tea commands the established base. The steepest expansion runs through extracts.
Grade:
Certification tier determines market access eligibility and price realization across regulatory jurisdictions.
- Premium:Single-origin or single-estate selections with documented harvest dates and cultivar provenance. Direct-trade relationships in California and New York concentrate demand here, driven by cold-brew RTD formulation requirements for whole-leaf sensory profiles.
- Organic:Cultivation protocols excluding synthetic pesticides and fertilizers, audited to USDA, EU, or JAS standards. German and Dutch importers are tightening procurement toward this tier under F-Gas Regulation residue limits.
- Conventional:Standard agricultural input regimes meeting baseline MRL thresholds for mass-market distribution.
- Specialty:Terroir-designated or handcrafted grades including shade-grown and hand-rolled variants.
Conventional grade commands the established base. Organic climbs the fastest.
End User:
Customer type dictates packaging format, lot size, and traceability documentation requirements.
- Foodservice:Bulk loose-leaf procurement for cafes, restaurants, and hospitality chains requiring consistent brewing parameters. Urban markets in Japan and South Korea concentrate demand here, driven by matcha latte preparation standards.
- Retail:Branded packaged goods through conventional grocery and specialty tea shops. United Kingdom supermarket chains anchor volume here, though shelf space is shifting toward organic and premium tiers.
- E-Commerce:Direct-to-consumer subscription and marketplace platforms bypassing traditional wholesale tiers.
- Exporters:Reprocessing and re-export operations in Dubai and Singapore serving Middle East and Southeast Asian markets.
Retail commands the established base. E-commerce gains share fastest.
Form:
Leaf integrity level correlates with extraction efficiency, brewing control, and end-use application range.
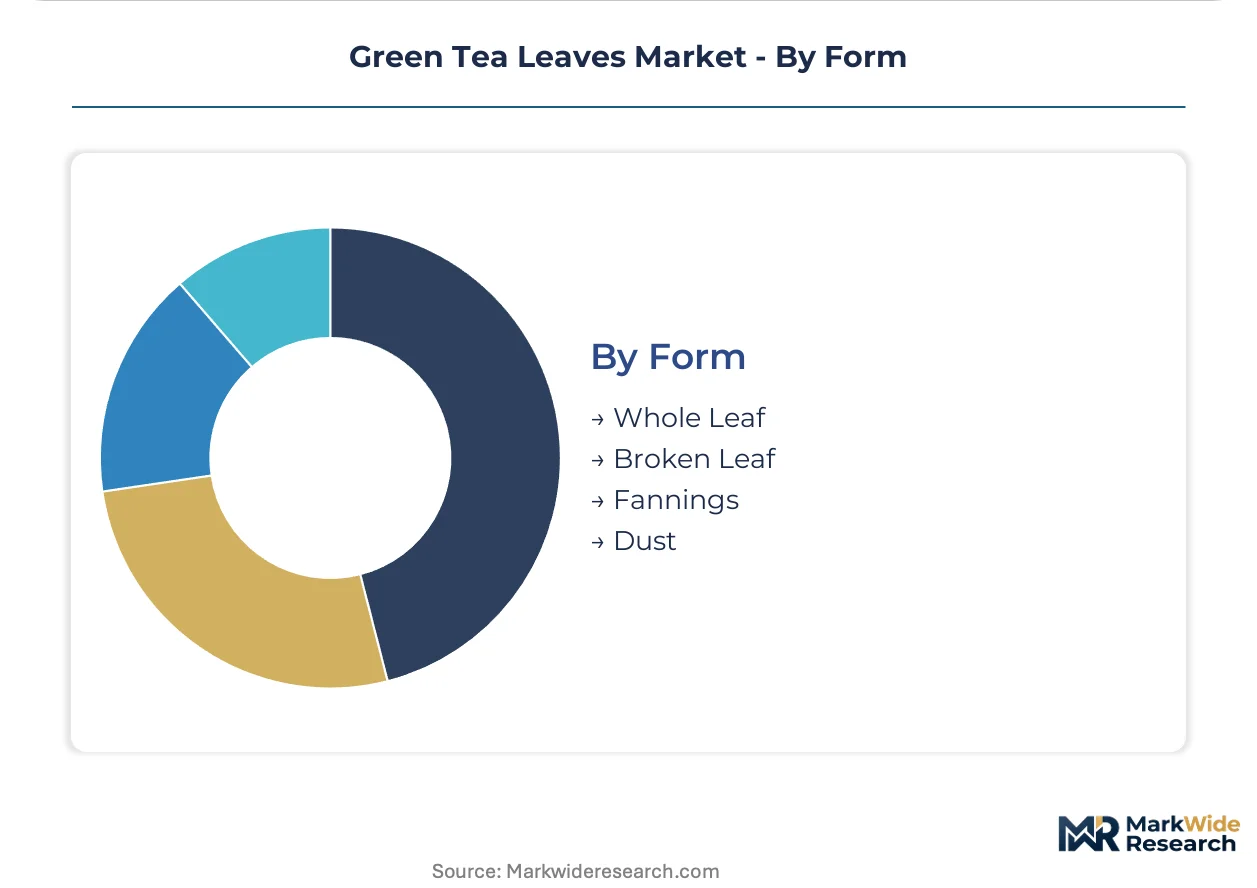
- Whole Leaf:Intact foliage with minimal breakage, preserving volatile aromatic compounds. Cold-brew RTD manufacturers in North America concentrate procurement here, driven by extraction technology advances enabling ambient-stable ready-to-drink formulations.
- Broken Leaf:Partially fractured grades offering faster infusion for foodservice bulk brewing.
- Fannings:Small leaf particles standard for bagged tea sachets and quick-extraction applications.
- Dust:Fine particulate grades for instant tea production and industrial extraction feedstock.
Fannings commands the established base. Whole leaf shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-grade green tea leaves command 40% higher realizations in Japanese and German import channels than in conventional mass-market destinations, creating a pronounced pricing-power asymmetry between quality-focused Northern European and East Asian buyers versus price-sensitive South Asian and Middle Eastern markets.
China
Domestic consumption of ceremonial-grade Longjing and Biluochun varieties is accelerating in Shanghai and Hangzhou metro areas, while Zhejiang and Anhui provinces anchor export-grade cultivation. The Ministry of Agriculture and Rural Affairs is tightening residue monitoring protocols under national green food certification standards. Hangzhou's Xihu district remains the epicenter for premium Longjing production, with estate-integrated suppliers capturing margin through direct-trade relationships bypassing traditional auction houses.
Japan
Cold-brew ready-to-drink formulations are driving procurement of whole-leaf tencha grades in Tokyo and Osaka convenience retail channels. The Ministry of Agriculture, Forestry and Fisheries enforces JAS organic certification that restricts eligible import origins to residue-compliant Chinese and Indian estates. Shizuoka Prefecture concentrates domestic cultivation, with Kakegawa city processors supplying matcha powder to North American specialty beverage manufacturers.
Germany
Specialty tea retailers in Berlin and Hamburg are consolidating procurement toward regenerative-certified loose-leaf grades as the EU F-Gas Regulation tightens maximum residue limits for Rotterdam and Hamburg port entries. The Federal Office of Consumer Protection and Food Safety coordinates enforcement with EFSA safety dossier requirements. Hamburg's Speicherstadt district hosts Europe's largest tea trading and re-export operations, with importers retrofitting cold-storage infrastructure to maintain organic certification integrity.
United States
Direct-to-consumer subscription platforms in California and New York are displacing conventional grocery shelf space for premium loose-leaf and matcha varieties. The FDA oversees pesticide residue tolerances and health claim substantiation for functional beverage formulations. Los Angeles and San Francisco metropolitan areas concentrate cold-brew RTD innovation, with beverage startups signing multi-year offtake agreements with single-estate Japanese and Chinese suppliers.
Vietnam
Estate operators in Lam Dong and Thai Nguyen provinces are pivoting toward organic certification to capture EU and Japanese buyer demand as Chinese supply faces Green Deal compliance pressures. The Ministry of Agriculture and Rural Development administers VietGAP standards that align with export market requirements. Da Lat city's highland estates are emerging as alternative origins for whole-leaf grades previously sourced exclusively from Zhejiang and Shizuoka prefectures.
Green Tea Leaves Market Competitive Landscape
Vertically integrated estate operators and brand-house multinationals split the market between upstream supply control and downstream channel access. Three strategic archetypes dominate: plantation-integrated suppliers capturing margin through direct-trade relationships, multi-brand conglomerates sustaining volume across bagged and premium segments, and specialty pure-plays commanding price multiples in ceremonial-grade matcha and loose-leaf tiers. Competitive intensity centers on regenerative certification acquisition and cold-chain infrastructure deployment rather than capacity expansion.
Within the estate-integrated tier, Tata Consumer Products Limited and Associated British Foods plc exemplify backward-integrated sourcing strategies, while Ito En, Ltd. occupies a position bridging Japanese domestic cultivation with North American RTD formulation partnerships. These three entities represent contrasting geographic anchoring—Indian subcontinent supply dominance, European multi-channel brand architecture, and trans-Pacific cold-brew innovation pipelines—without any single archetype commanding decisive share across all quality tiers and regional markets.
| Leading Market Players |
|---|
| Unilever plc |
| Tata Consumer Products Limited |
| Associated British Foods plc |
| Ito En, Ltd. |
| The Bigelow Tea Company |
| Numi, Inc. |
| The Republic of Tea, Inc. |
| East West Tea Company, LLC |
| Typhoo Tea |
| Others |
Supply & Pricing Matrix
Zhejiang province's estate-integrated suppliers command disproportionate pricing leverage in premium loose-leaf segments, with Hangzhou's Xihu district Longjing cultivars realizing substantial premiums over Anhui-origin grades. This geographic concentration of ceremonial-quality production creates asymmetric bargaining power against German and Japanese buyers facing tightening EU F-Gas Regulation residue protocols.
Pricing Analysis
The customization-premium spread between direct-trade single-estate contracts and auction-standardized grades exceeds conventional commodity differentials, with JAS organic-certified whole-leaf tencha commanding substantial premia over conventional cut-tear-curl formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and origin traceability, with cold-brew RTD manufacturers absorbing the least price sensitivity due to formulation lock-in requirements. Pricing pressure stems from fertilizer and energy input volatility compressing smallholder margins in Anhui and Fujian provinces. Mass-market bagged tea buyers in United Kingdom supermarket chains exhibit highest price sensitivity, driving private-label substitution.
Supply Chain Analysis
Contract-manufacturing concentration among Japanese Kakegawa city processors and Chinese Hangzhou estate-integrated facilities dominates premium matcha and ceremonial-grade output. Geographic supply concentrates in China, Japan, and Vietnam, with Lam Dong province estates emerging as alternative organic-certified sources. Raw material dependencies rest on Camellia sinensis cultivar stock, synthetic fertilizer inputs, and cold-chain logistics infrastructure. Single-source vulnerability runs through Shizuoka Prefecture's tencha milling capacity for North American matcha demand. Distribution runs through Hamburg's Speicherstadt trading houses and direct-to-consumer subscription platforms bypassing traditional auction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green tea leaves represent a high-growth disruption as EU Green Deal agricultural standards and cold-brew extraction technology simultaneously reshape procurement requirements and formulation possibilities across beverage and nutraceutical value chains.
For Market Incumbents: Pre-empt certification audit backlogs by accelerating regenerative agriculture transitions in Zhejiang and Anhui estates before EU F-Gas Regulation mandates harden. Secure multi-year offtake agreements with California and New York cold-brew RTD startups to lock in whole-leaf demand. Vertical integration into cold-storage infrastructure at Rotterdam and Hamburg port entries defends organic certification integrity against emerging Vietnamese competitors. For New Entrants and Emerging Players: Mid-tier organic-certified whole-leaf grades for German specialty retailers represent the most penetrable entry point, as incumbent estate-integrated suppliers concentrate on ceremonial matcha and direct-trade premium segments. Vietnamese Lam Dong and Thai Nguyen province estates offer untapped capacity for JAS organic pivots serving Japanese buyer demand. A subscription-based direct-to-consumer platform targeting urban UK and US loose-leaf buyers bypasses legacy auction system barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among estate-integrated suppliers with captive cultivation and established direct-trade relationships with North American beverage manufacturers. Long-term viability over a multi-year horizon favors operators with backward integration into organic-certified land banks and cold-chain infrastructure. Acquisition targets should demonstrate residue compliance capabilities under evolving EU Green Deal protocols. The signal to watch is JAS organic certification backlog clearance rates as early indicator of supply-access arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | Estate operators securing EU-compliant residue protocols maintain Rotterdam and Hamburg port access under tightening F-Gas Regulation standards. |
| Cold-Chain Infrastructure Deployment | Retrofitted cold-storage facilities at Hamburg's Speicherstadt trading houses preserve organic certification integrity through distribution. |
| Direct-Trade Relationship Consolidation | California beverage startups signing multi-year offtake agreements with single-estate Japanese suppliers bypass opaque auction intermediaries. |
| Cold-Brew RTD Formulation Partnership | North American convenience retail channels expand addressable volume for minimally processed Camellia sinensis through extraction technology advances. |
| Blockchain Provenance Tracking Implementation | Distributed-ledger documentation for organic and fair-trade claims digitizes quality premiums previously captured by traditional trading houses. |
Research Methodology
A standing panel of estate operations managers, specialty tea buyers at German and Japanese importers, cold-brew RTD formulation scientists, and organic certification auditors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against customs records, JAS organic certification databases, EU F-Gas Regulation enforcement disclosures, and EFSA safety dossier filings. Bottom-up cultivation volume estimates from Zhejiang and Anhui provincial agricultural bureaus triangulated against top-down import value data from Hamburg and Rotterdam port authorities.
Scenario-bracketing around EU Green Deal implementation timelines and cold-brew technology diffusion curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, certification grade, end-user channel, and leaf integrity form alongside regional regulatory cluster differentiation. CAGRs derived from compound growth trajectory analysis incorporating estate capacity expansion plans and substitution threat dynamics from yerba mate and guayusa extracts. Forecast inputs included climate anomaly probability distributions for three-province supply concentration and JAS organic audit clearance rates.
Practitioners should monitor EU F-Gas Regulation enforcement intensity, JAS organic certification backlog durations, and cold-brew RTD formulation patent filings for early signals of forecast revision triggers. Quarterly review of residue limit compliance rates at Rotterdam and Hamburg ports, estate-level regenerative agriculture transition progress, and direct-to-consumer subscription platform customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Black Tea Base Bubble Tea Market
Tea
Nitro Tea Market
Tea
Matcha Tea Market
Tea
Plant Based New Tea Drink Market
Tea
Herbal Tea Market
Tea
Natural Tea Extract Market
Tea
Oolong Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Moringa Tea Market
Tea
Tea Infuser Market
Tea
Asia-Pacific Organic Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Slimming Tea Market
Tea
White Tea Market
Tea
Single Origin Tea Market
Tea
Black Tea Market