
 Middle East Ready to Drink Tea Market | 2026-2036
Middle East Ready to Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Ready to Drink Tea Market Insights
Saudi Food and Drug Authority sugar disclosure mandates is decoupling formulation economics from legacy recipes, forcing manufacturers to rebuild cost models around alternative sweeteners and clean-label positioning. The Coca-Cola Company leverages its Gulf bottling infrastructure to sustain chilled distribution dominance across hypermarket chains. PepsiCo Inc anchors its portfolio through Aquafina-tea hybrid lines that compete directly with local bottlers in convenience channels. Nestle S.A. differentiates via Nescafe-Tea bundle placements that occupy premium refrigerator end-caps in Saudi retail.
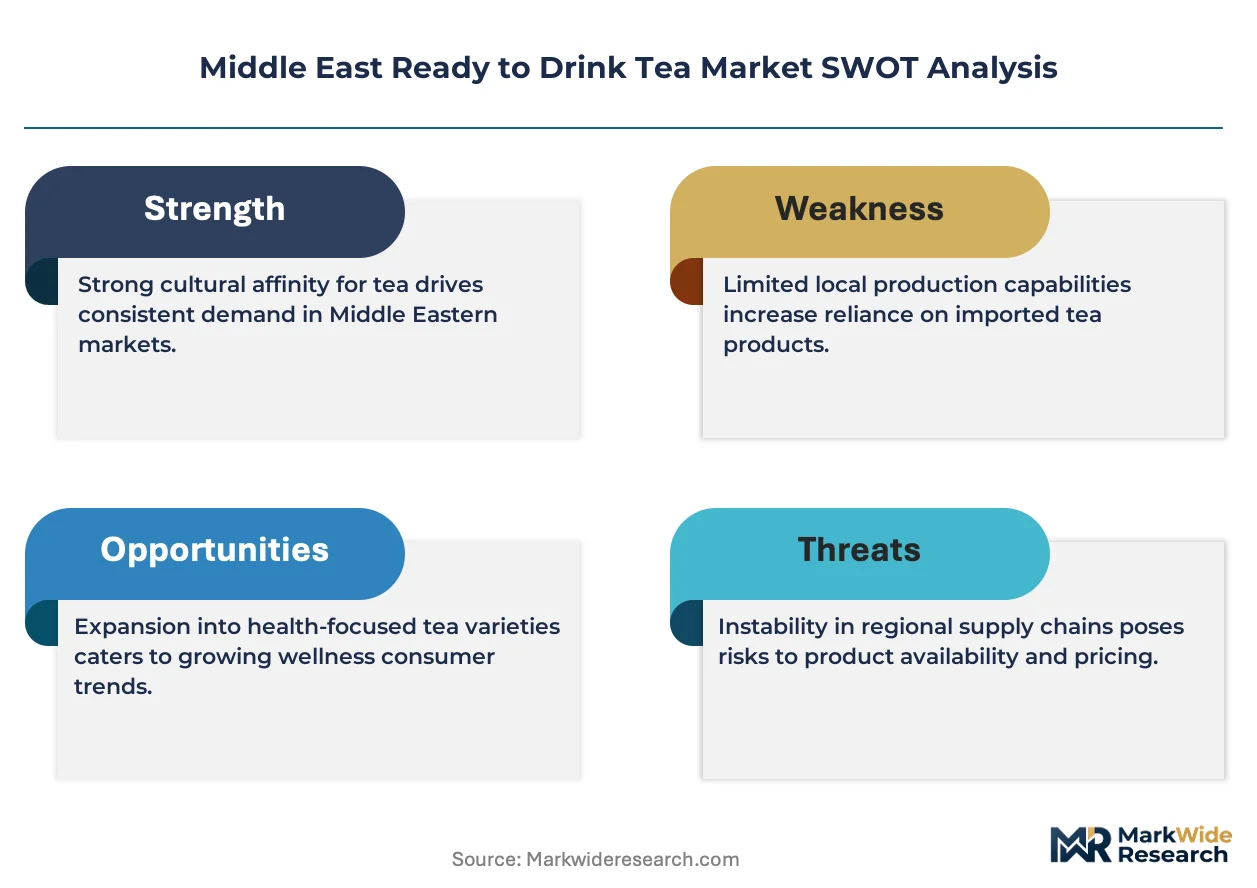
Middle East Ready to Drink Tea comprises brewed, extracted, or infused tea beverages, pasteurized or aseptically filled, with total soluble solids typically ranging from 4-12 Brix and pH adjusted for ambient or chilled shelf stability; these products serve as immediate-consumption refreshment alternatives to carbonates and juices in high-temperature climates. Black Tea formulations dominate volume through their familiarity in Gulf consumption culture, while Green Tea captures margin pools among health-conscious consumers seeking antioxidant positioning. Herbal Tea segments specializing in hibiscus and chamomile variants navigate regulatory complexity around botanical health claims that vary across national food codes in the region.
Gulf Standards Organization beverage safety protocols intersect with Saudi Food and Drug Authority ingredient registration requirements and UAE Ministry of Climate Change and Environment import certification to create multi-layered compliance architecture for cross-border RTD tea trade. FSSAI-equivalent enforcement in Bahrain and Oman adds further testing obligations for microbial limits and preservative thresholds that shape regional supply chain design. Stakeholders must monitor evolving excise tax structures on sweetened beverages as Gulf finance ministries recalibrate public health revenue instruments.
Market Dynamics
Saudi Food and Drug Authority sugar disclosure mandates are decoupling formulation economics from legacy recipes, forcing manufacturers to rebuild cost models around alternative sweeteners and clean-label positioning. This regulatory pressure is compressing margins for traditional high-Brix formulations while creating first-mover advantages for reformulated portfolios.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Arabia's sugar content disclosure requirements are accelerating reformulation investments and opening shelf space for reduced-calorie variants in convenience channels.
- Chilled Distribution Infrastructure:Hypermarket chains across the Gulf Cooperation Council are expanding refrigerated end-cap capacity, enabling premium RTD tea placement adjacent to carbonated alternatives.
- Youth Consumption Pivot:Young adult demographics in Dubai and Riyadh are displacing carbonated soft drinks with RTD tea, concentrating demand in metropolitan retail corridors.
Market Restraints
- Input Cost Volatility:Tea leaf procurement faces price instability from climate-impacted harvests in Sri Lankan and Kenyan supply basins, squeezing raw material economics.
- Multi-Jurisdictional Compliance:Gulf Standards Organization protocols intersect with UAE Ministry of Climate Change and Environment import certification, creating layered testing obligations that elongate cross-border shipment timelines.
- Water-Based Substitution:Bottled water and functional hydration beverages compete directly on price-per-liter in Saudi and UAE convenience channels, limiting RTD tea volume expansion.
Strategic Opportunities
- Herbal Botanical Positioning:Hibiscus and chamomile variants can navigate health claim complexity under varying national food codes across Bahrain, Oman, and Kuwait.
- Excise Tax Arbitrage:Gulf finance ministry recalibrations of sweetened beverage taxation create formulation incentives for sub-threshold sugar content that escapes levy classification.
- Bundle Placement Innovation:Coffee-tea hybrid refrigerator positioning in Saudi retail captures premium margin pools through adjacent-category traffic.
Industry Challenges
- Preservative Threshold Navigation:FSSAI-equivalent microbial limits in Bahrain and Oman require reformulation of ambient-stable recipes without compromising shelf life.
- Botanical Registration Complexity:Cross-border ingredient approval timelines vary across Saudi Food and Drug Authority and UAE Ministry systems, delaying new product introductions.
- Refrigerated Last-Mile Costs:Chilled distribution requirements in 45°C ambient conditions inflate logistics expenditure for premium SKUs targeting convenience stores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Ready to Drink Tea Market |
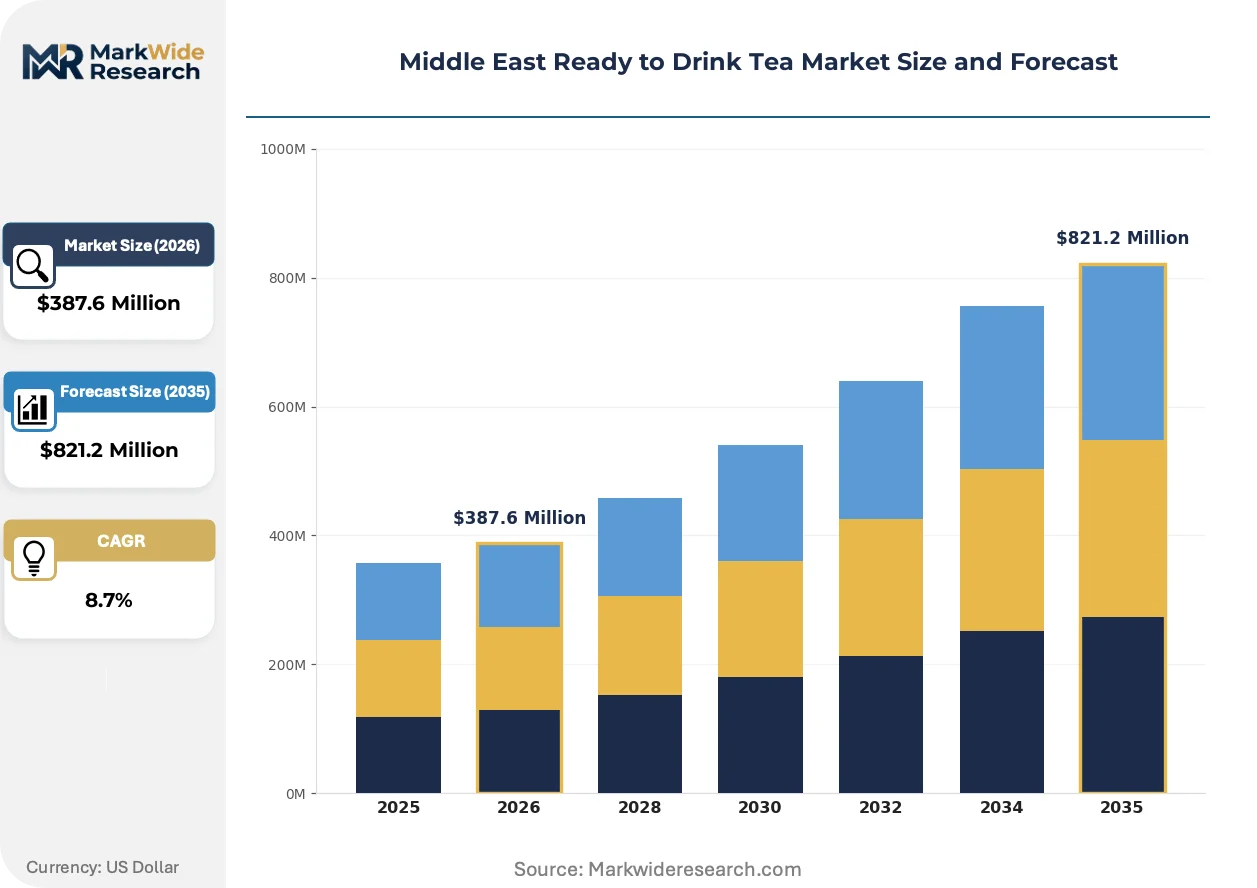
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Flavored Tea Packaging Type: Bottles, Cans, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores End User: Young Adults, Working Professionals, Health Conscious Consumers, Tourists |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc, Nestle S.A., Keurig Dr Pepper Inc, Rauch Fruchtsäfte GmbH & Co OG, Sapporo Holdings Limited, Barakat Group of Companies, The Savola Group, Nai Arabia Food Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Ready to Drink Tea Market Trends and Innovations
Aseptic filling technology and alternative sweetener chemistry are compressing the cost gap between premium and mass-market RTD tea tiers. Formulation labs across Dubai and Riyadh are racing to match clean-label positioning with Gulf climate stability requirements.
Hot-fill aseptic processing is automating the transition from preservative-dependent recipes to extended-shelf-life clean labels. Saudi bottlers are adopting these systems at accelerated capex cycles to secure SFDA-compliant reduced-sugar positioning. The technology is automating quality assurance protocols that previously required manual batch testing, compressing production lead times for reformulated variants.
Gulf Standards Organization beverage safety protocols are tightening preservative thresholds and microbial limits across cross-border trade. This regulatory compression is forcing manufacturers to standardize formulations at the lowest common denominator across GCC jurisdictions. Black tea and green tea segments are responding with accelerated aseptic line investments to maintain ambient distribution without chemical preservatives.
Young adult consumers in metropolitan Saudi Arabia and the UAE are rotating purchases toward antioxidant-positioned green tea variants during summer months. Convenience store chains are displacing carbonated shelf facings with chilled RTD tea to capture this seasonal demand rotation. This pattern concentrates in Riyadh and Dubai hypermarkets where premium refrigerator placement commands measurable traffic conversion.
Middle East Ready to Drink Tea Market Segmentation
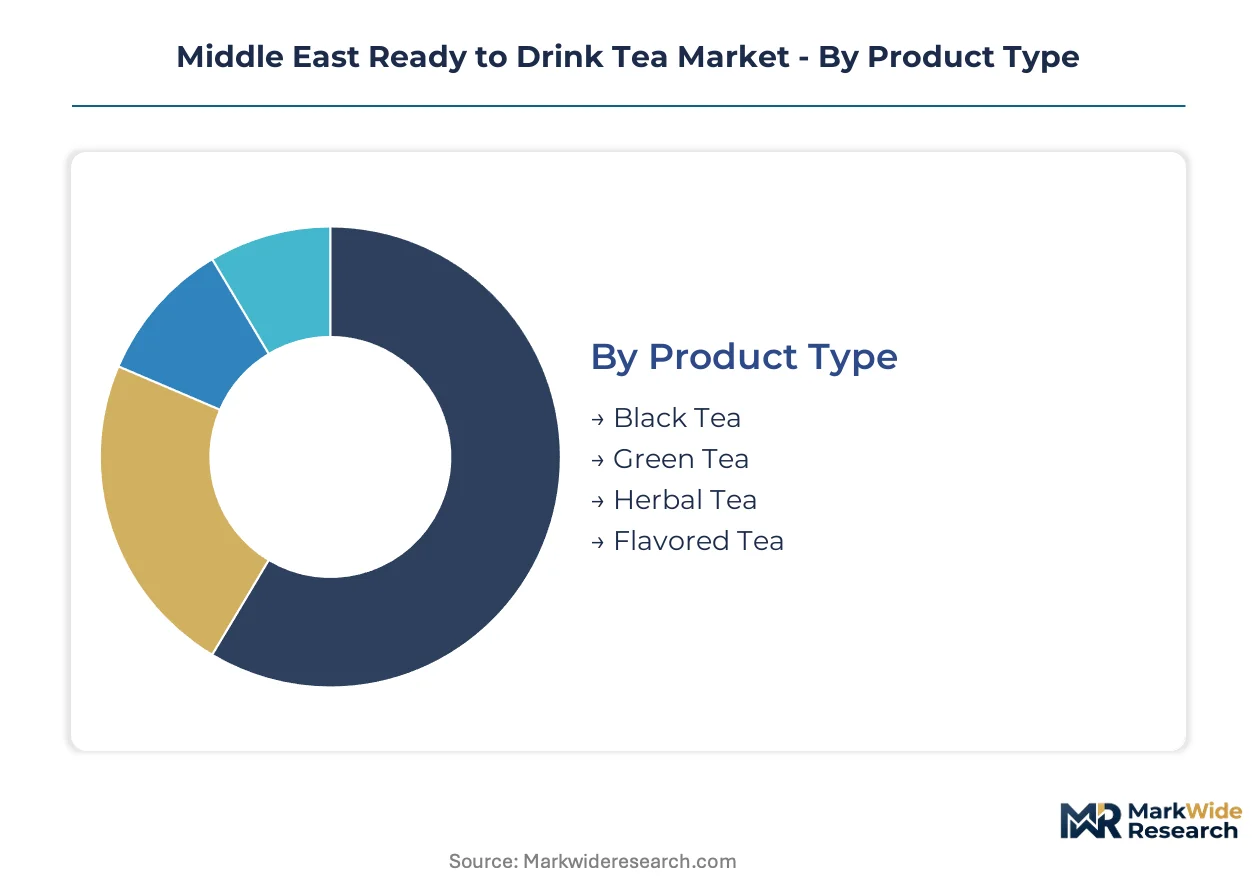
RTD tea segmentation in the Middle East reflects divergent purchasing logics across Gulf Cooperation Council retail environments. Product formulation, packaging durability, and channel accessibility each command distinct buyer priorities shaped by climate conditions and regulatory frameworks.
Product Type:
Consumer familiarity with traditional brewing methods differentiates purchase patterns across Gulf markets.
- Black Tea:Brewed from fully oxidized Camellia sinensis leaves with robust tannin profiles and amber coloration. Volume concentrates in Saudi hypermarkets where older demographics favor traditional taste profiles resistant to reformulation pressures.
- Green Tea:Minimally oxidized leaf extraction retaining catechin compounds and lighter body. Dubai convenience stores report strongest uptake among fitness-oriented consumers seeking antioxidant positioning during summer heat peaks.
- Herbal Tea:Hibiscus and chamomile infusions navigate variable botanical health claim regulations across Bahrain, Oman, and Kuwait national food codes.
- Flavored Tea:Fruit-forward and spice-infused variants targeting younger palates in UAE retail corridors.
Black Tea leads volumes today; Green Tea is gaining share fastest.
Packaging Type:
Thermal stability requirements and retail channel infrastructure dictate format selection across ambient and chilled distribution networks.
- Bottles:PET and glass formats with UV-resistant barrier layers support extended shelf life in 45°C Saudi storage conditions. Riyadh hypermarkets prioritize 500ml bottles for immediate-consumption placement adjacent to carbonated alternatives.
- Cans:Aluminum formats with internal epoxy linings prevent metal-ion migration into acidic tea matrices. UAE convenience chains favor 330ml slim cans for chilled end-cap displays targeting young adult demographics.
- Pouches:Flexible laminated films with aluminum oxide barriers serve price-sensitive segments in Omani retail.
- Tetra Packs:Aseptic carton formats enabling ambient distribution without refrigerated last-mile costs in Kuwait.
Bottles dominate current shelf presence; Cans are expanding most quickly in premium chilled channels.
Distribution Channel:
Refrigeration capacity and foot traffic patterns determine where margin pools concentrate across metropolitan retail corridors.
- Supermarkets:Large-format retail with dedicated beverage aisles and premium refrigerator end-caps. Dubai and Riyadh hypermarket chains anchor volume through bundle promotions and seasonal display rotations.
- Convenience Stores:Small-footprint urban retail with limited chilled capacity prioritizing immediate consumption. Saudi Arabia's expanding forecourt retail networks displace carbonated facings with RTD tea during summer demand peaks.
- Online Retailers:E-commerce platforms with ambient warehousing bypassing chilled last-mile constraints.
- Specialty Stores:Health-focused and gourmet retailers curating premium imported variants.
Supermarkets capture the largest revenue base; Convenience Stores show the steepest expansion trajectory.
End User:
Lifestyle segmentation tracks how consumption occasions vary across demographic cohorts and seasonal patterns.
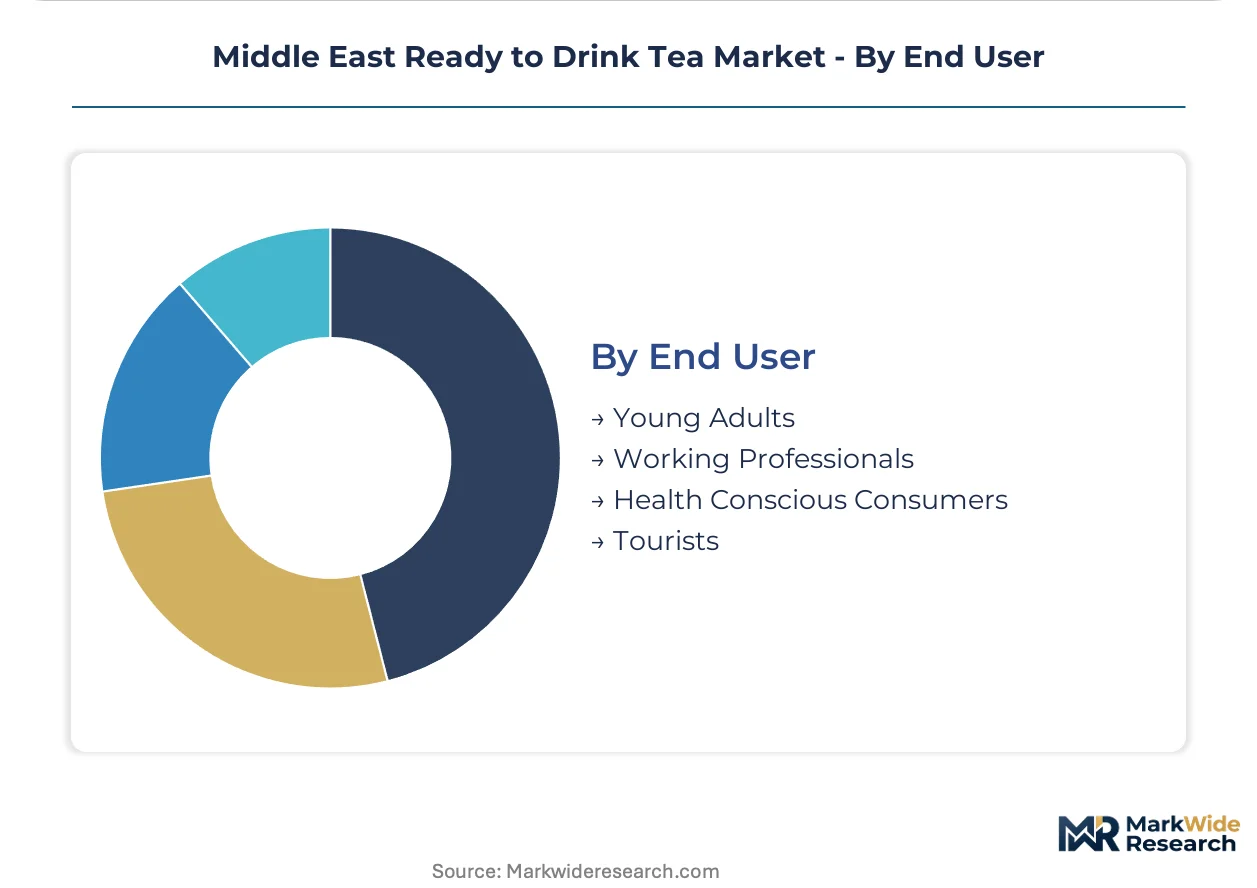
- Young Adults:University students and early-career professionals aged 18-30 driving flavor experimentation. This cohort in Dubai and Riyadh rotates purchases seasonally, displacing carbonates with chilled RTD tea during summer months.
- Working Professionals:Office-based consumers seeking portable refreshment without caffeine crash associations. Saudi corporate campuses are expanding vending machine RTD tea placement alongside traditional hot beverage options.
- Health Conscious Consumers:Fitness-oriented buyers prioritizing low-sugar and antioxidant claims.
- Tourists:Visitors seeking familiar hydration formats in UAE hospitality channels.
Young Adults anchor current demand; Health Conscious Consumers are climbing the fastest as SFDA labeling mandates reshape formulation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young marketing professionals and retail operations specialists concentrate in Gulf Cooperation Council metropolitan corridors, anchoring demand generation and distribution innovation across the region.
Saudi Arabia
Chilled RTD tea displaces carbonated soft drinks in Riyadh convenience stores as young adults pivot toward perceived healthier refreshment. Saudi Food and Drug Authority sugar disclosure mandates force reformulation investments toward reduced-calorie variants. Jeddah hypermarket chains expand refrigerated end-cap capacity to capture summer demand peaks.
United Arab Emirates
Dubai's fitness-oriented consumers drive antioxidant-positioned green tea uptake during extreme heat periods. UAE Ministry of Climate Change and Environment import certification requirements layer compliance obligations onto cross-border shipment timelines. Abu Dhabi forecourt retail networks prioritize immediate-consumption chilled placement adjacent to premium bottled water.
Kuwait
Health-conscious demographics seek low-sugar formulations as excise tax structures on sweetened beverages reshape purchasing economics. Gulf Standards Organization beverage safety protocols standardize preservative thresholds across national borders. Kuwait City supermarkets anchor volume through bundle promotions and seasonal display rotations.
Qatar
Working professionals in Doha's corporate corridors demand portable refreshment without caffeine crash associations. National food codes govern botanical health claims for hibiscus and chamomile variants. The Pearl-Qatar retail cluster commands premium refrigerator placement for imported RTD tea lines.
Bahrain
FSSAI-equivalent enforcement mechanisms impose microbial limits and preservative thresholds that shape ambient-stable recipe design. Young adult university populations rotate purchases seasonally toward chilled alternatives. Manama's expanding convenience store footprint displaces carbonated facings with RTD tea during summer months.
Middle East Ready to Drink Tea Market Competitive Landscape
The competitive structure tilts toward multinational beverage conglomerates with established Gulf bottling infrastructure and chilled distribution networks. Tiered positioning separates premium refrigerator end-cap placement from mass-market ambient shelf competition. Two strategic archetypes dominate: global soft drink majors leveraging existing cold chain assets, and regional bottlers exploiting local ingredient sourcing flexibility. Dominant competitive moves include portfolio diversification into hybrid coffee-tea bundles and accelerated aseptic line investments to secure clean-label positioning.
Among North American beverage majors, The Coca-Cola Company and PepsiCo Inc exemplify the infrastructure-dependent archetype, anchoring competitive positioning through captive Gulf bottling networks and hypermarket chain relationships. Nestle S.A. occupies a distinct tier through Nescafe-Tea bundle placements that capture premium margin pools in Saudi retail refrigeration. These three conglomerates represent the primary competitive anchors against which regional specialists and private-label entrants must differentiate.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc |
| Nestle S.A. |
| Keurig Dr Pepper Inc |
| Rauch Fruchtsäfte GmbH & Co OG |
| Sapporo Holdings Limited |
| Barakat Group of Companies |
| The Savola Group |
| Nai Arabia Food Company |
| Others |
Pricing and Supply Chain Analysis
SFDA sugar disclosure mandates are forcing procurement teams to source alternative sweeteners and reformulate legacy recipes, compressing input cost models and redistributing pricing power toward suppliers with clean-label certification capabilities.
Pricing Analysis
Bundled coffee-tea refrigerator placement commands premium positioning against unbundled single-category SKUs in Saudi hypermarkets. Three-tier pricing structure across premium chilled, standard ambient, and economy pouch formats reflects refrigeration cost pass-through and brand equity gaps. Pricing pressure stems from excise tax thresholds on sweetened beverages that incentivize sub-levy sugar reformulation. Price-sensitive buyers concentrate in Omani and Kuwaiti convenience channels, while premium placement in Dubai's The Pearl-Qatar cluster shows lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Sri Lankan and Kenyan tea leaf supply basins exposed to climate-impacted harvest volatility. Raw material economics draw from black tea extracts, green tea catechins, and alternative sweetener chemistries. Supply chain risk centers on Gulf Standards Organization microbial limit variations that force lowest-common-denominator formulation standardization. Distribution runs through captive bottling infrastructure at hypermarket chains and forecourt retail networks across Riyadh and Dubai corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East RTD tea market reads as a late-cycle quality story as young adult demand pivots toward antioxidant-positioned green tea variants with premium refrigerator placement economics.
For Market Incumbents: Extend aseptic filling capacity investments to secure SFDA-compliant clean-label positioning before regulatory deadlines tighten. Deepen backward integration into alternative sweetener supply to defend margin compression from input cost volatility. Anchor hypermarket chain relationships through exclusive chilled end-cap agreements that block entrant shelf access. For New Entrants and Emerging Players: Begin with herbal botanical variants in Bahrain and Oman where health claim complexity creates white-space navigation opportunities for specialized formulators. Target Kuwaiti health-conscious demographics with sub-excise-threshold sugar positioning. Pursue direct-to-specialty-store distribution to bypass captive bottler infrastructure at major retailers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional bottlers possessing local ingredient sourcing flexibility and Gulf Standards Organization pre-certification capabilities. Long-term viability hinges on chilled distribution infrastructure ownership across 45°C ambient conditions. Watch for SFDA enforcement acceleration as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Line Investment | Automates clean-label transition for SFDA sugar disclosure compliance in Saudi bottling facilities. |
| Alternative Sweetener Sourcing | Rebuilds cost models around stevia and monk fruit extracts to escape excise tax classification. |
| Refrigerated End-Cap Partnership | Secures premium placement adjacent to carbonated alternatives in Dubai hypermarket chains. |
| Herbal Botanical Registration | Navigates variable national food codes for hibiscus and chamomile variants across Bahrain and Oman. |
| Coffee-Tea Bundle Positioning | Captures premium margin pools through adjacent-category traffic in Saudi retail refrigeration. |
Research Methodology
Direct dialogue with beverage brand managers, hypermarket category buyers, Gulf bottling facility operators, and SFDA regulatory consultants anchored qualitative grounding. Secondary validation drew from Saudi Food and Drug Authority labeling circulars, Gulf Standards Organization beverage safety protocols, UAE Ministry of Climate Change and Environment import certification records, and Nielsen retail audit data across GCC metropolitan corridors. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Bottom-up modeling segmented volume and value across product type, packaging durability tier, distribution channel refrigeration requirement, and end-user demographic cohort. CAGRs were derived from segment-level growth rate synthesis applied across the projection horizon. Forecast inputs incorporated SFDA enforcement timeline assumptions, excise tax threshold calibration by Gulf finance ministries, and climate-impacted tea leaf harvest volatility from Sri Lankan and Kenyan supply basins.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to preservative thresholds, geopolitical disruption to Red Sea shipping lanes, and abrupt reformulation failures in 45°C stability testing. Forecasts reflect documented assumptions about consumer acceptance of alternative sweetener taste profiles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Matcha Tea Market
Tea
Africa Tea Market
Tea
White Tea Extract Market
Tea
Instant Tea Premix Consumption Market
Tea
Instant Tea Premixes Market
Tea
Black Tea Base Bubble Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Pyramid Tea Bags Market
Tea
Rooibos Tea Market
Tea
Herbal Tea Market
Tea
Global Catechin Market
Tea
Oolong Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Matcha Products Market
Tea
Tea Concentrate Market
Tea
Global Tea Bag Market