
 Africa Ready to Drink Tea Market | 2026-2036
Africa Ready to Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Ready to Drink Tea Market Outlook
Kenya's Tea Board quality certification requirements is restructuring procurement standards across the Africa ready to drink tea supply chain. BOS Brands (Pty) Ltd leverages its rooibos-specialized vertical integration to secure premium positioning in South African retail channels. The Coca-Cola Company anchors its Honest Tea distribution through existing cold-chain infrastructure spanning multiple African markets. PepsiCo, Inc. competes aggressively on price in Nigeria's convenience store segment with Lipton-branded chilled offerings.
Africa ready to drink tea comprises commercially brewed, packaged tea beverages preserved through pasteurization, aseptic filling, or hot-fill processes, typically containing tea extract concentrations of 0.3-0.6% solids, sweeteners, acidulants, and shelf-life stabilizers for ambient or refrigerated distribution. The product serves consumers seeking portable, consistent-quality alternatives to freshly brewed tea in climates where chilled refreshment dominates consumption occasions. Bottled tea leads volume across the continent due to established PET and glass bottling lines originally built for soft drinks, while herbal tea and rooibos variants capture disproportionate margin pools through premium positioning in South African and Kenyan supermarkets. Fruit infused tea represents the fastest-growing flavor dimension, driven by youth preference for novel taste profiles distributed through convenience stores and foodservice channels in West African cities.
FSSAI-equivalent national food safety agencies in Nigeria and Kenya enforce labeling, preservative limits, and shelf-life declarations that determine which imported and locally produced ready to drink tea formulations gain retail authorization. South Africa's Department of Health regulations on sugar content and front-of-pack warning labels are pressuring reformulation toward reduced-calorie variants across multinational and domestic portfolios. Stakeholders must monitor how divergent national sweetener and additive standards fragment formulation requirements across Africa's major markets.
Market Dynamics
Kenya's Tea Board quality certification mandates are forcing bottlers to restructure procurement networks, creating tiered supplier access that separates compliant blenders from informal sources across East African supply chains.
Growth Catalysts
- Urban Convenience Infrastructure:Cold-chain expansion in Lagos and Nairobi enables shelf-stable distribution of chilled tea formats to convenience stores previously limited to ambient carbonated beverages.
- Kenya Tea Board Certification:Mandatory quality labeling standards are elevating consumer trust in packaged tea, accelerating formal channel migration away from unpackaged alternatives.
- Aseptic Filling Technology:New hot-fill and pasteurization lines originally built for soft drinks are being repurposed for tea extraction at 0.3-0.6% solids concentration, lowering entry barriers for regional bottlers.
Market Restraints
- Sugar Input Volatility:Reformulation pressures from South Africa's Department of Health front-of-pack warning labels are colliding with fluctuating sucrose and alternative sweetener costs across the continent.
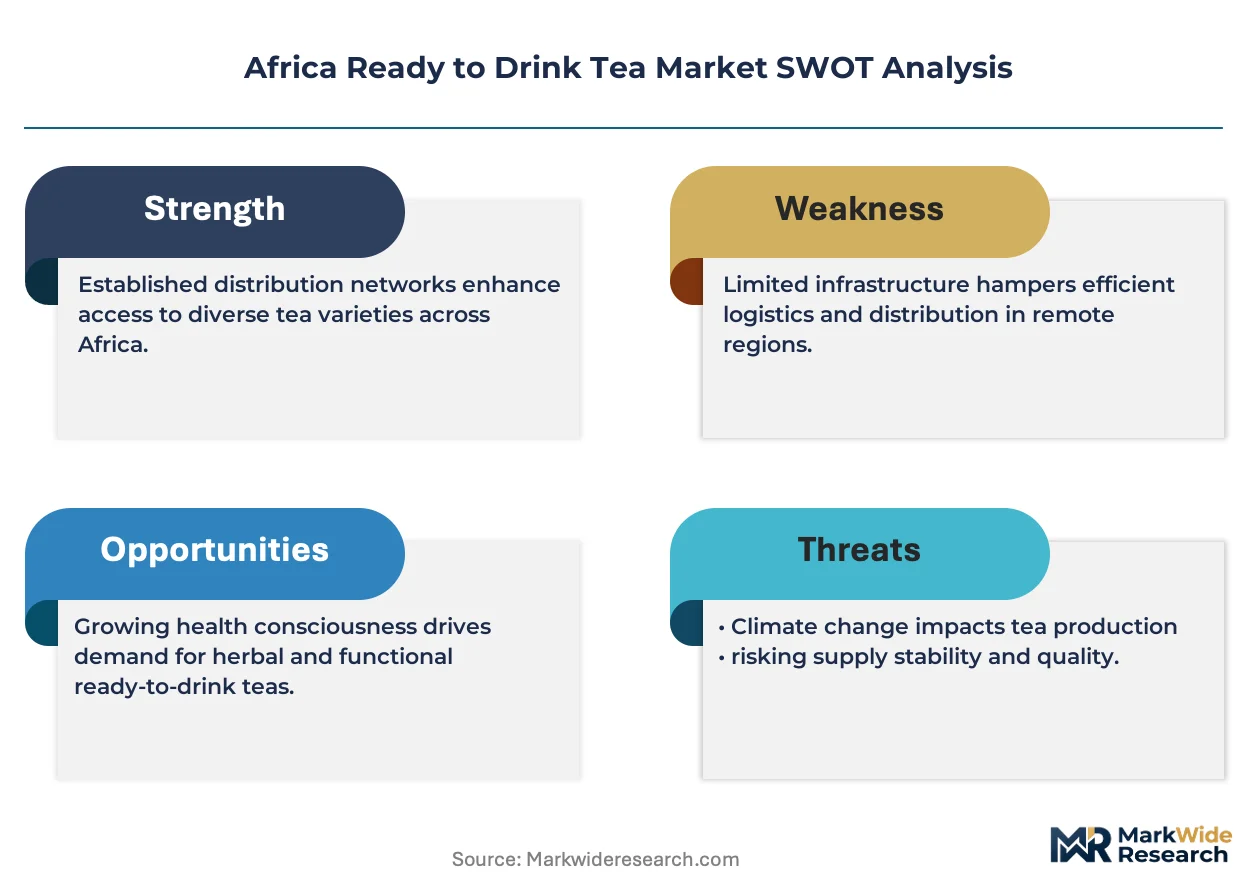
- Import Dependency:Nigeria's ready-to-drink tea segment relies heavily on foreign extraction equipment and flavor stabilizers, exposing margins to currency fluctuation and freight cost spikes.
- Refrigeration Gap:Inconsistent grid electricity in secondary Kenyan and Nigerian cities limits chilled distribution reach, compressing addressable market geography to major urban corridors.
Strategic Opportunities
- Herbal Variant White Space:Rooibos and indigenous herbal infusions remain underdeveloped in West African markets outside South Africa's premium supermarket channels, offering margin expansion potential.
- Foodservice Direct Distribution:Bypassing traditional wholesale layers to supply quick-service restaurants and workplace cafeterias in Accra and Dar es Salaam captures higher-frequency consumption occasions.
- Fruit-Infused Format Innovation:Youth preference for novel taste profiles in Lagos convenience stores points to unsatisfied demand for mango, hibiscus, and citrus-blended tea extensions.
Industry Challenges
- Formulation Fragmentation:Divergent national sweetener and additive standards between Nigeria's food safety agency, Kenya's Tea Board, and South Africa's Department of Health force SKUs that cannot cross borders without reformulation.
- Cold-Chain Capex Burden:Establishing refrigerated distribution for chilled tea formats requires fleet investment that domestic bottlers struggle to finance against multinational cold-chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Ready to Drink Tea Market |
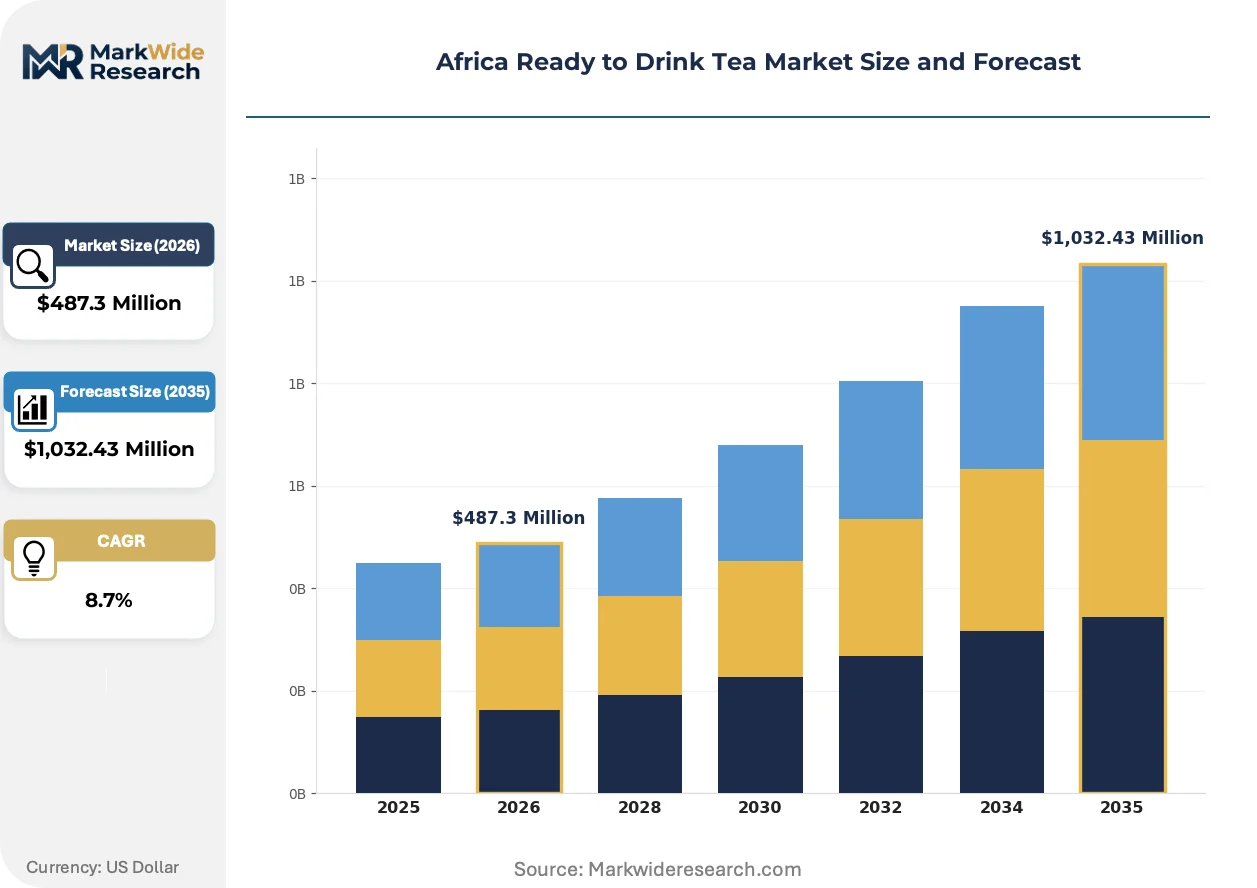
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottled Tea, Canned Tea, Ready-to-Serve Tea, Instant Tea Flavor: Black Tea, Green Tea, Herbal Tea, Fruit Infused Tea Packaging Type: Glass Bottles, Aluminium Cans, Tetra Packs, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice |
| Companies Covered | BOS Brands (Pty) Ltd, The Coca-Cola Company, PepsiCo, Inc., CWAY Group, Clover S A (Pty) Ltd, Tata Consumer Products Ltd, Unilever, Nestlé, Dynamic Brands Manufacturing (Pty) Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Ready to Drink Tea Market Strategic Shifts
Technology and regulatory pressure are converging to reshape how ready-to-drink tea is formulated, certified, and distributed across African markets with divergent infrastructure maturity.
Aseptic processing systems with integrated extraction modules are expanding into mid-sized Nigerian and Kenyan bottling facilities, enabling in-house tea concentrate production that previously required imported premix. Young urban professionals in Lagos are adopting these locally processed formats at accelerating rates. The technology is expanding into secondary cities by compressing the capital threshold for shelf-stable tea manufacturing.
South Africa's Department of Health regulations on sugar content and front-of-pack warning labels are pressuring reformulation toward reduced-calorie variants across multinational and domestic portfolios. Bottlers must navigate divergent national sweetener standards that fragment formulation requirements. The premium segment is responding fastest, with rooibos and unsweetened variants gaining shelf space in Cape Town and Johannesburg supermarkets.
Convenience stores in West African cities are displacing traditional open-market tea vendors as the primary purchase channel for ready-to-drink formats. Young professionals in Lagos and Accra now buy chilled tea during commute and workday occasions rather than brewing at home. This channel rotation is most visible in Nigeria, where formal retail penetration has overtaken informal distribution in Lagos state.
Africa Ready to Drink Tea Market Segmentation
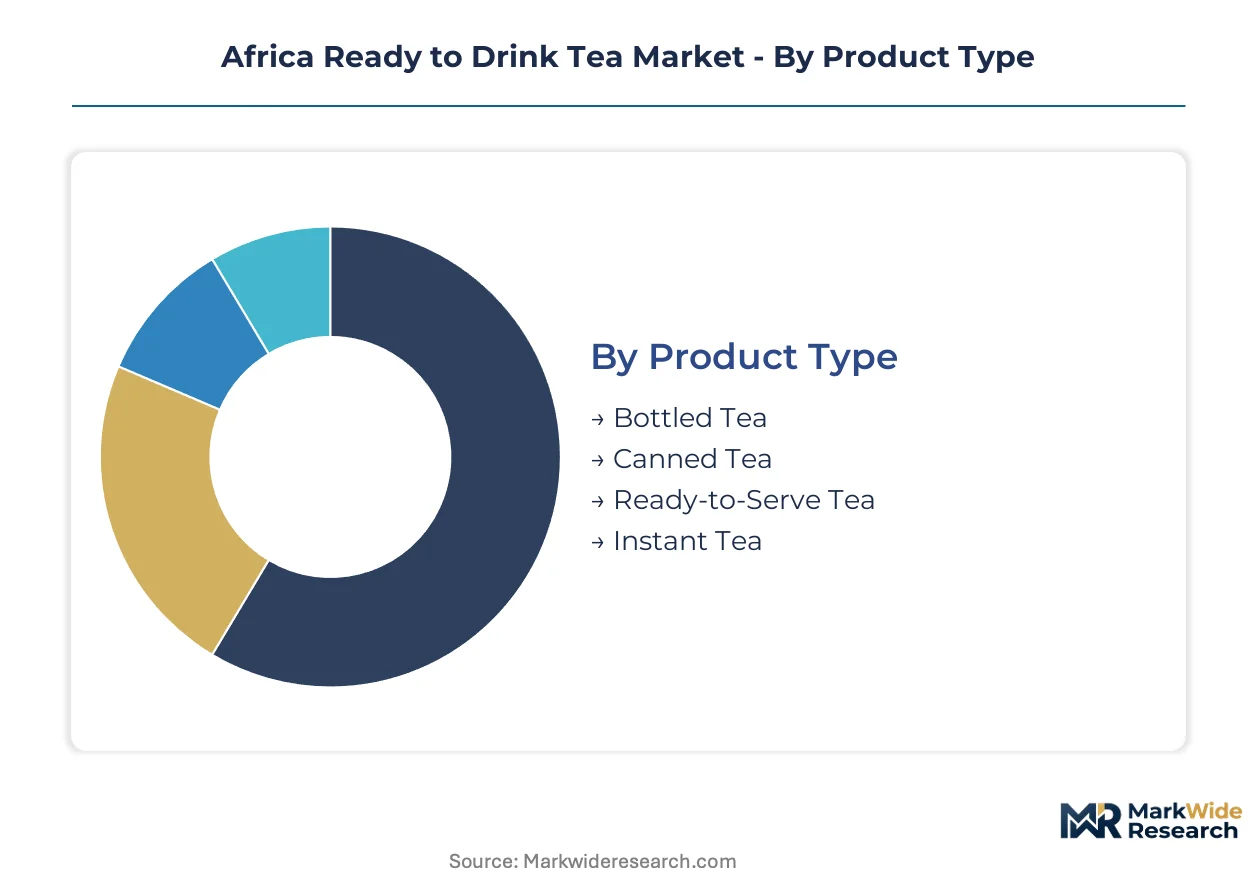
Segmentation in Africa's ready-to-drink tea market reveals how infrastructure constraints and consumer preferences fragment commercial opportunity across packaging formats, flavor profiles, and channel access. Bottlers must match product specifications to cold-chain availability, regulatory thresholds, and urban purchasing patterns that vary sharply between Lagos convenience stores and Cape Town supermarkets.
Product Type:
Purchase frequency and consumption occasion determine format selection, with portability and shelf stability driving buyer decisions across climates with uneven refrigeration.
- Bottled Tea:PET and glass bottling lines originally built for soft drinks now handle tea extraction at 0.3-0.6% solids concentration. Lagos and Nairobi convenience stores stock chilled bottled formats for commute consumption, though grid instability limits reach beyond major urban corridors.
- Canned Tea:Aluminium cans deliver ambient shelf stability that bypasses cold-chain gaps in secondary Nigerian and Kenyan cities. Youth consumers in Accra favor canned formats for workplace and outdoor occasions where refrigeration is unavailable.
- Ready-to-Serve Tea:Larger-volume containers target foodservice and household consumption in South African supermarkets. Kenya Tea Board certification requirements are elevating quality standards for this segment in formal retail channels.
- Instant Tea:Powder and liquid concentrates serve price-sensitive consumers and rural distribution points with limited cold infrastructure. Nigerian open markets move instant formats through informal vendor networks.
Volume sits with bottled formats leveraging existing soft-drink infrastructure; growth tilts toward canned variants that solve refrigeration gaps in expanding urban markets.
Flavor:
Raw material sourcing proximity and indigenous taste preferences create geographic flavor strongholds that resist standardization across national markets.
- Black Tea:Kenya's tea-growing regions supply concentrated black tea extract to regional bottlers. Nigerian consumers show strongest preference for sweetened black tea in chilled formats distributed through Lagos convenience stores.
- Green Tea:Health-positioned variants gain traction in South African premium supermarkets alongside reduced-sugar formulations. Cape Town and Johannesburg retailers allocate expanding shelf space to unsweetened green tea lines.
- Herbal Tea:Rooibos from South Africa's Cederberg region commands premium positioning through vertical integration by specialized producers. Kenyan and Nigerian markets remain underdeveloped for herbal variants outside niche urban segments.
- Fruit Infused Tea:Mango, hibiscus, and citrus blends capture youth demand in West African cities. Lagos convenience stores report strongest velocity for novel fruit-tea combinations targeting experimental taste preferences.
Black tea anchors volume through established extraction supply chains; fruit-infused variants are expanding most quickly as bottlers respond to generational taste shifts in coastal West African markets.
Packaging Type:
Material choice reflects a trade-off between shelf-life extension, recycling infrastructure, and capital investment requirements for regional bottlers.
- Glass Bottles:Premium positioning in South African supermarkets leverages perceived quality and reusability deposit schemes. Higher freight costs and breakage rates constrain glass adoption in Nigerian distribution networks.
- Aluminium Cans:Lightweight and infinitely recyclable, cans suit ambient distribution in markets with refrigeration gaps. Kenyan bottlers are adding canning lines repurposed from soft-drink operations to capture this demand.
- Tetra Packs:Aseptic carton technology enables shelf-stable distribution without cold-chain investment. Nigerian secondary cities with inconsistent grid electricity favor Tetra Pack formats for household stock-up purchasing.
- Pouches:Lowest per-unit packaging cost supports price-competitive positioning in informal retail channels. Instant tea concentrates in flexible pouches dominate rural Kenyan distribution points.
Glass holds premium positioning in developed retail; Tetra Packs are gaining share fastest where infrastructure constraints favor ambient-stable formats.
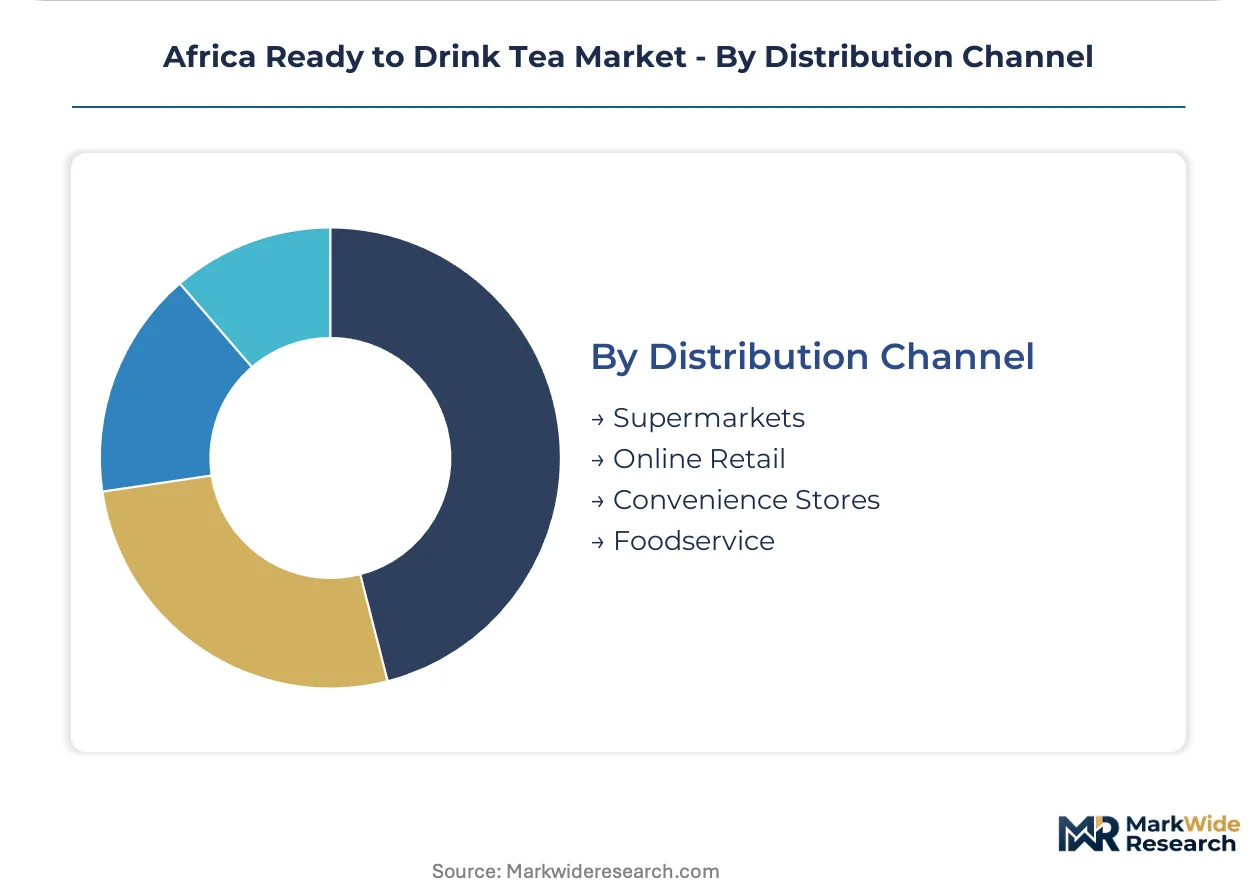
Distribution Channel:
Channel selection determines margin structure, brand control, and access to consumption occasions ranging from impulse refreshment to planned household purchasing.
- Supermarkets:Formal retail in South Africa and Nigeria's major cities provides brand-building visibility and premium pricing power. Kenya's supermarket consolidation is concentrating ready-to-drink tea assortment decisions among fewer buyers.
- Online Retail:E-commerce penetration remains limited but is expanding in Lagos and Nairobi for bulk and subscription formats. Delivery logistics for chilled products constrain online growth to ambient-stable variants.
- Convenience Stores:Lagos and Accra convenience stores have displaced open-market vendors as the primary channel for single-serve chilled tea. Young professionals purchase during commute and workday occasions, driving highest-frequency consumption.
- Foodservice:Direct supply to quick-service restaurants and workplace cafeterias in Dar es Salaam and Accra captures institutional volume. Bypassing wholesale layers improves margins for bottlers with direct distribution capability.
Supermarkets and convenience stores split volume in urban centers; foodservice is climbing the fastest as bottlers build direct distribution relationships with institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos and Nairobi anchor Africa's ready-to-drink tea consumption, with cold-chain expansion enabling chilled distribution to convenience stores that previously stocked only ambient carbonated beverages. These urban corridors concentrate demand from young professionals seeking portable refreshment alternatives.
Nigeria
Lagos convenience stores drive the highest-frequency consumption occasions as young professionals purchase chilled tea during commute and workday hours. The country's national food safety agency enforces labeling and preservative limits that determine which imported and locally produced formulations gain retail authorization. Northern Nigerian cities remain underserved due to refrigeration gaps, compressing addressable geography to major urban corridors.
Kenya
Nairobi's supermarket consolidation concentrates assortment decisions among fewer buyers while accelerating formal channel migration. Kenya's Tea Board mandates quality certification and labeling standards that separate compliant blenders from informal sources across East African supply chains. Secondary cities face inconsistent grid electricity that limits chilled distribution reach beyond the capital corridor.
South Africa
Cape Town and Johannesburg supermarkets allocate expanding shelf space to reduced-sugar and unsweetened variants responding to Department of Health front-of-pack warning label requirements. The country's Department of Health regulations on sugar content are pressuring reformulation across multinational and domestic portfolios. Rooibos from the Cederberg region commands premium positioning through specialized producers with backward integration into raw material supply.
Ghana
Accra's quick-service restaurants and workplace cafeterias capture higher-frequency consumption occasions through direct foodservice distribution bypassing traditional wholesale layers. The country's food safety regulator enforces standards that parallel Nigeria's framework while permitting greater flexibility in sweetener formulations. Youth consumers favor canned formats for workplace and outdoor occasions where refrigeration is unavailable.
Tanzania
Dar es Salaam's institutional buyers are climbing fastest as bottlers build direct distribution relationships with foodservice channels. The country's national standards bureau maintains additive thresholds that diverge from Kenyan Tea Board requirements, fragmenting cross-border SKU compatibility. Port infrastructure supports imported extraction equipment and flavor stabilizers that domestic production currently lacks.
Africa Ready to Drink Tea Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification compliance and cold-chain infrastructure dimensions. The market structures around multinational beverage conglomerates with existing African distribution networks, regional bottlers repurposing soft-drink production lines, and specialized rooibos producers with captive supply of indigenous raw materials. Three archetypes dominate: scale-driven multinationals leveraging cross-market infrastructure, mid-sized regional bottlers exploiting aseptic technology cost compression, and vertical specialists commanding premium positioning through unique raw material access. Competitive intensity manifests through portfolio diversification into fruit-infused variants and direct foodservice distribution relationships that bypass wholesale margin extraction.
Among multinational conglomerates, The Coca-Cola Company and PepsiCo, Inc. exemplify scale-driven archetypes that occupy positions across multiple African markets through existing cold-chain infrastructure. BOS Brands (Pty) Ltd represents the specialized verticalist model, anchoring premium-tier positioning through rooibos-specific backward integration that competitors cannot readily replicate. These three companies illustrate how divergent strategic starting points—global scale versus regional specialization versus raw material captivity—produce distinct competitive positions within the same market expansion window.
| Leading Market Players |
|---|
| BOS Brands (Pty) Ltd |
| The Coca-Cola Company |
| PepsiCo, Inc. |
| CWAY Group |
| Clover S A (Pty) Ltd |
| Tata Consumer Products Ltd |
| Unilever |
| Nestlé |
| Dynamic Brands Manufacturing (Pty) Ltd |
| Others |
Value Chain & Pricing Dynamics
Tea Board of Kenya quality certification benchmarks cascade through procurement tiers into price stratification that separates compliant blenders from informal sources. Bottlers absorbing these certification costs pass differential pricing through to retail channels, with Lagos convenience stores and Cape Town supermarkets occupying distinct margin bands.
Pricing Analysis
Kenya Tea Board certification grade anchors value-based pricing across the supply chain, with compliant extract concentrations commanding premiums in formal retail channels. Price differentiation rests on certification status and cold-chain delivery capability, not brand equity alone. Cost compression in economy-tier ambient formats is intensifying because Nigerian bottlers face currency-driven input volatility. Price-sensitive buyers in secondary Kenyan cities favor instant concentrates, while Lagos professionals accept chilled premiums for commute consumption.
Supply Chain Analysis
Kenya's domestic-content mandates for tea extract sourcing are reshaping procurement networks across East African bottling operations. Geographic supply concentration centers on Kenya, South Africa, and Nigeria for extraction and formulation. Raw material dependencies include Cederberg rooibos, Kenyan black tea solids, and imported flavor stabilizers. Single-source vulnerability runs through Nigerian bottlers' reliance on foreign extraction equipment. Distribution runs through cold-chain-equipped wholesalers in Lagos and Nairobi, with ambient-stable formats reaching secondary cities via traditional trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Kenya Tea Board certification requirements erect barrier-to-entry moats favoring incumbent blenders with established supplier audits and quality management systems.
For Market Incumbents: Anticipate margin pressure from aseptic technology cost compression enabling mid-sized regional bottlers to enter shelf-stable segments. Defend position by deepening backward integration into Kenyan tea-growing cooperatives and accelerating direct foodservice distribution in Accra and Dar es Salaam to bypass wholesale margin extraction.
For New Entrants and Emerging Players: Northern Nigerian cities with refrigeration gaps present the most penetrable white-space target for ambient-stable canned formats. Secondary Kenyan urban corridors offer comparable entry points for Tetra Pack variants. Foodservice direct supply to workplace cafeterias provides the clearest go-to-market angle with lower channel establishment costs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized rooibos producers with captive Cederberg supply in South Africa during periods of input cost volatility. Long-term viability over a multi-year horizon hinges on certification-compliant assets with established cold-chain partnerships. Watch Kenya Tea Board enforcement intensity as the inflection signal separating formal-channel winners from informal-market survivors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tea Cooperatives | Kenya Tea Board compliance secures preferential extraction supply for certified bottlers. |
| Direct Foodservice Distribution Buildout | Accra and Dar es Salaam workplace cafeterias capture higher-frequency institutional volume. |
| Aseptic Filling Technology Deployment | Repurposed soft-drink lines lower capital thresholds for shelf-stable tea manufacturing. |
| Fruit-Infused Variant Pipeline Expansion | Mango and hibiscus blends target youth preference shifts in Lagos convenience stores. |
| Cold-Chain Infrastructure Partnership | Third-party refrigerated logistics extend chilled format reach beyond major urban corridors. |
Study Parameters
Multi-period observation of Kenya Tea Board certification adoption rates, Lagos convenience store SKU velocity, and South African supermarket shelf-space allocation anchored the trend analysis, supplemented by interviews with bottling plant managers, category buyers at Nigerian retailers, tea board regulatory officers, and cold-chain logistics operators. Secondary validation drew from customs trade records, national food safety agency filings, retail audit databases, and beverage industry association reports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Input-output matrices mapped tea extract supply flows through formulation, packaging format selection, and channel distribution across the projection horizon. Segmentation dimensions included product type, flavor profile, packaging material, and distribution channel, with regulatory framework clusters treated as cross-cutting modifiers. CAGRs were derived from fitted trend extrapolation with elasticity adjustments for income and urbanization drivers. Forecast inputs incorporated aseptic technology penetration curves and cold-chain infrastructure expansion timelines.
Revisions become necessary when Kenya Tea Board enforcement intensity shifts, Nigerian currency volatility exceeds historical bands, or South African sugar-content regulations tighten beyond current warning-label thresholds. Forecasts reflect documented assumptions about certification compliance rates and infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Green Tea Extract Market
Tea
Black Tea Extracts Market
Tea
Tea Polyphenols Market
Tea
North America Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Tea Infuser Market
Tea
Rooibos Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Green Tea Leaves Market
Tea
Nitro Tea Market
Tea
US Ready to Drink Tea Market
Tea
Organic Tea Market
Tea
Smart Tea Set Market
Tea
Europe Tea Market
Tea
Green Tea Market
Tea
Light-Fermented Tea Market