
 Tea Concentrate Market | 2026-2036
Tea Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Concentrate Market Analytics
The tea concentrate industry is repositioning around a widening gap between artisanal cold-brew extracts and mass-market instant powders. PepsiCo, Inc. leverages its bottling network to dominate ready-to-drink distribution in North American convenience channels. Tata Consumer Products Limited anchors its portfolio on heritage sourcing from Indian estates, competing on provenance credentials. ITO EN, Ltd. specializes in green tea concentrate applications, sustaining technical leadership through proprietary extraction patents.
Tea concentrate denotes a reduced-volume preparation derived from brewed tea leaves through evaporation, freeze concentration, or membrane filtration, typically yielding solids content between 20% and 65% for industrial reconstitution. Manufacturers deploy these concentrates across beverage manufacturing, food service dispensing systems, and private-label retail formulations where batch consistency and shelf stability matter. Liquid concentrates command the deepest margin pools in food service contracts, while powdered concentrates occupy volume leadership in emerging markets with weaker cold-chain infrastructure. Organic feature positioning is accelerating fastest among specialty store channels, though caffeinated variants still generate the majority of revenue across supermarkets and online retail.
FDA oversees concentrate labeling and health claims in the United States, while EFSA governs novel food approvals and caffeine content thresholds across European markets. Japan's Ministry of Health, Labour and Welfare enforces pesticide residue limits that directly shape sourcing requirements for concentrate suppliers serving East Asian export channels. Stakeholders must monitor evolving sugar taxation frameworks and single-use packaging mandates, as these policies increasingly determine which concentrate formats and distribution channels retain cost competitiveness.
Market Dynamics
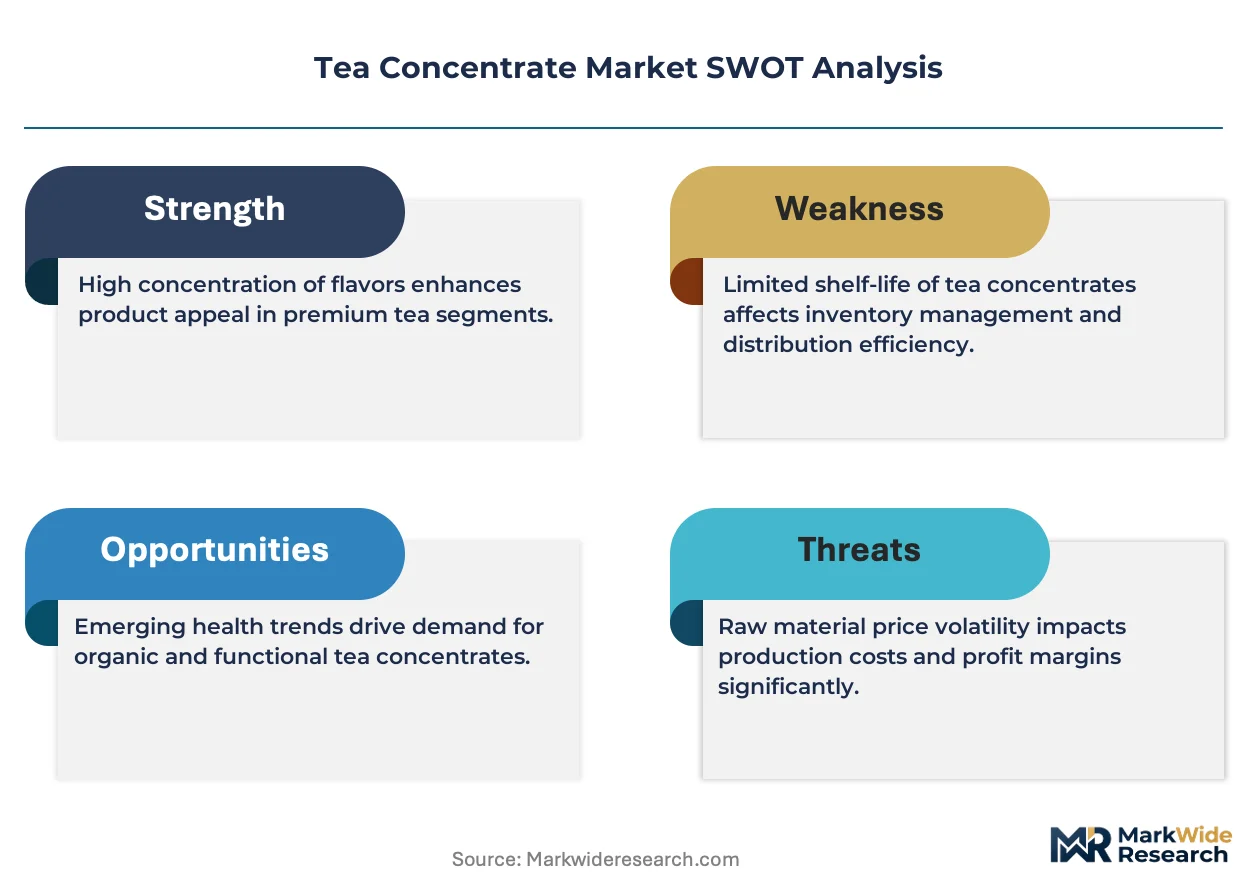
Cold extraction patents and freeze-concentration equipment economics are compressing production costs while reshaping competitive moats between artisanal and industrial concentrate suppliers.
Growth Catalysts
- Japan's pesticide residue limits:These Ministry of Health, Labour and Welfare standards are accelerating certified organic sourcing investments by concentrate exporters serving East Asian channels.
- Food service dispensing systems:Labor efficiency mandates in quick-service restaurant chains are pulling liquid concentrate volumes into fountain beverage infrastructure.
- Cold-chain infrastructure gaps:Powdered concentrate formats are capturing volume leadership in emerging markets where refrigeration reliability remains uneven.
Market Restraints
- Input cost volatility:Tea leaf auction prices in Indian and Kenyan exchanges fluctuate with monsoon patterns, compressing margin predictability for concentrate processors.
- Supply concentration risk:Premium estate sourcing clusters in Assam and Darjeeling create geographic vulnerability to climate-induced yield shocks.
- Substitution threat:Ready-to-drink bottled teas and cold-brew coffee concentrates are diverting convenience-oriented consumers from reconstituted concentrate formats.
Strategic Opportunities
- German organic retail channels:Premium tea culture intersects with Bio-Siegel certification requirements, creating white space for heritage-provenance concentrate positioning.
- Carbonated tea hybrids:Sparkling water convergence with tea concentrates is opening new fountain and canned beverage applications.
- US sugar taxation frameworks:Municipal and state-level sweetened beverage taxes are incentivizing unsweetened concentrate formulations as restaurant cost-avoidance strategies.
Industry Challenges
- Extraction chemistry expertise:The scarcity of process engineers skilled in membrane filtration and freeze-concentration is extending pilot-to-production timelines for new facilities.
- Dual certification complexity:Simultaneous USDA Organic and EU organic compliance requires parallel audit trails that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Concentrate Market |
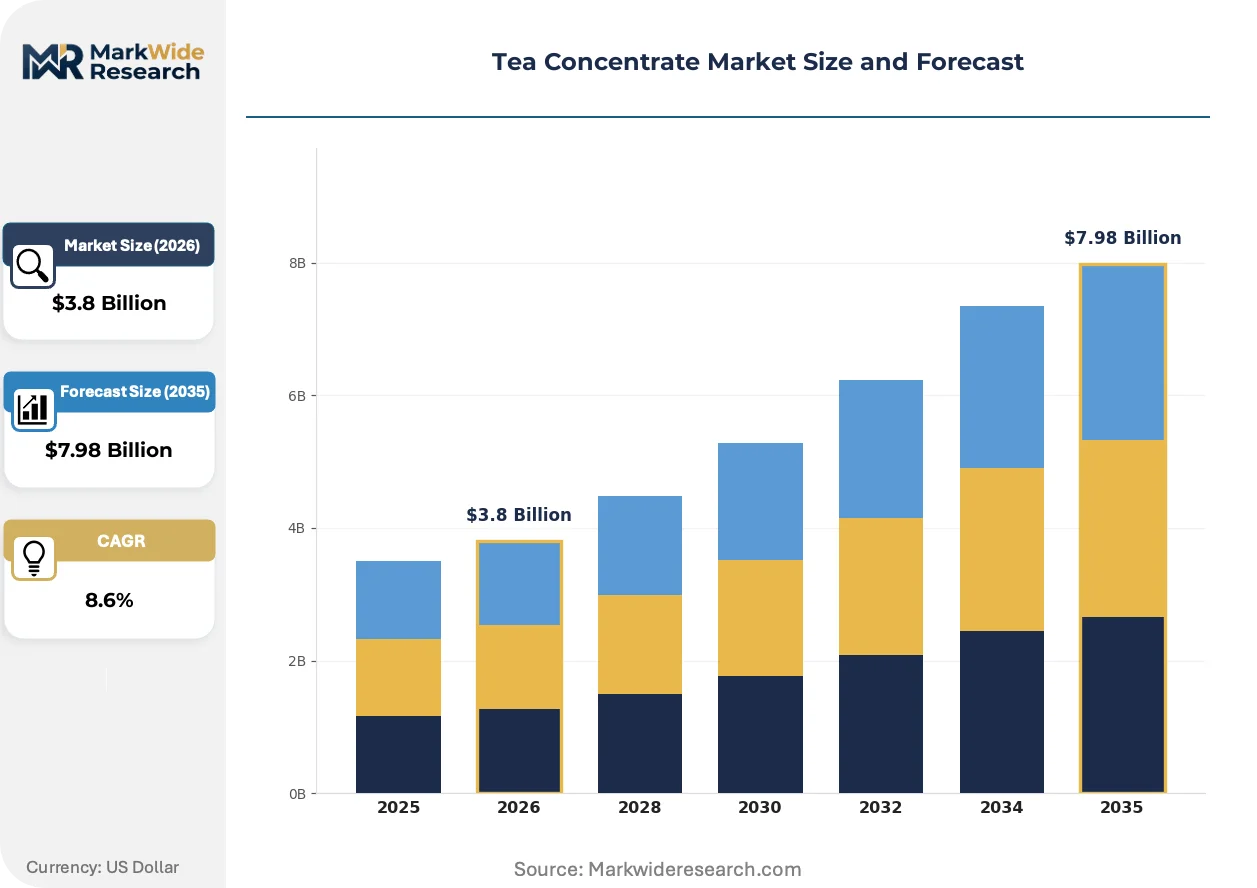
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrates, Powdered Concentrates, Instant Tea, Ready-to-Drink Feature: Organic, Non-GMO, Low Calorie, Caffeinated Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Restaurants, Beverage Manufacturers, Retailers, Consumers |
| Companies Covered | PepsiCo, Inc., Tata Consumer Products Limited, Unilever PLC, Nestlé S.A., A. Holliday & Company Inc., H&H Products Company, Cooper Tea Company LLC, Maya Tea Company, ITO EN, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Concentrate Market Evolving Landscape
Production technology and regulatory compliance frameworks are converging to redefine what constitutes premium concentrate quality, while distribution channels fragment between institutional food service and direct-to-consumer formats.
Membrane filtration systems incorporating ceramic microfiltration and reverse osmosis stages are rewriting the economics of high-solids extraction. Mid-scale concentrate processors in the United States and Germany are retrofitting existing evaporation lines with these hybrid systems to capture specialty-grade outputs previously reserved for artisanal cold-brew operations. The technology is rewriting the boundary between mass-market and craft concentrate positioning by enabling batch consistency at previously unattainable scale.
EFSA novel food approval pathways for new botanical concentrate sources are extending time-to-market for innovation pipelines. The regulatory friction is compressing R&D investment returns for suppliers seeking to diversify beyond Camellia sinensis-derived products. European beverage manufacturers are responding by consolidating formulation efforts around grandfathered ingredient lists rather than pioneering unproven extracts.
Direct procurement relationships between restaurant chains and concentrate processors are displacing traditional distributor intermediaries in North American food service. Large operators are negotiating captive supply agreements that specify extraction method, solids content, and custom flavor profiles. This channel restructuring is most visible in the United States, where regional beverage management groups are consolidating purchasing authority across multi-brand portfolios.
Tea Concentrate Market Segmentation
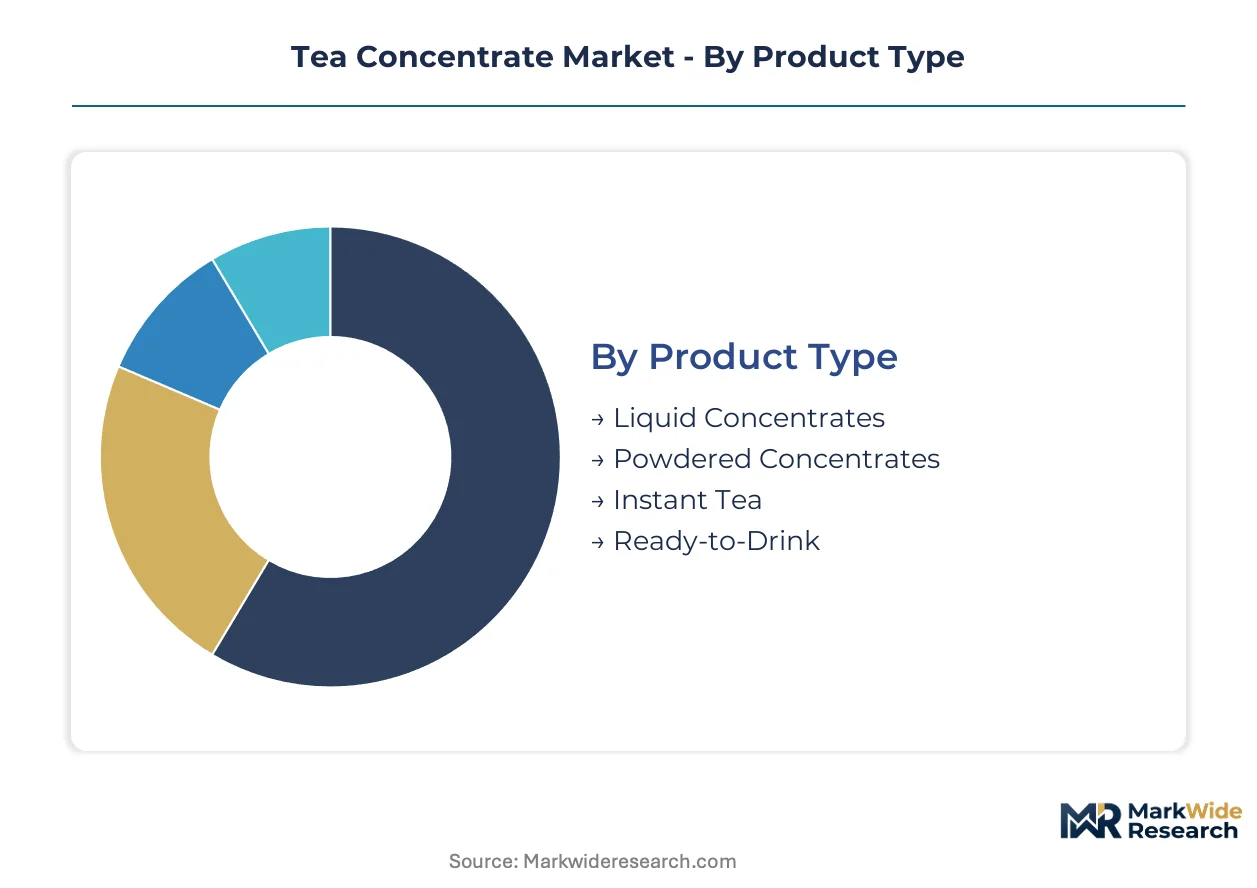
Tea concentrate procurement patterns diverge sharply between food service operators optimizing labor costs and retail consumers prioritizing shelf stability. Format selection—liquid versus powdered—directly constrains which distribution channels and end-use applications remain economically viable for suppliers.
Product Type:
Upgrade cycles in extraction equipment are pushing processors toward hybrid membrane systems that blur traditional format boundaries between artisanal and industrial outputs.
- Liquid Concentrates:Reduced-volume preparations with solids content between 20% and 65%, typically deployed through fountain dispensing systems. Food service chains in the United States negotiate captive supply agreements specifying extraction method and custom flavor profiles, locking in volume commitments against price volatility.
- Powdered Concentrates:Spray-dried or freeze-dried formats yielding extended ambient shelf life without cold-chain dependency. Emerging markets with uneven refrigeration reliability drive procurement here, particularly for private-label retail formulations.
- Instant Tea:Pre-sweetened and pre-flavored powders designed for single-serve reconstitution. Convenience-oriented consumers in Japan favor these for home and workplace consumption.
- Ready-to-Drink:Bottled or canned beverages manufactured from concentrate bases. PepsiCo dominates North American convenience channel distribution for these finished products.
Volume placements concentrate in Liquid Concentrates; the faster expansion belongs to Powdered Concentrates.
Feature:
Certification costs stratify supplier bases, with dual USDA Organic and EU organic compliance requiring parallel audit trails that strain quality assurance bandwidth.
- Organic:Certified sourcing from estates meeting Japan's Ministry of Health, Labour and Welfare pesticide residue limits. Specialty store channels in Germany with Bio-Siegel requirements accelerate positioning here.
- Non-GMO:Verification through supply chain documentation excluding genetically modified inputs. Beverage manufacturers seeking clean-label positioning drive specification.
- Low Calorie:Unsweetened or reduced-sugar formulations. Municipal sugar taxation in US states incentivizes restaurant procurement as cost-avoidance strategy.
- Caffeinated:Standard formulations retaining natural tea alkaloid content. Supermarkets and online retail generate majority of revenue here despite decaffeinated alternatives.
Revenue concentration sits with Caffeinated variants; Organic certification commands the steepest expansion trajectory.
Distribution Channel:
Direct procurement relationships between restaurant chains and concentrate processors are displacing traditional distributor intermediaries in North American food service.
- Online Retail:Direct-to-consumer platforms enabling subscription and bulk purchasing. Consumers seeking heritage-provenance concentrates from Indian estates favor this channel.
- Supermarkets:Mass-market retail with private-label and branded concentrate placement. Volume leadership concentrates here for standard caffeinated formulations.
- Specialty Stores:Curated retail emphasizing organic certification and single-origin sourcing. German Bio-Siegel compliance creates white space for premium positioning.
- Food Service:Fountain dispensing systems and back-of-house reconstitution for restaurants. Labor efficiency mandates in quick-service chains pull liquid concentrate volumes.
Supermarkets anchor volume; Food Service channels are climbing the fastest as operator consolidation accelerates.
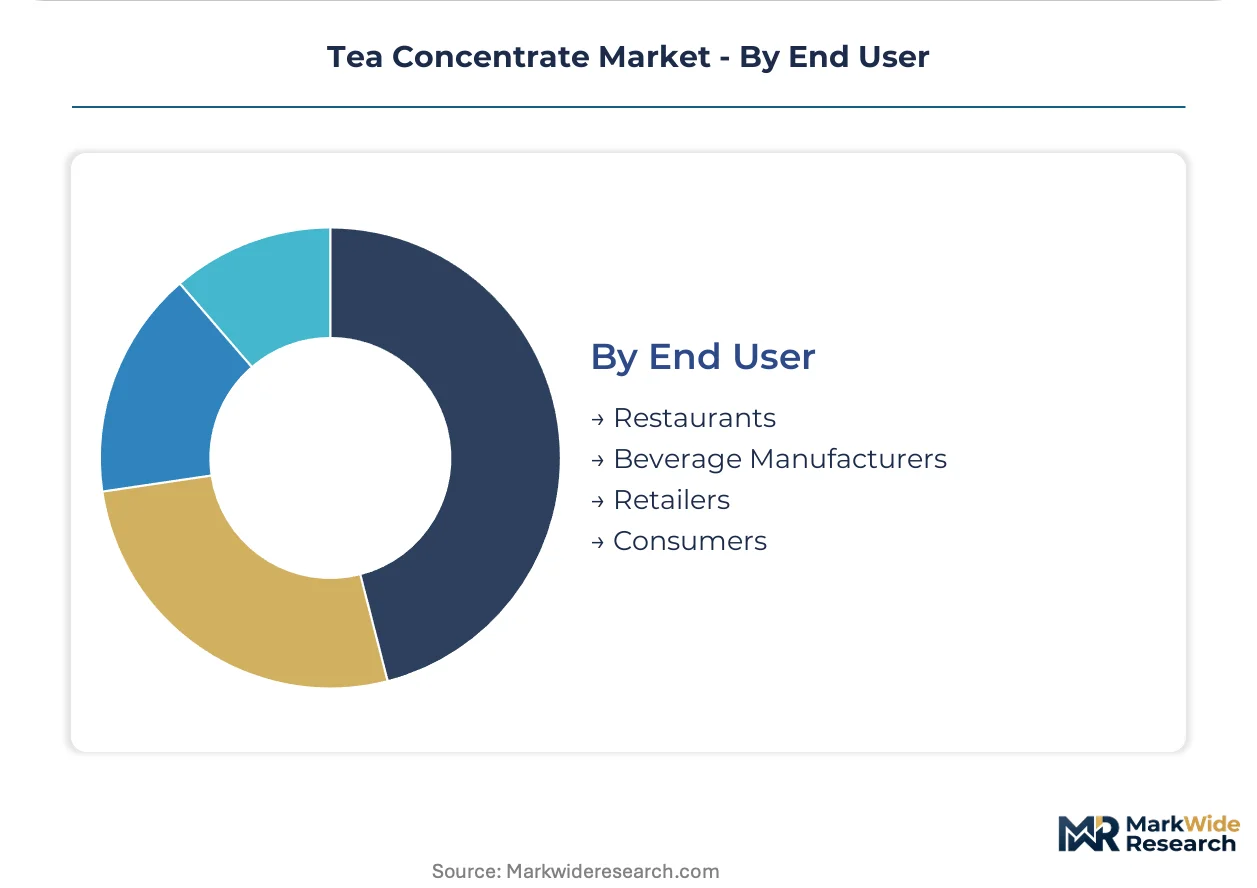
End User:
Application requirements fragment between batch consistency mandates for manufacturers and flavor customization demands from restaurant chains.
- Restaurants:Fountain beverage infrastructure and back-of-house reconstitution systems. Regional beverage management groups in the United States consolidate purchasing authority across multi-brand portfolios.
- Beverage Manufacturers:Industrial-scale concentrate procurement for finished product lines. Batch consistency and shelf stability specifications dominate procurement criteria.
- Retailers:Private-label formulation and branded concentrate stocking. Supermarkets and specialty stores drive differentiated positioning requirements.
- Consumers:Direct purchase for home reconstitution. Convenience orientation and provenance interest shape format selection between liquid and powdered options.
Beverage Manufacturers lock in the largest volume commitments; Restaurants are gaining share fastest through captive supply restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan Port anchors concentrate import volumes into China, channeling spray-dried powders from Indian estates through bonded warehousing facilities before redistribution to beverage manufacturers across the Yangtze River Delta.
United States
Fountain beverage infrastructure upgrades in quick-service restaurants drive liquid concentrate procurement from regional processors. FDA labeling requirements for caffeine content disclosure shape formulation decisions by concentrate suppliers. Georgia's Atlanta metro corridor hosts captive supply negotiations between beverage management groups and concentrate processors serving multi-brand restaurant portfolios.
Germany
Bio-Siegel certification requirements in specialty retail channels accelerate organic concentrate sourcing from Darjeeling and Assam estates. EFSA novel food approval pathways constrain innovation timelines for botanical extract diversification. Hamburg's port logistics cluster handles bulk concentrate shipments for redistribution to European beverage manufacturers.
Japan
Green tea concentrate applications dominate food service and retail channels, with unsweetened variants preferred for workplace consumption. Ministry of Health, Labour and Welfare pesticide residue limits enforce certified organic sourcing investments by concentrate exporters. Shizuoka Prefecture's tea processing corridor maintains technical leadership through proprietary extraction patent portfolios.
India
Heritage-provenance positioning leverages estate sourcing from Assam and Darjeeling for export markets demanding traceability credentials. FSSAI food safety standards govern concentrate manufacturing facility licensing and hygiene protocols. Kolkata's auction houses and processing infrastructure cluster remains central to price discovery and bulk concentrate production for international buyers.
United Kingdom
Premium tea culture sustains demand for cold-brew concentrates in specialty coffee chains and independent cafés. Sugar taxation frameworks at municipal levels incentivize unsweetened concentrate formulations. London's food service procurement networks consolidate purchasing authority across regional restaurant groups seeking custom flavor profiles.
Tea Concentrate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction technology tiers, with membrane filtration specialists commanding pricing power over spray-dried commodity suppliers. The vendor base stratifies between multinational beverage conglomerates with captive bottling networks and mid-scale regional processors serving food service contracts. Three archetypes dominate: heritage-provenance specialists competing on estate sourcing credentials, technology-led processors extracting value through cold-concentration patents, and scale-driven commodity suppliers optimizing spray-drying economics. Consolidation pressures concentrate among food service channel intermediaries, while capacity expansion concentrates in hybrid membrane-evaporation retrofit facilities.
Among multinational beverage conglomerates, PepsiCo, Inc. and Nestlé S.A. occupy positions defined by distribution infrastructure scale rather than extraction technology ownership. Tata Consumer Products Limited represents the heritage-provenance archetype, with its corporate name signaling Indian estate sourcing advantages. ITO EN, Ltd. exemplifies technology-led positioning through its geographic concentration in Japan's green tea processing corridor. These three anchors illustrate how competitive differentiation fragments across sourcing credibility, processing technology, and channel control rather than converging on a single dimension.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Tata Consumer Products Limited |
| Unilever PLC |
| Nestlé S.A. |
| A. Holliday & Company Inc. |
| H&H Products Company |
| Cooper Tea Company LLC |
| Maya Tea Company |
| ITO EN, Ltd. |
| Others |
Value Network & Pricing Analysis
Captive supply agreements between restaurant chains and concentrate processors anchor both procurement stability and pricing power in food service channels. This integration pattern insulates volume commitments from auction volatility while compressing margins for distributors displaced from the value chain.
Pricing Analysis
Throughput-based pricing anchors liquid concentrate contracts in fountain beverage infrastructure, with extraction method and solids content specifications driving differentiation between membrane-filtered specialty grades and spray-dried commodity tiers. Price differentiation hinges on organic certification grade and captive supply volume scale. Cost compression in powdered formats is intensifying because cold-chain infrastructure gaps in emerging markets favor ambient-stable alternatives. Quick-service restaurant chains exhibit the lowest price sensitivity due to labor-cost avoidance priorities, while private-label retailers face acute pressure from input cost pass-through.
Supply Chain Analysis
Single-source vulnerability sits with Assam and Darjeeling estate clusters for premium-grade leaf inputs. Raw material procurement draws from Indian auction houses, Kenyan exchanges, and Shizuoka Prefecture processing corridors. Supply chain risk centers on climate-induced yield shocks in geographically concentrated growing regions. Distribution runs through bonded warehousing at Shanghai's Yangshan Port for Asian markets, with Hamburg's logistics cluster serving European beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over estate sourcing to lock in provenance credentials and margin capture.
For Market Incumbents: Anchor market position through proprietary extraction patent portfolios and captive bottling network expansion. Cold-brew coffee concentrate substitution threatens reconstituted format volumes. Backward integration into certified organic estate sourcing in Assam and Darjeeling defends premium-tier pricing power against commodity-grade competitors. For New Entrants and Emerging Players: Food service dispensing system manufacturers represent the most accessible channel partner type for market entry. White space concentrates in German specialty retail channels demanding Bio-Siegel compliance and in carbonated tea hybrid applications for fountain infrastructure. A membrane filtration technology licensing play offers the clearest go-to-market angle against established spray-dried commodity suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational beverage conglomerates seeking provenance credentials or extraction technology assets. Long-term viability favors processors with hybrid membrane-evaporation retrofit capacity and dual USDA-EU organic certification capabilities. The signal to watch is municipal sugar taxation expansion accelerating unsweetened concentrate procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Supply Agreement | Locks volume commitments against Indian auction price volatility for restaurant chains. |
| Membrane System Retrofit | Enables specialty-grade output at industrial scale for mid-scale processors. |
| Dual Organic Certification | Opens German Bio-Siegel and US specialty retail channels simultaneously. |
| Cold-Chain Infrastructure Partnership | Extends liquid concentrate viability into emerging markets with refrigeration gaps. |
| Proprietary Extraction Patent | Creates defensible moat in green tea concentrate applications for Japanese processors. |
Research Methodology
Multi-period observation of extraction technology adoption rates and food service procurement contract structures anchored the trend analysis, supplemented by interviews with concentrate processing plant managers, quick-service restaurant beverage procurement leads, organic certification auditors, and Indian estate operations directors. Secondary validation drew from FDA labeling guidance documents, EFSA novel food approval registers, Japan's Ministry of Health pesticide residue limit publications, and FSSAI facility licensing records. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Segment-weighting across product type, certification feature, and distribution channel dimensions shaped the analytical framework over the projection horizon. Solids content tiers, extraction method categories, and end-use application splits structured the segmentation model. CAGRs were derived from slope analysis of technology diffusion curves and channel shift trajectories. Forecast inputs incorporated cold-chain infrastructure development indices and sugar taxation policy adoption patterns across US states.
Caveats apply where EFSA regulatory timeline extensions or climate-induced yield shocks in Assam and Darjeeling could materially shift the outlook. Forecasts reflect documented assumptions about membrane filtration cost reduction trajectories and food service operator consolidation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
APAC RTD Tea Market
Tea
US Ready to Drink Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Global Tea Bag Market
Tea
US RTD Organic Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Fermented Tea Market
Tea
White Tea Market
Tea
Smart Tea Set Market
Tea
High Protein Tea Market
Tea
Bottled Milk Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Edible Tea Market
Tea
White Tea Extract Market