
 North America Tea Market | 2026-2036
North America Tea Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tea Market Analytics
Specialty cafes and wellness-oriented foodservice operators are unwinding decades of coffee-centric beverage programs, redirecting menu development budgets toward curated tea collections. Unilever PLC anchors its North American position through deep grocery channel control and established household brand recognition. Tata Consumer Products competes via premium sourcing narratives and direct-to-consumer subscription models. R.C. Bigelow, Inc. sustains family-owned manufacturing scale in Connecticut, leveraging domestic production for rapid flavor innovation cycles.
North America tea comprises processed Camellia sinensis leaves and botanical infusions, typically packaged at moisture levels below 6 percent to prevent mold and preserve volatile aromatic compounds, then distributed for hot or cold consumption across retail and foodservice channels. Black tea occupies the largest volume share due to its entrenched position in conventional grocery and quick-service restaurant iced tea programs, though green tea and herbal tea segments capture disproportionate margin pools through health-positioned premium pricing. Loose leaf and cold brew brewing methods are expanding fastest among health-conscious and young adult consumer types, while bagged tea dominates absolute unit sales through supermarket and online retail distribution channels.
The FDA governs tea product labeling, safety, and health claim substantiation, while the USDA administers organic certification standards that shape premium positioning and price architecture across the category. State-level sugar tax proposals in California and New York are forcing reformulation toward unsweetened and naturally flavored variants. Stakeholders must monitor evolving FDA guidance on bioactive compound labeling and anticipate which brewing format investments align with shifting channel preferences between direct sales and specialty retail.
Market Dynamics
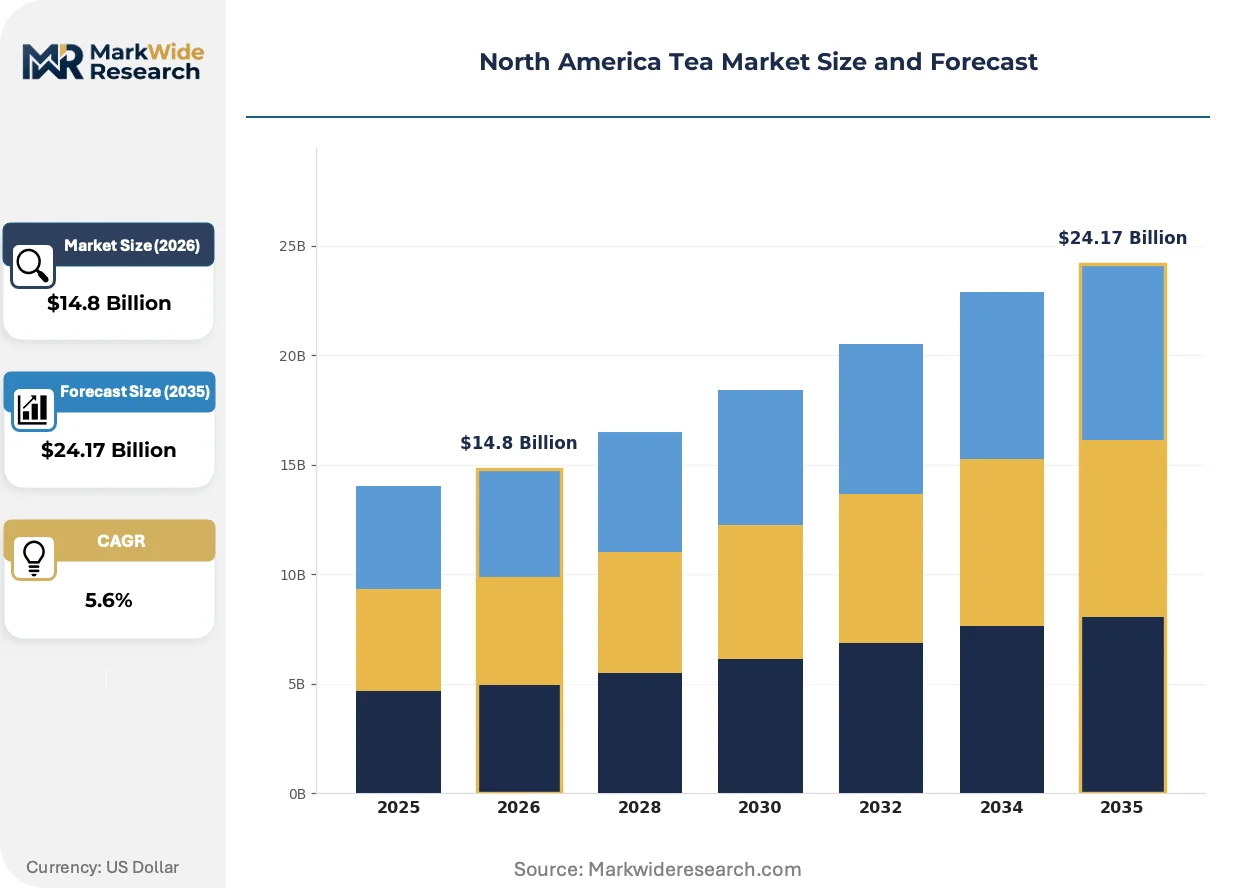
Specialty cafes and wellness-oriented foodservice operators are unwinding decades of coffee-centric beverage programs, redirecting menu development budgets toward curated tea collections that command premium price points and repeat visitation patterns.
Growth Catalysts
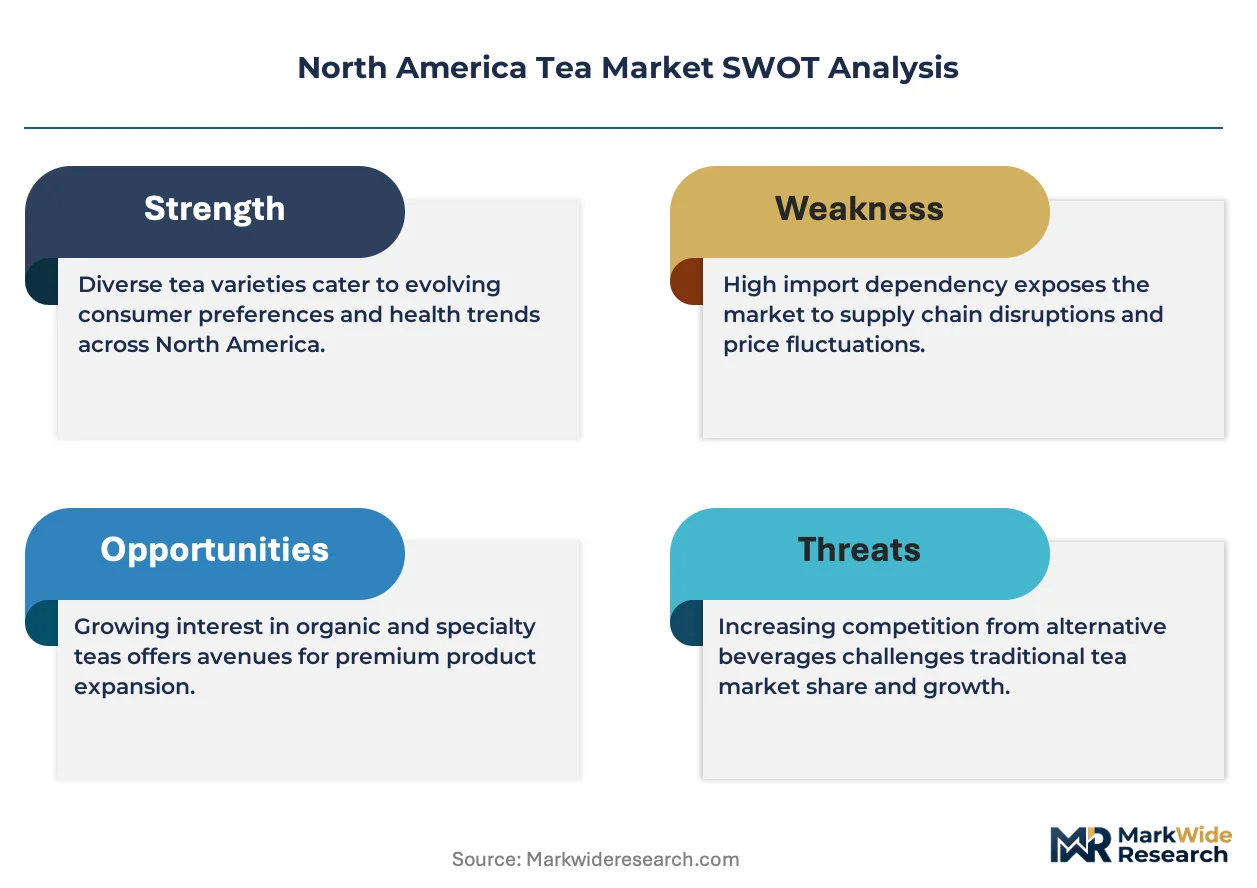
- California sugar tax momentum:Proposed state-level levies on sweetened beverages are accelerating reformulation toward unsweetened and naturally flavored tea variants that align with clean-label positioning.
- Cold brew brewing methods:Extended steeping protocols at refrigerated temperatures are capturing young adult consumers seeking smoother flavor profiles and reduced astringency in ready-to-drink formats.
- Pacific Northwest consumption clusters:Metropolitan corridors in Oregon and Washington demonstrate disproportionate per-capita spending on functional and premium tea categories, validating targeted distribution investments.
Market Restraints
- Camellia sinensis supply concentration:Raw leaf sourcing depends on limited origin regions outside North America, exposing processors to climate volatility and currency fluctuation risks.
- FDA health claim substantiation:Stringent evidentiary requirements for bioactive compound labeling constrain marketing narratives around functional benefits and limit premium pricing justification.
- Energy drink substitution:Caffeinated alternatives with aggressive flavor engineering and lower per-unit costs capture convenience-store and gas-station channel placement that tea struggles to secure.
Strategic Opportunities
- USDA organic certification tailwinds:Federal organic standards create price architecture separation that rewards processors investing in certified supply chain traceability and third-party verification.
- Direct-to-consumer subscription models:Curated delivery services bypass conventional grocery slotting fees while building recurring revenue and first-party consumer data assets.
- Functional botanical convergence:Adaptogenic and nootropic ingredient integration opens positioning beyond traditional caffeine delivery toward stress-management and cognitive performance applications.
Industry Challenges
- Flavor innovation cycle compression:Family-owned manufacturers with domestic production assets face compressed development timelines as larger competitors accelerate seasonal limited-edition releases.
- Moisture control compliance:Maintaining sub-6 percent packaging standards requires capital-intensive humidity monitoring systems and specialized sealing equipment across distributed production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tea Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Oolong Tea Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Consumer Type: Health Conscious, Casual Drinkers, Premium Buyers, Young Adults Brewing Method: Loose Leaf, Bagged Tea, Cold Brew, Instant Tea |
| Companies Covered | Unilever PLC, Tata Consumer Products, Keurig Dr Pepper Inc., R.C. Bigelow, Inc., Starbucks Corp., Nestlé SA, Hain Celestial Group Inc., Arizona Beverages USA, PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tea Market Evolving Landscape
Brewing format preferences and regulatory disclosure requirements are restructuring competitive advantage away from scale economies toward speed-to-market and formulation transparency.
Extended cold steeping protocols are supplanting traditional hot-brew extraction methods in foodservice and ready-to-drink manufacturing. Young adult consumers and health-conscious segments are adopting these techniques at accelerating rates, drawn to reduced tannin bitterness and enhanced aromatic preservation. This shift is compressing demand for conventional tea bag formats while expanding equipment and ingredient supplier opportunities in the cold brew ecosystem.
The FDA's updated nutrition labeling requirements are forcing reformulation of sweetened tea portfolios across conventional grocery and quick-service restaurant channels. Industrial consequence includes accelerated R&D spending on natural flavor masking technologies and zero-calorie sweetener blends. Unsweetened variants and single-origin positioning are capturing disproportionate shelf space expansion in California metropolitan markets where disclosure scrutiny runs highest.
Specialty retail and foodservice buyers are consolidating procurement authority into centralized beverage category managers with technical sourcing expertise. This concentration is displacing fragmented local purchasing decisions and demanding supplier investment in food safety documentation, traceability systems, and flexible minimum order quantities. The Pacific Northwest and California corridors exhibit the most pronounced buyer consolidation, with regional cafe chains adopting corporate-level tea program standardization.
North America Tea Market Segmentation
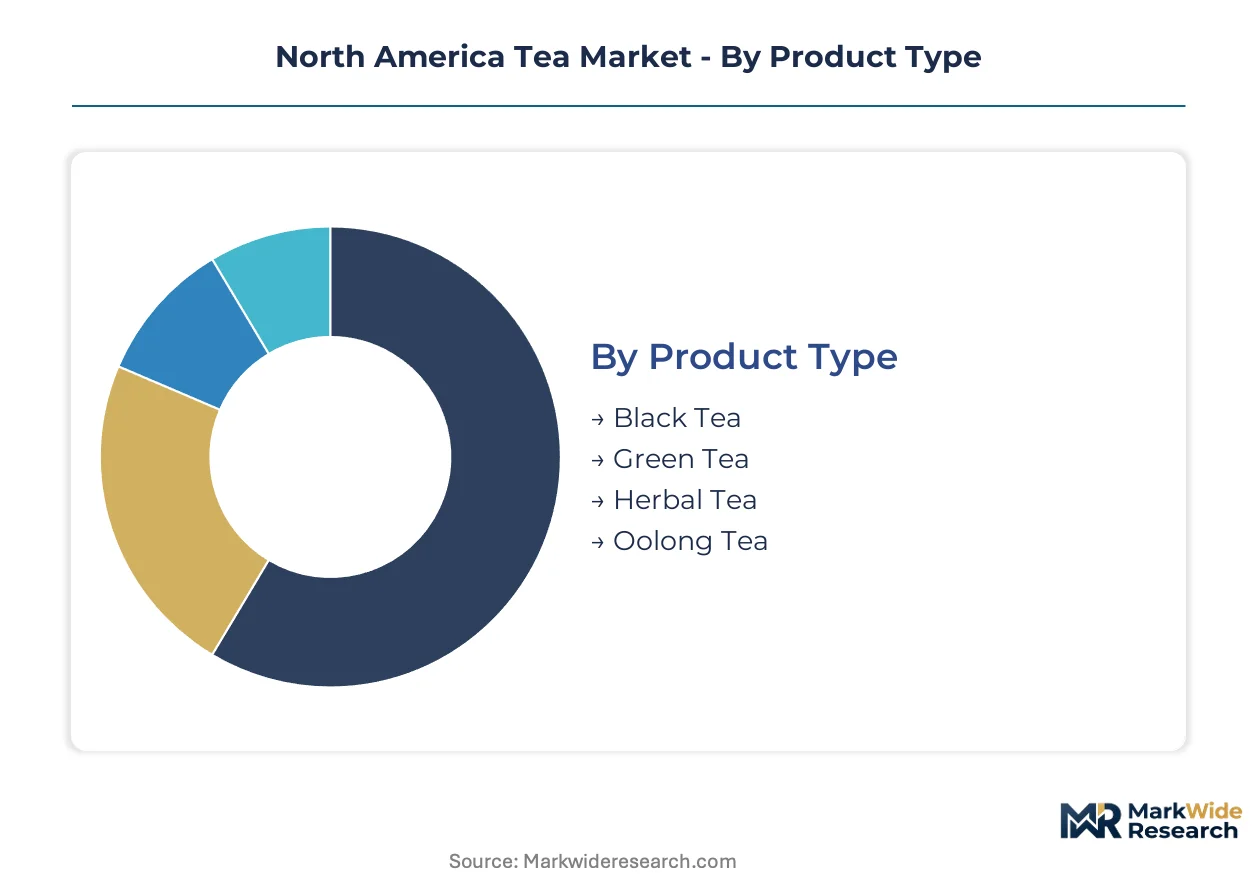
Tea segmentation in North America reflects divergent margin structures across brewing formats and channel strategies. Premium positioning concentrates in direct-to-consumer and specialty retail pathways, while volume scale dominates conventional grocery and foodservice distribution.
Product Type:
Black tea commands the deepest margin pools through entrenched foodservice contracts and conventional grocery placement, though green and herbal variants capture superior unit economics in premium channels.
- Black Tea:Fully oxidized Camellia sinensis leaves deliver standardized caffeine content and shelf-stable flavor profiles. Demand concentrates in quick-service restaurant iced tea programs across Texas and the Southeastern states, where bulk brewing protocols favor consistent extraction and cost efficiency.
- Green Tea:Minimally processed leaves retain catechins and lighter aromatic compounds. California metropolitan corridors and Pacific Northwest wellness retailers drive disproportionate per-capita consumption, propelled by FDA-permitted antioxidant positioning and clean-label formulation trends.
- Herbal Tea:Botanical infusions without Camellia sinensis leverage functional ingredient narratives for premium pricing.
- Oolong Tea:Partially oxidized processing creates flavor complexity targeting connoisseur segments in specialty retail.
The dominant share belongs to Black Tea, while Green Tea is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics, with digital pathways offering superior data capture but requiring fulfillment infrastructure investment.
- Online Retail:Direct-to-consumer platforms bypass slotting fees and enable subscription recurring revenue. Young adult demographics in urban coastal markets demonstrate highest conversion rates for curated discovery models and limited-release sourcing narratives.
- Supermarkets:Mass-market placement demands trade promotion spending and packaging standardization for shelf-ready logistics. Bagged black tea dominates aisle placement through Connecticut-based domestic manufacturing and rapid replenishment cycles.
- Specialty Stores:Curated assortments command premium price architecture through educated staff and experiential merchandising.
- Direct Sales:Foodservice and hospitality contracts require technical specification compliance and volume flexibility.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly.
Consumer Type:
Behavioral segmentation reveals divergent purchasing frequencies and price elasticity profiles across wellness-motivated and occasion-based consumption patterns.
- Health Conscious:Functional benefit seekers prioritize organic certification and bioactive compound transparency. USDA organic seal penetration runs highest among this cohort, validating supply chain traceability investments and third-party verification costs.
- Premium Buyers:Connoisseur segments drive single-origin and limited-harvest sourcing premiums. Metropolitan corridors in California and New York sustain specialty cafe menu development budgets for curated tea collections.
- Casual Drinkers:Occasion-based consumption favors convenience formats and familiar flavor profiles.
- Young Adults:Cold brew adoption and social media discovery patterns concentrate in this demographic.
Health Conscious consumers anchor premium tier revenue, while Young Adults are gaining share fastest.
Brewing Method:
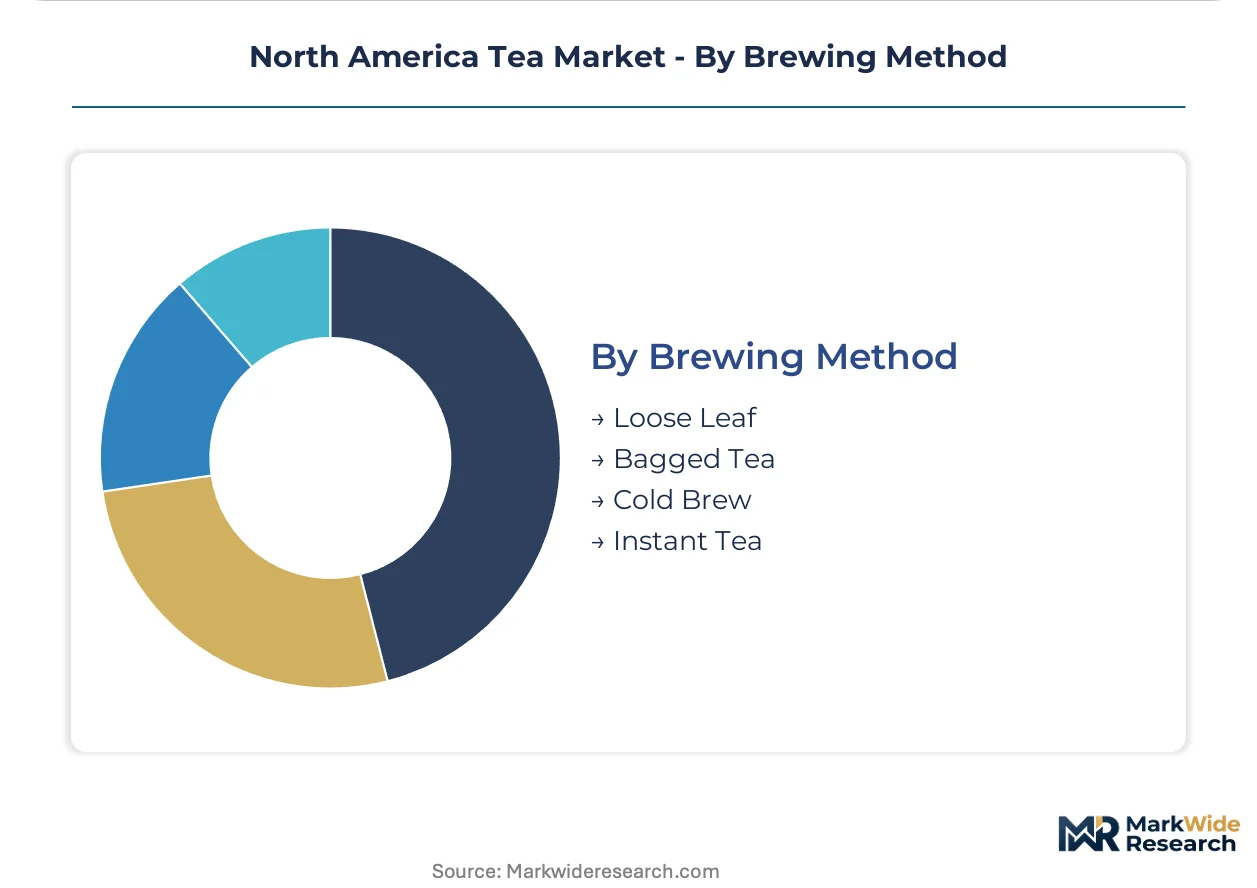
Format selection dictates equipment requirements, packaging moisture control standards, and channel placement feasibility across retail and foodservice environments.
- Cold Brew:Extended refrigerated steeping produces smoother flavor profiles with reduced tannin extraction. Young adult adoption in Pacific Northwest metropolitan markets accelerates foodservice equipment procurement and ready-to-drink manufacturing line investment.
- Loose Leaf:Whole leaf preservation enables multiple infusions and ceremonial preparation rituals. Specialty retailers in Oregon and Washington demonstrate highest per-square-foot sales velocity for premium loose leaf assortments.
- Bagged Tea:Standardized portion control dominates absolute unit sales through supermarket and convenience channels.
- Instant Tea:Soluble powder formats target foodservice efficiency and travel retail applications.
Bagged Tea holds volume dominance, though Cold Brew is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tea leaf shipments from India and China supply the bulk of raw material entering United States and Canadian processing facilities. Cross-border trade flows concentrate in Pacific Coast ports and Great Lakes distribution hubs. Regional consumption patterns diverge sharply between iced tea strongholds in the Southeast and premium hot tea markets in coastal metropolitan corridors.
United States
California metropolitan corridors and the Pacific Northwest drive disproportionate per-capita spending on functional and premium tea categories. FDA nutrition labeling requirements and state-level sugar tax discussions in California and New York are accelerating reformulation toward unsweetened variants. Connecticut-based domestic manufacturing anchors rapid flavor innovation cycles for bagged black tea distributed through conventional grocery channels.
Canada
Health-conscious consumers in Toronto and Vancouver metropolitan areas sustain strong demand for organic-certified and botanical infusion products. Health Canada and the Canadian Food Inspection Agency administer labeling standards that align with premium positioning strategies. British Columbia and Ontario retail channels demonstrate highest velocity for loose leaf and cold brew formats among young adult demographics.
Mexico
Traditional herbal consumption patterns in central and southern states create foundation demand for botanical infusions and regional ingredient sourcing. COFEPRIS regulatory oversight shapes import documentation requirements for processed tea entering through Veracruz and Manzanillo ports. Mexico City metropolitan area exhibits emerging specialty cafe development with curated tea menu expansion alongside established coffee culture.
North America Tea Market Competitive Landscape
Listed leaders compete with private specialists across grocery channel control and direct-to-consumer subscription capabilities. The market structure exhibits tiered consolidation with multinational conglomerates commanding mass-market shelf space while family-owned manufacturers and specialty operators capture premium margin pools. Three archetypes dominate: grocery channel anchors with deep distribution infrastructure, wellness-positioned specialists with organic certification narratives, and foodservice integrators with cafe and hospitality contract expertise. Dominant competitive moves include portfolio diversification into functional botanical blends and strategic partnerships with specialty retail buyers.
Within the grocery channel anchor tier, Unilever PLC and Keurig Dr Pepper Inc. occupy positions representing scale-driven mass-market penetration. Tata Consumer Products exemplifies the wellness-positioned specialist archetype through premium sourcing narratives. R.C. Bigelow, Inc. anchors the family-owned manufacturing segment with Connecticut-based production assets enabling rapid innovation cycles.
| Leading Market Players |
|---|
| Unilever PLC |
| Tata Consumer Products |
| Keurig Dr Pepper Inc. |
| R.C. Bigelow, Inc. |
| Starbucks Corp. |
| Nestlé SA |
| Hain Celestial Group Inc. |
| Arizona Beverages USA |
| PepsiCo, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Indian and Chinese leaf suppliers and North American processors lock in both supply access and price visibility, insulating buyers from spot market volatility while constraining flexibility to pivot toward emerging origin regions. These arrangements concentrate pricing power upstream with estate-level producers, forcing downstream brands to compete on formulation innovation rather than procurement arbitrage.
Pricing Analysis
Cold brew versus conventional hot-extract versus instant-soluble technology-generation pricing gaps are widening as equipment-intensive formats command premium shelf placement in California and Pacific Northwest retail channels. Three-tier pricing structure across premium loose leaf, standard bagged, and economy instant formats stratifies around USDA organic certification and single-origin traceability claims. Pricing pressure stems from state-level sugar tax proposals accelerating reformulation costs toward unsweetened variants. Casual drinkers in conventional grocery channels exhibit highest price sensitivity, while premium buyers in specialty retail demonstrate inelastic demand for limited-harvest sourcing narratives.
Supply Chain Analysis
Inbound logistics costs through Pacific Coast ports and Great Lakes distribution hubs fluctuate with container availability on Asia-North America trade lanes, compressing margins for just-in-time leaf importers. Raw material sourcing draws from India, China, and Kenya for Camellia sinensis leaf, with botanical infusions resting on Egyptian chamomile, South African rooibos, and Argentinian yerba mate dependencies. Single-source vulnerability concentrates in Assam and Yunnan origin regions exposed to climate volatility. Distribution runs through Connecticut-based domestic manufacturing for rapid replenishment cycles in conventional grocery, while direct-to-consumer subscriptions bypass wholesale markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as direct-to-consumer subscription infrastructure creates interoperability between discovery algorithms and recurring revenue capture, elevating first-party data assets above traditional brand equity.
For Market Incumbents: Fortify grocery channel control through exclusive retail partnerships and rapid seasonal limited-edition release cycles that exploit domestic production scale advantages. Energy drink substitution threats in convenience-store channels demand investment in ready-to-drink cold brew capacity with lower per-unit cost structures. Backward integration into certified organic estate partnerships secures supply traceability for premium tier positioning. For New Entrants and Emerging Players: USDA organic certification fast-track programs in India and Kenya enable rapid premium positioning without legacy slotting fee burdens. Underpenetrated cold brew equipment and ingredient supplier ecosystems in Pacific Northwest metropolitan corridors offer white-space entry points. Curated discovery models targeting young adult demographics in urban coastal markets bypass incumbent brand recognition barriers through social media-native go-to-market architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with proprietary sourcing narratives and first-party data infrastructure. Long-term viability across the analysis window favors acquisition targets with certified supply chain traceability and flexible minimum order quantity capabilities serving consolidating foodservice procurement authority. Cold brew format adoption velocity in Pacific Northwest metropolitan markets signals inflection timing for manufacturing equipment plays.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses grocery slotting fees while capturing recurring revenue and first-party consumer data assets in California metropolitan corridors. |
| USDA Organic Certification Investment | Creates price architecture separation that rewards processors investing in certified supply chain traceability and third-party verification. |
| Cold Brew Manufacturing Scale-Up | Captures young adult consumer adoption in Pacific Northwest markets seeking smoother flavor profiles and reduced astringency. |
| Functional Botanical Integration | Opens positioning beyond traditional caffeine delivery toward stress-management applications with adaptogenic ingredient sourcing. |
| Foodservice Contract Consolidation | Aligns with centralized beverage category manager procurement authority demanding traceability systems and flexible minimum order quantities. |
Research Methodology
Desk research of customs trade databases, FDA labeling guidance documents, and USDA organic certification records preceded structured interviews with tea procurement directors at specialty cafe chains, category buyers at conventional grocery retailers, flavor innovation leads at domestic manufacturers, and logistics coordinators at Pacific Coast import facilities. Primary fieldwork combined with secondary validation across Nielsen retail audit data and FERC trade flow records enabled bottom-up volume triangulation against top-down category expenditure estimates.
Variance decomposition across product type, distribution channel, consumer behavior segment, and brewing method dimensions structured the analytical framework over the projection horizon. CAGRs were derived from modeled unit velocity trajectories in tracked retail channels and foodservice volume commitments, with cold brew format adoption curves and sugar tax reformulation timelines serving as industry-specific forecast inputs.
Underlying assumptions cover stable FDA bioactive compound labeling guidance and continued Pacific Coast port throughput capacity, with deviation risk concentrated in climate-induced leaf harvest volatility and currency fluctuation exposure in Indian rupee and Chinese yuan-denominated supply contracts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Probiotic Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
US Ready to Drink Tea Market
Tea
Smart Tea Maker Market
Tea
Herbal Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Fermented Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Moringa Tea Market
Tea
China Tea Market
Tea
Edible Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Bottled Milk Tea Market
Tea
Nitro Tea Market
Tea
Global Tea Market
Tea
Green Tea Leaves Market