
 Moringa Tea Market | 2026-2036
Moringa Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Moringa Tea Market Analysis
Organic certification tier is reorganizing competitive dynamics in moringa tea as buyers demand verifiable supply chain documentation. Organic India leverages its vertically controlled farming cooperatives in Rajasthan to sustain premium positioning. Grenera Nutrients anchors South Indian processing capacity with ISO-certified extraction facilities. Kuli Kuli differentiates through direct-trade relationships with West African cultivators, occupying a transparency-focused niche in North American distribution.
Moringa tea comprises dried and processed leaves of Moringa oleifera, a drought-resistant tree native to the Indian subcontinent, typically standardized to retain glucosinolate and isothiocyanate compounds through low-temperature dehydration. The beverage serves functional wellness applications where consumers seek plant-derived antioxidants and mineral fortification without caffeine content. Loose leaf formats dominate margin pools through specialty health store channels, while instant tea concentrates represent the fastest-growing segment among time-constrained urban professionals. Tea bag configurations remain mature in conventional retail, though sachet packaging innovations are gaining traction in hospitality and corporate food service procurement.
India's FSSAI mandates nutritional labeling and pesticide residue limits for herbal products, while the U.S. FDA exercises oversight through dietary supplement Current Good Manufacturing Practice regulations. The EU EFSA novel food authorization pathway shapes market access for new moringa-derived formats entering European commerce. Stakeholders must monitor evolving organic certification reciprocity agreements between major producing and consuming jurisdictions to anticipate supply chain reconfiguration requirements.
Market Dynamics
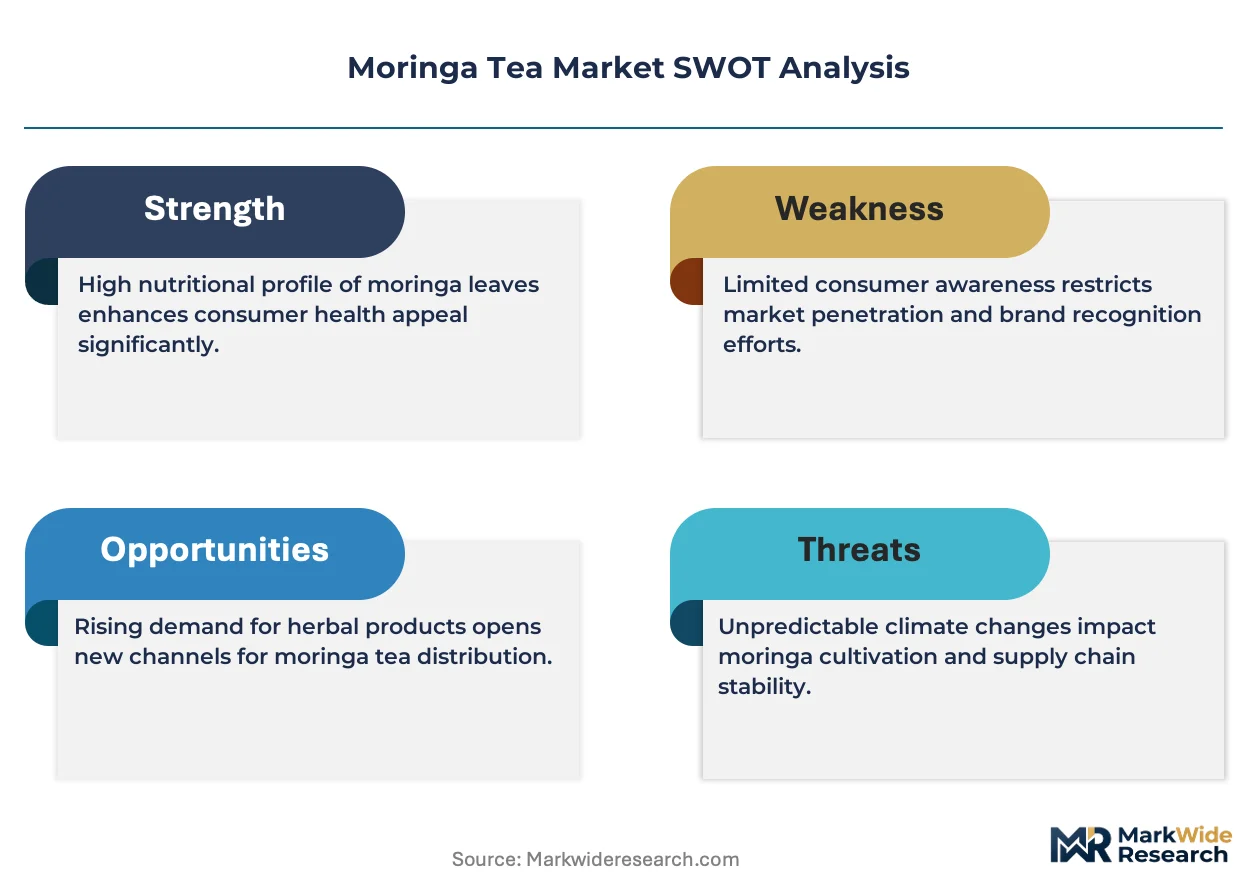
Organic certification requirements are fragmenting competitive positioning in moringa tea as buyers demand batch-level traceability from farm to finished product, forcing processors to restructure supplier relationships and documentation systems.
Growth Catalysts
- FSSAI Nutritional Labeling Mandate:India's enforcement of standardized nutritional declarations for herbal products is elevating consumer trust in packaged moringa tea formats across domestic retail channels.
- West African Cultivation Expansion:Emerging leaf supply from Senegal and Ghana is diversifying raw material origins beyond Indian subcontinent dependence, reducing monsoon-driven harvest volatility.
- Low-Temperature Dehydration:Adoption of sub-40°C drying protocols preserves glucosinolate bioactivity, enabling functional positioning in premium wellness segments that command price premiums over conventional herbal alternatives.
Market Restraints
- EU Novel Food Authorization Friction:EFSA's prolonged safety assessment timelines for new moringa-derived formats delay European market entry by 18-36 months, concentrating revenue in less regulated jurisdictions.
- Maharashtra-Tamil Nadu Supply Concentration:Overreliance on two Indian state clusters for raw leaf creates geographic vulnerability to localized drought, pest outbreaks, and logistics disruptions.
- Instant Coffee Substitution:Caffeine-seeking professionals in corporate food service channels default to established soluble coffee brands, compressing trial rates for moringa's caffeine-free positioning.
Strategic Opportunities
- Corporate Wellness Programs:North American employers are integrating functional herbal beverages into subsidized breakroom offerings, creating B2B procurement channels bypassing conventional retail markup structures.
- Sachet Packaging Innovation:Single-serve hospitality formats are penetrating airline and hotel procurement, replacing bulk loose-leaf configurations that require preparation labor.
- USDA Organic Certification Reciprocity:Expanding mutual recognition agreements between Indian NPOP and USDA NOP standards are reducing dual-audit costs for exporters targeting premium American retail tiers.
Industry Challenges
- Phytochemical Standardization Expertise Gap:Analytical chemists capable of validating isothiocyanate and flavonoid consistency across harvest batches remain scarce in processing facilities, creating quality control bottlenecks.
- ISO 22000 Certification Timeline:Food safety management system accreditation requires 12-18 month implementation cycles that delay contract manufacturing relationships with multinational beverage distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moringa Tea Market |
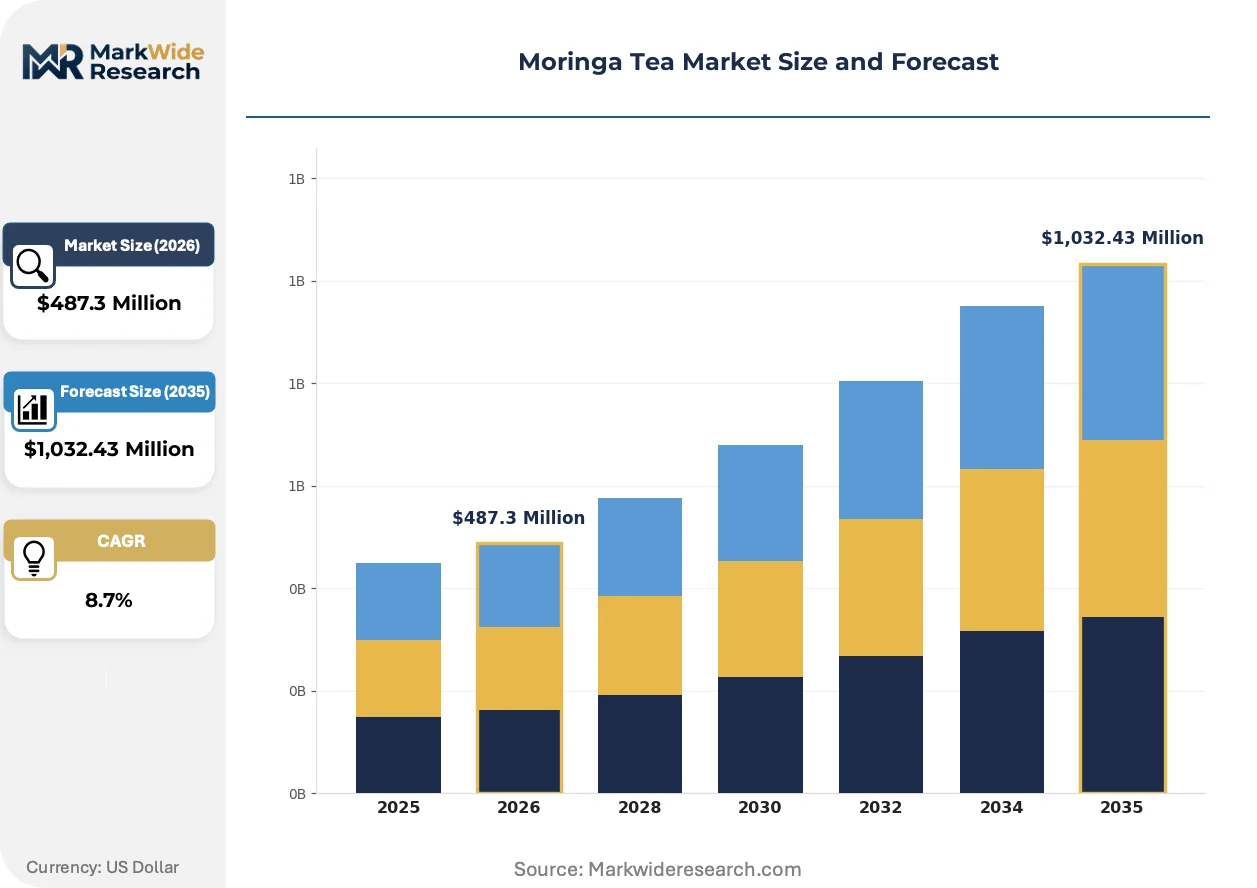
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Instant Tea, Powdered Tea End User: Retail Consumers, Food Service, Health Stores, Online Retailers Flavor: Herbal, Mint, Lemon, Blended Packaging Type: Boxed, Sachets, Bulk, Bottled |
| Companies Covered | Organic India, Aayuritz Phytonutrients, Kuli Kuli, Rainforest Herbs, Moringa Source, Grenera Nutrients, MoringaConnect, Buddha Teas, Rootalive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moringa Tea Market Emerging Trajectories
Processing technology and packaging formats are converging to extend shelf stability while preserving bioactive compounds, reshaping how moringa tea moves from cultivation clusters to consumption occasions.
Cold-milling micronization is displacing conventional hammer-milling in premium processing facilities. Specialty health retailers and direct-to-consumer brands are adopting sub-50 micron particle specifications that accelerate cold-water solubility. This particle size reduction is displacing instant tea concentrates that rely on heat-extraction methods degrading heat-sensitive antioxidants.
REACH-compliant packaging material regulations in the European Union are mandating migration-tested laminates for herbal product contact surfaces. Industrial consequence includes accelerated phase-out of conventional plasticized films in favor of aluminum-polyethylene composites with documented heavy metal thresholds. German and Dutch importers are most affected, requiring suppliers to submit complete additive declarations before customs clearance.
Subscription-based replenishment models are capturing recurring revenue from wellness-focused urban households. Direct-to-consumer channels are replacing intermittent specialty store purchases with algorithm-driven delivery cadences matched to consumption velocity. This pattern is most visible in California and New York metropolitan areas where time-constrained professionals prioritize convenience over retail browsing.
Moringa Tea Market Segmentation
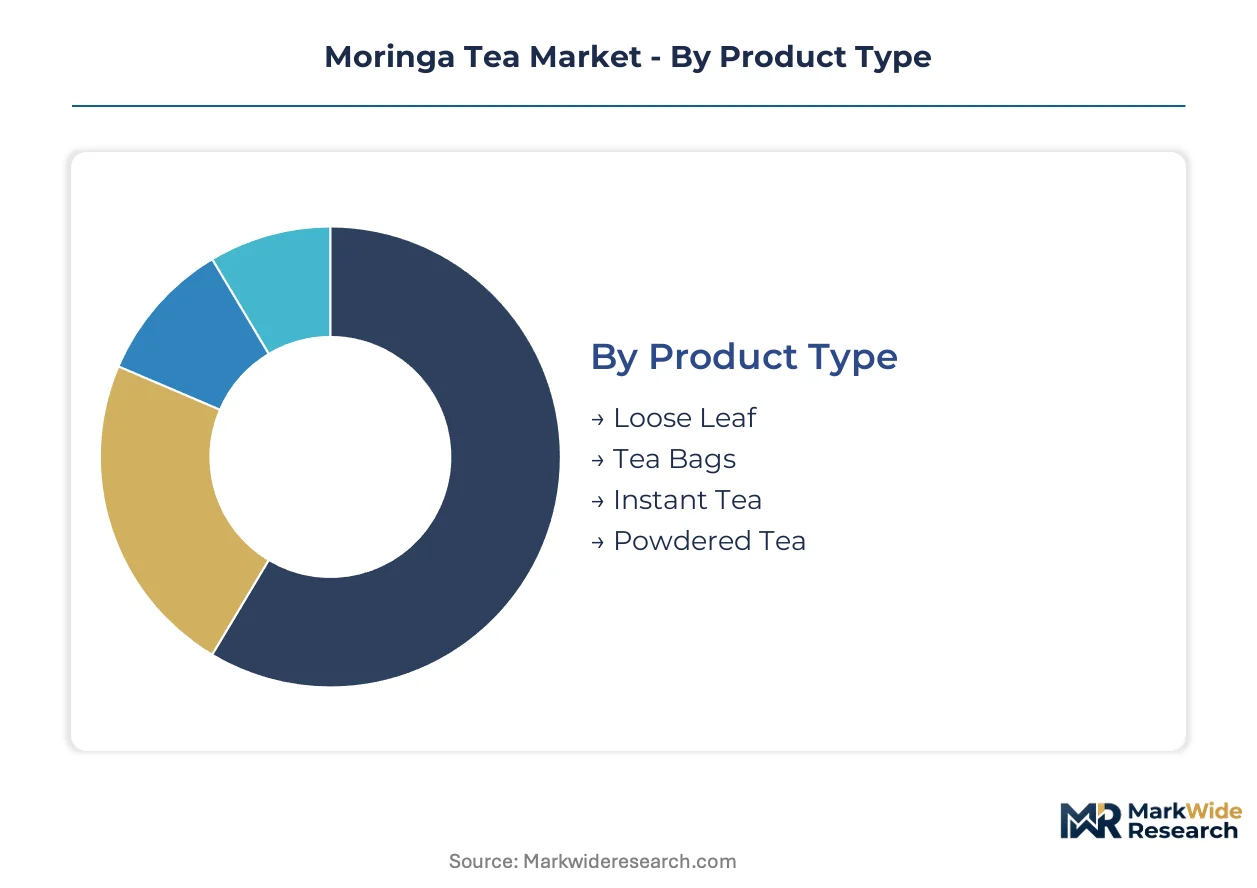
Moringa tea segmentation reveals how processing format, distribution channel, and consumption occasion create distinct margin profiles and regulatory exposure. Each dimension carries specific compliance burdens and buyer expectations that reshape supplier priorities.
Product Type:
USDA NOP and EU organic certification requirements diverge most sharply across processing formats, forcing exporters to maintain parallel documentation systems for loose leaf versus instant concentrates.
- Loose Leaf:Whole dried leaves retain maximum glucosinolate content through sub-40°C dehydration protocols. Specialty health stores in California and New York metropolitan areas concentrate demand here, driven by consumers seeking unprocessed antioxidant retention and ritual preparation experience.
- Instant Tea:Spray-dried or freeze-dried extracts enable cold-water solubility for time-constrained professionals. Corporate food service channels in North American urban centers are expanding procurement of this format, though caffeine-free positioning faces substitution pressure from soluble coffee brands.
- Tea Bags:Heat-sealed filter paper configurations dominate conventional retail shelf presence. FSSAI-mandated nutritional labeling compliance is standardizing declaration formats across Indian domestic packaged goods.
- Powdered Tea:Micronized leaf material below 50 microns accelerates dissolution in smoothies and functional beverages. Direct-to-consumer subscription models are capturing recurring revenue from wellness-focused households seeking versatile ingredient formats.
Loose leaf handles the majority of throughput; instant tea is the fastest mover on share.
End User:
Procurement patterns diverge sharply between price-sensitive institutional buyers and premium-seeking individual consumers, creating three-tier pricing stratification across channels.
- Retail Consumers:Individual purchasers through supermarkets and e-commerce platforms prioritize convenience and certified organic labeling. EU EFSA novel food authorization requirements constrain new product introduction timelines for European market entry.
- Food Service:Airlines, hotels, and corporate cafeterias demand single-serve sachet formats with minimal preparation labor. REACH-compliant packaging mandates in Germany and the Netherlands are accelerating migration to aluminum-polyethylene composite laminates with documented additive declarations.
- Health Stores:Independent specialty retailers command margin premiums through staff-curated assortments and education-heavy selling environments. Cold-milling micronization specifications differentiate premium tier offerings from conventional hammer-milled alternatives.
- Online Retailers:Algorithm-driven replenishment cadences match consumption velocity for subscription-based households. Amazon and direct-to-consumer brand sites are displacing intermittent brick-and-mortar purchases in California and New York metropolitan areas.
Retail consumers generate the highest absolute volume; online retailers are climbing the fastest on revenue contribution.
Flavor:
Flavor innovation expands addressable occasions beyond traditional herbal positioning, though phytochemical stability varies across formulation approaches.
- Herbal:Unflavored moringa leaf delivers pure isothiocyanate and flavonoid profiles for wellness purists. Maharashtra and Tamil Nadu processing clusters supply raw material for this foundational category.
- Mint:Peppermint or spearmint blending masks vegetal bitterness for novice consumers. West African cultivation expansion in Senegal and Ghana is diversifying leaf supply origins for flavored formulations.
- Lemon:Citrus acidification requires careful pH management to preserve bioactive compound stability during shelf life.
- Blended:Multi-herb combinations with tulsi, ashwagandha, or ginger target Ayurveda-informed consumers in Indian domestic and diaspora markets.
Herbal maintains the dominant volume position; blended formats are gaining share fastest among experimentation-oriented buyers.
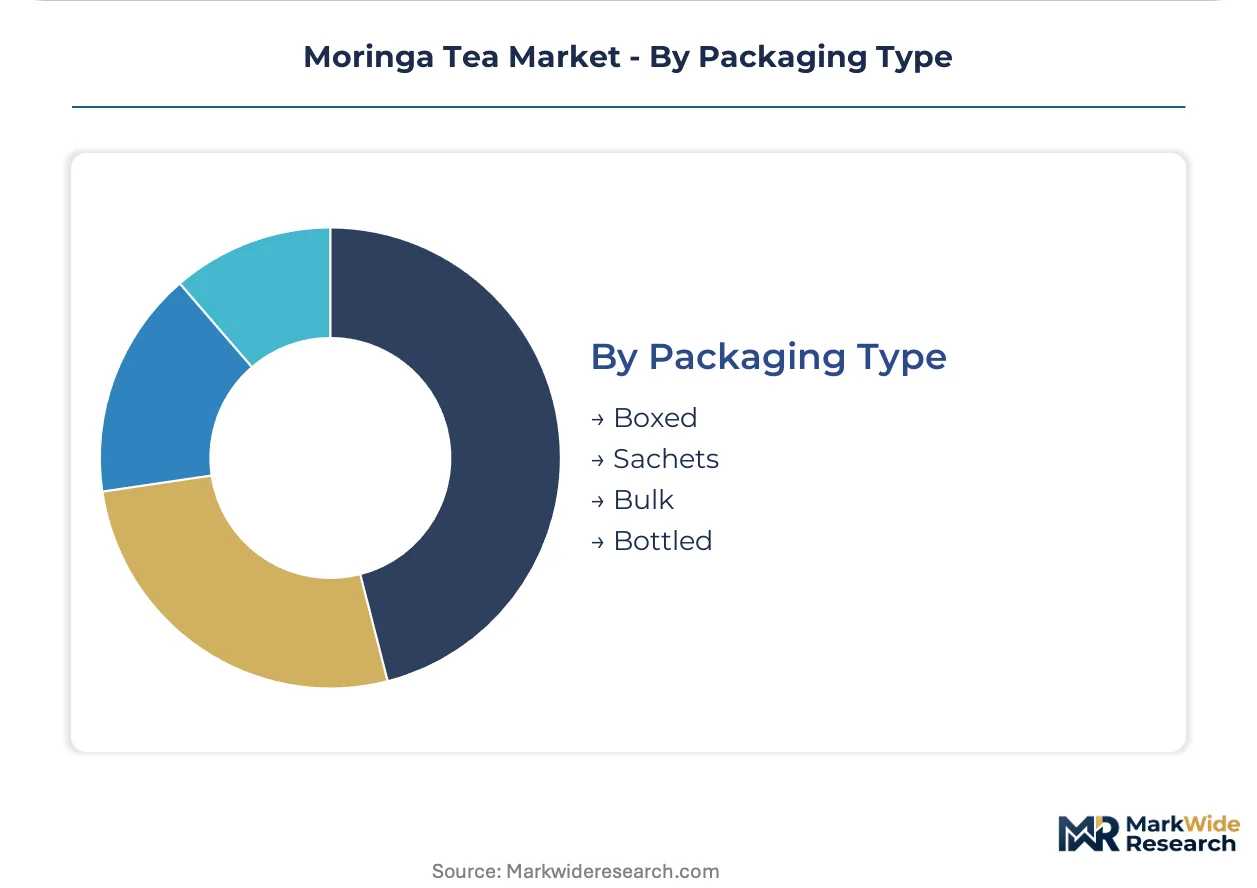
Packaging Type:
Unit economics and logistics efficiency separate bulk commodity movements from premium finished goods, with sustainability credentials increasingly influencing procurement decisions.
- Boxed:Carton-encased retail configurations dominate supermarket shelf presentation. FSSAI nutritional labeling mandates standardize declaration placement across Indian domestic packaged herbal products.
- Sachets:Single-serve pillow packs penetrate hospitality and corporate food service channels requiring portion control and minimal waste. REACH-compliant migration testing is mandatory for EU-bound shipments.
- Bulk:Food service and industrial buyers procure loose material for in-house blending or private label manufacturing. ISO 22000 certification requirements delay contract manufacturing relationships with multinational beverage distributors by 12-18 months.
- Bottled:Ready-to-drink liquid extracts in PET or glass target convenience-seeking urban professionals. EFSA novel food authorization friction concentrates revenue in less regulated jurisdictions for this emerging format.
Boxed configurations carry the bulk of unit volume; sachets are expanding most quickly in hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping procurement geography as Indian processors seek alternative leaf sources while North American buyers diversify supplier bases beyond subcontinent dependence.
United States
Corporate wellness procurement and direct-to-consumer subscription models drive volume in California and New York metropolitan areas. FDA dietary supplement Current Good Manufacturing Practice regulations enforce batch-level documentation for imported herbal products. Los Angeles and San Francisco distribution clusters handle the bulk of West Coast customs clearance for Rajasthan-origin organic certified shipments.
Germany
REACH-compliant packaging mandates and EFSA novel food authorization requirements create dual compliance burdens for moringa-derived beverage entrants. German importers in Hamburg and Frankfurt concentrate procurement of aluminum-polyethylene composite laminates with documented additive declarations. Bavarian specialty retailers command margin premiums through staff-curated functional herbal assortments.
India
FSSAI nutritional labeling mandates and pesticide residue limits standardize domestic packaged herbal product formats. Maharashtra and Tamil Nadu processing clusters anchor raw leaf supply, though Rajasthan farming cooperatives are expanding organic certified cultivation for export-oriented production. Mumbai and Chennai ports handle the majority of containerized shipments to North American and European destinations.
Senegal
West African cultivation expansion diversifies raw material origins beyond Indian subcontinent monsoon dependence. National agricultural extension programs support smallholder cooperatives in leaf drying and preliminary processing. Dakar-based exporters are establishing direct-trade relationships with North American transparency-focused distributors, bypassing traditional Indian processing intermediaries.
United Kingdom
Ayurveda-informed diaspora consumers in London and Birmingham sustain demand for blended moringa-tulsi formulations. Trading standards enforcement mirrors EU novel food guidance, delaying new format introductions pending safety assessment alignment. Heathrow logistics corridors facilitate re-export distribution to continental European markets.
Moringa Tea Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and supply chain control dimensions. The vendor base stratifies between vertically integrated farming cooperatives, ISO-certified processing facilities, and direct-trade sourcing specialists. Three archetypes dominate: organic-certified origin controllers, extraction technology specialists, and transparency-focused niche distributors. Capacity expansion in West African cultivation and cold-milling micronization adoption represent the primary competitive moves reshaping positioning.
Within the organic-certified origin controller tier, Organic India exemplifies vertically integrated cooperative structures, while Grenera Nutrients anchors South Indian processing capacity. Kuli Kuli occupies a transparency-focused niche through West African direct-trade relationships, representing the geographic diversification archetype in North American distribution channels.
| Leading Market Players |
|---|
| Organic India |
| Aayuritz Phytonutrients |
| Kuli Kuli |
| Rainforest Herbs |
| Moringa Source |
| Grenera Nutrients |
| MoringaConnect |
| Buddha Teas |
| Rootalive |
| Others |
Supply Flow & Price Mechanics
Processing scale economies at Maharashtra and Tamil Nadu dehydration facilities create dual pressure on regional price floors and procurement concentration. Large-batch sub-40°C drying protocols reduce per-unit energy costs while locking smaller Rajasthan cooperatives into premium organic tier positioning where FSSAI compliance costs sustain higher entry barriers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across USDA NOP certification tier, volume scale, and cold-milling micronization specification. Three-tier pricing structure across premium, standard, and economy levels separates Rajasthan-origin organic loose leaf from Maharashtra conventional grades and West African supply still awaiting full traceability documentation. Cost compression in instant tea concentrates is intensifying because spray-dried extract capacity expansion outpaces corporate food service procurement velocity. Health stores and direct-to-consumer subscription households exhibit lowest price sensitivity, while airline and hotel procurement teams drive hardest bargain on sachet unit economics.
Supply Chain Analysis
Inventory lead times stretch 8-14 weeks for EU-bound shipments awaiting EFSA additive declaration clearance and REACH-compliant laminate migration testing. Raw material supply concentrates in India, Senegal, and Ghana, with leaf sourcing drawing from smallholder cooperatives, national agricultural extension programs, and vertically integrated Rajasthan farming collectives. Single-source vulnerability persists around Maharashtra-Tamil Nadu processing clusters where monsoon disruption or localized drought can sever bulk supply to North American and European distributors. Distribution runs through Mumbai and Chennai port consolidation for ocean freight, with Los Angeles and Hamburg handling customs clearance and last-mile fragmentation to health store networks and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated North American corporate wellness procurement teams and algorithm-driven subscription platforms, fragmenting traditional health store channel influence and compressing intermediary margin capture.
For Market Incumbents: Consolidate backward integration into West African cultivation through direct-trade cooperative development, insulating against Indian monsoon volatility and capturing transparency-premium positioning before EFSA novel food authorization friction delays competitor entry. Prioritize ISO 22000 certification acceleration to lock multinational beverage distributor contract manufacturing relationships ahead of 12-18 month implementation cycles facing late movers. For New Entrants and Emerging Players: Differentiate on phytochemical standardization expertise by building in-house analytical chemistry capabilities for isothiocyanate batch validation, addressing the quality control bottleneck that incumbent processors struggle to staff. Target Senegal and Ghana leaf supply origins where national agricultural extension programs reduce smallholder onboarding friction, and pursue hospitality sachet procurement channels where REACH-compliant packaging capabilities remain underdeveloped among established Indian exporters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription brands with algorithm-driven replenishment cadences matched to California and New York metropolitan consumption velocity, suggesting superior cash flow quality versus intermittent retail-dependent competitors. Over a five-to-ten year horizon, acquisition targets should emphasize vertically integrated farming cooperatives with dual USDA-NPOP organic certification reciprocity and cold-milling micronization capacity. The signal to watch is EFSA novel food authorization timeline compression for moringa-derived ready-to-drink formats, which would unlock European revenue concentration currently diverted to less regulated jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| West African Cultivation Expansion | Senegal and Ghana cooperatives diversify leaf supply beyond Indian monsoon dependence. |
| Cold-Milling Micronization Adoption | Sub-50 micron specifications accelerate cold-water solubility for premium health store positioning. |
| USDA-NPOP Certification Reciprocity | Dual-audit cost reduction enables Rajasthan-origin organic penetration of American retail tiers. |
| Sachet Packaging Innovation | Single-serve formats penetrate airline and hotel procurement with minimal preparation labor. |
| Direct-to-Consumer Subscription Launch | Algorithm-driven replenishment captures recurring revenue from California and New York households. |
Methodological Framework
Initial hypotheses were tested against primary input from dehydration facility operations managers, FSSAI regulatory compliance officers, North American health store category buyers, and West African agricultural extension coordinators and refined through secondary validation against customs export records, FSSAI nutritional labeling enforcement reports, EFSA novel food submission databases, and USDA NOP organic certification registries. Bottom-up volume builds from Maharashtra and Tamil Nadu processing cluster capacity utilization were triangulated against top-down demand estimates from corporate wellness procurement surveys and direct-to-consumer subscription platform data.
Variance decomposition across the projection horizon isolates segment-level contributions from loose leaf, instant tea, tea bag, and powdered tea formats, with additional modeling dimensions for organic certification tier, distribution channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical export velocity and forward-looking procurement intention surveys. Industry-specific forecast inputs include West African cultivation expansion timelines, EFSA novel food authorization pipeline status, and REACH-compliant packaging material transition rates among German and Dutch importers.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI enforcement consistency, EFSA regulatory posture stability, or organic certification reciprocity maintenance would require recalibration. Forecasts reflect documented assumptions about smallholder cooperative onboarding velocity, corporate wellness program adoption curves, and cold-milling equipment deployment rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
White Tea Extract Market
Tea
North America Tea Market
Tea
Rooibos Tea Market
Tea
Smart Tea Set Market
Tea
Global Tea Bag Market
Tea
Black Tea Extracts Market
Tea
Asia-Pacific Green Tea Market
Tea
Bottled Milk Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Tea Polyphenols Market
Tea
Instant Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Global Fruit Tea Market
Tea
RTD Tea Market