
 Tea Subscription Market | 2026-2036
Tea Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Subscription Market Analytics
Artificial intelligence-driven flavor profiling is narrowing the gap between mass-market convenience and artisanal curation in tea subscription fulfillment. Adagio Teas leverages its direct-to-consumer platform to sustain deep customer engagement through personalized blending tools. Harney & Sons anchors its competitive position with heritage sourcing relationships and premium loose-leaf specialization. David's Tea competes through vibrant retail-showroom integration that drives online subscription conversion.
A tea subscription constitutes a recurring-commerce arrangement delivering curated tea selections to subscribers at fixed intervals, typically involving temperature-controlled storage specifications, origin-traceable inventory lots, and rotating seasonal catalogs designed to introduce consumers to new cultivars without bulk commitment. The service exists primarily to reduce consumer decision fatigue while generating predictable revenue streams for producers and intermediaries. Monthly subscription frequency dominates volume due to alignment with household consumption cycles and lower per-shipment logistics overhead. Loose-leaf packaging commands margin concentration among enthusiasts seeking whole-leaf integrity, while tea bags capture broader retail-consumer penetration through convenience positioning.
The FDA oversees food safety and labeling requirements for imported tea products entering United States commerce, including pesticide residue thresholds and allergen declarations that subscription services must verify across supplier networks. The EU Green Deal and REACH frameworks govern packaging material compliance and chemical safety for European subscribers, compelling operators to audit compostability claims and supply chain transparency. USDA organic certification functions as a demand filter among health-conscious segments, creating tiered market access based on verification investment. Stakeholders must monitor evolving extended producer responsibility laws in key states and European member countries that will reshape fulfillment cost structures and packaging R&D priorities.
Market Dynamics
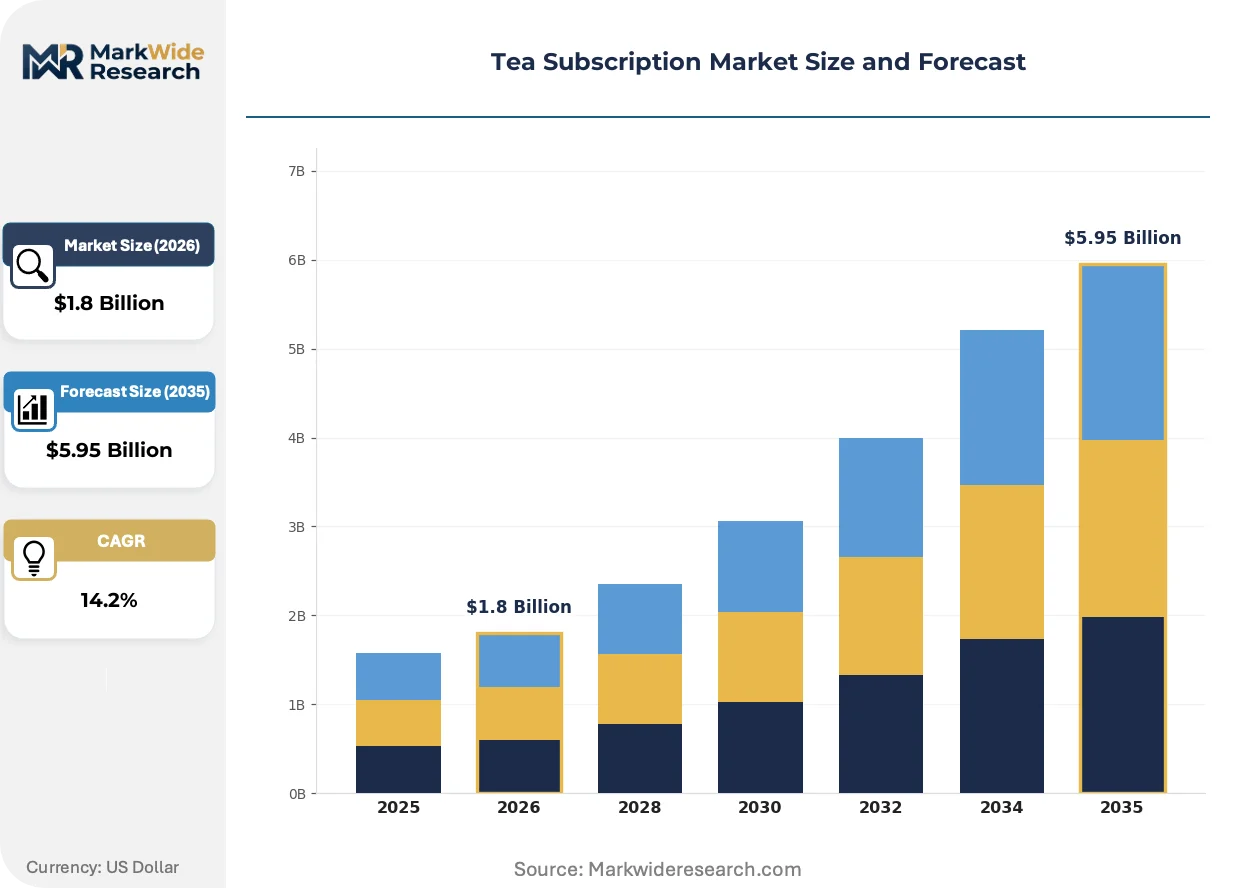
Recurring-commerce infrastructure is compressing customer acquisition costs while EU Green Deal packaging mandates are forcing fulfillment networks toward compostable materials and refillable formats. These twin pressures are reshaping how operators structure inventory, logistics partnerships, and margin allocation across temperature-controlled supply chains.
Growth Catalysts
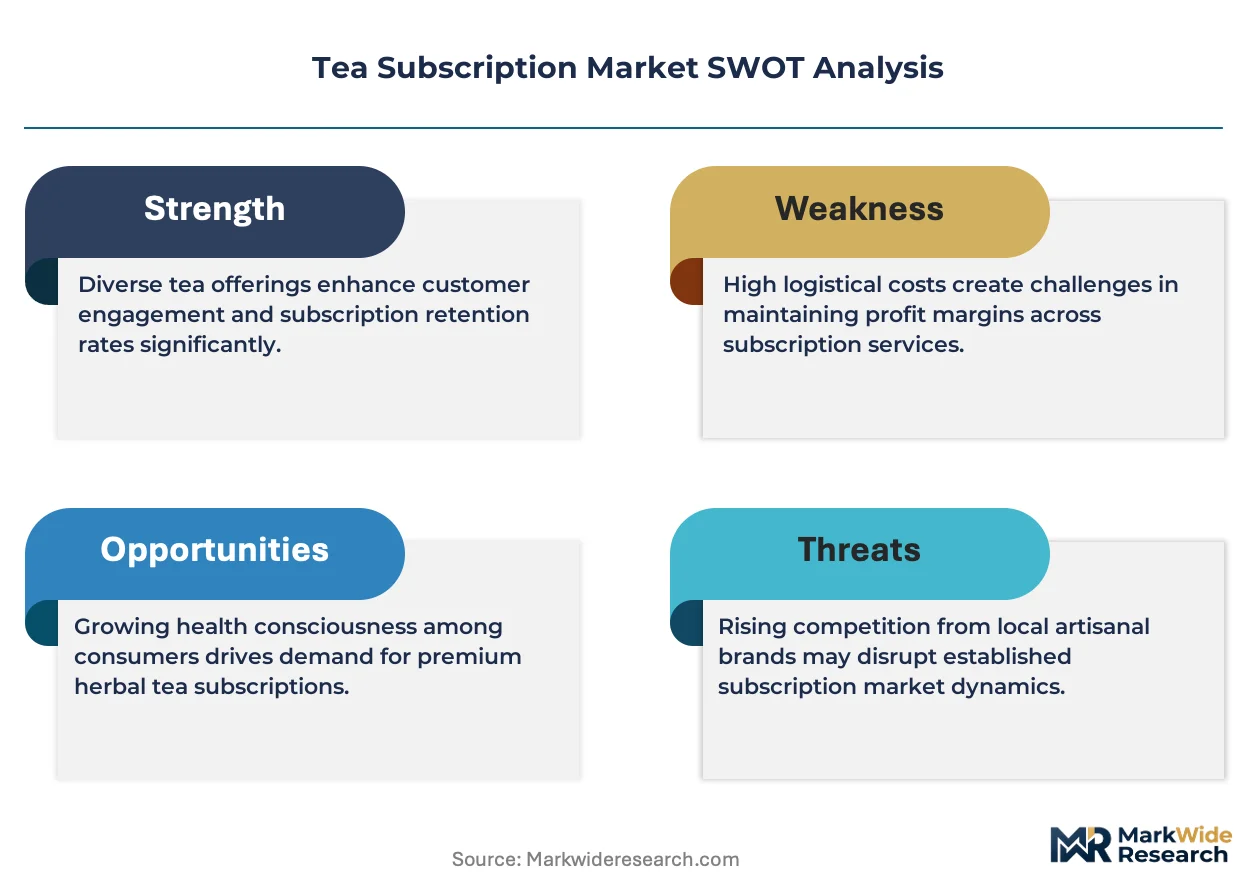
- EU Green Deal packaging directives:Compostable material mandates are accelerating R&D investment in biodegradable sachets and refillable caddies, creating first-mover advantages for compliant operators.
- Wellness-oriented retail consumers:Curated discovery experiences are pulling subscription volumes upward as health-conscious buyers seek origin-traceable cultivars without bulk commitment.
- Artificial intelligence-driven flavor profiling:Machine learning algorithms are narrowing the curation gap between mass-market convenience and artisanal tea blending, expanding addressable market reach.
Market Restraints
- Specialty tea leaf supply concentration:Premium whole-leaf inventory clusters in specific high-altitude growing regions, exposing fulfillment networks to climate volatility and harvest timing risk.
- Temperature-controlled logistics cost structure:Cold-chain specifications for preserving aromatic compound integrity inflate per-shipment overhead versus ambient e-commerce categories.
- Heritage brand substitution threat:Established loose-leaf retailers with direct sourcing relationships capture enthusiast segments resistant to curated intermediation.
Strategic Opportunities
- United Kingdom demand concentration:Digital-native subscription habits intersect with entrenched tea culture, creating fertile ground for premium tier expansion and gifting-category development.
- USDA organic certification tier:Verification investment unlocks health-conscious segment access and supports pricing stratification across certified and conventional inventory lots.
- Retail-showroom channel convergence:Physical tasting bars and immersive brand experiences are driving online subscription conversion through sensory trial before commitment.
Industry Challenges
- Extended producer responsibility compliance timelines:Evolving state-level packaging laws in California, New York, and Washington require proactive audit systems and supplier network renegotiation.
- Origin-traceable inventory management:Lot-tracking systems must integrate cultivar provenance, harvest date, and storage condition data across fragmented supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Subscription Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Type: Monthly, Bi-monthly, Quarterly, Weekly Tea Type: Green, Black, Herbal, White Packaging Type: Loose Leaf, Tea Bags, Sachets, Pods Customer Type: Retail Consumers, Corporate Clients, Event Planners, Gift Buyers |
| Companies Covered | Adagio Teas, Amoda Tea, Atlas Tea Club, Field to Cup, Tea Sparrow, Tea Runners, Harney & Sons, Eco-Cha, David's Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Subscription Market Evolving Landscape
Subscription fulfillment is pivoting from static catalogs toward dynamic, data-driven curation systems that respond to individual consumption patterns and seasonal preference shifts. Three developments are redefining operational architecture and customer value creation.
Artificial intelligence flavor profiling engines analyze individual rating histories, seasonal preferences, and cross-category purchase patterns to generate personalized tea selections. Wellness-oriented retail consumers are adopting these tools fastest, with monthly active users expanding across direct-to-consumer platforms. The technology is hybridizing artisanal curation with mass-market scalability, compressing the historical trade-off between discovery breadth and personalization depth.
REACH framework chemical safety requirements and EU Green Deal packaging waste directives are compelling operators to audit compostability claims and eliminate single-use plastic sachets. Industrial consequence includes accelerated supplier qualification timelines and reformulation partnerships with biodegradable material innovators. European subscriber volumes face the most immediate compliance pressure, with operators front-loading certification investment to maintain market access.
Digital-native buyers are compressing switching cycles and demanding unbundled trial formats before annual commitment. Traditional quarterly prepaid models are yielding to flexible pause-skip-modify interfaces that reduce subscriber churn through control rather than lock-in. This behavioral pivot is most visible in United Kingdom and United States urban markets, where subscription fatigue has elevated cancellation ease to a competitive differentiator.
Tea Subscription Market Segmentation
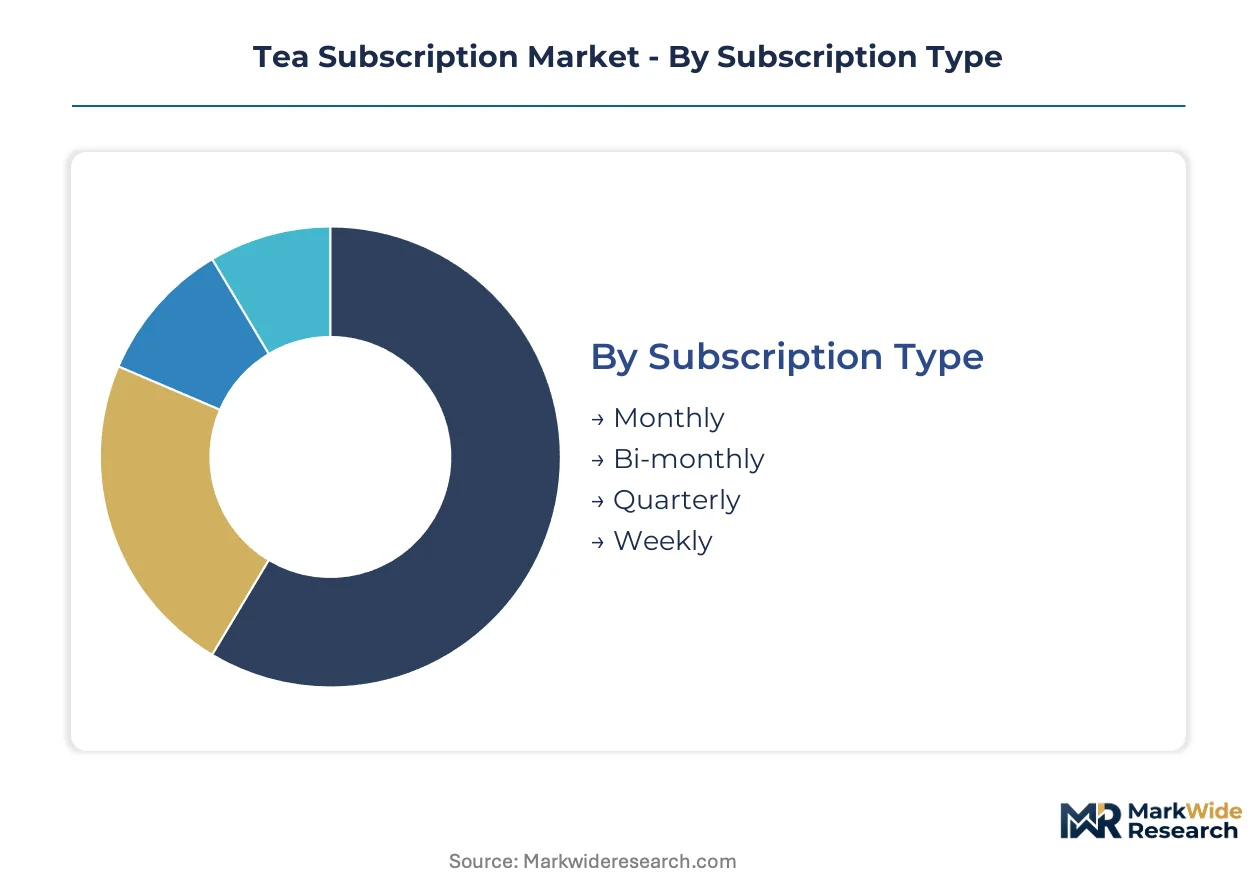
Subscription frequency, tea cultivar, packaging format, and buyer category each command distinct fulfillment economics and margin structures. Operators must align inventory depth and curation complexity with segment-specific consumption velocity and price sensitivity.
Subscription Type:
Delivery cadence determines working capital intensity and customer lifetime value trajectories across fulfillment networks.
- Monthly:Dominant frequency aligning with household consumption cycles and minimizing per-shipment logistics overhead. Wellness-oriented retail consumers in the United Kingdom drive volume concentration through habitual replenishment patterns.
- Quarterly:Prepaid annual commitments with seasonal catalog rotations targeting gift-buying occasions and corporate procurement calendars. Lower churn exposure offsets reduced cash flow velocity.
- Bi-monthly:Intermediate cadence capturing moderate enthusiasts seeking discovery breadth without pantry accumulation.
- Weekly:Ultra-fresh formats for specialty cultivars with rapid aromatic degradation, limited to premium urban corridors with same-day or next-day delivery infrastructure.
Monthly holds installed capacity. Quarterly is rotating up the share rankings.
Tea Type:
Cultivar selection governs sourcing geography, storage specifications, and customer acquisition cost stratification.
- Black:Fully oxidized leaves with extended shelf stability and broad palate familiarity anchoring mass-market subscription tiers. Established demand concentrates in the United Kingdom and United States where breakfast and afternoon traditions persist.
- Green:Minimal oxidation requiring temperature-controlled storage and rapid inventory turnover to preserve catechin integrity. Health-conscious segments in North American and European urban markets are expanding share fastest.
- Herbal:Caffeine-free infusions of botanicals and dried fruits capturing wellness-oriented buyers and evening consumption occasions. Functional ingredient claims require careful FDA and EFSA labeling compliance.
- White:Least processed cultivar with delicate flavor profiles and premium positioning dependent on origin-traceable harvest lots from Fujian and Yunnan provinces.
Black holds installed capacity. Green is rotating up the share rankings.
Packaging Type:
Format selection directly interfaces with EU Green Deal compliance timelines and per-unit margin architecture.
- Loose Leaf:Whole-leaf integrity commanding enthusiast loyalty and pricing stratification, though requiring accessory investment (infusers, measuring tools) that elevates customer acquisition friction.
- Tea Bags:Convenience-optimized penetration format with compostable material transitions underway to satisfy REACH framework and extended producer responsibility mandates.
- Sachets:Premium pyramid or rectangular formats bridging loose-leaf quality perception with single-serve convenience, popular in corporate and hospitality channels.
- Pods:Proprietary single-serve systems with highest per-cup cost and hardware lock-in, limited to integrated platform operators.
Tea Bags hold installed capacity. Loose Leaf is rotating up the share rankings.
Customer Type:
Buyer category shapes curation complexity, payment terms, and churn risk profiles across recurring revenue streams.
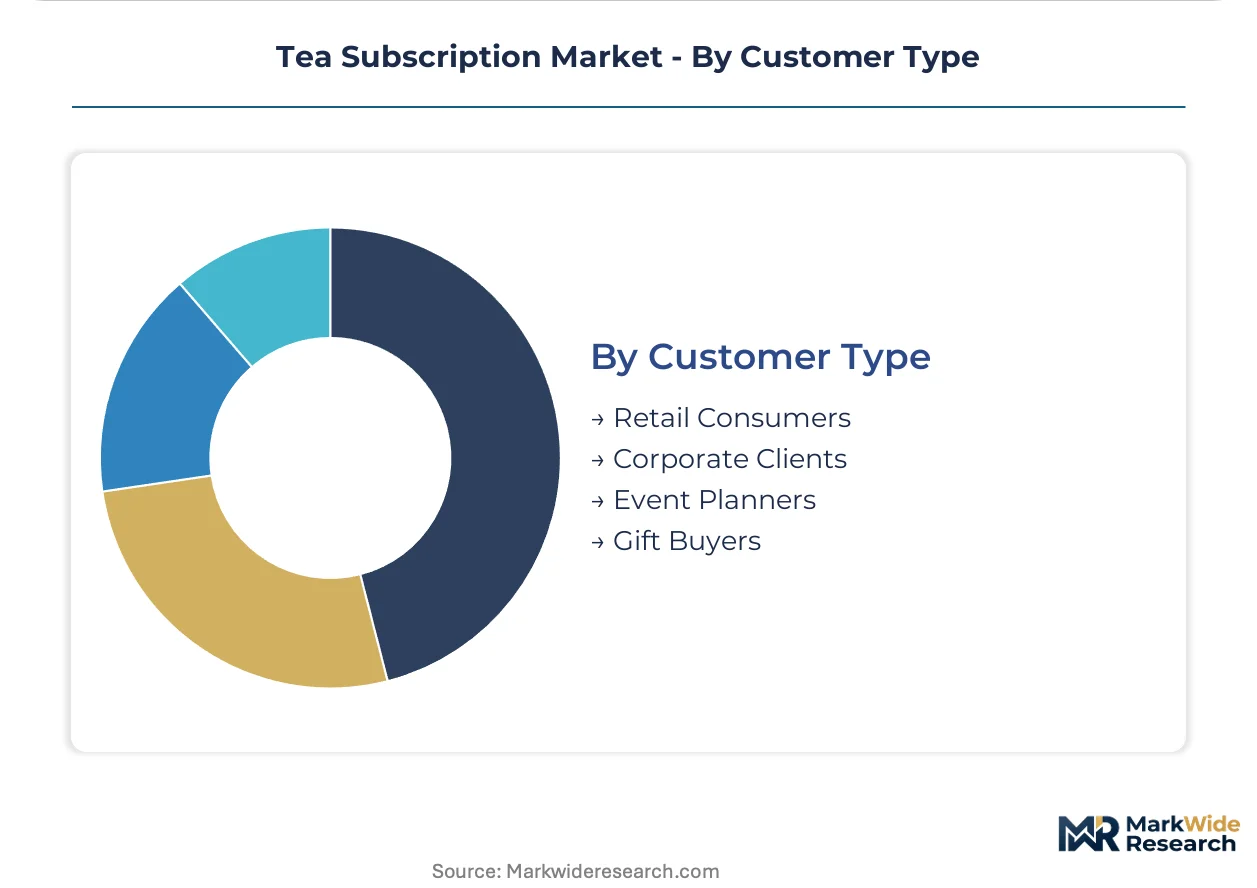
- Retail Consumers:Individual subscribers seeking curated discovery or habitual replenishment, with digital-native buyers in the United Kingdom and United States demanding flexible pause-skip-modify interfaces.
- Corporate Clients:B2B procurement of branded tea programs for office hospitality, requiring volume tiering and co-branded packaging with extended payment cycles.
- Event Planners:Episodic bulk purchasing for weddings, conferences, and seasonal gatherings with concentrated demand spikes and customization requirements.
- Gift Buyers:One-time or annual prepaid subscriptions targeting holiday and occasion-based giving, with presentation packaging and recipient experience optimization.
Retail Consumers hold installed capacity. Corporate Clients is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness-oriented retail consumers concentrate subscription demand in mature tea-drinking cultures where digital-native buying habits intersect with established consumption rituals. United Kingdom households anchor volume through habitual replenishment patterns. United States urban markets expand fastest through health-conscious segments seeking origin-traceable cultivars.
United Kingdom
Digital-native subscription habits drive premium tier expansion across London, Manchester, and Edinburgh metro corridors. The UK's extended producer responsibility framework pressures operators toward compostable packaging formats and refillable caddy systems. Yorkshire-based fulfillment networks are retrofitting temperature-controlled logistics to preserve aromatic compound integrity for whole-leaf inventory.
United States
Health-conscious segments in New York, San Francisco, and Seattle accelerate green tea and herbal subscription adoption through AI-driven flavor profiling platforms. FDA pesticide residue thresholds and allergen declaration requirements compel supplier network auditing across fragmented origin bases. Pacific Northwest roasting and blending clusters are integrating subscription fulfillment into existing specialty beverage infrastructure.
Germany
REACH framework chemical safety mandates and EU Green Deal packaging waste directives accelerate biodegradable sachet development among Berlin and Hamburg operators. Organic certification penetration exceeds regional averages, creating tiered market access based on USDA and EU organic verification. Bavarian logistics hubs are piloting refillable caddy return systems to reduce per-shipment material overhead.
Japan
Minimal oxidation tea traditions in Kanto and Kansai regions sustain demand for temperature-controlled storage specifications and rapid inventory turnover. METI guidelines on food import safety and labeling harmonization shape cross-border subscription fulfillment architecture. Shizuoka prefecture cultivation clusters supply origin-traceable harvest lots to Tokyo-based curation platforms.
Canada
Health Canada and PMRA regulatory alignment with FDA frameworks simplifies cross-border supplier qualification for Toronto and Vancouver operators. Wellness-oriented retail consumers in Ontario and British Columbia drive herbal and functional tea subscription growth. Montreal blending facilities are expanding loose-leaf packaging capacity to serve bilingual domestic and export demand.
Tea Subscription Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base lacking dominant share concentration. Direct-to-consumer platforms with proprietary curation algorithms anchor one strategic tier, while heritage loose-leaf retailers with sourcing relationships anchor another. Subscription-native entrants with flexible pause-skip-modify interfaces occupy a third position. Competitive moves concentrate on geographic expansion into United Kingdom and United States urban corridors, plus portfolio diversification toward functional wellness blends.
Among direct-to-consumer specialists, Adagio Teas and David's Tea exemplify platform-centric positioning through personalized blending tools and retail-showroom integration. Harney & Sons occupies a heritage-sourcing archetype with premium loose-leaf specialization. These three companies represent distinct competitive vectors: technology-enabled curation, physical-digital channel convergence, and origin-traceable supply relationships.
| Leading Market Players |
|---|
| Adagio Teas |
| Amoda Tea |
| Atlas Tea Club |
| Field to Cup |
| Tea Sparrow |
| Tea Runners |
| Harney & Sons |
| Eco-Cha |
| David's Tea |
| Others |
Value Network & Pricing Analysis
Undercapacity in temperature-controlled fulfillment networks across the United Kingdom and Germany is elevating carrier rates and compressing margin buffers for subscription operators serving wellness-oriented retail consumers. This utilization squeeze is forcing brands toward longer-term logistics contracts and regional consolidation to defend pricing power.
Pricing Analysis
Cost-plus contracts indexed to green tea futures and biodegradable packaging material baskets dominate procurement between cultivar suppliers and subscription operators. Pricing stratifies across premium, standard, and economy tiers based on USDA organic certification status and origin-traceable harvest lot granularity. Price erosion runs through the standard tier as private-label entrants replicate AI-driven curation interfaces without heritage sourcing overhead. Corporate clients exhibit lowest price sensitivity due to volume commitments and co-branding requirements, while individual retail consumers in bi-monthly cadences show highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for operators dependent on Fujian province white tea and Yunnan pu-erh inventories. Sourcing gravity centers on China, India, and Kenya for black tea cultivars, with Japan and Taiwan anchoring premium green tea supply. Raw material dependencies include temperature-controlled warehousing capacity, compostable sachet films compliant with REACH frameworks, and origin-verification blockchain infrastructure. Single-source vulnerability concentrates in high-altitude Darjeeling estates facing climate volatility. Distribution runs through direct-to-consumer platforms and retail-showroom convergence channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tea subscription market is cycling through a post-pandemic normalization phase as wellness-oriented retail consumers stabilize their habitual replenishment patterns after volatile trial-heavy adoption curves.
For Market Incumbents: Pre-empt substitution threats from heritage loose-leaf retailers by locking exclusive harvest lot contracts with Darjeeling and Uji cultivation clusters. Deepen backward integration into compostable packaging R&D partnerships to satisfy EU Green Deal compliance timelines ahead of smaller competitors. Prioritize certification investment in USDA organic and EU organic tiers to maintain pricing stratification against private-label entrants. For New Entrants and Emerging Players: Pursue white-space opportunities in corporate subscription programs for hybrid workplace hospitality, where procurement decentralization has weakened incumbent channel control. Target quarterly gifting segments with flexible pause-skip-modify interfaces that reduce cancellation friction. Enter through AI-driven flavor profiling platforms that narrow the curation gap without requiring multi-year sourcing relationship buildout. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer platforms with proprietary curation algorithms and established temperature-controlled logistics partnerships. Long-term viability hinges on subscription-native operators that have already absorbed compliance investment for extended producer responsibility frameworks. Watch for inflection signals in corporate client churn rates as hybrid work policies stabilize.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Packaging Transition | EU Green Deal mandates accelerate biodegradable sachet R&D partnerships with material innovators. |
| AI Flavor Profiling Investment | Machine learning curation engines compress the artisanal-mass market personalization gap for wellness consumers. |
| Corporate Subscription Expansion | B2B procurement programs for office hospitality unlock volume tiering with extended payment cycles. |
| Origin-Traceable Lot Integration | Blockchain-verified harvest documentation satisfies health-conscious segment demand for cultivar provenance. |
| Retail-Showroom Channel Convergence | Physical tasting bars in London and New York metro corridors drive online subscription conversion through sensory trial. |
Research Methodology
Desk research of customs trade databases, FDA import refusal records, and EU packaging compliance registries preceded structured interviews with tea subscription platform operators, specialty tea importers, temperature-controlled logistics providers, and biodegradable material suppliers. Primary fieldwork with curation algorithm developers and heritage loose-leaf procurement directors validated secondary findings. Bottom-up subscriber volume estimates triangulated against top-down retail audit data.
Assumptions held fixed across the projection horizon include EU Green Deal packaging directive enforcement timelines and FDA pesticide residue threshold stability. Variable inputs encompass wellness consumer adoption curves for AI-driven personalization and corporate client procurement normalization post-hybrid work transition. The analytical framework modeled subscription frequency, tea cultivar, packaging format, and buyer category segmentation dimensions. CAGRs derived from logistic curve fitting to historical subscription commerce penetration patterns, with temperature-controlled logistics cost inflation and organic certification tier expansion as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance timelines and supplier network consolidation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Floral Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Instant Tea Premixes Market
Tea
Asia-Pacific Green Tea Market
Tea
Detox Tea Market
Tea
Light-Fermented Tea Market
Tea
Asia-Pacific Tea Market
Tea
Global Tea Bag Market
Tea
Tea Infuser Market
Tea
Global Fruit Tea Market
Tea
China Tea Market
Tea
Pyramid Tea Bags Market
Tea
Butterfly Pea Flower Tea Market
Tea
Green Tea Bag Market
Tea
Global Tea Market