
 APAC RTD Tea Market | 2026-2036
APAC RTD Tea Market Size, Share, and Industry Trends Forecast 2026-2036
APAC RTD Tea Market Insights
Skilled cold-brew extraction technicians is bifurcating the APAC RTD Tea Market into premium artisanal lines and mass-volume production. Suntory Holdings Limited leverages its Japanese R&D base to sustain leadership in unsweetened green tea formulations. Uni-President Enterprises Corp anchors its position through captive distribution across Taiwan's convenience store network. Ito En Ltd specializes in bottle-grade clarity standards that differentiate its product on retail shelves.
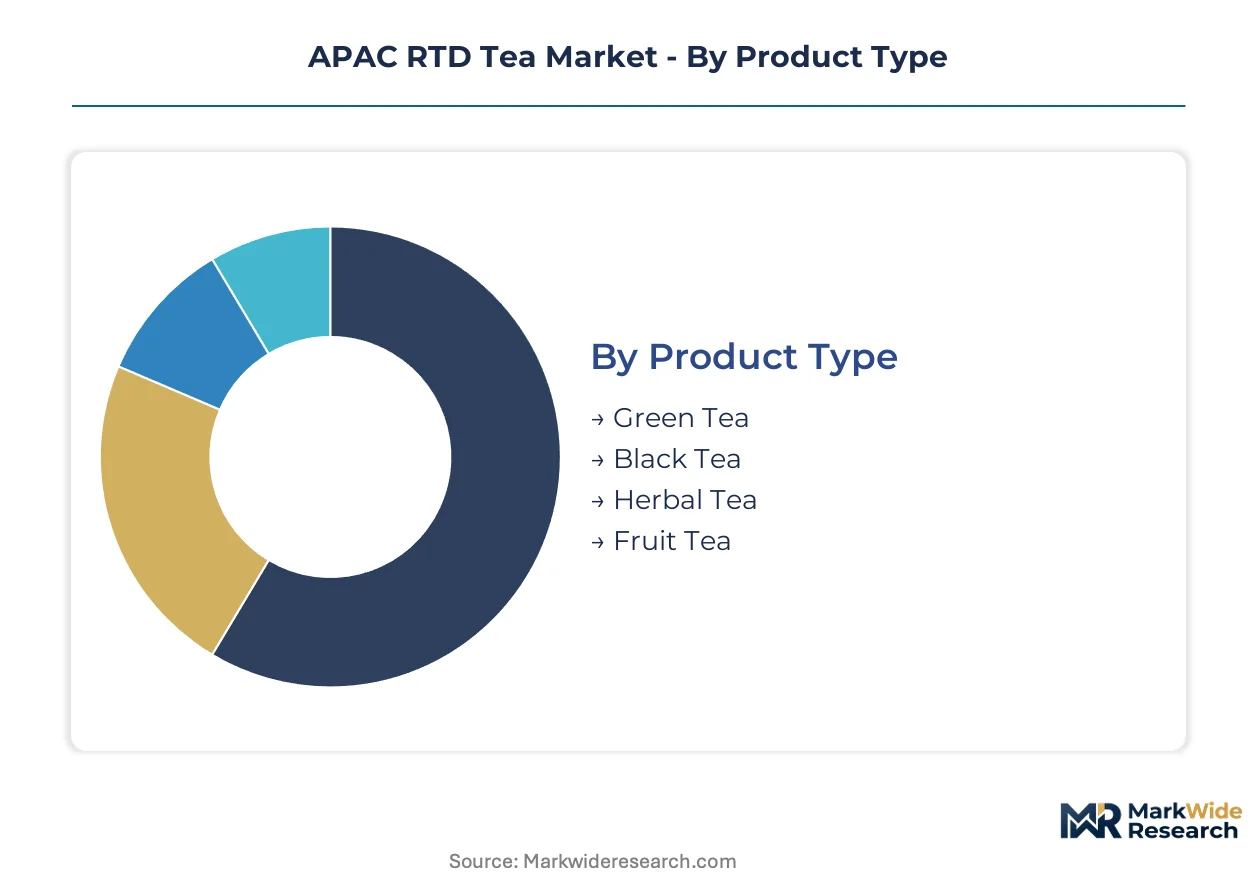
Ready-to-drink tea comprises brewed, extracted, or infused tea formulations packaged in PET, glass, or aluminum containers with shelf-stable preservation, typically processed through hot-fill, aseptic, or cold-brew methods for ambient or chilled distribution. Green tea occupies the largest volume share due to established consumption rituals in Japan and China, while fruit tea represents the fastest-expanding margin pool as younger consumers seek flavor-forward alternatives to carbonated soft drinks. Herbal tea segments draw premium positioning from ayurvedic and traditional Chinese medicine associations, particularly among health-conscious consumers in India and Thailand.
Japan's METI enforces container recycling mandates that shape PET lightweighting investments, while China's SAMR monitors additive and labeling compliance under national food safety standards. India's FSSAI imposes caffeine disclosure requirements that influence formulation choices for black tea products. Stakeholders must track evolving sugar taxation schemes across Indonesia, the Philippines, and Thailand as these determine whether reformulated low-calorie lines or full-sugar heritage recipes capture shelf space in the region's fastest-growing retail channels.
Market Dynamics
Japan's METI energy-efficiency standards for beverage production equipment are forcing manufacturers toward cold-brew extraction technologies, compressing capital cycles and fragmenting technical capabilities across the APAC RTD Tea Market.
Growth Catalysts
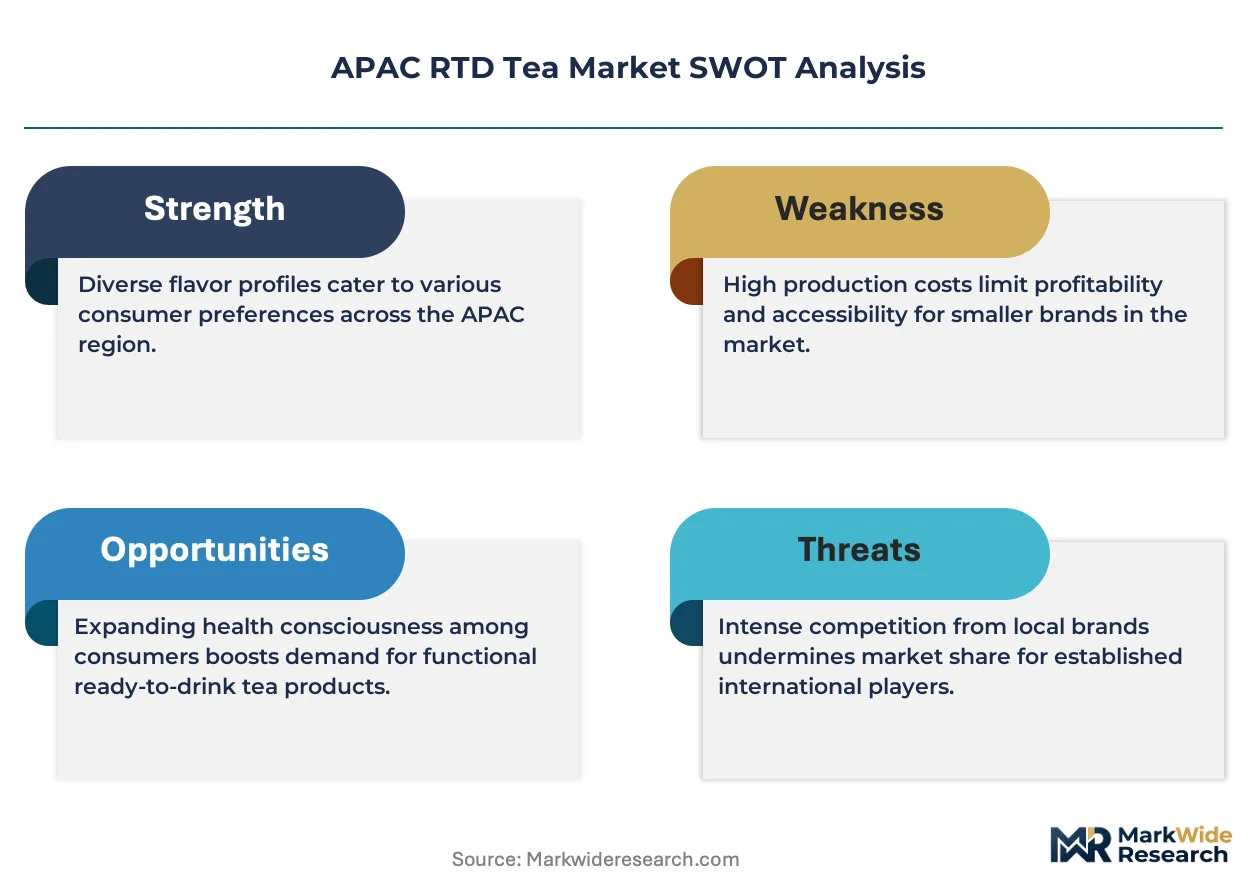
- Low-sugar formulation mandates:Indonesia's sugar taxation schemes are accelerating reformulation investments among domestic bottlers targeting health-conscious urban consumers.
- Convenience store penetration:China's tier-one cities now support grab-and-go consumption patterns that normalize chilled RTD tea as a daily beverage staple.
- Cold-brew extraction adoption:METI efficiency standards are pulling Japanese manufacturers toward ambient-temperature processing that preserves polyphenol integrity while cutting thermal energy inputs.
Market Restraints
- Aluminum can supply concentration:Southeast Asian bottlers depend on Thai and Vietnamese smelter outputs, exposing margin structures to regional energy price volatility.
- Herbal ingredient traceability gaps:India's FSSAI caffeine disclosure requirements create compliance friction for ayurvedic blenders sourcing from fragmented agricultural cooperatives.
- PET lightweighting limits:Japan's container recycling mandates have pushed bottle gauge reduction near structural thresholds, constraining further material cost savings.
Strategic Opportunities
- Tier-two city expansion:China's interior provinces present underpenetrated distribution white space where local cold-chain infrastructure is now maturing.
- Functional positioning convergence:Traditional Chinese medicine associations in Thailand are enabling premium pricing for herbal teas targeting stress-relief applications.
- Direct-to-office channel emergence:Corporate pantry services in South Korean tech corridors are displacing vending-machine dependence for unsweetened green tea procurement.
Industry Challenges
- Cold-brew technician scarcity:Skilled extraction specialists command wage premiums that bifurcate workforce quality between premium artisanal lines and mass-volume facilities.
- Multi-jurisdiction label compliance:China's SAMR additive standards diverge from India's FSSAI disclosure formats, forcing parallel packaging runs for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC RTD Tea Market |
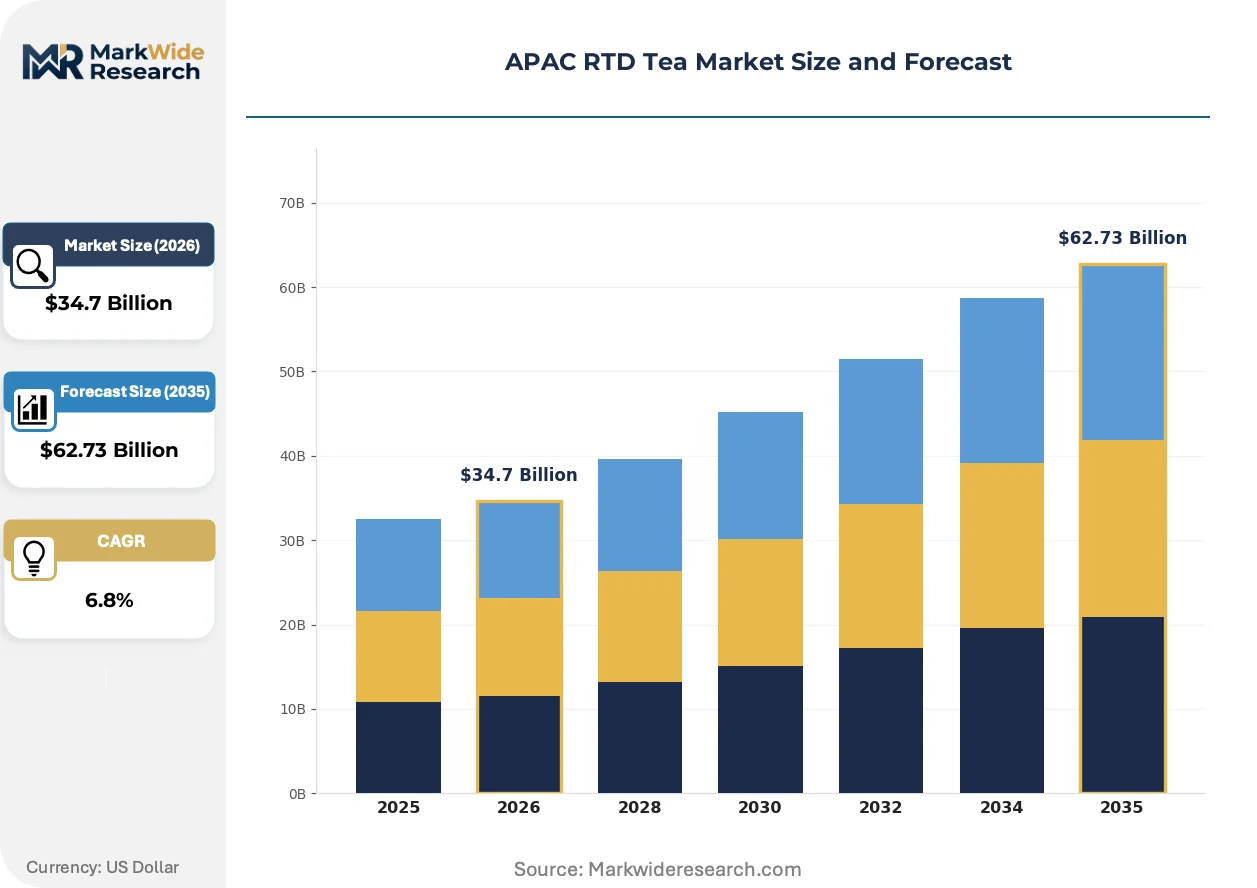
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Fruit Tea Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice End User: Young Adults, Working Professionals, Students, Health-Conscious Consumers Flavor: Peach, Lemon, Mint, Original |
| Companies Covered | Suntory Holdings Limited, Ito En Ltd, The Coca-Cola Company, Uni-President Enterprises Corp, Tingyi (Cayman Islands) Holding Corporation, Nongfu Spring Co Ltd, JDB Group, Nestlé S.A., Asahi Group Holdings Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC RTD Tea Market Trends and Innovations
Cold-brew processing, regulatory packaging mandates, and channel-specific formulation strategies are actively restructuring competitive capabilities across the APAC RTD Tea Market.
Aseptic cold-fill technology is decomposing the traditional hot-fill equipment base that has dominated shelf-stable tea production for decades. Mid-scale Thai and Vietnamese bottlers are adopting modular cold-brew lines at accelerated replacement cycles. This technology shift is compressing the viable scale threshold for regional entrants, privileging facilities that can amortize precision filtration infrastructure across diversified beverage portfolios.
China's SAMR enforcement of GB standards for food-contact materials is tightening specifications for recycled PET incorporation in beverage containers. Domestic bottlers must now validate migration testing for every secondary raw material batch. Black tea formulations with higher tannin content face disproportionate scrutiny under these leaching protocols, pushing some manufacturers toward glass alternatives for premium heritage lines.
Young adults across Southeast Asian urban centers are consolidating purchase decisions around convenience store chilled cabinets rather than traditional grocery ambient aisles. This behavioral pivot rewards brands with dedicated cooler slot negotiations and punishes those dependent on shelf-stable distribution economics. Bangkok and Jakarta convenience networks are now the primary battleground for fruit tea trial and brand switching.
APAC RTD Tea Market Segmentation
Segmentation in the APAC RTD Tea Market reveals how regulatory frameworks and channel economics reshape competitive priorities across distinct product and consumer clusters. Manufacturers must align formulation investments with jurisdiction-specific compliance requirements while targeting distribution networks that concentrate purchasing power.
Product Type:
Japan's METI energy-efficiency standards and China's SAMR additive regulations create divergent compliance burdens that favor certain tea categories over others in cross-border production strategies.
- Green Tea:Unsweetened formulations dominate volume in Japanese and Chinese retail, with cold-brew extraction preserving polyphenol integrity under METI-mandated thermal efficiency protocols. Demand concentrates in China's tier-one cities where convenience store chilled cabinets normalize daily consumption rituals.
- Black Tea:Higher tannin content triggers disproportionate scrutiny under China's GB standards for food-contact material migration, pushing some heritage lines toward glass packaging. India's FSSAI caffeine disclosure requirements add label complexity for export-bound production.
- Herbal Tea:Ayurvedic and traditional Chinese medicine associations enable premium positioning in India and Thailand.
- Fruit Tea:Young adults in Bangkok and Jakarta convenience networks drive trial and brand switching for flavor-forward alternatives.
Green Tea handles the majority of throughput; Fruit Tea is expanding most quickly on share.
Distribution Channel:
Channel economics in Southeast Asian urban centers reward cold-chain capabilities that shelf-stable distribution models cannot replicate.
- Convenience Stores:China's tier-one cities and Bangkok-Jakarta corridors have shifted purchasing decisions toward chilled cabinets, making cooler slot negotiations the primary battleground for brand visibility. Young adult consumers consolidate trial behavior around grab-and-go formats.
- Supermarkets:Ambient-aisle economics still dominate volume in India's fragmented retail landscape and China's tier-two provinces where cold-chain infrastructure remains underdeveloped.
- Online Retailers:Direct-to-office subscription models in South Korean tech corridors are displacing vending-machine dependence for unsweetened green tea procurement.
- Foodservice:Corporate pantry services and QSR fountain programs capture institutional volume in Japanese and Taiwanese urban markets.
Supermarkets retain the widest geographic footprint; Convenience Stores are climbing the fastest in revenue concentration.
End User:
Demographic targeting must account for divergent sugar taxation sensitivities across Indonesia, the Philippines, and Thailand.
- Young Adults:Southeast Asian urban centers drive adoption of low-sugar formulations as sugar taxation schemes accelerate reformulation investments. Convenience store chilled cabinets in Bangkok and Jakarta serve as the primary trial environment.
- Health-Conscious Consumers:Premium herbal positioning in India and Thailand leverages ayurvedic associations for stress-relief applications.
- Working Professionals:South Korean tech corridor offices and Japanese corporate pantries normalize unsweetened green tea as workplace staples.
- Students:Price-sensitive volume in China's university towns and India's tier-two cities.
Young Adults generate the highest trial velocity; Health-Conscious Consumers command the steepest expansion trajectory in average revenue per user.
Flavor:
Flavor innovation strategies must navigate China's SAMR additive compliance and Indonesia's evolving sugar taxation enforcement.
- Original:Unflavored formulations anchor Japanese and Chinese unsweetened green tea rituals, with bottle-grade clarity standards differentiating premium positioning.
- Peach:Southeast Asian fruit tea segments capture younger consumers seeking alternatives to carbonated soft drinks in Bangkok and Jakarta convenience networks.
- Lemon:Citrus profiles dominate black tea refreshment positioning in India's FSSAI-regulated market.
- Mint:Herbal convergence applications in Thai traditional medicine-influenced product development.
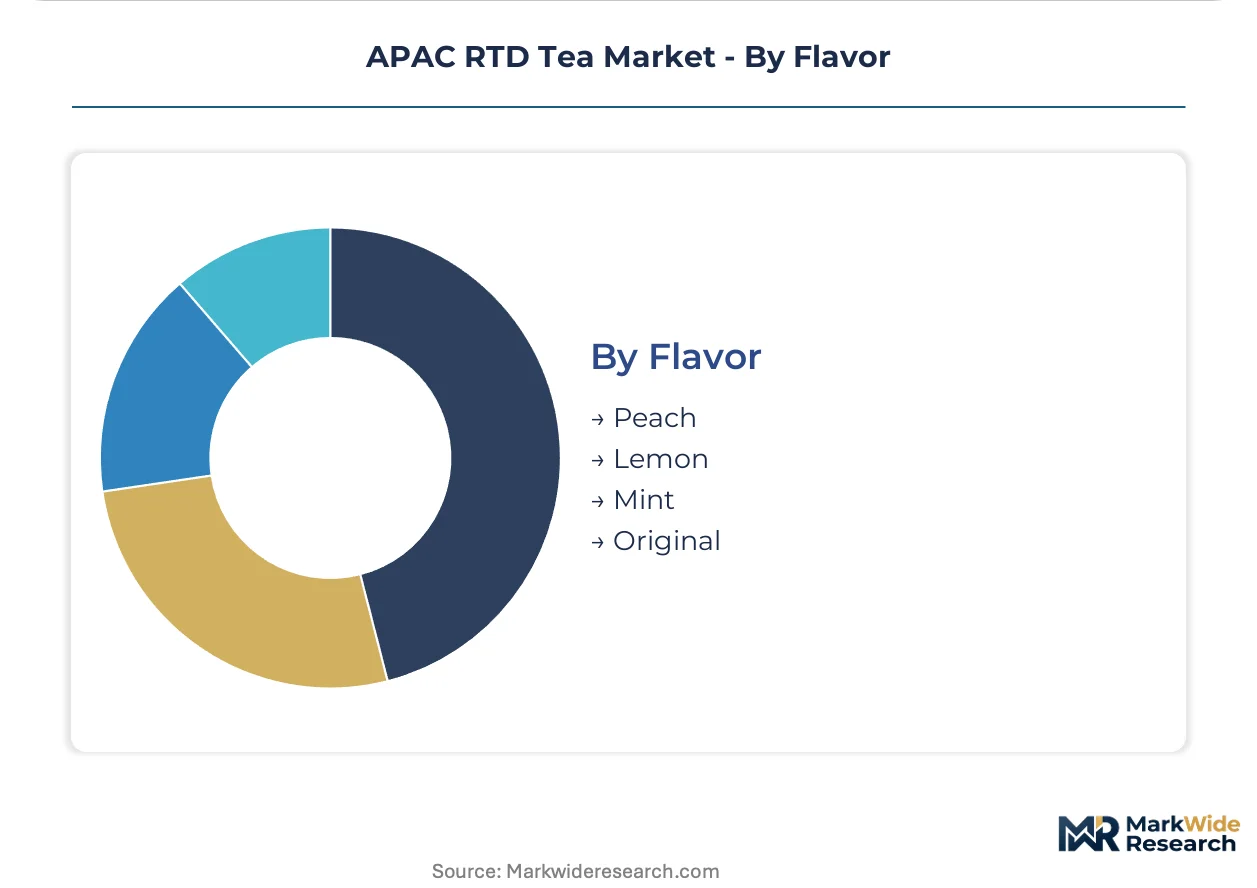
Original maintains volume leadership; Peach is gaining share fastest among flavor-forward entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI energy-efficiency standards anchor Japanese production protocols that cascade across the APAC RTD Tea Market, while China's SAMR additive regulations and India's FSSAI disclosure requirements fragment compliance architectures across the region.
China
Tier-one city convenience store penetration normalizes chilled RTD tea as daily consumption ritual, while SAMR enforcement of GB standards for food-contact materials tightens recycled PET specifications. Shanghai and Beijing retail corridors concentrate grab-and-go purchasing power that rewards dedicated cooler slot negotiations.
Japan
Unsweetened green tea rituals sustain volume leadership through cold-brew extraction preserving polyphenol integrity, while METI container recycling mandates push PET lightweighting toward structural thresholds. Kanto and Kansai industrial clusters house precision filtration infrastructure amortizable across diversified beverage portfolios.
India
FSSAI caffeine disclosure requirements influence black tea formulation choices for export-bound production, while ayurvedic associations enable premium herbal positioning among health-conscious consumers. Maharashtra and Karnataka bottling corridors face traceability friction sourcing from fragmented agricultural cooperatives.
Indonesia
Sugar taxation schemes accelerate low-sugar reformulation investments targeting health-conscious urban consumers, while evolving enforcement patterns determine shelf space allocation between reformulated lines and full-sugar heritage recipes. Jakarta and Surabaya convenience networks serve as primary trial environments for flavor-forward entrants.
Thailand
Traditional Chinese medicine associations enable premium pricing for herbal teas targeting stress-relief applications, while Bangkok convenience store chilled cabinets consolidate young adult purchase decisions away from ambient grocery aisles. Central Thailand bottling facilities source aluminum can inputs exposed to regional smelter energy price volatility.
APAC RTD Tea Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Japanese and Taiwanese beverage conglomerates commanding unsweetened green tea and captive distribution capabilities respectively. Regional bottlers cluster around cold-brew extraction competencies or convenience store network control. Three archetypes dominate: integrated R&D leaders with proprietary extraction protocols, distribution-anchored conglomerates with captive retail channels, and mid-scale specialists leveraging modular cold-fill technology. Competitive moves concentrate on cold-chain infrastructure partnerships and multi-jurisdiction label compliance systems.
Among Japanese beverage conglomerates, Suntory Holdings Limited and Ito En Ltd occupy positions exemplifying integrated R&D leadership in unsweetened formulations and bottle-grade clarity standards respectively. Uni-President Enterprises Corp anchors the distribution-anchored archetype through its Taiwan-based captive convenience store network control.
| Leading Market Players |
|---|
| Suntory Holdings Limited |
| Ito En Ltd |
| The Coca-Cola Company |
| Uni-President Enterprises Corp |
| Tingyi (Cayman Islands) Holding Corporation |
| Nongfu Spring Co Ltd |
| JDB Group |
| Nestlé S.A. |
| Asahi Group Holdings Ltd |
| Others |
Pricing and Supply Chain Analysis
Cold-brew extraction equipment replacement is compressing capital cycles across Japanese and Taiwanese bottling corridors, simultaneously redrawing procurement geography toward precision filtration suppliers and intensifying price competition among mid-scale regional entrants unable to amortize modular line investments across diversified portfolios.
Pricing Analysis
Japanese unsweetened green tea commands 40-60% premiums over Indonesian and Vietnamese mass-volume lines, with price differentiation anchored in METI-mandated energy efficiency compliance and bottle-grade clarity certification tiers. Three-tier pricing structure across premium artisanal, standard cold-fill, and economy hot-fill levels stratifies buyer access, with South Korean corporate pantry services and Chinese tier-one convenience store networks showing lowest price sensitivity while Indian university towns and Indonesia's tier-two cities concentrate volume-driven procurement. Pricing pressure stems from aluminum can feedstock volatility linked to Thai and Vietnamese smelter energy costs, squeezing margin structures for fruit tea entrants dependent on Southeast Asian canning infrastructure.
Supply Chain Analysis
Inventory lead times for cold-brew filtration membranes and aseptic filling valves have extended from Japanese and German precision equipment suppliers, creating working capital strain for Thai and Vietnamese bottlers scaling modular line deployments. Geographic supply concentrates in China for PET resin and recycled flake, Japan for extraction technology, and Thailand for aluminum can sheet, with raw material dependencies on green tea leaf from Zhejiang and Shizuoka prefectures, ayurvedic botanicals from Maharashtra agricultural cooperatives, and high-fructose syrup from Guangdong refiners. Single-source vulnerability in precision filtration membrane supply poses structural risk, while distribution runs through captive convenience store networks in Taiwan, chilled cabinet slot negotiations in Bangkok and Jakarta, and direct-to-office subscription channels in Seoul tech corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled cold-brew extraction technicians represent the critical bottleneck bifurcating workforce quality between premium artisanal facilities and mass-volume plants, with wage premiums for qualified specialists compressing returns for entrants lacking training infrastructure or captive R&D pipelines.
For Market Incumbents: Compound defensive positioning by acquiring modular cold-fill technology providers in Vietnam and Thailand to lock in precision filtration capacity before regional bottler consolidation accelerates, while investing in METI-compliant energy efficiency certification for Japanese production assets to sustain premium pricing power against Indonesian sugar-taxation-driven reformulation competitors. For New Entrants and Emerging Players: Lead with functional herbal positioning in India's ayurvedic-influenced stress-relief segment, where FSSAI caffeine disclosure requirements create compliance friction for black tea exporters and premium pricing tolerance runs highest among health-conscious urban consumers, using direct-to-office channel partnerships in South Korean tech corridors as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-replacement phase that favors integrated R&D leaders with proprietary extraction protocols and captive distribution networks over asset-light brand licensors. Long-term viability over the next decade hinges on cold-chain infrastructure control and multi-jurisdiction label compliance systems. Acquisition targets should demonstrate precision filtration amortization across diversified beverage portfolios. The signal to watch is convenience store cooler slot negotiation outcomes in Bangkok and Jakarta, where chilled cabinet access determines trial velocity for flavor-forward entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Brew Technology Licensing | Japanese METI efficiency standards pull regional bottlers toward ambient-temperature extraction preserving polyphenol integrity. |
| Captive Convenience Store Network Expansion | Taiwan's Uni-President model demonstrates how cooler slot control in tier-one cities secures daily consumption rituals. |
| Ayurvedic Herbal Certification Investment | Thai traditional medicine associations enable premium positioning for stress-relief applications among health-conscious consumers. |
| Recycled PET Migration Testing Infrastructure | China's SAMR GB standards enforcement requires batch validation capabilities that fragment compliance architectures. |
| Direct-to-Office Channel Development | South Korean tech corridor corporate pantries displace vending-machine dependence for unsweetened green tea procurement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cold-brew extraction technicians, beverage brand managers, convenience store category buyers, FSSAI compliance officers, and METI energy efficiency auditors, combined with secondary validation against customs records for PET resin and aluminum can sheet trade flows, Japanese container recycling mandate filings, Chinese SAMR GB standard enforcement bulletins, and Nielsen retail audit data for chilled cabinet velocity. Bottom-up volume modeling triangulated against top-down category spend estimates.
Across the analysis window, forecasts applied analytical frameworks segmenting by product type, distribution channel, end-user demographic, and flavor profile, with CAGRs derived from regression analysis against convenience store penetration rates, cold-chain infrastructure maturity indices, and sugar taxation enforcement intensity. Industry-specific inputs included METI energy efficiency compliance cost curves and FSSAI caffeine disclosure label complexity scores.
The analysis sits within stated boundaries; outcomes outside sustained cold-brew technology adoption, stable aluminum smelter energy pricing, or consistent sugar taxation enforcement would require recalibration. Forecasts reflect documented assumptions regarding convenience store cooler slot availability and precision filtration supplier capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Subscription Market
Tea
Matcha Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Tea Essence Market
Tea
Herbal Tea Market
Tea
US RTD Organic Tea Market
Tea
Bottled Tea Market
Tea
Instant Tea Premix Consumption Market
Tea
Matcha Products Market
Tea
Asia-Pacific Tea Market
Tea
Probiotic Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Oolong Tea Market
Tea
South America Tea Market