
 New Style Tea Drink Market | 2026-2036
New Style Tea Drink Market Size, Share, and Industry Trends Forecast 2026-2036
New Style Tea Drink Market Insights
Franchise-based asset-light expansion is rewriting competitive economics in the New Style Tea Drink space, enabling rapid store proliferation without heavy balance-sheet commitment. Hey Tea leverages premium positioning and direct-store control in top-tier Chinese cities to sustain margin density. Mixue Group anchors extreme value pricing through captive supply chain infrastructure across lower-tier markets. Nayuki Holdings Limited differentiates via bakery-tea fusion concepts that occupy distinct daypart occasions.
New style tea drinks encompass brewed, blended, or extracted tea bases combined with dairy, fruit, or functional additives, served chilled or at ambient temperature with standardized sweetness and ice parameters for repeatable consumer experiences. The category serves refreshment, social ritual, and portable caffeine delivery functions for mobile, time-constrained consumers. Iced tea variants dominate volume throughput in convenience channels, while matcha formulations command premium price realization in specialty stores. Health-conscious consumers represent the fastest-expanding buyer cohort, though students still provide the largest absolute transaction frequency across Boba and fruit-tea lines.
China's SAMR enforces GB standards on food-contact materials and additive disclosures, directly shaping formulation and packaging choices for products sold domestically. Japan's METI and PMDA oversee functional claim substantiation for tea-derived beverages, creating a compliance threshold for health-positioned entrants. The EU's EFSA and F-Gas Regulation indirectly affect cold-chain equipment standards for European export-oriented producers. Stakeholders must monitor how evolving plastic-reduction mandates and sugar-tax proposals across these jurisdictions will reshape cost structures and permissible product architectures.
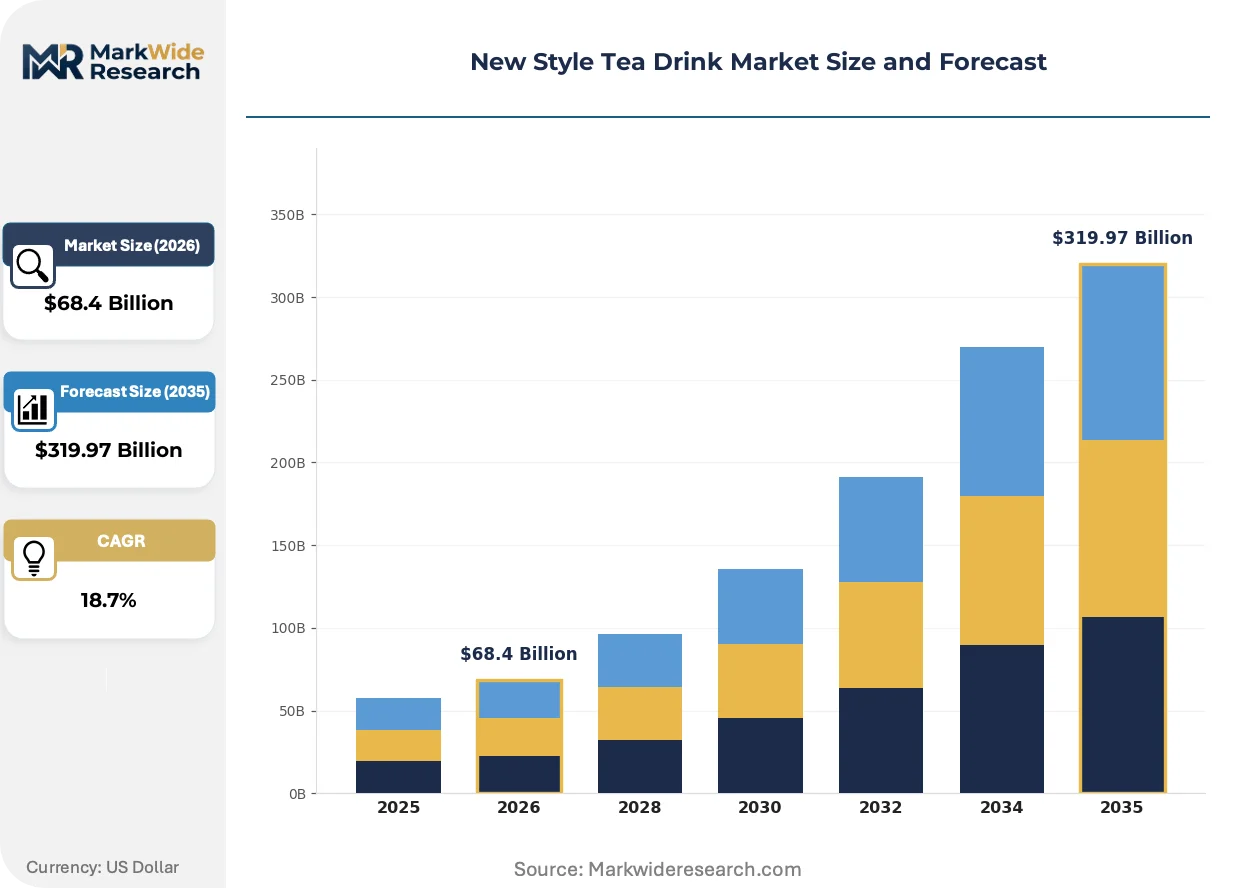
Market Dynamics
Franchise-based asset-light expansion is compressing capital requirements for store rollout while China's SAMR food-contact material standards under GB protocols are forcing substrate reformulation across packaging supply chains.
Growth Catalysts
- Urban professional cohort expansion:Young office workers in dense metropolitan corridors are normalizing ready-to-drink tea as portable caffeine and social ritual, driving repeat purchase frequency in convenience channels.
- GB standard enforcement:SAMR's tightening food-contact material regulations are accelerating migration toward biodegradable and fiber-based packaging substrates, opening innovation windows for compliant suppliers.
- Functional additive integration:Collagen, probiotics, and adaptogenic botanicals are attracting health-conscious buyers seeking beverage-as-supplement positioning beyond refreshment.
Market Restraints
- Fresh fruit input volatility:Seasonal price swings for strawberries, mangoes, and citrus concentrate squeeze margin predictability for fruit-tea lines.
- Single-use packaging friction:Municipal plastic-reduction mandates in Shanghai, Shenzhen, and Beijing impose compliance costs and operational complexity for cold-drink dispensing.
- Dairy alternative quality variance:Oat and coconut milk substitutes suffer texture inconsistency across batches, limiting premium positioning for lactose-free formulations.
Strategic Opportunities
- Lower-tier city penetration:Tier-three and tier-four Chinese municipalities remain underserved by premium new-style tea concepts, presenting whitespace for value-engineered formats.
- Smart locker distribution:Unattended pickup points in subway stations and residential compounds reduce rent burden while capturing impulse occasions.
- Dual carbon alignment:China's MEE carbon intensity targets create preferential financing and zoning access for brands with verified low-carbon supply chains.
Industry Challenges
- Barista-equivalent talent scarcity:Shortage of trained tea sommeliers capable of executing complex extraction and layering protocols at speed limits quality consistency during peak hours.
- Cross-regional supply chain synchronization:Coordinating perishable fruit and dairy logistics across provinces with divergent cold-chain maturity creates spoilage risk and working capital pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Style Tea Drink Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $319.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iced Tea, Herbal Tea, Matcha, Boba Distribution Channel: Online Retail, Supermarket, Convenience Store, Specialty Store Consumer Type: Health-Conscious, Millennials, Students, Office Workers Flavor Profile: Citrus, Berry, Spiced, Floral |
| Companies Covered | Nestlé, Tata Global Beverages, Hey Tea, CoCo Fresh Tea & Juice, Ito En, Nayuki Holdings Limited, The Coca-Cola Company, Mixue Group, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Style Tea Drink Market Trends and Innovations
Digital ordering infrastructure and formulation science are converging to compress wait times and enable mass customization at unit economics previously reserved for standardized service.
Automated tea-brewing robotics is virtualizing the barista function in high-throughput locations. Chains in Shanghai and Beijing are deploying precision extraction machines that calibrate temperature, timing, and agitation parameters per order. This technology is virtualizing labor-intensive preparation steps while maintaining output consistency across shift changes and location expansions.
China's GB 4806 series on food-contact materials is compelling packaging substrate transitions. SAMR enforcement of heavy-metal limits and migration testing protocols is disqualifying conventional plastic laminates. Domestic suppliers are accelerating pulp-molded and PLA-coated alternatives to retain market access.
Subscription-based consumption is displacing purely transactional purchasing for core users. Office workers in Guangzhou and Chengdu are enrolling in monthly tea-pass programs that bundle delivery, customization, and loyalty rewards. This shift concentrates predictable revenue and reduces customer acquisition cost burdens for operators with dense urban footprints.
New Style Tea Drink Market Segmentation
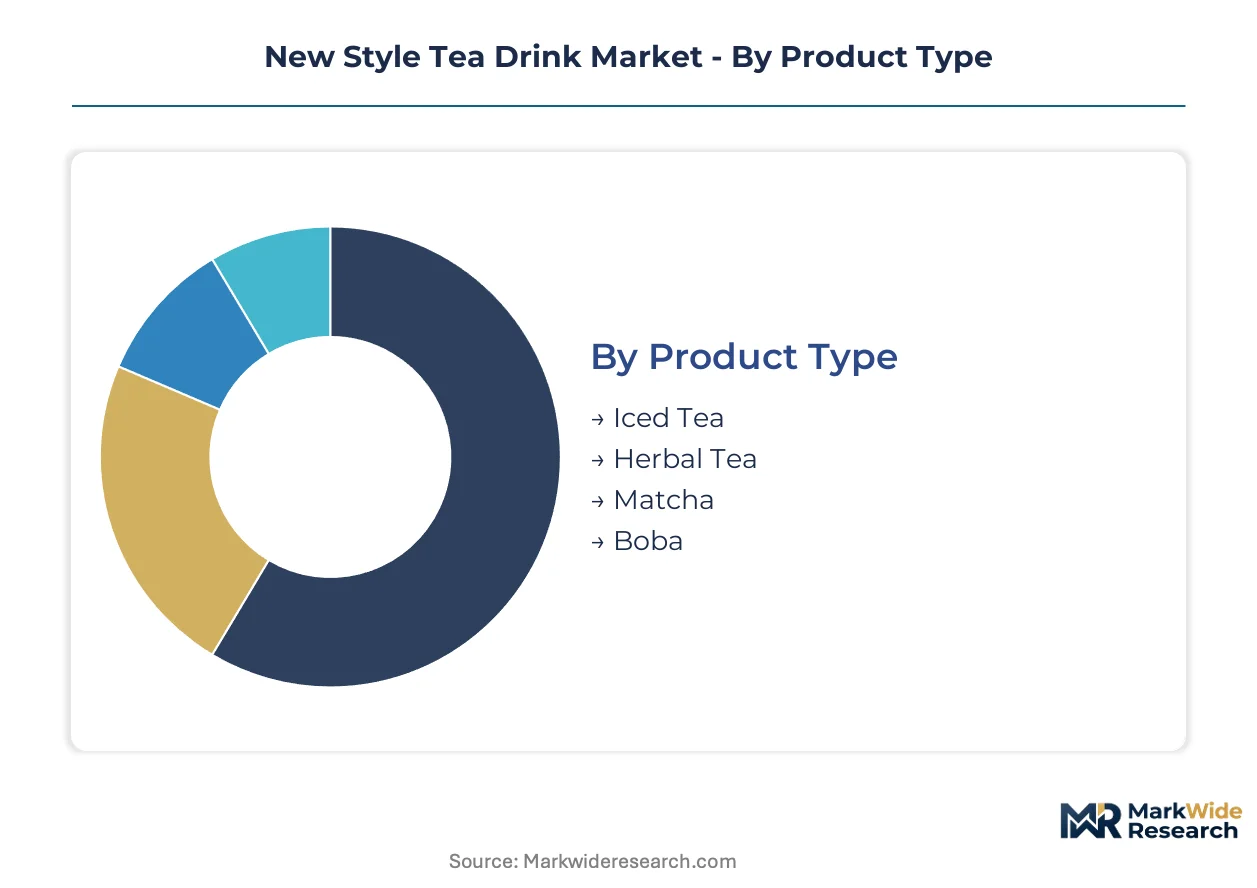
Segmentation in the New Style Tea Drink Market reveals distinct consumption occasions and channel preferences that shape formulation, packaging, and pricing architecture. Understanding how product formats intersect with distribution infrastructure and consumer psychographics enables operators to optimize portfolio composition and capital deployment.
Product Type:
Mature formats anchor volume throughput while emerging variants capture premium price realization through functional positioning.
- Iced Tea:Brewed black or green tea bases served chilled with standardized sweetness parameters dominate convenience channel velocity. Office workers in Shanghai and Beijing generate repeat purchase frequency for portable caffeine delivery during commute windows.
- Boba:Chewy tapioca pearls suspended in sweetened milk tea create tactile differentiation and social media shareability. Students across Guangzhou and Chengdu sustain the highest transaction frequency, though dairy alternative quality variance limits lactose-free premium positioning.
- Herbal Tea:Botanical infusions without Camellia sinensis base target caffeine-averse consumers seeking functional relaxation benefits.
- Matcha:Stone-ground green tea powder formulations command elevated price points in specialty retail through ceremonial preparation rituals and antioxidant health claims.
Iced tea handles the majority of throughput; matcha is expanding most quickly on share through premium channel penetration.
Distribution Channel:
Channel cost structures range from high-touch experiential formats to low-margin high-velocity convenience infrastructure.
- Convenience Store:Refrigerated grab-and-go formats with 24-hour availability capture impulse occasions near transit nodes and residential compounds. China's SAMR food-contact material standards under GB protocols are accelerating packaging substrate transitions toward compliant fiber-based alternatives.
- Specialty Store:Made-to-order preparation with customizable sweetness, ice, and topping parameters enables premium price realization. Hey Tea and Nayuki Holdings Limited concentrate store networks in tier-one cities where consumers accept wait times for experiential consumption.
- Online Retail:Subscription-based monthly tea-pass programs concentrate predictable revenue and reduce customer acquisition costs for operators with dense urban footprints.
- Supermarket:Multi-pack formats and seasonal promotions drive household stock-up behavior for at-home consumption occasions.
Convenience stores handle the majority of throughput; specialty stores are gaining share fastest through premium format expansion.
Consumer Type:
Demographic cohorts exhibit divergent price sensitivity, health orientation, and occasion-based purchasing patterns.
- Office Workers:Time-constrained professionals in dense metropolitan corridors normalize ready-to-drink tea as portable caffeine and social ritual. Automated tea-brewing robotics in Shanghai and Beijing locations compress wait times while maintaining output consistency.
- Health-Conscious:Buyers seeking beverage-as-supplement positioning drive collagen, probiotic, and adaptogenic botanical integration. Japan's METI and PMDA functional claim substantiation requirements create compliance thresholds for health-positioned entrants.
- Students:Price-sensitive cohort providing largest absolute transaction frequency across Boba and fruit-tea lines with high social sharing behavior.
- Millennials:Experience-oriented consumers balancing premium willingness with digital-native ordering expectations and loyalty program engagement.
Office workers handle the majority of throughput; health-conscious consumers are climbing the fastest on share.
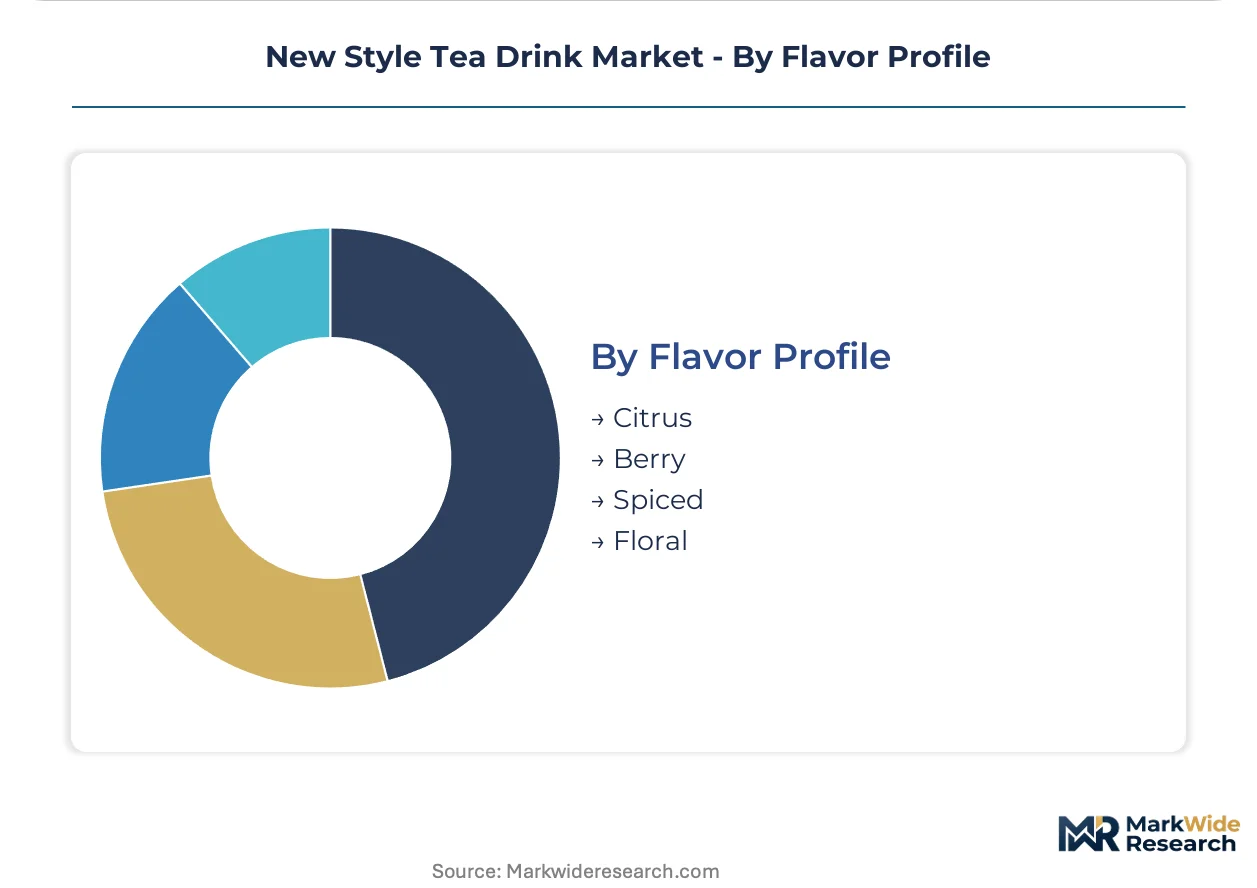
Flavor Profile:
Flavor architecture spans fresh fruit dependency against stable synthetic or extract-based alternatives with divergent margin predictability.
- Citrus:Lemon, yuzu, and grapefruit formulations deliver refreshment functionality with year-round ingredient availability. Municipal plastic-reduction mandates in Shenzhen impose compliance costs for cold-drink dispensing of citrus-forward chilled formats.
- Berry:Strawberry and blueberry lines attract seasonal demand spikes but suffer fresh fruit input volatility that squeezes margin predictability.
- Floral:Rose, jasmine, and osmanthus extracts enable differentiation without perishable supply chain complexity.
- Spiced:Cinnamon, ginger, and cardamom profiles target warming consumption occasions and functional digestive positioning.
Citrus handles the majority of throughput; floral is gaining share fastest through supply chain stability advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon targets under MEE guidance are redirecting capital toward low-carbon supply chain certification across major tea drink markets. SAMR's GB 4806 food-contact material standards are accelerating packaging substrate transitions in tier-one cities. Japan's METI oversees functional claim substantiation for health-positioned entrants, while EU EFSA standards shape cold-chain equipment requirements for export-oriented producers.
China
Urban professionals in Shanghai, Beijing, and Shenzhen normalize ready-to-drink tea as portable caffeine and social ritual. SAMR enforces GB standards on food-contact materials and additive disclosures, compelling reformulation of packaging substrates. Hey Tea and Nayuki Holdings Limited concentrate dense store networks in tier-one cities where consumers accept wait times for experiential consumption.
Japan
Health-conscious buyers seeking beverage-as-supplement positioning drive demand for collagen and probiotic formulations. METI and PMDA oversee functional claim substantiation for tea-derived beverages, creating compliance thresholds for entrants. Tokyo and Osaka anchor specialty retail concentration where matcha formulations command premium price realization through ceremonial preparation rituals.
South Korea
Young office workers in Seoul Capital Area generate repeat purchase frequency for portable caffeine delivery during commute windows. MFDS regulates food-contact materials and additive safety, aligning with regional sustainability mandates. Busan-Ulsan corridor supports cold-chain infrastructure development for perishable fruit and dairy logistics.
United States
Students and millennials sustain transaction frequency across Boba and fruit-tea lines with high social sharing behavior. FDA oversees food additive safety and labeling requirements for imported tea beverages. California and New York Metro concentrate specialty store expansion where premium positioning attracts experience-oriented consumers.
United Kingdom
Health-conscious consumers represent the fastest-expanding buyer cohort for functional botanical infusions. EFSA standards indirectly affect product architecture for brands seeking continental European market access. London/Southeast anchors demand concentration where subscription-based monthly tea-pass programs concentrate predictable revenue.
New Style Tea Drink Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans multinational beverage conglomerates, Chinese new-style tea chains, and regional specialty operators. Three archetypes dominate: premium experiential chains with direct-store control, extreme-value players leveraging captive supply chains, and diversified FMCG giants with retail shelf presence. Competitive moves concentrate on franchise-based asset-light expansion and packaging substrate innovation compliant with tightening food-contact regulations.
Within the premium experiential tier, Hey Tea and Nayuki Holdings Limited exemplify direct-store control strategies in China's tier-one cities. Mixue Group occupies a position at the value-engineered end through extreme pricing and lower-tier market penetration. Among diversified multinational players, Nestlé and The Coca-Cola Company represent FMCG giants with retail distribution scale and brand portfolio breadth. These three archetypes—premium chain, value chain, and diversified conglomerate—anchor competitive positioning across distinct price-occasion segments.
| Leading Market Players |
|---|
| Nestlé |
| Tata Global Beverages |
| Hey Tea |
| CoCo Fresh Tea & Juice |
| Ito En |
| Nayuki Holdings Limited |
| The Coca-Cola Company |
| Mixue Group |
| Unilever |
| Others |
Pricing and Supply Chain Analysis
Fresh fruit input volatility determines both tiered price spreads across premium and value formats and supply chain configuration in the New Style Tea Drink Market. Seasonal price swings for strawberries, mangoes, and citrus concentrate force operators to choose between perishable-forward premium positioning and extract-based economy lines, with each path demanding distinct cold-chain investments and supplier relationships.
Pricing Analysis
Certification level under China's GB 4806 food-contact material standards creates the primary spread between premium and mass-market tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with specialty stores commanding premium realization through experiential preparation while convenience channels compete on volume velocity. Cost compression in fruit-tea lines is intensifying because fresh input volatility squeezes margin predictability. Students represent the most price-sensitive buyer cohort, while health-conscious consumers demonstrate lowest sensitivity for functional additive positioning.
Supply Chain Analysis
Tariff exposure between China and key fruit-exporting regions dominates supply chain risk planning for new style tea operators. Manufacturing concentration centers on China, Taiwan, and Thailand for tapioca pearl production, tea extraction, and packaging substrate fabrication. Raw material dependencies rest on seasonal fruit imports, dairy and alternative milk proteins, and biodegradable packaging films. Single-source vulnerability in perishable fruit logistics creates spoilage exposure during peak demand windows. Distribution runs through franchise-partner networks in lower-tier cities alongside direct-store control in premium metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The New Style Tea Drink Market rewards operators who attach recurring revenue layers to transactional formats. Subscription-based monthly tea-pass programs in Guangzhou and Chengdu are expanding faster than standalone store count, concentrating predictable revenue and reducing customer acquisition cost burdens.
For Market Incumbents: Build captive supply chain moats through backward integration into tea extraction and fruit processing to defend against margin pressure from fresh input volatility. Add capacity in tier-three and tier-four Chinese municipalities where value-engineered formats face limited premium competition. Invest in GB 4806-compliant packaging substrate certification to preempt regulatory disqualification of conventional plastic laminates. For New Entrants and Emerging Players: Tier-three and tier-four Chinese municipalities present the most penetrable whitespace for value-engineered formats with simplified menus and automated preparation. Target smart locker distribution in subway stations and residential compounds to capture impulse occasions without flagship store rent burdens. Pursue dual carbon alignment certification to unlock preferential financing and zoning access under China's MEE carbon intensity targets. For Investors and Strategic Acquirers: SAMR's enforcement timeline for biodegradable packaging mandates reshapes the acquisition landscape toward suppliers with compliant substrate portfolios. Long-term viability favors operators with demonstrated unit economics in both premium experiential and extreme-value tiers. Monitor municipal plastic-reduction mandate expansion across Shanghai, Shenzhen, and Beijing as the signal for accelerated packaging cost structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Franchise-Based Asset-Light Expansion | Enables rapid store proliferation without heavy balance-sheet commitment across tier-three cities. |
| Automated Tea-Brewing Robotics Deployment | Virtualizes labor-intensive preparation while maintaining output consistency across Shanghai and Beijing locations. |
| Biodegradable Packaging Transition | Retains market access under SAMR's GB 4806 heavy-metal limits and migration testing protocols. |
| Smart Locker Distribution Network | Reduces rent burden while capturing impulse occasions in subway stations and residential compounds. |
| Functional Additive Integration | Attracts health-conscious buyers seeking collagen, probiotic, and adaptogenic botanical positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with supply chain directors, franchise operations managers, regulatory affairs specialists, and category buyers at convenience retailers; and secondary validation through SAMR regulatory filings, customs trade data for fruit and dairy inputs, SEC disclosures from listed operators, and retail audit databases. Bottom-up store count and transaction frequency estimates triangulated against top-down market sizing from trade associations and food-service industry reports.
Forecast inputs considered product type segmentation across iced tea, boba, herbal, and matcha formats; distribution channel dynamics spanning convenience stores, specialty retail, online subscription, and supermarket; and consumer type differentiation among office workers, health-conscious buyers, students, and millennials. CAGRs were derived from growth driver quantification and constraint boundary analysis across the projection horizon. Industry-specific inputs included cold-chain infrastructure maturity indices and municipal plastic-reduction mandate implementation timelines.
Practitioners should monitor fresh fruit price volatility, SAMR enforcement intensity for food-contact materials, and franchisee recruitment rates in lower-tier cities for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Asia-Pacific Green Tea Market
Tea
Herbal Tea Market
Tea
Global Fruit Tea Market
Tea
Tea Subscription Market
Tea
Plant Based New Tea Drink Market
Tea
Floral Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
High Protein Tea Market
Tea
Matcha Market
Tea
Natural Tea Extract Market
Tea
Fermented Tea Market
Tea
Probiotic Tea Market
Tea
White Tea Extract Market
Tea
US Ready to Drink Tea Market
Tea
Nitro Tea Market
Tea
Green Tea Leaves Market