
 Asia-Pacific Ready to Drink Tea Market | 2026-2036
Asia-Pacific Ready to Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ready to Drink Tea Market Outlook
Single-source PET bottle procurement is repositioning toward multi-material supplier networks across the Asia-Pacific Ready to Drink Tea value chain. Uni-President Enterprises Corp leverages captive bottling infrastructure across Taiwan and mainland China. Ito En Ltd anchors its competitive stance through direct-sourced tea leaf procurement from Shizuoka prefecture plantations. Nongfu Spring Co Ltd differentiates via deep well water extraction protocols and cold-fill aseptic lines.
Ready to Drink Tea denotes brewed, shelf-stable tea beverages processed through hot-fill or aseptic cold-fill methods, typically formulated with pH below 4.6 for ambient stability and packaged in oxygen-barrier containers to preserve polyphenol content. The product category serves convenience-driven consumption occasions spanning workplace hydration, transit consumption, and on-premise foodservice replacement. Green tea formulations command premium shelf positioning in Japanese and South Korean convenience stores, while black tea variants dominate mass-market volume across Southeast Asian supermarkets. Tetra Pak aseptic cartons capture growing share in India's urban retail expansion, though PET bottles retain cost leadership in China's high-throughput distribution environment.
Japan's METI enforces container recycling quotas under the Act on Promotion of Recycling of Resources, compelling reformulation toward lighter-weight packaging and plant-derived materials. China's SAMR implements GB standards for prepackaged beverage labeling, including sugar content disclosure requirements that redirect R&D toward reduced-calorie formulations. India's FSSAI mandates caffeine threshold declarations, shaping product portfolios for entry into organized retail channels. Stakeholders must monitor evolving extended producer responsibility frameworks across Australia, South Korea, and Thailand to anticipate compliance-driven packaging transitions.
Market Dynamics
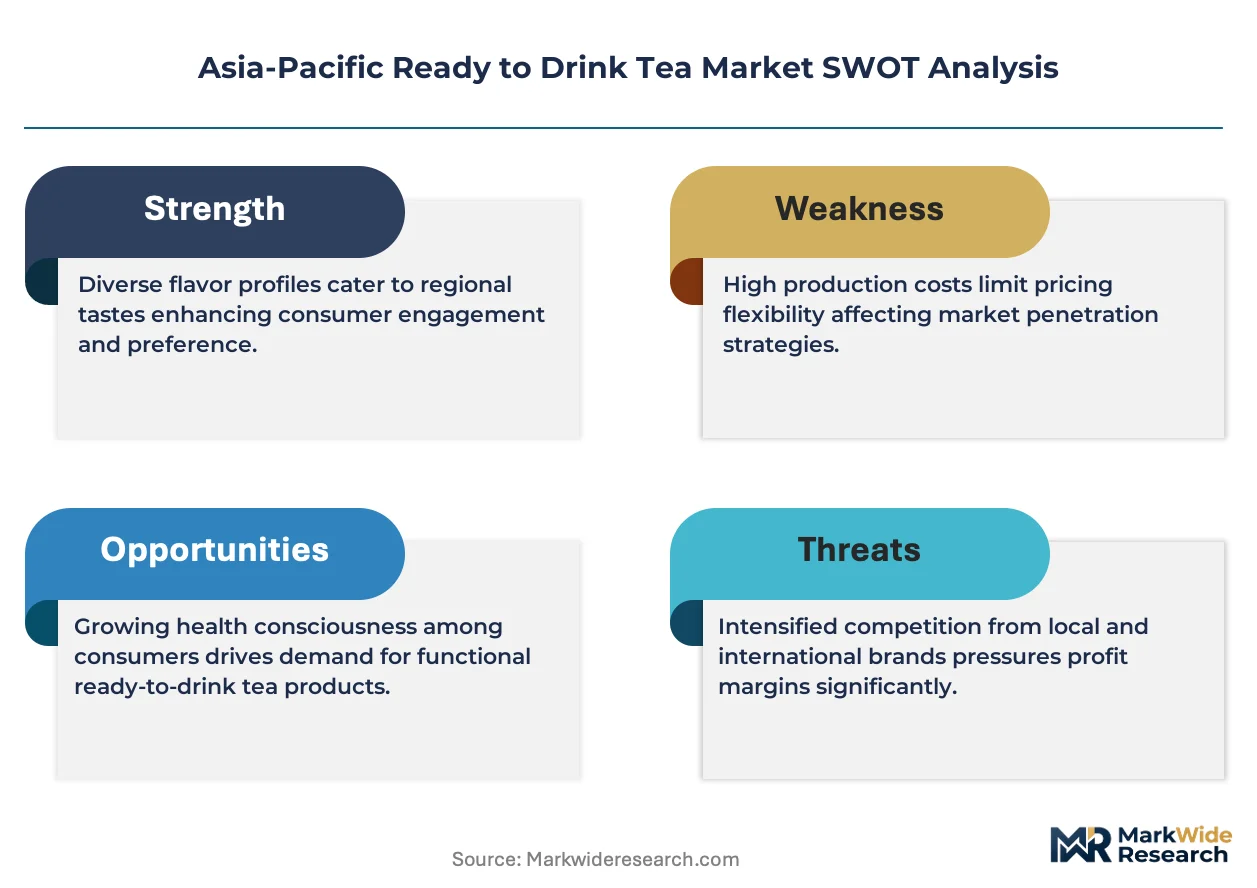
Japan's METI container recycling mandates under the Act on Promotion of Recycling of Resources are forcing capital reallocation across the Asia-Pacific Ready to Drink Tea value chain. Producers must retrofit filling lines for lighter-weight PET and plant-derived materials while maintaining oxygen-barrier performance for polyphenol preservation.
Growth Catalysts
- Urban convenience culture:Young professionals in Shanghai, Mumbai, and Jakarta treat bottled tea as workplace hydration and transit consumption staples. Convenience store penetration in Chinese coastal megacities accelerates impulse purchase frequency.
- FSSAI caffeine disclosure mandates:India's organized retail channel entry now requires labeled caffeine thresholds, standardizing product portfolios and expanding shelf access for compliant brands in modern trade formats.
- Hot-fill to aseptic cold-fill migration:Cold-fill lines preserve volatile aromatic compounds in green tea formulations, unlocking premium positioning in Japanese and South Korean convenience channels.
Market Restraints
- Aluminum and rPET input cost volatility:Lightweighting mandates collide with recycled polymer supply constraints, squeezing margin structures for mid-tier producers dependent on spot-market resin procurement.
- Shizuoka prefecture leaf concentration:Direct-sourced Japanese green tea procurement anchors quality differentiation but exposes supply security to climate volatility in Honshu island cultivation zones.
- Sugar content disclosure friction:China's SAMR GB labeling standards redirect R&D spend toward reformulation, delaying new product pipelines and complicating portfolio architecture across calorie tiers.
Strategic Opportunities
- Tetra Pak aseptic carton penetration:India's urban retail expansion favors ambient carton formats for distribution efficiency in temperature-variable logistics environments, creating white space beyond PET-dominated China.
- Extended producer responsibility tailwinds:Australia's emerging packaging stewardship frameworks reward early movers with compliance credits, incentivizing regional hub investment ahead of mandatory phase-ins.
- Deep well water + cold-fill convergence:Mineral extraction protocols paired with aseptic technology enable unheated processing claims, differentiating premium lines in Thailand's foodservice replacement channel.
Industry Challenges
- Aseptic line engineering talent scarcity:Cold-fill sterilization system design and validation expertise concentrates with European and Japanese equipment OEMs, complicating localized technical workforce development.
- Multi-material supplier network orchestration:Transitioning from single-source PET procurement to bio-based and recycled content portfolios demands new quality assurance protocols and contract structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ready to Drink Tea Market |
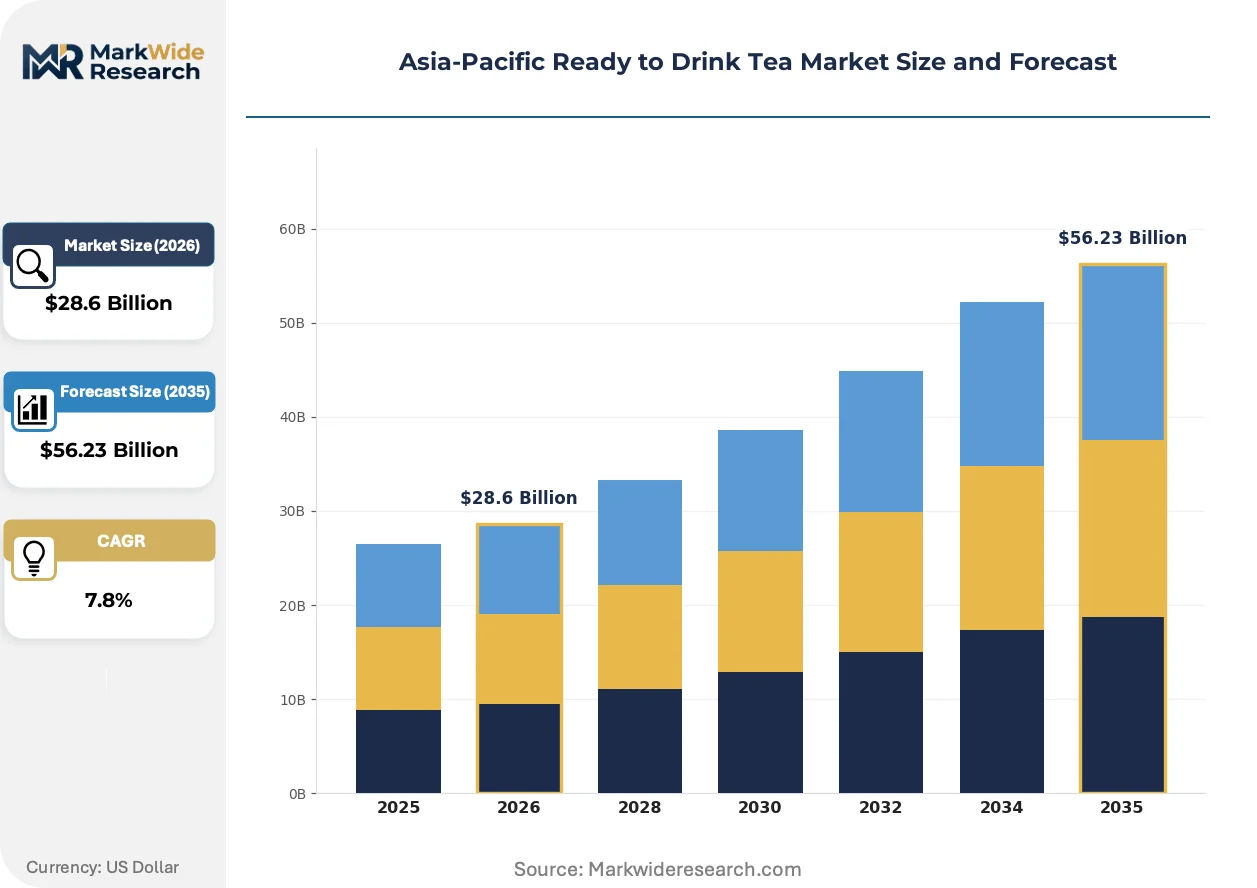
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Oolong Tea Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Packaging Type: Bottles, Cans, Pouches, Tetra Packs Flavor Profile: Peach, Lemon, Mint, Jasmine |
| Companies Covered | Uni-President Enterprises Corp, Asahi Group Holdings Ltd, Ito En Ltd, The Coca-Cola Company, Nestle SA, Suntory Holdings Limited, Nongfu Spring Co Ltd, Kirin Holdings Company Limited, Tingyi (Cayman Islands) Holding Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ready to Drink Tea Market Strategic Shifts
Cold-fill aseptic technology is compressing traditional hot-fill infrastructure economics while regulatory disclosure mandates reshape formulation priorities. Distribution channel fragmentation and material science advances are converging to redefine competitive differentiation.
Aseptic cold-fill processing is overtaking hot-fill methods for premium green tea lines in Japan and South Korea. Convenience store buyers in Tokyo and Seoul now specify non-thermal processing to preserve catechin integrity and volatile aromatic profiles. This technology compression is enabling shorter ingredient lists and cleaner-label positioning against mass-market heat-treated alternatives.
China's SAMR sugar content disclosure requirements under GB standards are redirecting R&D investment toward reduced-calorie formulations and alternative sweetener systems. Manufacturers must redesign label architectures and reformulate legacy black tea portfolios to maintain shelf placement in organized retail. The coastal megacity segment from Shanghai to Guangzhou shows the most aggressive compliance-driven product line pruning.
Procurement patterns in Southeast Asia are fragmenting as foodservice operators unbundle beverage supply from traditional distributor arrangements. Direct manufacturer relationships are replacing layered wholesale structures in Bangkok and Ho Chi Minh City urban cores. This channel disintermediation is most visible in premium on-premise replacement occasions where menu differentiation demands customized formulation and packaging formats.
Asia-Pacific Ready to Drink Tea Market Segmentation
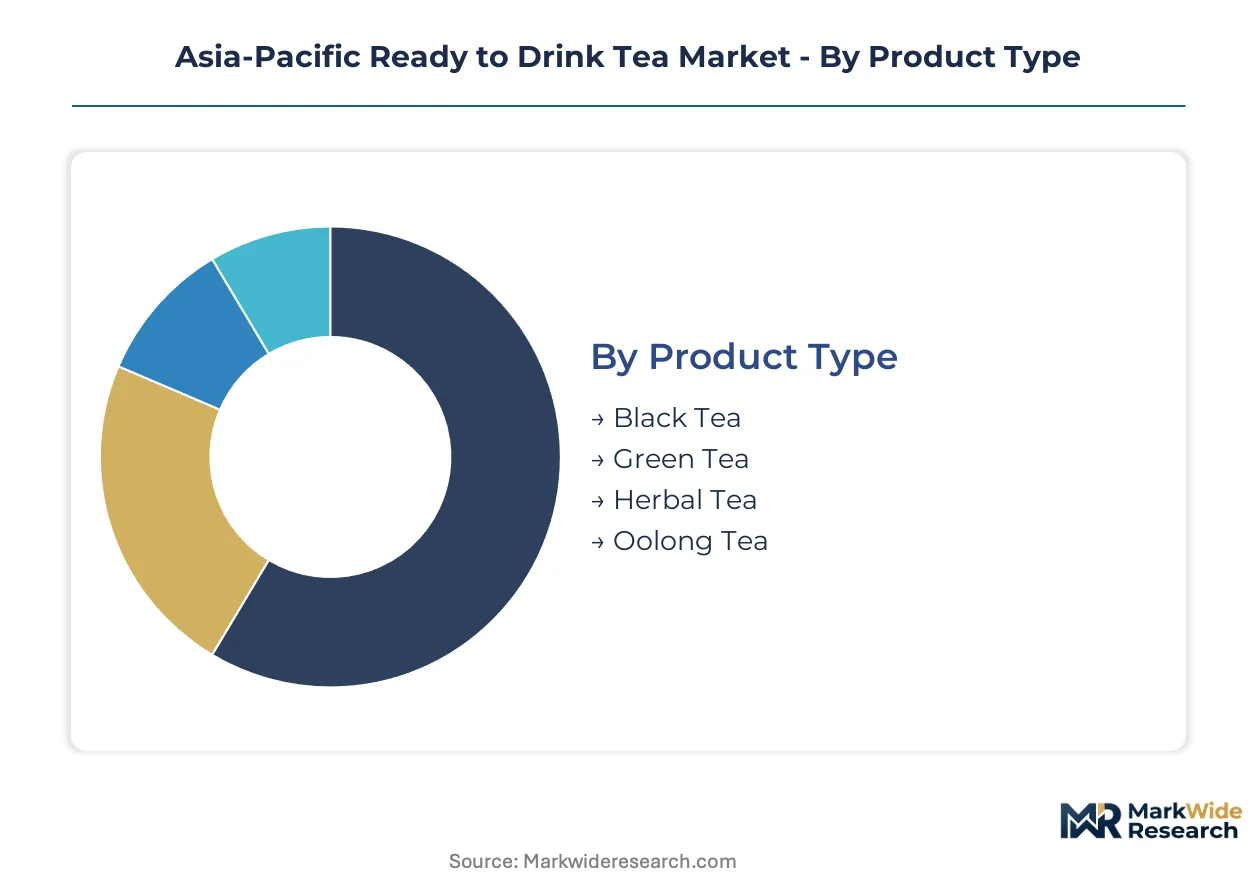
Segmentation in the Asia-Pacific Ready to Drink Tea market reveals how packaging technology, retail format economics, and regional taste preferences create distinct competitive battlegrounds. Producers must align formulation, filling infrastructure, and route-to-market strategies against these dimensions simultaneously.
Product Type:
Consumer willingness to pay premium prices varies sharply across tea bases, with polyphenol retention claims and origin storytelling driving tiered positioning strategies.
- Green Tea:Cold-fill aseptic processing preserves catechin integrity and volatile aromatic compounds. Japanese and South Korean convenience stores command shelf premiums for Shizuoka-sourced formulations with non-thermal processing claims.
- Black Tea:Hot-fill infrastructure dominates mass-market production. Southeast Asian supermarkets from Bangkok to Jakarta drive volume through familiar flavor profiles and cost-optimized PET packaging.
- Herbal Tea:Caffeine-free positioning captures evening consumption occasions. India's FSSAI disclosure mandates accelerate compliant portfolio expansion.
- Oolong Tea:Semi-oxidized processing requires specialized extraction protocols. Taiwan's captive plantation networks supply mainland China premium channels.
Volume sits with Black Tea; growth tilts toward Green Tea.
Distribution Channel:
Route-to-market selection determines margin capture, with cold chain requirements and impulse purchase mechanics creating diverging investment profiles.
- Convenience Stores:Urban China's coastal megacities from Shanghai to Guangzhou generate high-frequency impulse purchases. 24-hour operations and refrigerated grab-and-go fixtures favor premium cold-fill SKUs with shorter ingredient lists.
- Supermarkets:Mass-market volume concentrates in Southeast Asian multi-format retailers. Ambient shelf stability and multi-pack bundling drive procurement decisions.
- Online Retailers:Direct-to-home delivery expands in India's temperature-variable logistics environment. Tetra Pak carton formats reduce breakage risk versus PET bottles.
- Specialty Stores:Curated assortments target gift occasions and health-conscious demographics. Limited distribution footprint demands higher per-unit margins.
Supermarkets dominate transaction volume; Convenience Stores are climbing the fastest.
Packaging Type:
Material science investments and extended producer responsibility frameworks are compressing traditional format economics across the region.
- Bottles:PET retains cost leadership in China's high-throughput distribution environment. Japan's METI recycling mandates accelerate lightweighting and rPET integration.
- Tetra Packs:Aseptic carton technology enables ambient distribution without cold chain infrastructure. India's urban retail expansion favors this format for logistics efficiency.
- Cans:Aluminum input cost volatility squeezes margin structures. Premium positioning in Japanese vending channels sustains niche demand.
- Pouches:Flexible format reduces shipping cube and material weight. Limited oxygen barrier performance constrains polyphenol preservation claims.
Bottles hold installed base dominance; Tetra Packs gain share fastest.
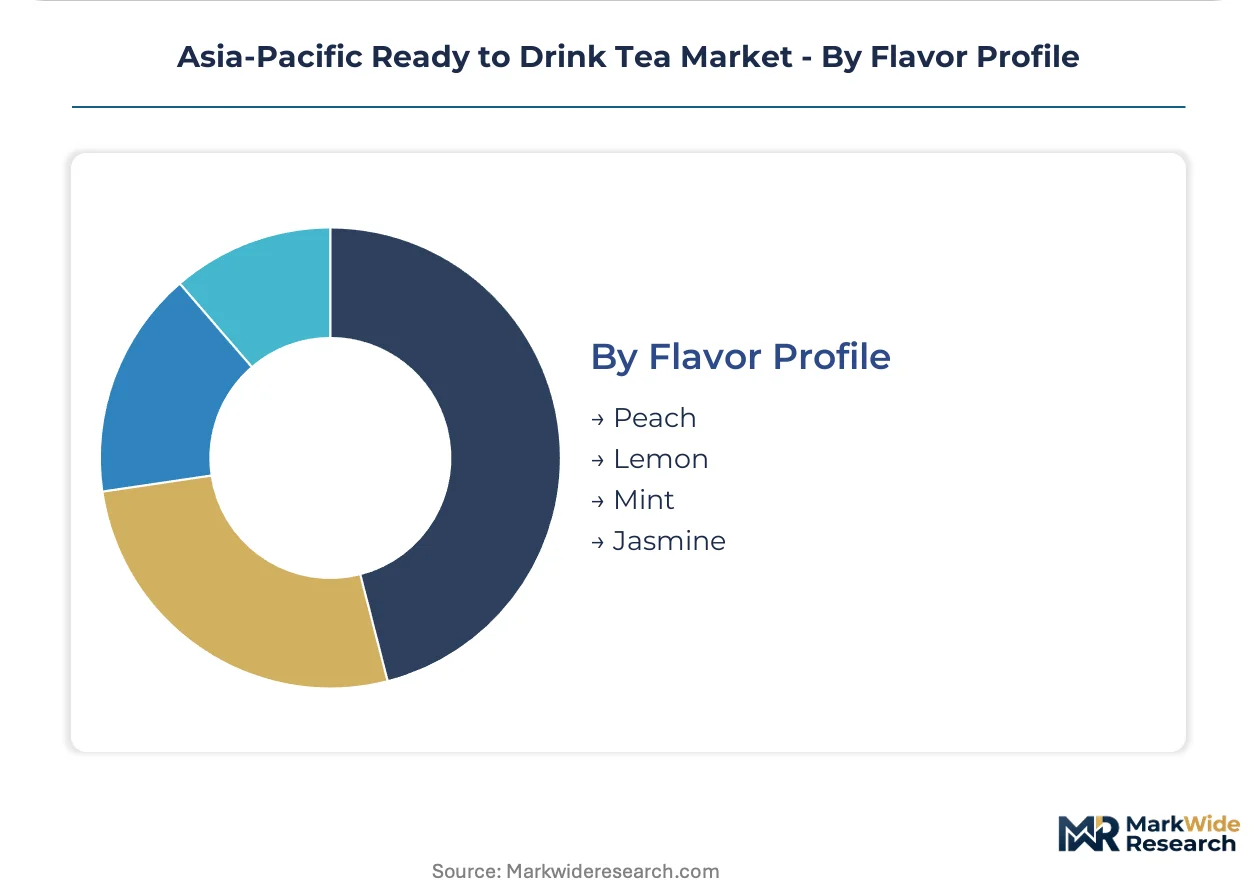
Flavor Profile:
Regional palate preferences and botanical sourcing security shape formulation pipeline priorities and ingredient procurement networks.
- Lemon:Citrus acidification assists pH management for ambient stability. Mass-market black tea formulations across Southeast Asia standardize on this profile.
- Peach:Stone fruit extracts command premium positioning in South Korean and Japanese convenience channels. Synthetic versus natural flavor sourcing creates tiered price architecture.
- Jasmine:Scented green tea variants leverage established Chinese processing expertise. Floral aromatic compounds require careful cold-fill handling.
- Mint:Herbal tea applications target digestive health positioning. Limited cultivation concentration in specific Asian geographies creates supply planning complexity.
Lemon anchors volume deployment; Peach shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shizuoka prefecture tea leaf plantations anchor premium green tea sourcing for Japanese and South Korean formulation networks. China's Yangtze and Pearl River Delta manufacturing clusters drive PET bottle throughput at continental scale. India's Assam and Darjeeling cultivation zones supply black tea extract for mass-market RTD deployment.
China
Coastal megacities from Shanghai to Guangzhou generate high-frequency workplace hydration demand among young professionals. SAMR's GB standards for sugar content disclosure redirect R&D investment toward reduced-calorie black tea portfolios. Yangtze River Delta filling facilities retrofit cold-fill aseptic lines to preserve volatile aromatic compounds in premium green tea SKUs.
Japan
Tokyo and Osaka convenience store channels specify non-thermal processing claims for catechin-retentive green tea positioning. METI's Act on Promotion of Recycling of Resources enforces container recycling quotas and lightweighting mandates. Shizuoka prefecture direct-sourced leaf procurement networks face climate volatility exposure across Honshu island cultivation zones.
India
Mumbai and Delhi urban retail expansion drives Tetra Pak aseptic carton adoption for temperature-variable logistics efficiency. FSSAI caffeine threshold disclosure mandates standardize product portfolios for organized modern trade channel entry. Assam tea extract processing clusters supply black tea concentrate for mass-market PET and carton formulations.
South Korea
Seoul Capital Area convenience store penetration accelerates impulse purchase frequency for premium cold-fill green tea lines. MFDS labeling requirements align with regional disclosure trends for functional beverage claims. Busan-Ulsan manufacturing corridors host aseptic line infrastructure serving both domestic convenience channels and export formulation.
Australia
Sydney and Melbourne metropolitan markets demonstrate emerging demand for plant-derived packaging materials under stewardship frameworks. State-level extended producer responsibility schemes reward early compliance investment with credit accumulation. New South Wales distribution hubs test bio-based bottle formats ahead of mandatory recycling phase-ins.
Asia-Pacific Ready to Drink Tea Market Competitive Environment
Capacity expansion dominates the current landscape as producers retrofit filling lines for lightweight PET and cold-fill aseptic technology. The market structures around three tiers: integrated beverage conglomerates with captive bottling infrastructure, regional specialists with direct agricultural sourcing relationships, and contract manufacturers serving private-label retail programs. Strategic archetypes include plantation-integrated formulators, mineral water-anchored diversified players, and multinational soft drink portfolio extenders. Competitive moves concentrate on cold-fill technology licensing and multi-material supplier network orchestration.
Within the plantation-integrated tier, Ito En Ltd exemplifies direct-sourced leaf procurement from named cultivation zones, while Uni-President Enterprises Corp represents captive bottling infrastructure spanning Taiwan and mainland China manufacturing nodes. Nongfu Spring Co Ltd anchors the mineral-extraction-differentiated archetype through deep well water sourcing protocols. These three entities occupy distinct competitive positions without overlapping strategic emphasis on processing technology, agricultural integration, or water resource control.
| Leading Market Players |
|---|
| Uni-President Enterprises Corp |
| Asahi Group Holdings Ltd |
| Ito En Ltd |
| The Coca-Cola Company |
| Nestle SA |
| Suntory Holdings Limited |
| Nongfu Spring Co Ltd |
| Kirin Holdings Company Limited |
| Tingyi (Cayman Islands) Holding Corporation |
| Others |
Value Chain & Pricing Dynamics
Cold-fill aseptic line migration simultaneously compresses hot-fill infrastructure economics and concentrates processing capability among equipment holders with validated sterilization protocols. This technology shift redraws margin structures as premium green tea positioning in Japanese and South Korean convenience channels commands catechin-retention premiums while mass-market black tea segments face cost-optimized PET bottling pressure.
Pricing Analysis
Service bundling separates equipment-validated aseptic processing claims from unbundled hot-fill commodity production, with cold-fill warranties carrying premium markups for polyphenol preservation guarantees. Three-tier pricing structure across premium cold-fill green tea, standard hot-fill black tea, and economy private-label tiers reflects quality grade and processing technology differentiation. Pricing pressure stems from aluminum and rPET input cost volatility squeezing mid-tier producers dependent on spot-market resin procurement. Mass-market supermarket buyers in Southeast Asia exhibit highest price sensitivity, while Japanese convenience store channels demonstrate lowest sensitivity for certified Shizuoka-sourced formulations.
Supply Chain Analysis
Regional distribution centers in China's Yangtze River Delta and Pearl River Delta manufacturing clusters anchor hub-and-spoke patterns serving coastal megacity demand. Geographic supply concentration centers on China for PET resin and filling infrastructure, Japan for Shizuoka prefecture tea leaf procurement, and India for Assam black tea extract processing. Raw material dependencies include tea leaf concentrates, oxygen-barrier packaging substrates, and aseptic validation chemicals. Single-source vulnerability in Shizuoka cultivation zones exposes premium green tea networks to climate disruption. Distribution runs through layered wholesale structures in Southeast Asia and direct-manufacturer relationships in disintermediating Bangkok and Ho Chi Minh City urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where METI recycling mandates and cold-fill capital requirements force weaker players toward contract manufacturing or exit. Compliance-driven packaging transitions and aseptic line engineering scarcity accelerate shakeout timelines.
For Market Incumbents: Hedge Shizuoka supply concentration by diversifying leaf procurement into Taiwan oolong networks and Vietnam herbal cultivation zones. Lock in multi-year rPET supply contracts before Australia's extended producer responsibility frameworks tighten recycled content mandates. Prioritize cold-fill capacity addition in Busan-Ulsan corridors to capture Seoul Capital Area premium channel growth. For New Entrants and Emerging Players: Aseptic carton technology-first wedge opens India's Tetra Pak-favoring urban retail expansion where temperature-variable logistics disadvantage PET-dependent incumbents. Target Mumbai and Delhi modern trade channels with FSSAI-compliant caffeine-disclosed herbal tea portfolios. Pursue direct foodservice relationships in Bangkok's unbundling beverage supply environment for customized formulation contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in mineral water-anchored diversified players with deep well extraction protocols and captive cold-fill infrastructure. Long-term viability favors entities controlling both upstream agricultural sourcing and downstream aseptic processing validation. Watch Australia's state-level packaging stewardship credit accumulation rates as inflection indicator for regional hub investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Aseptic Line Retrofit | Preserves catechin integrity for premium Japanese convenience store positioning against heat-treated alternatives. |
| Multi-Material Supplier Network Orchestration | Enables rPET and plant-derived packaging compliance under Japan's METI recycling quota enforcement. |
| Direct-Sourced Tea Leaf Procurement | Secures Shizuoka cultivation zone access for quality differentiation in South Korean premium channels. |
| Tetra Pak Aseptic Carton Penetration | Captures India's urban retail expansion with ambient distribution efficiency in temperature-variable logistics. |
| Deep Well Water Extraction Protocol | Differentiates premium lines through unheated processing claims in Thailand's foodservice replacement channel. |
Study Parameters
Multi-period observation of filling line investment patterns, regulatory disclosure compliance timelines, and convenience store SKU proliferation anchored the trend analysis, supplemented by interviews with beverage brand managers, category buyers at Chinese coastal retailers, aseptic equipment OEM technical directors, and FSSAI regulatory affairs leads. Secondary validation drew from SAMR GB standard filings, METI recycling quota documentation, Tetra Pak format adoption data in Indian modern trade, and customs records for PET resin and tea extract trade flows. Bottom-up facility capacity estimates triangulated against top-down retail audit data.
Input-output matrices modeled volume and value trajectories across tea base type, processing technology tier, packaging format, distribution channel economics, and regional regulatory cluster intensity throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and demographic urbanization patterns. Industry-specific forecast inputs included convenience store penetration rates in Chinese coastal megacities and FSSAI caffeine disclosure compliance timelines for organized retail channel entry.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate disruption scenarios in Honshu island cultivation zones and abrupt rPET supply constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Floral Tea Market
Tea
Tea Packaging Market
Tea
Instant Tea Premix Consumption Market
Tea
Bottled Milk Tea Market
Tea
Mate Tea Market
Tea
Asia-Pacific Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Natural Tea Extract Market
Tea
Global Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Green Tea Market
Tea
Global Catechin Market
Tea
APAC RTD Tea Market
Tea
Fermented Tea Market
Tea
Probiotic Tea Market
Tea
Africa Ready to Drink Tea Market