
 Natural Tea Extract Market | 2026-2036
Natural Tea Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Tea Extract Market Insights
Botanical extracts from standardized tea polyphenols is rebalancing cost structures across functional beverage and nutraceutical supply chains. Givaudan leverages captive sourcing relationships with tea-growing cooperatives to secure catechin-rich raw material streams. Kerry Group anchors its position through integrated extraction-to-flavor formulation capabilities across European and North American facilities. Taiyo International specializes in Sunphenon-grade green tea extract production, dominating high-purity EGCG supply for dietary supplement clients.
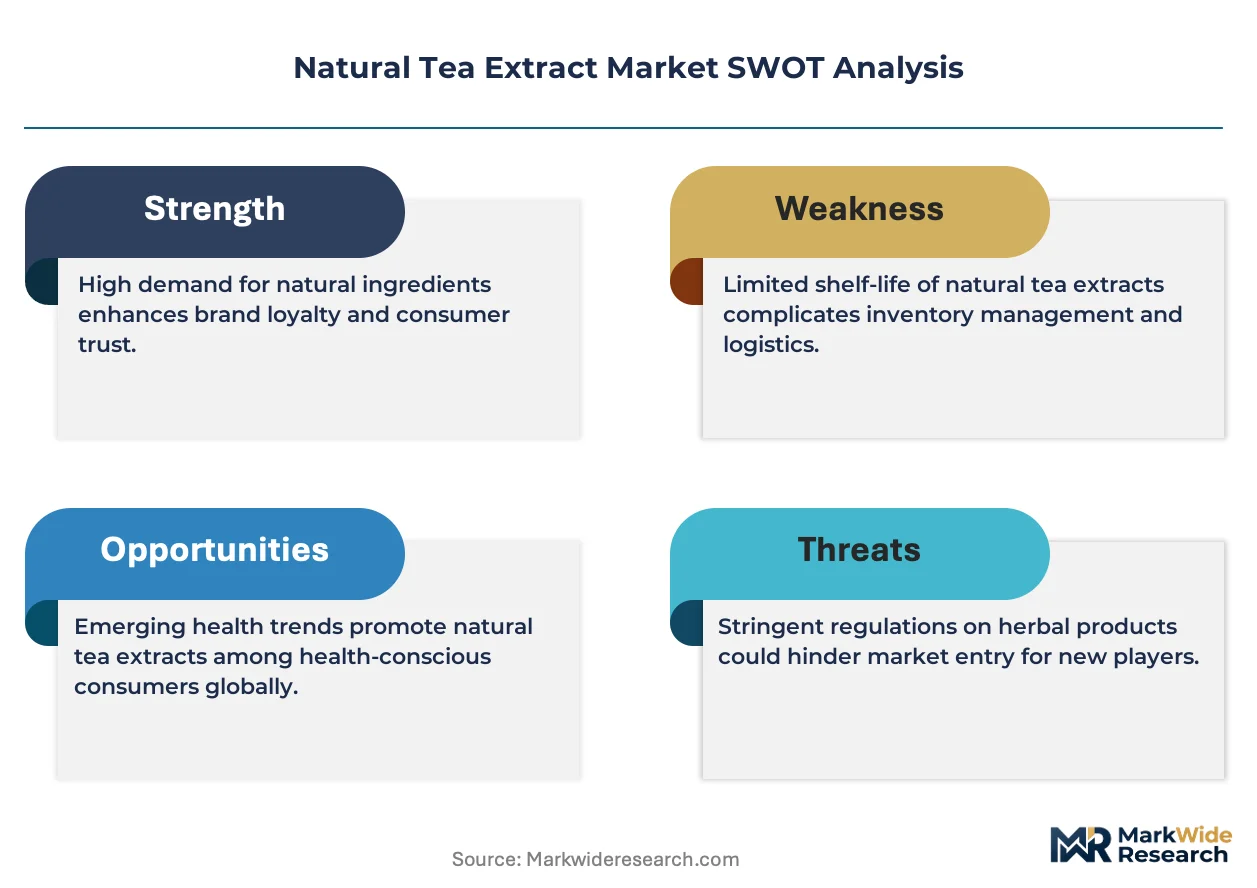
Natural tea extract comprises concentrated bioactive compounds—primarily catechins, theaflavins, and L-theanine—isolated from Camellia sinensis leaves through solvent or supercritical CO2 processing, typically standardized to 50-95% polyphenol content for reproducible functional performance. Green tea extract leads product type demand due to established clinical validation of EGCG antioxidant properties, while black tea extract gains traction in cosmetic applications leveraging theaflavin anti-inflammatory credentials. Supercritical CO2 extraction commands premium positioning among extraction methods for solvent-free certification compliance, though ultrasonic extraction scales more aggressively in mid-tier dietary supplement supply.
FDA GRAS self-affirmation requirements and EFSA novel food authorization frameworks shape ingredient market access timelines for tea extract suppliers targeting fortified food applications. REACH registration obligations and EU Green Deal sustainable sourcing mandates are forcing extraction facilities to document supply chain traceability from plantation to isolate. Stakeholders must monitor evolving pharmacovigilance expectations from EMA and national regulators as tea extract dosage thresholds in pharmaceutical-grade applications attract tighter toxicological scrutiny.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are compressing approval timelines for tea extract suppliers while concentrating procurement among vertically integrated botanical processors capable of documenting plantation-to-isolate traceability.
Growth Catalysts
- EFSA Novel Food Authorization:Fortified food manufacturers across the European Union are accelerating tea extract incorporation as novel food pathways clarify dosage thresholds for catechin-enriched products.
- Supercritical CO2 Extraction:Solvent-free certification compliance is commanding premium positioning among extraction methods, with dietary supplement brands prioritizing CO2-processed EGCG isolates for label transparency.
- Zhejiang Province Cultivation Clusters:Raw material concentration in China's tea-growing heartland is reducing procurement friction for extraction facilities expanding polyphenol isolation capacity.
Market Restraints
- Camellia sinensis Leaf Price Volatility:Weather-induced harvest fluctuations in Yunnan and Assam are transmitting cost instability through upstream extract supply chains.
- REACH Registration Burden:European extraction facilities face documentation-intensive obligations for tea-derived isolates under ECHA chemical safety frameworks.
- Synthetic Antioxidant Substitution:Butylated hydroxytoluene and tertiary butylhydroquinone retain cost advantages in mass-market beverage applications despite clean-label headwinds.
Strategic Opportunities
- Brazil Cosmetic Formulation Pipeline:ANVISA regulatory harmonization is opening formulation pathways for theaflavin-rich black tea extracts in dermocosmetic anti-inflammatory applications.
- EU Green Deal Sustainable Sourcing Mandates:Carbon footprint documentation requirements are creating first-mover advantages for extraction facilities with certified organic plantation partnerships.
- Ultrasonic-Assisted Extraction Convergence:Mid-tier dietary supplement manufacturers are adopting hybrid ultrasonic-CO2 processing to balance purity credentials with throughput scaling.
Industry Challenges
- Phytochemist Talent Scarcity:Standardization of catechin content to 95% polyphenol thresholds requires specialized analytical chemistry capabilities that extraction facilities struggle to recruit.
- EMA Pharmacovigilance Escalation:Toxicological scrutiny of EGCG dosage thresholds in pharmaceutical-grade applications is extending clinical validation timelines for new extract entrants.
- Legacy ERP Integration Friction:Plantation-to-isolate traceability systems are colliding with established inventory management platforms at mid-sized botanical processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Tea Extract Market |
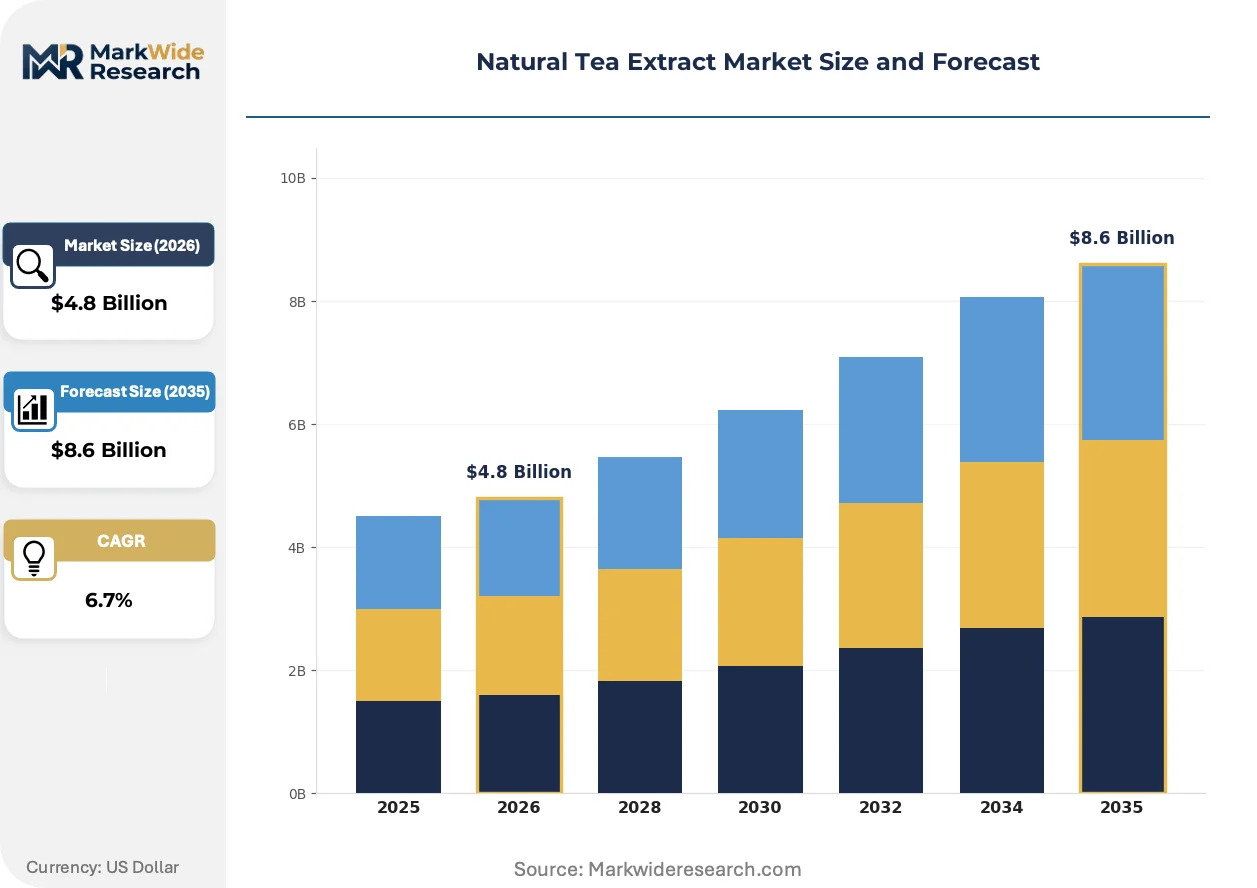
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea Extract, Black Tea Extract, White Tea Extract, Oolong Tea Extract, Pu-erh Tea Extract Application: Dietary Supplements, Functional Beverages, Cosmetics, Pharmaceuticals, Nutraceuticals Extraction Method: Soxhlet Extraction, Ultrasonic Extraction, Microwave-Assisted Extraction, Cold Press Extraction, Supercritical CO2 Extraction End User Industry: Food & Beverage Manufacturers, Personal Care Brands, Pharmaceutical Companies, Sports Nutritionists, Wellness Centers |
| Companies Covered | Givaudan, Indena S.p.A., Kerry Group, Taiyo International, Martin Bauer Group, Finlays, ADM, Kemin Industries, AVT Natural Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Tea Extract Market Trends and Innovations
Extraction technology evolution and regulatory documentation requirements are compressing the supplier base toward integrated processors while opening formulation pathways in adjacent verticals.
Supercritical CO2 extraction with integrated fractionation is rewriting purity-versus-yield tradeoffs for high-EGCG green tea isolates. Pharmaceutical-grade dietary supplement manufacturers are adopting this technology at accelerated procurement cycles. The structural consequence is marginalizing solvent-based extraction capacity in premium segments while ultrasonic methods capture mid-tier volume.
REACH registration obligations combined with EU Green Deal sustainable sourcing mandates are forcing extraction facilities to deploy blockchain-enabled plantation documentation. ECHA compliance timelines now extend 18-24 months for novel tea-derived isolates. European functional beverage brands are responding by consolidating supplier relationships with vertically integrated processors possessing established registration portfolios.
Clean-label certification is driving buyer preference toward polyphenol standardization transparency rather than bulk volume pricing. Direct contracting between functional beverage formulators and extraction facilities is displacing traditional botanical ingredient distributors. This pattern concentrates in North American markets where FDA GRAS self-affirmation documentation carries explicit liability weight.
Natural Tea Extract Market Segmentation
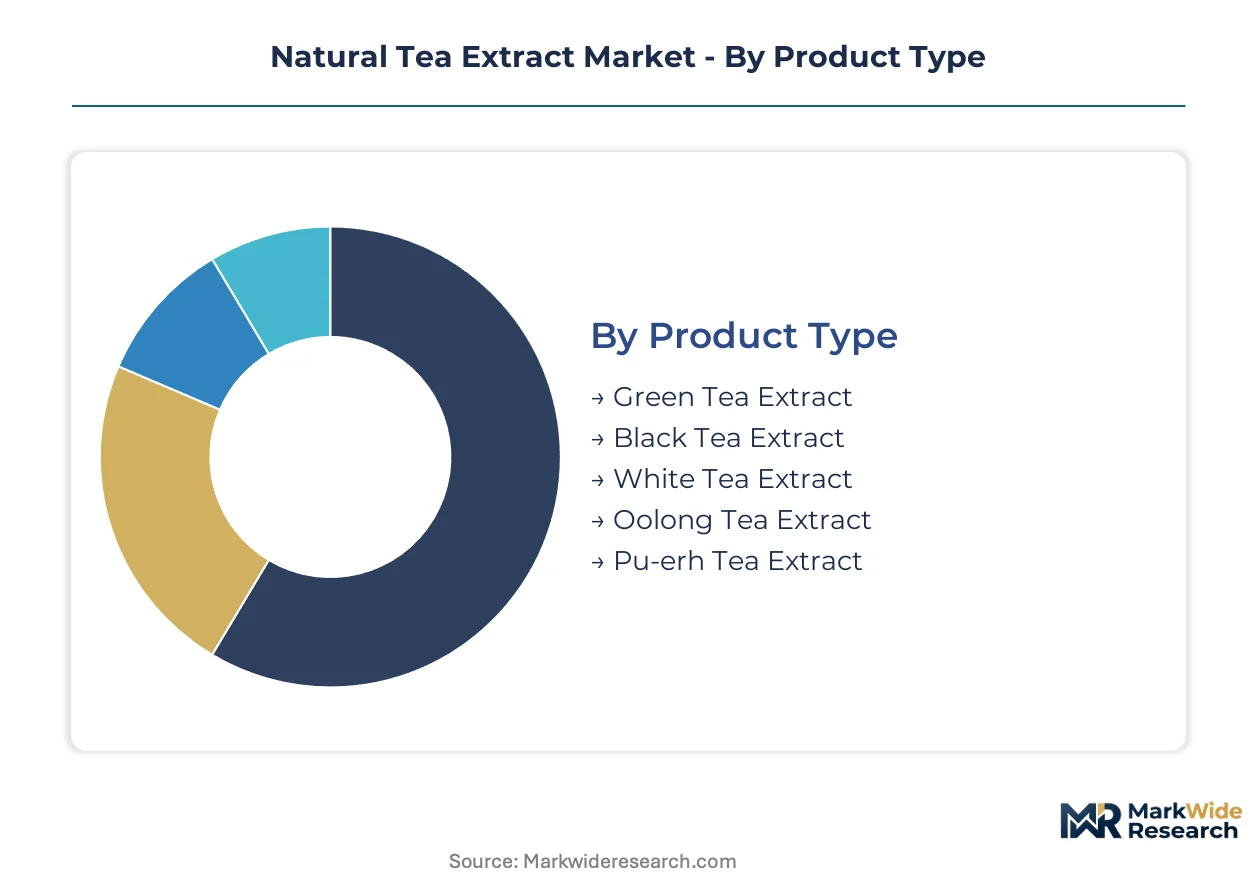
Product type differentiation in natural tea extract markets centers on polyphenol composition profiles that determine end-use suitability. Extraction method selection directly shapes certification compliance and procurement economics across pharmaceutical and nutraceutical supply chains.
Product Type:
Polyphenol standardization thresholds vary significantly across Camellia sinensis processing variants, creating tiered supply relationships with distinct end-use industries.
- Green Tea Extract:Standardized to 50-95% EGCG content for antioxidant applications. Demand concentrates in North American dietary supplement manufacturing where FDA GRAS self-affirmation documentation carries explicit liability weight for catechin dosage formulations.
- Black Tea Extract:Rich in theaflavins and thearubigins with documented anti-inflammatory properties. Procurement is accelerating among European cosmetic formulators responding to EFSA novel food authorization clarity for dermocosmetic applications.
- White Tea Extract:Minimal processing preserves delicate catechin profiles for premium skincare lines.
- Oolong Tea Extract:Partial oxidation delivers intermediate polyphenol complexity for traditional medicine applications.
- Pu-erh Tea Extract:Post-fermentation chemistry targets digestive health positioning in Asian nutraceutical markets.
Mature deployment sits with Green Tea Extract. Newer deployment is concentrated in Black Tea Extract.
Application:
Regulatory pathway complexity fragments procurement patterns across functional food, pharmaceutical, and cosmetic verticals with divergent documentation requirements.
- Dietary Supplements:Capsule and tablet formulations demanding 95% polyphenol standardization with third-party HPLC verification. Volume leadership belongs to North American contract manufacturers serving direct-to-consumer wellness brands.
- Functional Beverages:Ready-to-drink fortification requiring heat-stable extract forms for pasteurization compatibility. Clean-label mandates from EFSA and FDA are compressing supplier qualification timelines toward vertically integrated processors.
- Cosmetics:Topical anti-aging and anti-inflammatory formulations leveraging theaflavin-rich isolates.
- Pharmaceuticals:Investigational drug applications subject to EMA pharmacovigilance escalation for EGCG toxicological thresholds.
- Nutraceuticals:Positioned between food and drug classifications with evolving novel food frameworks.
Volume concentration rests with Dietary Supplements. Margin expansion is steepest in Pharmaceuticals.
Extraction Method:
Capital intensity and solvent residue specifications create stratified competitive positions between premium certification-grade and mid-tier volume processors.
- Supercritical CO2 Extraction:Solvent-free processing yielding pharmaceutical-grade isolates with documented terpene preservation. European extraction facilities deploy this technology to satisfy REACH registration obligations and EU Green Deal carbon footprint documentation mandates.
- Ultrasonic Extraction:Mechanical cavitation reducing processing time while maintaining moderate polyphenol yields. Mid-tier dietary supplement manufacturers in China adopt hybrid ultrasonic-CO2 configurations to balance purity credentials with throughput scaling.
- Soxhlet Extraction:Conventional solvent-based processing with established cost structures for commodity-grade applications.
- Microwave-Assisted Extraction:Rapid heating profiles suited for pilot-scale botanical research.
- Cold Press Extraction:Minimal thermal degradation for premium cosmetic oil co-extraction.
Certification-grade supply concentrates in Supercritical CO2 Extraction. Throughput scaling favors Ultrasonic Extraction.
End User Industry:
Downstream consolidation patterns concentrate procurement power among multinational formulators with captive quality assurance capabilities.
- Food & Beverage Manufacturers:Multi-ton procurement contracts requiring plantation-to-isolate traceability systems. North American functional beverage brands are displacing traditional botanical distributors through direct extraction facility contracting.
- Personal Care Brands:Clean-label positioning demands driving preference for organic-certified raw material streams with blockchain-enabled documentation.
- Pharmaceutical Companies:Clinical-grade extract specifications with extended EMA validation timelines.
- Sports Nutritionists:Niche formulation expertise in ergogenic catechin applications.
- Wellness Centers:Direct-to-consumer extract dispensing with limited regulatory oversight.
Procurement volume leadership sits with Food & Beverage Manufacturers. Documentation sophistication is climbing fastest in Personal Care Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement gravity for natural tea extract concentrates in China, where Zhejiang and Yunnan provinces anchor both cultivation and extraction capacity expansion. Functional beverage manufacturers in the United States and Germany are accelerating direct contracting with vertically integrated processors.
China
Polyphenol-rich extract demand from domestic nutraceutical manufacturers and export-oriented dietary supplement brands drives volume. SAMR's tightening clean-label enforcement compresses supplier qualification timelines toward documented plantation-to-isolate traceability. Hangzhou and Kunming extraction clusters are expanding supercritical CO2 capacity to serve pharmaceutical-grade EGCG specifications.
United States
FDA GRAS self-affirmation requirements for fortified functional beverages concentrate procurement among vertically integrated botanical processors. Kerry Group and ADM anchor North American extraction-to-formulation capabilities across Midwest and Northeast facilities. Chicago and New Jersey processing hubs are displacing traditional botanical distributors through direct brand contracting.
Germany
EFSA novel food authorization clarity accelerates catechin-enriched product development across functional food manufacturers. REACH registration obligations and EU Green Deal carbon footprint documentation mandate blockchain-enabled plantation traceability from extraction facilities. Hamburg and Bavaria processing centers dominate pharmaceutical-grade isolate production for European dietary supplement brands.
India
Domestic Ayurvedic medicine manufacturers and export-oriented cosmetic formulators drive theaflavin-rich black tea extract procurement. FSSAI standardization requirements for botanical ingredients tighten analytical chemistry documentation thresholds. Assam and Darjeeling cultivation belts are integrating backward into extraction capacity to capture margin from isolate exports.
Brazil
ANVISA regulatory harmonization opens formulation pathways for theaflavin-rich extracts in dermocosmetic anti-inflammatory applications. Clean-label positioning among São Paulo-based personal care brands drives preference for organic-certified raw material streams. Southern cultivation regions are scaling extraction partnerships to serve Latin American cosmetic manufacturers.
Natural Tea Extract Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ingredient-grade suppliers capturing premium pricing through certification documentation while toll processors compete on throughput scale. The vendor base concentrates among three strategic archetypes: vertically integrated botanical processors with captive plantation relationships, extraction technology specialists with supercritical CO2 capabilities, and diversified flavor houses with integrated formulation services. Competitive moves center on M&A consolidation of mid-tier extraction facilities and geographic expansion of plantation partnerships to satisfy EU Green Deal traceability mandates.
Among the integrated processor tier, Givaudan and Kerry Group exemplify the extraction-to-formulation model, with the former leveraging captive sourcing cooperatives and the latter anchoring position through North American and European facility networks. Taiyo International occupies a specialized position in high-purity EGCG supply, representing the technology-driven archetype that dominates pharmaceutical-grade dietary supplement channels. Indena S.p.A. and Martin Bauer Group sit within the European botanical processing tradition, with Italian and German origins respectively signaling regulatory compliance sophistication for EFSA and REACH frameworks.
| Leading Market Players |
|---|
| Givaudan |
| Indena S.p.A. |
| Kerry Group |
| Taiyo International |
| Martin Bauer Group |
| Finlays |
| ADM |
| Kemin Industries |
| AVT Natural Products |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between supercritical CO2-extracted isolates and solvent-processed commodity grades manifests in parallel supply chain configurations, with pharmaceutical-grade EGCG streams commanding plantation-to-isolate traceability investments that commodity ultrasonic extraction avoids entirely.
Pricing Analysis
Volume-midpoint extraction runs through ultrasonic-assisted processing with hybrid CO2 finishing, while margin peaks sit with pharmaceutical-grade supercritical isolates. Three-tier pricing structure across premium, standard, and economy levels separates solvent-free certified EGCG from mid-tier polyphenol concentrates and commodity-grade bulk extracts. Pricing pressure stems from synthetic antioxidant substitution in mass-market beverage applications, where BHT and TBHQ retain cost advantages despite clean-label headwinds. Contract manufacturers serving direct-to-consumer wellness brands exhibit highest price sensitivity; pharmaceutical-grade dietary supplement channels show least elasticity due to EMA toxicological scrutiny requirements.
Supply Chain Analysis
Camellia sinensis leaf supply rests on cultivation clusters in China, India, and Kenya, with Zhejiang and Yunnan provinces anchoring both raw material concentration and extraction capacity expansion. Polyphenol-rich feedstock, pharmaceutical-grade CO2 equipment, and HPLC verification capabilities constitute critical input dependencies. Single-source vulnerability concentrates in Yunnan harvest fluctuations, where weather-induced leaf price volatility transmits cost instability through upstream extract supply chains. Distribution runs through direct contracting between functional beverage formulators and vertically integrated processors, displacing traditional botanical ingredient distributors in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction capacity scarcity props pricing power among certified-grade suppliers, constraining supply expansion for pharmaceutical-grade EGCG specifications and sustaining margin premiums through the forecast horizon.
For Market Incumbents: Deploy blockchain-enabled plantation documentation to defend against REACH registration burden escalation and EU Green Deal traceability mandates. Secure captive sourcing cooperatives in Zhejiang Province to anchor polyphenol feedstock control. Accelerate M&A consolidation of mid-tier ultrasonic extraction facilities facing legacy ERP integration friction.
For New Entrants and Emerging Players: Capture Brazilian dermocosmetic formulation pathways opened by ANVISA regulatory harmonization for theaflavin-rich black tea extracts. Target ultrasonic-CO2 hybrid processing configurations to serve mid-tier dietary supplement manufacturers balancing purity credentials with throughput scaling. Lead with organic-certified raw material partnerships to satisfy EU Green Deal carbon footprint documentation requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated processors possessing established EFSA novel food authorization portfolios given accelerating fortified food development across European functional beverage manufacturers. Prioritize acquisition targets with SAMR-compliant traceability systems and Hangzhou or Kunming extraction cluster presence. Watch EMA pharmacovigilance escalation on EGCG dosage thresholds as inflection indicator for pharmaceutical-grade channel viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Partnerships | Captures margin from leaf to isolate while satisfying EU Green Deal traceability mandates. |
| Supercritical CO2 Capacity Expansion | Positions extraction facilities for pharmaceutical-grade EGCG specifications under EMA scrutiny. |
| EFSA Novel Food Authorization Investment | Accelerates market access timelines for catechin-enriched fortified food applications. |
| Blockchain-Enabled Traceability Deployment | Documents plantation-to-isolate carbon footprint for REACH registration compliance. |
| Ultrasonic-CO2 Hybrid Processing Adoption | Balances purity credentials with throughput scaling for mid-tier dietary supplement supply. |
Research Methodology
Trade databases, EFSA novel food authorization filings, and SEC 10-K disclosures from publicly listed botanical processors formed the secondary backbone, cross-referenced against primary interviews with extraction facility plant managers, functional beverage formulation directors, dietary supplement contract manufacturers, and SAMR regulatory consultants. Bottom-up volume modeling from individual extraction facility capacities combined with top-down demand aggregation across end-use verticals to establish market sizing triangulation.
Historical trendline analysis of polyphenol standardization thresholds, extraction technology adoption curves, and regulatory authorization timelines informed projection frameworks across the modeling period. Segmentation dimensions encompassed product type, application, extraction method, and end-user industry, with CAGRs derived from slope analysis of standardized extract pricing trajectories and capacity expansion announcements. Forecast inputs incorporated Camellia sinensis harvest variability indices and clean-label certification penetration rates by geography.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA pharmacovigilance rulings on EGCG toxicological thresholds and weather-induced leaf price volatility in Yunnan. Forecasts reflect documented assumptions on regulatory pathway clarity and extraction technology cost curves. A small set of named triggers—SAMR enforcement escalation, ANVISA harmonization completion, and supercritical CO2 equipment lead times—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Matcha Products Market
Tea
Asia-Pacific Tea Market
Tea
Tea Essence Market
Tea
Herbal Tea Market
Tea
Global Catechin Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
RTD Tea Market
Tea
Slimming Tea Market
Tea
Detox Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Tea Concentrate Market
Tea
Plant Based New Tea Drink Market
Tea
High Protein Tea Market
Tea
US Ready to Drink Tea Market
Tea
Fermented Tea Market
Tea
North America Ready-To-Drink Tea Market