
 Metallic Labels Market | 2026-2036
Metallic Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Labels Market Foresight
Modular packaging configurations with detachable metallic identification tags is hardening across industrial supply chains. Avery Dennison Corporation leverages its pressure-sensitive adhesive portfolio to dominate high-specification electronics labeling. 3M Company anchors its position through captive supply of specialty films and substrates for harsh-environment applications. Consolidated Label specializes in short-run custom metallic finishes for premium consumer goods brands seeking differentiation.
Metallic labels are substrate-based identification products manufactured from aluminum, stainless steel, brass, or copper, typically processed through etching, anodizing, or screen-printing to achieve durable marking resistant to corrosion, abrasion, and temperature extremes. Their primary purpose is to provide permanent product identification, branding, traceability, and regulatory compliance marking across industrial and consumer applications. Aluminum labels lead volume due to cost efficiency and lightweight properties, while stainless steel commands premium positioning in chemical-processing and marine environments where salt spray resistance is mandatory. Pressure-sensitive adhesive formats are displacing mechanical fastening in automotive assembly lines, reducing installation labor and enabling curved-surface application.
EPA guidelines govern volatile organic compound emissions from adhesive formulations used in U.S.-manufactured metallic labels, while REACH restricts Substances of Very High Concern in European-imported products. ISO 9001 quality management certification and IEC standards for electronics marking shape supplier qualification criteria across OEM procurement teams. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and California that will mandate recycled content thresholds in metal substrates.
Market Dynamics
Pressure-sensitive adhesive formats are displacing mechanical fastening across automotive assembly lines, compressing installation labor while enabling curved-surface application on complex component geometries. This substrate-format transition is reshaping supplier qualification criteria and procurement specifications across industrial OEMs.
Growth Catalysts
- REACH compliance mandates:European Substances of Very High Concern restrictions are forcing material disclosure upgrades across adhesive chemistries, creating specification pull for certified metallic label suppliers.
- Automotive traceability requirements:Parts manufacturers are expanding metallic label procurement for component-level identification to satisfy warranty tracking and recall management protocols.
- Germany's precision equipment standards:Industrial corridor concentration around Munich and Stuttgart is generating demand for corrosion-resistant anodized aluminum labels in machine tool and automation equipment.
Market Restraints
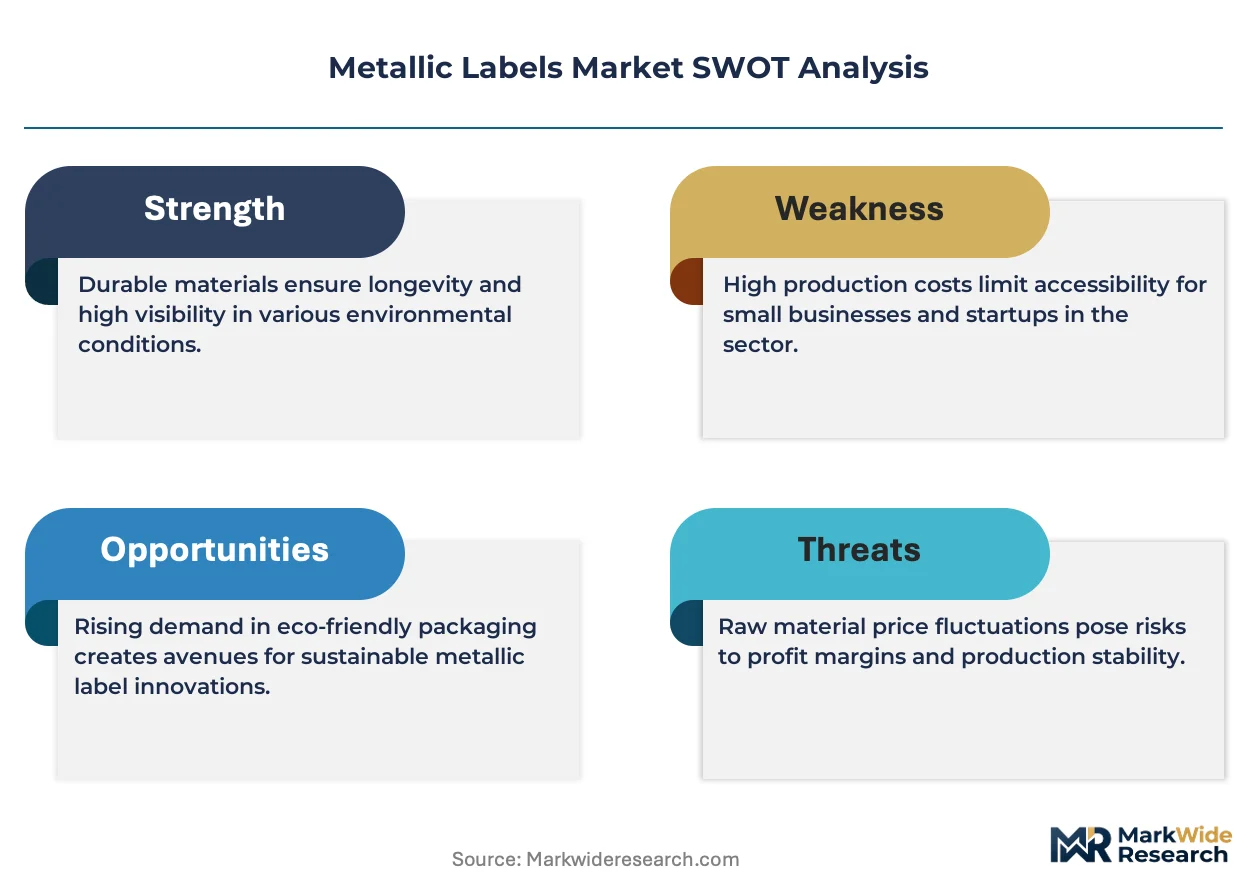
- Specialty film supply concentration:Captive production of polyester and polyimide substrates by integrated chemical conglomerates limits independent label converter margin flexibility.
- EPA VOC emission thresholds:Volatile organic compound limits on adhesive formulations increase compliance costs for U.S.-based manufacturing operations.
- Digital printing substitution:Variable-data inkjet and laser marking systems threaten short-run metallic label volumes in electronics and consumer goods applications.
Strategic Opportunities
- Extended producer responsibility frameworks:EU and California mandates for recycled metal content thresholds will favor converters with closed-loop aluminum sourcing capabilities.
- Modular detachable tag configurations:Supply chains are adopting separable metallic identification elements for reverse logistics and asset recovery programs.
- Marine environment specification gaps:Salt-spray-resistant stainless steel labels remain underpenetrated in offshore wind and shipbuilding sectors outside Northern Europe.
Industry Challenges
- Anodizing chemistry expertise shortage:Skilled technicians capable of color-stable sulfuric acid anodizing on thin aluminum substrates are concentrated among aging workforces in industrial Midwest regions.
- IEC electronics marking certification timelines:OEM qualification cycles for flame-retardant label substrates extend 18-24 months, delaying revenue recognition for new product introductions.
- Legacy mechanical fastening integration:Automotive plants with sunk capital in rivet and screw installation equipment resist adhesive-format conversion despite labor cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Labels Market |
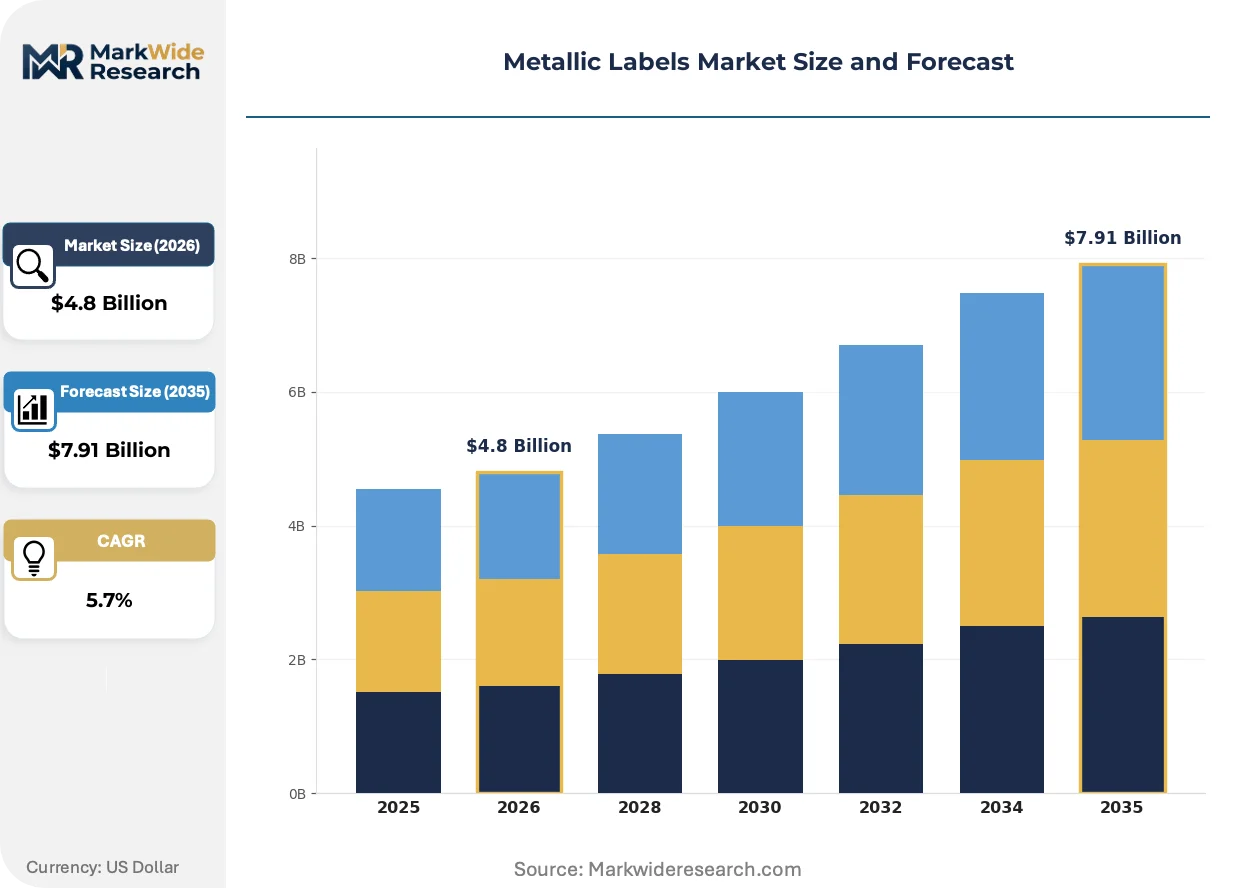
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Stainless Steel, Brass, Copper Adhesive Type: Permanent, Removable, Pressure-Sensitive, Heat-Activated Application: Industrial Equipment, Consumer Products, Electronics, Automotive Parts Finish Type: Brushed, Polished, Matte, Glossy |
| Companies Covered | Consolidated Label, Avery Dennison Corporation, 3M Company, Resource Label Group, CCL Industries, UPM Raflatac, Metalphoto of Cincinnati, Brady Corporation, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Labels Market Shifts & Advancements
Laser-etched serialization is compressing marking cycle times while eliminating consumable screen-printing inventories. Convergence between digital identification and physical durability requirements is forcing technology choices that favor permanent substrate solutions over temporary marking alternatives.
Direct-part marking lasers are unifying traceability and branding functions onto metallic substrates without secondary label attachment. Automotive Tier-1 suppliers are adopting these systems at pilot scale in powertrain component lines. The technology is unifying what were previously separate identification and decoration procurement decisions into single-source specifications.
REACH authorization procedures for chromium trioxide in anodizing sealants are tightening process chemistry documentation across European supply chains. Industrial consequences include accelerated migration to trivalent chromium and cobalt-free alternatives. German automotive OEMs are most affected, with procurement teams now requiring full material disclosure to Substances of Very High Concern lists.
Specification-driven vendor consolidation is compressing approved supplier lists at major electronics contract manufacturers. Direct sourcing relationships with substrate mills are displacing distributor intermediaries for high-volume programs. This pattern is most visible in Taiwan and South Korea, where ODM procurement teams are centralizing metallic label qualification under corporate-level commodity management.
Metallic Labels Market Segmentation
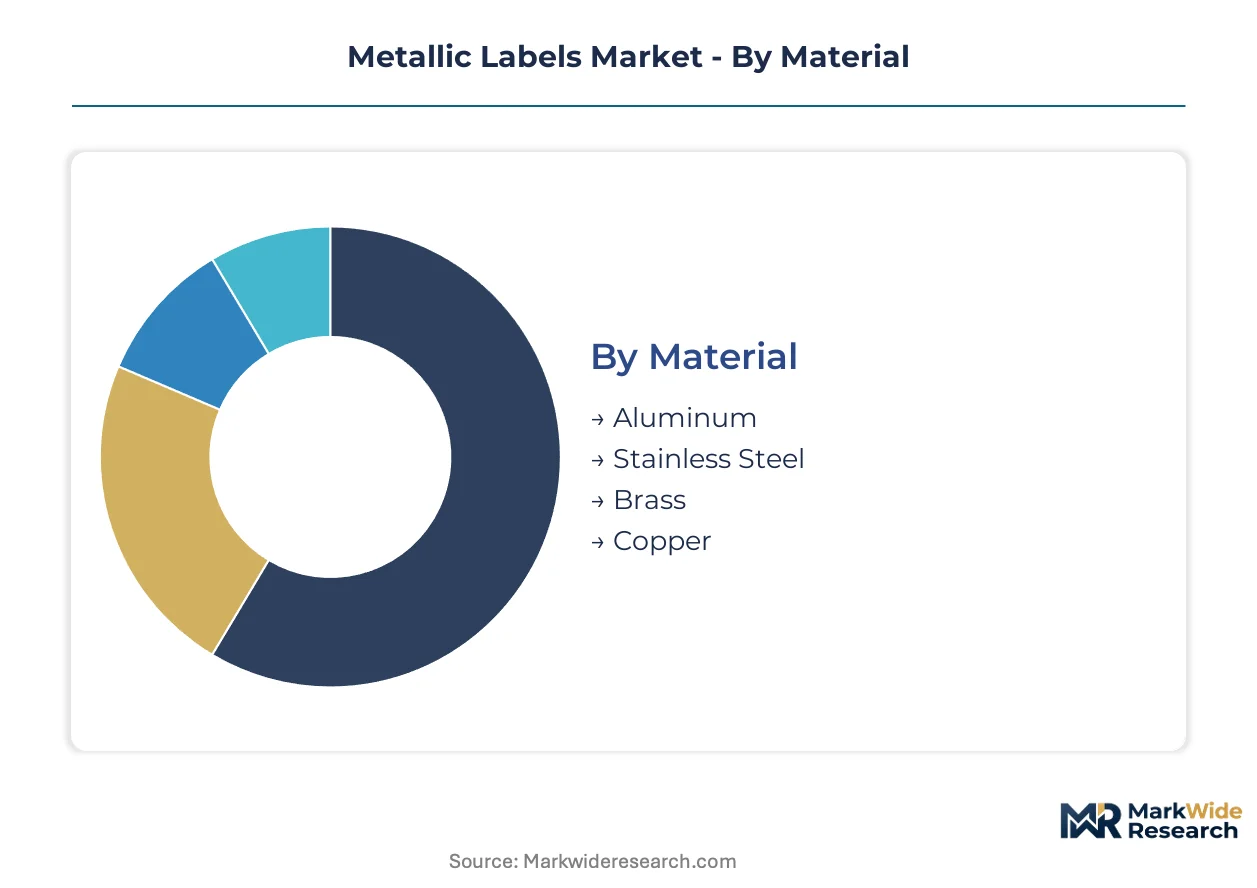
Material selection dictates corrosion resistance and temperature tolerance in metallic label procurement. Finish specifications and adhesive formats further segment supplier capabilities across industrial verticals with divergent compliance requirements.
Material:
Cost-performance tradeoffs dominate material selection decisions across end-use specifications.
- Aluminum:Lightweight substrate processed through anodizing or etching for moderate durability. Demand concentrates in German automotive supply chains where component weight reduction intersects with anodized color stability requirements under REACH Substances of Very High Concern protocols.
- Stainless Steel:Austenitic and ferritic grades deliver salt-spray resistance exceeding 1,000 hours in marine and chemical-processing deployments. Procurement from offshore wind manufacturers in Northern Europe is accelerating as turbine nacelle labeling specifications harden against North Sea corrosion.
- Brass:Copper-zinc alloy offering decorative warmth and moderate corrosion resistance for architectural and premium consumer goods applications.
- Copper:High electrical conductivity substrate serving grounding identification and electrical panel marking in industrial infrastructure.
Aluminum leads on scale; stainless steel leads on momentum.
Adhesive Type:
Surface geometry and removability requirements shape format selection across assembly line configurations.
- Permanent:Solvent-acrylic formulations delivering structural bonding to metal, glass, and painted substrates. Automotive powertrain manufacturers specify these for warranty-traceable component marking where label detachment voids compliance.
- Removable:Low-tack acrylics enabling residue-free detachment for temporary asset tracking and promotional applications. Electronics contract manufacturers in Taiwan use these for prototype phase identification before permanent serialization.
- Pressure-Sensitive:Instant-bonding films displacing mechanical fastening in curved-surface automotive applications. EPA VOC emission thresholds are compressing formulation options for U.S.-based converters.
- Heat-Activated:Thermosetting adhesives requiring elevated temperature curing for extreme-environment durability in aerospace and industrial oven equipment.
Pressure-sensitive formats are expanding most quickly; permanent adhesives retain volume dominance.
Application:
End-use durability specifications create tiered supplier qualification barriers.
- Industrial Equipment:Machine tool and automation labeling requiring abrasion resistance and chemical exposure tolerance. Munich-Stuttgart industrial corridor demand centers on anodized aluminum with laser-etched serialization.
- Automotive Parts:Component-level traceability for recall management and warranty tracking. Tier-1 suppliers specify metallic labels for powertrain and chassis components under NHTSA defect tracking protocols.
- Electronics:Flame-retardant substrate marking for PCBs and enclosures. IEC certification timelines extend 18-24 months for new supplier qualification.
- Consumer Products:Premium branding and decoration for cosmetics, spirits, and luxury goods. Short-run custom finishes dominate with rapid design iteration requirements.
Industrial equipment leads on scale; automotive parts show steepest expansion trajectory.
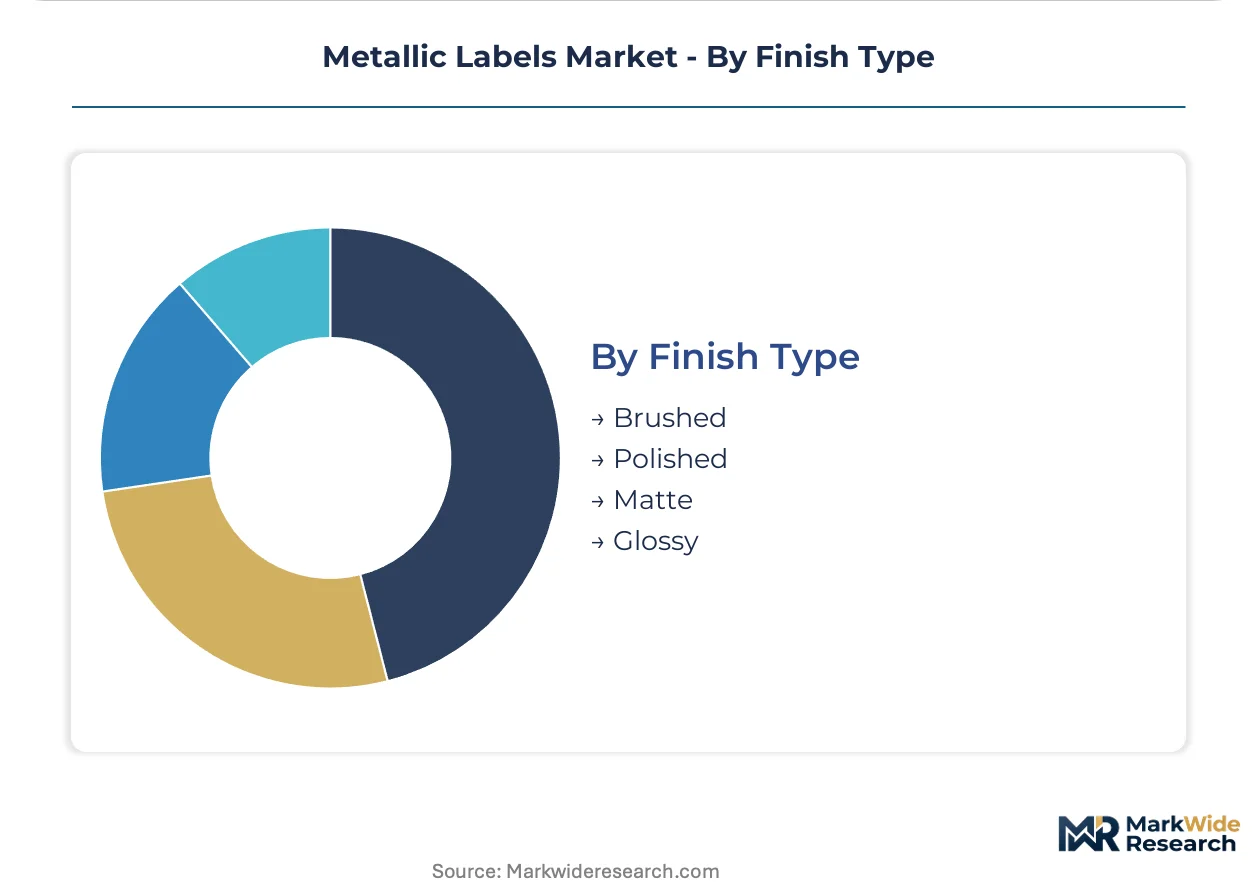
Finish Type:
Aesthetic differentiation and functional reflectivity determine surface treatment selection.
- Brushed:Directional abrasion pattern concealing fingerprints and minor scratches. Industrial control panel manufacturers prefer this for high-touch equipment interfaces.
- Matte:Diffuse surface minimizing glare for readability under variable lighting. Electronics enclosure labeling specifies matte finishes for barcode scan reliability.
- Polished:Mirror-like surface maximizing reflectivity for decorative architectural and premium consumer applications.
- Glossy:High-shear lacquer coating enhancing color saturation for brand visibility in retail environments.
Brushed finishes command industrial volume; matte treatments gain share fastest in electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallic label manufacturing originated in the German industrial belt during the post-war machine tool boom, with anodizing expertise spreading to North American automotive corridors and East Asian electronics hubs by the 1980s. Today's demand geography traces this lineage through precision equipment clusters in Southern Germany, Tier-1 automotive supply chains in the US Midwest, and contract manufacturing concentrations in Taiwan and South Korea.
Germany
Automotive OEMs in Munich and Stuttgart specify anodized aluminum labels for powertrain traceability under REACH Substances of Very High Concern protocols. ECHA authorization procedures for chromium trioxide in sealants are accelerating migration to trivalent chromium alternatives. The Baden-Württemberg industrial corridor hosts the densest concentration of sulfuric acid anodizing technicians outside Japan.
United States
EPA volatile organic compound thresholds on adhesive formulations are compressing domestic converter margins while NHTSA defect tracking mandates expand metallic label procurement for chassis components. Michigan and Ohio-based Tier-1 suppliers specify pressure-sensitive formats for curved-surface powertrain marking. The industrial Midwest retains aging workforces with legacy anodizing chemistry expertise.
China
MIIT standards for electronics flame-retardant marking are tightening qualification requirements for PCB and enclosure labels. Yangtze River Delta contract manufacturers centralize metallic label procurement under corporate commodity management. Shanghai and Suzhou-based ODMs are displacing distributor intermediaries through direct substrate mill relationships.
South Korea
Display and semiconductor equipment manufacturers in the Seoul Capital Area specify IEC-certified flame-retardant labels with 18-24 month qualification cycles. MFDS pharmaceutical labeling requirements are spilling over into industrial equipment marking standards. Busan-Ulsan shipbuilding clusters remain underpenetrated for salt-spray-resistant stainless steel labels despite North Sea specification precedents.
Japan
METI industrial equipment export standards are propagating Japanese labeling specifications through Southeast Asian supply chains. Kansai region machine tool builders specify laser-etched serialization on anodized aluminum for traceability compliance. Nagoya-based automotive suppliers pilot direct-part marking lasers that unify branding and identification functions without secondary label attachment.
Metallic Labels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adhesive chemistry certification and substrate sourcing control. The vendor base organizes into three tiers: integrated chemical conglomerates with captive film production, specialized label converters with anodizing expertise, and short-run custom finishers serving premium consumer brands. Consolidation pressure is intensifying through OEM qualification list compression and direct mill relationships displacing distribution intermediaries.
Within the integrated materials tier, Avery Dennison Corporation and 3M Company occupy positions anchored by pressure-sensitive adhesive portfolios and specialty film supply chains. Consolidated Label exemplifies the short-run custom finisher archetype targeting spirits and cosmetics brands with rapid design iteration requirements. These three entities represent distinct competitive vectors: materials science integration at scale, harsh-environment substrate durability, and premium consumer differentiation through metallic finish customization.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| 3M Company |
| Consolidated Label |
| Resource Label Group |
| CCL Industries |
| UPM Raflatac |
| Metalphoto of Cincinnati |
| Brady Corporation |
| Multi-Color Corporation |
Supply & Pricing Matrix
Extended producer responsibility frameworks in the European Union and California gate both qualified supply and premium-tier pricing access by mandating recycled metal content thresholds that only converters with closed-loop aluminum sourcing capabilities can satisfy. This regulatory filter stratifies the supplier base into certified premium tiers and uncertified commodity players, compressing margin flexibility for those lacking verified circular supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified anodized aluminum labels from uncertified equivalents and basic etched products. Price differentiation hinges on ECHA-compliant adhesive chemistry disclosure and ISO 9001 quality certification tier. Cost compression in the standard tier is intensifying because EPA VOC emission thresholds are forcing formulation changes that raise compliance overhead. Electronics contract manufacturers in Taiwan exhibit the highest price sensitivity due to centralized procurement under corporate commodity management, while German automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive Tier-1 suppliers and electronics contract manufacturers, displacing distributor intermediaries for high-volume programs. Supply concentrates in Germany, the United States, and Taiwan, with sulfuric acid anodizing expertise concentrated in aging industrial Midwest workforces and the Baden-Württemberg corridor. Raw material dependencies draw from specialty polyester and polyimide films, solvent-acrylic adhesive formulations, and virgin and recycled aluminum substrates. Single-source vulnerability in captive film production by integrated chemical conglomerates limits independent converter margin flexibility. Distribution runs through direct mill relationships for qualified suppliers and regional converter networks for short-run custom finishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metallic labels market functions as a geographic-arbitrage play where converters with European REACH certification command premium positioning against U.S.-based competitors facing stricter EPA VOC compliance costs. This regulatory cost differential creates margin expansion opportunities for qualified suppliers serving cross-border automotive and electronics supply chains.
For Market Incumbents: Deepen backward integration into specialty film supply through captive production partnerships or direct mill relationships, insulating margin pressure from integrated chemical conglomerates. Prioritize trivalent chromium anodizing chemistry investment ahead of ECHA chromium trioxide authorization restrictions. Secure closed-loop aluminum sourcing capabilities to meet EU and California recycled content mandates before qualification windows close. For New Entrants and Emerging Players: Electronics distributors in Taiwan and South Korea offer the most penetrable channel entry point, as specification-driven vendor consolidation compresses approved supplier lists and creates replacement demand for qualified alternatives. Target marine environment applications in offshore wind and shipbuilding sectors outside Northern Europe, where salt-spray-resistant stainless steel labels remain underpenetrated despite proven North Sea specifications. Lead with IEC electronics marking certification investment to overcome the 18-24 month OEM qualification barrier. For Investors and Strategic Acquirers: Roll-up economics work for specialized label converters with anodizing expertise because aging technician workforces in the industrial Midwest and Germany create non-replicable capability scarcity that strategic buyers will pay premiums to access. Target mid-cap converters holding sulfuric acid anodizing certifications and existing automotive OEM supplier status. Watch for ECHA authorization decisions on chromium trioxide as the inflection indicator for accelerated trivalent chromium migration and associated retooling investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Film Supply | Captive substrate sourcing insulates converters from integrated chemical conglomerate pricing power. |
| REACH-Compliant Adhesive Chemistry Certification | ECHA Substances of Very High Concern disclosure qualifies suppliers for German automotive procurement. |
| Closed-Loop Aluminum Sourcing Program | EU extended producer responsibility mandates favor converters with verified recycled content supply chains. |
| Trivalent Chromium Anodizing Transition | ECHA chromium trioxide authorization restrictions force process chemistry migration ahead of deadlines. |
| IEC Electronics Marking Certification Investment | Flame-retardant substrate qualification opens access to Taiwan and South Korea ODM procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with label converter operations managers, automotive Tier-1 procurement leads, electronics contract manufacturer commodity managers, and specialty film technical directors with secondary validation against customs trade data, SEC 10-K filings, ECHA authorization databases, and IEC certification registries. Bottom-up volume modeling across material, adhesive, application, and finish segments triangulated against top-down industry value estimates.
Segment-weighting approaches distributed value and volume across aluminum, stainless steel, brass, and copper substrates; permanent, removable, pressure-sensitive, and heat-activated adhesive formats; and industrial equipment, automotive parts, electronics, and consumer products end-uses. CAGRs were derived from regression analysis of historical procurement patterns and projected qualification timelines across the analysis window. Industry-specific inputs included REACH authorization procedure timelines, EPA VOC threshold compliance cost curves, and IEC electronics marking certification cycle durations.
Revisions become necessary when ECHA authorization decisions accelerate, EPA guidelines tighten adhesive emission thresholds, or digital printing substitution rates in electronics marking exceed baseline assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
GCC Labels and Release Liners Market
Labels
Primary Packaging Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Global Thermal Transfer Label Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Ethical Label Market
Labels
Laser Printable Wristbands Market
Labels
In-Mold Labeling (IML) Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Die Cut Labels Market
Labels
Label Applicator Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Global Automotive Labels Market
Labels
Global Laminated Labels Market
Labels
North America Self-Adhesive Labels Market