
 Label Applicator Market | 2026-2036
Label Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Label Applicator Market Outlook
ISO 9001 certification cycles for labeling machinery suppliers is unwinding the competitive set, favoring manufacturers with documented quality management systems. Herma GmbH leverages its Swabian engineering heritage to dominate precision pressure-sensitive applications. ProMach anchors North American demand through a distributed service network that reduces downtime for food and beverage packagers. Krones AG extends its glass and PET line integration expertise into high-speed rotary labelers for brewery clients.
A label applicator is an electromechanical device that affixes adhesive-backed substrates to product surfaces at speeds ranging from 20 to 800 containers per minute, employing vacuum drums, wipe-on pads, or air-blow mechanisms depending on substrate rigidity and contour complexity. Automatic applicators command the largest installed base across beverage bottling halls, while digital printing technology captures the fastest expansion as brands shift to shorter run lengths and variable data for traceability. Pressure sensitive labelers occupy the mature core of the market, with margin pools migrating toward integrated vision-inspection modules that verify barcode grade and print quality inline.
FDA 21 CFR Part 11 and EU MDR serialization mandates compel pharmaceutical end users to specify equipment with audit trails and electronic signature capabilities, tightening vendor qualification. ECHA REACH compliance for adhesive chemistries and substrate coatings adds material disclosure burdens that favor suppliers with in-house polymer formulation expertise. Stakeholders must weigh total cost of ownership against speed-to-compliance when selecting between European precision builders and Asian cost-optimized alternatives.
Market Dynamics
Serialization mandates from FDA 21 CFR Part 11 and EU MDR are compressing equipment replacement cycles, forcing pharmaceutical packagers to retire legacy labelers before mechanical end-of-life. This regulatory pressure concentrates purchasing authority among quality-assurance directors who prioritize audit-trail capabilities over raw throughput.
Growth Catalysts
- EU MDR serialization deadlines:Medical device manufacturers across Germany, France, and Italy must deploy track-and-trace-ready labelers by compliance dates, pulling forward capital expenditure into verification-enabled systems.
- Contract packaging expansion:Third-party logistics providers in the Netherlands and Belgium are consolidating multi-brand production into shared facilities that demand flexible, quick-changeover applicator platforms.
- Digital print integration:Inkjet and laser-coding modules are merging with pressure-sensitive turrets, enabling lot-specific graphics without plate changes and collapsing setup times for craft beverage runs.
Market Restraints
- Adhesive input volatility:Acrylic and rubber-based hot-melt formulations face ECHA REACH disclosure burdens that extend raw-material qualification timelines and compress formulation margins.
- Precision component concentration:Servo motors, vacuum pumps, and vision sensors source predominantly from Japanese and German suppliers, creating single-point vulnerability for mid-tier builders.
- Substitution by direct-to-object printing:UV-curable inkjet systems for secondary packaging are bypassing label substrates entirely in corrugated tray applications, eroding addressable volume in logistics end-uses.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's phased implementation of drug serialization creates first-mover advantage for suppliers establishing local assembly and validation support in Gujarat and Telangana.
- Wine and spirits premiumization:Short-run decorated labels with tactile varnishes and foil effects are migrating from flexographic pre-print to hybrid digital-finish inline systems at boutique California and Bordeaux estates.
- CE marking acceleration:Machinery Directive compliance consulting bundled with hardware sales differentiates European builders against lower-cost Asian competitors in Middle Eastern and North African markets.
Industry Challenges
- Mechatronics talent scarcity:Control-systems engineers capable of integrating PLC, servo, and vision architectures command premium compensation in Stuttgart and Munich, constraining R&D expansion.
- FAT/SAT timeline compression:Factory acceptance and site acceptance testing protocols for pharmaceutical-grade equipment now span 12-18 months, tying working capital and delaying revenue recognition.
- Legacy line integration:Retrofitting serialization-ready labelers into 1990s-era bottling halls requires mechanical adapters and safety-system upgrades that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Label Applicator Market |
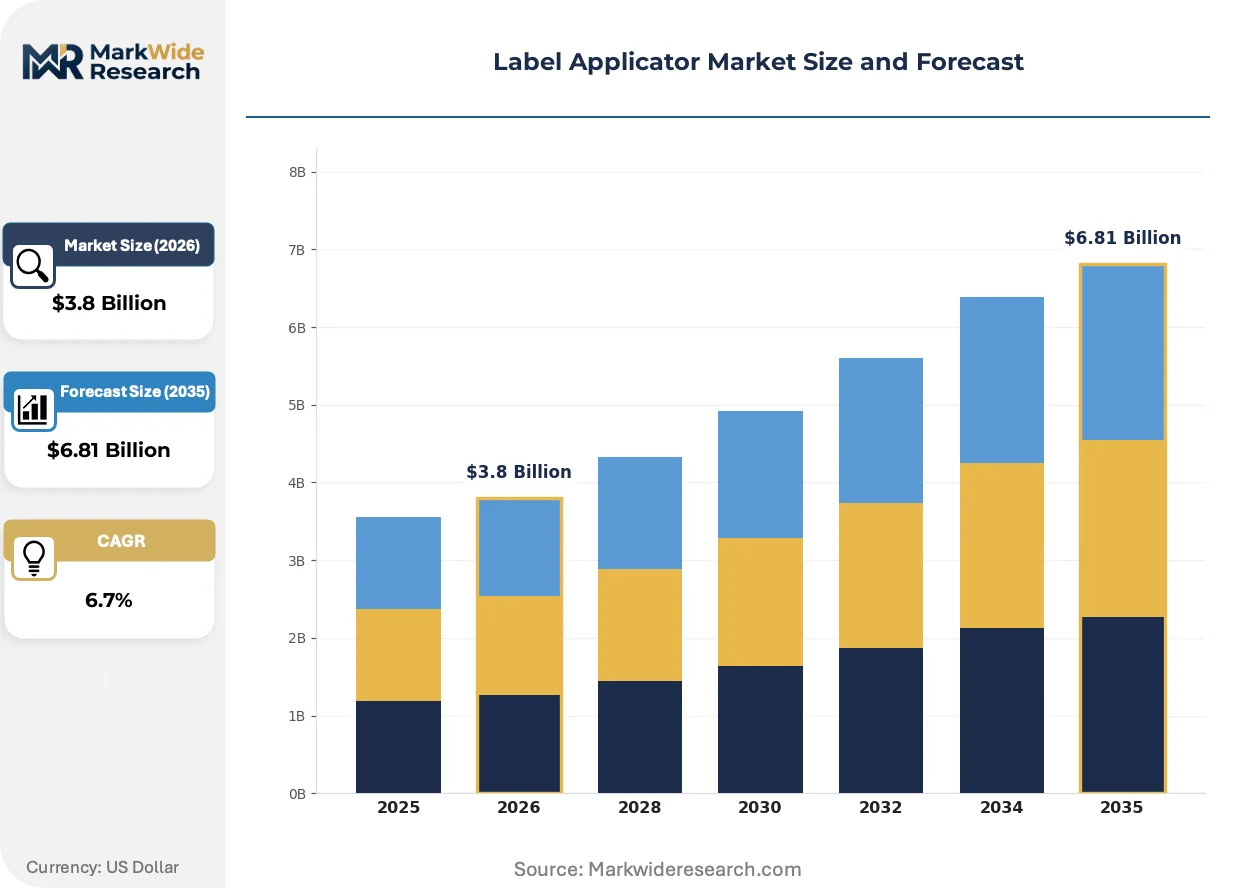
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Applicators, Semi-Automatic Applicators, Manual Applicators, Pressure Sensitive Labelers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Inkjet, Thermal Transfer, Laser, Digital Printing Application: Packaging, Retail, Industrial, Logistics |
| Companies Covered | Herma GmbH, ProMach, Accraply, Krones AG, Label-Aire, Quadrel Labeling Systems, CTM Labeling Systems, Videojet Technologies, Universal Labeling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Label Applicator Market Strategic Shifts
Convergence between electromechanical precision and data-centric compliance is redefining equipment specifications. Buyers now evaluate labelers as nodes in traceability networks rather than isolated production tools.
Vision-inspection modules with inline barcode grading and OCR verification are fragmenting the traditional separation between application and quality control. Pharmaceutical packagers in New Jersey and North Carolina are specifying integrated camera arrays that reject containers before downstream accumulation. This convergence compresses floor space requirements while elevating software validation burdens.
FDA's intensified scrutiny of electronic records and signatures under 21 CFR Part 11 is disqualifying equipment lacking configurable user-access hierarchies. Quality directors now demand audit trails capturing every parameter change with timestamp and operator ID. This enforcement is shifting procurement preference toward builders with documented software lifecycle processes and third-party security assessments.
Service unbundling is separating hardware purchase from maintenance contracts and spare-part subscriptions. Food and beverage multinationals in Brazil and Mexico are negotiating outcome-based uptime guarantees rather than fixed preventive schedules. This transfer of operational risk to OEMs pressures service-network density and remote-diagnostic capability investments.
Label Applicator Market Segmentation
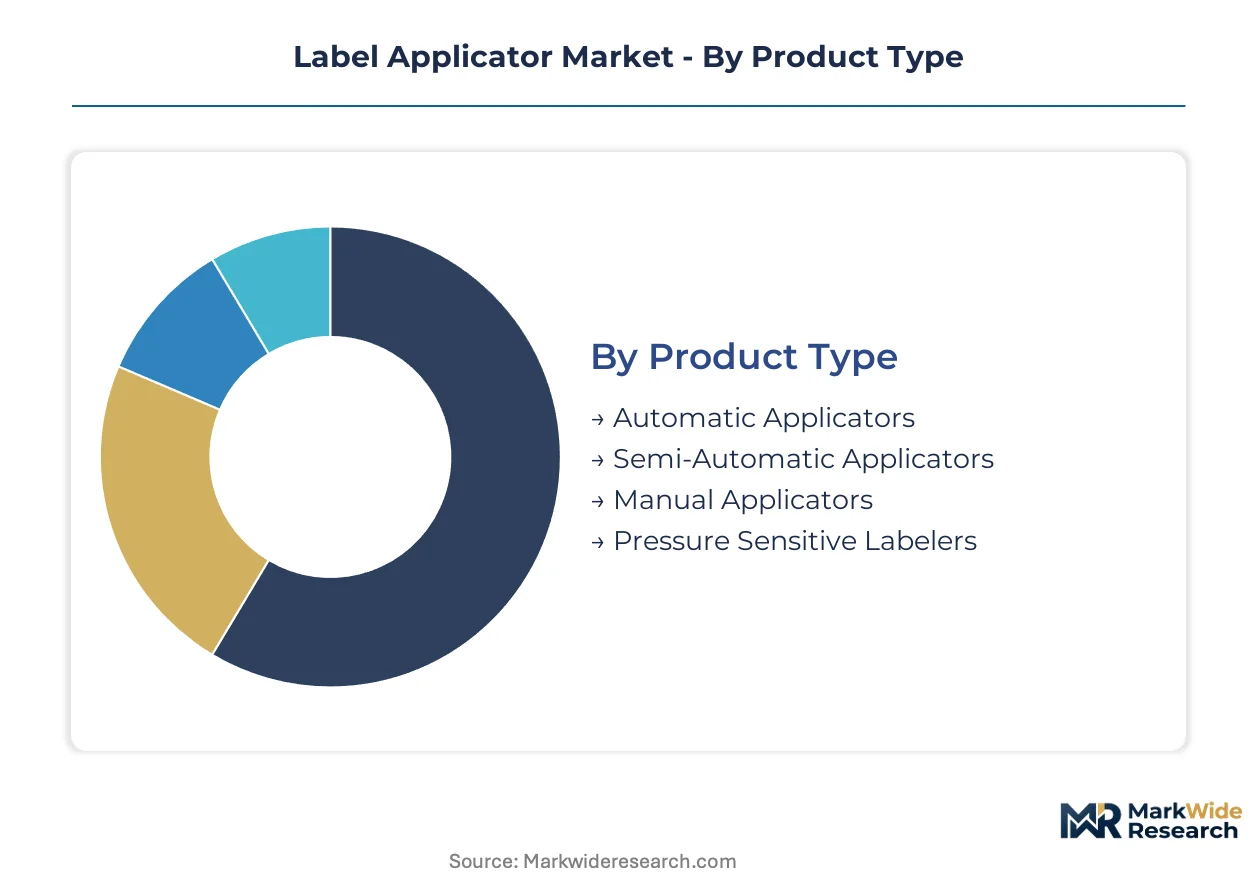
Label applicator procurement patterns diverge sharply across product configurations, end-use industries, and integration technologies. Equipment buyers prioritize speed-to-compliance in pharmaceutical serialization, while beverage packagers emphasize changeover flexibility. Understanding these segment-specific trade-offs clarifies vendor positioning and R&D allocation priorities.
Product Type:
Domestic production clusters in Germany and Japan supply precision automatic systems, while semi-automatic and manual variants increasingly source from cost-optimized Asian assembly hubs serving export markets.
- Automatic Applicators:Electromechanical systems deploy vacuum drums or air-blow mechanisms to achieve 200-800 containers per minute in continuous bottling operations. Demand concentrates in German brewery halls and North American beverage co-packers seeking rotary turret configurations with servo-driven changeover. FDA 21 CFR Part 11 audit-trail requirements now filter procurement toward builders with documented software validation protocols.
- Pressure Sensitive Labelers:These systems apply adhesive-backed substrates through wipe-on pads or tamp-blow actuators, dominating the installed base across mature packaging lines. Stuttgart-area contract packaging organizations specify these for EU MDR-compliant medical device serialization, where inline vision verification integrates directly with turret architectures.
- Semi-Automatic Applicators:Operator-fed systems serve mid-volume craft producers in California wine country and Belgian specialty brewers needing shorter runs without full automation capital burden.
- Manual Applicators:Hand-held or bench-mounted devices address micro-batch cosmetics producers and pilot-line pharmaceutical facilities in Telangana and Gujarat where throughput requirements remain below 20 units per minute.
Automatic applicators hold the largest share; momentum sits with pressure sensitive labelers as serialization mandates deepen integration requirements.
End User:
Margin structures vary dramatically across end-use categories, with pharmaceutical and electronics buyers accepting 40-60% equipment premiums for validation documentation that food and beverage purchasers reject.
- Food & Beverage:Carbonated soft drink bottlers in Mexico and Brazil drive volume demand for high-speed rotary systems with quick-changeover tooling. ProMach's distributed service network reduces downtime guarantees for these price-sensitive buyers who prioritize throughput over traceability depth.
- Pharmaceuticals:New Jersey and North Carolina packagers specify integrated camera arrays and electronic signature capabilities under intensified FDA 21 CFR Part 11 enforcement. Equipment replacement cycles compress as legacy labelers retire before mechanical end-of-life to meet serialization deadlines.
- Cosmetics:Premium fragrance and skincare brands in France demand tactile varnish and foil-effect labeling systems with hybrid digital-finish capabilities for short-run decorated substrates.
- Electronics:Consumer device manufacturers in South Korea and Taiwan apply tamper-evident and regulatory compliance labels to product housings and packaging, with emphasis on anti-static materials and cleanroom-compatible operation.
Food and beverage generates the highest unit volumes; pharmaceuticals command the steepest price premiums and fastest specification evolution.
Technology:
Technology selection tracks directly against run-length economics and variable data requirements, with digital modalities capturing share from mechanical printing in applications below 50,000-unit production runs.
- Digital Printing:Piezoelectric inkjet and toner-based systems enable lot-specific graphics without plate changes, collapsing setup times for craft beverage runs and pharmaceutical serialization. Bordeaux and California wine estates adopt these for personalized label campaigns and regional vintage differentiation.
- Laser:Permanent marking systems etch substrates through ablation or color-change chemistry, serving electronics manufacturers requiring tamper-proof traceability codes and medical device producers facing EU MDR durability mandates.
- Thermal Transfer:Wax-resin and resin ribbons deliver barcode-grade print quality for logistics carton labeling in Dutch and Belgian third-party distribution centers where smudge resistance outweighs speed requirements.
- Inkjet:Continuous and drop-on-demand systems apply variable data to primary and secondary packaging, with UV-curable formulations gaining traction in corrugated tray applications competing against direct-to-object printing substitution.
Digital printing is climbing the fastest as brand portfolios fragment toward shorter runs; thermal transfer retains dominance in high-volume logistics encoding.
Application:
Application context determines integration depth, with packaging line installations requiring synchronized PLC architectures while retail and logistics deployments prioritize standalone operation and manual loading interfaces.
- Packaging:Primary and secondary container labeling in continuous bottling halls demands servo-synchronized turrets with vision feedback loops. Krones AG extends glass and PET line integration expertise here for brewery clients requiring 99.5% efficiency guarantees.
- Logistics:Pallet and carton labeling for warehouse automation relies on print-and-apply systems with WMS integration, though UV-curable inkjet substitution for secondary corrugated applications erodes addressable label volume in this segment.
- Retail:In-store price marking and promotional labeling uses portable applicators with thermal transfer or direct thermal print engines, common in French and German hypermarket chains managing frequent price rotation.
- Industrial:Asset tracking and work-in-process labeling in automotive and aerospace manufacturing applies durable substrates through automated or semi-automated systems, with emphasis on chemical resistance and extreme temperature performance.
Packaging commands the dominant revenue position; logistics faces the strongest substitution pressure from direct-to-object coding technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 enforcement in the United States and EU MDR serialization mandates across European member states are compressing equipment replacement cycles and redirecting capital expenditure toward verification-enabled systems. Germany's precision machinery clusters and India's emerging pharmaceutical packaging hubs are capturing disproportionate investment flows as regulatory deadlines approach.
United States
New Jersey and North Carolina pharmaceutical packagers are retiring legacy labelers before mechanical end-of-life to meet FDA 21 CFR Part 11 compliance deadlines. The agency's intensified scrutiny of electronic records and signatures disqualifies equipment lacking configurable user-access hierarchies. Quality-assurance directors in these states now prioritize audit-trail capabilities over raw throughput specifications.
Germany
Stuttgart and Karlsruhe precision machinery clusters serve contract packaging organizations across the European Union with EU MDR-compliant serialization-ready equipment. ECHA REACH disclosure burdens for adhesive chemistries extend raw-material qualification timelines. Swabian engineering heritage dominates pressure-sensitive applications through documented quality management systems and ISO 9001 certification cycles.
India
CDSCO's phased implementation of drug serialization creates first-mover advantage for suppliers establishing local assembly in Gujarat and Telangana. Pharmaceutical packaging lines in these states are expanding automated labeling systems as domestic production scales to serve export markets. Pilot-line facilities in Hyderabad and Ahmedabad specify manual and semi-automatic applicators for throughput requirements below 20 units per minute.
China
Yangtze River Delta electronics manufacturers apply tamper-evident labels to consumer device housings with emphasis on anti-static materials and cleanroom-compatible operation. NMPA serialization requirements for pharmaceutical traceability are tightening equipment specifications. Cost-optimized assembly hubs in the region increasingly supply semi-automatic and manual variants to export markets.
Brazil
Food and beverage multinationals in São Paulo and Rio de Janeiro negotiate outcome-based uptime guarantees rather than fixed preventive maintenance schedules. ANVISA pharmaceutical serialization mandates are pulling forward capital expenditure into verification-enabled systems. Service-network density and remote-diagnostic capability investments transfer operational risk to OEMs serving these price-sensitive buyers.
Label Applicator Market Competitive Environment
Player mix skews toward precision European engineering houses and distributed North American service networks. The vendor base concentrates around three strategic archetypes: Swabian precision builders with polymer formulation expertise, North American integrators with dense service footprints, and Asian cost-optimized assemblers. Dominant competitive moves include M&A-driven portfolio diversification into vision-inspection modules and geographic expansion through local assembly partnerships in India and Southeast Asia.
Among German precision builders, Herma GmbH and Krones AG exemplify the engineering-intensive tier with documented software validation protocols and glass and PET line integration expertise. ProMach anchors the North American service-network archetype with distributed coverage that reduces downtime guarantees for food and beverage packagers. These three entities represent distinct competitive positioning vectors—European precision compliance, North American operational reliability, and integrated line architecture—rather than overlapping market contests.
| Leading Market Players |
|---|
| Herma GmbH |
| ProMach |
| Accraply |
| Krones AG |
| Label-Aire |
| Quadrel Labeling Systems |
| CTM Labeling Systems |
| Videojet Technologies |
| Universal Labeling Systems |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for servo motors and vacuum pumps from Japanese suppliers compress inventory buffers for mid-tier European builders, concentrating pricing power with precision component manufacturers while forcing downstream equipment vendors to absorb working capital strain or pass cost escalation to pharmaceutical buyers with locked validation protocols.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with FDA 21 CFR Part 11-compliant systems commanding substantial premiums over standard CE-marked alternatives. Pharmaceutical quality-assurance directors accept higher capital outlays for documented software validation protocols and electronic signature capabilities. Cost compression in semi-automatic and manual variants intensifies as Asian assembly hubs scale export-oriented production. Food and beverage packagers in Brazil and Mexico exhibit the greatest price sensitivity, prioritizing outcome-based uptime guarantees over upfront equipment expenditure.
Supply Chain Analysis
Strategic stockpiling of acrylic hot-melt adhesives and rubber-based formulations dominates procurement behavior among German precision builders facing ECHA REACH disclosure burdens. Component sourcing concentrates in Japan for servo motors and vision sensors, Germany for precision mechanical assemblies, and China for cost-optimized structural elements. Single-source vulnerability for vacuum pump subassemblies creates concentration risk. Distribution runs through OEM-direct channels for pharmaceutical-grade equipment and distributor networks for food and beverage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The label applicator market is recovering from a cyclical trough driven by compressed pharmaceutical capital expenditure cycles. Equipment replacement waves triggered by serialization mandates are pulling forward demand from traditional mechanical end-of-life timelines.
For Market Incumbents: Consolidate service-network density in India and Southeast Asia to capture CDSCO serialization implementation phases. Deepen backward integration into adhesive polymer formulation to offset ECHA REACH margin compression. Acquire vision-inspection module specialists to defend against integrated line architecture competition from beverage OEMs. For New Entrants and Emerging Players: Differentiate on rapid validation support for mid-tier pharmaceutical contract packagers in Telangana and Gujarat facing FAT/SAT timeline pressures. Target semi-automatic applicator segments serving California wine country and Belgian specialty brewers with hybrid digital-finish capabilities. Pursue outcome-based service contracts that transfer uptime risk from cash-constrained craft producers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because serialization mandates across FDA, EU MDR, and CDSCO jurisdictions create sustained equipment refresh cycles. Acquisition targets include Swabian precision builders with documented ISO 9001 quality systems and in-house software validation expertise. Watch for inflection when pharmaceutical quality-assurance directors gain consolidated procurement authority over engineering departments.| Strategic Initiative | Industry Significance |
|---|---|
| Vision-Inspection Module Integration | Pharmaceutical packagers in New Jersey specify inline camera arrays that reject containers before downstream accumulation. |
| Local Assembly Partnerships in India | CDSCO serialization deadlines create first-mover advantage for suppliers establishing Gujarat and Telangana validation support. |
| Outcome-Based Service Contracts | Brazilian food and beverage multinationals negotiate uptime guarantees that transfer operational risk to OEMs. |
| Adhesive Formulation Backward Integration | ECHA REACH disclosure burdens favor builders with in-house polymer expertise over dependent competitors. |
| Digital Print Technology Licensing | Bordeaux and California wine estates adopt hybrid systems for short-run tactile varnish and foil-effect campaigns. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and industry association disclosures. Interviews with quality-assurance directors at pharmaceutical packagers, maintenance engineers at beverage bottling facilities, procurement leads at contract packaging organizations, and aftermarket service heads at precision machinery OEMs informed demand-side dynamics. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH substance registrations, CDSCO serialization circulars, and equipment supplier technical specifications. Bottom-up unit demand estimates triangulated against top-down capital expenditure flows across end-use industries.
Segmentation dimensions modeled include product configuration, end-use industry, integration technology, and application context across the projection horizon. Analytical framework incorporated run-length economics for digital versus mechanical printing modalities, regulatory compliance tier effects on procurement authority, and service-network density impacts on aftermarket revenue capture. CAGRs derived from equipment replacement cycle compression analysis and emerging market penetration curves. Forecast inputs included pharmaceutical serialization deadline schedules and craft beverage production fragmentation indices.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or adhesive chemistry stability would require recalibration. Forecasts reflect assumptions regarding serialization mandate adherence timelines and precision component supply continuity. Revision becomes warranted when single-source supplier concentration for servo motors crosses critical thresholds or when direct-to-object printing substitution accelerates beyond modeled logistics application erosion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
In-Mold Labeling (IML) Market
Labels
Global Sensormatic Labels Market
Labels
Eco-Friendly Labels Market
Labels
Integrated Labeling System Market
Labels
Indicative Seals Market
Labels
Tags Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Polyester Labels Market
Labels
Sleeve Label Market
Labels
Freshness Indicator Label Market
Labels
Water Dissolvable Labels Market
Labels
Holographic Labels Market
Labels
Waterproof and Weatherproof Label Market
Labels
Multi-Part Labels Market
Labels
Foil Labels Market
Labels
Safety Labels Market