
 Shipping Label Market | 2026-2036
Shipping Label Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Label Market Insights
E-commerce fulfillment is pivoting toward automated sortation systems that demand machine-readable labels with near-perfect scan rates. Avery Dennison Corporation leverages its adhesive chemistry portfolio to anchor premium positions in temperature-variable logistics. CCL Industries Inc. competes through specialized pharmaceutical and healthcare labeling that sustains compliance-heavy specifications. Zebra Technologies Corporation dominates enterprise printing hardware, extending its influence into software-integrated label workflows.
Shipping labels are pressure-sensitive or non-pressure-sensitive substrates bearing printed identification, routing, and compliance data, typically manufactured with acrylic or hot-melt adhesives applied via slot-die coating to achieve peel strengths between 0.5 and 2.0 N/cm for corrugated and polyolefin surfaces. Their primary commercial purpose is to enable automated package tracking, customs clearance, and last-mile sorting across multimodal supply chains. Thermal transfer labels occupy the highest-margin tier due to durability requirements in cold-chain logistics, while direct thermal formats lead volume in short-lifecycle e-commerce applications where label lifespan rarely exceeds fourteen days. Digital printing technology is displacing flexography in run lengths below ten thousand impressions, concentrating margin pools in equipment-ink-substrate bundled contracts.
The EPA regulates volatile organic compound emissions from adhesive solvents used in domestic label manufacturing, while the EU Green Deal's packaging and packaging waste regulation mandates recyclability criteria that reshape substrate selection across European supply chains. ISO 15415 and ISO 15416 barcode quality standards govern machine-readability thresholds that determine label acceptance in automated distribution centers. Stakeholders must monitor adhesive reformulation timelines and regional extended producer responsibility implementations to anticipate material cost step-changes.
Market Dynamics
E-commerce fulfillment automation is compressing label lifecycle requirements while forcing substrate transitions toward recyclable stocks under EU packaging waste mandates. This dual pressure is restructuring supplier relationships around bundled equipment-ink-material contracts.
Growth Catalysts
- Automated Sortation Deployment:Distribution centers in Germany and the Netherlands are retrofitting conveyor systems that require ISO 15416-compliant barcode quality. Label specifications now mandate minimum 1.5 N/cm peel strength for polyolefin surfaces.
- EU Green Deal Packaging Mandates:The regulation's recyclability criteria are accelerating paper substrate adoption across Rhine-Ruhr logistics corridors. Adhesive reformulation timelines are compressing as converters retool coating lines.
- Cold-Chain Logistics Expansion:Pharmaceutical distributors are specifying thermal transfer labels with acrylic adhesives for temperature-variable routes. This segment commands premium positioning due to durability thresholds exceeding fourteen-day lifecycles.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and hot-melt adhesive prices fluctuate with propylene derivative markets. Coating operations face margin compression when resin costs spike without contract pass-through mechanisms.
- Concentrated Equipment Supply:Enterprise printing hardware sourcing concentrates among three dominant vendors. Buyers face limited negotiation leverage for software-integrated workflow bundles.
- Digital Printing Run-Length Economics:Flexography retains cost advantage above ten thousand impressions. Mid-volume converters remain locked into legacy equipment amortization cycles.
Strategic Opportunities
- Extended Producer Responsibility Gaps:France and Italy lag Germany in EPR implementation for packaging waste. First-mover converters can establish compliant substrate supply before enforcement tightens.
- Healthcare Compliance Specialization:Temperature logging labels with integrated RFID are penetrating pharmaceutical cold chains. This convergence creates white space beyond standard barcode applications.
- Direct Thermal Short-Lifecycle Dominance:E-commerce returns processing is driving demand for labels with sub-seven-day adhesion requirements. This segment tolerates lower durability specifications that reduce material costs.
Industry Challenges
- Adhesive Chemistry Talent Scarcity:Formulation chemists with slot-die coating expertise are concentrated among legacy manufacturers. Recruitment competition intensifies as substrate transitions accelerate.
- ISO Certification Timeline Compression:Barcode quality verification under ISO 15415 requires capital investment in verification hardware. Smaller converters face six-to-twelve-month compliance windows.
- Legacy Workflow Integration Friction:Enterprise printing hardware upgrades disrupt existing warehouse management system connections. IT integration costs often exceed equipment procurement budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Label Market |
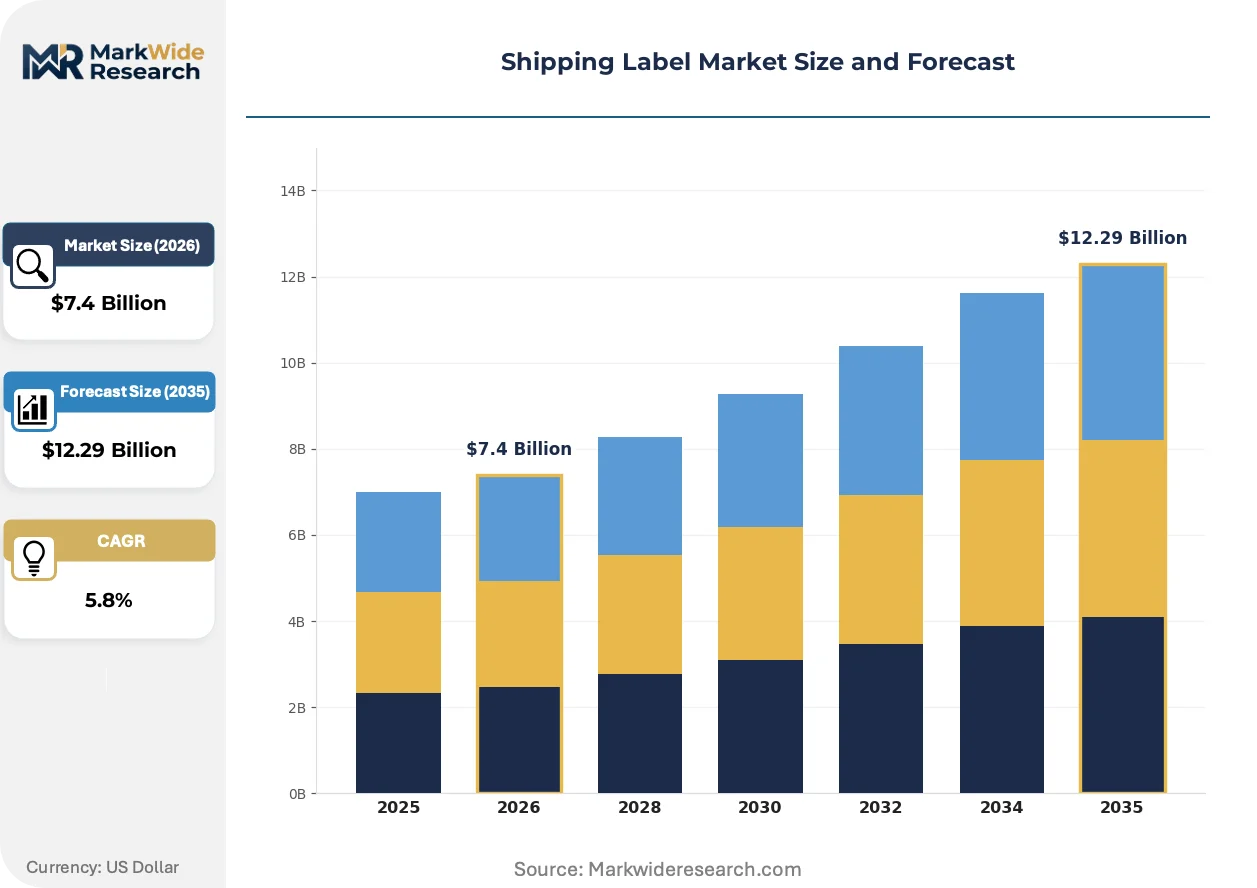
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Direct Thermal, Thermal Transfer, Inkjet, Laser Material: Paper, Polyester, Polypropylene, Vinyl End Use: E-Commerce, Logistics, Retail, Healthcare Printing Technology: Digital Printing, Flexography, Offset Printing, Screen Printing |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., 3M Company, Zebra Technologies Corporation, UPM Raflatac, Multi-Color Corporation, Mondi plc, Honeywell International Inc., SATO Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Label Market Trends and Innovations
Digital printing technology is fragmenting production economics while regulatory pressure on adhesive emissions intensifies. These forces are converging to reshape converter competitive positioning and buyer procurement criteria.
Print-head technology is modularizing around swappable thermal transfer and direct thermal configurations. Third-party logistics providers in the Netherlands are adopting dual-mode printers to handle mixed e-commerce and cold-chain volumes on single production lines. This hardware flexibility is compressing converter margins on dedicated equipment sales.
REACH restrictions on volatile organic compounds are forcing solvent-based adhesive reformulation across European coating operations. Manufacturers are migrating toward hot-melt and waterborne systems that satisfy ECHA registration thresholds. German converters near Rhine-Ruhr distribution hubs face the steepest compliance timelines due to regional air quality enforcement.
Buyer consolidation among pan-European e-commerce platforms is extending payment terms and demanding vendor-managed inventory arrangements. Label converters serving Amazon and Zalando fulfillment networks are absorbing working capital pressure in exchange for volume commitments. This procurement compression is most visible in Poland and Czech Republic, where new distribution capacity is concentrating demand among fewer decision-makers.
Shipping Label Market Segmentation
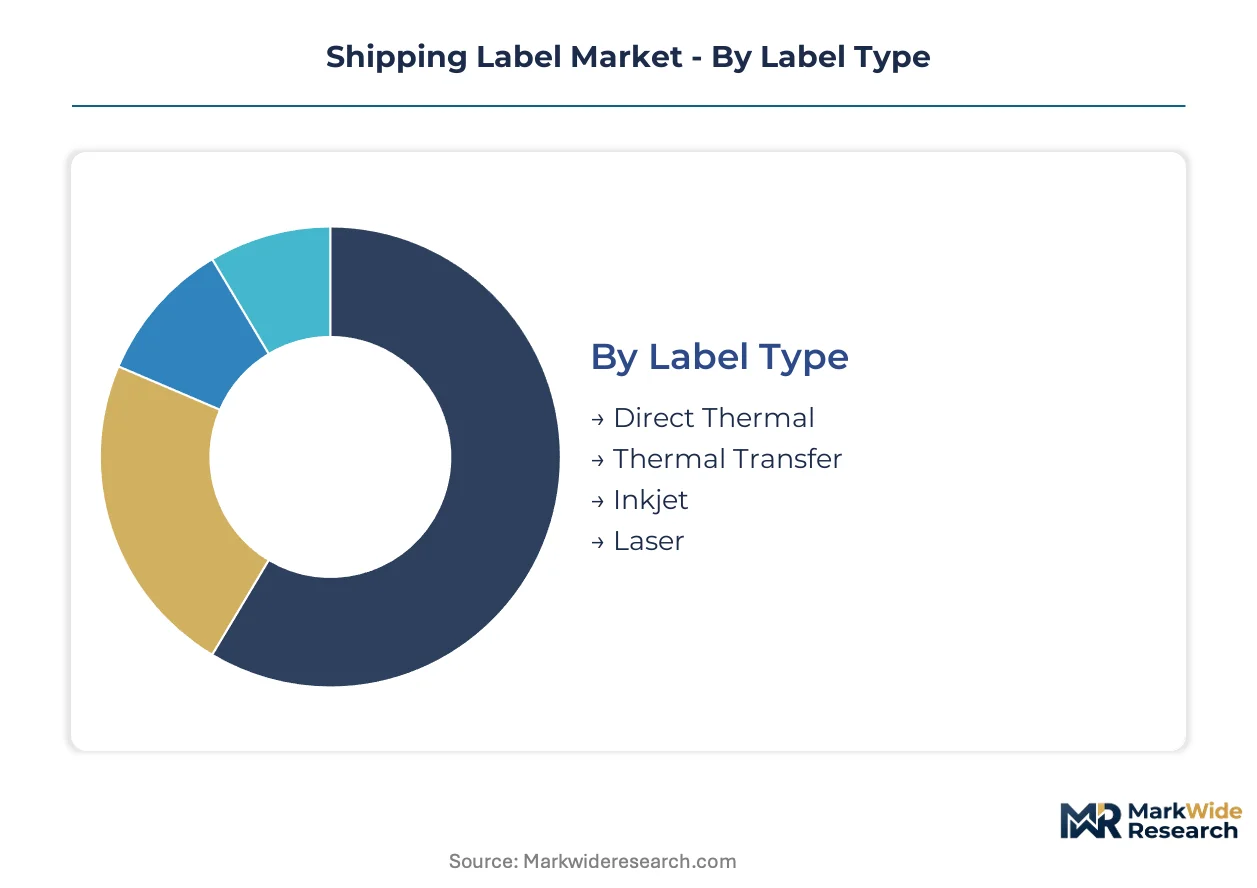
Shipping label procurement decisions cascade across substrate chemistry, print durability requirements, and end-use compliance thresholds. Converter margins depend on matching the correct segment combination to lifecycle specifications and regional regulatory timelines.
Label Type:
Printer fleet refresh cycles determine segment transitions, with distribution centers replacing hardware every five to seven years to capture scan-rate improvements and adhesive compatibility advances.
- Thermal Transfer:These labels utilize a ribbon-based imaging process that deposits wax or resin ink onto synthetic substrates. Durability specifications exceed fourteen-day lifecycles, attracting pharmaceutical distributors in Germany and the Netherlands who require temperature-variable logistics compliance. Cold-chain expansion across Rhine-Ruhr corridors sustains premium positioning for this segment.
- Direct Thermal:Heat-sensitive coatings activate without ribbons, reducing consumable costs for high-volume operations. E-commerce fulfillment centers in Poland and Czech Republic specify sub-seven-day adhesion requirements for returns processing, tolerating lower durability that compresses material costs. Short-lifecycle dominance in automated sortation environments drives placement velocity.
- Inkjet:Piezoelectric drop-on-demand systems enable full-color variable data printing for branded unboxing experiences. Specialty retailers in France leverage this capability for seasonal promotional campaigns.
- Laser:Electrophotographic fusion bonding suits office environments with intermittent print volumes and archival durability needs. Corporate mailrooms in Italy retain installed bases despite slower throughput.
Volume placements concentrate in Direct Thermal; the faster expansion belongs to Thermal Transfer.
Material:
Substrate selection hinges on surface energy compatibility with adhesive chemistries and recyclability mandates under EU packaging waste directives.
- Paper:Uncoated and semi-gloss stocks dominate e-commerce volume due to cost efficiency and compatibility with waterborne adhesives. German converters near Rhine-Ruhr hubs accelerate coating line retooling to meet EU Green Deal recyclability criteria.
- Polyester:PET films deliver dimensional stability across temperature extremes from -40°C to 150°C. Pharmaceutical cold-chain specifications in the Netherlands mandate this substrate for thermal transfer applications.
- Polypropylene:Biaxially oriented PP balances flexibility with moisture resistance, serving outdoor logistics applications in Poland where humidity fluctuation degrades paper alternatives.
- Vinyl:PVC-based stocks withstand chemical exposure and UV degradation for hazardous materials labeling. Industrial chemical distributors in Czech Republic specify vinyl for drum and container identification.
Paper commands placement volume; Polyester captures the steepest expansion trajectory as cold-chain compliance tightens.
End Use:
Application environments dictate adhesive peel strength requirements, barcode density specifications, and integration complexity with warehouse management systems.
- E-Commerce:Automated sortation systems demand ISO 15416-compliant barcode quality with minimum 1.5 N/cm peel strength for polyolefin surfaces. Amazon and Zalando fulfillment networks in Poland and Czech Republic consolidate procurement among fewer converters, extending payment terms.
- Logistics:Multimodal supply chains require labels surviving hand-offs between air, road, and rail carriers. Third-party providers in the Netherlands deploy dual-mode printers handling mixed freight volumes.
- Retail:Shelf-edge and promotional labeling prioritizes print aesthetics and rapid changeover capabilities. French hypermarkets specify direct thermal formats for price markdown agility.
- Healthcare:Temperature logging labels with integrated RFID penetrate pharmaceutical cold chains. Compliance-heavy specifications in Germany sustain specialized converter relationships.
E-Commerce anchors placement volume; Healthcare gains share fastest through compliance specialization.
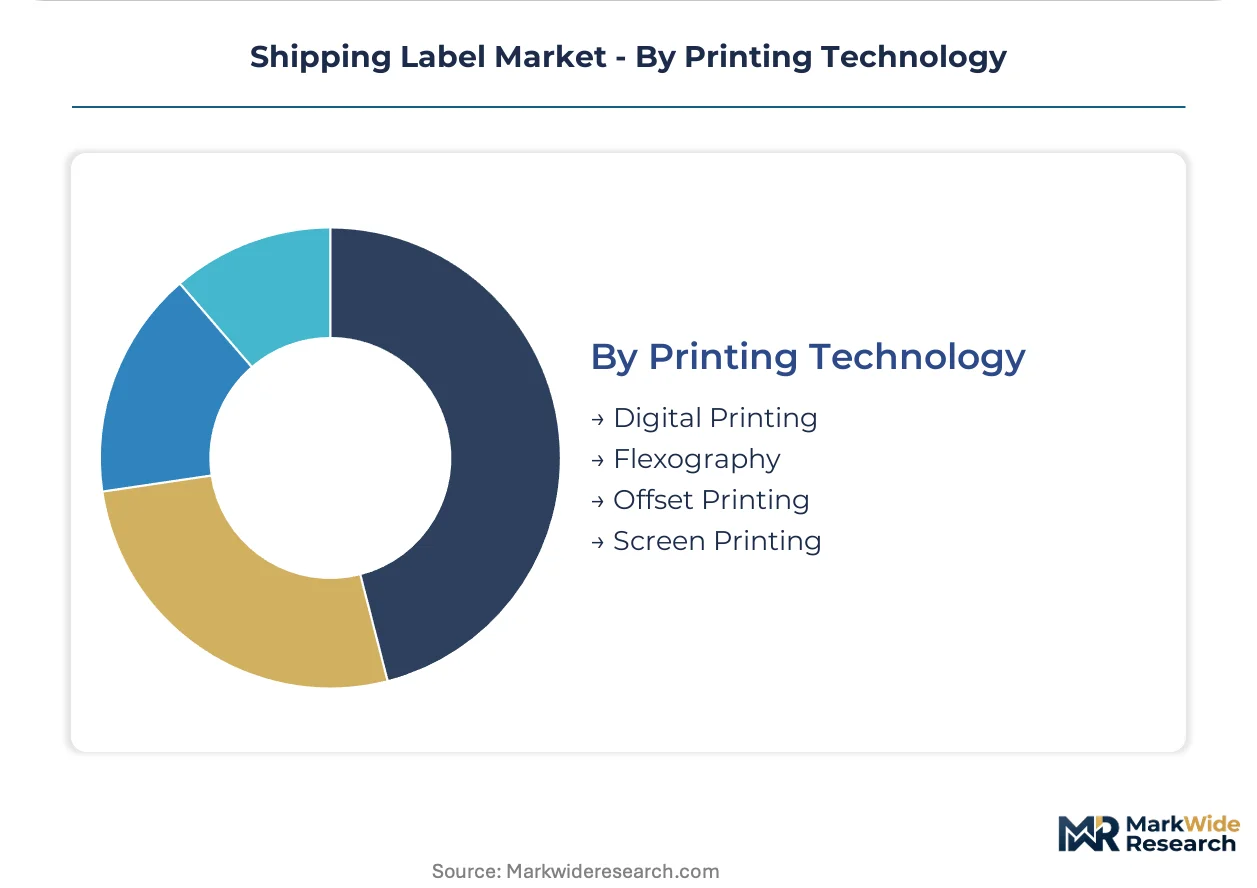
Printing Technology:
Capital equipment amortization and run-length economics determine converter technology portfolios, with digital presses displacing flexography below ten thousand impressions.
- Digital Printing:Electrophotographic and inkjet systems enable variable data and short-run customization without plate costs. Mid-volume converters in Italy and France adopt digital to escape legacy flexography amortization cycles.
- Flexography:Rotary relief printing retains cost advantage above ten thousand impressions with polymer plate technology. High-volume e-commerce label production in Germany and Poland concentrates around flexographic operations.
- Offset Printing:Lithographic transfer delivers fine-line detail and color consistency for premium retail applications. Italian cosmetics brands specify offset for packaging embellishment labels.
- Screen Printing:Thick-film ink deposition creates tactile and opaque effects for industrial safety and branding. Czech industrial equipment manufacturers use screen printing for durable asset tags.
Flexography holds placement volume; Digital Printing climbs fastest as run lengths fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones around Rotterdam and Antwerp concentrate European distribution infrastructure. Tax incentives for logistics automation in these zones accelerate label specification upgrades. Rhine-Ruhr corridor cities anchor substrate converter capacity.
Germany
Automated sortation deployment across DHL and Amazon fulfillment centers drives ISO 15416-compliant barcode demand. The EU Green Deal's packaging waste regulation accelerates paper substrate transitions. Cologne-Düsseldorf logistics clusters absorb coating line retooling investments.
United States
E-commerce fulfillment automation at FedEx and UPS hubs compresses label lifecycle requirements. EPA volatile organic compound rules pressure solvent-based adhesive reformulation. Chicago and Dallas distribution corridors concentrate thermal transfer specification growth.
Netherlands
Third-party logistics providers deploy dual-mode printers for mixed freight volumes. REACH restrictions force hot-melt adhesive migration across coating operations. Rotterdam port logistics zones integrate vendor-managed inventory arrangements.
Poland
Amazon and Zalando fulfillment network expansion concentrates procurement among fewer converters. Extended producer responsibility implementation lags Western Europe. Warsaw and Poznań distribution hubs extend payment terms to secure volume commitments.
China
Cross-border e-commerce platform consolidation drives machine-readable label standardization. SAMR packaging waste guidelines reshape substrate selection criteria. Yangtze River Delta logistics cities absorb digital printing technology upgrades.
Shipping Label Market Competitive Landscape
Top-tier vendors anchor adhesive chemistry and enterprise hardware positions, while mid-scale converters compete on regional compliance specialization. The market exhibits tiered concentration around bundled equipment-ink-material contracts. Strategic archetypes include integrated adhesive-substrate manufacturers, specialized pharmaceutical label converters, and enterprise printing hardware providers. Dominant competitive moves involve coating line retooling for recyclable stocks and software-integrated workflow bundling.
Among North American diversified manufacturers, Avery Dennison Corporation and 3M Company exemplify integrated adhesive-substrate positioning. Zebra Technologies Corporation anchors the enterprise hardware tier. These three entities represent distinct competitive vectors: adhesive chemistry control, materials science breadth, and software-integrated printing systems respectively.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| 3M Company |
| Zebra Technologies Corporation |
| UPM Raflatac |
| Multi-Color Corporation |
| Mondi plc |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters across Germany and Poland anchor supply discipline through generational capital allocation that resists short-term pricing erosion. Their patient financing structures sustain coating line retooling investments despite EU Green Deal compliance cost spikes, creating asymmetric pricing power against private-equity-rolled competitors chasing quarterly returns.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent orders from contract-scheduled volumes, with Rhine-Ruhr distribution hubs commanding premiums for sub-48-hour substrate turnaround. Three-tier pricing structure across thermal transfer, direct thermal, and inkjet formats reflects durability specification tiers and ISO 15416 certification investment. Cost compression in direct thermal runs through e-commerce buyer consolidation at Amazon and Zalando networks. Small-format converters serving Polish returns-processing centers exhibit highest price sensitivity; pharmaceutical distributors specifying cold-chain acrylic adhesives demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with propylene derivative feedstocks concentrated among German and Dutch petrochemical complexes. Acrylic and hot-melt adhesive production draws from these corridors, with coating operations tethered to regional resin availability. Tariff exposure on Asian-sourced PET films threatens polyester substrate cost stability. Distribution runs through vendor-managed inventory arrangements at Rotterdam-Antwerp logistics zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal packaging waste mandates erect barrier-to-entry moats favoring converters with completed coating line retooling.
For Market Incumbents: To counter adhesive chemistry talent scarcity, anchor retention through slot-die coating expertise certification programs in Cologne-Düsseldorf clusters. Deepen backward integration into waterborne adhesive formulation to capture margin pools escaping solvent-based competitors facing REACH restrictions. For New Entrants and Emerging Players: Extended producer responsibility gaps in Poland and Czech Republic open a window for compliant substrate supply before enforcement tightens to Western European timelines. Target healthcare temperature-logging labels with integrated RFID as the most penetrable white space beyond commoditized barcode applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized pharmaceutical label converters in the Netherlands with ISO 15415 verification hardware already deployed. Watch adhesive reformulation timeline compression as the signal indicating which coating operations face existential compliance cost spikes versus capture-ready margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retooling for Recyclable Stocks | EU Green Deal compliance in Rhine-Ruhr corridors separates viable converters from stranded assets. |
| Software-Integrated Workflow Bundling | Zebra Technologies' enterprise hardware dominance forces mid-scale converters toward value-added service layers. |
| Healthcare Compliance Specialization | Temperature-variable logistics certification in Germany sustains premium positioning against e-commerce commoditization. |
| Dual-Mode Printer Fleet Deployment | Netherlands third-party logistics providers capture mixed freight volumes through thermal transfer and direct thermal flexibility. |
| Vendor-Managed Inventory Arrangements | Amazon and Zalando consolidation in Poland and Czech Republic shifts working capital burden onto converter balance sheets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with coating line engineers, adhesive formulation chemists, pharmaceutical procurement managers, and third-party logistics operations directors. ECHA registration databases, EU packaging waste directive implementation timelines, and ISO certification body audit records supplied triangulation points. Bottom-up converter capacity assessments and top-down e-commerce fulfillment volume estimates were reconciled across analysis approaches.
Segment-level modeling addressed label type, substrate material, end-use application, and printing technology dimensions across the projection horizon. Cold-chain logistics expansion rates and automated sortation deployment timelines informed thermal transfer versus direct thermal growth trajectories. CAGR derivation rested on adhesive chemistry substitution elasticity and regulatory compliance cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for digital printing displacement of flexography would alter the outlook. Forecasts reflect assumptions about EU Green Deal enforcement intensity and REACH adhesive reformulation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Tags Market
Labels
Oxygen Indicator Labels Market
Labels
Global Automotive Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Pin Feed Labels Market
Labels
Integrated Labeling System Market
Labels
Hot Melt Glue Labeler Market
Labels
Label Applicator Market
Labels
Global Thermal Transfer Label Market
Labels
Freshness Indicator Label Market
Labels
Global Sensormatic Labels Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
Canning Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Freezer Label Market