
 Self-Laminating Labels Market | 2026-2036
Self-Laminating Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Laminating Labels Market Analytics
EU packaging sustainability directives are recalibrating material specifications across the self-laminating labels value chain. Brady leverages captive film-coating capabilities to sustain margin control in industrial-grade applications. Avery Dennison Corporation anchors North American healthcare demand through specialized adhesive chemistries designed for patient-wear compliance.
Self-laminating labels consist of a printable substrate topped with a transparent protective film that seals upon application, typically constructed from polyester or vinyl layers with pressure-sensitive acrylic adhesives, engineered to preserve barcode integrity against abrasion, chemical exposure, and moisture in harsh operating environments. Polyester label types dominate industrial asset-tracking deployments where thermal transfer printing must survive degreasing solvents and UV exposure. Vinyl configurations compete aggressively in shipping applications requiring conformability to curved surfaces, while paper-based variants occupy cost-sensitive inventory management roles in education and light retail.
OSHA hazard communication standards and FDA Unique Device Identification rules jointly shape product durability benchmarks and traceability mandates in the United States. REACH chemical restrictions in Europe constrain adhesive formulations, forcing reformulation investments that filter through to end-user pricing structures. Stakeholders must monitor evolving extended producer responsibility frameworks, as these will determine which substrate-recovery economics prevail across major demand centers.
Market Dynamics
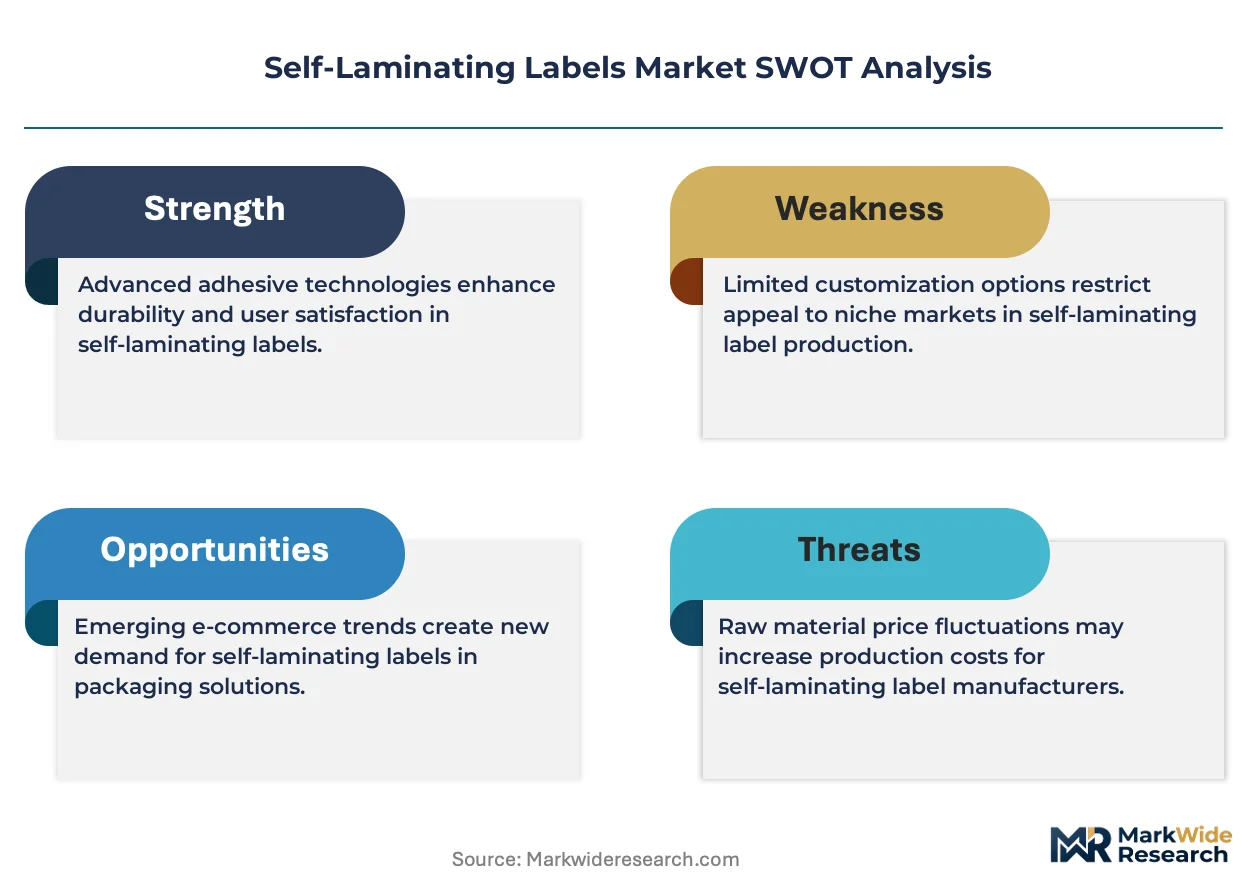
EU Green Deal packaging sustainability mandates are forcing substrate-thinning investments across the self-laminating labels value chain, compressing legacy film specifications while demanding equivalent durability performance.
Growth Catalysts
- FDA Unique Device Identification rules:Healthcare facilities in the United States must deploy patient-wear labels surviving repeated sterilization cycles, accelerating specification upgrades for thermal-transfer printable wristbands.
- Germany's industrial manufacturing corridor:Asset-tracking protocols in automotive and machinery clusters mandate barcode legibility exceeding ten years, concentrating demand for polyester-based constructions with solvent-resistant adhesives.
- Pressure-sensitive acrylic adhesive advances:New formulations achieving conformability to curved surfaces without lifting are displacing mechanical fasteners in shipping container applications.
Market Restraints
- Petrochemical feedstock volatility:Polyester and vinyl substrate costs fluctuate with crude oil derivatives, squeezing converter margins on fixed-price industrial contracts.
- REACH chemical restrictions:ECHA constraints on adhesive solvent compositions force reformulation investments that pass through to end-user pricing structures.
- Digital watermark substitution:RFID and NFC tagging in high-value logistics is capturing share in applications previously served by printed barcode labels.
Strategic Opportunities
- India's pharmaceutical export expansion:Cold-chain logistics for temperature-sensitive biologics creates demand for moisture-resistant labels surviving condensation cycles.
- EU extended producer responsibility frameworks:Pending substrate-recovery mandates will reward converters with established recycling partnerships and mono-material constructions.
- Near-field communication convergence:Hybrid labels combining printed barcodes with embedded NFC chips are opening premium tiers in medical device authentication.
Industry Challenges
- Thin-film coating precision:Substrate-thinning to meet EU sustainability targets requires capital-intensive coating line upgrades that smaller converters cannot finance.
- Multi-jurisdiction compliance timelines:Simultaneous FDA UDI, REACH, and emerging state-level packaging laws in California and New York create certification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Laminating Labels Market |
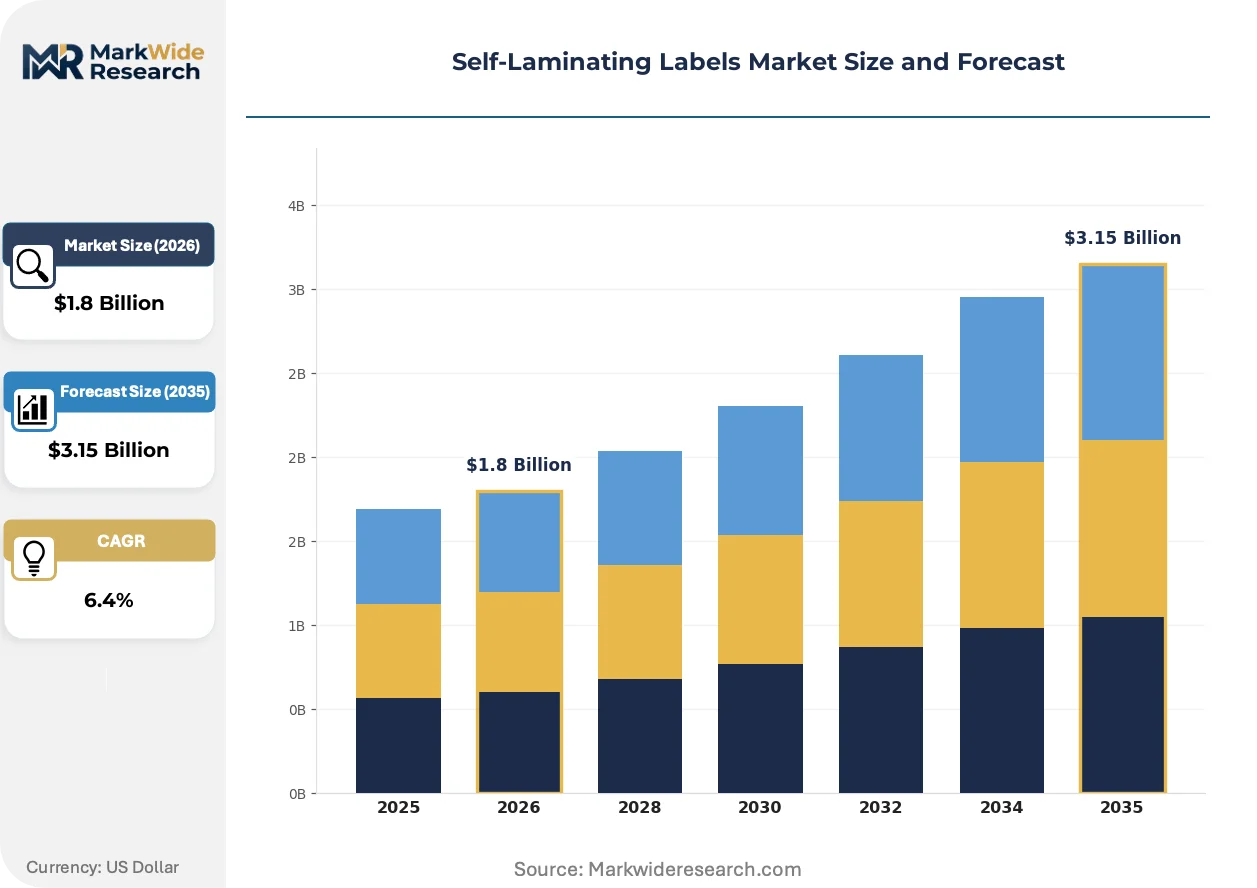
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Paper, Vinyl, Polyester, Polypropylene End User: Retail, Healthcare, Manufacturing, Education Application: Product Identification, Shipping, Inventory Management, Asset Tracking Distribution Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Brady, TE Connectivity, Panduit, 3M, Phoenix Contact, HellermannTyton, Avery Dennison Corporation, CCL Industries, Brother, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Laminating Labels Market Evolving Landscape
Laser-etched variable data printing is compressing production lead times for short-run industrial labels, while bio-based adhesive research targets performance parity with petroleum-derived acrylics.
Water-based acrylic adhesive formulations are rewriting durability benchmarks for pressure-sensitive labels. Automotive assembly plants in Germany and the United States are piloting these chemistries for under-hood applications previously reserved for solvent-borne systems. The technology is rewriting cost structures by eliminating volatile organic compound capture equipment and reducing hazardous material handling premiums.
REACH chemical authorization procedures are extending reformulation timelines for European converters. ECHA scrutiny of isocyanate-based curing agents is forcing adhesive suppliers to validate alternative cross-linking chemistries. Medical device label producers face the tightest compliance windows, with MDR traceability requirements layering atop substance restrictions.
Consolidated procurement through group purchasing organizations is compressing supplier margins in North American healthcare. Hospital systems in the United States are unbundling label supply from broader medical consumables contracts, forcing specialized converters to compete directly with diversified distributors. The shift is most visible in California and Texas, where integrated delivery networks command regional purchasing volumes.
Self-Laminating Labels Market Segmentation
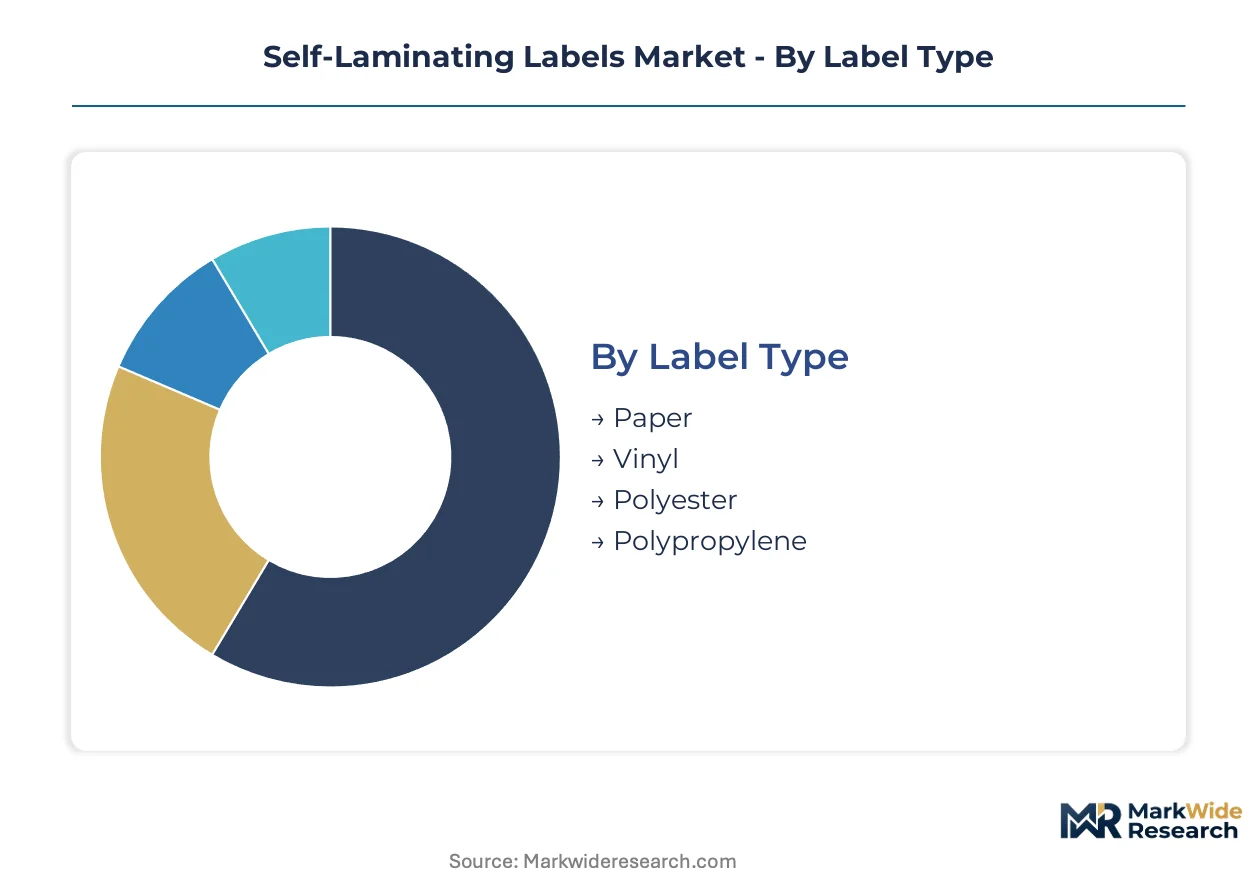
Self-laminating labels serve divergent durability requirements across industrial, medical, and commercial environments. Material selection, end-use compliance burdens, and procurement channel economics create distinct competitive battlegrounds within each segment category.
Label Type:
Polyester and vinyl formulations command disproportionate converter capacity due to industrial contract volumes and healthcare certification requirements.
- Polyester:Thermal-transfer printable constructions with solvent-resistant acrylic adhesives dominate automotive under-hood applications and medical device sterilization cycles. German machinery manufacturers specify ten-year barcode legibility, concentrating demand in Baden-Württemberg and Bavaria industrial clusters where asset-tracking protocols mandate polyester durability.
- Vinyl:Conformable calendered films with aggressive pressure-sensitive adhesives displace mechanical fasteners on curved shipping containers. United States logistics providers specify vinyl for intermodal freight exposed to condensation and UV degradation during cross-country rail transit.
- Paper:Cost-sensitive education and light retail inventory management.
- Polypropylene:Thin-film sustainability plays for EU Green Deal compliance.
Today's leader: Polyester. Tomorrow's challenger: Polypropylene.
End User:
Healthcare procurement consolidation and manufacturing traceability mandates are reshaping customer concentration patterns.
- Healthcare:FDA Unique Device Identification rules require patient-wear wristbands surviving repeated autoclave cycles. United States hospital systems in California and Texas unbundle label supply from broader medical consumables contracts, forcing specialized converters to compete directly with diversified distributors.
- Manufacturing:OSHA hazard communication standards and long-duration asset-tracking protocols in Germany's automotive corridor specify thermal-transfer polyester with chemical-resistant overlamination.
- Retail:Price-driven inventory management with shorter durability requirements.
- Education:Basic paper-based solutions for library and equipment tracking.
Healthcare commands premium pricing power. Manufacturing delivers volume stability.
Application:
Asset-tracking and shipping applications concentrate specification complexity where barcode failure carries operational penalties.
- Asset Tracking:Ten-year legibility mandates in industrial environments demand polyester constructions with UV-stable overlamination. German automotive suppliers and United States aerospace maintenance facilities specify identical durability benchmarks despite differing regulatory frameworks.
- Shipping:Conformability to corrugated and curved surfaces drives vinyl adoption. REACH-compliant adhesive reformulations for European logistics are climbing the fastest as ECHA restrictions force chemistry investments that filter through to end-user pricing.
- Product Identification:Variable data printing with laser-etched serialization for anti-counterfeiting.
- Inventory Management:Short-cycle retail and education applications with minimal environmental exposure.
Shipping volumes scale with e-commerce velocity. Asset-tracking margins expand with compliance stringency.
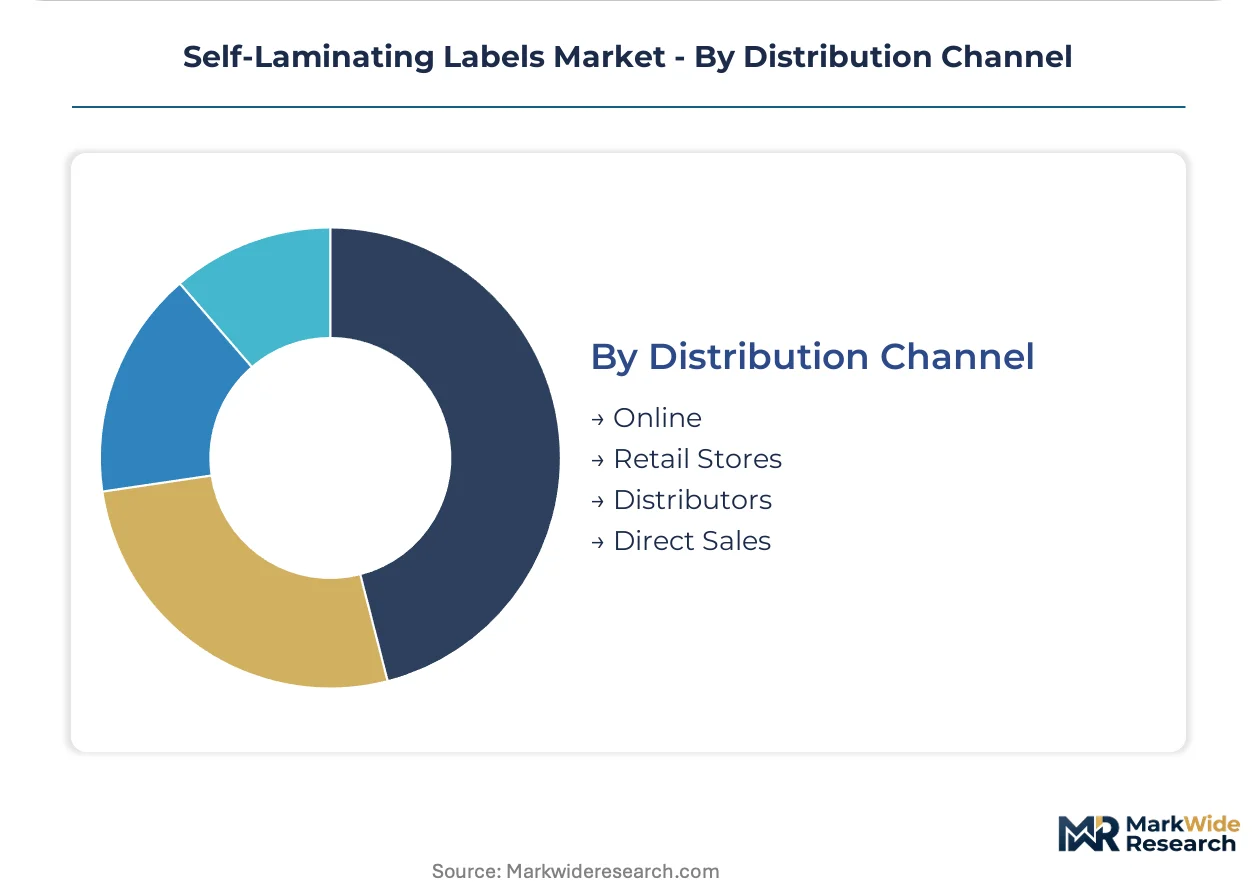
Distribution Channel:
Channel selection reflects order fragmentation, technical support requirements, and contract pricing leverage.
- Distributors:Industrial MRO procurement in Germany and the United States flows through specialized converter-distributor relationships providing technical specification support and consolidated logistics.
- Direct Sales:Large healthcare systems and automotive OEMs negotiate volume contracts bypassing distribution markups. Group purchasing organizations in United States hospital networks compress supplier margins through consolidated procurement.
- Online:Small-batch and emergency replenishment orders.
- Retail Stores:Consumer and small business immediate-need purchases.
Distributors anchor industrial volume. Direct sales capture healthcare premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers and American polymer scientists anchor the industry's technical workforce, concentrating formulation expertise in industrial corridors where durability specifications are most stringent.
United States
FDA Unique Device Identification rules drive patient-wear wristband demand across hospital systems in California and Texas. OSHA hazard communication standards mandate chemical-resistant labeling for industrial asset tracking. The Midwest automotive belt and Southeast aerospace maintenance clusters specify ten-year barcode legibility for polyester constructions.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria require solvent-resistant thermal-transfer labels for machinery asset tracking. REACH chemical restrictions force adhesive reformulation investments that pass through to converter pricing. The industrial manufacturing corridor concentrates demand for UV-stable overlamination in degreasing environments.
China
Export-oriented electronics manufacturers in the Yangtze River Delta specify moisture-resistant labels for cold-chain logistics. GB standards for packaging traceability align with dual carbon goals pushing substrate-thinning investments. Shenzhen and Shanghai logistics hubs drive vinyl adoption for intermodal shipping conformability.
India
Pharmaceutical exporters in Maharashtra and Gujarat require condensation-resistant labels for temperature-sensitive biologics. CDSCO traceability mandates for medical devices accelerate specification upgrades. The Mumbai-Pune industrial corridor concentrates cold-chain infrastructure investment driving premium label demand.
Japan
Precision equipment manufacturers in the Chubu region specify laser-etched variable data printing for anti-counterfeiting applications. METI sustainability guidelines push converters toward thinner film substrates. The Osaka-Kobe manufacturing cluster demands hybrid labels combining barcodes with embedded authentication features.
Self-Laminating Labels Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the self-laminating labels value chain, with integrated film coaters maintaining margin control against specialized adhesive formulators. The market structure tiers between diversified industrial conglomerates, captive healthcare specialists, and regional substrate converters. Three archetypes dominate: integrated material-science players with captive polymer supply, healthcare-focused converters with FDA certification depth, and industrial distributors with specification support capabilities. Competitive moves center on backward integration into film coating and strategic partnerships with recycling operators anticipating EU extended producer responsibility frameworks.
Among diversified industrial conglomerates, 3M and TE Connectivity exemplify the integrated material-science archetype with polymer chemistry depth. Avery Dennison Corporation occupies a position within the healthcare-specialist tier, leveraging adhesive formulation expertise for patient-wear compliance. Brady represents the industrial-grade converter archetype, sustaining margin control through captive film-coating capabilities and specification support for harsh-environment deployments.
| Leading Market Players |
|---|
| Brady |
| TE Connectivity |
| Panduit |
| 3M |
| Phoenix Contact |
| HellermannTyton |
| Avery Dennison Corporation |
| CCL Industries |
| Brother |
| Others |
Value Network & Pricing Analysis
Group purchasing organizations at United States hospital systems command consolidated procurement volumes, forcing converters toward contract-based long-term offtake structures with embedded volume discounts and performance guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified healthcare grades from industrial durability tiers and basic paper-based inventory solutions. Price differentiation hinges on certification grade and volume scale, with polyester medical wristbands commanding substantial premiums over vinyl shipping labels. Pricing pressure stems from REACH-compliant adhesive reformulation costs filtering through European converter pricing. Healthcare procurement committees demonstrate lowest price sensitivity due to patient-safety compliance mandates, while education and light retail buyers prioritize unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with petrochemical feedstock suppliers in the United States, Germany, and China, where polyester and vinyl substrate production concentrates. Raw material dependencies include crude oil derivatives for film substrates, acrylic monomers for pressure-sensitive adhesives, and release liners coated with silicone. Supply chain risk centers on tariff exposure for imported specialty adhesives subject to ECHA authorization delays. Distribution runs through converter-distributor partnerships for industrial MRO procurement, with direct sales channels capturing large healthcare system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA Unique Device Identification rules and EU Green Deal packaging mandates layering compliance-driven specification upgrades atop base demand.
For Market Incumbents: Deepen captive film-coating capabilities to defend margin position against petrochemical feedstock volatility and substrate-thinning investments required for EU sustainability compliance. Prioritize backward integration into adhesive formulation to offset REACH reformulation cost pass-throughs. Secure recycling partnerships anticipating extended producer responsibility frameworks. For New Entrants and Emerging Players: Enter via India's pharmaceutical export corridor, where cold-chain logistics for temperature-sensitive biologics creates unmet demand for moisture-resistant labels surviving condensation cycles. Target Maharashtra and Gujarat pharmaceutical clusters with condensation-resistant constructions. Pursue hybrid NFC-enabled label development for medical device authentication premiums. For Investors and Strategic Acquirers: Industrial conglomerates with polymer chemistry depth represent the most active acquirer in this space, seeking adhesive formulation capabilities and healthcare certification portfolios. Long-term viability rests on converters bridging sustainability mandates with durability performance. Watch ECHA substance authorization timelines as inflection indicators for reformulation investment cycles and competitive shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Coating | Captive substrate production insulates Brady and 3M from petrochemical volatility. |
| REACH-Compliant Adhesive Reformulation | ECHA authorization timelines force chemistry investments that reshape European converter economics. |
| Hybrid NFC-Enabled Label Development | Embedded authentication chips open premium tiers in FDA UDI-mandated medical device tracking. |
| Recycling Partnership Formation | EU extended producer responsibility frameworks reward established substrate-recovery networks. |
| Water-Based Acrylic Scale-Up | Eliminating VOC capture equipment rewrites cost structures for automotive under-hood applications. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining interviews with adhesive formulators, converter operations managers, hospital procurement committees, and industrial MRO buyers. Secondary validation draws from FDA 510(k) filings, ECHA substance authorization databases, customs trade data for film substrate imports, and SEC disclosures from diversified materials companies. Bottom-up demand modeling triangulates against top-down market sizing across label type, end user, and application segments.
Granularity-level modeling disaggregates volume and value outputs by material substrate, adhesive chemistry, printing technology, and regional regulatory cluster across the analysis window. CAGRs derive from segment-level growth rate reconciliation with macroeconomic drivers including healthcare infrastructure investment and industrial manufacturing output. Forecast inputs incorporate FDA UDI implementation pace, EU Green Deal packaging timeline acceleration, and automotive production forecasts from Germany's industrial corridor.
Inputs from hospital procurement databases and converter production records were available through the study window; gaps in real-time adhesive pricing transparency introduce uncertainty bands around margin projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Non-Adhesive Tags Market
Labels
Global Automotive Labels Market
Labels
Repositionable Labels Market
Labels
Glue Applied Automotive Labels Market
Labels
Global Tamper Evident Labels Market
Labels
Sustainable Labels Market
Labels
Hang Tags Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Inventory Tags Market
Labels
Oxygen Indicator Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Thermal Labels Market
Labels
Wrap Around Labels Market
Labels
Fiber Optic Labels Market
Labels
Tags Market
Labels
Primary Packaging Labels Market