
 Sleeve Label Market | 2026-2036
Sleeve Label Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeve Label Market Analytics
Software-defined color management and digital print workflows is consolidating value away from pure substrate supply toward integrated design-to-shelf services. CCL Industries leverages vertical integration across pre-press, extrusion, and recycling streams to capture margin from brand owners seeking closed-loop compliance. Avery Dennison Corporation sustains R&D intensity in wash-off adhesive technologies that enable PET bottle-to-bottle circularity. Berry Global anchors North American beverage volume through manufacturing scale in multi-layer shrink film.
Sleeve labels are tubular or flat substrates—typically polyethylene, polypropylene, or oriented polystyrene—that encircle containers and conform through heat or adhesive application, providing 360-degree printable surface area for branding, tamper evidence, and regulatory information. Shrink sleeves dominate value capture in carbonated soft drinks and craft beer where contoured bottles demand high conformability, while in-mold labels compete on permanence and scratch resistance in personal care. Digital printing technology grows fastest among printing methods, enabling run-length flexibility and SKU proliferation for private-label cosmetics and seasonal beverage promotions.
FDA food-contact substance regulations and the EU Packaging and Packaging Waste Regulation shape material selection, recyclability design, and market access for sleeve label suppliers serving transatlantic CPG brands. REACH restrictions on phthalate plasticizers in PVC formulations redirect formulation investment toward polyolefin alternatives. ISO 14001 environmental management certifications increasingly gate supplier qualification for multinational food and beverage procurement teams. Stakeholders must monitor sorting infrastructure investments and extended producer responsibility fee structures to align substrate choices with evolving cost-to-recover economics.
Market Dynamics
Sorting infrastructure investments across Germany, France, and Italy are reshaping substrate specifications as beverage brands redesign packaging for compatibility with existing recovery streams rather than building parallel collection systems.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets force CPG brands to specify polyolefin shrink sleeves over PVC alternatives, pulling through demand for compatible substrates.
- Digital print adoption:Beverage and cosmetics brands deploy inkjet and toner systems for seasonal SKU proliferation, compressing minimum order quantities from millions to thousands of units.
- German EPR infrastructure:Dual-system sorting investments create pull-through for sleeve labels designed to separate cleanly from PET bottles during mechanical recycling.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene feedstock prices track crude oil and natural gas benchmarks, compressing converter margins during energy price spikes.
- Asian supply concentration:Oriented polystyrene film production clusters in China and South Korea, exposing European converters to freight cost surges and currency swings.
- Sorting technology gaps:Near-infrared detection systems at municipal recovery facilities misidentify dark-pigmented shrink sleeves as contaminants, limiting color options for brand designers.
Strategic Opportunities
- Wash-off adhesive platforms:Avery Dennison and competitors invest in alkali-soluble formulations that release from PET during caustic washing, enabling bottle-to-bottle circularity under FDA food-contact rules.
- Poland and Czech Republic:Underpenetrated beverage markets with expanding modern retail formats create demand for premium sleeve-labeled imports and local production.
- Extended Producer Responsibility fee differentials:France and Italy modulate EPR contributions based on recyclability scores, incentivizing design-for-recycling investments.
Industry Challenges
- Pre-press talent scarcity:Converters struggle to hire operators fluent in both flexographic platemaking and digital workflow management as hybrid production expands.
- Multi-substrate certification timelines:ISO 14001 and EU food-contact compliance documentation for new film formulations extend qualification cycles by 12-18 months.
- Legacy press integration:Digital front-end systems require retrofitting of existing flexographic and gravure lines, creating production scheduling conflicts during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeve Label Market |
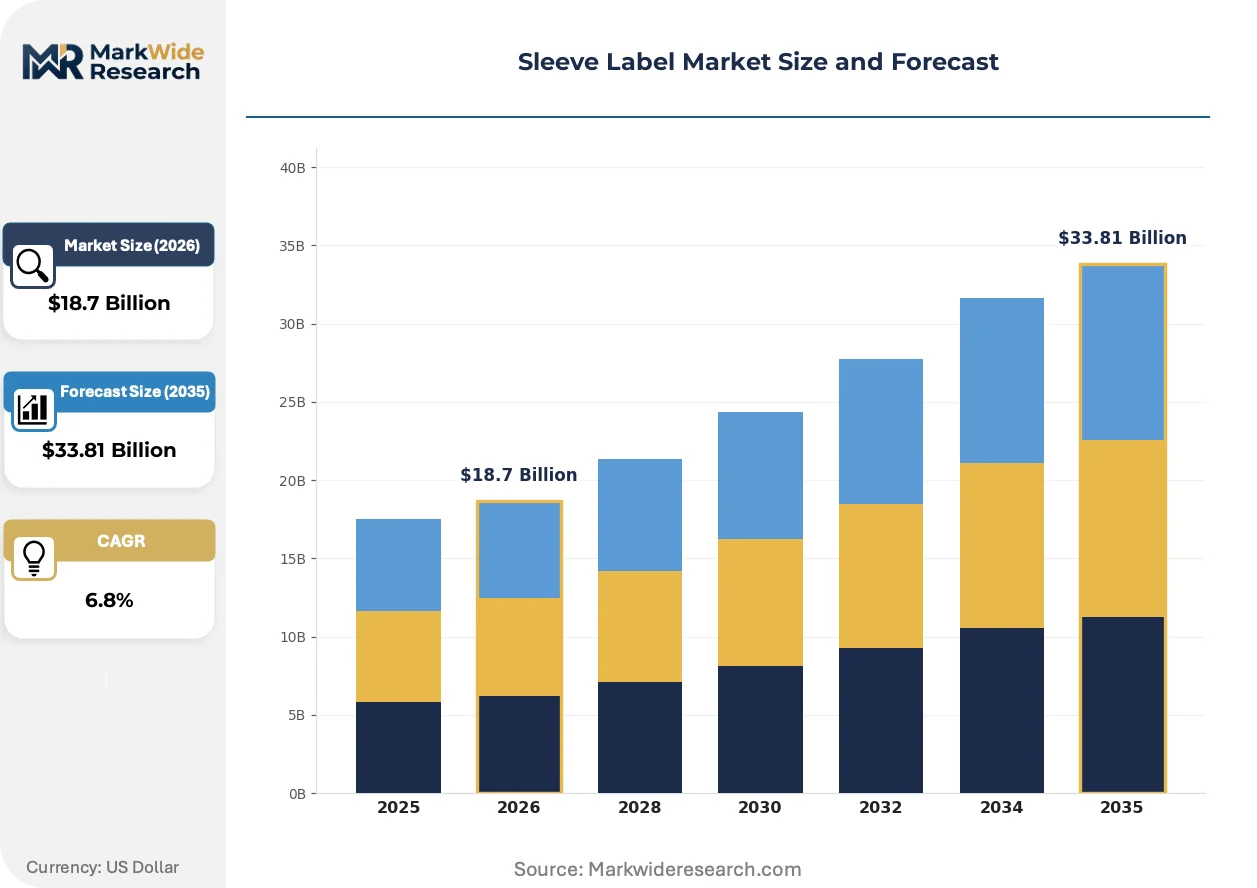
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, In-Mold Labels, Sleeve Wraps Material: Polyethylene, Polypropylene, PVC, Paper End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Printing Technology: Flexographic, Digital, Gravure, Offset |
| Companies Covered | CCL Industries, Berry Global, Fuji Seal International, Avery Dennison Corporation, Amcor plc, Huhtamaki, Klockner Pentaplast, Multi-Color Corporation, Fort Dearborn Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeve Label Market Evolving Landscape
Software-defined production workflows are collapsing traditional boundaries between design, pre-press, and manufacturing, enabling real-time substrate selection based on regional recycling infrastructure rather than static specifications.
Digital printing is converging with artificial intelligence-driven color management systems that predict substrate behavior during heat-shrink application. Craft beverage brands in Belgium and the Netherlands adopt these platforms for micro-batch seasonal releases, compressing design-to-shelf cycles from weeks to days. The technology is converging with cloud-based proofing tools that eliminate physical press checks, reducing waste and enabling distributed manufacturing.
REACH restrictions on phthalate plasticizers in PVC formulations have redirected formulation investment toward polyolefin shrink films across European converter operations. The regulation forces reformulation of legacy sleeve recipes used in personal care and household chemical applications. German and French brands now specify polyolefin substrates by default, treating PVC compatibility as a disqualifying factor in supplier qualification.
Brand owners are consolidating sleeve label procurement with secondary packaging specifications, demanding integrated design services that coordinate container shape, label conformability, and palletization efficiency. This bundling displaces standalone label converters who lack structural packaging engineering capabilities. The shift is most visible in Nordic markets where Arla Foods and Carlsberg Group enforce supplier integration across primary and secondary packaging tiers.
Sleeve Label Market Segmentation
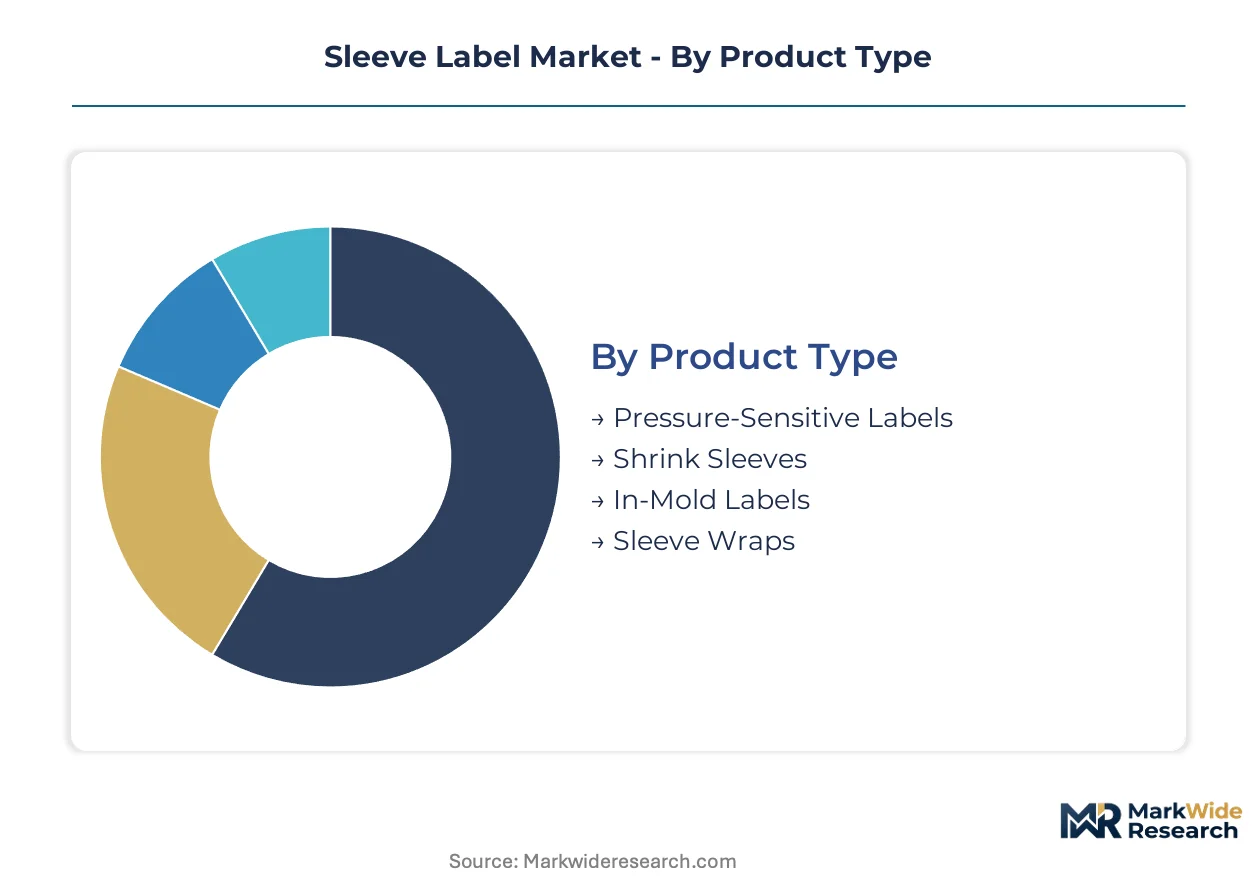
Sleeve label procurement decisions cascade through substrate chemistry, container geometry, and regulatory compliance requirements. Brand owners map these technical specifications against recovery infrastructure capabilities to qualify suppliers.
Product Type:
Upgrade cycles in beverage packaging are compressing as brands pivot from legacy adhesive formats to conformable sleeve architectures that maximize shelf impact.
- Shrink Sleeves:Multi-layer polyolefin or oriented polystyrene substrates that conform to contoured containers through controlled heat application, delivering 360-degree printable surface area. Carbonated soft drink brands in Germany and craft beer producers in Belgium specify these for complex bottle geometries where flat labels fail to adhere. REACH restrictions on phthalate plasticizers are accelerating migration from PVC-based alternatives.
- Pressure-Sensitive Labels:Face-stock materials laminated with permanent or removable adhesives that bond without heat activation, dominating flat-surface applications where conformability is unnecessary. Wash-off adhesive R&D at Avery Dennison targets PET bottle-to-bottle circularity under FDA food-contact regulations.
- In-Mold Labels:Polypropylene films fused to container walls during blow-molding or injection-molding, creating permanent scratch-resistant decoration for personal care and household chemical segments.
- Sleeve Wraps:Partial-coverage sleeve formats applied to specific container zones for tamper evidence or promotional banding, common in pharmaceutical secondary packaging.
Shrink sleeves sit at the top of the volume ranking, with in-mold labels climbing the fastest in premium personal care applications.
Material:
Raw material selection now hinges on near-infrared detectability at municipal recovery facilities rather than purely on printability or cost.
- Polyethylene:Linear low-density and high-density grades offering balanced shrink performance and mechanical recycling compatibility. French beverage brands specify polyethylene shrink sleeves to optimize EPR fee differentials under national extended producer responsibility modulation.
- Polypropylene:Oriented and cast film variants with superior clarity and stiffness, preferred for in-mold label applications where permanence matters. Italian converters favor polypropylene for its clean separation characteristics in existing sorting infrastructure.
- PVC:Legacy substrate with excellent shrink ratios but declining adoption due to ECHA REACH restrictions on phthalate plasticizers and chlorine content complicating mechanical recycling.
- Paper:Fiber-based sleeve formats for short-run promotional applications and brands pursuing plastic reduction narratives, limited by moisture sensitivity in beverage cold-chain distribution.
Polyethylene dominates current procurement volumes, though polypropylene is expanding most quickly as in-mold label adoption accelerates.
End User:
Customer procurement patterns diverge sharply between high-SKU-velocity beverage segments and stability-focused pharmaceutical applications.
- Food & Beverage:Carbonated soft drinks, craft beer, and functional beverages driving shrink sleeve specification for contoured glass and PET containers. German sorting infrastructure investments create pull-through for polyolefin substrates designed to separate cleanly during caustic washing.
- Cosmetics:Premium skincare and fragrance brands prioritizing in-mold labels for scratch resistance and tactile quality, with digital print enabling micro-batch seasonal releases.
- Pharmaceuticals:Regulatory serialization requirements and tamper-evidence mandates favoring pressure-sensitive labels with integrated security features over sleeve formats.
- Household Products:Bleach and cleaning chemical brands specifying solvent-resistant PVC or polyolefin sleeves for chemical compatibility, though REACH is forcing reformulation toward phthalate-free alternatives.
Food & beverage commands the largest share of sleeve label procurement, while cosmetics generates the steepest expansion trajectory through digital print adoption.
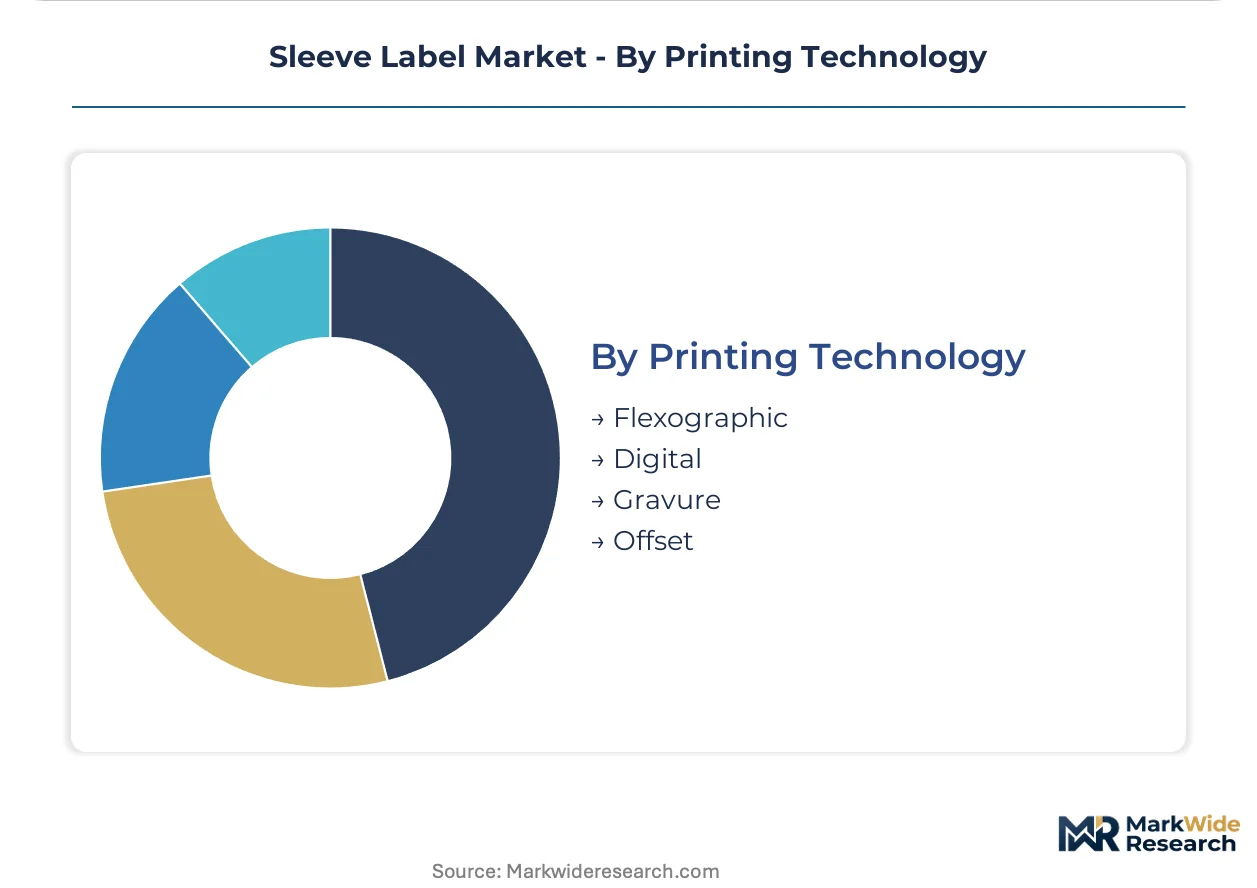
Printing Technology:
Capital deployment in press technology is bifurcating between long-run flexographic efficiency and digital run-length flexibility.
- Flexographic:Rotary letterpress-derived technology using photopolymer plates and anilox rollers, dominating high-volume beverage runs where plate costs amortize across millions of units. Berry Global anchors North American volume through flexographic scale.
- Digital:Inkjet and electrophotographic systems eliminating platemaking and enabling run-length compression from millions to thousands, critical for private-label cosmetics and seasonal beverage promotions. CCL Industries integrates digital front-ends with pre-press workflows to collapse design-to-shelf cycles.
- Gravure:Engraved cylinder technology delivering superior ink laydown and metallic effects, concentrated in high-end personal care where visual differentiation justifies cylinder investment.
- Offset:Lithographic transfer process limited in sleeve applications by substrate handling constraints, primarily serving paper-based sleeve formats and pre-printed liner materials.
Flexographic output leads by absolute volume, though digital is gaining share fastest as SKU proliferation accelerates across beverage and cosmetics segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in sleeve label procurement intensity despite sharing the EU regulatory framework, with German beverage brands specifying polyolefin substrates at higher rates due to mature sorting infrastructure investments.
Germany
Beverage brands in Bavaria and North Rhine-Westphalia specify polyethylene shrink sleeves for contoured PET bottles. The country's dual-system EPR scheme modulates fees based on recyclability scores, incentivizing design-for-recycling investments. Stuttgart-area converters develop alkali-soluble adhesive platforms that release cleanly during caustic washing.
France
Paris-headquartered cosmetics houses drive in-mold label specification for premium skincare packaging. Extended producer responsibility fee differentials under national modulation schemes reward polyolefin substrate selection. Lyon-based converters integrate digital front-ends with flexographic lines for seasonal SKU compression.
United States
Carbonated soft drink brands in Texas and California specify multi-layer shrink films for complex bottle geometries. FDA food-contact substance regulations govern wash-off adhesive qualification for PET bottle-to-bottle circularity. Chicago-area converters anchor North American beverage volume through manufacturing scale.
Italy
Sparkling water and prosecco producers in Veneto and Emilia-Romagna favor polypropylene sleeves for clarity and stiffness. National sorting infrastructure investments near Milan and Bologna accommodate clean label separation during mechanical recycling. Turin-based converters specialize in gravure-printed metallic effects for luxury beverage applications.
Belgium
Craft beer producers in Flanders adopt digital printing platforms for micro-batch seasonal releases. REACH restrictions on phthalate plasticizers redirect formulation toward polyolefin alternatives across converter operations. Brussels-area pre-press specialists collapse design-to-shelf cycles through cloud-based proofing tools.
Sleeve Label Market Competitive Landscape
Top-tier vendors anchor integrated design-to-shelf services, while mid-scale converters compete on regional logistics and substrate specialization. The market structure consolidates around players with captive recycling stream access and pre-press workflow control. Three archetypes dominate: vertically integrated film extruders, digital-native specialists, and legacy flexographic scale operators. Competitive moves concentrate on strategic partnerships with sorting infrastructure providers and portfolio diversification into wash-off adhesive platforms.
Within the integrated-tier vector, CCL Industries and Avery Dennison Corporation exemplify archetypes combining pre-press capability with recycling stream engineering. Berry Global occupies a position representing North American scale concentration in multi-layer shrink film production. Fuji Seal International sits within the Asia-Pacific supply chain cluster, reflecting regional substrate sourcing patterns.
| Leading Market Players |
|---|
| CCL Industries |
| Berry Global |
| Fuji Seal International |
| Avery Dennison Corporation |
| Amcor plc |
| Huhtamaki |
| Klockner Pentaplast |
| Multi-Color Corporation |
| Fort Dearborn Company |
| Others |
Value Network & Pricing Analysis
Pre-press operator concentration in Stuttgart and Lyon drives labor-cost differentials that separate premium digital-native converters from standard-tier flexographic operators across European sleeve label procurement.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standard-grade polyethylene shrink sleeves, compressing margins for legacy Western European converters. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by digital workflow capability and EPR compliance certification. Pricing pressure stems from resin cost volatility tracking natural gas benchmarks, with private-label beverage brands exhibiting highest price sensitivity and premium cosmetics houses showing least.
Supply Chain Analysis
Freight cost surges on Asia-Europe routes expose converters dependent on Chinese and South Korean oriented polystyrene film supply. Raw material sourcing draws from Saudi Arabian polyethylene, Belgian polypropylene, and Taiwanese film substrates. Single-source vulnerability concentrates in phthalate-free adhesive formulations qualified under REACH. Distribution runs through converter-direct relationships with multinational beverage brand procurement teams, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards margin expansion through digital workflow adoption that collapses design-to-shelf cycles and commands premium pricing from craft beverage brands.
For Market Incumbents: Extend pre-press workflow control into cloud-based proofing and AI-driven color management to defend against digital-native specialists. Deepen backward integration into alkali-soluble adhesive platforms that release cleanly from PET during caustic washing. Capture EPR fee differentials by qualifying polyolefin substrates under French and Italian modulation schemes. For New Entrants and Emerging Players: Regional sorting infrastructure providers represent the most accessible channel partner type for market entry. Target Poland and Czech Republic beverage markets where modern retail expansion outpaces local converter capacity. Deploy digital inkjet platforms for micro-batch seasonal releases to establish footprint before flexographic scale investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale flexographic operators lacking digital front-end integration and recycling stream partnerships. Long-term viability hinges on captive access to wash-off adhesive technologies and pre-press talent pipelines. Monitor German EPR fee modulation announcements as inflection indicator for substrate specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Workflow Integration | CCL Industries collapses design-to-shelf cycles from weeks to days for craft beverage brands. |
| Wash-off Adhesive Platform Development | Avery Dennison enables PET bottle-to-bottle circularity under FDA food-contact substance regulations. |
| Backward Integration into Film Extrusion | Berry Global anchors North American beverage volume through captive multi-layer shrink film supply. |
| EPR Compliance Certification Investment | Converters qualify for French fee differentials by documenting polyolefin substrate recyclability scores. |
| Pre-press Talent Pipeline Development | Stuttgart-area technical institutes train operators fluent in hybrid flexographic-digital workflows. |
Research Methodology
Bottom-up beverage and cosmetics brand modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with pre-press directors, procurement leads at multinational CPG brands, EPR scheme administrators, and recycling facility operators combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance restrictions, and customs trade data on polyethylene and polypropylene film imports.
Historical trendline analysis of substrate specification shifts and printing technology adoption patterns informed projection frameworks across the modeling period. Segmentation dimensions include product type, material chemistry, end-use vertical, and printing technology tier. CAGRs derive from elasticity modeling against EU regulatory compliance deadlines and digital press installation trajectories. Forecast inputs incorporate German dual-system EPR fee modulation schedules and near-infrared sorting infrastructure deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH restriction expansions and resin price volatility. Forecasts reflect documented assumptions about regulatory enforcement consistency and brand owner sustainability commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Label Applicator Market
Labels
Self-Laminating Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Direct Thermal Labels Market
Labels
Extended Text Labels Market
Labels
Wet Glue Labels Market
Labels
BOPP Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Europe Self Adhesives Label Market
Labels
Ripeness Indicator Labels Market
Labels
Global Label Market
Labels
Stretch Sleeve Labels Market
Labels
Wire Marking Labels Market
Labels
Holographic Scratch-Off Labels Market
Labels
Ethical Label Market
Labels
Wash Off Labels Market