
 Repositionable Labels Market | 2026-2036
Repositionable Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Repositionable Labels Market Analytics
Southeast Asia is tilting toward repositionable label production as Thailand and Vietnam expand converting capacity for export markets. Avery Dennison Corporation leverages its materials science portfolio to dominate premium film-based repositionable solutions across North America and Europe. CCL Industries anchors its position through backward integration into specialty adhesive polymers, while Huhtamaki competes aggressively in food-grade repositionable packaging labels with proprietary low-tack formulations.
Repositionable labels are pressure-sensitive constructions featuring removable or low-tack adhesives that permit clean detachment and reapplication without substrate damage, typically manufactured through silicone release coating and face stock lamination processes for temporary identification, pricing, and inventory tracking. Plastic and film substrates command the widest margin pools due to their durability in logistics environments, whereas paper repositionable labels retain volume leadership in retail promotional applications where single-use economics prevail. The adhesive type dimension separates removable formulations, which dominate pharmaceutical vial labeling, from repositionable grades gaining share in reusable container tracking systems.
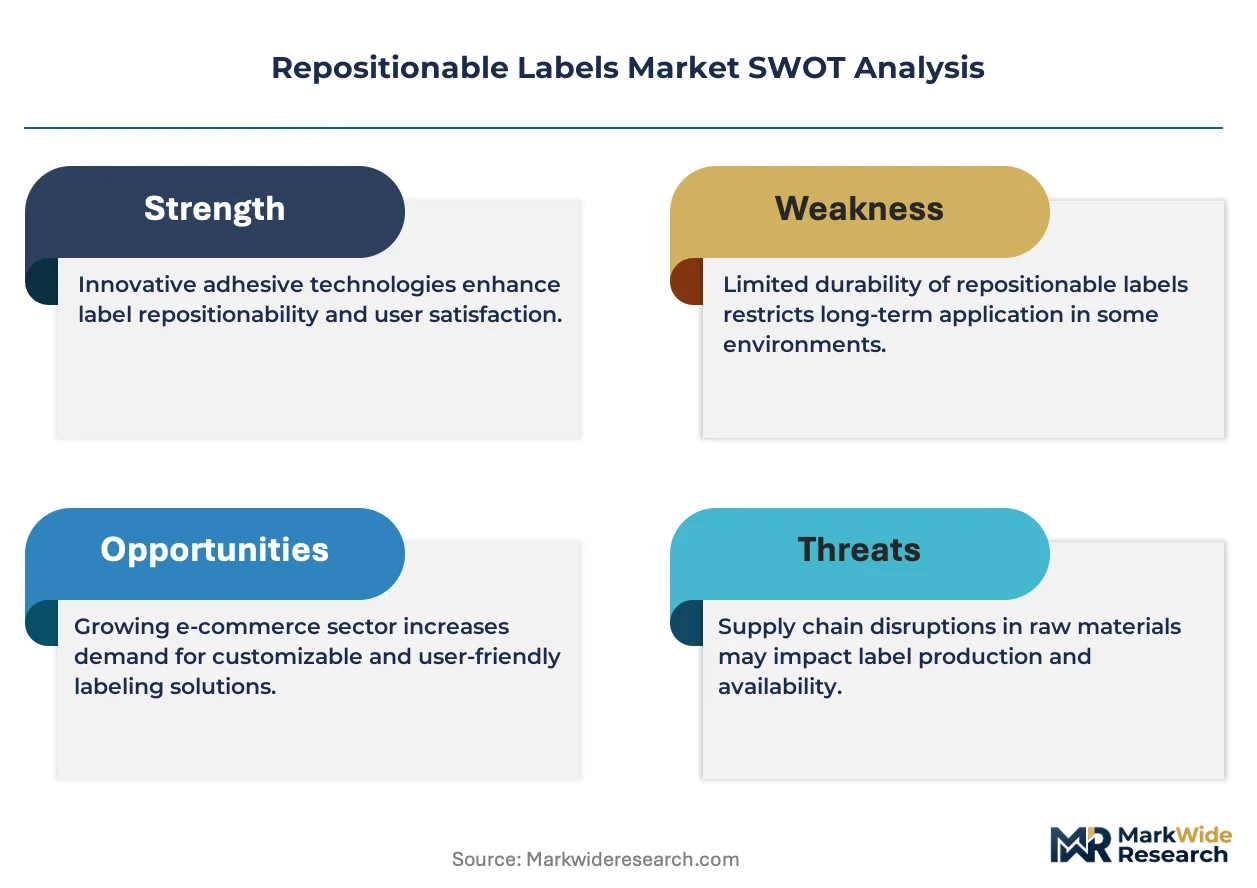
FDA regulations govern adhesive migration limits in pharmaceutical and food-contact repositionable labels, while EPA standards constrain solvent-based adhesive emissions during manufacturing. REACH compliance in Europe restricts certain plasticizers in vinyl face stocks, reshaping raw material sourcing for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks as these determine whether repositionable constructions qualify for recycling stream acceptance or face disposal cost penalties.
Market Dynamics
E-commerce fulfillment networks are forcing repositionable label specifications toward higher cycle counts and cleaner release profiles, as automated sortation systems reject labels that leave adhesive residue on reusable totes and poly-mailers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The regulation's material traceability mandates are compelling logistics operators to adopt removable barcode labels that maintain data integrity across multiple handling cycles without substrate degradation.
- Reusable container tracking systems:Food and beverage distributors in Germany's industrial labeling corridor are deploying repositionable RFID-enabled labels to monitor asset rotation through washing and sterilization protocols.
- Silicone release coating advances:Low-surface-energy formulations developed for pharmaceutical vial applications are migrating into cold-chain logistics, enabling clean detachment from condensation-prone surfaces.
Market Restraints
- Specialty adhesive polymer concentration:Backward integration by dominant film substrate producers limits independent converter access to proprietary low-tack formulations, constraining margin flexibility for mid-tier competitors.
- REACH plasticizer restrictions:The regulation's constraints on phthalate alternatives in vinyl face stocks force raw material requalification, extending product development timelines for exporters serving European pharmaceutical clients.
- Paper substrate price volatility:Pulp cost fluctuations and energy-intensive drying processes compress converter margins in retail promotional segments where single-use economics resist price pass-through.
Strategic Opportunities
- Thailand and Vietnam converting expansion:Southeast Asian production capacity growth creates export supply for Australian and Middle Eastern markets seeking alternatives to European sourcing.
- Extended producer responsibility frameworks:Recycling stream acceptance criteria under development in multiple jurisdictions will advantage repositionable constructions that qualify for clean material recovery versus disposal cost penalties.
- Digital printing convergence:Integration of inkjet systems with in-line silicone coating enables short-run customization for pharmaceutical serialization without plate changeover costs.
Industry Challenges
- Adhesive migration testing protocols:FDA validation requirements for pharmaceutical and food-contact applications demand extended extraction studies that extend commercialization timelines by 12-18 months.
- Release liner waste management:Converters face escalating disposal costs for silicone-coated backing materials as municipal waste streams reject multi-layer constructions, forcing investment in delamination and fiber recovery equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Repositionable Labels Market |
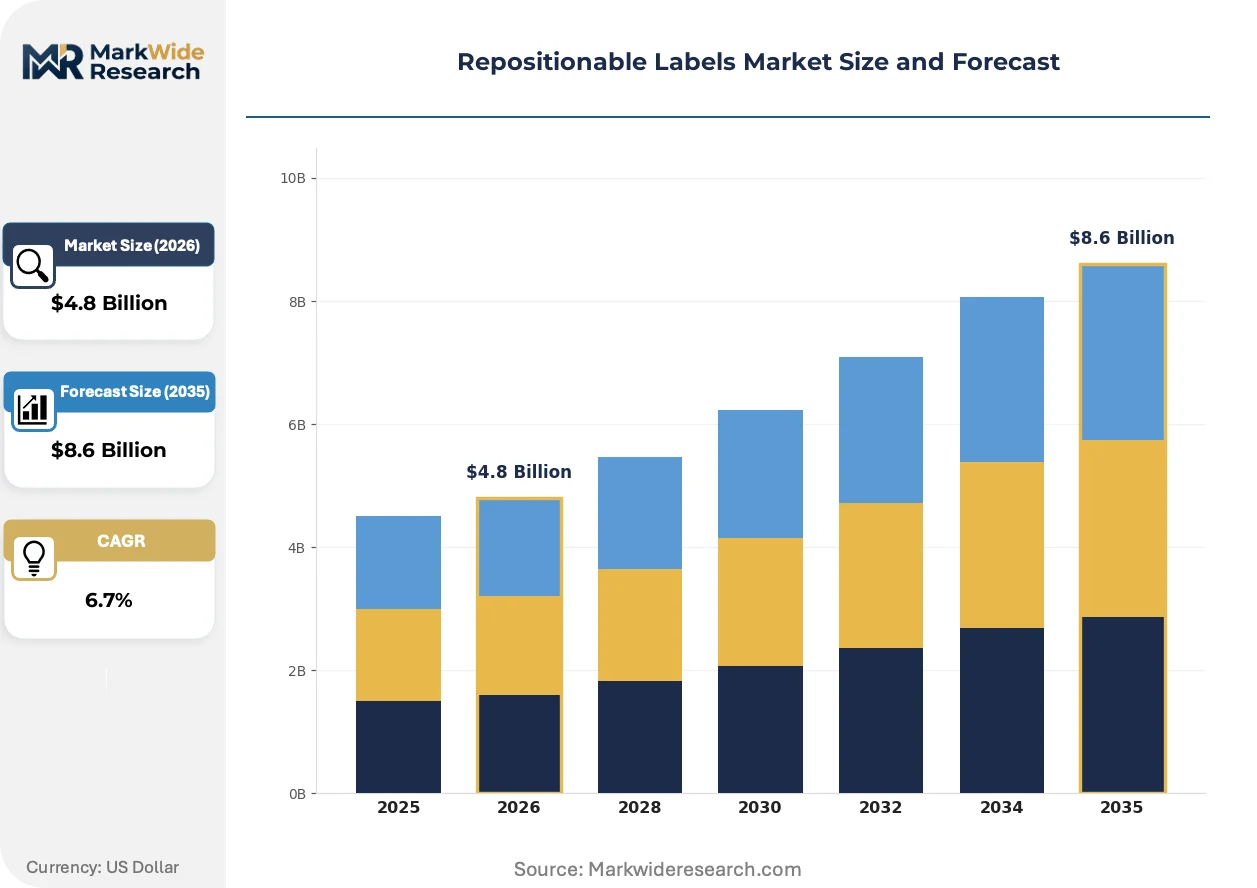
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Plastic, Vinyl, Film End User: Consumer Goods, Food & Beverage, Pharmaceuticals, Retail Adhesive Type: Removable, Repositionable, Permanent, Low-Tack Application: Promotional, Inventory Management, Packaging, Addressing |
| Companies Covered | Multi-Color Corporation, Huhtamaki, Avery Dennison Corporation, StickerYou Inc, Fuji Seal International, CCL Industries, Consolidated Label Co, 3M, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repositionable Labels Market Evolving Landscape
Digital production workflows and regulatory material restrictions are converging to redefine repositionable label specifications, compressing minimum order quantities while expanding performance requirements across temperature and humidity extremes.
Water-based acrylic adhesive systems are collapsing the performance gap between removable and permanent constructions in logistics applications. Third-party fulfillment operators in the Netherlands and Belgium are specifying these formulations for seasonal promotional campaigns requiring clean removal from corrugated shippers. The technology is collapsing converter inventory requirements by enabling single-base-stock strategies across multiple adhesion grades.
REACH Annex XVII restrictions on organotin catalysts in silicone release coatings are forcing reformulation of standard curing systems. European adhesive suppliers are qualifying platinum-catalyzed alternatives that maintain release stability across wider temperature ranges. Pharmaceutical label converters serving German and French markets are absorbing qualification costs fastest, driven by batch-level traceability requirements under the EU Falsified Medicines Directive.
Direct-to-brand procurement models are disintermediating traditional distributor channels in North American e-commerce labeling. Large fulfillment networks are consolidating specification authority and negotiating directly with film substrate producers for custom constructions. This pattern is most visible among California and Texas-based operators managing multi-tenant warehouse facilities where label standardization across clients reduces operational complexity.
Repositionable Labels Market Segmentation
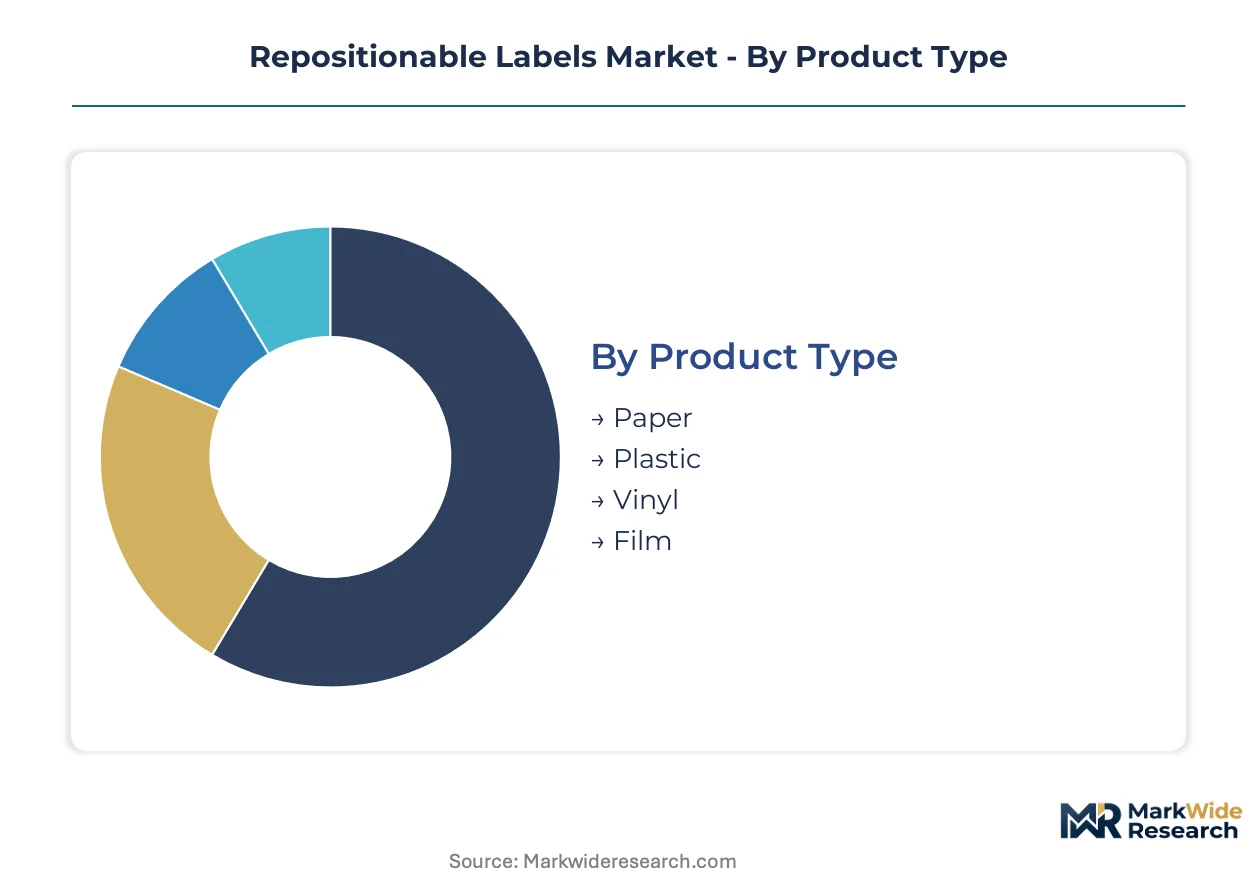
Repositionable label specifications diverge sharply across use-case durability requirements, from single-cycle retail promotions to multi-hundred-cycle logistics tracking. Material selection and adhesive chemistry must align with substrate compatibility, environmental exposure, and regulatory contact limits.
Product Type:
The use-case spectrum spans temporary indoor signage through cold-chain logistics, with substrate durability determining economic viability across cycle counts.
- Film:Polyester and polypropylene constructions deliver moisture resistance and dimensional stability for automated sortation environments. Demand concentrates in German pharmaceutical distribution hubs where condensation-prone cold storage demands clean release without adhesive transfer.
- Paper:Calendered wood pulp face stocks with silicone release coatings dominate retail promotional applications where single-use economics prevail and moisture exposure is minimal. Pulp cost volatility compresses converter margins in this volume-leading segment.
- Plastic:Polyethylene and polyolefin substrates balance conformability with tear resistance for curved container surfaces. Food-grade formulations from Huhtamaki serve reusable container tracking in beverage distribution networks.
- Vinyl:Plasticized PVC face stocks face REACH Annex XVII restrictions on phthalate alternatives, forcing raw material requalification for exporters serving European pharmaceutical clients.
The dominant share belongs to Paper, while Film is closing the gap fastest as logistics operators specify higher durability for reusable packaging systems.
End User:
Customer procurement patterns separate specification-driven pharmaceutical buyers from price-sensitive retail operators.
- Pharmaceuticals:FDA-regulated adhesive migration limits govern vial and syringe labeling where clean detachment prevents contamination. Extended extraction studies extend commercialization timelines by 12-18 months for new formulations.
- Retail:Seasonal promotional campaigns drive demand for clean-removal pricing labels on glass and coated paperboard. Dutch and Belgian fulfillment operators specify water-based acrylic systems for corrugated shipper compatibility.
- Food & Beverage:FSSAI and FDA food-contact compliance requirements constrain adhesive selection for direct-contact packaging applications.
- Consumer Goods:Beauty and electronics brands deploy repositionable labels for limited-edition packaging where premium unboxing experiences justify higher material costs.
Pharmaceuticals commands the specification authority, while Retail generates the highest unit volumes through promotional turnover.
Adhesive Type:
Performance gradients separate clean-release formulations from aggressive tack systems.
- Removable:Medium-tack acrylic emulsions permit detachment without residue for pharmaceutical vial applications. German and French markets absorb qualification costs fastest under EU Falsified Medicines Directive batch-level traceability requirements.
- Repositionable:Ultra-low-tack silicone-modified systems enable multiple reapplication cycles for reusable container tracking. RFID-enabled constructions from CCL Industries monitor asset rotation through washing and sterilization protocols.
- Low-Tack:Proprietary formulations compete in food-grade packaging where adhesive transfer must remain below detection thresholds.
- Permanent:Standard pressure-sensitive adhesives serve transitional applications where initial repositionability converts to fixed attachment.
Removable formulations anchor current revenue, though Repositionable grades are expanding most quickly into circular economy packaging systems.
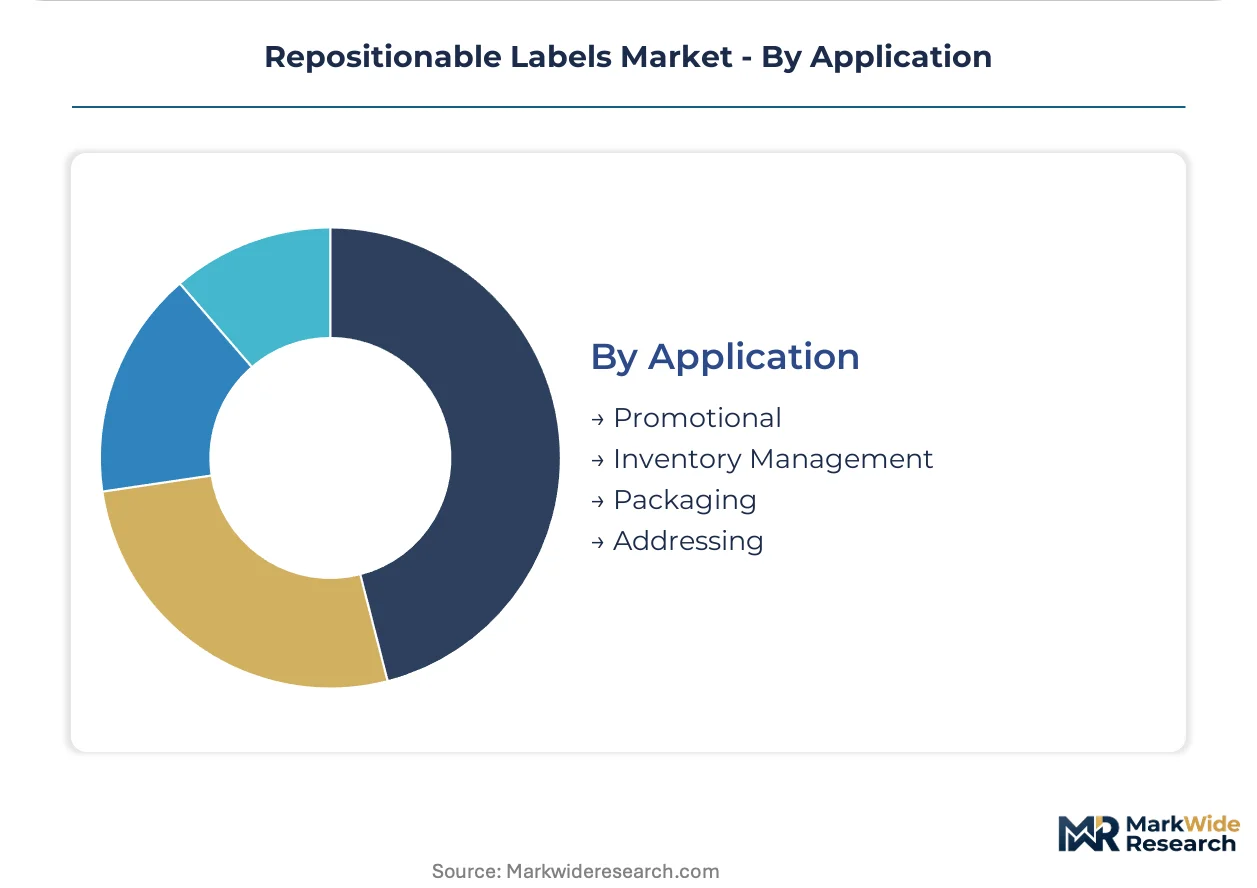
Application:
Functional requirements separate static information display from dynamic data capture.
- Inventory Management:Barcode and RFID-enabled labels track assets through multiple handling cycles in e-commerce fulfillment networks. Automated sortation systems reject constructions leaving adhesive residue on reusable totes.
- Packaging:Primary and secondary package labeling demands substrate compatibility with corrugated, film, and rigid container surfaces. California and Texas-based fulfillment networks negotiate directly with film substrate producers for custom constructions.
- Promotional:Short-run seasonal campaigns require digital printing compatibility with in-line silicone coating for plateless customization.
- Addressing:Shipping label applications prioritize print contrast and moisture resistance over multiple reapplication cycles.
Inventory Management leads technology investment, while Packaging offers the broadest addressable surface area across end-use verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Material science capabilities cluster around Düsseldorf and Cologne in Germany, where specialty adhesive polymer production feeds European pharmaceutical and logistics demand. Thailand and Vietnam are expanding converting capacity for export markets, while North American e-commerce fulfillment networks drive specification authority toward direct-to-brand procurement models.
United States
FDA adhesive migration limits govern pharmaceutical vial labeling applications where clean detachment prevents contamination. EPA standards constrain solvent-based adhesive emissions during manufacturing in Ohio and Illinois converting corridors. California and Texas-based fulfillment networks negotiate directly with film substrate producers for custom repositionable constructions in multi-tenant warehouse facilities.
Germany
REACH Annex XVII restrictions on phthalate alternatives in vinyl face stocks force raw material requalification for exporters serving pharmaceutical clients. The EU Falsified Medicines Directive drives batch-level traceability requirements that absorb qualification costs fastest in German and French markets. The industrial labeling corridor around Düsseldorf and Cologne anchors specialty adhesive polymer production for reusable container tracking systems.
Thailand
Expanding converting capacity targets Australian and Middle Eastern markets seeking alternatives to European sourcing for repositionable label supply. National industrial policy supports packaging material exports through Board of Investment incentives for adhesive substrate manufacturing. Bangkok and Eastern Economic Corridor facilities serve regional distribution networks for food-grade and logistics applications.
Vietnam
Export-oriented production growth concentrates in Ho Chi Minh City and Binh Duong provinces for pressure-sensitive label converting. Manufacturing cost advantages attract investment from regional brand owners seeking supply chain diversification from China. Domestic demand from electronics assembly and food processing sectors drives specification familiarity with removable adhesive grades.
Netherlands
Third-party fulfillment operators in the Netherlands and Belgium specify water-based acrylic adhesive systems for seasonal promotional campaigns requiring clean removal from corrugated shippers. REACH compliance requirements shape raw material sourcing for converters serving pan-European pharmaceutical distribution. Rotterdam logistics hub proximity enables rapid specification response for cold-chain logistics applications.
Repositionable Labels Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in adhesive polymer and release coating supply. The vendor base separates between consolidated film substrate producers with captive adhesive formulation capabilities and fragmented converters dependent on third-party material supply. Three archetypes dominate: materials science conglomerates with backward integration into specialty polymers, mid-tier converters leveraging geographic proximity to end-use clusters, and digital-native platforms disintermediating traditional distribution. Competitive moves concentrate on strategic partnerships for silicone release coating technology and capacity expansion in Southeast Asian converting corridors.
Among materials science conglomerates, Avery Dennison Corporation and 3M occupy positions exemplifying premium film-based solution dominance across North America and Europe. CCL Industries anchors the specialty adhesive polymer tier through upstream control over proprietary low-tack formulations. Huhtamaki represents the food-grade packaging specialist archetype competing in repositionable labels for beverage distribution networks. These three entities illustrate how competitive positioning separates substrate-integrated players from converters dependent on external adhesive supply.
| Leading Market Players |
|---|
| Multi-Color Corporation |
| Huhtamaki |
| Avery Dennison Corporation |
| StickerYou Inc |
| Fuji Seal International |
| CCL Industries |
| Consolidated Label Co |
| 3M |
| LINTEC Corporation |
| Others |
Value Network & Pricing Analysis
Düsseldorf and Cologne's specialty adhesive polymer corridor concentrates formulation expertise that feeds downstream pricing power to converters serving pharmaceutical and logistics end users. Capacity tightness in silicone release coating supply lets integrated film substrate producers command premium realizations for multi-cycle repositionable constructions, while independent converters absorb margin compression from raw material concentration.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European repositionable label supply, separating compliant platinum-catalyzed silicone systems from legacy organotin-cured alternatives facing phase-out. Three-tier pricing structure across premium film-based, standard paper, and economy promotional levels reflects certification grade and cycle-count durability. Pricing pressure stems from pulp cost volatility compressing converter margins in retail promotional segments where single-use economics resist price pass-through. Retail operators exhibit highest price sensitivity, while pharmaceutical buyers prioritize FDA-validated adhesive migration compliance over unit cost.
Supply Chain Analysis
Specialty adhesive polymer feedstock draws from Germany, the United States, and Japan, with silicone resin production anchoring in the Düsseldorf industrial cluster and acrylic emulsion supply concentrating in Ohio and Illinois converting corridors. Raw material dependencies center on silicone resins, acrylic monomers, and release-coated liner substrates. Single-source vulnerability in pharmaceutical-grade silicone release coatings exposes converters to extended lead times during formulation requalification cycles. Distribution runs through direct-to-brand procurement models in North American e-commerce fulfillment networks and traditional converter-distributor channels in European pharmaceutical supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Repositionable label markets reward service-attach strategies where formulation requalification and serialization compliance services expand recurring revenue faster than base material supply. After-sales adhesive migration testing and FDA validation support packages capture margin pools inaccessible to commodity converters.
For Market Incumbents: Entrench specification authority by deepening captive supply of proprietary low-tack adhesive polymers and accelerating platinum-catalyzed silicone qualification for REACH Annex XVII compliance. Defend against Southeast Asian cost competition through integrated digital printing workflows that collapse minimum order quantities for pharmaceutical serialization. Prioritize certification investment in EU Falsified Medicines Directive batch-level traceability systems. For New Entrants and Emerging Players: Vietnam's expanding converting capacity represents underpenetrated white space for export-oriented producers targeting Australian and Middle Eastern markets seeking European sourcing alternatives. Food-grade repositionable packaging for beverage distribution networks offers the most penetrable application segment given Huhtamaki's concentrated position. Pursue go-to-market partnerships with regional brand owners in Ho Chi Minh City electronics assembly corridors to build specification familiarity before scaling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials science conglomerates with backward integration into specialty adhesive polymers over fragmented converters dependent on third-party supply. Long-term viability hinges on recycling stream acceptance criteria under extended producer responsibility frameworks. Acquisition target archetype: mid-tier converters with digital printing integration and established pharmaceutical validation protocols. Watch silicone release coating delamination technology as inflection indicator for circular economy qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Adhesive Polymers | CCL Industries' upstream control over proprietary low-tack formulations secures margin pools inaccessible to independent converters. |
| Digital Printing Workflow Integration | In-line silicone coating with inkjet systems enables short-run pharmaceutical serialization without plate changeover costs. |
| Platinum-Catalyzed Silicone Qualification | REACH Annex XVII organotin restrictions force reformulation investment that absorbs fastest in German and French markets. |
| Southeast Asian Converting Expansion | Thailand and Vietnam capacity growth targets Australian and Middle Eastern export markets seeking supply diversification. |
| Extended Producer Responsibility Compliance | Recycling stream acceptance criteria advantage repositionable constructions qualifying for clean material recovery versus disposal penalties. |
Research Methodology
A standing panel of adhesive formulation chemists, pharmaceutical packaging procurement managers, logistics operations directors, and converter plant managers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against FDA adhesive migration guidance documents, EPA solvent emission standards, ECHA REACH substance restrictions, and EU Packaging and Packaging Waste Regulation implementation texts. Bottom-up demand modeling across end-use segments triangulated with top-down supply capacity assessments from film substrate producers and silicone release coating manufacturers.
Scenario-bracketing framed volume and value projections across the analysis window, with sensitivity testing for pulp cost volatility, regulatory timeline acceleration, and e-commerce fulfillment network consolidation. Segmentation dimensions modeled included substrate type, adhesive chemistry, end-use vertical, application function, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for technology substitution effects and capacity expansion announcements. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate implementation pace and reusable container tracking system deployment rates in German beverage distribution networks.
Practitioners should monitor REACH plasticizer restriction enforcement intensity and extended producer responsibility framework finalization for early signals requiring forecast revision. Cross-checking against customs trade data for silicone resin and acrylic monomer import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Die Cut Labels Market
Labels
Label Applicator Market
Labels
Global Label Market
Labels
Wire Marking Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Global in-Mold Labels Market
Labels
Holographic Scratch-Off Labels Market
Labels
Global Pressure Labels Market
Labels
Heat Shrink Sleeve Market
Labels
ESD Protective Signage Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Water Dissolvable Labels Market
Labels
Safety Labels Market
Labels
Polyester Labels Market
Labels
HAZMAT Labels Market
Labels
Booklet Labels Market