
 High Gloss Labels Market | 2026-2036
High Gloss Labels Market Size, Share, and Industry Trends Forecast 2026-2036
High Gloss Labels Market Foresight
ISO 9001 quality management certification is redrawing competitive boundaries among label converters serving premium packaging tiers. Avery Dennison Corporation leverages its captive film-coating capacity to sustain margin control across polypropylene substrate lines. CCL Industries Inc. anchors its position through specialized pharmaceutical serialization capabilities on high-gloss stocks. UPM Raflatac competes via integrated pulp-to-label operations that secure fiber traceability for European brand owners.
High gloss labels are pressure-sensitive or adhesive-backed decorative facestocks engineered with specular reflectance values exceeding 70 GU at 60 degrees, typically constructed from cast-coated paper, biaxially oriented polypropylene, or polyvinyl chloride with solvent-based or UV-cured lacquer topcoats. Their primary commercial purpose is to deliver premium visual hierarchy on retail shelves, where surface brilliance signals quality tier and commands attention in cluttered point-of-sale environments. Polypropylene substrates lead volume owing to dimensional stability and moisture resistance, while digital printing technology represents the fastest-expanding output method as brand owners compress design-to-shelf cycles for limited-edition campaigns. Pressure-sensitive adhesive types dominate the specification mix, though repositionable variants are gaining traction in reusable premium cosmetics packaging where residue-free removal protects container aesthetics.
FDA regulations govern indirect food-contact compliance for labels affixed to edible product packaging, while EPA oversight of volatile organic compound emissions constrains solvent-based coating operations in domestic manufacturing. REACH and the EU Green Deal are jointly phasing out certain phthalate plasticizers common in legacy PVC facestocks, redirecting formulation investment toward bio-based alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs will soon assign end-of-life collection costs directly to label converters rather than downstream packagers.
Market Dynamics
REACH compliance and the EU Green Deal are forcing converters to reformulate adhesives and phase out phthalate plasticizers in legacy PVC facestocks, restructuring raw material sourcing across European supply chains.
Growth Catalysts
- Premium cosmetics packaging:Western European luxury brands are accelerating specification of high-gloss finishes for shelf differentiation in saturated retail environments.
- REACH chemical disclosure:Tightening adhesive formulation requirements are consolidating demand among certified converters with compliant supply chains.
- Digital printing adoption:Brand owners compress design-to-shelf cycles for limited-edition campaigns, expanding short-run high-gloss output.
Market Restraints
- Solvent-based coating constraints:EPA volatile organic compound emission limits restrict domestic manufacturing capacity expansion for traditional lacquer topcoats.
- Film substrate concentration:Biaxially oriented polypropylene supply concentrates among Asian petrochemical producers, exposing converters to freight and tariff volatility.
- Bio-based adhesive immaturity:Performance gaps in pressure-sensitive bio-adhesives limit immediate substitution for fossil-derived formulations in moisture-critical applications.
Strategic Opportunities
- Repositionable adhesives:Residue-free removal variants are gaining traction in reusable premium cosmetics packaging where container aesthetics must be preserved.
- Extended producer responsibility frameworks:Emerging programs in multiple jurisdictions will assign end-of-life collection costs directly to label converters, creating first-mover advantage for circular-design specialists.
- Pharmaceutical serialization:Specialized track-and-trace capabilities on high-gloss stocks open regulated healthcare packaging segments with stringent authentication requirements.
Industry Challenges
- ISO 9001 certification timelines:Quality management accreditation demands 12-18 month implementation cycles that delay entry into premium packaging tiers.
- Fiber traceability integration:European brand owners require pulp-to-label documentation that strains legacy converter record-keeping systems.
- UV-cured lacquer capital intensity:Curing equipment upgrades require substantial investment for converters transitioning from solvent-based coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Gloss Labels Market |
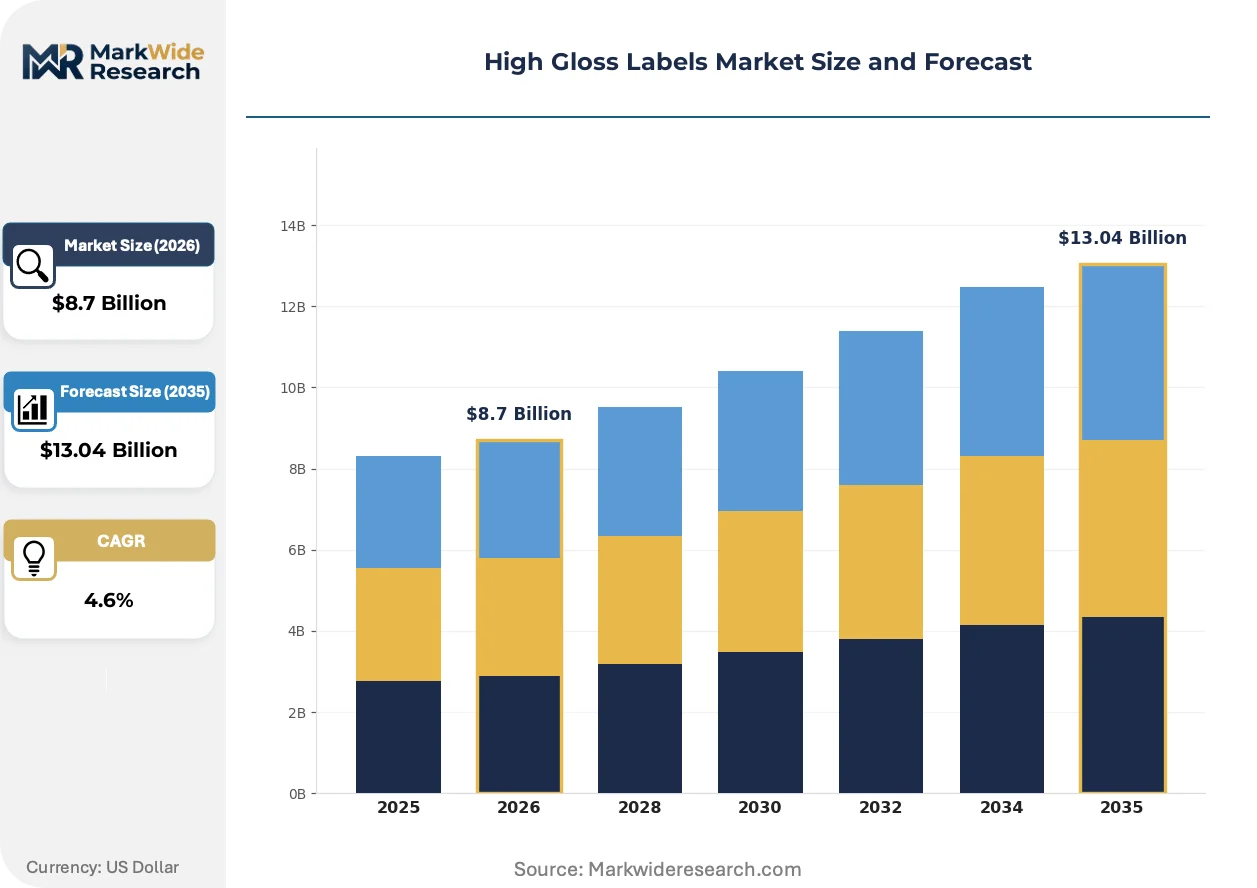
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: PVC, Paper, Polypropylene, Vinyl Adhesive Type: Permanent, Removable, Repositionable, Pressure-Sensitive End User: Food & Beverage, Cosmetics, Pharmaceuticals, Retail Printing Technology: Flexographic, Digital, Offset, Screen Printing |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., UPM Raflatac, 3M Company, Constantia Flexibles Group GmbH, Multi-Color Corporation, Mondi plc, SATO Holdings Corporation, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Gloss Labels Market Shifts & Advancements
Digital printing technology is compressing production cycles while regulatory pressure on chemical formulations is redirecting R&D investment toward bio-based alternatives.
UV-cured lacquer topcoats deliver specular reflectance exceeding 70 GU at 60 degrees with reduced volatile organic compound emissions. Premium cosmetics and spirits brands in Germany and France are specifying UV-cured finishes for limited-edition releases. This technology is supplanting solvent-based coating lines in facilities serving Western European luxury packaging markets.
REACH and the EU Green Deal are jointly phasing out certain phthalate plasticizers common in legacy PVC facestocks. Converters must reformulate toward bio-based alternatives or switch to polypropylene substrates entirely. Pharmaceutical and food-contact label segments face the tightest compliance deadlines and are accelerating supplier qualification processes.
Brand owners now compress design-to-shelf cycles from months to weeks for seasonal and influencer-collaboration campaigns. Short-run digital production is displacing conventional flexographic workflows in cosmetics and specialty food verticals. This pattern is most visible in France and Germany where luxury houses rotate packaging designs quarterly.
High Gloss Labels Market Segmentation
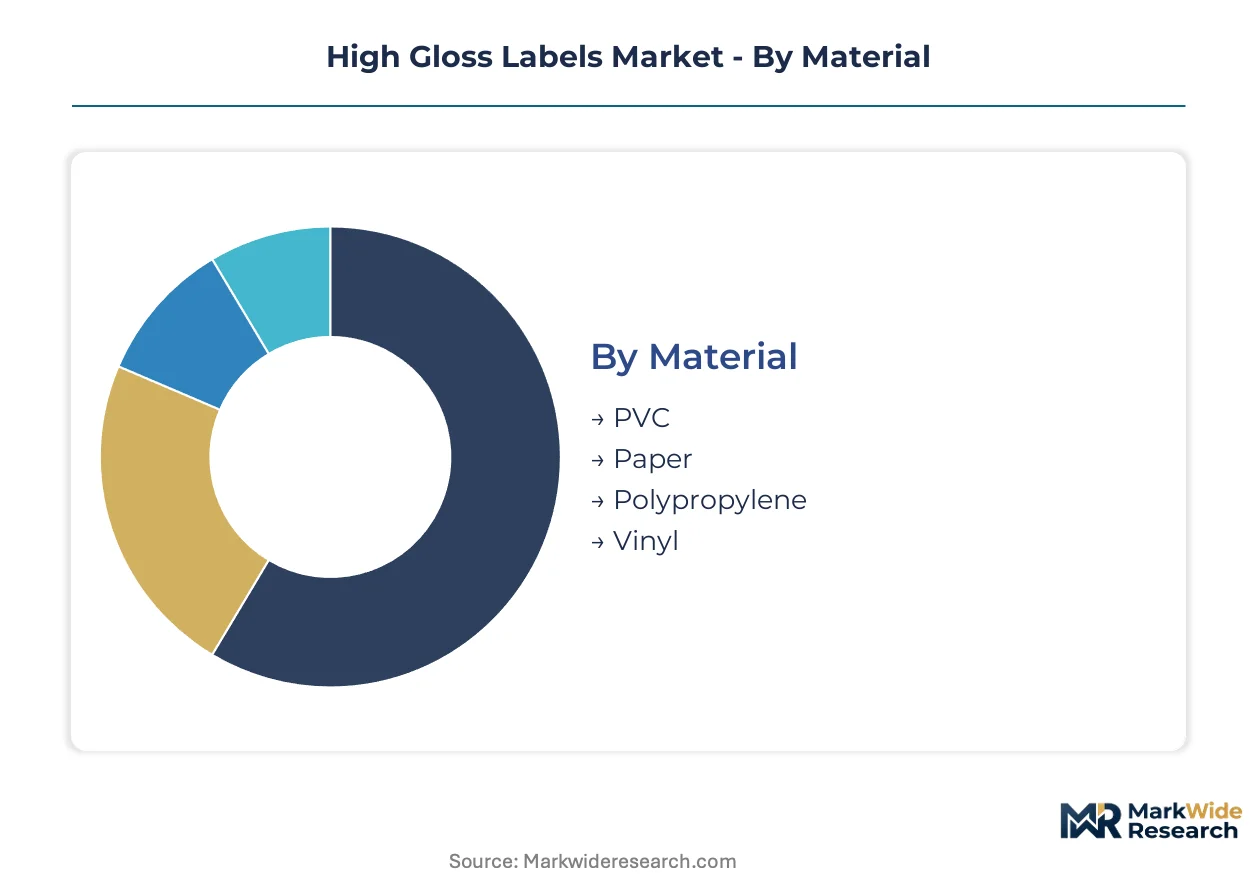
Material chemistry and adhesive performance define regulatory compliance pathways for high-gloss labels. Segmentation clarity enables converters to align substrate-adhesive combinations with specific end-use certification requirements.
Material:
REACH and the EU Green Deal are phasing out phthalate plasticizers in legacy formulations, redirecting specification toward compliant substrates.
- Polypropylene:Biaxially oriented polypropylene delivers dimensional stability and moisture resistance exceeding 70 GU specular reflectance. Demand concentrates in German and French cosmetics packaging where premium shelf differentiation commands specification priority.
- PVC:Legacy polyvinyl chloride facestocks face accelerated substitution as ECHA restrictions on phthalate plasticizers tighten compliance deadlines for pharmaceutical and food-contact segments.
- Paper:Cast-coated paper stocks serve spirits and specialty food verticals in Western Europe with integrated pulp-to-label traceability meeting brand owner documentation requirements.
- Vinyl:Flexible vinyl substrates retain niche positioning in durable goods labeling where moisture exposure and mechanical abrasion resistance outweigh sustainability preferences.
Established volume favors polypropylene; emerging adoption favors paper with certified fiber chains.
Adhesive Type:
Performance requirements in moisture-critical applications sustain fossil-derived formulation dominance despite bio-based R&D investment.
- Pressure-Sensitive:Acrylic and rubber-based pressure-sensitive adhesives dominate specification mix across premium packaging tiers, though repositionable variants gain traction in reusable cosmetics containers where residue-free removal preserves container aesthetics.
- Permanent:Permanent adhesives anchor food and beverage applications requiring tamper-evidence and extended shelf-life adhesion under refrigerated conditions.
- Repositionable:Repositionable formulations expand in luxury cosmetics where quarterly design rotations demand clean removal for container reuse.
- Removable:Removable adhesives serve promotional and temporary labeling segments with clean-release characteristics protecting underlying package surfaces.
Pressure-sensitive formulations capture the steepest expansion trajectory in limited-edition campaigns; permanent adhesives retain volume leadership in staple consumer goods.
End User:
Regulatory stringency varies sharply across verticals, with pharmaceutical serialization and FDA food-contact compliance imposing the tightest qualification barriers.
- Cosmetics:Premium cosmetics brands in Germany and France accelerate high-gloss specification for quarterly packaging rotations and influencer-collaboration launches, compressing design-to-shelf cycles to weeks.
- Pharmaceuticals:Pharmaceutical serialization mandates require specialized track-and-trace capabilities on high-gloss stocks, opening regulated healthcare segments with stringent authentication requirements.
- Food & Beverage:FDA indirect food-contact compliance governs adhesive and coating selection for edible product packaging, constraining formulation flexibility in domestic manufacturing.
- Retail:Retail applications span private-label spirits and specialty foods where UV-cured lacquer finishes signal quality tier in saturated point-of-sale environments.
Cosmetics drives specification innovation; pharmaceuticals commands margin premiums through compliance complexity.
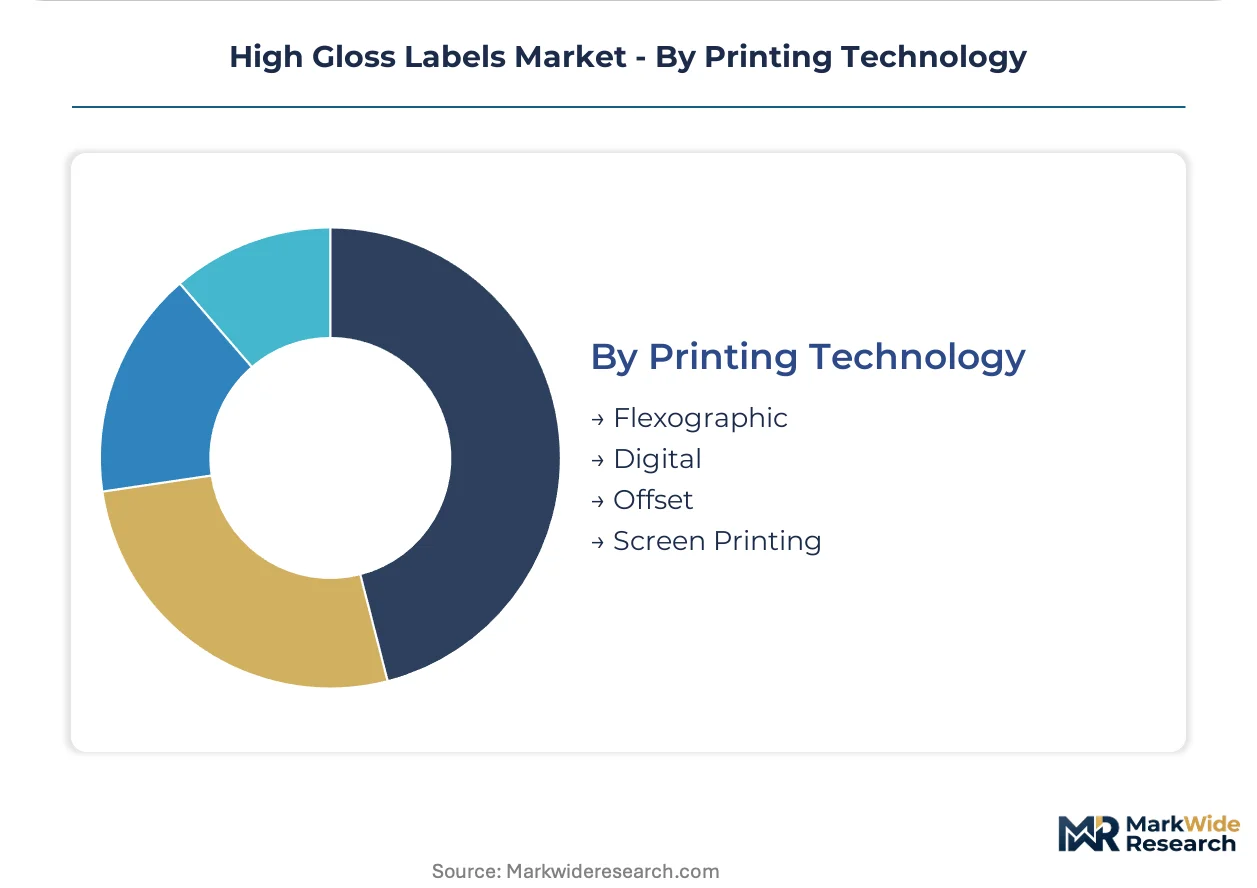
Printing Technology:
Capital intensity and run-length economics determine technology selection across converter footprints serving Western European luxury markets.
- Digital:Digital printing compresses production cycles from months to weeks, displacing conventional workflows in French and German luxury houses rotating designs quarterly for seasonal and collaboration releases.
- Flexographic:Flexographic output retains cost advantage in long-run staple goods where design stability spans annual production cycles.
- Offset:Offset lithography serves mid-volume cosmetics and spirits applications requiring precise color matching across extended print runs.
- Screen Printing:Screen printing delivers opaque, high-build effects for premium spirits and specialty cosmetics where tactile dimensionality reinforces luxury positioning.
Digital gains share fastest in limited-edition campaigns; flexographic retains volume dominance in continuous production schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Western Europe's dominance in high-gloss label distribution, connecting German and French converters to Asian film substrate suppliers. Rail corridors from Rotterdam to the Rhine-Ruhr and Paris basins enable just-in-time delivery of biaxially oriented polypropylene to label manufacturing clusters.
Germany
Premium cosmetics houses in Hamburg and Berlin drive quarterly packaging rotations requiring UV-cured lacquer finishes. REACH enforcement through ECHA is accelerating supplier qualification timelines for adhesive compliance. The Rhine-Ruhr manufacturing corridor concentrates converter capacity serving spirits and pharmaceutical serialization segments.
France
Limited-edition luxury launches from Paris-based beauty brands compress design-to-shelf cycles to weeks, expanding digital printing adoption. ANSM pharmaceutical labeling requirements intersect with EU Green Deal plasticizer restrictions, tightening formulation standards. The Île-de-France cluster anchors high-gloss production for fragrance and cosmetics exporters.
United States
FDA indirect food-contact compliance governs adhesive selection for specialty food packaging in California and New York Metro markets. EPA volatile organic compound limits constrain solvent-based coating expansion in domestic manufacturing. The Midwest converter belt around Chicago serves national spirits and retail private-label demand.
China
Dual carbon goals under MEE oversight are redirecting film substrate production toward lower-emission processes in the Yangtze River Delta. GB standards for food-contact materials impose parallel compliance burdens to Western regulations. The Pearl River Delta hosts packaging converter clusters supplying export-oriented cosmetics manufacturers.
India
FSSAI food-labeling regulations and CDSCO pharmaceutical serialization mandates are elevating compliance barriers for domestic converters. Maharashtra and Gujarat industrial corridors attract investment in UV-cured coating capacity to serve regional FMCG and generic drug exporters. BIS certification requirements concentrate demand among quality-accredited suppliers.
High Gloss Labels Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth, creating a tiered structure where scale advantages meet agility in compliance navigation. The market consolidates around converters with captive film-coating capacity and integrated pulp-to-label operations. Three archetypes dominate: multinational materials conglomerates with backward integration into substrates, mid-cap specialists with pharmaceutical serialization capabilities, and regional converters with digital printing flexibility. Competitive moves center on ISO 9001 certification acquisition and UV-cured lacquer line upgrades.
Within the multinational tier, Avery Dennison Corporation exemplifies scale-driven substrate control, while CCL Industries Inc. occupies a position emphasizing regulated healthcare packaging specialization. UPM Raflatac anchors the integrated pulp-to-label archetype with fiber traceability systems. These three represent distinct strategic postures: captive manufacturing, compliance complexity, and supply chain transparency.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| UPM Raflatac |
| 3M Company |
| Constantia Flexibles Group GmbH |
| Multi-Color Corporation |
| Mondi plc |
| SATO Holdings Corporation |
| Lintec Corporation |
| Others |
Supply & Pricing Matrix
Polypropylene substrate substitution for legacy PVC facestocks is simultaneously redrawing supply geography toward Asian petrochemical corridors and compressing pricing power among European converters lacking captive film-coating capacity. REACH-driven reformulation costs and freight volatility from concentrated BOPP supply are feeding through to margin structures across premium packaging tiers.
Pricing Analysis
Certification level creates the primary spread across converter quotations, with ISO 9001-accredited suppliers commanding substantial premiums over uncertified competitors in pharmaceutical and cosmetics segments. Three-tier pricing structure separates REACH-compliant specialty grades from standard industrial labels and economy promotional stocks. Pricing pressure stems from bio-based adhesive R&D investment cycles that strain mid-cap balance sheets before performance parity achievement. Private-label spirits buyers exhibit highest price sensitivity, while pharmaceutical serialization clients accept premium positioning for compliance-certain supply chains.
Supply Chain Analysis
South Korea, China, and Singapore anchor biaxially oriented polypropylene substrate production, with the Yangtze River Delta and Pearl River Delta hosting the densest film extrusion clusters serving export markets. Converter operations draw from solvent-based lacquer suppliers in Germany, UV-curable resin specialists in Japan, and release liner producers in Finland. Single-source vulnerability concentrates in Asian BOPP supply given limited Western alternatives with comparable dimensional stability. Distribution runs through Rotterdam port consolidation followed by rail corridors to Rhine-Ruhr and Paris basin manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales technical compliance consulting represents a faster-expanding revenue layer than substrate manufacturing itself, as brand owners outsource REACH documentation and fiber traceability audit preparation to qualified converter partners.
For Market Incumbents: Compound certification depth through ECHA-recognized testing laboratory partnerships that accelerate client supplier qualification timelines. Extend backward integration into UV-cured lacquer resin formulation to capture margin currently flowing to Japanese chemical specialists. Defensive positioning requires preemptive investment in repositionable adhesive R&D before bio-based performance gaps close and specialty cosmetics demand surges. For New Entrants and Emerging Players: ISO 9001 fast-track accreditation through notified body relationships in Germany or France opens immediate access to premium cosmetics packaging procurement committees. White-space concentration sits in Indian pharmaceutical export labeling, where CDSCO serialization mandates and FSSAI food-contact rules are elevating compliance barriers faster than domestic converter capacity expansion. Target Maharashtra and Gujarat industrial corridors with UV-cured coating equipment partnerships as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with pharmaceutical serialization capabilities and established ECHA compliance track records. Long-term viability over the next decade hinges on circular-design competency as extended producer responsibility frameworks mature across European jurisdictions. Acquisition target archetype: converters with digital printing flexibility and repositionable adhesive formulation expertise. Watch ANSM and ECHA regulatory calendar alignment as the signal for accelerated supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| UV-Cured Lacquer Line Upgrade | Reduces VOC emissions to EPA limits while achieving 70+ GU specular reflectance for cosmetics clients. |
| Backward Integration into BOPP Extrusion | Captures margin from Asian petrochemical suppliers and insulates against freight volatility in substrate supply. |
| Pharmaceutical Serialization Partnership | Opens regulated healthcare segments with CDSCO and EMA track-and-trace authentication requirements. |
| Bio-Based Adhesive R&D Consortium | Pools formulation investment to close performance gaps in moisture-critical pressure-sensitive applications. |
| Fiber Traceability System Implementation | Meets pulp-to-label documentation demands from Western European luxury brand sustainability procurement teams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with label converter plant managers, cosmetics brand packaging directors, pharmaceutical regulatory affairs leads, and chemical adhesive R&D directors. Secondary validation drew from ECHA substance restriction updates, FDA indirect food-contact guidance documents, EU Green Deal implementation timelines, and customs trade data for biaxially oriented polypropylene substrate flows. Bottom-up volume modeling from converter capacity utilization rates was triangulated against top-down demand estimates from end-use industry production forecasts.
Across the analysis window, projections incorporate material substrate substitution dynamics, adhesive formulation compliance cost trajectories, and digital printing adoption curves segmented by cosmetics, pharmaceutical, food and beverage, and retail end-use verticals. Modeled dimensions include polypropylene versus paper substrate splits, pressure-sensitive versus repositionable adhesive type shares, and flexographic versus digital printing technology transitions. CAGRs were derived from elasticity-adjusted demand functions calibrated to historical pricing response patterns in premium packaging procurement.
Underlying assumptions cover REACH plasticizer phase-out adherence timelines and ECHA enforcement intensity, with deviation risk concentrated in bio-based adhesive performance breakthroughs that could accelerate substitution faster than modeled. Recalibration cycles align with material shifts in EU Green Deal implementation and extended producer responsibility framework adoption across member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Coated Wet Glue Label Market
Labels
North America Self-Adhesive Labels Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Direct Thermal Labels Market
Labels
Self-Laminating Labels Market
Labels
Kraft Labels Market
Labels
Industrial Label Printers Market
Labels
Oxygen Indicator Labels Market
Labels
Extended Text Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Pin Feed Labels Market
Labels
Global Pressure Labels Market
Labels
Variable Data Printing Labels Market
Labels
Cut and Stack Labels Market
Labels
Printable Tags Market
Labels
Future-Proof Pharma Labels Market