
 Global Cryogenic Label Market | 2026-2036
Global Cryogenic Label Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryogenic Label Market Foresight
Polyester is consolidating its position over vinyl in cryogenic label construction as laboratories prioritize thermal-transfer readability after multiple freeze-thaw cycles. Brady Corporation leverages its specialty materials portfolio to dominate North American laboratory supply channels. Avery Dennison Corporation anchors its position through direct thermal adhesive formulations engineered for liquid nitrogen exposure. 3M Company differentiates via metalized film substrates that sustain barcode integrity across cryosurgical instrument tracking workflows.
Cryogenic labels are pressure-sensitive identification substrates constructed from polymer films with cryogenic-grade adhesives, typically rated for adhesion retention from minus 196 degrees Celsius to ambient temperatures, designed to maintain legibility and attachment on vials, straws, and canisters subjected to ultra-low thermal stress. Their primary purpose is to eliminate sample misidentification in temperature-critical storage environments where standard labels delaminate or become illegible. Thermal transfer product types lead value generation due to superior print durability against alcohol and disinfectant exposure, while self-laminating formats represent the fastest-growing configuration as biobanks automate high-throughput processing. Polypropylene material composition occupies the volume-dominant tier for routine pharmaceutical storage, whereas polyimide commands premium positioning in cell and tissue preservation applications where thermal cycling frequency is highest.
FDA 21 CFR Part 820 quality system requirements shape adhesive validation protocols for pharmaceutical manufacturers, while EMA's Good Distribution Practice guidelines mandate traceability standards that elevate label performance specifications across European cold chains. EPA oversight of chemical storage containment indirectly drives demand for solvent-resistant cryogenic labeling in environmental specimen repositories. ISO 10993 biocompatibility testing frameworks increasingly influence substrate selection for diagnostic centers processing patient-derived materials. Stakeholders must monitor evolving harmonization between FDA Unique Device Identification rules and EU MDR label durability standards, as divergence in compliance thresholds would fragment procurement specifications and strain supplier qualification programs.
Market Dynamics
Biobanking automation is compressing procurement cycles and forcing adhesive suppliers to validate performance at throughput speeds previously unseen in cell therapy manufacturing workflows.
Growth Catalysts
- EMA Good Distribution Practice:European cold-chain traceability mandates are elevating label durability specifications across pharmaceutical logistics networks.
- Cell therapy manufacturing:Commercial-scale production of CAR-T therapies is multiplying vial-labeling volumes in GMP cleanroom environments.
- Liquid nitrogen storage:Expansion of long-term biorepositories in Singapore and South Korea is pulling demand for polyimide substrates rated to minus 196 degrees Celsius.
Market Restraints
- Specialty adhesive supply:Silicone-acrylate hybrid formulations depend on concentrated petrochemical feedstock suppliers in the US Gulf Coast.
- REACH compliance costs:ECHA substance evaluation timelines extend adhesive qualification cycles by 12-18 months for European market entry.
- Thermal-transfer ribbon substitution:Direct thermal printing advances threaten consumable attachment rates in routine pharmaceutical storage applications.
Strategic Opportunities
- India biobanking infrastructure:CDSCO-regulated clinical trial expansion and government-funded biorepository networks remain undersupplied with validated cryogenic labeling systems.
- RFID-thermal convergence:Embedding UHF inlays in self-laminating cryogenic formats enables automated sample tracking without secondary barcode verification steps.
- US IRA biomanufacturing incentives:Domestic production tax credits for advanced therapy manufacturing are redirecting label procurement toward US-based converters.
Industry Challenges
- ISO 10993 biocompatibility testing:Diagnostic centers processing patient-derived materials face extended validation timelines for substrate-adhesive combinations.
- Legacy LIMS integration:Automated label applicators must interface with decades-old laboratory information management systems lacking API connectivity.
- Cleanroom-qualified technician scarcity:GMP manufacturing sites report insufficient trained personnel for adhesive performance validation under aseptic conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryogenic Label Market |
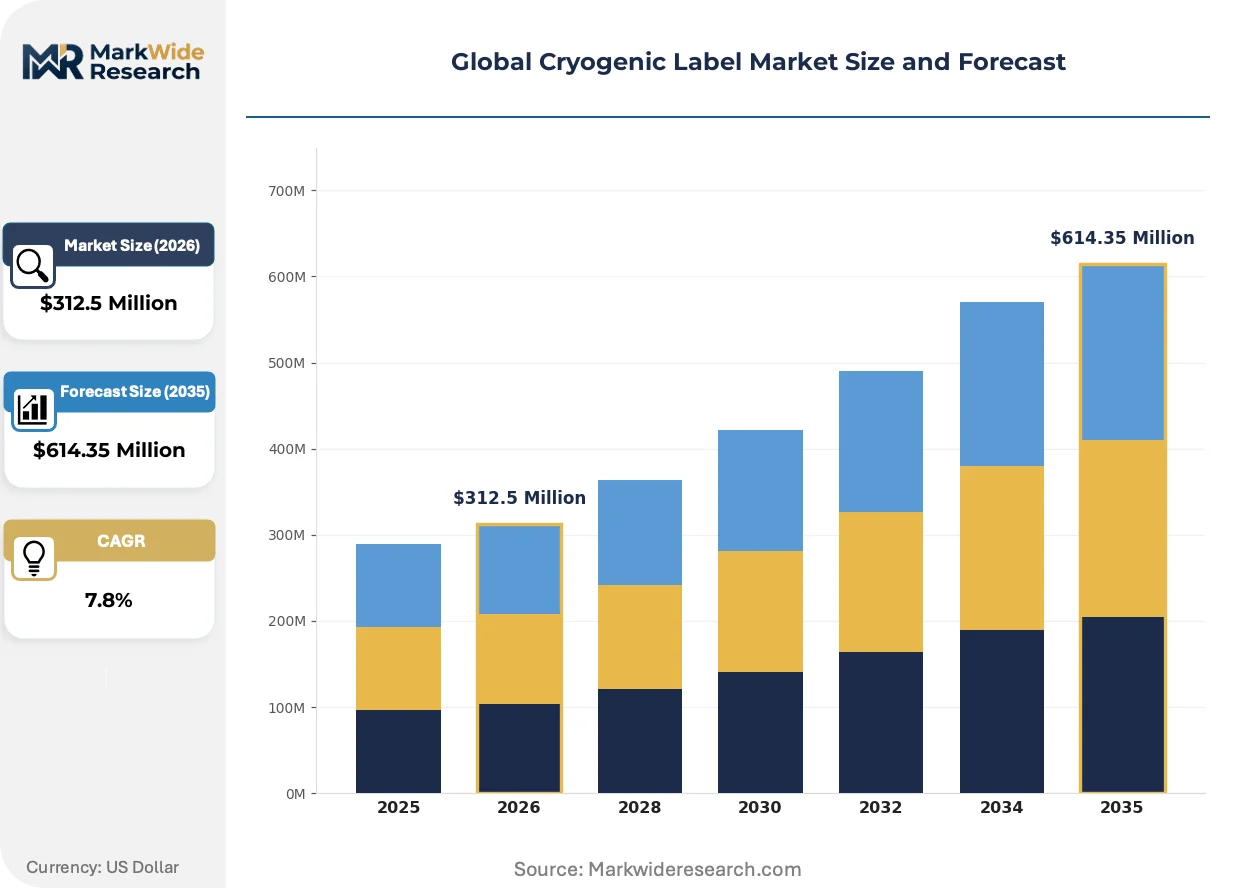
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Laminating, Removable, Printable, Laser Compatible, Thermal Transfer, Direct Thermal Material Composition: Polypropylene, Polyester, Vinyl, Polyethylene, Polyimide, Metalized Film Application: Biobanking, Pharmaceutical Storage, Laboratory Sample Tracking, Cell & Tissue Preservation, Chemical Storage, Cryosurgery End User: Clinical Laboratories, Research Institutes, Blood Banks, Pharmaceutical Manufacturers, Biotech Companies, Diagnostic Centers |
| Companies Covered | Brady Corporation, Avery Dennison Corporation, GA International Inc., Thermo Fisher Scientific Inc., 3M Company, Diversified Biotech, CCL Industries, UPM Raflatac, LabTAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryogenic Label Market Shifts & Advancements
Print-on-demand infrastructure is collapsing minimum order quantities while digital adhesive deposition techniques are rewriting converter economics for short-run specialty labels.
Self-laminating cryogenic label construction is modularizing around automated applicator compatibility. Biobanks processing 10,000-plus samples daily specify wraparound formats with 2-millimeter overlap tolerances. Equipment OEMs in Germany and Japan are standardizing feed mechanisms around this dimensional envelope, compressing format fragmentation that previously required custom die tooling.
REACH Annex XVII restrictions on organotin catalysts are forcing reformulation of pressure-sensitive adhesives used in European pharmaceutical cold chains. Manufacturers must resubmit technical dossiers to ECHA for continued market access. German and Swiss converters are accelerating qualification of tin-free UV-cured alternatives ahead of 2025 enforcement windows.
Consolidated procurement through group purchasing organizations is displacing direct converter relationships at US academic medical centers. Stanford, Mayo Clinic, and MD Anderson now negotiate cryogenic label contracts through shared sourcing consortia. This concentration is visible across NIH-funded biorepositories, where standardized specifications reduce supplier qualification overhead.
Global Cryogenic Label Market Segmentation
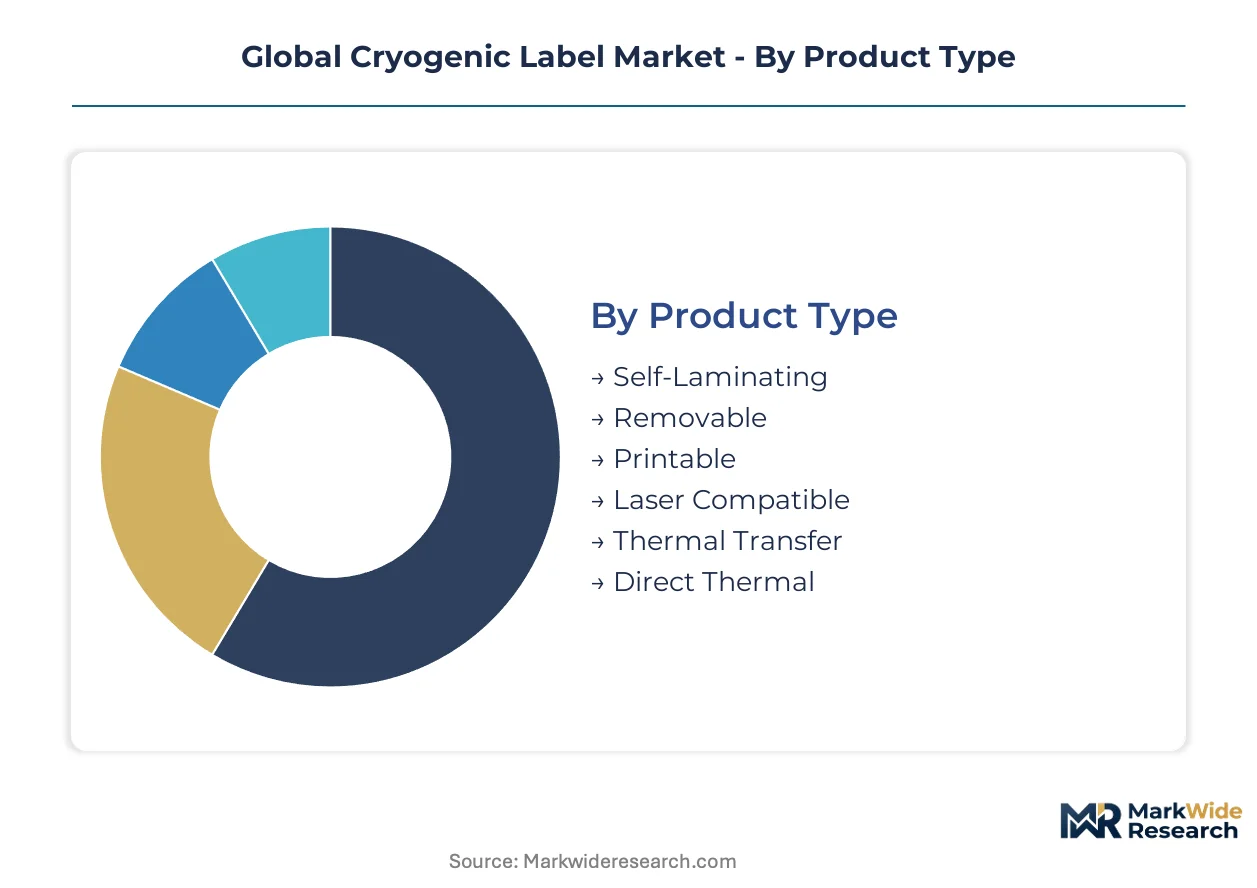
Cryogenic label procurement fragments across performance tiers where thermal durability requirements dictate material selection and printing technology. Laboratories with automated workflows demand format standardization, while specialized preservation applications require bespoke substrate engineering.
Product Type:
Standardization pressure from biobank automation equipment vendors is collapsing format diversity toward interchangeable core specifications.
- Thermal Transfer:These labels receive resin-ribbon imprints that resist alcohol wipes and disinfectant exposure across repeated freeze-thaw cycles. Pharmaceutical manufacturers in Germany and Switzerland specify thermal transfer for GMP-compliant cold chains where barcode legibility failures trigger regulatory non-conformance.
- Self-Laminating:A transparent overlaminate seals printed information against condensation and mechanical abrasion during liquid nitrogen retrieval. Biobanks in Singapore and South Korea are adopting wraparound self-laminating formats as they scale automated sample processing beyond 10,000 vials daily.
- Removable:Low-tack adhesives permit temporary identification during short-term pharmaceutical staging without residue contamination.
- Printable:Pre-cut blanks compatible with desktop laser and inkjet systems serve research institutes with intermittent labeling volumes.
- Laser Compatible:Specially coated polymers withstand high-heat marking processes used in metal canister identification.
- Direct Thermal:Heat-sensitive coatings eliminate ribbon costs but sacrifice durability under solvent exposure, finding use in routine clinical laboratory storage with limited chemical contact.
Most installed capacity flows through thermal transfer formats. Expansion is steepest in self-laminating configurations as high-throughput biobanking automation proliferates.
Material Composition:
Cost-performance tradeoffs separate commodity polymer films from engineered substrates rated for extreme thermal cycling.
- Polypropylene:This polymer dominates routine pharmaceutical storage at minus 80 degrees Celsius with balanced flexibility and chemical resistance. US clinical laboratories specify polypropylene for vaccine vial identification where cost efficiency outweighs extreme temperature exposure.
- Polyimide:Amber-colored aromatic polyimide films maintain dimensional stability at liquid nitrogen temperatures minus 196 degrees Celsius. Cell therapy manufacturers in California and Massachusetts require polyimide for CAR-T preservation workflows where thermal cycling frequency degrades standard substrates.
- Polyester:Biaxially oriented polyethylene terephthalate offers superior print receptivity and is displacing vinyl in North American laboratory supply channels.
- Vinyl:Plasticized polyvinyl chloride films persist in cost-sensitive applications but face displacement where thermal transfer readability is critical.
- Polyethylene:Low-density formulations provide conformability on irregular container geometries in chemical storage applications.
- Metalized Film:Aluminum-coated polymers enable RFID inlay integration and electromagnetic shielding for specialized tracking requirements.
Volume concentration sits with polypropylene across standard cold-chain applications. Polyimide is climbing the fastest as cell and gene therapy manufacturing scales commercially.
Application:
Regulatory stringency varies sharply across use cases, from research-grade flexibility to pharmaceutical GMP mandates.
- Biobanking:Long-term specimen repositories demand adhesion retention across decades of liquid nitrogen immersion. Government-funded networks in India and government biorepositories in the United States are expanding capacity, pulling demand for validated polyimide and polyester constructions.
- Pharmaceutical Storage:Distribution cold chains require labels that survive temperature excursions without delamination. EMA Good Distribution Practice enforcement is elevating durability specifications across European logistics networks.
- Laboratory Sample Tracking:High-velocity processing environments prioritize print speed and applicator compatibility over extreme temperature ratings.
- Cell & Tissue Preservation:Living material preservation imposes the most severe thermal cycling requirements, driving specification of premium substrate-adhesive combinations.
- Chemical Storage:Solvent-resistant adhesives prevent label degradation in environmental specimen repositories subject to EPA containment oversight.
- Cryosurgery:Instrument tracking applications leverage metalized films for barcode integrity across sterilization and freezing workflows.
Procurement scale concentrates in biobanking infrastructure. Steepest specification escalation is occurring in cell and tissue preservation as commercial therapy manufacturing expands.
End User:
Buying power consolidation through group purchasing organizations is reshaping supplier relationships across customer categories.
- Clinical Laboratories:Hospital-affiliated labs process high sample volumes with standardized thermal transfer workflows. US academic medical centers including Stanford and Mayo Clinic now negotiate cryogenic label contracts through shared sourcing consortia.
- Pharmaceutical Manufacturers:GMP cleanroom requirements impose extensive adhesive validation protocols under FDA 21 CFR Part 820 quality system mandates.
- Research Institutes:NIH-funded biorepositories drive specification standardization to reduce supplier qualification overhead across distributed networks.
- Blood Banks:Regulatory traceability requirements from FDA and international equivalents mandate durable identification across frozen plasma storage.
- Biotech Companies:Cell therapy developers represent emerging demand concentration with specialized substrate requirements for cryopreserved therapeutic products.
- Diagnostic Centers:ISO 10993 biocompatibility testing frameworks increasingly govern substrate selection for patient-derived material processing.
Contract concentration is tightest among clinical laboratories. Biotech companies are gaining share fastest as advanced therapy manufacturing scales beyond research quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston biotechnology corridor generates concentrated demand for polyimide cryogenic labels as CAR-T manufacturers scale commercial production. Stanford and Mayo Clinic anchor US academic medical center procurement through shared sourcing consortia. Singapore and South Korean biorepositories are expanding liquid nitrogen storage capacity for regional cell banking networks.
United States
Pharmaceutical cold-chain investments and clinical laboratory infrastructure drive label consumption across vaccine distribution and cell therapy manufacturing. FDA 21 CFR Part 820 quality system requirements shape adhesive validation protocols for GMP cleanroom environments. California and Massachusetts host the densest concentrations of cryopreserved therapeutic product manufacturers.
Germany
EMA Good Distribution Practice enforcement elevates durability specifications across pharmaceutical logistics networks serving European distribution. REACH Annex XVII restrictions on organotin catalysts force adhesive reformulation ahead of 2025 enforcement windows. German equipment OEMs standardize feed mechanisms for self-laminating wraparound formats with 2-millimeter overlap tolerances.
Switzerland
Swissmedic regulatory frameworks mandate traceability standards that elevate label performance specifications for precision medicine applications. Swiss converters accelerate qualification of tin-free UV-cured adhesive alternatives to maintain European market access. Basel and Zurich anchor pharmaceutical manufacturing clusters with specialized substrate requirements for biologics storage.
Singapore
Expansion of long-term biorepositories pulls demand for polyimide substrates rated to minus 196 degrees Celsius for regional cell banking networks. The country's national pharmaceutical regulator aligns with international traceability standards for cold-chain distribution. Biopolis research hub drives specification standardization for automated high-throughput sample processing.
India
CDSCO-regulated clinical trial expansion and government-funded biorepository networks remain undersupplied with validated cryogenic labeling systems. Government biorepository infrastructure expansion pulls demand for polyester and polyimide constructions. Hyderabad and Bangalore clusters concentrate diagnostic center procurement for patient-derived material processing.
Global Cryogenic Label Market Competitive Landscape
Global majors compete with regional champions across specialty materials portfolios and converter relationships. The vendor base separates into consolidated specialty materials suppliers, diversified adhesive technology platforms, and focused laboratory supply distributors. Three archetypes dominate: integrated materials-converter operations, adhesive technology licensors, and distribution-centric service providers. Competitive moves concentrate on strategic partnerships with biobank automation equipment OEMs and geographic expansion through converter acquisitions.
Within the integrated materials tier, Brady Corporation and Avery Dennison Corporation exemplify vertically positioned suppliers with direct control over substrate and adhesive formulation. 3M Company occupies a distinct position through metalized film substrate capabilities. These three anchors demonstrate how specialty materials mastery translates into laboratory supply channel dominance.
| Leading Market Players |
|---|
| Brady Corporation |
| Avery Dennison Corporation |
| GA International Inc. |
| Thermo Fisher Scientific Inc. |
| 3M Company |
| Diversified Biotech |
| CCL Industries |
| UPM Raflatac |
| LabTAG |
| Others |
Supply & Pricing Matrix
Specialized adhesive chemists concentrated in the US Gulf Coast and German industrial corridors command wage premiums that translate directly into pricing-tier spreads across cryogenic label categories. Labor-cost differentials between these technical centers and emerging converter operations in India widen the gap between premium polyimide substrates and economy-grade polypropylene alternatives.
Pricing Analysis
Input-cost pass-through from silicone-acrylate hybrid adhesive feedstocks anchors pricing stratification across premium, standard, and economy tiers. Certification grade under ISO 10993 biocompatibility frameworks and FDA 21 CFR Part 820 quality system compliance separate premium polyimide constructions from commodity alternatives. Cost compression in standard-tier polyester labels is intensifying because thermal-transfer ribbon substitution threats squeeze converter margins. Research institutes with intermittent labeling volumes exhibit highest price sensitivity, while GMP pharmaceutical manufacturers prioritize performance over unit economics.
Supply Chain Analysis
Freight cost volatility on trans-Pacific routes from Chinese polymer film suppliers disrupts converter inventory planning for North American laboratory supply channels. Raw material sourcing draws from petrochemical feedstock networks in the US Gulf Coast, biaxially oriented film production in Germany and Japan, and silicone adhesive manufacturing concentrated in Switzerland and the United States. Single-source vulnerability to REACH Annex XVII organotin catalyst restrictions threatens European market access for legacy adhesive formulations. Distribution runs through group purchasing organizations at US academic medical centers and direct converter relationships with German equipment OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cryogenic Label Market compounds steadily as biobanking automation multiplies vial-labeling volumes across government-funded repository networks worldwide. Cell therapy manufacturing scale-up provides durable demand underpinning.
For Market Incumbents: Lock in adhesive validation protocols with biobank automation equipment OEMs in Germany and Japan before emerging Asian converters achieve EMA compliance. Secure backward integration into specialty silicone-acrylate feedstocks to defend against petrochemical supply concentration on the US Gulf Coast. Prioritize tin-free UV-cured adhesive R&D to maintain European market access ahead of REACH enforcement windows. For New Entrants and Emerging Players: Enter via CDSCO-regulated clinical trial expansion in India, where government biorepository networks remain undersupplied with validated cryogenic labeling systems. Target diagnostic centers in Hyderabad and Bangalore processing patient-derived materials under emerging ISO 10993 frameworks. Lead with print-on-demand digital adhesive deposition capabilities to collapse minimum order quantities for research institutes. For Investors and Strategic Acquirers: Laboratory supply distributors with established GPO relationships at US academic medical centers are the most active acquirer in this space, consolidating converter relationships to capture procurement concentration. Five-to-ten-year viability rests on cell therapy manufacturing scale beyond research quantities. Monitor RFID-thermal convergence adoption rates in Singapore biorepositories as inflection indicator for automated sample tracking premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Partnership | Secures EMA-compliant tin-free UV-cured alternatives ahead of REACH Annex XVII enforcement. |
| Automation Equipment Integration | Aligns self-laminating wraparound formats with German and Japanese OEM feed mechanism standards. |
| Biocompatibility Certification Investment | Unlocks diagnostic center procurement governed by ISO 10993 substrate selection frameworks. |
| Geographic Converter Acquisition | Captures CDSCO-regulated clinical trial expansion in undersupplied Indian biorepository networks. |
| RFID-Thermal Convergence Development | Enables automated sample tracking without secondary barcode verification in Singapore biobanks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive R&D directors, biobank operations managers, GPO contracts specialists, and laboratory supply procurement leads with secondary validation. FDA 21 CFR Part 820 filings, ECHA substance evaluation dossiers, ISO 10993 biocompatibility test reports, and customs trade data on polymer film imports anchored the data foundation. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighting across product type, material composition, application, and end user dimensions drove the analytical framework over the projection horizon. Thermal transfer and self-laminating format splits, polypropylene-to-polyimide material migration patterns, and biobanking versus pharmaceutical storage application shares informed the modeling structure. CAGRs derived from installed automation equipment growth curves and cell therapy manufacturing capacity announcements.
Inputs from ECHA substance evaluation timelines and CDSCO clinical trial registration databases were available through the study window; gaps in real-time biobank automation equipment deployment rates introduce uncertainty bands around high-throughput processing adoption forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Label Applicator Market
Labels
Retro-Reflective Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Braille Labels Market
Labels
Printable Tags Market
Labels
United States Print Label Market
Labels
Time Temperature Indicator Labels Market
Labels
Syringe Labels Market
Labels
Global Laminated Labels Market
Labels
Metallic Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Domed Labels Market
Labels
Linerless Labels Market
Labels
Sleeve Label Market
Labels
Shrink Sleeve Labels Market
Labels
Global Sensormatic Labels Market