
 Global Resealable Packaging Labels Market | 2026-2036
Global Resealable Packaging Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resealable Packaging Labels Market Intelligence
Aftermarket label application services is reshaping margin distribution across the value chain. Avery Dennison leverages its North American film extrusion network to control substrate supply. UPM Raflatac anchors European demand through its specialized pressure-sensitive portfolio for chilled food. Constantia Flexibles dominates pharmaceutical resealable applications with high-barrier laminates.
Resealable packaging labels are multi-layer constructions combining facestock, pressure-sensitive or heat-activated adhesive, and release liner, engineered for repeated open-close cycles without tearing the primary package. Their commercial purpose centers on consumer convenience, portion control, and product freshness retention across flexible and semi-rigid containers. Pressure-sensitive labels lead value generation due to compatibility with existing converting equipment, while digital printing technology captures the fastest growth as brands shorten run lengths for SKU proliferation. Film labels sustain premium positioning in personal care where aesthetic clarity and moisture resistance command higher unit economics.
The EPA regulates volatile organic compound emissions from adhesive coating operations in the United States, compelling domestic converters to invest in thermal oxidizers or water-based systems. REACH and the EU Packaging and Packaging Waste Directive shape material compliance across European supply chains, restricting certain phthalate plasticizers in flexible label films. China's MEE enforces stricter effluent standards on coating plants in the Yangtze River Delta cluster. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing product platforms across multinational accounts.
Market Dynamics
Pressure-sensitive adhesive systems are displacing heat-activated alternatives across food and personal care applications, driven by converter demand for line-speed compatibility and the EPA's volatile organic compound enforcement tightening coating economics in the United States.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' circular economy targets compel brand owners to specify recyclable mono-material label constructions, expanding addressable volume for compatible adhesive platforms.
- Chilled food logistics expansion:Cold-chain infrastructure investment across Germany and China creates demand for low-tack pressure-sensitive labels that maintain adhesion through temperature cycling.
- Digital print convergence:Inkjet and toner technologies enable economical short runs, allowing regional food processors to deploy SKU-specific resealable graphics without plate costs.
Market Restraints
- Petrochemical feedstock volatility:Acrylic adhesive monomers and polypropylene facestock resins track crude oil and natural gas liquids, compressing converter margins during upstream price spikes.
- German coating cluster concentration:A disproportionate share of European solvent-free adhesive capacity sits in the Rhine-Ruhr industrial zone, creating geographic supply risk during river logistics disruptions.
- Competing closure technologies:Zipper pouches and integrated slider mechanisms in flexible packaging substitute label-based reseal for certain snack and produce applications.
Strategic Opportunities
- India food processing formalization:FSSAI packaging regulations and organized retail expansion create first-mover potential for pressure-sensitive reseal in spice and dairy segments.
- Pharmaceutical compliance labeling:EU MDR device traceability requirements and unit-dose dispensing trends favor tamper-evident resealable constructions for secondary packaging.
- Solvent-free adhesive chemistry:UV-curable and hot-melt systems eliminate thermal oxidizer capex, opening contract coating services to mid-tier converters previously excluded by environmental compliance costs.
Industry Challenges
- Adhesive formulator talent scarcity:Specialized polymer chemistry expertise for resealable tack balance commands premium compensation, constraining R&D throughput at emerging converters.
- Multi-jurisdiction certification timelines:Separate FDA food-contact notifications, EU EFSA compliance dossiers, and China NMPA registrations delay product launches by 18-24 months for global accounts.
- Legacy press retrofit complexity:Converting equipment originally specified for permanent adhesives requires web tension and drying modifications to handle repositionable constructions without liner release failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resealable Packaging Labels Market |
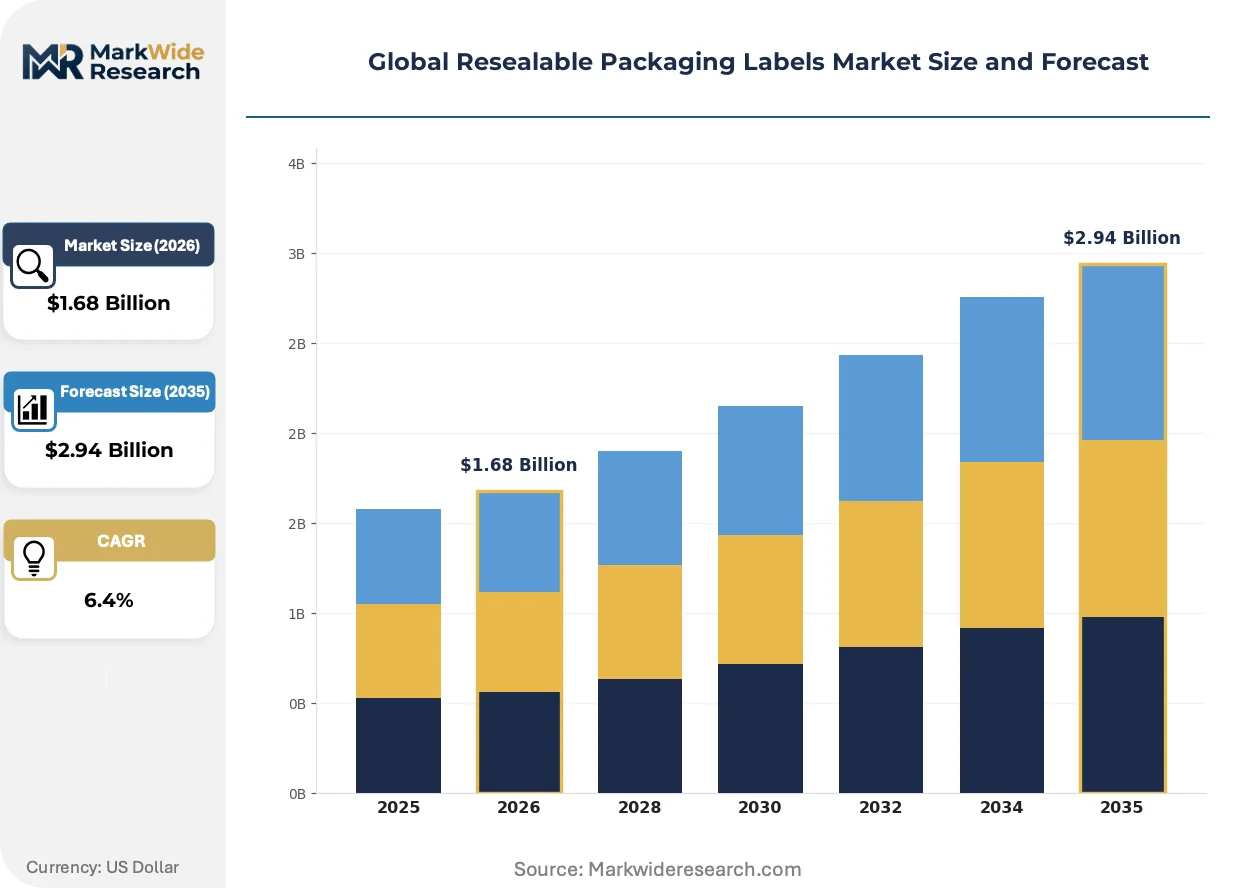
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Heat Seal, Cold Seal, Film Labels, Adhesive Labels, Tamper-Evident Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Household Products, Agriculture End User: Manufacturers, Packaging Companies, Retailers, E-Commerce, Wholesalers, Distributors Technology: Flexography, Digital Printing, Gravure, Inkjet, Transfer, Letterpress |
| Companies Covered | Avery Dennison, UPM Raflatac, CCL Industries, Constantia Flexibles, MacFarlane Labels Ltd, New York Label & Box Works, Veltego, Etik Ouest, Desmedt Labels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resealable Packaging Labels Market Strategic Shifts & Innovations
Digital workflow integration is collapsing traditional boundaries between design, proofing, and production, enabling brands to synchronize packaging graphics with seasonal campaigns and regulatory label changes without inventory obsolescence.
Laser die-cutting is collapsing mechanical tooling requirements for intricate resealable label shapes. Narrow-web converters serving craft food brands in the United States adopt fiber laser systems to eliminate blade setup times. The technology compresses minimum order quantities from ten thousand to five hundred units, fragmenting procurement across smaller regional suppliers.
REACH substance restrictions and the EU F-Gas Regulation are accelerating fluorochemical-free release liner development. Coating operations in Belgium and the Netherlands pilot silicone-free alternatives using plasma surface treatment. Pharmaceutical labelstock specifications in Germany now explicitly exclude per- and polyfluoroalkyl substances, forcing laminate suppliers to requalify entire product families.
Brand procurement teams are consolidating supplier panels and demanding line-item transparency on adhesive chemistry and substrate origin. Personal care multinationals in France and Switzerland now require technical data sheets disclosing plasticizer content and recyclability pathways. This audit intensity favors converters with integrated coating and metallization capabilities who can certify complete material genealogy.
Global Resealable Packaging Labels Market Segmentation
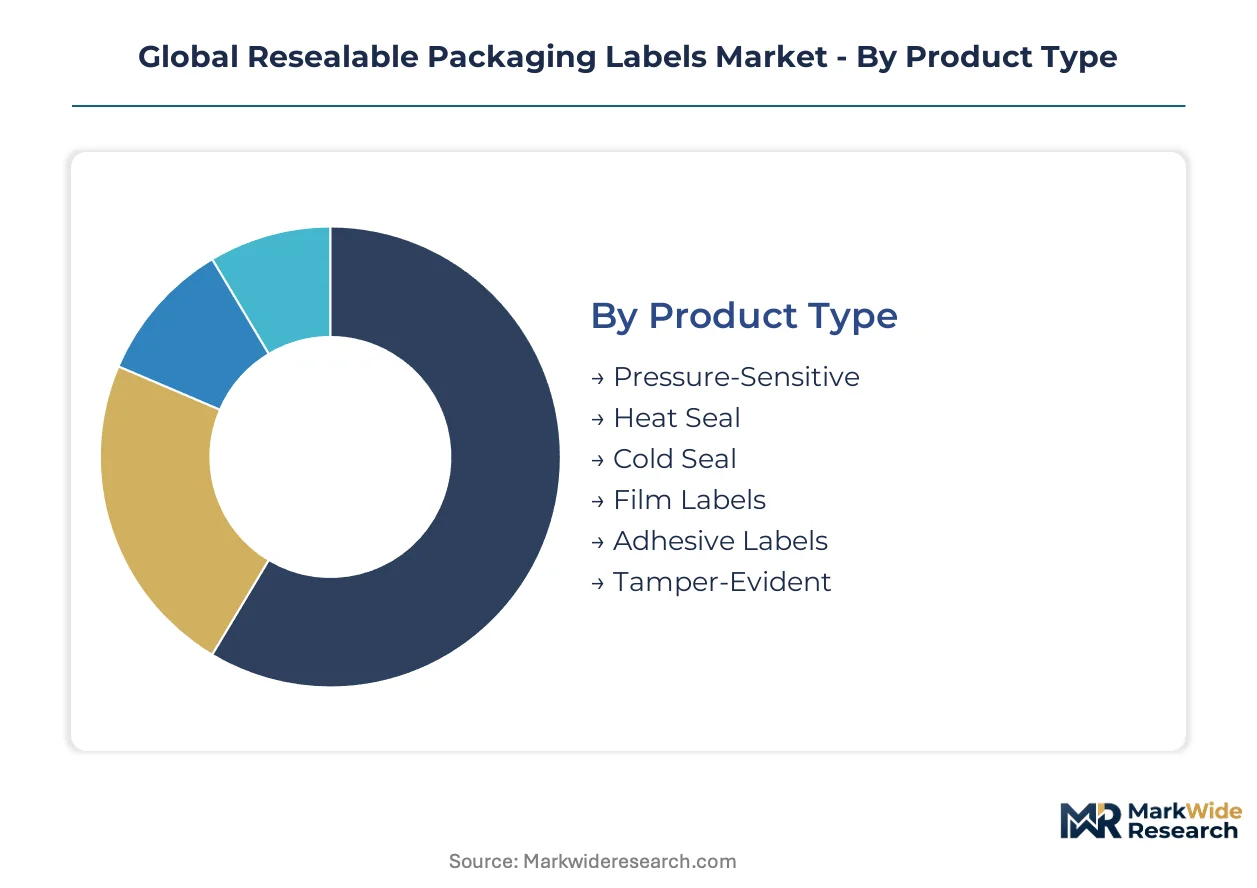
Resealable packaging labels serve heterogeneous demand cycles across converter equipment, end-use durability requirements, and brand refresh frequencies. Segment boundaries blur as pressure-sensitive platforms absorb share from heat-activated alternatives and digital workflows compress traditional print technology lifecycles.
Product Type:
Cycle times vary dramatically by adhesive chemistry and liner complexity, with repositionable constructions demanding more frequent formulation refreshes than permanent alternatives.
- Pressure-Sensitive:Acrylic or rubber-based adhesive coated on release liner enables immediate tack without heat activation, compatible with existing narrow-web converting lines. Food & beverage manufacturers in Germany and the United States specify these for chilled meat and cheese applications where line speed and temperature cycling resistance prove critical. The segment commands premium unit economics due to formulation complexity and liner waste disposal costs.
- Film Labels:Polypropylene or polyethylene facestock constructions deliver moisture resistance and optical clarity for premium personal care positioning. French and Swiss cosmetics brands specify metallized or clear film constructions where shelf aesthetics drive purchase decisions, though substrate costs run higher than paper alternatives.
- Heat Seal:Thermoplastic adhesive layers bond to flexible packaging substrates under controlled temperature and pressure, common in snack and bakery applications where hermetic closure matters.
- Cold Seal:Natural rubber latex formulations activate through pressure alone, serving chocolate and confectionery where heat would damage product integrity.
- Adhesive Labels:General-purpose constructions without specialized reseal functionality, often specified for cost-sensitive commodity applications.
- Tamper-Evident:Frangible or void-pattern adhesive systems that reveal package opening, increasingly specified for pharmaceutical secondary packaging under EU MDR traceability requirements.
Pressure-sensitive dominates installed base. Film labels are where expansion concentrates.
Application:
Margin profiles diverge sharply by sector, with pharmaceutical and personal care tolerating higher adhesive costs than food commodity segments where procurement squeezes converter margins.
- Food & Beverage:The largest volume sink, spanning fresh produce, dairy, deli meats, and baked goods where portion control and freshness retention justify label cost. Chinese cold-chain infrastructure investment and German discount retailer private-label expansion drive specification intensity, though price pressure from zipper pouch alternatives constrains growth in snack applications.
- Pharmaceuticals:Unit-dose blister packs and secondary compliance packaging demand tamper-evident reseal with batch-level traceability. EU MDR device regulations and FDA serialization mandates elevate specification complexity, creating stickier supplier relationships and longer qualification timelines.
- Personal Care:Wipes, masks, and cotton pad packaging prioritize moisture retention and premium tactile feel. Korean beauty brand expansion into Southeast Asia spreads film label specifications regionally.
- Electronics:Anti-static resealable pouches for components and accessories, a smaller volume segment with specialized ESD requirements.
- Household Products:Cleaning wipes and detergent pods where chemical resistance and child-resistance closures intersect.
- Agriculture:Seed and fertilizer packaging with UV stability requirements, concentrated in Midwestern United States and Brazilian agribusiness corridors.
Food & beverage anchors volume throughput. Pharmaceuticals is climbing the fastest on regulatory tailwinds.
End User:
Procurement sophistication stratifies sharply, with multinational manufacturers demanding full material genealogy while regional distributors prioritize unit cost and availability.
- Manufacturers:Brand-owning CPG companies with direct converter relationships, technical specification control, and sustainability audit requirements. Nestlé and Unilever procurement teams now mandate recyclability pathway documentation and adhesive chemistry disclosure.
- Packaging Companies:Contract converters and co-manufacturers serving mid-tier food processors, balancing equipment flexibility against SKU proliferation pressures.
- Retailers:Private-label specifiers including Aldi, Lidl, and Carrefour with centralized packaging design and aggressive cost targets.
- E-Commerce:Direct-to-consumer brands with short-run digital print requirements and rapid graphic refresh cycles.
- Wholesalers:Inventory-heavy intermediaries with limited technical specification involvement.
- Distributors:Regional stock-and-resell operations serving small-format converters and job shops.
Manufacturers dominate specification authority. E-commerce is gaining share fastest on digital print convergence.
Technology:
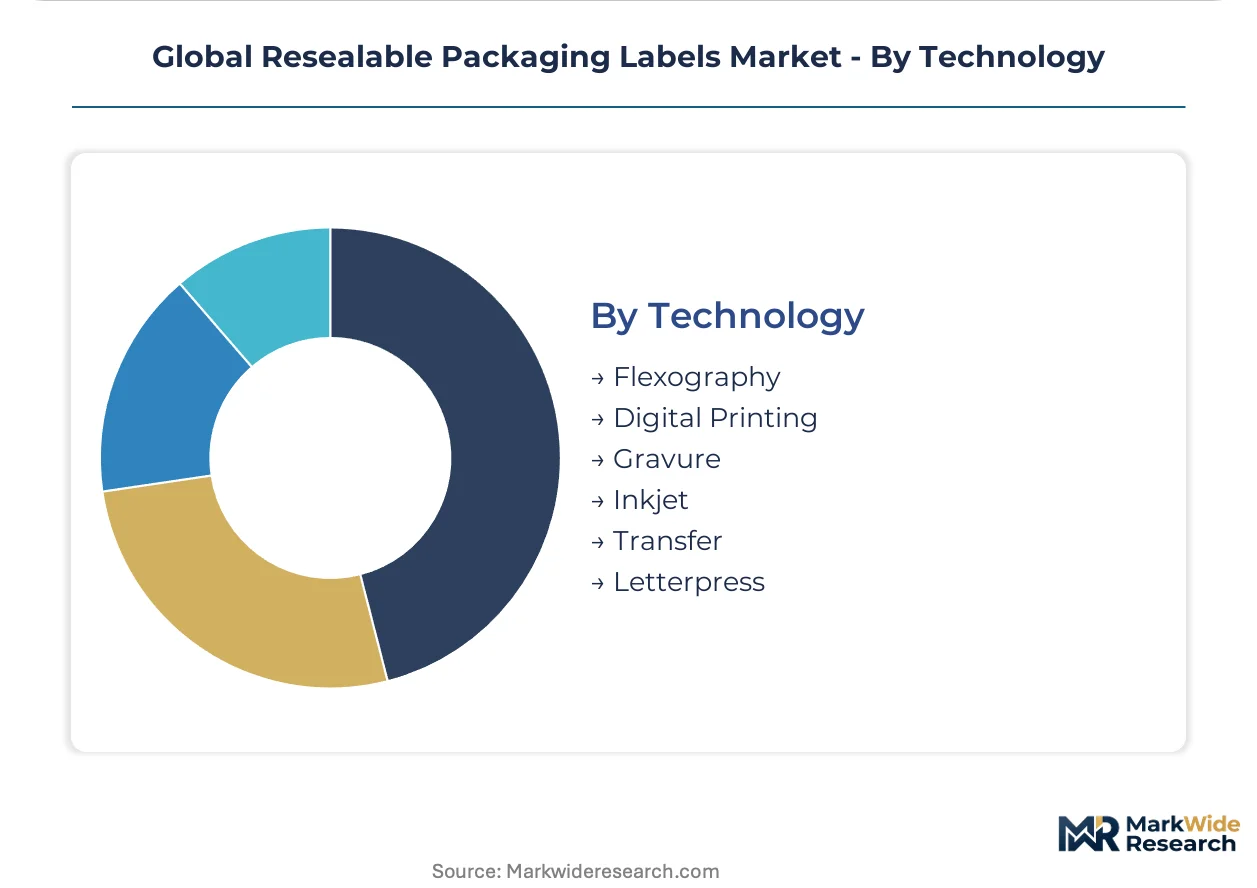
Capital intensity and changeover economics determine which print platforms survive as run lengths fragment and brand refresh cycles accelerate.
- Digital Printing:Toner and inkjet systems eliminate plate costs and enable economical runs below five hundred units. HP Indigo and Xeikon installations at narrow-web converters in the United States and Netherlands serve craft food brands and seasonal promotional campaigns with three-day turnaround requirements.
- Flexography:Rotary letterpress-derived platform with fast drying and high-speed capability, still dominant for long-run food and beverage work where unit cost minimization matters.
- Gravure:Cylinder-based intaglio printing with exceptional ink laydown and consistency, concentrated in high-volume Asian flexible packaging converters serving export markets.
- Inkjet:Single-pass and scanning systems capturing variable data and personalization applications, often hybridized with flexo for base graphics.
- Transfer:Thermal transfer and hot stamping for variable information and security features, common in pharmaceutical serialization.
- Letterpress:Traditional relief printing with limited new equipment investment, legacy installed base in older European converting facilities.
Flexography retains the deepest installed base. Digital printing is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and the United States consume resealable packaging labels through divergent application mixes. German demand concentrates in chilled food logistics and pharmaceutical compliance. Chinese consumption centers on cold-chain infrastructure buildout for fresh produce. The United States splits volume between craft food digital print and mass-market retail private label.
United States
EPA volatile organic compound enforcement tightens coating economics across Midwest converting corridors. Thermal oxidizer investments at Ohio and Wisconsin facilities exceed water-based system conversions. Narrow-web converters in the Chicago-Minneapolis corridor adopt HP Indigo and Xeikon systems to serve craft food brands with sub-five-hundred-unit runs.
Germany
EU Green Deal circular economy targets compel mono-material label specifications from Nestlé and Unilever procurement teams. REACH substance restrictions accelerate fluorochemical-free release liner pilots in Belgium and Netherlands coating operations. The Rhine-Ruhr industrial zone hosts disproportionate solvent-free adhesive capacity, creating geographic concentration risk during river logistics disruptions.
China
MEE effluent standards enforcement tightens coating plant operations in the Yangtze River Delta cluster. Cold-chain infrastructure investment across Jiangsu and Zhejiang provinces generates demand for low-tack pressure-sensitive labels surviving temperature cycling. Domestic labelstock producers operate integrated coating facilities serving both export markets and local dairy processors.
India
FSSAI packaging regulations and organized retail expansion create first-mover positioning for pressure-sensitive reseal in spice and dairy segments. Maharashtra and Gujarat food processors specify resealable constructions for export-compliant packaging. Mumbai-Pune converter clusters invest in narrow-web flexo and digital hybrid platforms to capture regional brand work.
France
Personal care multinationals mandate technical data sheets disclosing plasticizer content and recyclability pathways. ANSM pharmaceutical labeling requirements intersect with EU MDR device traceability standards. Île-de-France and Auvergne-Rhône-Alpes cosmetic brands specify metallized film constructions where shelf aesthetics command premium positioning.
Global Resealable Packaging Labels Market Key Industry Players
Capability concentration sits with specialized adhesive formulators; scale advantage sits with integrated film extruders and multinational labelstock producers. The vendor base stratifies across three tiers: global substrate suppliers controlling resin supply, regional converters with coating and metallization integration, and narrow-web specialists serving digital print fragmentation. Two dominant competitive moves are reshaping positioning: solvent-free adhesive chemistry investments eliminating environmental compliance barriers for mid-tier entrants, and laser die-cutting adoption collapsing minimum order quantities toward regional procurement fragmentation.
Among integrated multinational suppliers, Avery Dennison and UPM Raflatac occupy positions anchoring distinct regional demand vectors. Avery Dennison exemplifies the substrate-integrated archetype through North American film extrusion network control. UPM Raflatac represents the specialized pressure-sensitive portfolio approach, with European chilled food applications forming a core demand anchor. Constantia Flexibles sits within the high-barrier laminate specialization tier, serving pharmaceutical resealable applications where regulatory qualification timelines create supplier stickiness.
| Leading Market Players |
|---|
| Avery Dennison |
| UPM Raflatac |
| CCL Industries |
| Constantia Flexibles |
| MacFarlane Labels Ltd |
| New York Label & Box Works |
| Veltego |
| Etik Ouest |
| Desmedt Labels |
| Others |
Cost & Logistics Intelligence
Overcapacity in European solvent-free adhesive coating is compressing contract pricing while simultaneously pushing suppliers toward integrated film extrusion to defend margin. This utilization dynamic creates divergent pricing power between Rhine-Ruhr coating clusters and North American substrate-integrated competitors.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between multinational CPG brands and labelstock producers, insulating volume commitments from acrylic monomer spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade tamper-evident constructions from commodity food applications, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from zipper pouch substitution in snack segments, forcing resealable label converters to absorb adhesive cost spikes rather than pass through. Retail private-label specifiers exhibit highest price sensitivity, while pharmaceutical compliance packaging tolerates premium positioning.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing decisions for polypropylene facestock and silicone release liners. Supply concentrates in Germany, China, and the United States for integrated coating operations, with acrylic adhesive monomers and metallized film substrates drawing from petrochemical feedstocks in the US Gulf Coast and Middle East. Single-source vulnerability sits with German solvent-free adhesive formulators serving EU pharmaceutical accounts. Distribution runs through converter-direct relationships for multinational brands, with regional distributors handling mid-tier food processor fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resealable packaging labels represent early-cycle expansion as cold-chain infrastructure buildout across developing markets creates first-mover penetration opportunities for pressure-sensitive platforms. Digital print convergence accelerates SKU proliferation beyond legacy converter capacity.
For Market Incumbents: Pre-empt emerging entrant encroachment by securing captive supply of fluorochemical-free release liners ahead of REACH substance restrictions. Consolidate solvent-free adhesive capacity in the Rhine-Ruhr corridor to exploit geographic concentration risk as a competitive moat. Defend pharmaceutical account stickiness through EU MDR qualification timeline acceleration. For New Entrants and Emerging Players: Establish a beachhead in Indian spice and dairy packaging where FSSAI regulations and organized retail expansion outpace domestic converter capacity. Target e-commerce direct-to-consumer brands with sub-five-hundred-unit digital print requirements. Lead with laser die-cutting capability to collapse minimum order quantities and fragment procurement toward regional suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across UV-curable adhesive coating as environmental compliance capex barriers fall. The 5-10 year viability window favors contract coating services with solvent-free chemistry expertise over legacy thermal oxidizer-dependent facilities. Acquire narrow-web converters with digital hybrid platforms serving craft food brand fragmentation. Watch cold-chain infrastructure investment announcements in Jiangsu and Zhejiang provinces as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Adhesive Capacity Expansion | Eliminates EPA thermal oxidizer capex for Midwest US converters seeking environmental compliance. |
| Fluorochemical-Free Release Liner Development | Addresses REACH restrictions and EU F-Gas Regulation mandates for pharmaceutical labelstock specifications. |
| Digital Print Platform Integration | Captures SKU proliferation from craft food brands and seasonal promotional campaigns with rapid turnaround. |
| Backward Integration into Film Extrusion | Secures polypropylene facestock supply against petrochemical feedstock volatility in adhesive coating economics. |
| Pharmaceutical Compliance Certification Investment | Accelerates EU MDR and FDA food-contact notification timelines to lock in device traceability account stickiness. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association filings, customs records, and regulatory compliance databases. Conversations with adhesive formulators, narrow-web converter operations managers, CPG packaging procurement leads, and pharmaceutical labeling compliance officers inform demand-side validation. Secondary sources include EPA enforcement actions, REACH substance restriction updates, EFSA compliance dossiers, and China MEE effluent standard revisions. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporate adhesive chemistry platform adoption curves, digital print equipment installation rates, and cold-chain infrastructure investment pipelines. Segmentation dimensions span product type, application sector, end-user procurement sophistication, and print technology platform. Value projections derive from unit economics modeling of film versus paper facestock, with CAGRs calibrated to historical adhesive monomer price elasticity and converter margin compression patterns.
Sensitivities concentrate around petrochemical feedstock volatility, regulatory timeline acceleration for fluorochemical bans, and zipper pouch substitution rates in snack applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Sustainable Labels Market
Labels
Print Label Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Industrial Label Printers Market
Labels
Canning Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Repositionable Labels Market
Labels
Self-Laminating Labels Market
Labels
Water Dissolvable Labels Market
Labels
Indicative Seals Market
Labels
Global Automotive Labels Market
Labels
Foam Labels Market
Labels
Syringe Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Sleeve Label Market
Labels
Direct Thermal Labels Market