
 Global Submerged Arc Welding Market | 2026-2036
Global Submerged Arc Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submerged Arc Welding Market Intelligence
The established distribution channel relying on large industrial suppliers is fragmenting under pressure from specialized online platforms and direct-to-fabricator sales models. Lincoln Electric leverages its extensive global network to serve large-scale infrastructure projects. ESAB competes by offering integrated robotic and automated SAW systems for heavy manufacturing clients. Meanwhile, voestalpine Böhler Welding differentiates through its portfolio of high-performance welding consumables tailored for demanding applications in the energy sector.
Submerged arc welding is an automated process using a continuously fed consumable electrode where the welding arc is shielded by a blanket of granular fusible flux. This flux cover protects the molten weld pool from atmospheric contamination and allows for high deposition rates, making the process ideal for joining thick steel sections. Multi-wire technology represents the fastest-growing technology segment, driven by productivity needs in shipbuilding and offshore structure fabrication. While welding machines form the capital-intensive core, welding consumables like specialized fluxes and electrodes represent a recurring, high-margin revenue stream.
The market operates within strict regulatory and standards-based frameworks. The ASME Boiler and Pressure Vessel Code in the United States, ISO 3834 for welding quality management, and CE marking directives in Europe set stringent requirements for equipment safety and weld quality. These standards directly influence material certification and process validation for critical applications. The central strategic decision for manufacturers is balancing investment in standardized systems for volume markets against developing specialized solutions for high-specification niches.
Market Dynamics
The central dynamic shaping the submerged arc welding market is the global mandate for higher structural integrity in energy and transportation infrastructure. This pressure, codified in standards like API 1104, forces a shift toward automated, high-deposition processes that guarantee verifiable weld quality.
Growth Catalysts
- Infrastructure Investment:Large-scale energy pipeline projects in North America and transport infrastructure development under China's Belt and Road Initiative create sustained demand for SAW equipment and consumables for longitudinal and spiral seam welding.
- Stringent Quality Standards:The adoption of codes like the ASME Boiler and Pressure Vessel Code for nuclear and power generation components necessitates the high-quality, repeatable welds characteristic of the SAW process.
- Productivity in Shipbuilding:The need for high deposition rates in joining thick plates for commercial vessels and offshore platforms drives adoption of multi-wire and tandem SAW technologies, particularly in South Korean and Chinese shipyards.
Market Restraints
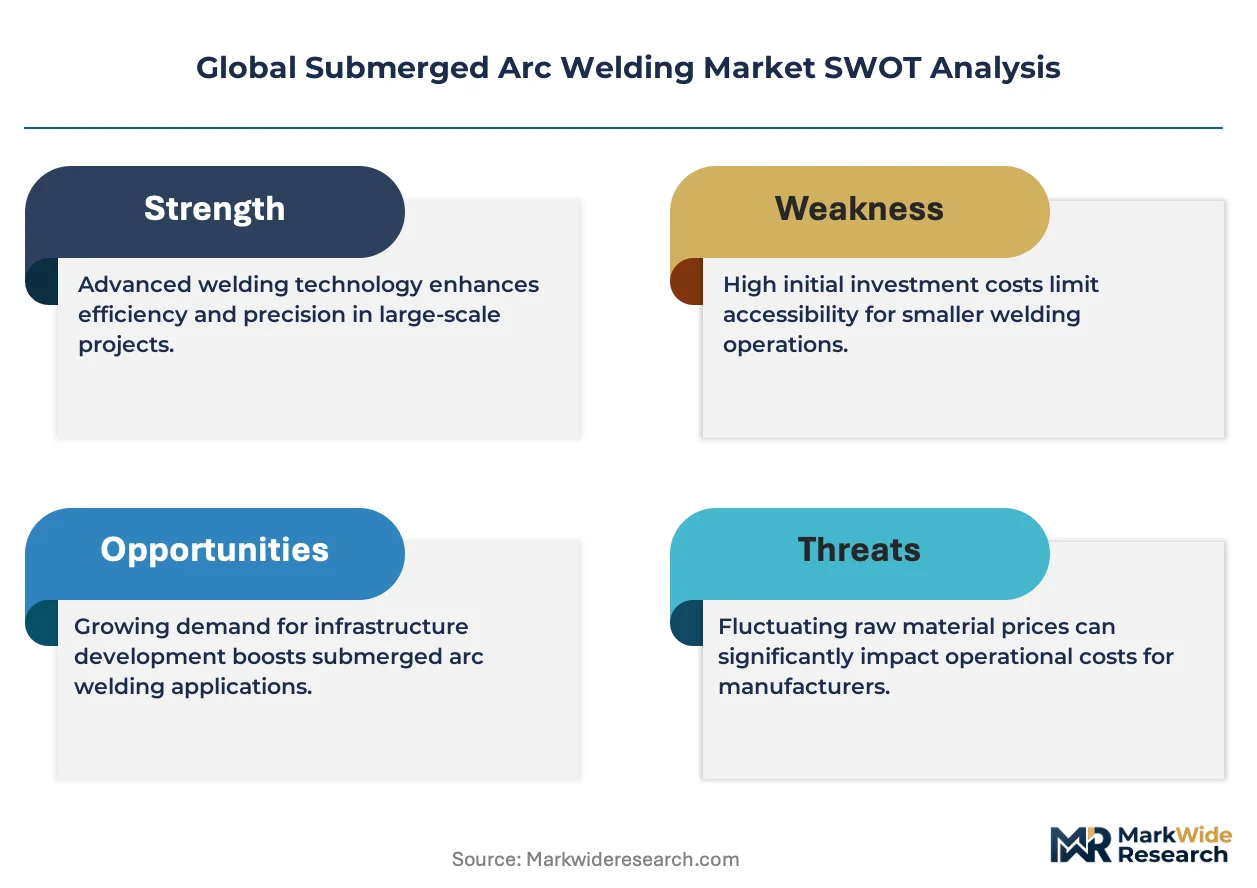
- High Capital Outlay:The significant initial investment required for automated SAW systems, including power sources, controllers, and manipulators, presents a barrier for smaller fabrication shops compared to manual or semi-automatic processes.
- Process Immobility:Submerged arc welding is primarily limited to flat and horizontal welding positions due to its reliance on a gravity-fed granular flux, making it unsuitable for many on-site repair or complex geometry applications.
- Skilled Operator Requirement:While automated, the process demands skilled technicians for setup, programming, and quality monitoring, creating a bottleneck in regions with shortages of trained welding personnel.
Strategic Opportunities
- Offshore Wind Fabrication:The construction of monopile and jacket foundations for offshore wind farms, particularly in the North Sea and off the US East Coast, opens a major new application for heavy-section SAW.
- Cladding and Hardfacing:Growing demand for corrosion-resistant and wear-resistant overlays in the chemical processing and mining industries provides an opportunity for specialized SAW consumables and processes.
- Digital Integration:Developing SAW systems with integrated data logging and monitoring capabilities to meet the traceability requirements of ISO 3834 presents a value-added opportunity for equipment manufacturers.
Industry Challenges
- Welding Fume Regulation:Stricter occupational health regulations, such as OSHA's rules on manganese exposure in the United States, require investment in advanced fume extraction systems, adding cost and complexity to SAW operations.
- Process Validation Timelines:The lengthy and expensive qualification of welding procedure specifications (WPS) for critical applications can delay project timelines and limit the adoption of new consumable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submerged Arc Welding Market |
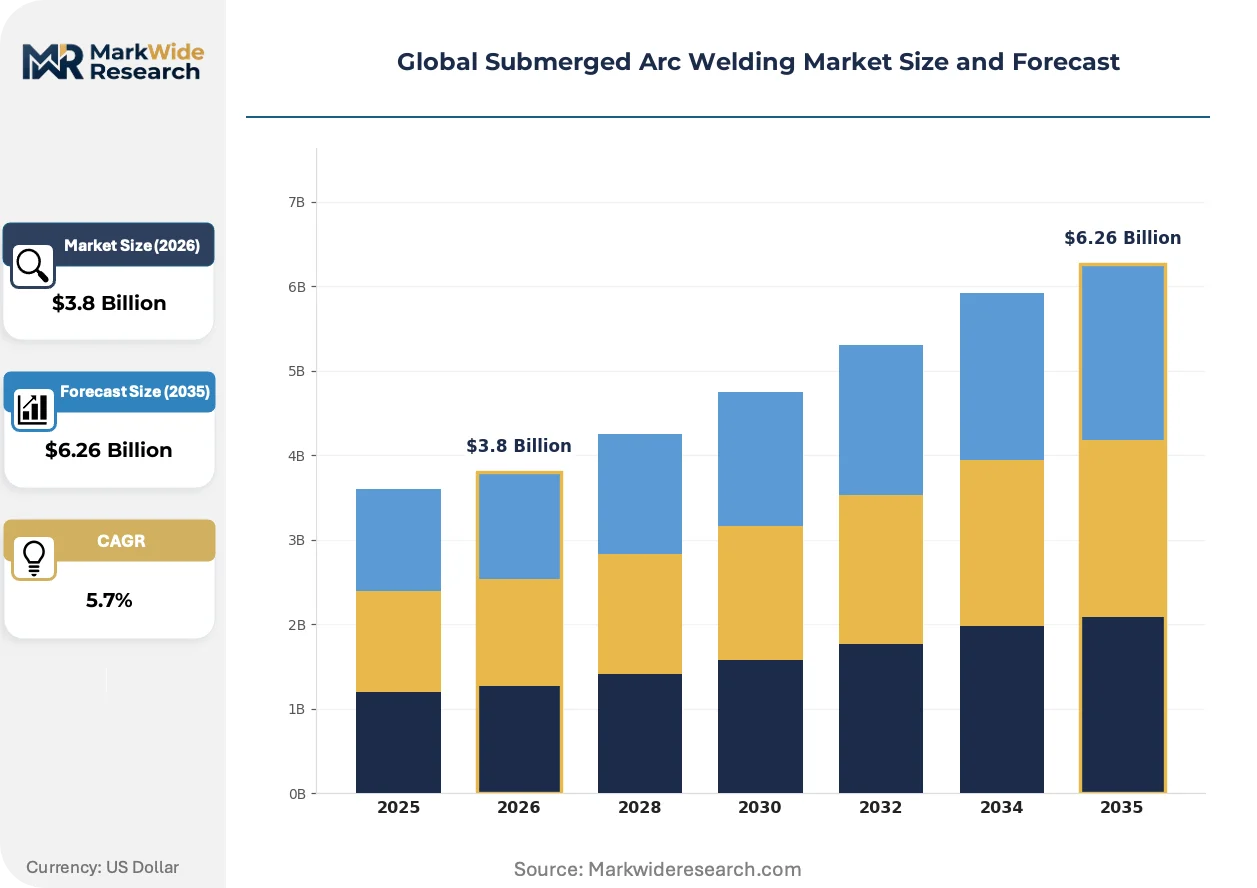
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Fluxes, Welding Electrodes, Welding Machines, Welding Consumables Technology: Single Wire, Tandem Wire, Twin Wire, Multi-Wire Application: Shipbuilding, Offshore Structures, Pressure Vessels, Pipeline Construction End User: Fabrication Shops, Heavy Machinery Manufacturers, Energy Sector, Construction Firms |
| Companies Covered | voestalpine Böhler Welding, OTC DAIHEN, Lincoln Electric, Carl Cloos Schweisstechnik, Panasonic Industry, ESAB, Fronius International, Kobelco Welding, Illinois Tool Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submerged Arc Welding Market Strategic Shifts & Innovations
Automation and data integration are defining the evolution of submerged arc welding. The focus is shifting from simple mechanization to intelligent systems that provide real-time process control and quality assurance, meeting demands for higher productivity and complete documentation traceability.
Advanced digital control systems are a primary focus of product evolution. These systems integrate the power source, wire feeder, and travel carriage into a single programmable unit. Heavy fabrication sectors like pressure vessel and wind tower manufacturing are early adopters, seeking consistent weld parameters over long seams. This technology is hybridizing the electromechanical welding process with software-driven controls, enabling pre-programmed weld sequences and reducing operator-induced variability.
European Union directives impose strict requirements on industrial equipment. The CE marking framework, particularly compliance with the Machinery Directive, mandates that SAW equipment manufacturers conduct thorough risk assessments and ensure specific safety features are integrated. This directly impacts equipment design, requiring features like interlocked guards and emergency stops. The directive most affects manufacturers exporting to or operating within the EU, forcing investment in certification and technical documentation.
Direct-to-fabricator sales models are beginning to disrupt traditional distribution channels for welding consumables. Specialized fabricators are increasingly purchasing specialized fluxes and wires from online platforms or directly from manufacturers to gain cost efficiencies and access to niche products. This shift is most prominent in North America, challenging the position of large industrial suppliers who have historically controlled regional supply chains for these high-margin recurring revenues.
Global Submerged Arc Welding Market Segmentation
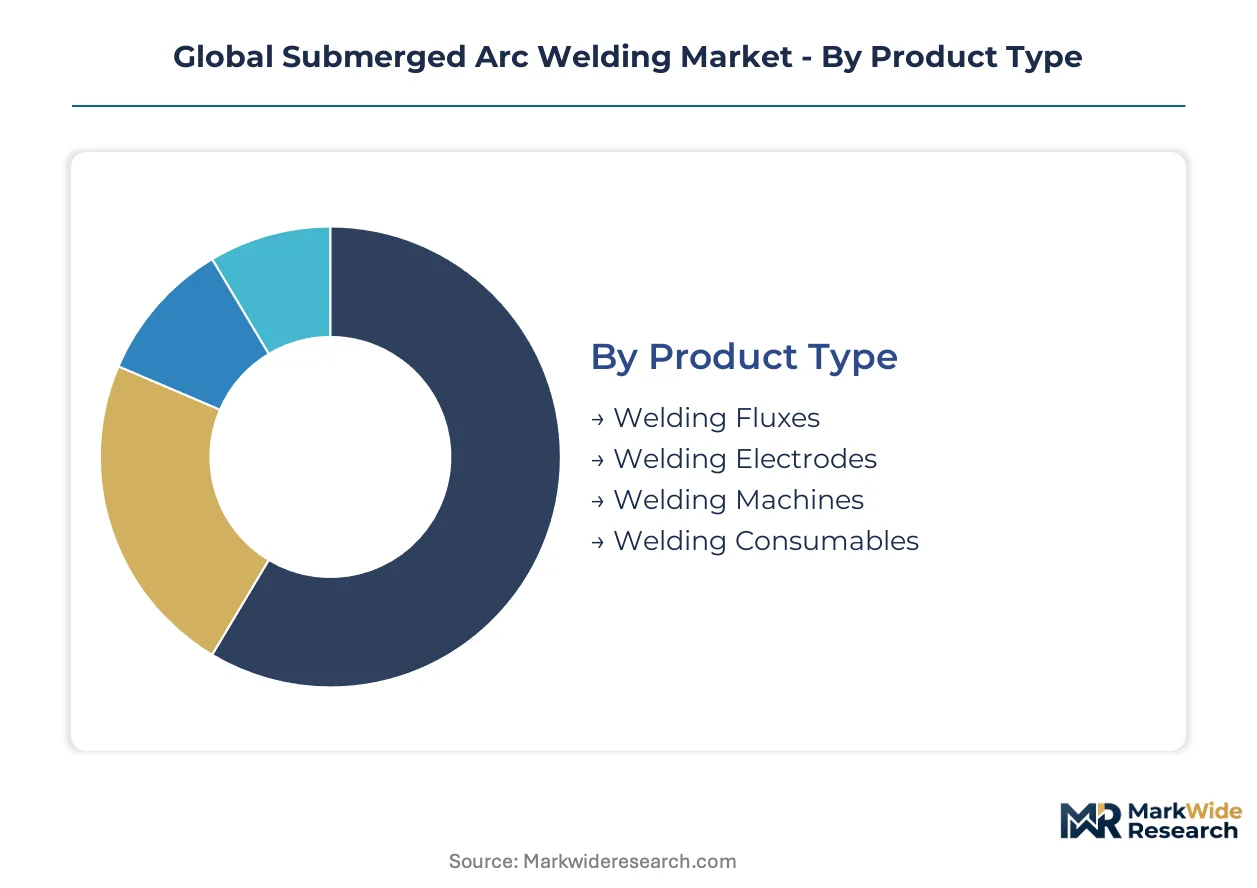
The submerged arc welding market segmentation provides a granular understanding of product and technology adoption across diverse industrial applications. This detailed breakdown highlights specific demand drivers and operational preferences shaping procurement patterns. Analyzing these segments reveals where investment concentrates and how different user groups prioritize process capabilities.
Product Type:
The product type segmentation addresses the spectrum of components required for effective submerged arc welding operations.
- Welding Consumables:This segment includes specialized fluxes, wires, and electrodes, consumed during welding to form the bead and protect it from atmospheric contamination. Demand for these recurring items is substantial within the energy sector, particularly for high-specification pipeline projects in North America, driven by stringent quality requirements.
- Welding Machines:These capital-intensive units comprise the power source, wire feeder, and control systems, often integrated with manipulators for automated operation. Heavy manufacturing clients, such as those in German wind tower fabrication, seek advanced digital control systems for consistent weld parameters over long seams.
- Welding Fluxes:Granular fusible materials form a protective blanket over the arc and molten metal, influencing weld chemistry and mechanical properties.
- Welding Electrodes:Continuously fed bare wire or cored electrodes conduct current and provide filler metal, available in various alloys for specific applications.
The dominant share belongs to Welding Consumables, while Welding Machines are closing the gap fastest due to automation investments.
Technology:
Technology segmentation differentiates systems based on wire configuration, impacting deposition rates and process efficiency.
- Multi-Wire:This technology employs two or more electrodes feeding into a single weld pool, significantly increasing deposition rates and productivity. Shipbuilding in South Korean and Chinese shipyards heavily utilizes multi-wire systems for joining thick plates in commercial vessels and offshore platforms.
- Single Wire:The most common and versatile SAW configuration, using one continuously fed electrode for general-purpose welding applications. This approach offers simplicity and cost-effectiveness, making it a staple for general fabrication shops and smaller pipeline projects in regions like India.
- Tandem Wire:Two electrodes operate in series, enabling independent control of welding parameters for higher speeds and deposition, common in large diameter pipe mills.
- Twin Wire:Two electrodes feed side-by-side from a single power source into the same weld pool, offering increased deposition compared to single wire systems.
Multi-wire technology exhibits the steepest expansion trajectory, driven by demands for enhanced productivity, while single wire systems maintain foundational market presence.
Application:
The application segments outline the primary end-use industries where submerged arc welding processes are extensively deployed.
- Pipeline Construction:SAW is critical for longitudinal and spiral seam welding of large-diameter pipes used in oil, gas, and water transmission infrastructure. Extensive energy pipeline projects in North America and transport infrastructure development under China's Belt and Road Initiative sustain demand.
- Shipbuilding:This sector relies on SAW for efficiently joining thick steel plates in the fabrication of commercial vessels, naval ships, and large cargo carriers. Productivity needs in South Korean and Chinese shipyards drive adoption of high-deposition SAW technologies for bulk carriers and container ships.
- Offshore Structures:Fabrication of oil rigs, platforms, and wind turbine foundations requires robust, high-integrity welds, making SAW a preferred process for heavy sections.
- Pressure Vessels:SAW ensures the high-quality, repeatable welds mandated by codes like ASME Boiler and Pressure Vessel Code for nuclear and power generation components.
Pipeline Construction represents the largest revenue contributor, while Offshore Structures show strong growth due to renewable energy investments.
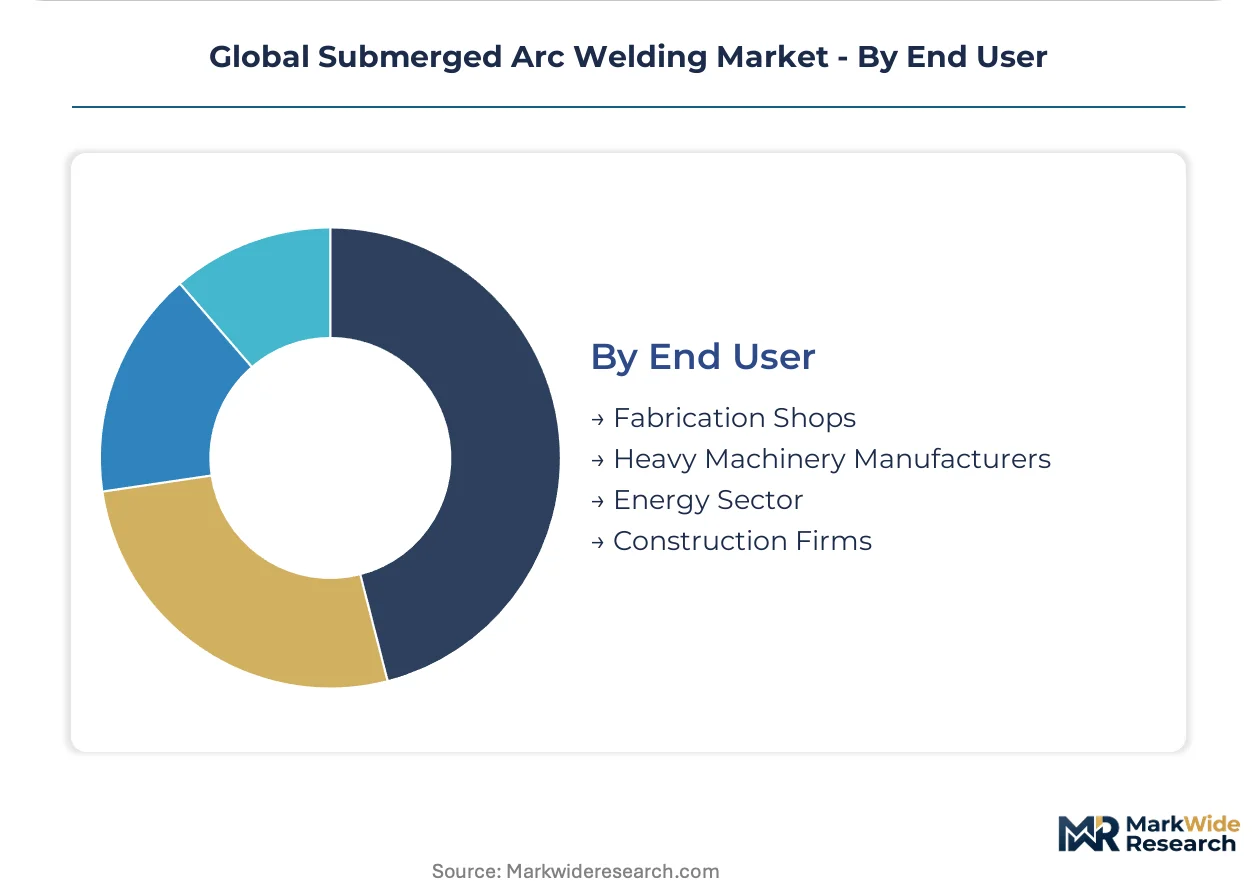
End User:
The end user segmentation categorizes the diverse entities that procure and implement submerged arc welding solutions.
- Energy Sector:This segment includes oil and gas, power generation, and chemical processing industries, demanding specialized SAW solutions for critical infrastructure. Stringent quality standards for components like pressure vessels and offshore wind foundations necessitate advanced SAW processes and high-performance consumables.
- Construction Firms:These include companies involved in large-scale infrastructure projects such as bridges, buildings, and transport networks, where structural integrity is paramount. China's Belt and Road Initiative and North American infrastructure investments drive substantial demand for SAW in fabricating heavy structural steel components.
- Fabrication Shops:These entities perform custom metalworking and assembly, utilizing SAW for various projects requiring high deposition rates and consistent weld quality.
- Heavy Machinery Manufacturers:Companies producing earthmoving equipment, agricultural machinery, and industrial vehicles employ SAW for robust and durable structural welds.
The Energy Sector holds significant revenue potential, driven by critical infrastructure needs, while Construction Firms demonstrate consistent demand across global projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for submerged arc welding solutions exhibits asymmetry, with high-specification equipment and consumables commanding premium rates in Germany compared to more cost-sensitive markets like India. This disparity reflects varying technological maturity and regulatory compliance across different regions. Demand drivers for SAW equipment and consumables remain robust globally.
United States
Demand for SAW in the United States stems from extensive energy pipeline construction and pressure vessel fabrication. The ASME Boiler and Pressure Vessel Code mandates high-quality, repeatable welds for critical components. Major infrastructure projects across Texas and the Gulf Coast drive significant procurement of automated SAW systems.
China
China's vast infrastructure development, including the Belt and Road Initiative, creates substantial demand for SAW in longitudinal and spiral seam welding of pipes. GB standards for welding ensure quality and safety in heavy manufacturing sectors. Shipyards in Dalian and Shanghai heavily utilize multi-wire SAW for bulk carriers and container ships.
Germany
German heavy manufacturing, particularly in wind tower fabrication and power generation, requires advanced SAW systems for consistent weld parameters. CE marking directives, including the Machinery Directive, impose strict safety and design requirements on equipment manufacturers. Welding technology clusters in the Ruhr region and Bavaria focus on digital control integration and automation for long seams.
South Korea
South Korean shipyards drive significant demand for multi-wire and tandem SAW technologies due to high productivity needs in shipbuilding and offshore platform construction. The country's national shipbuilding policies support advanced fabrication techniques for large commercial vessels. Ulsan and Geoje Island shipyards are major hubs for adopting high-deposition SAW processes for thick plates.
India
Infrastructure growth in India, including pipeline projects and general fabrication, sustains demand for single wire SAW configurations. BIS standards for welding quality guide material selection and process validation in various industrial applications. Manufacturing hubs around Pune and Chennai see consistent procurement of cost-effective SAW solutions for diverse projects.
Global Submerged Arc Welding Market Key Industry Players
Global industrial conglomerates and specialized welding technology providers split the market for submerged arc welding solutions. The competitive structure features a mix of broad-portfolio suppliers and niche players focusing on specific applications or advanced consumables. Strategic archetypes include integrated solution providers, high-performance consumable specialists, and automation-focused equipment manufacturers. Companies primarily engage in technology licensing, portfolio diversification, and strategic partnerships to enhance their market presence and address diverse client needs.
Among the integrated solution providers, Lincoln Electric, a US-based corporation, exemplifies a global footprint with extensive product offerings across equipment and consumables. ESAB, another prominent player, focuses on delivering automated and robotic welding systems for heavy manufacturing clients. voestalpine Böhler Welding, an Austrian-based entity, represents the specialization archetype, providing high-performance welding consumables tailored for demanding energy sector applications. These entities anchor different segments of the market, from general fabrication to highly specialized industrial needs.
| Leading Market Players |
|---|
| voestalpine Böhler Welding |
| OTC DAIHEN |
| Lincoln Electric |
| Carl Cloos Schweisstechnik |
| Panasonic Industry |
| ESAB |
| Fronius International |
| Kobelco Welding |
| Illinois Tool Works |
| Others |
Cost & Logistics Intelligence
China's concentrated demand for SAW equipment and consumables directly influences downstream margin pools for specialized items. This supply concentration impacts global pricing dynamics for core components.
Pricing Analysis
Configured-to-order robotic SAW systems command a premium over standard, off-the-shelf equipment, reflecting project-based pricing for complex integrations and transactional models for consumables. Price differentiation stems from quality grade, adherence to standards like API, and customization levels for integrated solutions. Pricing softness reflects intense competition for standard equipment in volume markets. Fabrication shops are most price-sensitive, whereas energy sector clients for high-specification applications exhibit lower sensitivity.
Supply Chain Analysis
Contract manufacturing capacity for core SAW equipment components concentrates in China, alongside specialized flux production. Global supply for welding consumables and machines draws from manufacturing hubs in China, Germany, and the United States. Raw material dependencies include steel wire, various flux ingredients, and electronic components for digital control systems. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution runs through a fragmenting network, shifting from large industrial suppliers towards direct-to-fabricator and online sales models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The submerged arc welding market is experiencing a shift in buyer power, driven by the fragmentation of traditional distribution channels towards direct-to-fabricator sales models. This shift empowers specialized fabricators with more procurement options.
For Market Incumbents: Build a technological moat through continuous investment in advanced digital control systems and integrated data logging capabilities. Incumbents must prioritize R&D for AI-driven process optimization to counter process immobility and skilled operator shortages. This strategy defends against specialized online platforms disrupting consumable sales and ensures compliance with ISO 3834 traceability requirements. Lincoln Electric and ESAB can leverage existing global networks for large-scale infrastructure projects.
For New Entrants and Emerging Players: Establish a beachhead in high-growth, specialized niches like offshore wind fabrication or corrosion-resistant cladding. Focus on developing high-performance consumables tailored for these demanding applications, bypassing the capital-intensive equipment market. The most penetrable segment involves specialized fluxes and wires sold directly via online platforms. This go-to-market angle leverages cost efficiencies and access to niche products for specialized fabricators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized specialized consumable manufacturers or automation software developers within the SAW ecosystem. The long-term viability of SAW remains strong for critical infrastructure projects over the next decade. Acquisition targets should focus on companies with proprietary flux formulations or advanced digital control IP. The signal to watch is an increased regulatory mandate for digital traceability and real-time process monitoring in critical welding applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Integration of SAW Systems | Enhances weld quality and traceability for critical applications under ISO 3834 requirements. |
| Specialized Consumables R&D | Addresses demand for high-performance welding materials in offshore wind and energy sectors. |
| Automated Multi-Wire Technology Expansion | Boosts productivity in shipbuilding and heavy manufacturing, particularly in Asian shipyards. |
| Direct-to-Fabricator Sales Channel Development | Disrupts traditional distribution, offering cost efficiencies and niche product access for fabricators. |
| Investment in Fume Extraction Solutions | Ensures compliance with stricter occupational health regulations like OSHA's manganese exposure rules. |
Research Approach
Operator-level perspectives from welding engineers, fabrication shop owners, procurement managers, and regulatory compliance officers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research, including ASME Boiler and Pressure Vessel Code, API standards, and national shipbuilding policies. This approach ensured a robust bottom-up and top-down validation of market insights.
Scenario-bracketing, encompassing optimistic, pessimistic, and base cases, formed the analytical framework across the projection horizon. The modeling integrated segmentation across product type, technology, application, end-user, and regional infrastructure investment patterns. CAGRs were derived from historical trends, projected demand drivers, and expert consensus. Key industry-specific inputs included planned pipeline construction projects and offshore wind farm development schedules.
Sensitivities concentrate around geopolitical shifts impacting infrastructure investment, commodity price fluctuations, and new regulatory mandates for weld quality. Forecasts reflect assumptions documented in the full report. Quarterly review of global energy demand, infrastructure spending, and steel prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Felling Heads Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Construction Equipment Tire Market