
 Concrete Block Making Machines Market | 2026-2036
Concrete Block Making Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Block Making Machines Market Outlook
Automated quality certification is bifurcating the competitive landscape between premium and commodity equipment tiers. QGM leverages integrated servo-hydraulic controls to sustain precision output in high-volume Chinese operations. Hydraform anchors the interlocking block niche with specialized soil-cement technology that dominates rural African markets. REIT Machine differentiates through PLC-controlled vibration systems that compete aggressively on cycle-time efficiency in Middle Eastern projects.
Concrete block making machines are industrial equipment designed to mold cement, aggregate, and water mixtures into standardized masonry units through hydraulic compression or mechanical vibration, typically achieving densities between 1,800 and 2,200 kg per cubic meter for load-bearing applications. Automatic machines with PLC-controlled batching and curing integration now lead capital expenditure flows among construction companies, while mobile machines represent the fastest-growing configuration as contractors seek on-site production flexibility near remote infrastructure sites. Hydraulic technology occupies the largest installed base, though vibration-based systems are displacing legacy mechanical presses in cost-sensitive emerging markets where energy efficiency determines total ownership economics.
CE marking under the EU Machinery Directive and ISO 12100 safety standards govern European market access, while India's BIS certification mandates structural load-testing for concrete masonry equipment sold domestically. The US EPA regulates particulate emissions from cement handling operations, shaping dust-collection specifications that manufacturers must integrate. Stakeholders should monitor how building code harmonization across ASEAN markets reshapes equipment specification requirements before committing to regional production strategies.
Market Dynamics
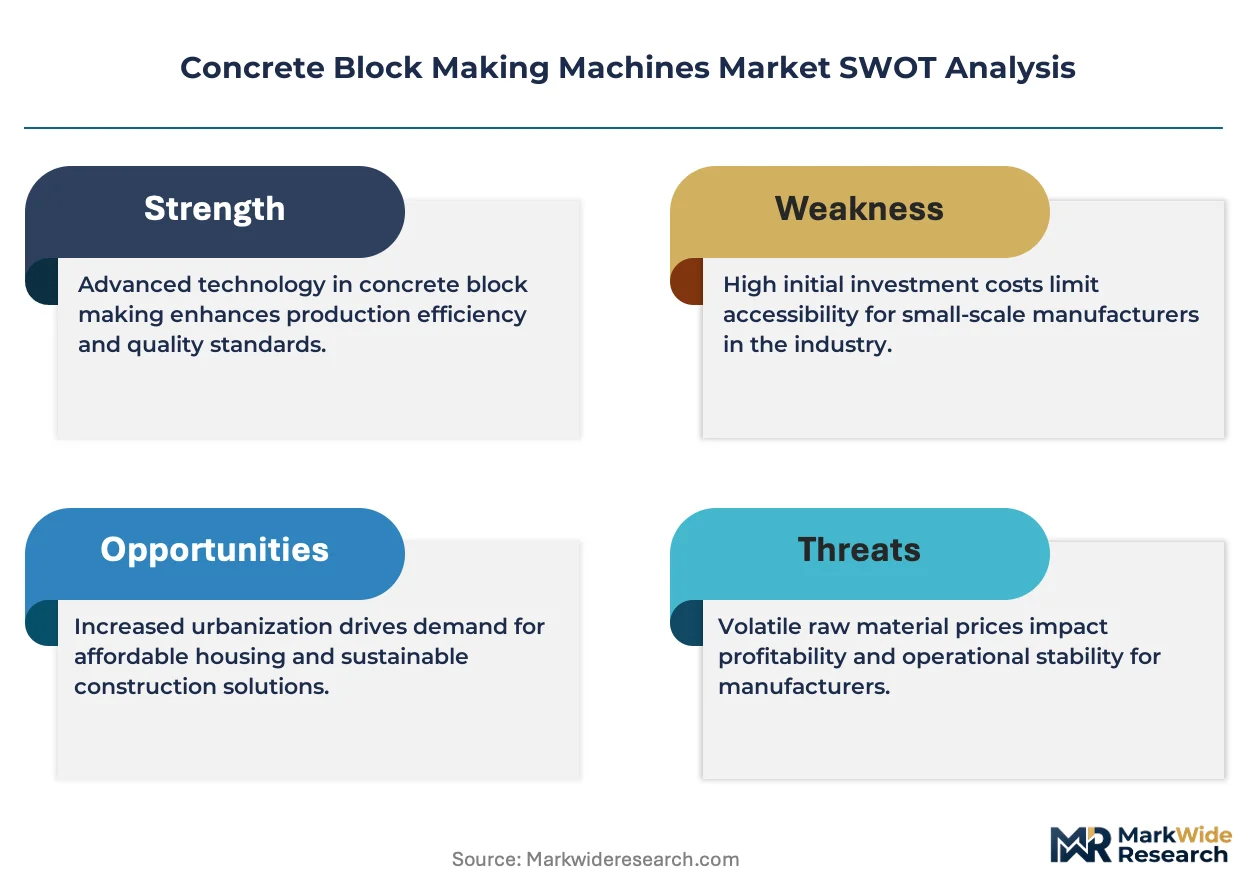
Automated quality certification is bifurcating the competitive landscape between premium and commodity equipment tiers, forcing manufacturers to choose between precision-engineered servo-hydraulic systems and cost-optimized mechanical presses.
Growth Catalysts
- India's urban infrastructure programs:Low-cost housing schemes and smart city initiatives are accelerating block production capacity additions across Maharashtra and Gujarat.
- EU Machinery Directive compliance:CE marking requirements for safety and energy efficiency are pressuring construction firms toward higher-efficiency equipment replacements.
- Soil-cement interlocking technology:Hydraform's specialized process dominates rural African markets where transport infrastructure limits centralized production.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-pressure cylinders and vibration motors compress margin predictability for equipment manufacturers.
- Chinese supply concentration:Critical servo-drive and PLC control modules source predominantly from Shenzhen and Shanghai, creating single-point vulnerability.
- Alternative walling materials:Autoclaved aerated concrete panels and prefabricated steel framing substitute for traditional masonry in mid-rise commercial construction.
Strategic Opportunities
- On-site mobile production:Remote infrastructure projects in Saudi Arabia and UAE are adopting trailer-mounted block plants to eliminate transport costs.
- EU Green Deal alignment:Carbon border adjustments and embodied carbon reporting create preference for electric-powered vibration systems over diesel hydraulics.
- Blockchain-integrated certification:Immutable quality records for load-bearing blocks open premium pricing in insurance-sensitive commercial developments.
Industry Challenges
- PLC programming specialization:Shortage of technicians capable of calibrating servo-hydraulic control loops delays commissioning and extends downtime.
- BIS certification timelines:India's mandatory structural load-testing procedures create 4-6 month approval backlogs for new equipment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Block Making Machines Market |
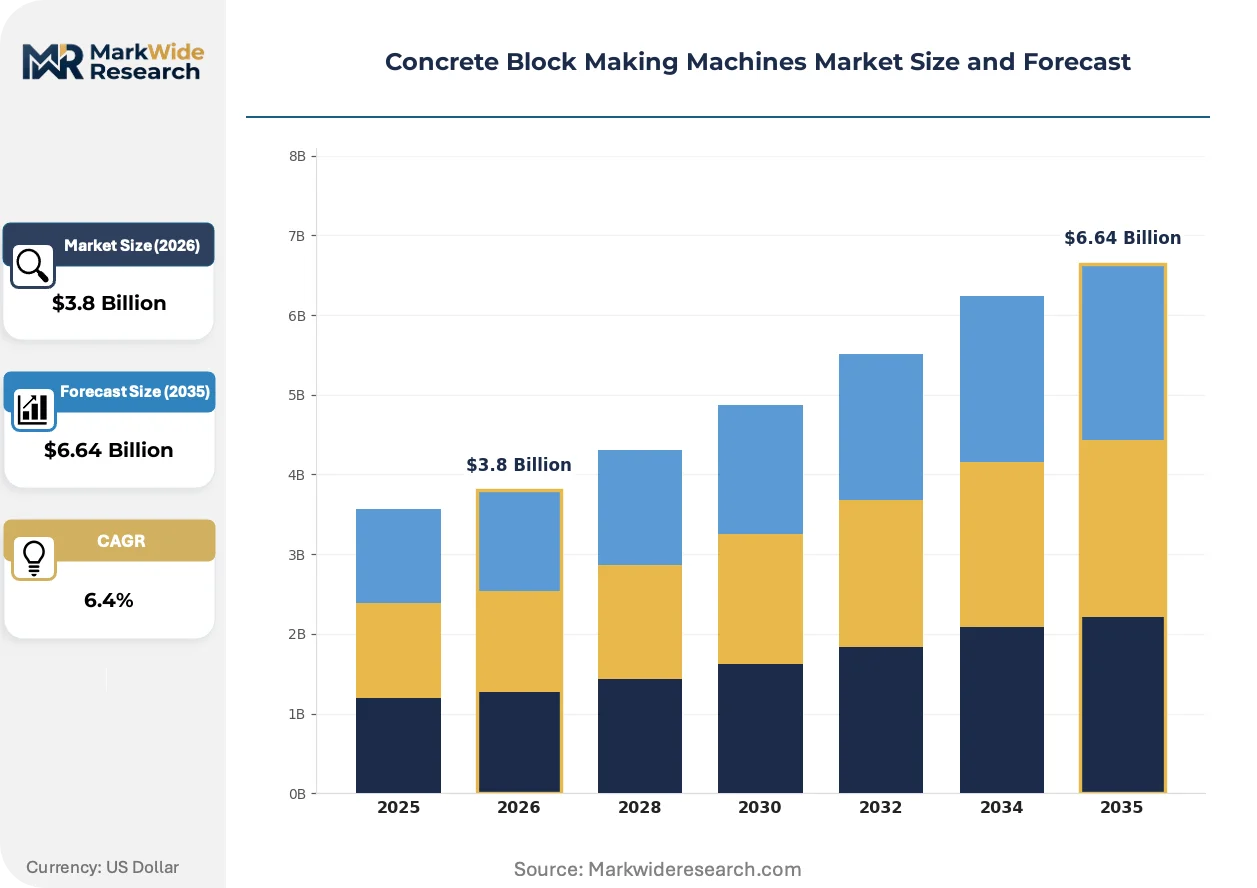
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Automatic Machines, Semi-Automatic Machines, Mobile Machines End User: Construction Companies, Contractors, Manufacturers, Builders Technology: Hydraulic, Vibration, PLC Controlled, Mechanical Capacity: Low Capacity, Medium Capacity, High Capacity, Others |
| Companies Covered | GM Quangong Machinery (QGM), Hydraform, Press Makina, Sadhana Engineering Industry, BESS Company, REIT Machine, Zenith, Henry, Global Machine Market, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Block Making Machines Market Strategic Shifts
Servo-electric actuation is displacing conventional hydraulic power units across high-volume production lines, while regulatory pressure on embodied carbon accelerates material efficiency investments.
Integrated servo-hydraulic control systems are decomposing the traditional separation between pressing and vibration stages in automatic block machines. Large-scale Chinese construction material producers are retrofitting legacy lines with closed-loop force feedback to achieve ±2% density consistency. This convergence is decomposing the historical premium-commodity equipment boundary by delivering precision at mid-market price points.
REACH restrictions on hydraulic fluid formulations are compelling European manufacturers to adopt bio-based synthetic oils or abandon fluid power entirely. The industrial consequence is accelerated R&D spending on direct-drive electric presses with regenerative braking. German equipment suppliers face the steepest compliance costs, while Italian producers leverage existing electric press expertise to capture displaced demand.
Rental and lease-to-own models are displacing outright purchase for mid-tier contractors in Middle Eastern markets. Equipment financiers in Dubai and Riyadh now bundle maintenance and spare parts into per-block pricing structures. This shift is most visible among Saudi general contractors executing Vision 2030 giga-projects, where balance sheet flexibility outweighs long-term ownership economics.
Concrete Block Making Machines Market Segmentation
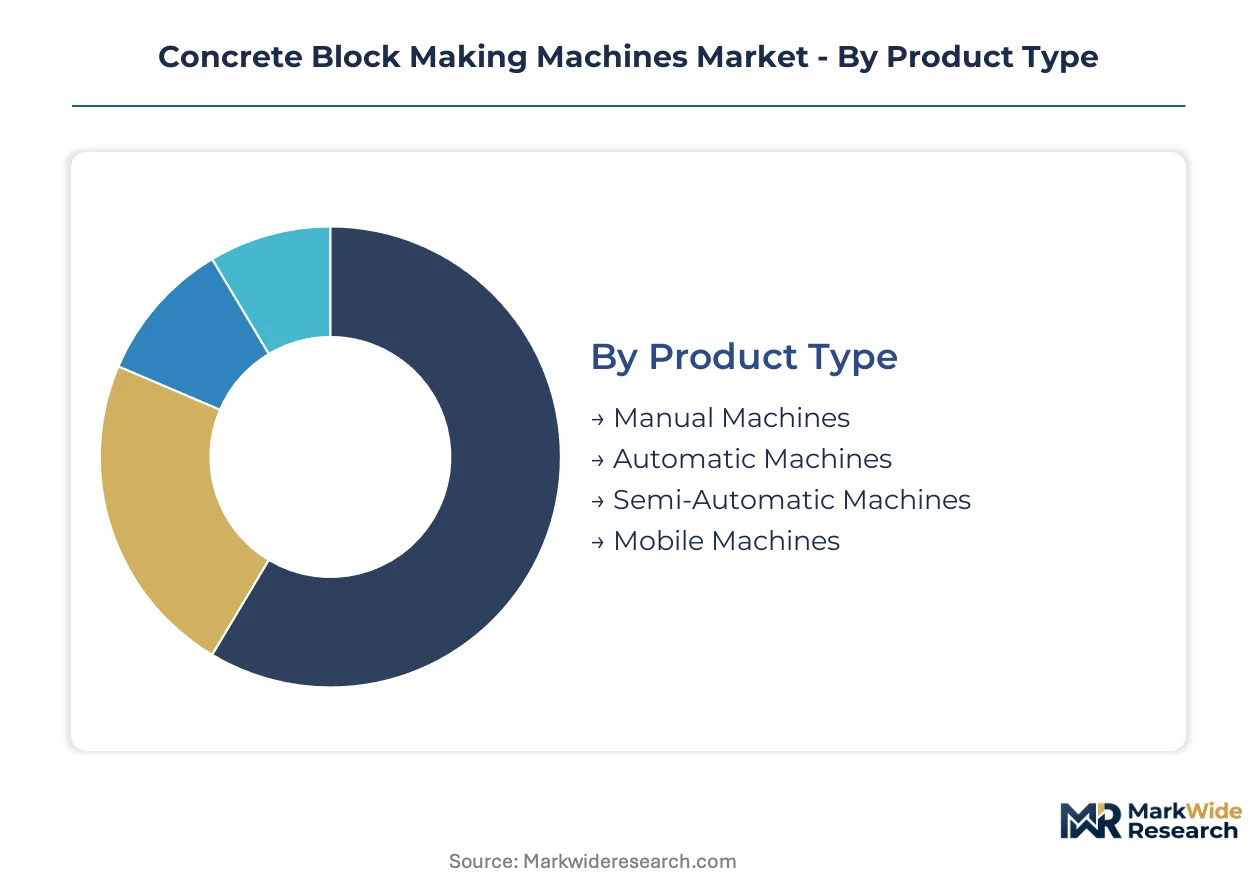
Concrete block making machines fragment across four structural dimensions that determine procurement patterns and margin profiles. Product type and technology choices drive capital intensity, while end-user scale and capacity requirements shape geographic deployment strategies.
Product Type:
Domestic production dominates manual and semi-automatic categories, while automatic and mobile machines flow through export channels into emerging infrastructure markets.
- Automatic Machines:PLC-controlled batching and curing integration enables continuous output with minimal labor intervention. Demand concentrates among large construction companies in India executing smart city and low-cost housing mandates where volume consistency outweighs capital expenditure.
- Mobile Machines:Trailer-mounted configurations enable on-site production at remote infrastructure locations, eliminating finished goods transport costs. Saudi Arabian and UAE contractors deploying Vision 2030 giga-projects are accelerating adoption where site accessibility limits centralized supply.
- Manual Machines:Hand-operated presses serve small-scale rural producers with minimal electrification requirements across African and South Asian markets.
- Semi-Automatic Machines:Hybrid designs balance labor input with mechanized vibration, finding traction among mid-tier contractors in Indonesia and Vietnam.
Automatic machines command the established base. The steepest expansion runs through mobile configurations.
End User:
Cost tier segmentation separates integrated manufacturers from project-based contractors with diverging total ownership economics.
- Construction Companies:Large-scale developers operating multi-year infrastructure programs favor high-capacity automatic lines with integrated quality certification. Indian urban infrastructure programs and Maharashtra-Gujarat industrial corridors are driving fleet upgrades.
- Contractors:Project-specific procurement favors lease-to-own and rental models, particularly among Saudi general contractors executing balance-sheet-light strategies under Vision 2030 financing structures.
- Manufacturers:Dedicated block producers serving regional distribution networks prioritize throughput optimization and energy efficiency under EU Green Deal carbon reporting requirements.
- Builders:Small-scale residential developers in emerging markets select manual or semi-automatic equipment based on initial capital constraints rather than lifecycle economics.
Construction companies absorb the majority of high-capacity installations. Contractors are gaining share fastest through equipment financing innovation.
Technology:
Application requirements determine power source selection, with hydraulic systems dominating load-bearing specifications and vibration technology penetrating cost-sensitive segments.
- Hydraulic:High-pressure compression systems achieve densities between 1,800 and 2,200 kg per cubic meter for structural masonry applications. European markets under CE marking and EU Machinery Directive compliance are sustaining replacement demand for energy-efficient servo-hydraulic upgrades.
- Vibration:Mechanical oscillation reduces capital cost and energy consumption, displacing legacy mechanical presses in Indian and Southeast Asian markets where electricity pricing determines operating economics.
- PLC Controlled:Programmable logic integration enables closed-loop force feedback and density consistency within ±2%, commanding premium positioning among quality-sensitive commercial developments.
- Mechanical:Cam-driven legacy presses retain residual presence in lowest-cost rural production environments with minimal technical support infrastructure.
Hydraulic systems anchor the installed base. PLC-controlled integration is climbing the fastest as precision requirements harden.
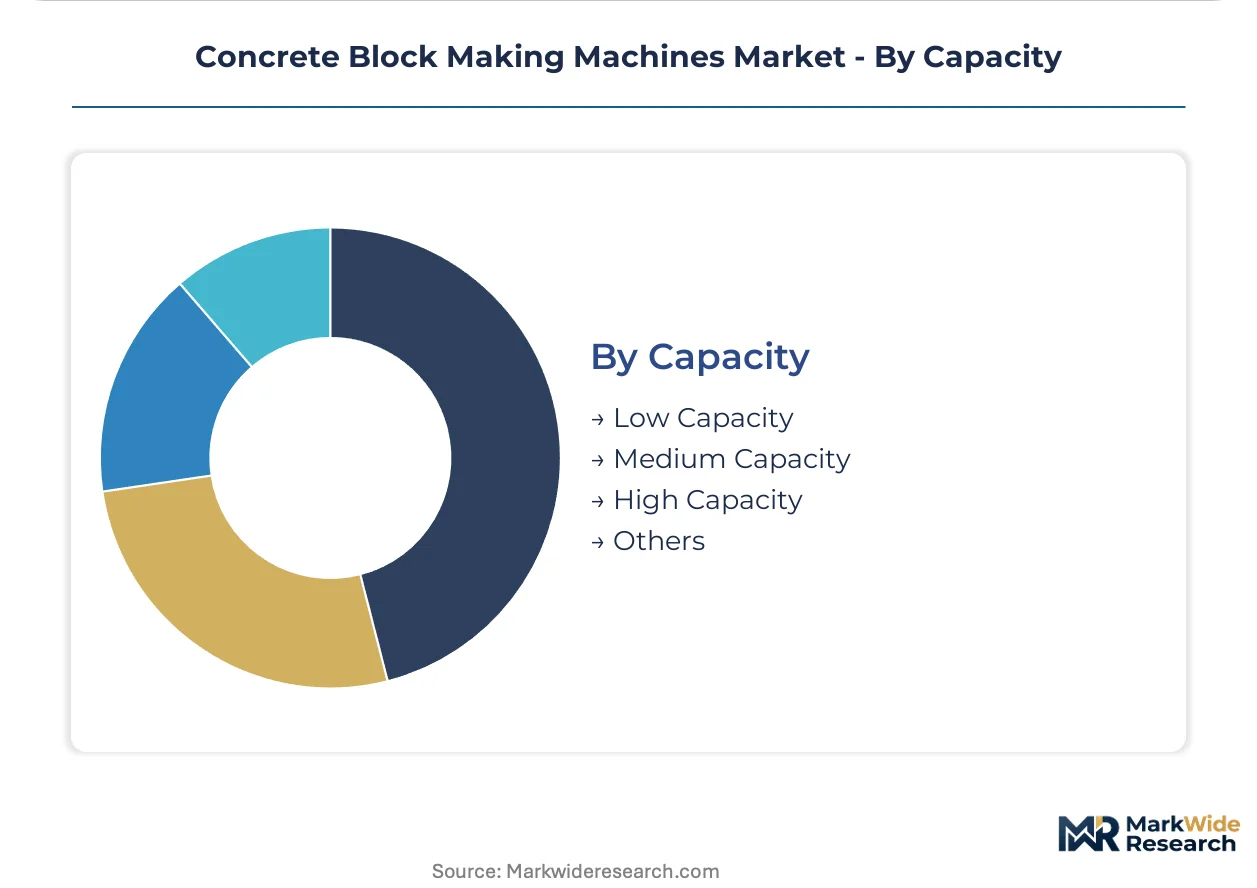
Capacity:
Volume scale segmentation aligns with customer capital depth and project duration, separating continuous production from intermittent batch operations.
- High Capacity:Continuous-output lines exceeding 2,000 blocks per hour serve dedicated manufacturing facilities supplying urban construction corridors. Chinese construction material producers retrofitting legacy lines with servo-hydraulic controls dominate this tier.
- Medium Capacity:Batch-flexible configurations balance throughput with product changeover capability, matching mid-rise commercial construction cycles in Brazil and Mexico.
- Low Capacity:Entry-level output levels serve rural housing programs and small contractor fleets across African markets where Hydraform's soil-cement interlocking technology reduces material transport dependency.
- Others:Specialized configurations including custom mold sizes and auxiliary curing systems address niche architectural block specifications.
High capacity lines dominate revenue concentration. Medium capacity equipment is expanding most quickly among diversifying regional contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, China, and India, with demand fragmentation pulling machinery toward construction corridors in Saudi Arabia and Brazil. Regulatory divergence across CE marking, BIS certification, and local content rules shapes regional deployment economics. Urban infrastructure programs in emerging economies are accelerating capacity additions near megacity construction zones.
China
Construction material producers in Jiangsu and Shandong provinces are retrofitting legacy lines with closed-loop force feedback systems. MIIT's dual carbon goals and GB standards for industrial energy efficiency are pressuring hydraulic equipment replacements. Shenzhen and Shanghai servo-drive manufacturing clusters supply critical PLC control modules to domestic and export markets.
India
Maharashtra and Gujarat industrial corridors are absorbing automatic machine installations for smart city and low-cost housing mandates. BIS certification mandates structural load-testing procedures that create 4-6 month approval backlogs for new equipment models. Delhi-NCR and Bangalore contractor fleets are expanding medium-capacity batch-flexible configurations for mid-rise commercial cycles.
Germany
REACH restrictions on hydraulic fluid formulations are compelling manufacturers to adopt bio-based synthetic oils or abandon fluid power entirely. CE marking under the EU Machinery Directive governs safety and energy efficiency compliance for European market access. Bavaria and North Rhine-Westphalia equipment suppliers face the steepest compliance costs while leveraging existing electric press expertise.
Saudi Arabia
Vision 2030 giga-projects are accelerating trailer-mounted mobile block plant adoption where site accessibility limits centralized supply. SFDA and local construction authority regulations shape equipment specification requirements for commercial developments. Riyadh and Eastern Province general contractors favor lease-to-own models with bundled maintenance for balance sheet flexibility.
Brazil
Mid-rise commercial construction cycles in São Paulo and Minas Gerais are driving medium-capacity equipment demand with batch-flexible configurations. ANVISA and national construction code harmonization reshape equipment specification requirements for regional production strategies. Rio Grande do Sul contractor fleets are diversifying toward vibration-based systems where electricity pricing determines operating economics.
Concrete Block Making Machines Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision-engineered servo-hydraulic specialists occupying premium tiers and mechanical press fabricators serving commodity segments. The vendor base separates into three strategic archetypes: integrated construction material conglomerates with captive equipment production, specialized machinery fabricators with regional service networks, and mobile configuration innovators targeting remote infrastructure logistics. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing agreements that transfer servo-electric actuation know-how across regional markets.
Within the precision-control tier, QGM represents integrated servo-hydraulic specialization for high-volume Chinese operations, while Hydraform anchors the interlocking block niche with soil-cement technology positioning for rural African markets. REIT Machine occupies a position among PLC-controlled vibration system specialists competing on cycle-time efficiency. These three exemplify how competitive positioning fragments across technology vectors rather than consolidating around scale or geography alone.
| Leading Market Players |
|---|
| GM Quangong Machinery (QGM) |
| Hydraform |
| Press Makina |
| Sadhana Engineering Industry |
| BESS Company |
| REIT Machine |
| Zenith |
| Henry |
| Global Machine Market |
| Others |
Value Chain & Pricing Dynamics
High-volume production scale in Chinese manufacturing clusters anchors both supply concentration and price floors for automatic block machines. CE marking compliance costs and BIS certification timelines create tiered entry barriers that stratify equipment pricing across premium servo-hydraulic and commodity mechanical press categories.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European markets, separating certified servo-hydraulic systems from uncertified mechanical alternatives. Three-tier pricing structure across premium PLC-controlled, standard hydraulic, and economy vibration-based levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Southeast Asian contractors prioritize electricity efficiency over precision specifications. Small-scale rural builders in African markets exhibit highest price sensitivity, while large construction companies executing smart city mandates in Maharashtra and Gujarat demonstrate lowest sensitivity due to volume-scale procurement.
Supply Chain Analysis
Shenzhen and Shanghai servo-drive manufacturing clusters underwrite critical PLC control module availability for domestic Chinese producers and export markets. Component sourcing draws from German hydraulic cylinder specialists, Italian vibration motor fabricators, and Chinese electronics assembly operations. Single-source vulnerability concentrates in high-pressure hydraulic systems and precision servo controllers. Distribution runs through regional equipment financiers in Dubai and Riyadh bundling maintenance into lease-to-own structures for Saudi Vision 2030 contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between blockchain-integrated quality certification systems and insurer risk models is repositioning equipment vendors as data-platform operators rather than pure hardware suppliers.
For Market Incumbents: Secure captive supply of servo-hydraulic control modules through backward integration into Shenzhen electronics clusters or long-term offtake agreements with Shanghai PLC specialists. Defend margin position against vibration-based displacement in Indian markets by embedding closed-loop force feedback as standard across mid-tier automatic lines. Certification investment in BIS pre-approval testing protocols reduces commissioning delays that currently favor established competitors with existing model clearances. For New Entrants and Emerging Players: Lead with mobile trailer-mounted configurations targeting remote Saudi giga-project sites where site accessibility constraints eliminate centralized supply competition. Hydraform's soil-cement interlocking niche in rural African markets remains underpenetrated by precision-control specialists, offering white-space entry through adapted vibration technology. Go-to-market execution should emphasize per-block financing partnerships with Dubai-based equipment lessors already active in Vision 2030 contractor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment financiers bundling maintenance and spare parts into lease structures, suggesting superior cash-flow quality versus outright sales-dependent manufacturers. Long-term viability favors mid-cap specialists with existing electric press expertise positioned to capture hydraulic displacement under REACH bio-fluid restrictions. Monitor BIS certification backlog durations as inflection indicator for Indian market access friction and incumbent protection intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Retrofit Program | REACH bio-fluid restrictions accelerate R&D spending on direct-drive electric presses with regenerative braking in Bavaria. |
| Blockchain Quality Integration | Immutable load-bearing certification opens premium pricing in insurance-sensitive commercial developments across Dubai. |
| Mobile Configuration Expansion | Trailer-mounted plants eliminate transport costs at remote Saudi giga-project sites under Vision 2030. |
| Lease-to-Own Financing Bundles | Per-block pricing structures with maintenance inclusion attract balance-sheet-light contractors in Riyadh. |
| BIS Pre-Certification Investment | Structural load-testing procedure mastery reduces 4-6 month approval backlogs for Maharashtra smart city deployments. |
Study Parameters
A spread of perspectives from plant engineers at construction material producers, procurement leads at Saudi general contractors, aftermarket service heads at European equipment suppliers, and channel partners in Indian industrial corridors converged on the working assumptions. Primary interview insights combined with customs trade data, BIS certification records, SEC 10-K filings from listed construction equipment manufacturers, and EU Machinery Directive compliance databases. Bottom-up equipment installation tracking and top-down construction output modeling provided triangulation across volume and value estimates.
Segmentation dimensions modeled include product type, technology architecture, end-user scale, and capacity tier across the projection horizon. CAGRs derived from regression analysis against construction output indices and infrastructure investment flows. Industry-specific forecast inputs incorporated MIIT dual carbon policy stringency and BIS approval timeline variability.
The analysis sits within stated boundaries; outcomes outside sustained Indian urban infrastructure program execution or EU Green Deal carbon border adjustment implementation would require recalibration. Forecasts reflect documented assumptions on steel and hydraulic component cost trajectories. Practitioners should keep alternative scenarios live as REACH hydraulic fluid restriction timelines and ASEAN building code harmonization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Used Machine Tools Market