
 Pressure Vessel Market | 2026-2036
Pressure Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Vessel Market Intelligence
Aftermarket service revenue is reconfiguring margin pools away from new-build fabrication across the pressure vessel supply chain. Babcock & Wilcox Enterprises leverages its installed base in power generation to capture recurring inspection and maintenance contracts. Larsen & Toubro Limited anchors large-project execution in the Middle East and Southeast Asia through integrated EPC capabilities. Mitsubishi Hitachi Power Systems specializes in supercritical and ultra-supercritical boiler systems, competing on high-efficiency thermal cycle parameters.
A pressure vessel is a closed container designed to hold gases or liquids at pressures substantially different from ambient, typically constructed from carbon steel, stainless steel, or composite laminates and manufactured through forging, welding, or filament winding to meet ASME Section VIII or equivalent design codes. Its primary purpose is to enable safe containment, reaction, heat transfer, or phase separation in industrial processes operating under mechanical stress and thermal load. Steel dominates material selection for high-pressure hydrocarbon service, while composite segments gain traction in hydrogen and CNG transport applications where weight reduction improves logistics economics. Chemical processing and power generation remain the largest end-user categories, though water treatment desalination vessels show structural momentum in coastal water-stressed regions.
ASME Boiler and Pressure Vessel Code, EU Pressure Equipment Directive, and ISO 16528 shape design certification, fabrication quality, and cross-border market access for suppliers serving multiple jurisdictions. China's SAMR enforces GB 150 standards for domestic pressure equipment, creating a parallel compliance track for foreign manufacturers seeking project participation. Stakeholders must monitor evolving hydrogen-specific design codes and carbon border adjustment mechanisms that will redefine competitive qualification thresholds.
Market Dynamics
ASME Section VIII code revisions and hydrogen infrastructure buildouts are compressing certification timelines while expanding addressable demand for high-pressure containment systems across energy transition corridors.
Growth Catalysts
- ASME Boiler and Pressure Vessel Code updates:North American fabrication standards are tightening qualification thresholds for hydrogen service, forcing upgrade cycles in existing installed bases.
- China petrochemical expansion:Integrated refinery and cracker complexes require high-capacity reactor vessels with advanced metallurgy specifications.
- Composite filament winding:Type IV hydrogen storage cylinders are displacing metallic alternatives in heavy-duty transport applications where weight reduction improves payload economics.
Market Restraints
- Nickel and molybdenum price volatility:Austenitic stainless steel input costs swing with mining supply disruptions, compressing fabrication margins on fixed-price EPC contracts.
- Specialized welder scarcity:ASME-certified pressure vessel welders concentrate in legacy manufacturing clusters, creating bottleneck risk for project execution.
- Extended ASME U-stamp certification timelines:Third-party inspection backlogs delay market entry for new fabrication facilities by 12-18 months.
Strategic Opportunities
- Saudi Arabia NEOM hydrogen megaproject:Giga-scale green ammonia production requires dedicated high-pressure storage and distribution vessel fleets.
- EU Carbon Border Adjustment Mechanism:Import tariffs on carbon-intensive steel are incentivizing local European fabrication capacity expansion.
- Modular skid-mounted systems:Shop-fabricated pressure vessel packages are displacing field-erected units in remote oilfield and mining applications.
Industry Challenges
- Hydrogen embrittlement metallurgy expertise:Advanced high-strength steel selection and welding procedure development require scarce materials engineering talent.
- Legacy asset digital retrofit integration:IoT sensor deployment on existing vessels faces mechanical design constraints and certification ambiguity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Vessel Market |
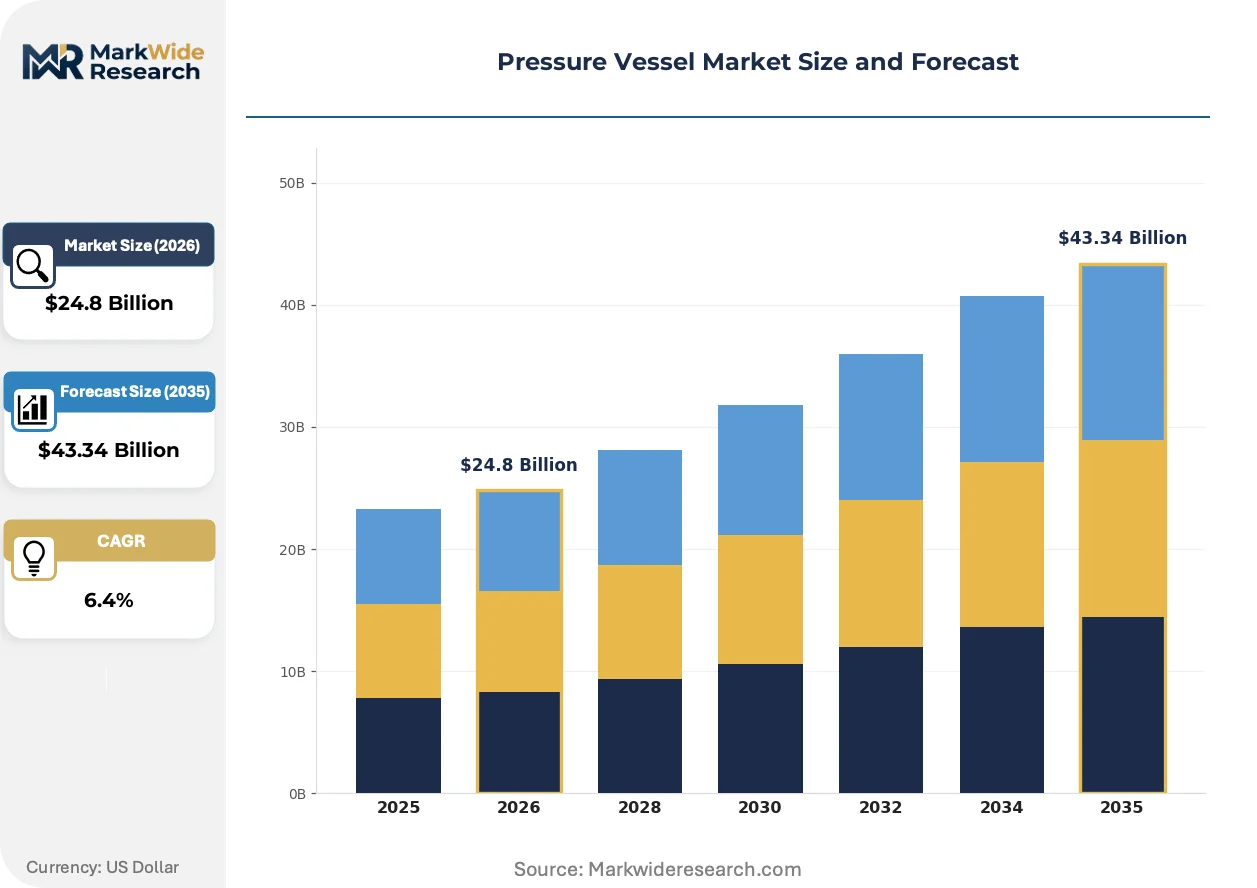
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Tanks, Heat Exchangers, Reactors, Boilers Material: Steel, Aluminum, Composite, Glass-Fiber End User: Oil & Gas, Power Generation, Chemical Processing, Water Treatment Installation: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Hitachi Zosen Corporation, Samuel Pressure Vessel Group, General Electric Company, Babcock & Wilcox Enterprises, Doosan Heavy Industries & Construction, Larsen & Toubro Limited, Bharat Heavy Electricals Limited, Andritz AG, Mitsubishi Hitachi Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Vessel Market Strategic Shifts & Innovations
Digital inspection protocols and advanced manufacturing methods are compressing fabrication cycles while enabling predictive maintenance business models across installed base fleets.
Composite pressure vessel construction is migrating from metal-lined Type III designs to linerless Type IV configurations. Heavy-duty truck and bus OEMs are accelerating adoption for onboard hydrogen storage. The shift is compressing per-kilogram storage costs while extending vessel fatigue life beyond metallic alternatives.
EU Pressure Equipment Directive 2014/68/EU amendments are tightening conformity assessment procedures for hydrogen service equipment. Notified body capacity constraints are extending CE marking timelines. German and Dutch fabricators are investing in dedicated hydrogen testing facilities to capture early certification advantages.
Aftermarket service contracts are unbundling from original equipment supply. Petrochemical operators in the US Gulf Coast are separating inspection and maintenance spend from capital procurement budgets. This bifurcation is enabling specialized service providers to capture recurring revenue streams independent of new-build fabrication cycles.
Pressure Vessel Market Segmentation
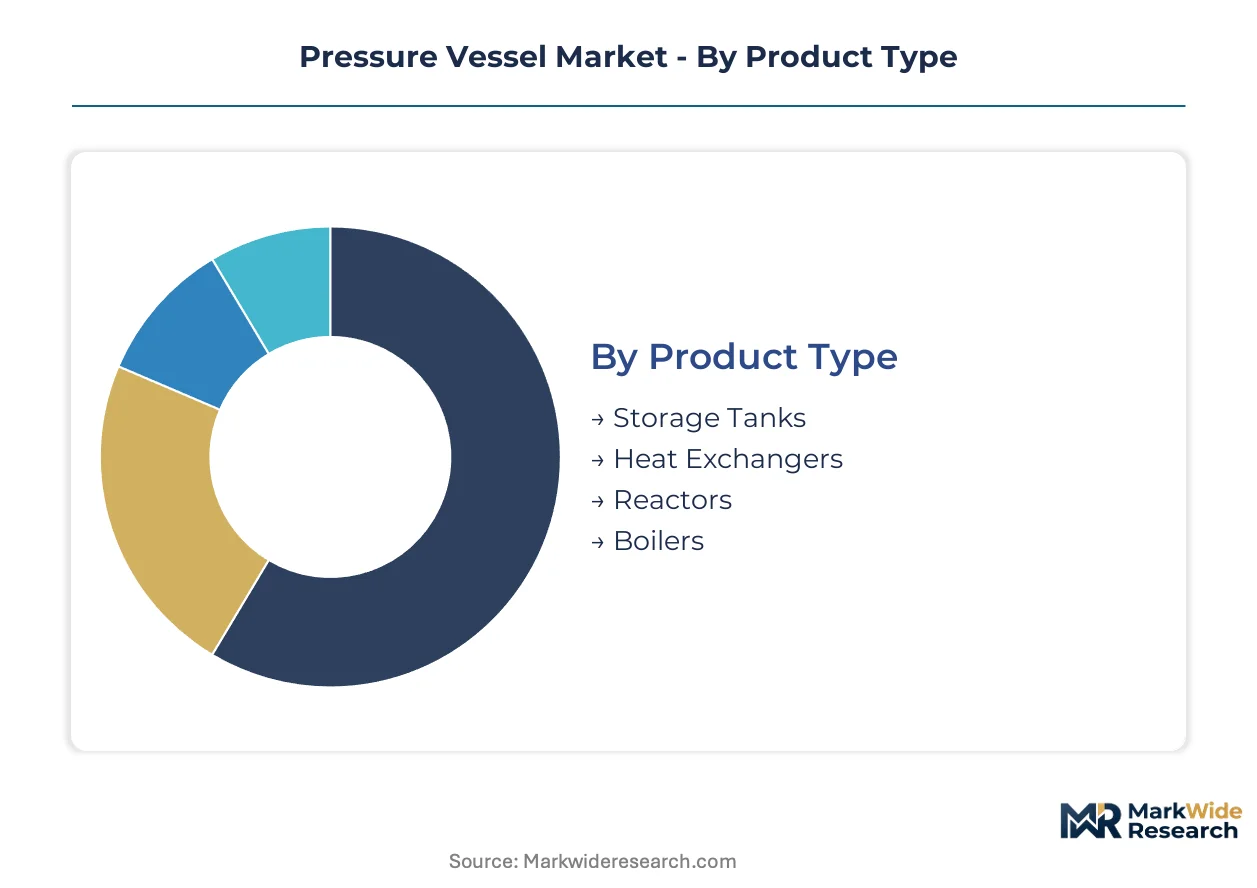
Pressure vessel procurement varies sharply by containment duty, metallurgical specification, and site constraints. Each segmentation axis reveals distinct margin structures and certification requirements that shape supplier positioning.
Product Type:
Process integration depth spans bulk commodity storage through precision reaction engineering.
- Storage Tanks:Atmospheric and pressurized containment systems handle hydrocarbon feedstocks and intermediate products. Demand clusters in US Gulf Coast petrochemical corridors where tank farm expansions serve export-oriented polyethylene complexes. API 650 and API 620 fabrication standards govern wall thickness and weld inspection protocols.
- Reactors:Catalytic conversion vessels operate under combined thermal and mechanical loading with exotic alloy requirements. China SAMR-certified fabricators dominate high-capacity reactor supply for integrated refinery and cracker projects along the Bohai Rim.
- Heat Exchangers:Shell-and-tube and plate configurations enable thermal energy recovery across process streams.
- Boilers:Steam generation systems serve power and industrial heat applications.
The dominant share belongs to Storage Tanks, while Reactors are closing the gap fastest.
Material:
Cost tiers separate commodity carbon grades from performance-engineered alternatives.
- Steel:Carbon and alloy grades constitute the baseline for high-pressure hydrocarbon service. Japanese fabricators leverage JIS-certified heat treatment expertise to supply ASME-stamped vessels for Southeast Asian LNG import terminals. Nickel-molybdenum price swings compress margins on fixed-price contracts.
- Composite:Carbon fiber filament winding enables Type IV hydrogen cylinders with 30-40% weight reduction versus metallic alternatives. German and Dutch specialists are investing in dedicated hydrogen testing facilities to capture early EU Pressure Equipment Directive certification advantages.
- Aluminum:Lightweight alloys serve cryogenic and aerospace-adjacent applications.
- Glass-Fiber:Reinforced thermoset constructions address corrosive chemical environments.
Steel retains volume leadership, though Composite is expanding most quickly in transport applications.
End User:
Customer maturity levels range from speculative project finance to recurring maintenance budgets.
- Chemical Processing:Continuous process plants require corrosion-resistant alloys and tight turnaround schedules. Operators on the US Gulf Coast are unbundling inspection contracts from capital procurement, enabling specialized service providers to capture recurring revenue.
- Power Generation:Supercritical and ultra-supercritical boiler systems compete on thermal efficiency parameters. Saudi Arabia NEOM hydrogen megaproject will require dedicated high-pressure storage fleets for giga-scale green ammonia production.
- Oil & Gas:Upstream and midstream containment spans exploration through distribution.
- Water Treatment:Desalination pressure vessels show structural momentum in coastal water-stressed regions.
Chemical Processing commands the largest installed base, while Water Treatment is gaining share fastest.
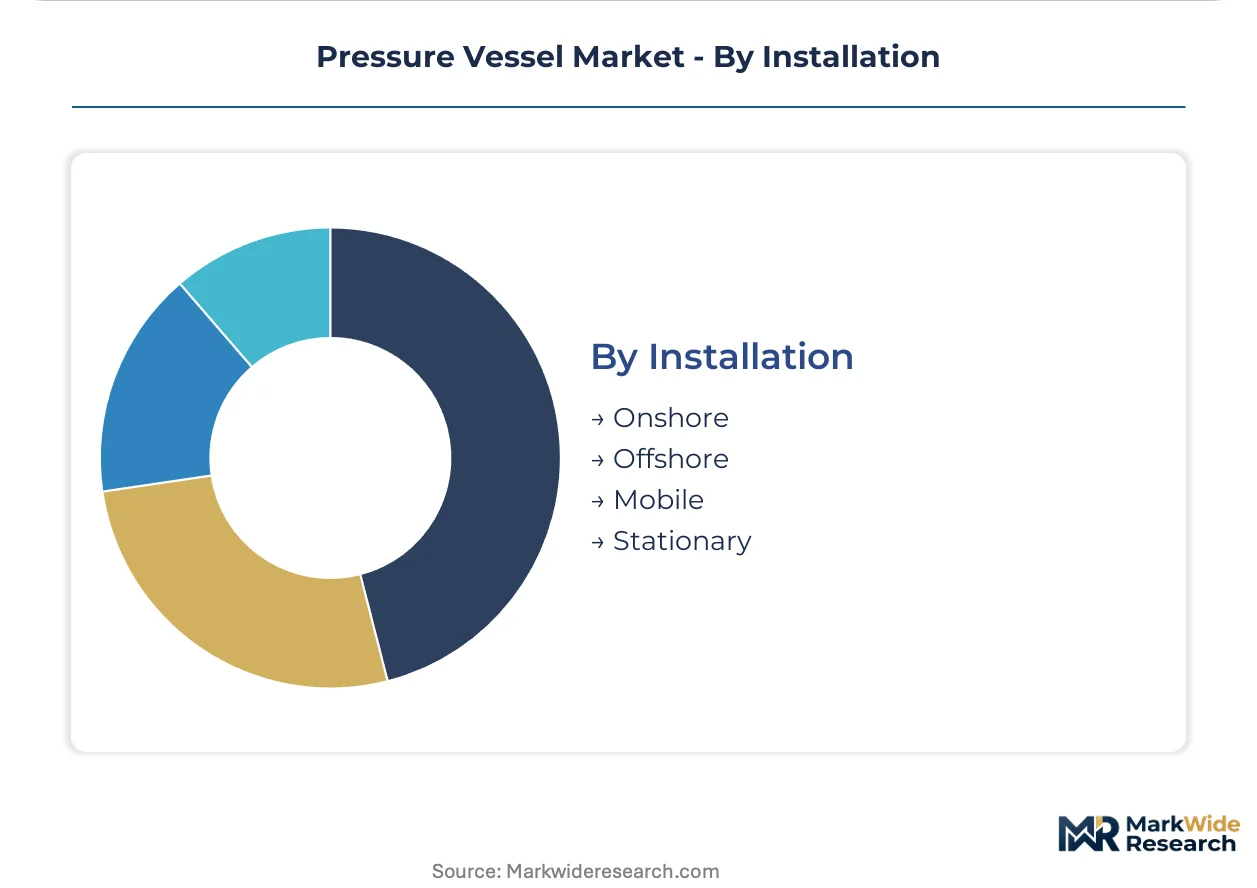
Installation:
Site logistics dictate fabrication location and modularization strategy.
- Onshore:Field-erected and shop-fabricated units serve fixed industrial facilities. Modular skid-mounted systems are displacing field-erected units in remote oilfield and mining applications where labor mobility is constrained.
- Offshore:Platform-integrated vessels face weight and space constraints with marine certification requirements.
- Mobile:Transportable containment serves temporary process needs and emergency response.
- Stationary:Permanent installations anchor long-term production infrastructure.
Onshore deployment dominates current order books, though Mobile installations are climbing fastest in distributed hydrogen fueling networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement dominates Middle Eastern project finance, while Japanese and German buyers prioritize metallurgical precision and certification pedigree over unit cost.
United States
Petrochemical renaissance along the Gulf Coast drives demand for high-capacity storage tanks and reactor vessels. EPA and OSHA enforce stringent fabrication standards for hydrogen service equipment. Houston anchors the largest concentration of ASME-certified fabrication yards, where modular skid-mounted systems are displacing field-erected units.
China
Integrated refinery and cracker complexes along the Bohai Rim require advanced alloy reactor vessels at unprecedented scale. SAMR enforces GB 150 standards, creating parallel compliance tracks for domestic and foreign suppliers. Dalian and Qingdao fabrication clusters dominate high-pressure containment output for nuclear and petrochemical buildouts.
Germany
Green hydrogen infrastructure investments accelerate demand for Type IV composite cylinders and high-pressure storage systems. EU Pressure Equipment Directive amendments tighten CE marking timelines for hydrogen service equipment. Ruhr Valley fabricators are investing in dedicated hydrogen testing facilities to capture early certification advantages.
Saudi Arabia
NEOM giga-scale green ammonia production requires dedicated high-pressure storage and distribution vessel fleets. SFDA and national energy regulators coordinate safety standards for hydrogen transport infrastructure. Jubail Industrial City hosts the largest concentration of heavy fabrication capacity serving regional energy transition projects.
Japan
Supercritical and ultra-supercritical boiler replacements drive precision pressure vessel demand from power utilities. METI oversees JIS certification alignment with ASME codes for export competitiveness. Nagoya and Yokohama manufacturing clusters specialize in heat-resistant alloy fabrication for thermal power applications.
Pressure Vessel Market Key Industry Players
Capability concentration sits with specialized metallurgical houses; scale advantage sits with integrated EPC conglomerates. The market structures around three tiers: global fabrication conglomerates with captive steel supply, regional specialists with certified welding capacity, and composite technology disruptors targeting hydrogen transport. Dominant competitive moves include backward integration into alloy steel production and strategic partnerships with hydrogen infrastructure developers.
Among Asia-Pacific-based conglomerates, Larsen & Toubro Limited and Mitsubishi Hitachi Power Systems exemplify divergent positioning strategies. Larsen & Toubro occupies a position within integrated EPC execution, anchoring large-project delivery across Middle Eastern and Southeast Asian corridors. Mitsubishi Hitachi Power Systems represents the precision-technology archetype, competing on thermal cycle efficiency parameters in supercritical boiler systems. Hitachi Zosen Corporation sits within the diversified industrial group tier, with pressure vessel fabrication representing one vertical among broader energy infrastructure capabilities.
| Leading Market Players |
|---|
| Hitachi Zosen Corporation |
| Samuel Pressure Vessel Group |
| General Electric Company |
| Babcock & Wilcox Enterprises |
| Doosan Heavy Industries & Construction |
| Larsen & Toubro Limited |
| Bharat Heavy Electricals Limited |
| Andritz AG |
| Mitsubishi Hitachi Power Systems |
| Others |
Cost & Logistics Intelligence
Commodity nickel and molybdenum price volatility compresses fabrication margins on fixed-price EPC contracts while simultaneously forcing tiered pricing stratification across austenitic stainless steel grades and carbon steel alternatives. This input cost uncertainty drives procurement officers toward long-term offtake agreements with Japanese and Korean metallurgical suppliers, reshaping inventory strategies across ASME-certified fabrication yards.
Pricing Analysis
Aftermarket inspection and maintenance contracts now drive lifetime value capture, with recurring service revenue streams unbundling from original equipment supply. Pricing stratifies across premium, standard, and economy tiers based on ASME U-stamp certification grade and bundled after-sales service intensity. Cost compression in standard-grade carbon steel vessels is intensifying due to Chinese oversupply in Dalian and Qingdao fabrication clusters. Midstream petrochemical operators on the US Gulf Coast demonstrate highest price sensitivity, while nuclear utilities and Saudi NEOM hydrogen developers prioritize metallurgical pedigree over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced carbon fiber filament winding equipment limit technology transfer to emerging hydrogen storage fabricators, constraining Type IV cylinder production scaling outside Germany and Japan. Supply concentrates in China for steel substrate and forging capacity, South Korea for specialized alloy processing, and Germany for composite hydrogen testing infrastructure. Raw material dependencies include nickel-molybdenum alloy feedstock, high-tensile carbon fiber tow, and ASME-certified welding consumables. Single-source vulnerability sits with Ukrainian nickel ore disruptions. Distribution runs through integrated EPC conglomerates anchoring project finance in Middle Eastern and Southeast Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent fabricators face substitution pressure from modular skid-mounted system providers displacing field-erected units in remote oilfield and mining applications.
For Market Incumbents: Harden certification moats by investing in dedicated hydrogen embrittlement testing facilities ahead of EU Pressure Equipment Directive amendments. Deepen backward integration into specialty alloy steel production to insulate margins from nickel-molybdenum volatility. Acquire ASME-certified welding talent pools in legacy manufacturing clusters to preempt execution bottlenecks. For New Entrants and Emerging Players: Modular hydrogen fueling networks in water-stressed coastal regions represent the most penetrable entry point, with desalination pressure vessel demand climbing fastest. Type IV composite cylinder fabrication for heavy-duty transport OEMs offers white-space capture where weight reduction improves payload economics. Partner with German and Dutch notified bodies early to compress CE marking timelines for hydrogen service equipment. For Investors and Strategic Acquirers: ASME Section VIII code revisions reshaping hydrogen service qualification thresholds reconfigure acquisition attractiveness toward metallurgical houses with scarce materials engineering talent. Long-term viability favors targets with captive installed base access for aftermarket revenue conversion. Watch EU Carbon Border Adjustment Mechanism implementation as the signal indicating European fabrication capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Testing Facility Investment | Captures early EU Pressure Equipment Directive certification advantages ahead of notified body bottlenecks. |
| Backward Integration into Alloy Production | Insulates margin structures from nickel-molybdenum price swings on fixed-price EPC contracts. |
| Modular Skid-Mounted System Expansion | Displaces field-erected units in remote Saudi and Australian mining corridors with constrained labor mobility. |
| Aftermarket Service Unbundling | Separates recurring inspection revenue from capital procurement budgets of US Gulf Coast petrochemical operators. |
| ASME Welder Talent Acquisition | Preempts project execution risk from certified welder scarcity concentrated in legacy manufacturing clusters. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPC project directors, pressure vessel procurement managers at petrochemical majors, ASME-certified welding supervisors, and aftermarket service heads at installed base fleets. Secondary validation drew from SAMR GB 150 regulatory filings, ASME Boiler and Pressure Vessel Code revision dockets, EU Pressure Equipment Directive notified body capacity reports, and customs trade data on nickel-molybdenum alloy imports. Bottom-up unit economics triangulated against top-down sectoral spend analysis across chemical processing, power generation, and hydrogen infrastructure buildouts.
Calibration anchored volume and value outputs to disclosed project awards, fabrication yard capacity utilization rates, and certified welder labor pool estimates across the projection horizon. Segmentation dimensions modeled encompass product type duty, metallurgical specification tier, end-user industry maturity, and installation logistics constraints. CAGRs derived from S-curve adoption patterns for hydrogen storage applications and replacement cycle analysis for supercritical boiler systems. Industry-specific forecast inputs included NEOM project phase commitments and China nuclear power buildout timelines.
Practitioners should monitor nickel-molybdenum mining supply disruptions, ASME U-stamp certification backlog durations, and EU Carbon Border Adjustment Mechanism tariff implementation for early signals of forecast deviation. Material shifts in hydrogen infrastructure subsidy allocation or SAMR domestic content requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Scaffold Technology Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Smart Crane Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Small Bulldozers Market