
 US Waterjet Cutting Machines Market | 2026-2036
US Waterjet Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
US Waterjet Cutting Machines Market Insights
Abrasive garnet is rebalancing cost structures as synthetic alternatives and recycling systems displace virgin mineral supply chains. Flow International Corporation leverages its high-pressure pump legacy to anchor premium system sales across defense subcontractors. OMAX Corporation differentiates through precision table design and software-controlled taper compensation. Hypertherm Inc. competes by extending plasma-waterjet hybrid workflows that capture metal service shops seeking single-platform flexibility.
Waterjet cutting machines deploy pressurized water streams, often mixed with abrasive particulate, to erode material through controlled jet impingement at pressures exceeding 60,000 psi; these systems execute cold cutting without heat-affected zones, preserving metallurgical integrity in hardened alloys and layered composites. Abrasive waterjet systems occupy the dominant revenue position due to throughput advantages in thick metal and stone applications, while robotic waterjet configurations represent the fastest-expanding segment as automotive and aerospace producers automate complex 3D trimming operations. Pure waterjet equipment sustains stable demand in food processing and foam fabrication where contamination risks prohibit abrasive media.
OSHA lockout-tagout and noise exposure standards shape machine guarding and enclosure specifications, while EPA effluent limitations under the Clean Water Act drive closed-loop filtration and abrasive recovery investments. State-level California Air Resources Board protocols add compliance layers for facilities operating in the Western region. Stakeholders must weigh capital allocation between standalone system upgrades and integrated automation platforms as labor availability tightens across Midwest manufacturing centers.
Market Dynamics
Abrasive garnet supply rebalancing and OSHA workplace safety mandates are compressing operational margins while accelerating capital deployment toward closed-loop filtration and automated trimming cells across Michigan automotive corridors and Texas energy-equipment hubs.
Growth Catalysts
- OSHA Noise Exposure Standards:Mandates for machine guarding and acoustic enclosures drive replacement cycles in legacy fabrication shops. Equipment upgrades prioritize integrated safety architectures over retrofitted add-ons.
- Titanium Aerospace Trimming:Cold-cutting preservation of metallurgical integrity in heat-sensitive alloys positions waterjet systems as mandatory for next-generation airframe component fabrication.
- Robotic 3D Configuration Adoption:Automotive producers automate complex contour trimming operations, expanding demand for multi-axis waterjet cells in Ohio and South Carolina assembly supplier networks.
Market Restraints
- Abrasive Media Cost Volatility:Virgin garnet mining concentration in Western Australia and India exposes US fabricators to freight rate fluctuations and currency hedge requirements.
- Plasma-Waterjet Hybrid Substitution:Metal service shops seeking single-platform flexibility increasingly specify combined thermal-mechanical cutting systems, compressing pure waterjet addressable share in steel plate processing.
- EPA Effluent Discharge Compliance:Clean Water Act limitations on suspended solids force capital-intensive closed-loop installation, extending payback periods for small-batch job shops.
Strategic Opportunities
- Closed-Loop Filtration Technology:Advanced abrasive recovery systems reduce virgin garnet consumption by seventy percent, creating recurring revenue streams through service contracts in California fabrication clusters.
- Food Processing Pure Waterjet Expansion:Contamination-risk-sensitive protein and produce cutting applications sustain stable equipment demand as USDA sanitary equipment standards tighten.
- Texas Energy-Equipment Manufacturing:Oilfield tool and pressure vessel fabricators adopt thick-section abrasive waterjet for exotic alloy profiling, offsetting upstream capital expenditure cyclicality with maintenance-of-way demand.
Industry Challenges
- Multi-Axis Programming Skill Scarcity:Robotic waterjet cell operation requires CAM software proficiency and jet kinematics knowledge that outpaces vocational training pipeline output in Midwest manufacturing centers.
- Legacy System Integration Friction:Brownfield facilities face MES connectivity gaps when retrofitting automated waterjet cells into established fabrication workflows, delaying throughput realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Waterjet Cutting Machines Market |
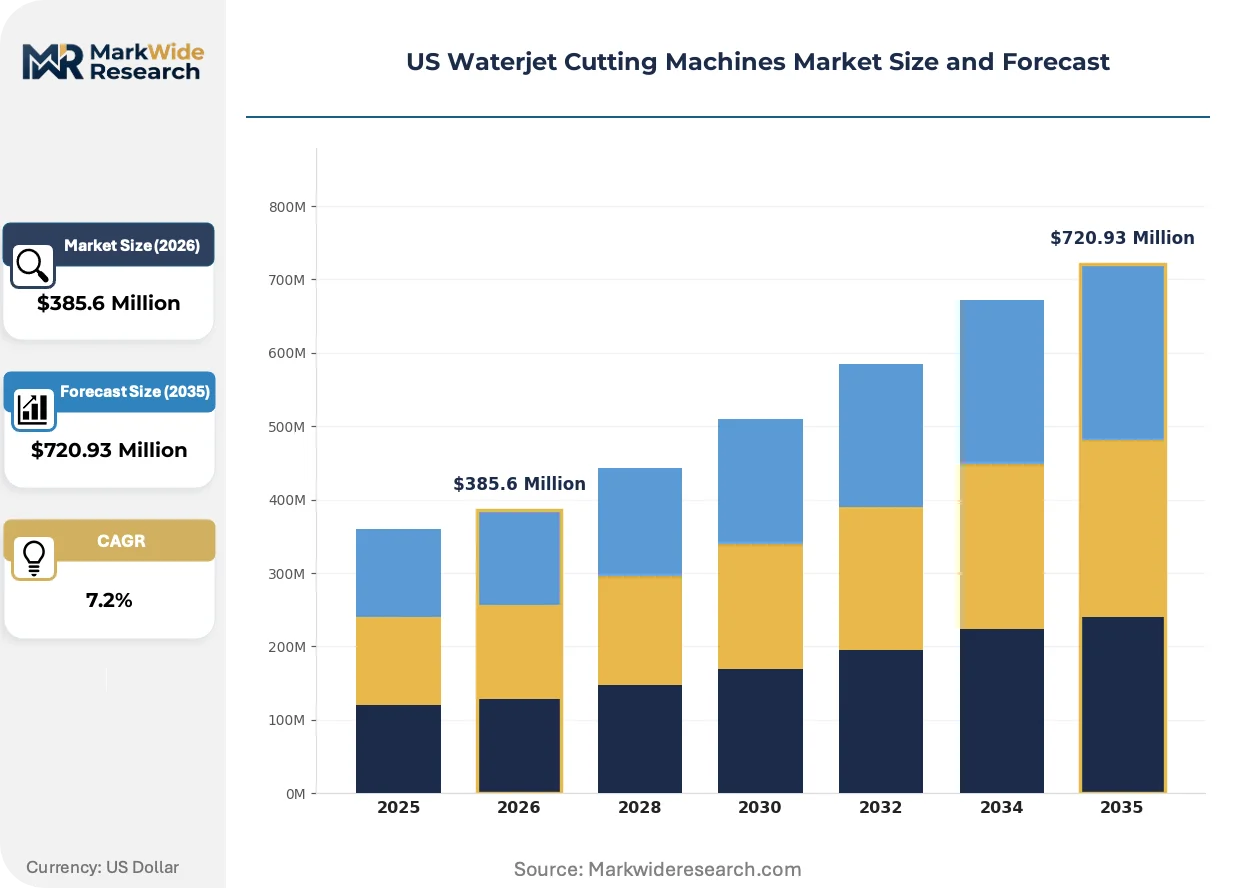
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $720.93 Million |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Waterjet, Abrasive Waterjet, Robotic Waterjet, Hybrid Waterjet Application: Metal Cutting, Stone Cutting, Glass Cutting, Foam Cutting End User: Aerospace, Automotive, Manufacturing, Architecture Technology: 2D Cutting, 3D Cutting, High-Pressure Systems, CNC Control |
| Companies Covered | OMAX Corporation, Flow International Corporation, Hypertherm Inc., WARDJet LLC, Koike Aronson Inc., Jet Edge Inc., Lincoln Electric Holdings Inc., Colfax Corporation, KMT GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Waterjet Cutting Machines Market Trends and Innovations
Software-controlled taper compensation and synthetic abrasive alternatives are redefining precision benchmarks and supply chain risk profiles across defense subcontractor and commercial aerospace supplier tiers.
Ultrahigh-pressure pump technology is expanding into precision-critical aerospace component fabrication, where 87,000 psi operating thresholds enable faster cutting speeds in titanium and Inconel without thermal distortion. Tier-1 airframe suppliers in Washington and Kansas are specifying these systems for production rate acceleration. The technology is expanding into composite trimming applications previously dominated by routing and milling, compressing capital equipment footprints on factory floors.
EPA effluent limitations under the Clean Water Act are forcing abrasive recovery system adoption across metal fabrication facilities, with discharge permit renewals contingent on suspended solids reduction. Closed-loop filtration investments now precede capacity expansion decisions in California and Great Lakes manufacturing zones. Stone and tile processors face the steepest compliance cost escalation, accelerating vendor consolidation toward turnkey system providers.
Service-based pricing models are displacing traditional equipment ownership in job shop segments, with throughput-guarantee contracts transferring operational risk to OEM service arms. Metal service centers in the Southeast are piloting per-cut metering arrangements that bundle abrasive, maintenance, and software updates. California fabricators show the highest contract penetration, driven by capital constraint preferences and regulatory compliance bundling requirements.
US Waterjet Cutting Machines Market Segmentation
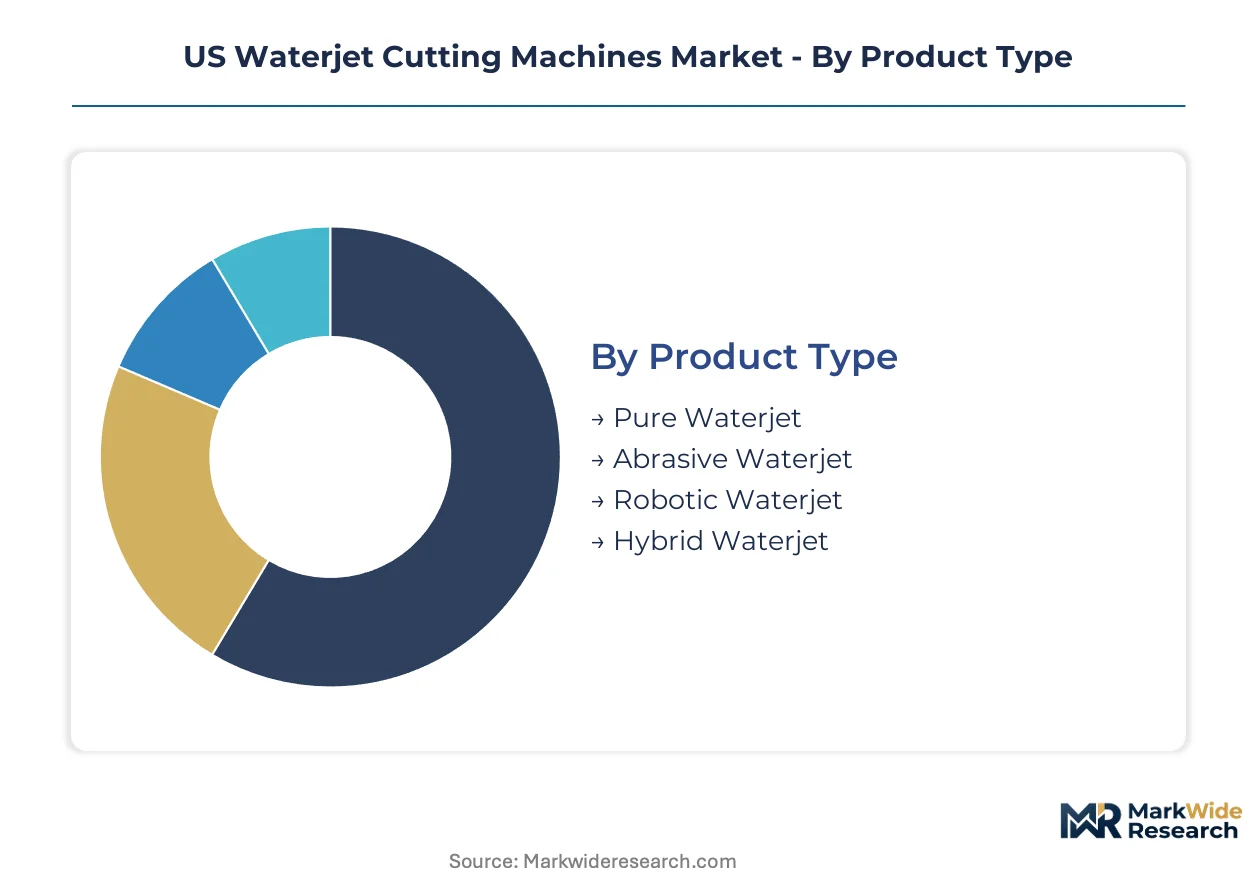
Waterjet cutting machines segment across four critical dimensions that determine capital allocation priorities and competitive positioning. Product type dictates abrasive consumption and maintenance intensity. Application and end-user concentration shape geographic demand clusters. Technology tier separates commodity fabricators from precision-critical aerospace suppliers.
Product Type:
Abrasive waterjet systems dominate volume shipments while robotic configurations command premium pricing and fastest expansion trajectories.
- Abrasive Waterjet:Pressurized water streams mixed with garnet abrasive erode thick metals, stone, and composites at pressures exceeding 60,000 psi. Michigan automotive suppliers and Texas oilfield equipment fabricators concentrate procurement here for titanium and exotic alloy profiling where thermal distortion risks prohibit plasma or laser alternatives.
- Robotic Waterjet:Multi-axis kinematic configurations automate complex 3D contour trimming for aerospace fuselage sections and automotive interior components. Ohio and South Carolina assembly supplier networks drive adoption as labor availability tightens across Midwest manufacturing centers.
- Pure Waterjet:Pressurized water without abrasive media serves food processing and foam fabrication applications where contamination risks exclude particulate matter. USDA sanitary equipment standards sustain stable replacement demand in protein and produce cutting operations.
- Hybrid Waterjet:Combined thermal-mechanical systems integrate plasma or laser pre-heating with waterjet finishing for single-platform flexibility in metal service shops seeking throughput optimization across varied material thicknesses.
Today's leader: Abrasive Waterjet. Tomorrow's challenger: Robotic Waterjet.
Application:
Metal cutting absorbs the majority of system shipments while foam cutting sustains defensible niche margins through regulatory moats.
- Metal Cutting:Cold-cutting preservation of metallurgical integrity in hardened steels, titanium, and Inconel positions waterjet as mandatory for heat-sensitive alloy fabrication. Defense subcontractors and commercial aerospace tier suppliers in Washington and Kansas specify ultrahigh-pressure configurations for production rate acceleration.
- Stone Cutting:Abrasive waterjet executes intricate architectural profiles in granite, marble, and engineered stone without crystalline silica dust generation. California and Great Lakes processors face steep EPA effluent compliance cost escalation, accelerating vendor consolidation toward turnkey system providers.
- Glass Cutting:Precision edge quality without micro-cracking serves automotive windshield and architectural panel fabrication. Thickness limitations constrain addressable share against diamond scribing in thin-glass electronics applications.
- Foam Cutting:Pure waterjet configurations slice polyurethane and polystyrene for packaging, furniture, and insulation products. Contamination-risk-sensitive medical and food-contact applications sustain equipment demand as FDA material safety standards tighten.
Metal Cutting anchors current revenue. Foam Cutting offers the most insulated margin profile.
End User:
Aerospace procurement prioritizes precision certification while automotive demand concentrates on throughput automation.
- Aerospace:Tier-1 airframe suppliers mandate waterjet systems for next-generation composite and titanium component trimming where heat-affected zones would compromise structural integrity. FAA production part approval processes and AS9100 quality certifications create qualification barriers that favor established OEM relationships.
- Automotive:Michigan supplier corridors and Southern assembly networks deploy robotic waterjet cells for interior trim, gasket, and insulation material processing. OSHA noise exposure standards and lockout-tagout mandates drive replacement cycles in legacy fabrication shops.
- Manufacturing:General metal fabrication job shops and contract manufacturers span diverse material portfolios from aluminum sheet to hardened tool steel. Capital constraint preferences in small-batch operations sustain service-based pricing model penetration.
- Architecture:Stone and tile contractors, monument fabricators, and custom metalwork studios specify waterjet for artistic and functional component production. Project-based demand cyclicality complicates capacity planning for dedicated equipment investments.
Aerospace commands the steepest premium. Automotive offers the deepest volume pool.
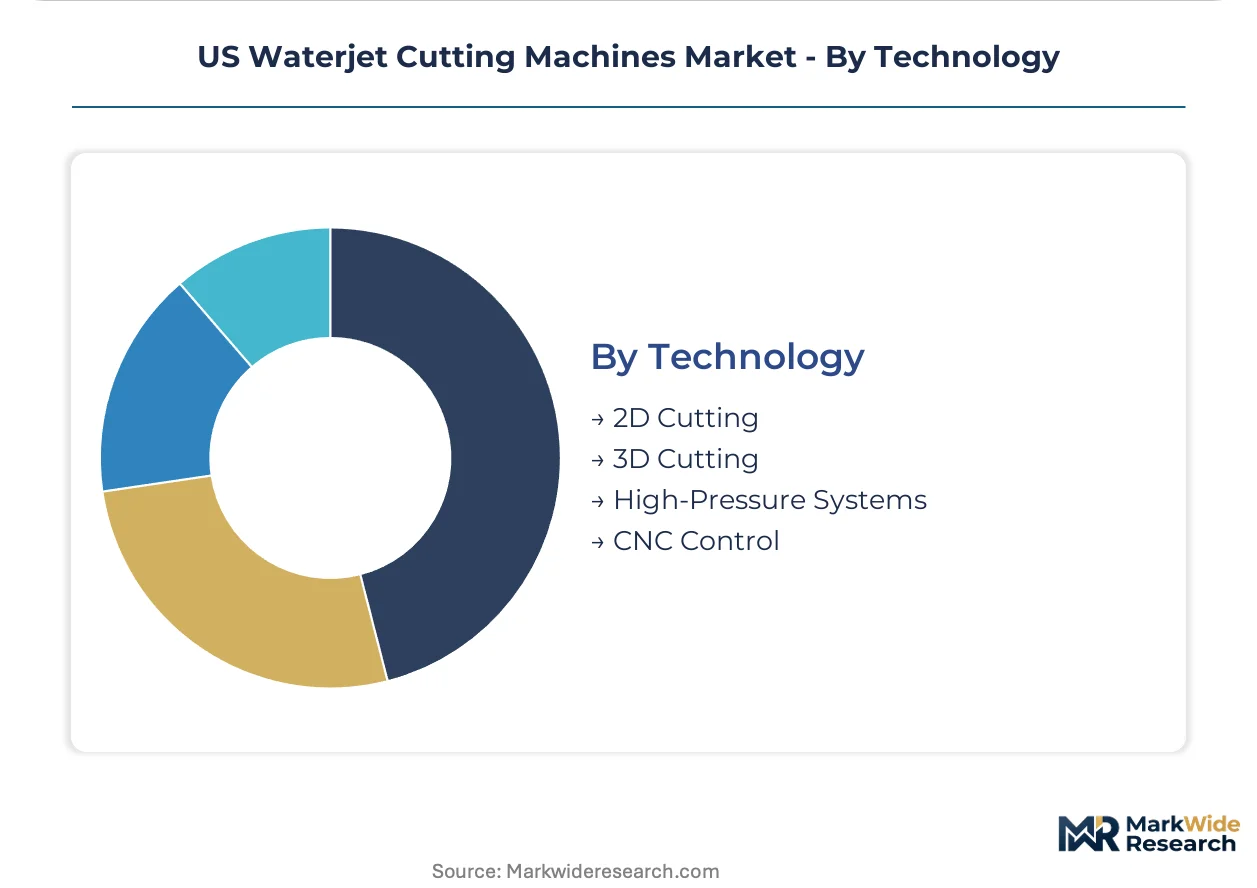
Technology:
3D cutting capabilities separate premium system tiers while CNC control standardization compresses differentiation at the base.
- 3D Cutting:Five and six-axis kinematic configurations enable complex contour following on compound curvature surfaces. Boeing and Airbus supplier networks in Wichita and Charleston drive specification for production-scale composite trimming previously dominated by routing and milling.
- High-Pressure Systems:87,000 psi operating thresholds enable faster cutting speeds in titanium and Inconel without thermal distortion. Ultrahigh-pressure pump technology expands from aerospace into precision-critical medical device and energy-equipment applications.
- 2D Cutting:Planar beam delivery serves flat stock processing in metal service centers and stone slab fabrication. Commoditization pressure intensifies as Chinese and European OEMs penetrate mid-market price tiers.
- CNC Control:Software-controlled taper compensation and jet kinematics programming differentiate premium system offerings. Multi-axis CAM proficiency scarcity outpaces vocational training pipeline output, constraining throughput realization in automated cell deployments.
3D Cutting claims the fastest expansion trajectory. CNC Control underpins every competitive positioning claim.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan's automotive supplier corridor anchors US waterjet demand, with Texas energy-equipment manufacturing and Pacific Northwest aerospace clusters driving regional specialization patterns across the country.
Michigan and the Great Lakes Automotive Belt
Tier-1 and Tier-2 automotive suppliers in Detroit, Grand Rapids, and Flint deploy abrasive waterjet systems for interior trim, gasket fabrication, and insulation material processing. OSHA noise exposure standards and lockout-tagout mandates accelerate replacement cycles in legacy fabrication shops across the region. Ohio and Indiana assembly supplier networks extend procurement demand for robotic waterjet cells as labor availability tightens.
Texas Energy-Equipment Manufacturing Corridor
Oilfield tool and pressure vessel fabricators in Houston, Midland-Odessa, and Corpus Christi adopt thick-section abrasive waterjet for exotic alloy profiling in downhole equipment and subsea components. EPA effluent discharge rules under the Clean Water Act force capital-intensive closed-loop filtration investments before permit renewals. Dallas-Fort Worth metal service centers pilot service-based pricing models with per-cut metering arrangements.
Pacific Northwest Aerospace and Defense
Boeing supplier networks in Seattle, Everett, and Spokane mandate waterjet systems for titanium and composite trimming where heat-affected zones compromise structural integrity. FAA production part approval processes and AS9100 quality certifications create qualification barriers favoring established OEM relationships. Washington and Kansas tier-1 airframe suppliers specify ultrahigh-pressure configurations for production rate acceleration.
California Fabrication and Environmental Compliance
Stone and tile processors in Los Angeles, San Francisco Bay Area, and Central Valley face steep EPA effluent compliance cost escalation, accelerating vendor consolidation toward turnkey system providers. California Air Resources Board protocols add compliance layers for facilities operating in the Western region. Advanced abrasive recovery systems reduce virgin garnet consumption by seventy percent, creating recurring revenue streams through service contracts.
Southeast Automotive and Metal Service Expansion
BMW, Mercedes-Benz, and Volvo assembly supplier networks in South Carolina and Alabama deploy robotic waterjet cells for complex contour trimming operations. Metal service centers in Georgia and Tennessee seek single-platform flexibility through plasma-waterjet hybrid workflows. Regional vocational training gaps in multi-axis CAM proficiency constrain throughput realization in automated cell deployments.
US Waterjet Cutting Machines Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs bundle filtration, software, and service contracts to capture compliance-driven replacement cycles. The vendor base separates into three distinct tiers: legacy high-pressure pump specialists, precision table and software innovators, and diversified thermal-cutting conglomerates. Consolidation pressure intensifies as service-based pricing models displace traditional equipment ownership and regulatory compliance bundling requirements favor turnkey providers. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping market structure.
Within the precision-tier specialist segment, OMAX Corporation and Flow International Corporation exemplify divergent strategic archetypes—one anchored in software-controlled motion systems, the other in ultrahigh-pressure pump heritage. Hypertherm Inc. occupies a hybrid position spanning thermal and mechanical cutting modalities. These three entities represent the competitive core around which mid-market challengers and regional fabricators orbit, each archetype commanding distinct price positioning and customer loyalty patterns across defense subcontractor, aerospace supplier, and metal service center segments.
| Leading Market Players |
|---|
| OMAX Corporation |
| Flow International Corporation |
| Hypertherm Inc. |
| WARDJet LLC |
| Koike Aronson Inc. |
| Jet Edge Inc. |
| Lincoln Electric Holdings Inc. |
| Colfax Corporation |
| KMT GmbH |
| Others |
Pricing and Supply Chain Analysis
Tier-1 aerospace suppliers and Michigan automotive procurement clusters anchor pricing power around performance-tier differentiation rather than commodity spot dynamics. Abrasive garnet cost pass-through and EPA compliance bundling now structure contract negotiations more than base equipment quotes.
Pricing Analysis
Input-cost pass-through from virgin garnet mining concentration in Western Australia and India compresses margins for standard abrasive waterjet tiers while ultrahigh-pressure pump configurations sustain premium positioning. Price differentiation rests on AS9100 certification tier and closed-loop filtration inclusion, with California fabricators showing highest contract penetration due to capital constraint preferences. Pricing pressure stems from plasma-waterjet hybrid substitution in metal service shops seeking single-platform flexibility. Small-batch job shops exhibit greatest price sensitivity; defense subcontractors with FAA production part approval requirements demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for high-pressure pump components and abrasive media qualification mandate supplier redundancy across Australia, India, and domestic recycling processors. Raw material dependencies center on garnet abrasive, ultrahigh-pressure ceramic plungers, and precision motion system components. Supply chain risk concentrates in freight rate volatility from Western Australian mining operations and currency hedge requirements. Distribution runs through OEM direct sales for turnkey systems and regional distributor networks for aftermarket consumables and service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on synthetic abrasive displacement and service-contract bundling that captures recurring revenue from EPA compliance mandates.
For Market Incumbents: Deepen backward integration into abrasive recycling technology to offset virgin garnet cost volatility and anchor customer lock-in through closed-loop filtration service contracts. Defend against plasma-waterjet hybrid substitution by accelerating software-controlled taper compensation roadmaps that preserve precision advantages in aerospace trimming applications.
For New Entrants and Emerging Players: Begin with pure waterjet configurations in food processing applications where USDA sanitary equipment standards create regulatory moats against thermal cutting alternatives. Target protein and produce cutting operations in California and Southeast processing clusters with contamination-risk-sensitive equipment specifications.
For Investors and Strategic Acquirers: Diversified thermal-cutting conglomerates seeking waterjet capability are the most active acquirer in this space, driven by single-platform bundling strategies for metal service centers. Long-term viability favors targets with installed base density in aerospace certification tiers. Watch for EPA effluent discharge permit renewal cycles as inflection indicators for compliance-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Filtration Technology Deployment | EPA Clean Water Act compliance mandates drive abrasive recovery system adoption across California and Great Lakes fabrication zones. |
| Robotic 3D Configuration Development | Automotive suppliers in Ohio and South Carolina automate complex contour trimming as labor availability tightens. |
| Ultrahigh-Pressure Pump Platform Expansion | Boeing and Airbus supplier networks in Wichita and Charleston specify 87,000 psi thresholds for titanium production rates. |
| Service-Based Pricing Model Pilot | Texas and Southeast metal service centers test per-cut metering arrangements bundling abrasive, maintenance, and software updates. |
| Synthetic Abrasive Alternative Qualification | Defense subcontractors and commercial aerospace tiers seek supply chain risk reduction from Western Australian mining concentration. |
Research Methodology
Coverage spans Michigan automotive corridors, Texas energy-equipment manufacturing, Pacific Northwest aerospace clusters, California fabrication zones, and Southeast automotive expansion, with primary inputs from each. Interviews with plant engineers at Tier-1 suppliers, OEM procurement teams, aftermarket service heads, and EHS compliance officers combined with secondary validation from OSHA enforcement databases, EPA discharge permit records, SEC 10-K filings, and customs trade data. Bottom-up equipment shipment analysis and top-down end-use demand estimation were triangulated.
Rate-of-change decomposition across the analysis window segmented by product type, application, end user, and technology tier. Modeled dimensions included pressure threshold classification, automation configuration, and regional regulatory cluster intensity. CAGRs were derived from installed base evolution and replacement cycle acceleration linked to OSHA noise exposure standard enforcement. Industry-specific forecast inputs incorporated abrasive garnet price index movements and FAA production part approval pipeline velocity.
Several conditions sit outside the modeled scope, including tariff rate shifts on Australian garnet imports, breakthrough plasma-waterjet hybrid performance thresholds, and state-level regulatory preemption. Forecasts reflect assumptions about EPA enforcement continuity and aerospace production rate stability. Deviation in OSHA lockout-tagout inspection intensity or California Air Resources Board protocol expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Snow Removal Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Crane Rail Market
Construction Equipment
India Construction Equipment Market