
 Hygienic Cladding Market | 2026-2036
Hygienic Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Hygienic Cladding Market Analysis
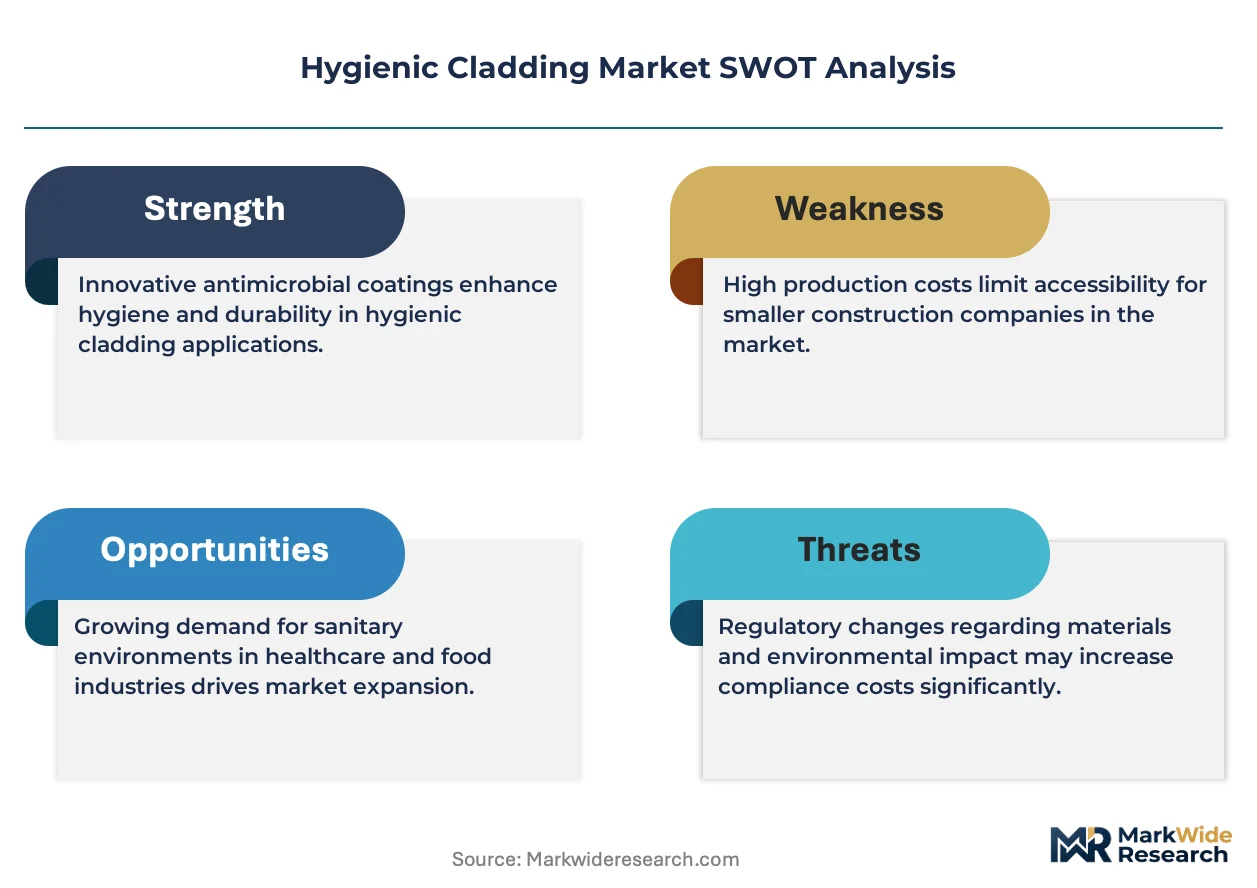
The EU Green Deal is expanding the addressable market for low-emission interior surfacing across food-safe environments. Altro Limited leverages deep vertical integration in resilient flooring and walling to control specification pipelines in UK healthcare estates. Polyflor Limited sustains manufacturing scale across multiple polymer formulations, anchoring supply security for large NHS refurbishment programs. KLEENCLAD International Private Limited specializes in antimicrobial PVC systems, competing on certified infection-control performance in Indian hospital construction.
Hygienic cladding denotes interior wall and ceiling surfacing engineered for wash-down durability, microbial resistance, and seamless joint integrity, typically manufactured from extruded polyvinyl chloride, cold-rolled stainless steel, or glass-reinforced thermoset composites with specified thicknesses from 1mm to 4mm. Its primary purpose is to create impervious barriers in moisture-prone zones where sanitation protocols demand frequent chemical cleaning and biological containment. PVC dominates volume across food processing and healthcare retrofit applications due to cost efficiency and ease of thermoformed fabrication, while stainless steel commands premium positioning in pharmaceutical cleanrooms where particulate shedding must approach zero. End-user demand fragments across healthcare facilities facing renovation backlogs and food processing units confronting updated HACCP visual-inspection standards.
FDA food-contact surface regulations and EU REACH chemical restrictions on plasticizer migration jointly shape material formulation roadmaps and supplier qualification timelines in this market. EMA cleanroom guidelines and ISO 14644 particulate classifications further constrain product architecture for pharmaceutical-grade installations. Buyers must monitor evolving biobased polymer certifications and cross-reference them against existing mechanical-fastening and welded installation method warranties before committing to multi-year cladding contracts.
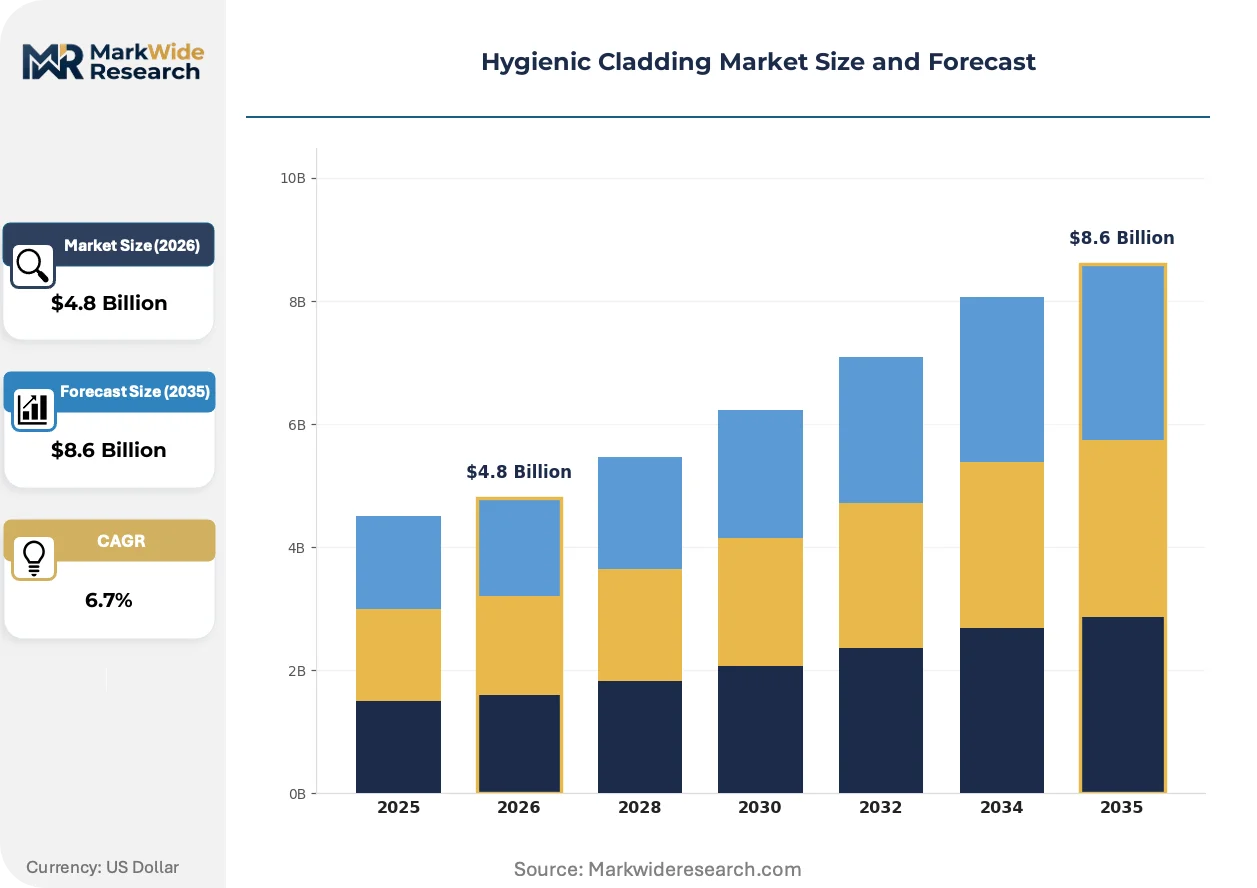
Market Dynamics
EU Green Deal building renovation mandates are compressing specification cycles for antimicrobial interior surfacing across food processing estates, forcing material suppliers to requalify polymer formulations against tightening emissions thresholds.
Growth Catalysts
- REACH plasticizer restrictions:Reformulation pressure is accelerating PVC compound innovation, opening substitution windows for phthalate-free alternatives in wash-down environments.
- Food processing wash-down protocols:Updated HACCP visual-inspection standards in Germany and France are triggering cladding replacement cycles in dairy and bakery facilities.
- Healthcare renovation backlogs:NHS estate refurbishment programs in the UK are channeling capital toward infection-control wall systems in acute care settings.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer feedstock costs fluctuate with naphtha and ethylene pricing, compressing margin stability for extrusion specialists.
- Stainless steel supply concentration:Cold-rolled coil for pharmaceutical-grade cladding concentrates among a narrow base of European and East Asian metallurgical suppliers.
- Welded seam labor intensity:Thermoplastic installation demands skilled hot-air welding technicians, creating bottlenecks in markets with constrained vocational training pipelines.
Strategic Opportunities
- Indian hospital construction:CDSCO infection-control guidelines are mandating antimicrobial surfacing in new tertiary care facilities, opening specification channels for certified PVC systems.
- Biobased polymer certification:EU Green Deal procurement preferences are creating early-mover advantage for suppliers with third-party-validated bio-attributed content claims.
- Modular cleanroom prefabrication:Convergence of offsite construction methods with ISO 14644-compliant cladding is reducing on-site contamination risk in pharmaceutical buildouts.
Industry Challenges
- Welding technician scarcity:Thermoplastic membrane certification programs have not scaled with installation demand, elongating project timelines in high-growth markets.
- Multi-jurisdiction compliance stacking:Suppliers serving both FDA food-contact and EMA cleanroom verticals must maintain parallel formulation and testing registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygienic Cladding Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinyl Chloride, Stainless Steel, Aluminum, Fiberglass End User: Healthcare Facilities, Food Processing Units, Laboratories, Cleanrooms Thickness: 1mm, 2mm, 3mm, 4mm Installation Method: Adhesive Bonding, Mechanical Fastening, Snap Lock, Welded |
| Companies Covered | Hygienic Wall Systems Ltd, KLEENCLAD International Private Limited, Altro Limited, AM Clad Limited, Interclad Systems Ltd, Polyflor Limited, The White Cladding Company Limited, Palram Industries Ltd, BioClad Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygienic Cladding Market Emerging Trajectories
Material science advances and procurement model evolution are restructuring competitive advantage around verified performance data rather than traditional specification relationships.
Antimicrobial additive integration is overtaking surface-coating approaches as the dominant hygiene-performance strategy. Silver-ion and copper-based compounds embedded during PVC extrusion provide durable microbial resistance without topical wear. Pharmaceutical cleanroom operators in Switzerland and Germany are specifying these integrated systems for 10-year lifecycle guarantees.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent food processors to improve envelope thermal performance alongside cladding hygiene ratings. Composite panels combining insulation cores with antimicrobial facing layers are gaining specification share in Nordic dairy retrofit programs. Installers are adapting fastening systems to accommodate thicker composite assemblies.
Digital substrate verification is replacing paper-chain documentation for infection-control procurement. NHS supply frameworks now require batch-level traceability data accessible via QR-coded installation records. This transparency mandate favors suppliers with integrated manufacturing and logistics data infrastructure over distributors assembling multi-source material packages.
Hygienic Cladding Market Segmentation
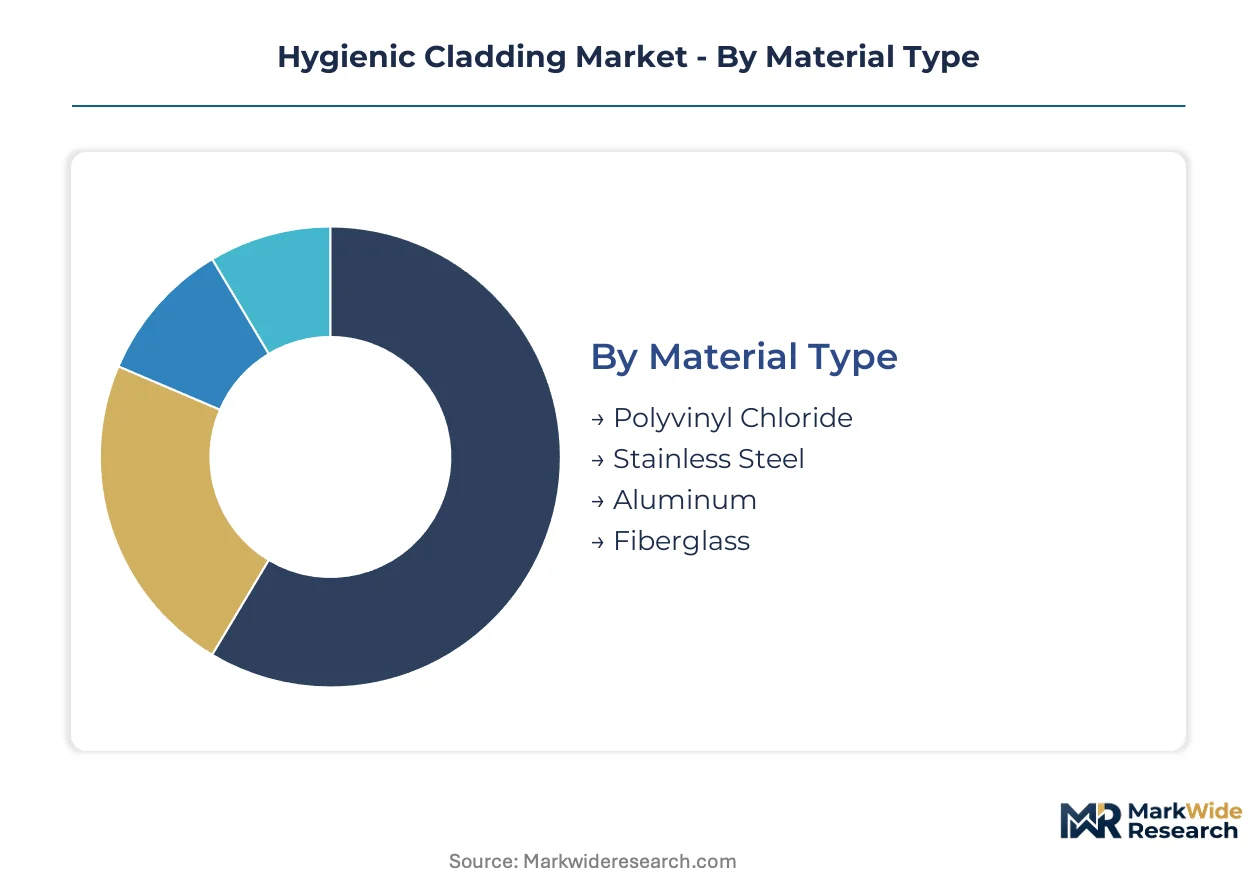
Hygienic cladding procurement hinges on matching material performance to environmental stress levels. Specification committees weigh wash-down frequency, chemical exposure, and regulatory compliance against installation complexity and lifecycle cost.
Material Type:
Customization intensity spans from commodity extrusions to precision metallurgy, with formulation control determining warranty terms and requalification burdens.
- Polyvinyl Chloride:Extruded thermoplastic formulations dominate volume through cost-efficient fabrication and thermoforming adaptability. Demand concentrates in German dairy and bakery retrofits where REACH plasticizer restrictions are forcing phthalate-free compound transitions.
- Stainless Steel:Cold-rolled austenitic grades deliver zero particulate shedding for pharmaceutical cleanrooms. Swiss and German pharmaceutical operators specify these systems for 10-year lifecycle guarantees under EMA cleanroom guidelines.
- Aluminum:Lightweight alloy panels with anodized or powder-coated finishes serve moderate-hygiene commercial kitchens where weight reduction simplifies retrofit installation.
- Fiberglass:Glass-reinforced thermoset composites provide chemical resistance in corrosive wash-down environments with extreme pH cycling.
Most installed capacity flows through Polyvinyl Chloride. Expansion is steepest in Stainless Steel.
End User:
Application environments dictate performance thresholds from antimicrobial surface ratings to joint integrity under thermal shock.
- Healthcare Facilities:Acute care estates require infection-control wall systems with seamless joint architecture and batch-level traceability. NHS refurbishment programs in the UK are channeling capital toward certified PVC installations with QR-coded documentation.
- Food Processing Units:HACCP visual-inspection standards in France and Germany trigger replacement cycles in wash-down zones. Dairy and bakery facilities prioritize cladding that withstands caustic cleaning regimens and thermal cycling from steam sanitation.
- Laboratories:Research environments balance chemical resistance with ease of decontamination for biological containment protocols.
- Cleanrooms:ISO 14644-compliant pharmaceutical installations demand particulate control approaching zero shedding, constraining material selection to welded stainless steel or integrated antimicrobial thermoplastics.
Healthcare Facilities anchor current procurement volume. Food Processing Units are climbing the fastest amid regulatory tightening.
Thickness:
Structural gauge selection reflects impact resistance requirements and substrate preparation economics.
- 1mm:Thin-gauge PVC serves light-duty commercial applications with minimal impact exposure and flat wall substrates.
- 2mm:Mid-range specification balances rigidity with thermoforming flexibility for curved architectural elements in healthcare corridors.
- 3mm:Heavy-duty grade dominates food processing installations where trolley impact and thermal expansion stress joint integrity.
- 4mm:Maximum gauge provides structural self-support in high-traffic zones with minimal substrate preparation, commanding premium positioning in pharmaceutical buildouts.
3mm specifications carry the heaviest installation volume. 4mm systems are gaining share fastest in pharmaceutical prefabrication.
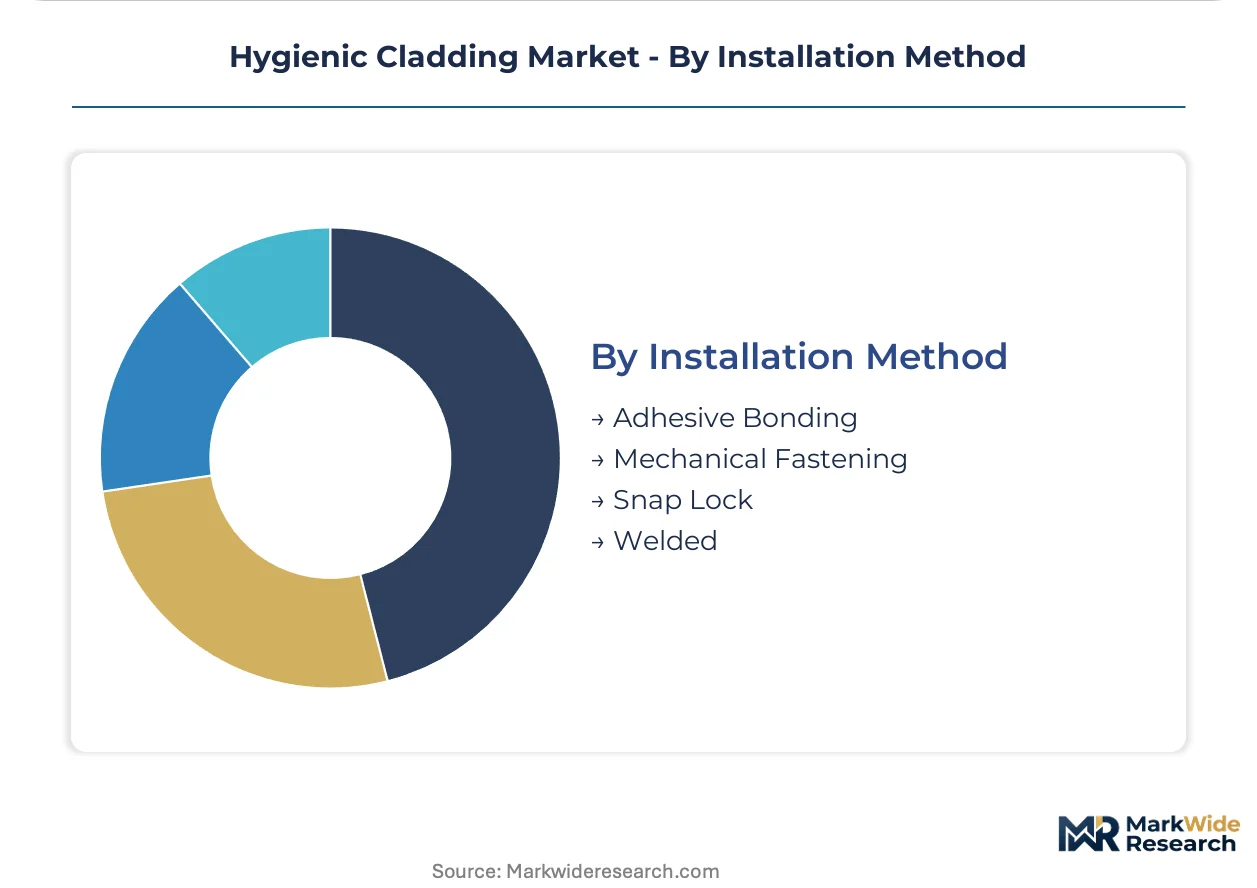
Installation Method:
Labor skill availability and contamination risk tolerance shape method selection across project types.
- Adhesive Bonding:Pressure-sensitive and structural adhesive systems enable rapid deployment in occupied healthcare wings with minimal dust generation.
- Mechanical Fastening:Concealed clip and screw systems permit future panel removal for infrastructure access in laboratory environments.
- Snap Lock:Interlocking edge profiles accelerate installation in standardized modular construction with trained crews.
- Welded:Hot-air welded thermoplastic seams deliver impervious joints for pharmaceutical cleanrooms and food wash-down zones. Technician certification bottlenecks elongate project timelines in high-growth markets.
Mechanical Fastening handles the broadest installed base. Welded methods are expanding most quickly where joint integrity is non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welding technicians concentrate in Germany's Ruhr industrial belt and the UK's Midlands manufacturing corridor, anchoring installation capacity for thermoplastic cladding systems across European food processing and healthcare estates.
Germany
Dairy and bakery facilities in Bavaria and Lower Saxony accelerate cladding replacement cycles under updated HACCP visual-inspection standards. REACH plasticizer restrictions force phthalate-free PVC compound transitions. Cologne-based fabricators supply antimicrobial wall systems to wash-down environments across the Rhine-Ruhr food processing cluster.
United Kingdom
NHS estate refurbishment programs channel capital toward infection-control wall systems in acute care settings across England and Scotland. CDSCO-aligned procurement frameworks now require batch-level traceability via QR-coded installation records. Manchester and Birmingham manufacturing corridors host specification pipelines for healthcare cladding retrofit.
France
Food processing units in the Île-de-France and Auvergne-Rhône-Alpes regions confront tightened sanitation protocols for dairy and meat handling environments. EU F-Gas Regulation phase-down schedules pressure refrigeration-dependent processors to improve envelope thermal performance alongside hygiene ratings. Lyon-based engineering firms specify composite panels combining insulation cores with antimicrobial facing layers.
India
CDSCO infection-control guidelines mandate antimicrobial surfacing in new tertiary care facilities across Maharashtra and Karnataka. Hospital construction in Mumbai and Bengaluru opens specification channels for certified PVC systems. Domestic fabricators compete with imported European systems on certified infection-control performance claims.
Switzerland
Pharmaceutical cleanroom operators under Swissmedic oversight specify silver-ion embedded thermoplastics for 10-year lifecycle guarantees. Basel and Zurich host precision manufacturing clusters demanding particulate control approaching zero shedding. EMA-aligned guidelines constrain material selection to welded stainless steel or integrated antimicrobial systems.
Hygienic Cladding Market Vendor Landscape
Capital-heavy extrusion specialists compete with asset-light specification designers for control of healthcare and food processing procurement pipelines. The vendor base arranges across three tiers: integrated polymer compounders with captive resin supply, regional fabrication houses serving national installation networks, and niche antimicrobial additive formulators. Strategic moves center on backward integration into polymer compounding and geographic expansion into Indian hospital construction.
Among UK-based resilient surfacing specialists, Altro Limited and Polyflor Limited occupy positions anchored in healthcare estate relationships. KLEENCLAD International Private Limited exemplifies the antimicrobial certification-focused archetype competing in Indian tertiary care buildouts. These three represent distinct competitive vectors: vertical control over specification pipelines, manufacturing scale across multiple polymer formulations, and certified infection-control performance in emerging markets.
| Leading Market Players |
|---|
| Hygienic Wall Systems Ltd |
| KLEENCLAD International Private Limited |
| Altro Limited |
| AM Clad Limited |
| Interclad Systems Ltd |
| Polyflor Limited |
| The White Cladding Company Limited |
| Palram Industries Ltd |
| BioClad Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap extrusion specialists across Germany and the UK anchor supply discipline through generational capital structures that resist quarterly margin pressure, enabling long-term compound formulation investments that commodity traders cannot match. This ownership pattern insulates pricing power against petrochemical volatility while concentrating procurement leverage among buyers with multi-year NHS or food processing framework contracts.
Pricing Analysis
Bundled installation-and-material packages command 15-25% premiums over unbundled panel supply, with hot-air welding certification requirements creating natural service attachment. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade stainless steel systems from dairy-grade PVC and commercial kitchen aluminum panels. Pricing pressure stems from REACH plasticizer reformulation costs compressing margins on legacy phthalate-dependent compounds. Food processing buyers exhibit highest price sensitivity due to HACCP compliance mandates draining capital reserves, while pharmaceutical cleanroom operators prioritize lifecycle guarantees over upfront cost.
Supply Chain Analysis
PVC resin supply rests on naphtha-fed ethylene crackers concentrated in Germany, Belgium, and the Netherlands, with plasticizer feedstocks drawing from East Asian adipic acid and phthalic anhydride producers. Cold-rolled stainless steel coil hinges on Austrian and Finnish metallurgical suppliers serving pharmaceutical specification tiers. Single-source vulnerability runs through welding equipment manufacturers in Germany's Ruhr belt, where hot-air tool production has not scaled with installation demand. Distribution runs through specification-controlled fabricator networks rather than open merchant channels, with project-based logistics dominating over stocked inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hygienic cladding market functions as a stable compounder anchored by regulatory renovation mandates across European healthcare and food processing estates that resist cyclical downturn. EU Green Deal building performance standards and infection-control guideline updates create predictable replacement cycle visibility.
For Market Incumbents: Extend specification pipeline control through captive welding technician training programs that lock in installation capacity for NHS and German dairy retrofit backlogs. Backward integration into phthalate-free compound production defends margin position against REACH-driven raw material cost spikes. Prioritize QR-coded batch traceability infrastructure to meet CDSCO-aligned procurement frameworks in Indian hospital construction.
For New Entrants and Emerging Players: The mid-tier price gap between premium stainless steel pharmaceutical systems and economy PVC food processing panels offers white-space positioning for composite panel specialists. Target French dairy processors confronting EU F-Gas Regulation thermal envelope upgrades with insulation-integrated antimicrobial facing layers. Enter through modular cleanroom prefabrication partnerships that bypass skilled welding bottlenecks.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses serving national installation networks without captive resin supply. Five-to-ten-year viability hinges on biobased polymer certification positioning ahead of EU Green Deal procurement preference maturation. Watch CDSCO enforcement intensity in Maharashtra and Karnataka as inflection signal for Indian market premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Phthalate-Free Compound Transition | REACH compliance secures specification continuity in German dairy and bakery retrofit pipelines. |
| Welding Technician Certification Scaling | Capacity expansion in UK's Midlands corridor addresses NHS refurbishment program bottlenecks. |
| Biobased Polymer Certification | Third-party validation unlocks EU Green Deal procurement preference in early-mover positioning. |
| Modular Cleanroom Prefabrication | Offsite construction convergence reduces on-site contamination risk for Swissmedic-regulated pharmaceutical buildouts. |
| QR-Coded Batch Traceability Infrastructure | Digital substrate verification meets NHS supply framework transparency mandates for infection-control procurement. |
Methodological Framework
Direct dialogue with plant engineers at German dairy processors, NHS estate refurbishment directors, CDSCO regulatory affairs leads, and hot-air welding certification program administrators grounded qualitative assessment in operational constraint realities. Secondary validation drew from EU REACH substance restriction updates, EMA cleanroom guideline revisions, NHS procurement framework disclosures, and customs data tracking PVC resin trade flows. Bottom-up demand modeling across food processing retrofit cycles and healthcare renovation backlogs triangulated against top-down construction spending forecasts.
Bottom-up volume builds aggregated project-level cladding specifications by material type, thickness gauge, and installation method across the analysis window. Segmentation dimensions modeled include material chemistry, end-use environment stress levels, and regional regulatory cluster alignment. CAGRs derived from fitted growth curves incorporating REACH plasticizer transition timelines, NHS capital program phasing, and CDSCO guideline enforcement trajectories. Industry-specific inputs encompass welding technician training pipeline capacity and biobased polymer certification validation timelines.
Caveats apply where REACH plasticizer restriction acceleration, NHS budget reallocation, or CDSCO enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions around skilled labor availability and raw material qualification timelines that remain exposed to revision. A small set of named triggers—welding technician certification scaling, biobased polymer standard maturation, and Indian regulatory enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Black Bricks Market